
 Netherlands Data Center Processor Market | 2026-2036
Netherlands Data Center Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Data Center Processor Market Insights
Platform licensing revenue is reshaping competitive economics in the Netherlands data center processor landscape. Intel Corporation leverages its x86 architecture dominance to sustain high-margin supply agreements with Dutch hyperscale operators. NVIDIA Corporation anchors AI accelerator procurement through CUDA ecosystem lock-in across Amsterdam-based cloud campuses.
Data center processors are integrated circuits engineered for continuous high-throughput computation, typically fabricated on sub-5nm process nodes with thermal design power ratings exceeding 200 watts for AI training workloads. These devices orchestrate server virtualization, database acceleration, and neural network inference across rack-scale deployments. GPU segments command premium positioning as generative AI training clusters multiply across Dutch facilities, while liquid cooling configurations expand fastest amid EU energy efficiency directives and rising chip power densities. CPU categories retain volume leadership in enterprise colocation and legacy workload consolidation.
The Netherlands Authority for Consumers and Markets enforces EU Green Deal compliance on data center power usage effectiveness, while the Dutch Digitalization Minister applies CSRD reporting standards to facility carbon footprints. BIS certification requirements for imported semiconductor equipment shape procurement timelines for Dutch infrastructure operators. Stakeholders must weigh sovereign cloud qualification criteria against accelerator supply constraints when committing to multi-year deployment schedules.
Market Dynamics
EU AI Act enforcement and national sustainability mandates are compressing deployment timelines for Dutch data center operators, forcing immediate capital allocation toward liquid-cooled infrastructure and certified sovereign cloud configurations.
Growth Catalysts
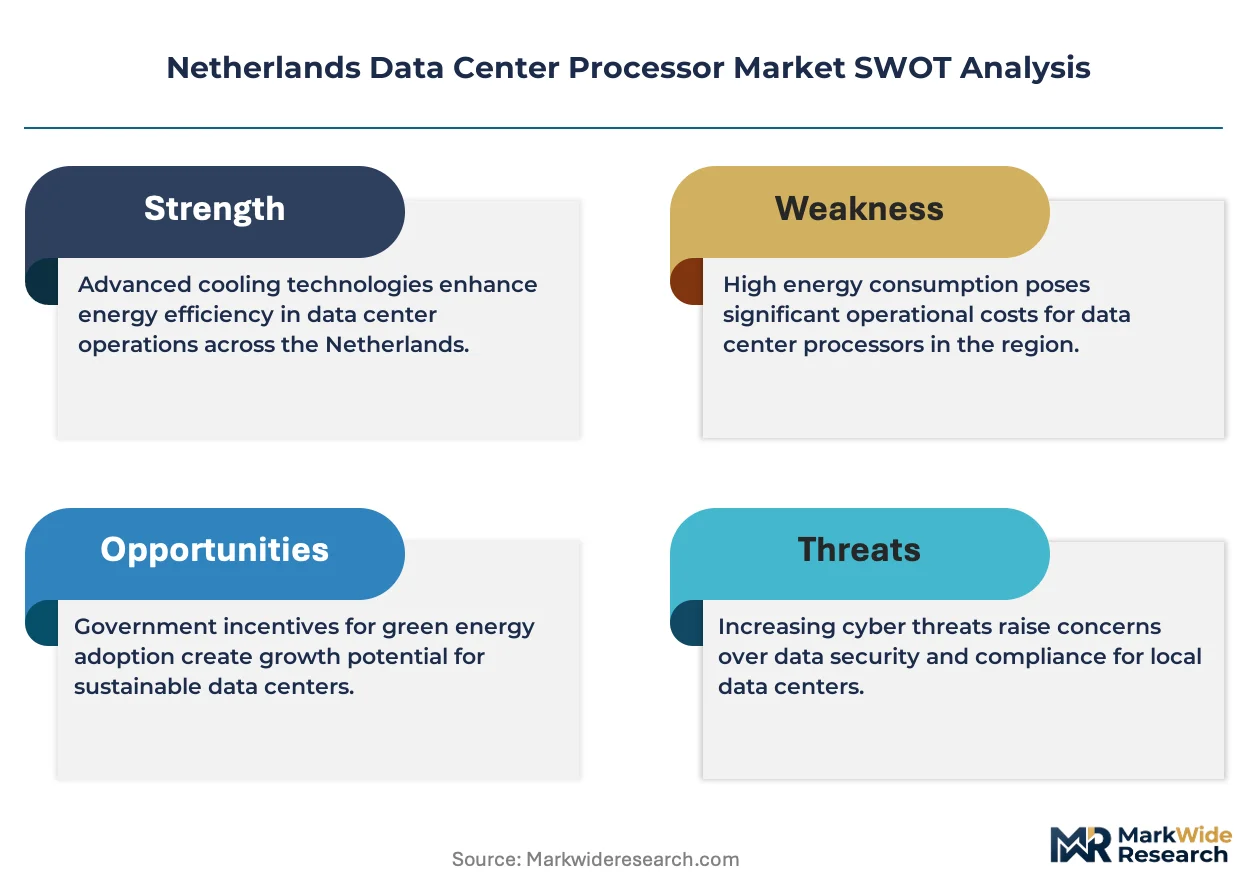
- EU AI Act compliance deadlines:Dutch facilities face mandatory algorithmic transparency requirements that accelerate procurement of traceable, high-performance compute clusters for financial services inference workloads.
- Randstad corridor concentration:Amsterdam and Eindhoven campuses serve pan-European sovereign cloud demand, concentrating AI training cluster investments in facilities with established fiber interconnects and grid access.
- Liquid cooling retrofits:Heat-reuse regulations under the EU Green Deal mandate energy recovery systems, driving processor refresh cycles toward high-TDP GPU and CPU sockets compatible with direct-to-chip cooling.
Market Restraints
- Accelerator supply concentration:Advanced AI chip fabrication concentrates at single-source foundries, exposing Dutch operators to allocation rationing and extended lead times for training-class GPUs.
- BIS certification friction:US export controls on semiconductor manufacturing equipment delay Dutch infrastructure procurement, particularly for facilities seeking sub-5nm process node deployments.
- Power grid saturation:Randstad substations face connection queue backlogs that cap facility expansion regardless of processor availability or capital commitment.
Strategic Opportunities
- Edge inference in North Brabant:Eindhoven's semiconductor equipment ecosystem supports low-latency manufacturing AI deployments underserved by hyperscale cloud concentrations.
- CSRD-aligned carbon accounting:Mandatory sustainability disclosure creates differentiated positioning for operators offering processor-level power telemetry and Scope 3 emission tracking.
- Neuromorphic-DSP convergence:Emerging sparse compute architectures promise order-of-magnitude efficiency gains for recommendation inference workloads in Dutch financial services colocation.
Industry Challenges
- Specialized thermal engineering scarcity:Liquid cooling system design and coolant chemistry expertise remains concentrated among legacy mainframe specialists, constraining retrofit velocity.
- Multi-vendor orchestration complexity:Heterogeneous CPU-GPU-DPU deployments require firmware harmonization across Intel, AMD, and ARM instruction set boundaries, extending integration timelines.
- Sovereign cloud certification timelines:Dutch government security clearances for classified workload hosting impose 18-24 month qualification periods that misalign with processor refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Data Center Processor Market |
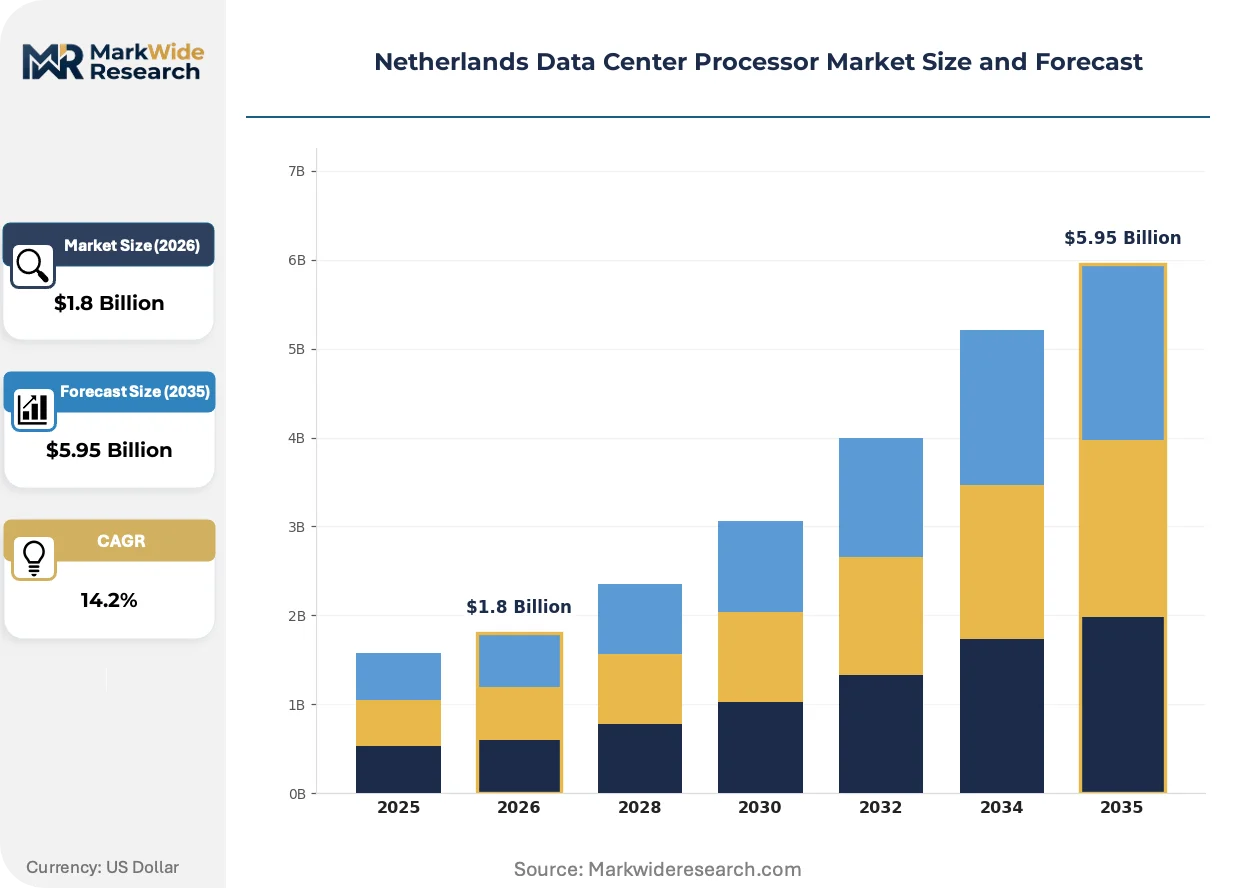
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Processor Type: CPUs, GPUs, APUs, TPUs Form Factor: Rackmount, Blade, Tower, Micro Cooling Method: Air Cooling, Liquid Cooling, Immersion Cooling, Refrigerant Cooling End User: Cloud Service Providers, Enterprises, Colocation Providers, Research Institutions |
| Companies Covered | Intel Corporation, NXP Semiconductors, NVIDIA Corporation, Broadcom Inc., Advanced Micro Devices Inc., Qualcomm Technologies, Arm Holdings, IBM Corporation, Marvell Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Data Center Processor Market Trends and Innovations
Computational density requirements and thermal constraints are forcing architectural discontinuities in Dutch data center processor deployments, with infrastructure design choices now preceding silicon selection rather than following it.
Direct liquid cooling manifolds with dielectric coolants are rendering obsolete air-cooled rack architectures across Amsterdam hyperscale campuses. Dutch operators with PUE commitments under the EU Green Deal are adopting warm-water cooling loops that recover 85% of chip thermal output for district heating networks. This thermal integration is rendering obsolete traditional CRAC-unit facility designs that treated heat as waste rather than revenue.
CSRD reporting standards applied by the Dutch Digitalization Minister now mandate processor-level carbon footprint disclosure across facility supply chains. Financial services tenants in Randstad colocation are demanding socket-level telemetry to satisfy their own Scope 3 accounting obligations. This regulatory pressure is compressing procurement evaluation criteria toward vendors with transparent foundry energy mixes and modular upgrade paths.
Hyperscale reservation contracts are displacing spot-market accelerator procurement for Dutch AI training clusters. Cloud service providers in the Amsterdam metro now commit to three-year compute reservations with foundry-backed allocation guarantees, transferring supply risk from operators to semiconductor vendors. This contractual evolution is most visible among generative AI startups relocating from London and Paris to access reserved Dutch capacity.
Netherlands Data Center Processor Market Segmentation
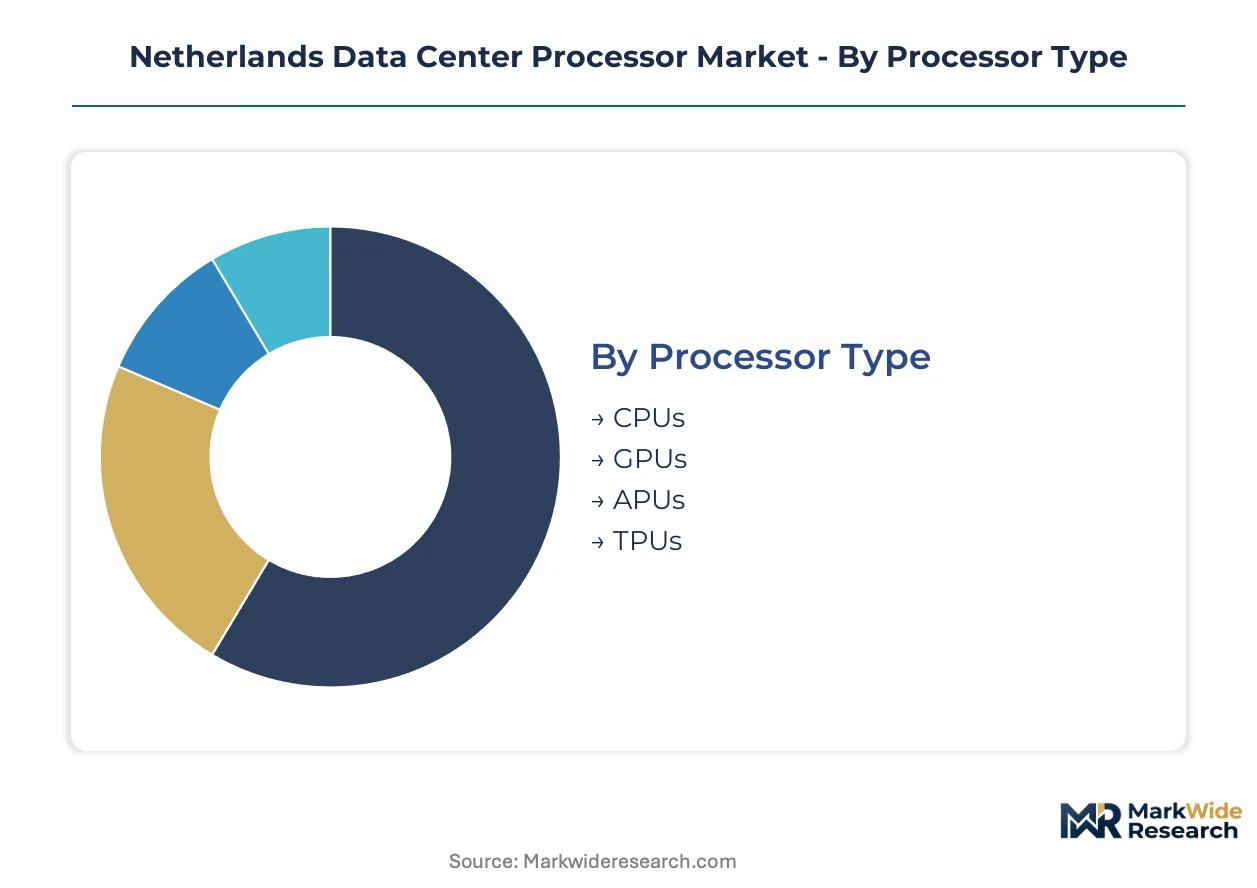
Processor selection in Dutch data centers now hinges on thermal integration capabilities and sovereign cloud certification requirements rather than raw compute metrics alone. Segmentation reveals how Amsterdam hyperscale operators and Eindhoven research clusters diverge in procurement priorities.
Processor Type:
Workload specialization spans from legacy enterprise virtualization to generative AI training across Dutch facilities.
- CPUs:x86 architectures dominate Randstad enterprise colocation for database consolidation and ERP workloads. Dutch financial services tenants in Amsterdam prioritize sockets with built-in memory encryption for CSRD-compliant data governance.
- GPUs:AI training clusters at Eindhoven cloud campuses command high-TDP accelerators with HBM memory stacks. EU AI Act traceability mandates favor GPUs with deterministic execution paths for algorithmic audit trails.
- APUs:Integrated CPU-GPU silicon serves edge inference nodes in North Brabant manufacturing corridors where rack space constraints limit discrete accelerator deployment.
- TPUs:Google Cloud's Amsterdam region deploys custom tensor accelerators for recommendation engine serving, though availability remains restricted to reserved capacity contracts.
The dominant share belongs to CPUs, while GPUs are closing the gap fastest.
Form Factor:
Physical deployment constraints in Randstad facilities favor density-optimized configurations over traditional tower architectures.
- Rackmount:Standard 19-inch chassis accommodate 2U-4U processor modules across Amsterdam hyperscale halls. Dutch operators with PUE commitments under the EU Green Deal select rackmount nodes with hot-aisle containment compatibility.
- Blade:Shared infrastructure chassis reduce per-socket power conversion losses in Eindhoven research clusters. Netherlands Organization for Applied Scientific Research deploys blade enclosures for fluid dynamics simulation farms.
- Tower:Standalone server enclosures persist in provincial Dutch enterprise data centers with sub-100kW facility limits.
- Micro:Compact edge nodes support latency-sensitive manufacturing AI at ASML supplier facilities near Veldhoven.
Rackmount configurations hold the installed base lead, with blade systems expanding most quickly in research-oriented deployments.
Cooling Method:
Thermal design power thresholds now determine cooling topology selection before processor procurement proceeds.
- Air Cooling:Traditional CRAC-dependent architectures serve sub-200W CPUs in legacy Amsterdam colocation halls. Dutch Digitalization Minister energy audits now penalize facilities relying solely on air cooling for high-density racks.
- Liquid Cooling:Direct-to-chip cold plates handle 700W+ GPU sockets across AI training clusters. Amsterdam operators with district heating contracts recover 85% of chip thermal output through warm-water loops.
- Immersion Cooling:Dielectric fluid baths enable 100kW+ rack densities for Eindhoven semiconductor simulation workloads.
- Refrigerant Cooling:Two-phase evaporative systems address hotspot management in mixed CPU-GPU deployments where liquid manifold retrofits prove impractical.
Air cooling retains volume leadership in legacy infrastructure, though liquid cooling is gaining share fastest amid heat-reuse regulations.
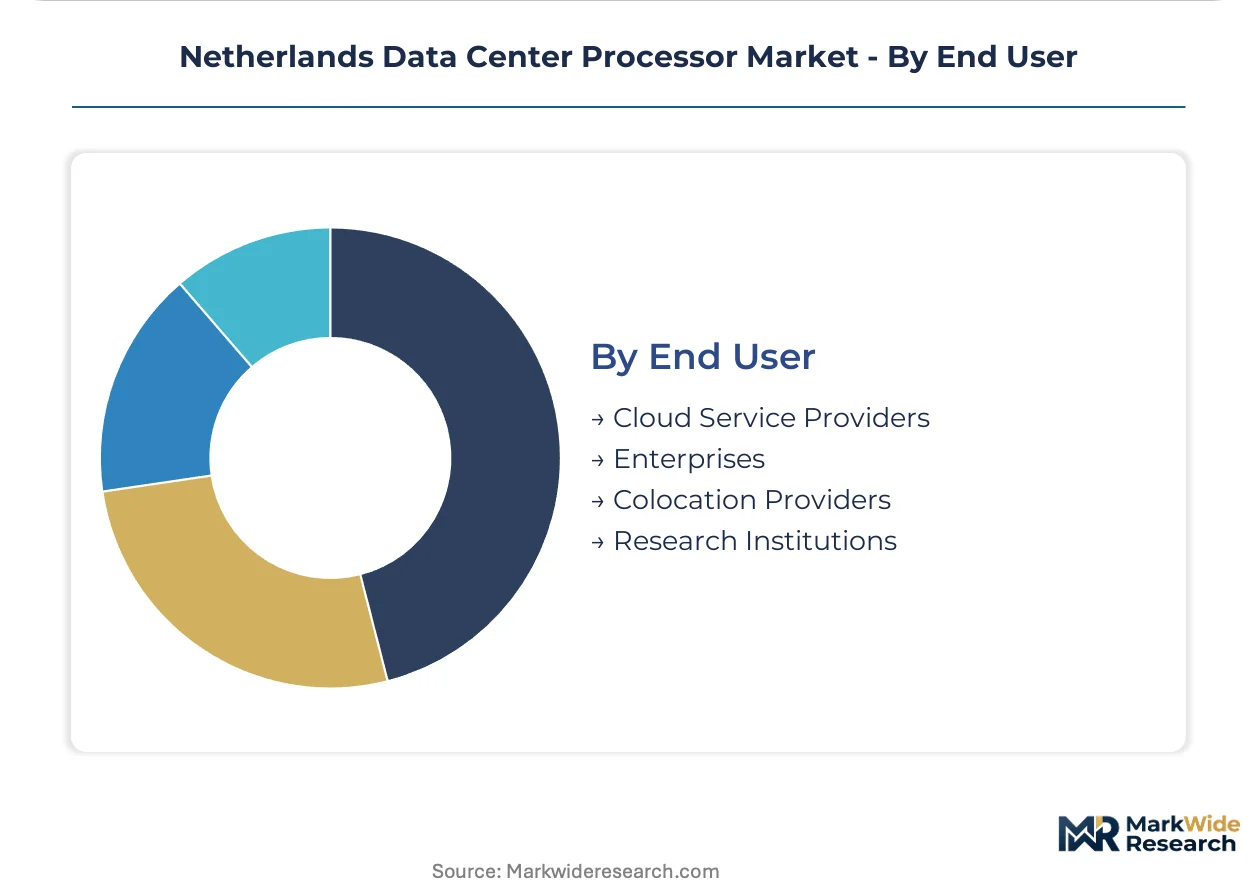
End User:
Procurement authority concentrates among operators with sovereign cloud certification and multi-year compute reservation capacity.
- Cloud Service Providers:Hyperscale operators in Amsterdam commit to three-year foundry allocation contracts for training-class GPUs. EU AI Act compliance investments favor CSPs with established algorithmic transparency frameworks.
- Enterprises:Dutch financial services firms in Zuidas district prioritize colocation with processor-level carbon telemetry for Scope 3 disclosure.
- Colocation Providers:Interxion and Equinix Amsterdam campuses offer certified sovereign cloud configurations with BIS-compliant equipment chains.
- Research Institutions:TU Eindhoven and SURF consortium deploy national supercomputing infrastructure with liquid-cooled processor architectures.
Cloud service providers command the dominant procurement volume, with research institutions climbing fastest on national AI infrastructure investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for data center processors varies sharply across Dutch sub-regions, with Randstad hyperscale operators absorbing premium accelerator costs while provincial enterprises defer procurement amid grid connection uncertainty.
Randstad
Amsterdam and Rotterdam campuses command three-year GPU reservation contracts from cloud service providers seeking EU AI Act compliance. The Dutch Digitalization Minister applies CSRD reporting standards to facility carbon footprints, mandating processor-level telemetry. Metro Amsterdam concentrates sovereign cloud infrastructure serving pan-European financial services workloads.
North Brabant
Eindhoven's semiconductor equipment ecosystem drives demand for low-latency edge inference processors at ASML supplier facilities. The Netherlands Authority for Consumers and Markets enforces EU Green Deal power usage effectiveness thresholds on manufacturing-adjacent data halls. The Veldhoven-Nuenen corridor hosts specialized micro data centers for lithography simulation workloads.
Central Netherlands
Utrecht and Amersfoort colocation providers face compressed margins as enterprises migrate to hyperscale alternatives, intensifying price competition for mid-range CPU sockets. National heat-reuse regulations accelerate liquid cooling retrofits in legacy facilities. The Utrecht Science Park deploys blade-based research clusters for fluid dynamics computation.
Northern Netherlands
Groningen and Leeuwarden facilities leverage surplus renewable grid capacity to attract carbon-conscious processor deployments from German cloud operators. BIS certification requirements for imported semiconductor equipment shape procurement timelines for cross-border infrastructure. The Eemshaven port zone anchors submarine cable landing stations with associated compute nodes.
Netherlands Data Center Processor Market Competitive Landscape
Foundry-dependent chip designers and fabless accelerator specialists split the market through divergent risk allocation models. Intel Corporation and NVIDIA Corporation anchor procurement volumes through long-term supply agreements with Dutch hyperscale operators. Three archetypes dominate: vertically integrated IDMs with captive fabrication, fabless GPU specialists leveraging foundry partnerships, and IP-licensing architecture providers. Competitive moves concentrate on multi-year reservation contracts with allocation guarantees and sovereign cloud certification bundling.
Within the fabless accelerator tier, NVIDIA Corporation exemplifies ecosystem lock-in through CUDA software moats, while Advanced Micro Devices Inc. occupies a position as the primary alternative supplier for training-class GPUs. Among Europe-based semiconductor players, NXP Semiconductors anchors the edge inference segment with automotive-derived processor architectures adapted for industrial data center deployments.
| Leading Market Players |
|---|
| Intel Corporation |
| NXP Semiconductors |
| NVIDIA Corporation |
| Broadcom Inc. |
| Advanced Micro Devices Inc. |
| Qualcomm Technologies |
| Arm Holdings |
| IBM Corporation |
| Marvell Technology |
| Others |
Pricing and Supply Chain Analysis
Single-source foundry dependency for sub-5nm AI accelerators determines both the three-tier pricing spread across reserved, spot-contract, and legacy-procurement tiers and the elongated supply chain shape that buffers Dutch operators against allocation rationing. BIS certification friction on semiconductor manufacturing equipment imports further compresses pricing power for operators without multi-year foundry-backed reservation capacity.
Pricing Analysis
Platform licensing revenue from CUDA ecosystem subscriptions and extended support contracts drives lifetime value for NVIDIA's Dutch hyperscale customers. Three-tier pricing structure across premium reserved allocation, standard spot-contract, and economy legacy-procurement levels stratifies by volume commitment and sovereign cloud certification tier. Pricing pressure stems from Intel's x86 margin defense in enterprise colocation, squeezing mid-range CPU socket margins. Cloud service providers exhibit lowest price sensitivity due to foundry-backed reservation guarantees, while provincial enterprises defer procurement amid grid connection uncertainty.
Supply Chain Analysis
Silicon wafer feedstock and advanced packaging substrates draw from Taiwan, South Korea, and USA fabrication complexes. EUV photoresists, HBM memory stacks, and CoWoS interposers anchor raw material dependencies. Single-source vulnerability concentrates at TSMC's leading-edge nodes, exposing Dutch operators to geopolitical allocation rationing. Distribution runs through Amsterdam-based hyperscale integrators and Eindhoven research consortium procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Netherlands data center processor market functions as a defensive-moat story where CUDA ecosystem lock-in and sovereign cloud certification entrenchment create switching costs that protect incumbent positioning against emerging sparse-compute architectures.
For Market Incumbents: Build ecosystem lock-in moats through expanded CUDA developer training programs and exclusive warm-water cooling integration partnerships with Randstad district heating operators. Threats from AMD's ROCm open-source acceleration and neuromorphic-DSP convergence in financial services inference demand counter-investment in algorithmic transparency tooling for EU AI Act compliance. Certification entrenchment via Dutch government security clearance pre-qualification extends contract renewal cycles. For New Entrants and Emerging Players: North Brabant edge inference nodes at ASML supplier facilities represent the most penetrable white-space target, underserved by hyperscale cloud concentrations. Eindhoven's semiconductor equipment ecosystem supports low-latency manufacturing AI deployments with rack space constraints that favor APU-integrated solutions over discrete accelerators. Go-to-market through TNO research partnership channels bypasses incumbent CSP reservation lock-in. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated cooling-system specialists with processor-agnostic manifold designs. Long-term viability across the analysis window hinges on thermal engineering capabilities rather than silicon architecture ownership. Acquisition targets should demonstrate liquid cooling retrofit execution velocity and CSRD-aligned carbon telemetry integration. Watch for Intel foundry service announcements as inflection indicators for x86 supply chain diversification.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Liquid Cooling Retrofit | Warm-water loop integration with Amsterdam district heating networks recovers 85% of thermal output. |
| Sovereign Cloud Certification | Dutch government security clearances for classified workloads extend contract terms and tenant retention. |
| Foundry Reservation Contract | Three-year compute commitments with allocation guarantees transfer supply risk from operators to vendors. |
| Neuromorphic Architecture R&D | Sparse compute designs promise order-of-magnitude efficiency gains for financial services recommendation engines. |
| CSRD Carbon Telemetry Integration | Socket-level power disclosure satisfies financial services tenant Scope 3 accounting obligations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center facility directors, cloud procurement officers, thermal engineering specialists, and Dutch Digitalization Minister policy advisors. Secondary validation drew from EU AI Act implementation guidance, CSRD technical standards, ACM enforcement records, hyperscaler capex disclosures, and foundry capacity announcements. Bottom-up installation tracking across Randstad, North Brabant, Central Netherlands, and Northern Netherlands sub-regions triangulated against top-down semiconductor import value flows.
Calibration anchored segment-level growth rates to observed reservation contract volumes, PUE compliance audit trajectories, and sovereign cloud certification pipeline status. Modeled dimensions span processor type, cooling topology, form factor density, and end-user procurement authority across the projection horizon. CAGR derivation incorporated foundry capacity expansion schedules, grid interconnection queue progression, and EU Green Deal enforcement intensity as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese foundry entrants or accelerated neuromorphic commercialization would shift outcomes beyond modeled ranges. Cross-checking against ACM energy audit disclosure trends and TNO research infrastructure procurement announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Global Battery Management IC Market
Chipset and Processors
Displayport IP Market
Chipset and Processors
Global Automotive Self-Driving Chip Market
Chipset and Processors
United States Data Center Processor Market
Chipset and Processors
South Korea Data Center Processor Market
Chipset and Processors
Americas Digital Signal Processor Market
Chipset and Processors
High-Performance Dual-Core Processor Market
Chipset and Processors
Combo Chip Market
Chipset and Processors
Europe Wi-Fi Chipset Market
Chipset and Processors
Deep Learning Chip Market
Chipset and Processors
Global Multimedia Chipsets Market
Chipset and Processors
Japan Microprocessor (MPU) Market
Chipset and Processors
Server Microprocessor Market
Chipset and Processors
Envelope Tracking Chips Market
Chipset and Processors
Poe Chipsets Market
Chipset and Processors
Surgical Chips Market