
 Europe Microcontroller (MCU) Market | 2026-2036
Europe Microcontroller (MCU) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Microcontroller (MCU) Market Insights
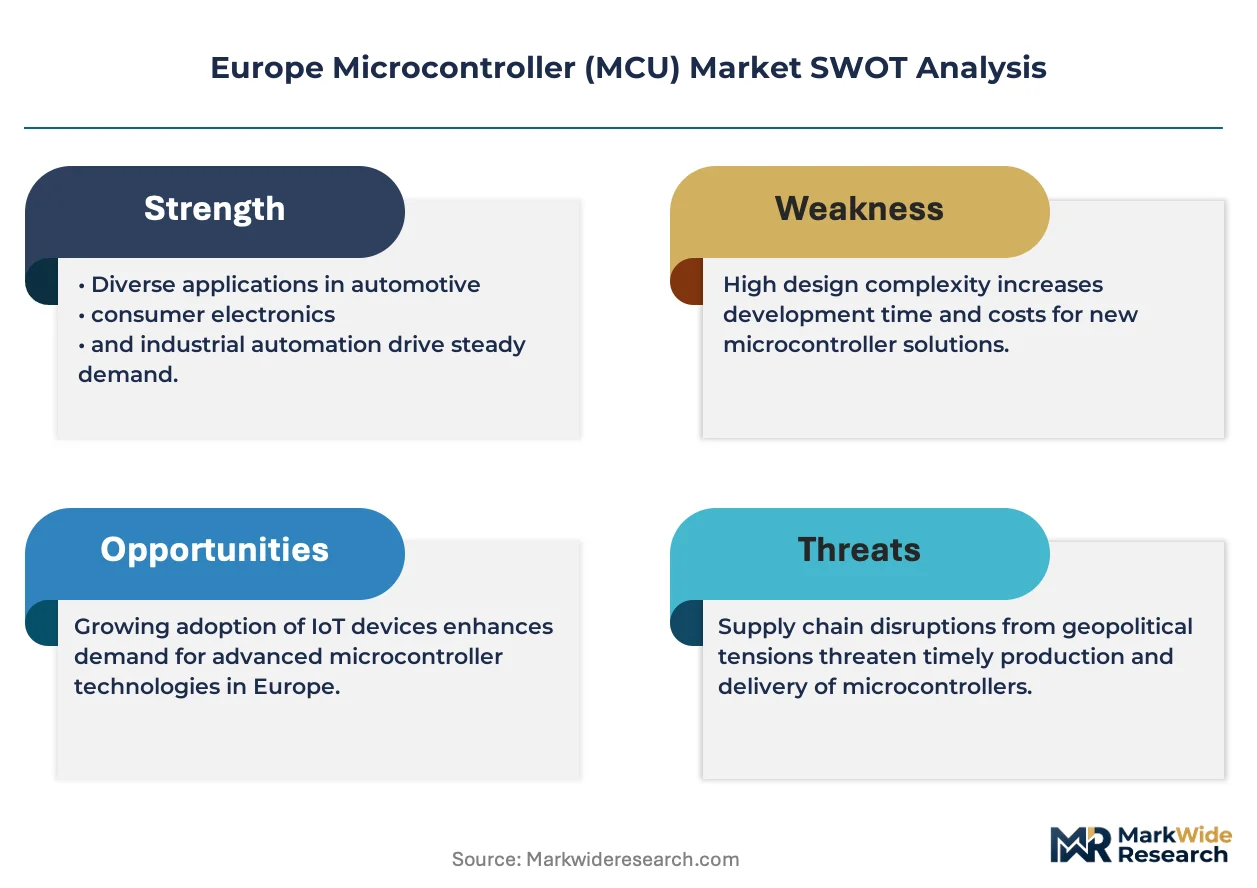
The Europe Microcontroller (MCU) Market is consolidating around a widening split between automotive-grade 32-bit platforms and commodity 8-bit controllers for white goods. Infineon Technologies AG leverages its captive SiC and MCU fab network in Austria and Germany to dominate automotive safety-critical sockets. STMicroelectronics N.V. anchors its position through deep ties with French and Italian industrial automation OEMs. NXP Semiconductors N.V. specializes in secure-element integration for payment and identity applications across Benelux banking infrastructure.
A microcontroller integrates a processor core, volatile and non-volatile memory, and programmable peripherals onto a single die, typically fabricated at nodes between 40nm and 90nm for automotive reliability. Its primary purpose is deterministic, low-latency control of electromechanical systems in resource-constrained environments. The 32-bit product tier now captures the bulk of design wins in electric powertrain and battery management systems where real-time operating systems demand higher addressable memory space. Automotive electronics represents the fastest-growing application segment as domain controller architectures disperse MCU counts across zonal gateways rather than consolidating into single SoCs.
The EU Green Deal and REACH chemical compliance frameworks are tightening material disclosure requirements for MCU packaging and substrate compositions. CE marking under the Radio Equipment Directive and functional safety mandates from ECE R10 and ISO 26262 are forcing non-automotive suppliers to upgrade qualification spend to access mobility supply chains. Stakeholders must monitor how the EU AI Act classifies embedded inference engines within mixed-signal MCUs, as this will determine whether edge AI coprocessors face additional conformity burdens or gain preferential treatment in public procurement.
Market Dynamics
Automotive domain controller architectures are dispersing MCU counts across zonal gateways rather than consolidating into single SoCs, forcing suppliers to recalibrate portfolio mixes toward safety-certified 32-bit platforms. This structural shift is compressing margins on legacy 8-bit controllers while elevating qualification barriers for entry into German and French OEM supply chains.
Growth Catalysts
- EU Green Deal embedded efficiency mandates:Procurement criteria now prioritize 32-bit architectures with deterministic power management, accelerating design wins in electric powertrain systems across German industrial corridors.
- Automotive zonal gateway proliferation:Domain controller disaggregation is multiplying MCU socket counts per vehicle, with French and Italian OEMs expanding safety-critical sourcing from established European suppliers.
- REACH chemical compliance frameworks:Material disclosure requirements for MCU packaging are filtering out non-compliant Asian competitors, consolidating share among Austrian and German captive fab networks.
Market Restraints
- 300mm wafer supply concentration:Advanced MCU fabrication depends on TSMC and GlobalFoundries capacity allocations, creating allocation risk for European fabless designers during automotive demand surges.
- ECE R10 and ISO 26262 qualification costs:Functional safety certification for ASIL-D rated MCUs requires 18-24 month validation cycles, freezing out mid-tier suppliers from mobility supply chains.
- SiC substrate cost volatility:Infineon's captive SiC supply provides insulation, but independent MCU houses face input cost pressure from constrained silicon carbide wafer availability.
Strategic Opportunities
- Benelux secure-element integration:NXP's payment infrastructure specialization creates a template for MCUs with embedded hardware security modules targeting EU digital identity frameworks.
- Edge AI coprocessor classification under EU AI Act:Mixed-signal MCUs with embedded inference engines may gain preferential procurement status if regulators classify them as low-risk embedded systems rather than high-risk AI.
- Industrial automation retrofit demand:Italian and French factory modernization programs are creating sockets for 32-bit MCUs with real-time Ethernet connectivity in legacy equipment upgrades.
Industry Challenges
- Functional safety engineering talent scarcity:ASIL-D certification expertise concentrates in Munich-Stuttgart corridor, creating recruitment bottlenecks for suppliers outside Germany's automotive cluster.
- Legacy 8-bit code base migration friction:White goods manufacturers face firmware rewrite costs when upgrading to 32-bit platforms, delaying procurement decisions and extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Microcontroller (MCU) Market |
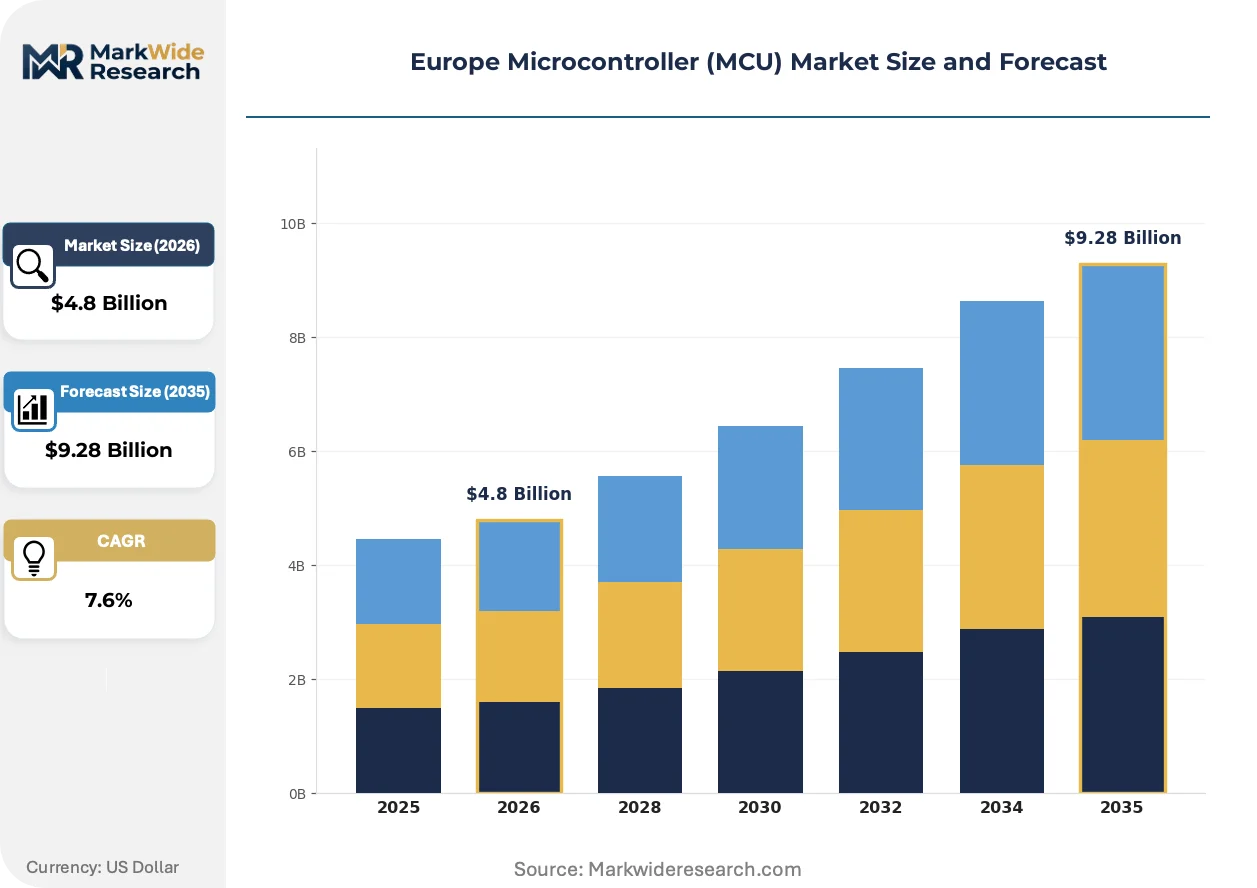
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 8-bit, 16-bit, 32-bit, Digital Signal Controllers Application: Consumer Electronics, Automotive Electronics, Industrial Automation, Medical Devices Technology: Analog, Digital, Mixed-Signal, Embedded End User: Manufacturers, System Integrators, Research Institutions, Developers |
| Companies Covered | Renesas Electronics Corporation, Texas Instruments, Inc., Infineon Technologies AG, Analog Devices, Inc., Arm Limited, STMicroelectronics N.V., Microchip Technology Incorporated, Silicon Labs, NXP Semiconductors N.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Microcontroller (MCU) Market Trends and Innovations
Deterministic low-latency control requirements are colliding with embedded AI inference demands, forcing MCU architects to integrate heterogeneous compute without sacrificing real-time guarantees. This tension is manifesting across three distinct vectors reshaping European procurement patterns.
RISC-V open instruction set architectures are rewriting competitive dynamics for 32-bit automotive MCUs. German Tier-1 suppliers are piloting RISC-V cores in non-safety-critical zonal controllers to reduce ARM licensing exposure. This technology is compressing royalty stacks and enabling customization of vector extensions for motor control algorithms.
REACH substance restrictions on lead-based solder and halogenated flame retardants are forcing substrate material transitions. ECHA's 2024 candidate list expansion is accelerating LCP and PPE resin adoption for high-temperature automotive sockets. MCU packaging houses in Austria and Germany are qualifying green molding compounds ahead of anticipated 2026 enforcement tightening.
Consolidated procurement through German OEM direct-sourcing programs is disintermediating traditional distribution. Stuttgart-based manufacturers now negotiate MCU supply agreements at holding-company level, bypassing Arrow and Avnet for strategic sockets. This channel compression is most visible in battery management system MCU categories where volume concentration justifies dedicated fab capacity reservations.
Europe Microcontroller (MCU) Market Segmentation
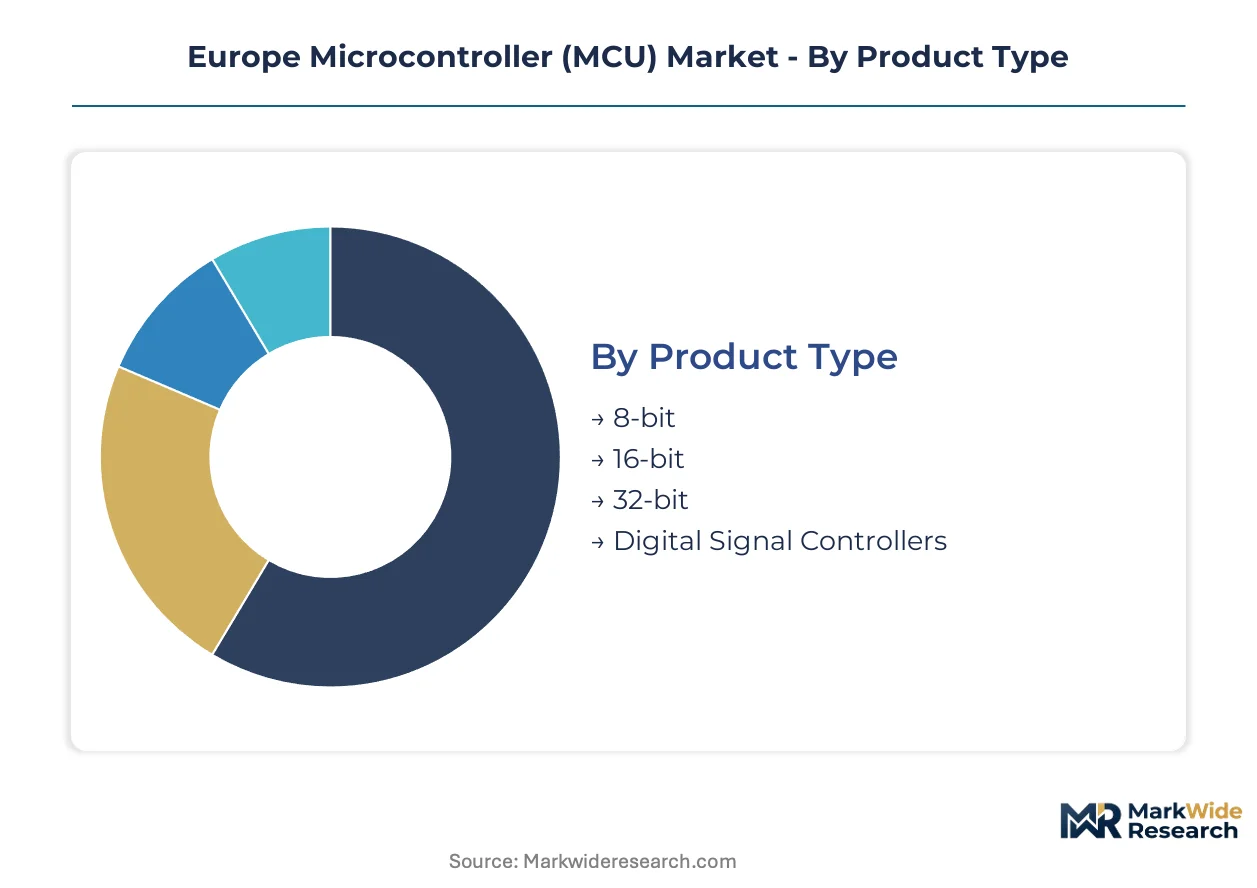
MCU procurement in Europe diverges sharply between safety-critical automotive sockets demanding ISO 26262 certification and cost-optimized industrial controllers. Buyers prioritize deterministic latency for powertrain applications while white goods OEMs optimize for firmware migration costs.
Product Type:
Bit-width selection determines memory addressing capacity, real-time operating system compatibility, and functional safety certification tier.
- 32-bit:ARM Cortex-M and RISC-V cores dominate electric vehicle powertrain and battery management systems. German OEMs mandate ASIL-D rated variants for zonal gateway architectures across Munich-Stuttgart supply chains.
- 8-bit:Legacy architectures persist in white goods motor control where firmware rewrite costs delay platform upgrades. REACH compliance pressures are forcing substrate material transitions even at this commodity tier.
- 16-bit:Mid-range controllers bridge cost-performance gaps in industrial sensor nodes.
- Digital Signal Controllers:Specialized architectures integrate DSP acceleration for motor control algorithms.
32-bit leads on scale; Digital Signal Controllers lead on momentum.
Application:
End-use concentration varies by regulatory exposure and qualification burden.
- Automotive Electronics:Domain controller disaggregation multiplies MCU counts per vehicle. French and Italian OEMs expand safety-critical sourcing from established European suppliers under ECE R10 mandates.
- Industrial Automation:Real-time Ethernet connectivity requirements drive 32-bit upgrades in Italian and French factory modernization programs.
- Consumer Electronics:Cost-optimized sockets favor 8-bit controllers with minimal peripheral integration.
- Medical Devices:MDR compliance and IEC 60601 safety standards elevate qualification spend for patient-contact applications.
Automotive Electronics anchors volume concentration; Industrial Automation shows steepest expansion trajectory.
Technology:
Signal processing architecture determines peripheral integration depth and analog precision.
- Mixed-Signal:Combines precision ADCs with digital cores for sensor fusion in battery management systems. EU AI Act classification debates surround embedded inference engines in this category.
- Embedded:Tight integration of memory and peripherals minimizes board space for space-constrained automotive modules.
- Analog:Discrete signal conditioning remains relevant for legacy industrial interfaces.
- Digital:Pure-logic implementations serve high-speed communication protocol stacks.
Mixed-Signal dominates design win value; Embedded climbs fastest on integration demands.
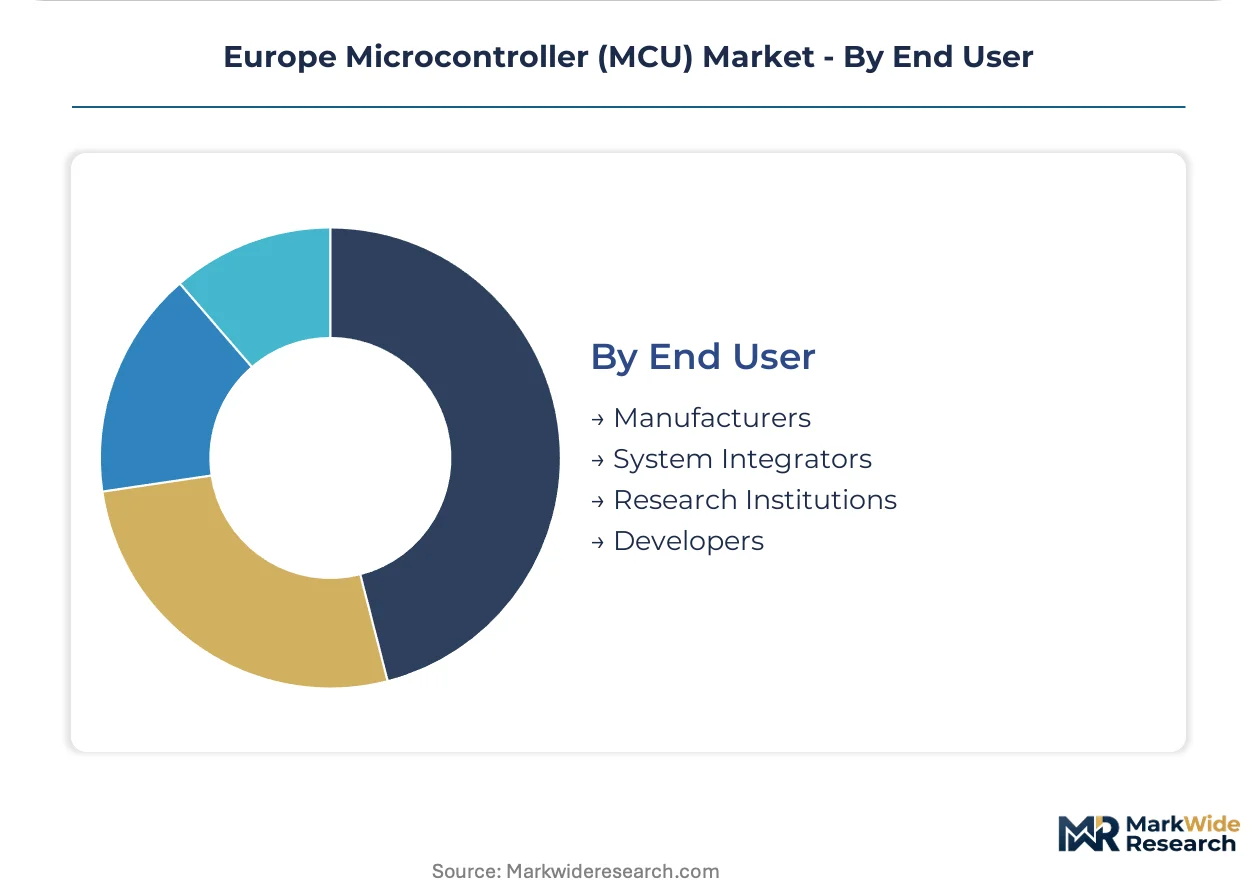
End User:
Procurement authority concentrates with direct OEM engagement displacing distribution channels.
- Manufacturers:German automotive OEMs negotiate MCU supply agreements at holding-company level, bypassing traditional distribution for strategic sockets. Volume concentration justifies dedicated fab capacity reservations.
- System Integrators:Industrial automation specialists in France and Italy aggregate demand across legacy equipment retrofit programs.
- Developers:RISC-V ecosystem participation concentrates in German Tier-1 pilot programs for non-safety-critical zonal controllers.
- Research Institutions:Academic partnerships with Austrian and German captive fab networks advance packaging material research under REACH frameworks.
Manufacturers command procurement leverage; System Integrators aggregate fragmented retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Functional safety engineering talent concentrates in Germany's automotive corridor, with embedded systems specialists clustering around Munich, Stuttgart, and Ingolstadt. This workforce density shapes procurement patterns and supplier qualification timelines across the continent.
Germany
Electric vehicle powertrain demand from BMW, Mercedes-Benz, and Volkswagen multiplies MCU socket counts per vehicle. ECE R10 electromagnetic compatibility mandates force suppliers to upgrade testing infrastructure. The Munich-Stuttgart industrial corridor anchors captive SiC and MCU fabrication networks serving Tier-1 safety-critical sourcing.
France
Renault and Stellantis expand zonal gateway architectures across hybrid and electric lineups. CE marking under the Radio Equipment Directive tightens documentation requirements for connected vehicle modules. The Île-de-France region hosts STMicroelectronics' advanced packaging research under REACH substance restriction frameworks.
Italy
Industrial automation retrofit programs drive 32-bit upgrades in legacy factory equipment. The EU Green Deal embedded efficiency mandates prioritize deterministic power management in motor control applications. Emilia-Romagna's machine tool builders aggregate fragmented demand through system integrator networks.
Netherlands
Payment infrastructure and digital identity applications concentrate demand for secure-element integration. GDPR data protection requirements extend to embedded hardware security modules in financial terminals. Eindhoven's high-tech campus anchors NXP's hardware security specialization for Benelux banking infrastructure.
United Kingdom
Arm Limited's Cambridge headquarters sustains processor architecture licensing dominance across European automotive design wins. MDR medical device regulations elevate qualification spend for patient-contact MCU applications. Southeast England's semiconductor design cluster feeds RISC-V ecosystem participation in non-safety-critical pilot programs.
Europe Microcontroller (MCU) Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered supplier base. Infineon and STMicroelectronics anchor the integrated tier through captive European fabrication, while fabless competitors depend on TSMC and GlobalFoundries capacity allocations. Three archetypes dominate: vertically integrated European houses with in-house SiC supply, ARM-licensed specialists with automotive safety certification, and mixed-signal generalists with industrial automation heritage. Competitive moves center on fab capacity reservations for automotive demand surges and REACH-compliant packaging material transitions ahead of 2026 enforcement tightening.
Within the integrated European tier, Infineon Technologies AG and STMicroelectronics N.V. exemplify the captive fabrication model that insulates against wafer supply volatility. NXP Semiconductors N.V. occupies a distinct position bridging secure-element hardware specialization with automotive zonal gateway penetration. These three companies represent the dominant competitive anchors shaping procurement authority consolidation through direct OEM engagement.
| Leading Market Players |
|---|
| Renesas Electronics Corporation |
| Texas Instruments, Inc. |
| Infineon Technologies AG |
| Analog Devices, Inc. |
| Arm Limited |
| STMicroelectronics N.V. |
| Microchip Technology Incorporated |
| Silicon Labs |
| NXP Semiconductors N.V. |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal embedded efficiency mandates gate qualified supply and premium-tier pricing access for automotive-grade 32-bit MCUs. REACH chemical compliance frameworks further stratify procurement tiers by disqualifying non-compliant packaging suppliers from German and French OEM direct-sourcing programs.
Pricing Analysis
Hardware-software bundling versus unbundled silicon supply splits pricing structures across automotive and industrial segments. Three-tier pricing structure across ASIL-D certified, ASIL-B intermediate, and uncertified economy levels reflects functional safety investment recovery. Pricing pressure stems from TSMC and GlobalFoundries capacity allocation constraints forcing spot-market premiums during automotive demand surges. White goods OEMs exhibit highest price sensitivity due to firmware migration friction delaying 32-bit upgrades, while German Tier-1 suppliers accept premium positioning for zonal gateway safety certification.
Supply Chain Analysis
Reverse-logistics flows for end-of-life automotive MCUs remain underdeveloped across European collection networks, though Austrian packaging houses pilot lead-free solder reclamation under REACH substance restriction frameworks. Wafer fabrication concentrates in Taiwan, South Korea, and the United States, with advanced MCU nodes drawing from TSMC and GlobalFoundries capacity. Silicon carbide substrate availability, copper leadframe alloys, and green molding compounds constitute critical input dependencies. Single-source vulnerability to TSMC automotive allocation decisions represents the dominant structural risk. Distribution runs through consolidated German OEM direct-sourcing programs that bypass traditional electronics distribution for strategic battery management and powertrain sockets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's MCU market reads as a late-cycle quality story justified by accelerating demand-shift toward ASIL-D certified 32-bit architectures in electric vehicle zonal gateways. Procurement authority consolidation around direct OEM engagement rewards qualification-heavy suppliers with durable pricing power.
For Market Incumbents: Lock in fab capacity reservations with TSMC and GlobalFoundries through multi-year automotive offtake agreements before allocation cycles tighten. Deepen captive SiC supply integration to insulate input cost volatility from constrained substrate markets. Defend against RISC-V open-architecture entrants by accelerating ARM ecosystem tool investments for safety-critical compiler certification. For New Entrants and Emerging Players: Capture industrial automation retrofit demand across Italian and French factory modernization programs where real-time Ethernet connectivity requirements outpace incumbent response timelines. Target Benelux secure-element integration for payment infrastructure as the most penetrable white-space segment. Pursue RISC-V core licensing partnerships with German Tier-1 pilot programs to bypass ARM royalty stacks in non-safety-critical zonal controllers. For Investors and Strategic Acquirers: Roll-up economics work for mixed-signal MCU specialists with industrial automation heritage because fragmented European factory equipment upgrade demand aggregates through system integrator networks lacking dominant platform suppliers. Five-to-ten year viability hinges on REACH-compliant packaging material transitions ahead of anticipated enforcement tightening. Watch ECHA candidate list expansion velocity as the critical inflection signal for packaging qualification spend acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Opens German OEM zonal gateway procurement to safety-critical socket suppliers under ECE R10 mandates. |
| RISC-V Architecture Licensing | Reduces ARM royalty exposure for German Tier-1 suppliers piloting open-instruction-set motor control customization. |
| REACH-Compliant Packaging Transition | Qualifies Austrian and German captive fab networks for 2026 enforcement tightening on lead-free solder and halogenated flame retardants. |
| Direct OEM Supply Agreement | Bypasses Arrow and Avnet channel compression through Stuttgart-based holding-company level negotiations for battery management MCUs. |
| Secure-Element Hardware Integration | Positions NXP-specialized suppliers for Benelux digital identity framework procurement under GDPR hardware security module extensions. |
Research Methodology
Bottom-up automotive and industrial automation modeling reconciled against top-down semiconductor fabrication capacity tracking forms the analytical core of this study. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, packaging house technical directors, and ECHA regulatory affairs specialists combined with secondary validation from SEC 10-K filings, IHS Markit vehicle production databases, ECHA candidate list publications, and customs trade data. Triangulation between demand-side socket counts and supply-side wafer allocation announcements ensures coherence across the analysis window.
Historical bit-width migration patterns and functional safety certification timelines anchor the projection framework. Segmentation dimensions span product architecture, application end-use, signal processing technology, and procurement authority concentration. CAGRs derive from regression analysis of electric vehicle platform ramp schedules correlated with MCU content-per-vehicle trajectories. Key forecast inputs include zonal gateway proliferation rates and REACH substance restriction implementation phasing.
Underlying measurement precision varies by segment; automotive electronics carry tighter precision than fragmented white goods retrofit demand. Forecasts reflect assumptions around TSMC capacity allocation continuity and EU AI Act classification outcomes for embedded inference engines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Power MOSFET Market
Semiconductor Devices
Asia-Pacific Semiconductor (Silicon) Intellectual Property Market
Semiconductor Devices
Japan Semiconductor Device in Consumer Industry Market
Semiconductor Devices
Die Spacer Market
Semiconductor Devices
Thin Wafer Market
Semiconductor Devices
Mosfet Power Transistors Market
Semiconductor Devices
Schottky Rectifiers Market
Semiconductor Devices
Flip Chip Market
Semiconductor Devices
Graphene Electronics Market
Semiconductor Devices
Temperature-Controlled Semiconductor Market
Semiconductor Devices
Global Bipolar Power Transistor Market
Semiconductor Devices
Multi-Chip Module (MCM) Market
Semiconductor Devices
Field-Effect Rectifier Diodes Market
Semiconductor Devices
Europe Power Transistor Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
IGBT Market