
 North America Silicon Carbide Wafers Market | 2026-2036
North America Silicon Carbide Wafers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Silicon Carbide Wafers Market Analytics
Domestic substrate producers in the United States is restructuring capacity allocation across the silicon carbide value chain. Wolfspeed, Inc. leverages its integrated materials-to-device footprint to control wafer supply for power semiconductor customers. Coherent Corp. anchors North American supply through specialized crystal growth operations serving defense and industrial buyers. SK siltron Co., Ltd. competes via its U.S.-based manufacturing presence focused on automotive-grade substrate volumes.
North America Silicon Carbide Wafers are synthetic crystalline substrates composed of silicon and carbon in a hexagonal polytype structure, typically manufactured through physical vapor transport or chemical vapor deposition methods, and engineered to withstand extreme temperatures, voltages, and switching frequencies in power electronics. The material serves as the foundational platform for fabricating metal-oxide-semiconductor field-effect transistors and Schottky diodes that convert and manage electrical energy in high-efficiency systems. Six-inch wafer formats currently dominate commercial production while eight-inch platforms represent the fastest-growing product category as equipment makers retool for larger-diameter processing. Electric vehicle applications command the deepest margin pools among end-use segments, with power electronics integration into onboard chargers and traction inverters driving substrate consumption. Crystal growth technology remains the most fiercely contested capability layer, with proprietary process yields determining competitive standing.
The U.S. Department of Energy, the EPA, and the IRA's advanced manufacturing production credit collectively shape North American silicon carbide wafer demand through domestic content requirements and clean energy procurement standards. The DOE's funding programs for semiconductor materials facilities and the EPA's tailpipe emissions rules directly accelerate automotive OEM demand for efficient power conversion components. Stakeholders must monitor how evolving federal semiconductor subsidies and state-level clean manufacturing incentives redistribute capacity investments across the region.
Market Dynamics
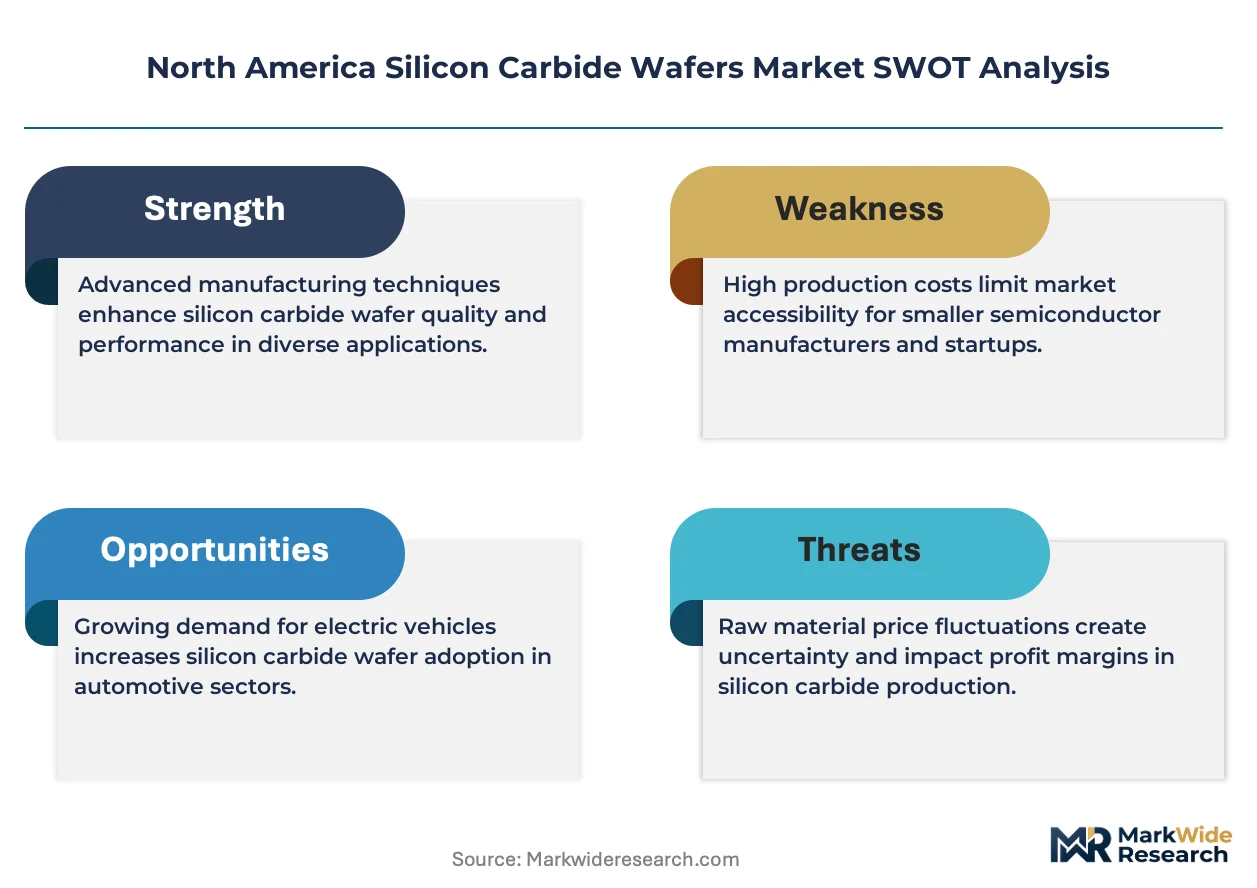
The transition from six-inch to eight-inch wafer formats is compressing capital efficiency thresholds across North American silicon carbide production lines, forcing substrate manufacturers to accelerate equipment retooling timelines ahead of automotive qualification cycles.
Growth Catalysts
- IRA Advanced Manufacturing Production Credit:The 45X tax credit is redirecting clean energy procurement toward domestic silicon carbide sources, with power electronics integrators restructuring supplier qualification criteria to capture incentive eligibility.
- Electric vehicle traction inverter integration:Automotive OEMs in the U.S. Midwest and Southeast are specifying silicon carbide substrates for next-generation powertrain architectures, creating pull-through demand for automotive-grade crystal growth capacity.
- Physical vapor transport yield improvements:Proprietary crystal growth process refinements are expanding usable wafer area per boule, reducing effective substrate cost per ampere of switching capacity for device manufacturers.
Market Restraints
- High-purity graphite supply concentration:Crucible and heater components for physical vapor transport reactors depend on limited qualified suppliers, exposing North American wafer producers to input cost volatility and delivery uncertainty.
- Epitaxial grade substrate qualification timelines:Automotive AEC-Q101 certification cycles extend 18-24 months, creating a structural lag between capacity investment and revenue recognition for new crystal growth lines.
- Gallium nitride on silicon substitution:Lower-voltage power applications below 650V increasingly specify GaN-on-Si devices, capping addressable market expansion for silicon carbide in consumer and industrial power supplies.
Strategic Opportunities
- Grid-scale energy storage inverters:Utility-scale battery installations across Texas and California are specifying silicon carbide power modules for megawatt-scale conversion efficiency, opening a demand vertical beyond automotive applications.
- DOE Semiconductor Materials Facilities funding:The department's dedicated substrate manufacturing grants are enabling brownfield expansion of domestic crystal growth operations without full capital burden on private balance sheets.
- 8-inch wafer equipment convergence:Tooling compatibility between silicon and silicon carbide processing is modularizing fab investments, allowing mixed-line utilization that improves capital intensity metrics for integrated device manufacturers.
Industry Challenges
- Defect engineering talent scarcity:Specialized expertise in micropipe density reduction and basal plane dislocation control remains concentrated among a small cohort of crystal growth engineers, constraining process transfer and scale-up velocity.
- Legacy silicon power module qualification inertia:Tier-1 automotive suppliers maintain active silicon IGBT supply agreements with penalty clauses, slowing silicon carbide substitution even where technical superiority is established.
- Cross-facility process standardization:Substrate producers struggle to replicate proprietary growth recipes across multiple reactor installations, creating yield variance that complicates customer volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Silicon Carbide Wafers Market |
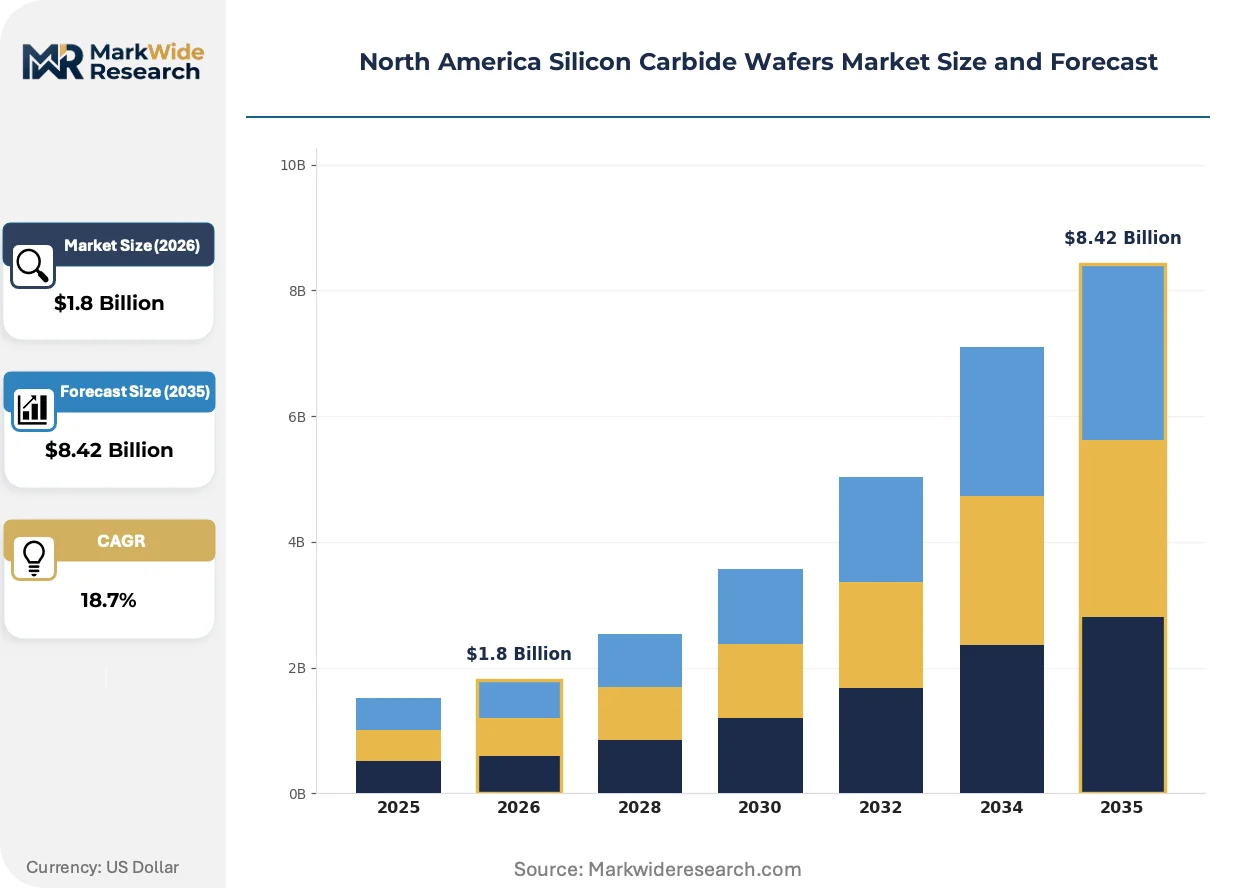
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 4-Inch Wafers, 6-Inch Wafers, 8-Inch Wafers, 10-Inch Wafers Application: Power Electronics, Electric Vehicles, LED Lighting, Solar Inverters End Use: Telecommunications, Consumer Electronics, Automotive, Aerospace Technology: Wafer Fabrication, Crystal Growth, Epilayer Technology, Substrate Technology |
| Companies Covered | Wolfspeed, Inc., Coherent Corp., SK siltron Co., Ltd., Entegris, STMicroelectronics, Infineon Technologies AG, ROHM Co., Ltd., MTI Corporation, American Elements, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Silicon Carbide Wafers Market Evolving Landscape
Wafer processing architectures are fragmenting across equipment generations as the industry bifurcates between optimized six-inch volume lines and experimental eight-inch pilot operations, creating divergent competitive capability stacks.
Hot-wall physical vapor transport reactor designs are modularizing substrate manufacturing footprints. These systems enable multi-chamber configurations that isolate thermal zones for improved boule uniformity. Automotive power module manufacturers are qualifying hot-wall output for traction inverter programs at accelerated timelines. The technology is compressing capital requirements per equivalent wafer output by enabling smaller-batch production with higher yield consistency.
EPA vehicle emissions standards are mandating powertrain efficiency gains that silicon-based switches cannot deliver. The regulatory trajectory is eliminating compliance pathways for conventional power electronics in 2027 and beyond model years. Heavy-duty truck OEMs operating in California and the Pacific Northwest are responding with accelerated silicon carbide inverter sourcing to meet fleet-average requirements.
Automotive OEMs are consolidating power electronics procurement through captive semiconductor divisions rather than tier-1 module suppliers. Ford, GM, and Stellantis are building internal substrate qualification teams that bypass traditional distribution channels. This vertical integration is most visible in Michigan and Ohio, where OEM engineering centers are co-locating with wafer supplier technical support facilities to compress development cycles.
North America Silicon Carbide Wafers Market Segmentation
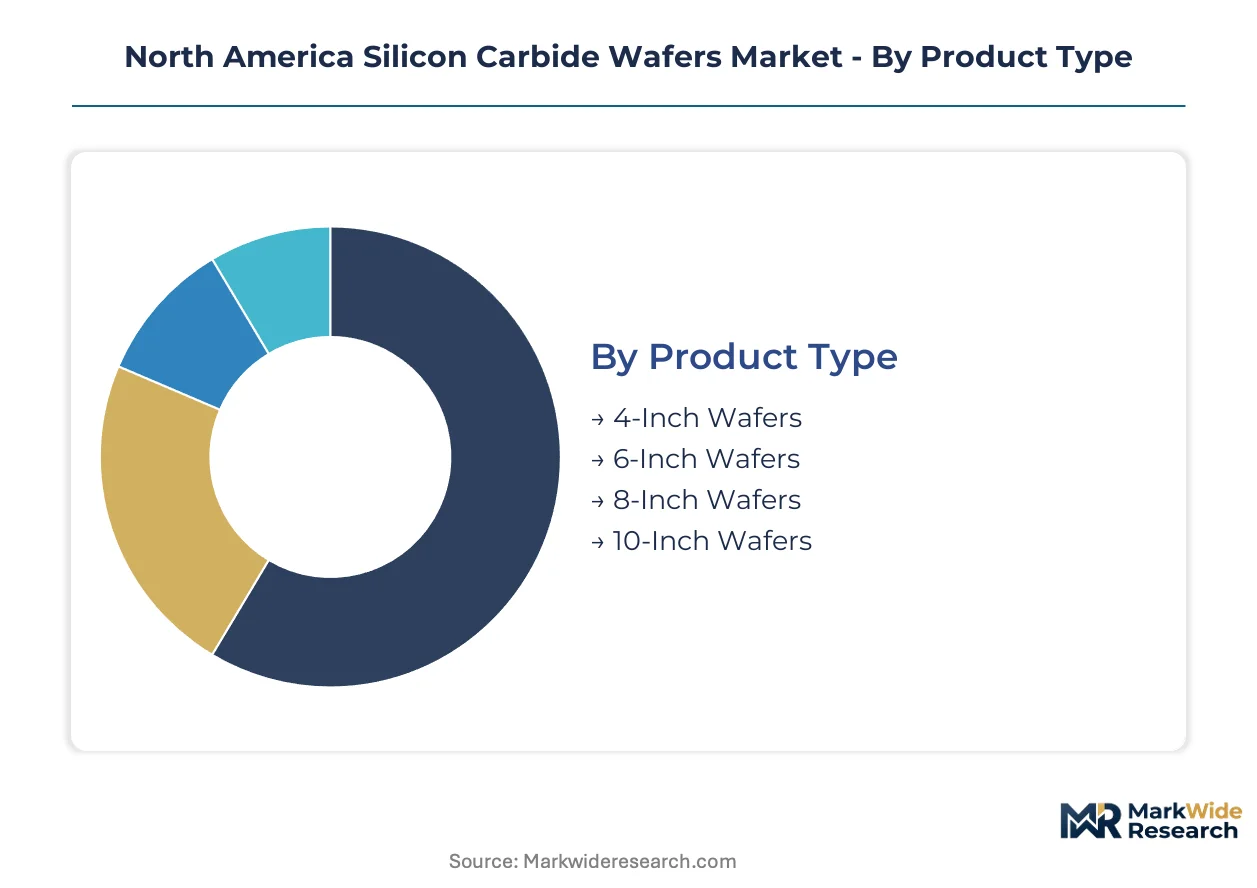
Silicon carbide wafer segmentation in North America reflects divergent manufacturing maturity across wafer diameters and sharply contrasting integration requirements between discrete component and embedded power module applications. Procurement patterns split between established automotive qualification programs and emerging grid infrastructure deployments.
Product Type:
Wafer diameter selection determines integration depth, with smaller formats serving standalone discrete devices and larger platforms enabling complex multi-die power modules.
- 6-Inch Wafers:The hexagonal polytype substrates currently anchor commercial production volumes across North American fabs. Midwest automotive OEMs specify this format for traction inverter programs where device count per module remains moderate and qualification heritage is strongest.
- 8-Inch Wafers:Expanding to 200mm enables higher die-per-wafer yields for integrated power stages. Southeast semiconductor clusters are retooling for this format as equipment compatibility with silicon processing lines reduces capital intensity for mixed-fab operations.
- 4-Inch Wafers:Legacy diameter serving specialized defense and industrial applications with low volume requirements.
- 10-Inch Wafers:Experimental format in early-stage pilot production with unproven crystal growth economics.
Six-inch formats lead volumes today; eight-inch platforms are gaining share fastest.
Application:
Application segments distribute across cost tiers, from premium automotive powertrain systems to standard-grade industrial conversion equipment.
- Power Electronics:Metal-oxide-semiconductor field-effect transistors and Schottky diodes for high-frequency switching. Texas and California utility-scale battery installations are specifying silicon carbide modules for megawatt-scale inverters.
- Electric Vehicles:Traction inverters and onboard chargers demanding automotive-grade substrate qualification. EPA tailpipe emissions standards are eliminating compliance pathways for silicon-based switches in heavy-duty truck fleets.
- Solar Inverters:Residential and commercial photovoltaic string inverters with moderate voltage requirements.
- LED Lighting:Substrate material for high-brightness LED epitaxial growth, a declining volume segment.
Electric vehicle applications command premium margins; power electronics for grid storage is climbing the fastest.
End Use:
End-use concentration varies by customer type, with automotive OEMs consolidating procurement through captive semiconductor divisions.
- Automotive:Powertrain electrification programs specifying AEC-Q101 qualified substrates. Ford, GM, and Stellantis technical centers in Michigan and Ohio are co-locating with wafer supplier engineering support.
- Aerospace:Satellite power systems and aircraft electrical distribution requiring radiation-hardened devices. Defense procurement prioritizes domestic crystal growth provenance.
- Telecommunications:Base station power supplies and data center conversion equipment.
- Consumer Electronics:Premium laptop adapters and mobile fast-charging accessories facing substitution pressure from gallium nitride on silicon.
Automotive end use dominates revenue; aerospace requirements are expanding most quickly on defense spending priorities.
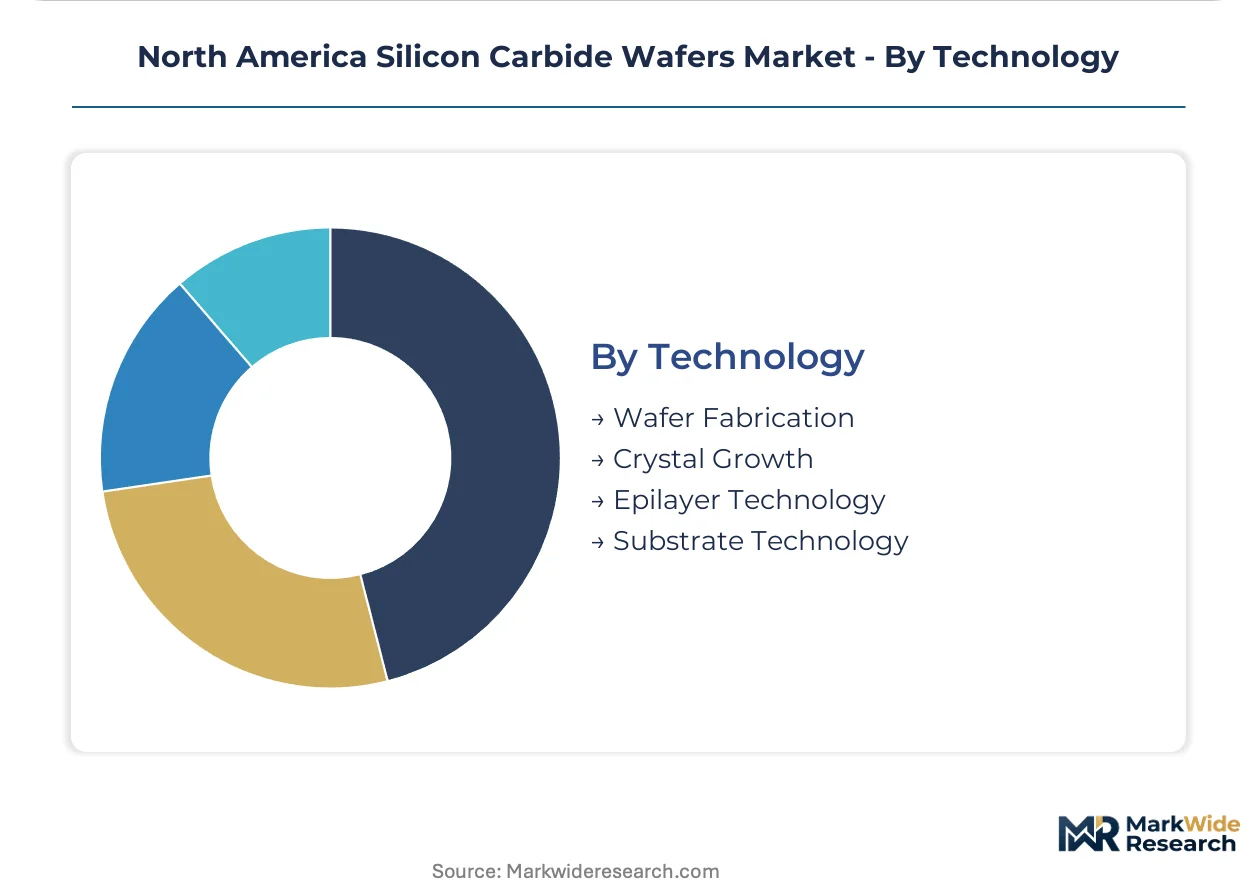
Technology:
Technology segments align with supply concentration, where proprietary crystal growth capabilities determine competitive standing.
- Crystal Growth:Physical vapor transport reactor operation producing silicon carbide boules. Hot-wall reactor designs are modularizing manufacturing footprints and compressing capital requirements per equivalent wafer output.
- Wafer Fabrication:Dicing, lapping, polishing, and cleaning operations converting boules into finished substrates. Process standardization across multiple reactor installations remains a persistent yield challenge.
- Epilayer Technology:Chemical vapor deposition of defect-controlled active layers on substrate surfaces.
- Substrate Technology:Thermal management and packaging integration for device mounting.
Crystal growth commands the steepest capability premiums; wafer fabrication is seeing the fastest process automation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic content requirements under the IRA are compressing cost-of-compliance gaps between U.S.-based and imported silicon carbide substrates, redirecting automotive procurement toward North American crystal growth operations.
United States
Midwest automotive OEMs and Southeast semiconductor clusters are co-locating engineering centers to compress substrate qualification timelines. The DOE's Semiconductor Materials Facilities funding accelerates brownfield crystal growth expansion in Michigan and Ohio. Wolfspeed's integrated materials-to-device footprint in North Carolina anchors domestic boule production for power electronics integrators.
Canada
Ontario-based power module manufacturers are qualifying silicon carbide substrates for heavy-duty truck electrification programs serving cross-border fleets. Health Canada's environmental assessments align with EPA tailpipe standards, eliminating regulatory friction for U.S.-spec inverter imports. Quebec's emerging clean technology corridor is attracting pilot-scale crystal growth operations targeting grid-scale storage applications.
Mexico
Nuevo León's automotive assembly plants are integrating silicon carbide traction inverters for export-compliant EV production under USMCA rules of origin. The country's national energy regulator is streamlining interconnection standards for utility-scale battery installations specifying domestic power conversion equipment. Bajío Region manufacturing parks are positioning for tier-2 substrate processing to serve U.S. fab demand.
North America Silicon Carbide Wafers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized defense and industrial qualification pathways outside automotive AEC-Q101 cycles. The North American silicon carbide wafer structure concentrates around three domestic crystal growth operations with differentiated materials-to-device integration depths. Integrated substrate-device manufacturers, specialized boule suppliers, and foreign-owned U.S. manufacturing affiliates represent the dominant strategic archetypes. Capacity expansion and backward integration into high-purity graphite supply chains constitute the primary competitive moves reshaping procurement relationships.
Among integrated materials-to-device specialists, Wolfspeed, Inc. exemplifies the captive supply archetype controlling wafer allocation for power semiconductor customers. Coherent Corp. anchors specialized crystal growth operations serving defense and industrial buyers with differentiated qualification heritage. SK siltron Co., Ltd. occupies a position within the foreign-owned U.S. manufacturing tier, focusing automotive-grade substrate volumes through its American production presence.
| Leading Market Players |
|---|
| Wolfspeed, Inc. |
| Coherent Corp. |
| SK siltron Co., Ltd. |
| Entegris |
| STMicroelectronics |
| Infineon Technologies AG |
| ROHM Co., Ltd. |
| MTI Corporation |
| American Elements |
| Others |
Value Network & Pricing Analysis
Automotive AEC-Q101 qualification tiers create a sharp bifurcation between premium epitaxial-grade substrates and standard industrial formats, with this certification ladder simultaneously compressing margins at the entry level and concentrating pricing power among qualified suppliers serving Midwest OEM traction inverter programs.
Pricing Analysis
Distributor margins absorb the steepest compression as Wolfspeed and Coherent pursue direct qualification relationships with Ford, GM, and Stellantis engineering centers. Three-tier pricing structure across automotive-grade, industrial-grade, and research-grade wafers separates buyers by certification burden and volume commitment. Pricing pressure stems from gallium nitride encroachment below 650V applications, forcing silicon carbide producers to defend position through faster automotive qualification cycles. Tier-1 automotive suppliers exhibit highest price sensitivity due to active silicon IGBT penalty clauses, while defense buyers accept premiums for domestic crystal growth provenance.
Supply Chain Analysis
Regional distribution centers in Michigan and Ohio coordinate hub-and-spoke delivery patterns to automotive OEM engineering centers, compressing qualification sample turnaround times. High-purity graphite crucibles and heater components draw from concentrated qualified suppliers in Japan and Germany, creating single-source vulnerability for physical vapor transport reactor operations. Tariff exposure runs through USMCA rules-of-origin verification for Mexican assembly integration. Distribution runs through captive semiconductor divisions at major OEMs rather than traditional tier-1 module supplier channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America silicon carbide wafers function as a stable compounder anchored by EPA tailpipe standards that eliminate compliance pathways for silicon-based power electronics across heavy-duty truck fleets.
For Market Incumbents: Anticipate gallium nitride substitution pressure below 650V by accelerating eight-inch wafer qualification timelines ahead of automotive model year cycles. Defensive consolidation of high-purity graphite supply agreements in Japan and Germany reduces input cost volatility exposure. Backward integration into hot-wall physical vapor transport reactor manufacturing compresses capital intensity per equivalent wafer output. For New Entrants and Emerging Players: Grid-scale energy storage inverter manufacturers in Texas and California represent an underserved buyer archetype with shorter qualification cycles than automotive AEC-Q101 programs. Defense radiation-hardened device specifications offer white-space entry outside automotive certification inertia. Target Quebec's emerging clean technology corridor for pilot-scale crystal growth operations serving utility-scale battery installations. For Investors and Strategic Acquirers: Consolidation pressure builds where proprietary crystal growth yields remain concentrated among a small cohort of defect engineering specialists with micropipe density control expertise. Long-term viability favors integrated materials-to-device footprints with captive automotive qualification heritage. Watch for inflection when eight-inch wafer equipment convergence enables mixed-line silicon and silicon carbide processing at Southeast semiconductor clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Wall PVT Reactor Deployment | Multi-chamber thermal zone isolation improves boule uniformity for automotive qualification. |
| Eight-Inch Wafer Format Transition | Equipment compatibility with silicon processing reduces capital intensity at mixed fabs. |
| Direct OEM Engineering Co-Location | Michigan and Ohio technical centers compress substrate qualification cycles with supplier support. |
| High-Purity Graphite Supply Anchoring | Long-term agreements with Japanese and German crucible suppliers mitigate input cost volatility. |
| Grid-Scale Storage Inverter Qualification | Texas and California utility battery specifications open demand vertical beyond automotive applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with crystal growth engineers, automotive power electronics procurement leads, and utility-scale inverter program managers alongside secondary validation through DOE funding disclosures, EPA regulatory filings, and SEC 10-K materials from listed substrate producers. Bottom-up wafer volume estimates by diameter format and application segment triangulated against top-down automotive electrification content projections and grid-scale battery deployment pipelines.
Segment-weighting approaches distributed value and volume across wafer diameter, application category, and end-use concentration dimensions over the projection horizon. CAGRs derived from equipment installation timelines, automotive model year qualification cycles, and federal incentive program trajectories. Crystal growth yield improvement curves and eight-inch equipment retooling schedules served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; automotive-grade substrate forecasts carry tighter precision than experimental ten-inch pilot production estimates. Forecast outputs reflect assumptions around IRA credit continuity, EPA regulatory trajectory, and graphite supply chain stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Rad-Hard Mosfets Market
Semiconductor Devices
China Semiconductor Device Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
Silicon Carbide Mosfets Market
Semiconductor Devices
AIN DBC Ceramic Substrate Market
Semiconductor Devices
Asia-Pacific Power Transistor Market
Semiconductor Devices
Japan Semiconductor Device Market
Semiconductor Devices
Dual Voltage Comparator Market
Semiconductor Devices
Global Vacuum Capacitors Market
Semiconductor Devices
Global ASIC Bitcoin Mining Hardware Market
Semiconductor Devices
Silicon Wafer Market
Semiconductor Devices
Leadframes Market
Semiconductor Devices
Chip Equalizers Market
Semiconductor Devices
Japan Power Transistor Market
Semiconductor Devices
3D TSV Device Market