

AC Voltage Transducer Market Size, Share, and Industry Trends Forecast 2026-2036
AC Voltage Transducer Market Insights
A widening capability gap between vertically integrated multinationals and component specialists is redrawing competitive boundaries in the AC Voltage Transducer Market. ABB leverages captive semiconductor fabrication to control sensor accuracy tolerances across its product portfolio. Siemens anchors its position through deep integration with grid automation software ecosystems. LEM specializes in Hall Effect architectures for high-frequency switching applications, occupying a defensible niche in renewable energy inverters.
An AC voltage transducer converts alternating current potential into a proportional standardized output signal, typically 4-20 mA or 0-10 V, using resistive dividers, isolation amplifiers, or magnetic modulation to achieve galvanic separation and measurement integrity. Digital output variants with embedded Modbus or IEC 61850 protocol stacks are displacing legacy analog interfaces in substation automation, while fiber optic transducers command premium positioning in electromagnetic interference-intensive environments such as railway traction systems and steel melting furnaces. Hall Effect segments sustain the fastest expansion trajectory, driven by non-contact measurement requirements in photovoltaic string monitoring and electric vehicle charging infrastructure.
The US Federal Energy Regulatory Commission mandates synchronized phasor measurement standards that dictate transducer bandwidth and reporting latency specifications for bulk power system operators. China's National Energy Administration enforces GB/T standards for smart meter interoperability, directly shaping procurement criteria for domestic grid equipment tenders. India's Central Electricity Authority technical regulations for grid connectivity require harmonic distortion monitoring capabilities that filter market access for non-compliant suppliers. Stakeholders must calibrate R&D roadmaps against evolving interoperability mandates rather than static product specifications.
Market Dynamics
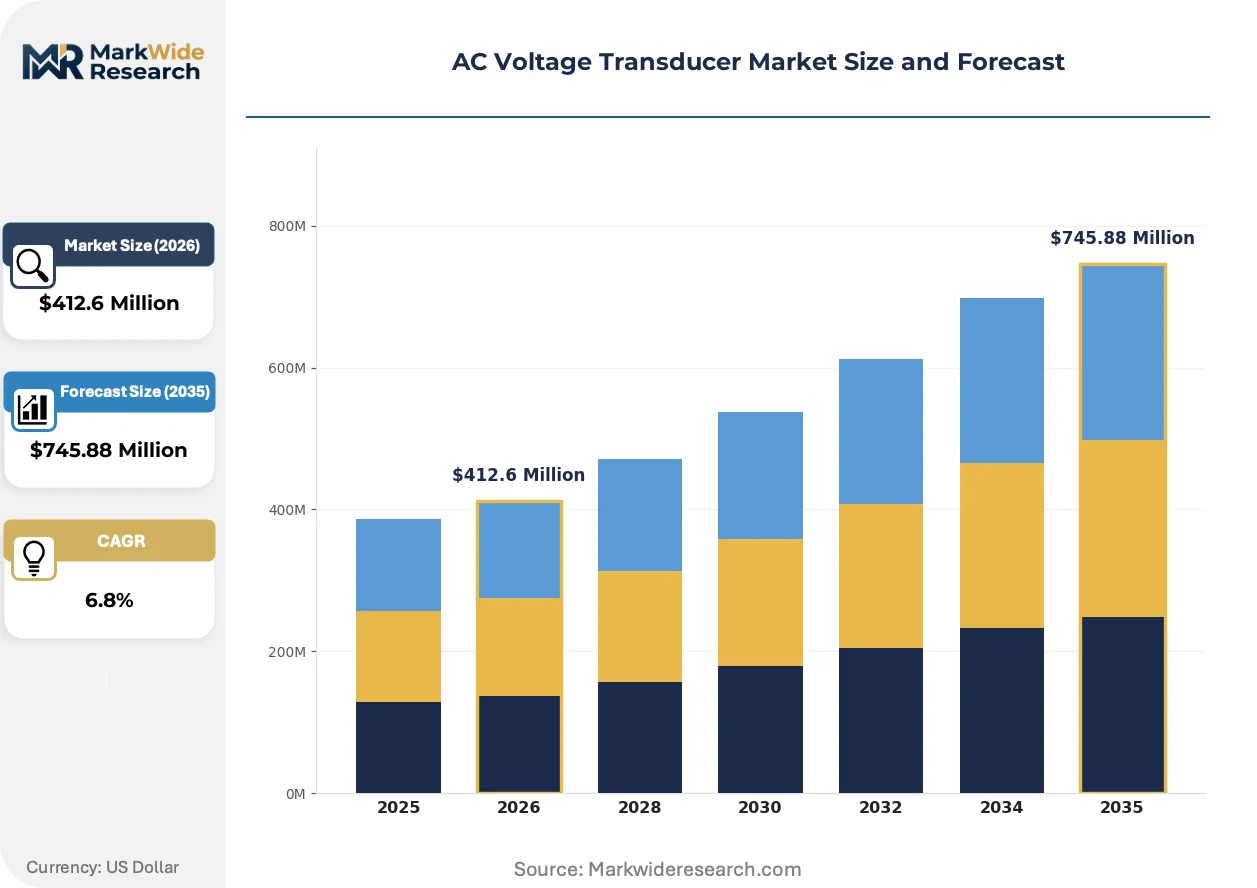
The AC Voltage Transducer Market is undergoing structural recalibration as IEC 61850 digital protocol adoption compresses product lifecycles and forces simultaneous hardware and firmware development cycles. This interoperability mandate is redrawing supplier capabilities.
Growth Catalysts
- Smart Grid Mandates:China's National Energy Administration enforces GB/T standards for smart meter interoperability, directly expanding procurement volumes for domestic grid equipment tenders and accelerating replacement cycles.
- Photovoltaic String Monitoring:Hall Effect architectures are capturing non-contact measurement requirements in utility-scale solar installations, with inverter manufacturers specifying galvanically isolated voltage sensing for arc fault detection.
- FERC Synchrophasor Standards:The US Federal Energy Regulatory Commission mandates synchronized phasor measurement specifications that dictate bandwidth and reporting latency requirements for bulk power system operators, forcing equipment upgrades.
Market Restraints
- Semiconductor Supply Concentration:Precision isolation amplifiers depend on captive semiconductor fabrication capacity concentrated in East Asian foundries, exposing lead time volatility for protection-grade transducers.
- Copper and Magnetic Core Costs:Resistive divider and magnetic modulation architectures face input cost pressure from copper price fluctuations and ferrite core availability constraints.
- Optical Transducer Substitution:Fiber optic voltage transducers command premium positioning in electromagnetic interference-intensive environments, compressing margins for conventional electromagnetic alternatives in steel melting and railway traction applications.
Strategic Opportunities
- India Grid Connectivity Expansion:The Central Electricity Authority technical regulations for grid connectivity require harmonic distortion monitoring capabilities, creating compliance-driven demand for multi-function transducers in transmission infrastructure.
- Electric Vehicle Charging Infrastructure:DC fast charging stations require isolated voltage sensing for power conversion stages, with Hall Effect segments capturing design wins in 350kW and above charging modules.
- EU F-Gas Regulation Phase-Down:The European Union's fluorinated gas regulation is accelerating substitution of gas-insulated switchgear with solid-state alternatives, expanding addressable market for compact voltage sensing in medium-voltage distribution.
Industry Challenges
- IEC 61850 Certification Timelines:Protection-grade transducers require interoperability certification against evolving protocol editions, extending product validation cycles and compressing revenue recognition windows.
- Embedded Firmware Talent Scarcity:Digital output variants require simultaneous analog design and embedded software engineering capabilities, with limited cross-trained personnel available for protocol stack integration.
- Legacy Substation Integration Complexity:Analog-to-digital interface migration demands backward compatibility with existing SCADA architectures, forcing dual-output product configurations that increase bill-of-materials complexity.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AC Voltage Transducer Market Trends and Innovations
Digital output protocols are compressing product differentiation cycles while electromagnetic interference immunity requirements are elevating material specifications. These forces are simultaneously enabling new entrants and eroding incumbent hardware advantages.
Silicon carbide isolation amplifiers are fragmenting the traditional magnetic modulation segment by enabling higher switching frequency measurement with reduced thermal drift. Railway traction system OEMs in Germany and Japan are specifying SiC-based voltage sensing for regenerative braking energy recovery circuits. This technology is fragmenting established supplier relationships as semiconductor vendors bypass traditional electromagnetic component specialists.
The EU CSRD sustainability reporting mandate is forcing voltage transducer manufacturers to document embodied carbon and supply chain due diligence across tier-two semiconductor suppliers. Industrial equipment OEMs serving European utilities are now requiring lifecycle assessment data as a procurement gate. Protection-grade device categories face the steepest documentation burden, with mid-tier suppliers struggling to meet verification timelines.
Specifying engineers are consolidating vendor relationships around integrated sensor-automation platform providers rather than discrete component suppliers. Grid automation software ecosystems from ABB and Siemens are absorbing transducer procurement decisions through pre-certified compatibility lists. This concentration is most visible in Chinese state grid tenders, where interoperability certification with domestic SCADA platforms determines short-list eligibility.
AC Voltage Transducer Market Segmentation
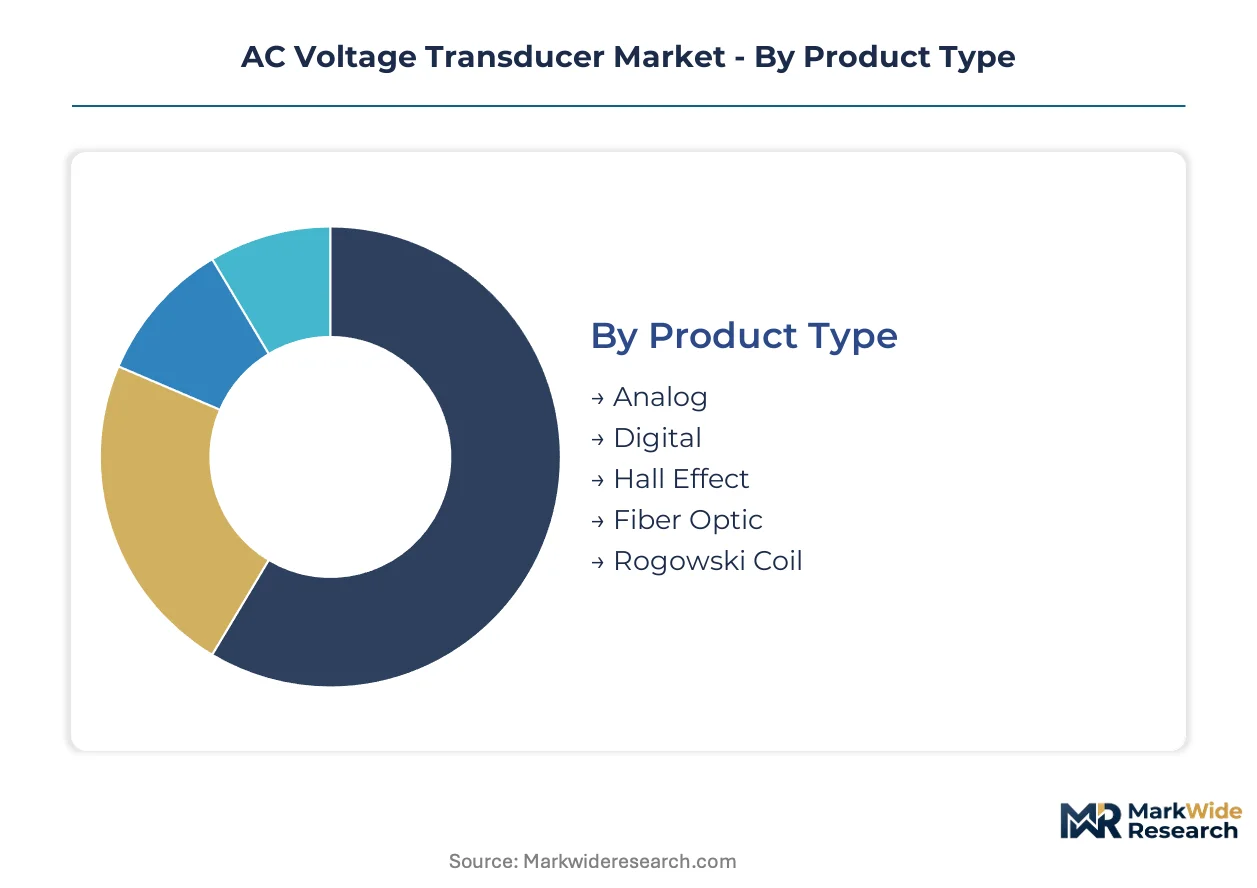
AC voltage transducer procurement patterns diverge sharply across product architectures, with protection-grade devices demanding certified interoperability while process monitoring applications prioritize cost efficiency. Segment boundaries are blurring as digital protocol adoption forces simultaneous hardware and firmware development cycles.
Product Type:
Domestic procurement concentrates on analog and resistive divider architectures in mature grid infrastructure markets, while Hall Effect and fiber optic variants drive export-led manufacturing from specialized component hubs in Germany and Japan.
- Analog:Resistive divider and isolation amplifier architectures deliver 4-20 mA or 0-10 V outputs with established calibration traceability. Demand concentrates in US utility substation retrofits where FERC synchrophasor mandates force bandwidth upgrades without full digital replacement.
- Hall Effect:Non-contact magnetic field sensing enables galvanic isolation without magnetic core saturation limitations. Photovoltaic string monitoring in utility-scale solar installations across Spain and Australia specifies these devices for arc fault detection compliance.
- Digital:Embedded IEC 61850 or Modbus protocol stacks enable direct substation automation integration. Chinese state grid tenders require GB/T standard compatibility.
- Fiber Optic:Complete electromagnetic immunity suits steel melting furnaces and railway traction environments. German and Japanese OEMs specify these for regenerative braking circuits.
- Rogowski Coil:Air-core toroidal winding enables flexible installation around high-current busbars. Industrial motor protection systems in South Korea deploy these for retrofit applications.
Analog architectures command the established base across legacy infrastructure. The steepest expansion runs through Hall Effect segments in renewable energy inverter integration.
Technology:
Cost tier stratification separates precision-grade optical and piezoelectric methods from commodity resistive approaches, with inductive architectures occupying the mid-tier for protection applications.
- Resistive:Voltage divider networks with precision thin-film resistors achieve basic accuracy for panel-mounted instrumentation. Manufacturing plants in Mexico and Vietnam specify these for cost-sensitive motor control centers.
- Inductive:Magnetic modulation through precision-wound transformers enables high isolation ratings with moderate bandwidth. Electric utilities in India deploy these for distribution transformer monitoring under CEA grid connectivity regulations.
- Capacitive:Dielectric isolation barriers suit high dv/dt environments in variable frequency drives. Industrial automation OEMs in Italy integrate these for compact motor drive designs.
- Piezoelectric:Crystal-based voltage sensing enables extreme temperature operation. Aerospace manufacturers in France specify these for engine monitoring systems.
- Optical:Pockels cell or Kerr effect modulation delivers complete galvanic isolation with nanosecond response. Research laboratories in Switzerland deploy these for pulsed power measurement.
Resistive methods anchor volume production for standard industrial applications. Optical technologies are climbing the fastest in electromagnetic interference-intensive environments.
Application:
Volume concentration tracks grid modernization investment cycles, with renewable energy systems and power monitoring commanding multi-year procurement commitments while railway and aerospace segments operate on project-specific tender timelines.
- Power Monitoring:Substation automation and distribution network visibility systems require synchronized measurement across voltage classes. US bulk power operators under FERC Order 881 mandate these for transmission congestion management.
- Renewable Energy Systems:Photovoltaic inverters and wind turbine power converters need isolated sensing for maximum power point tracking. Chinese inverter manufacturers specify Hall Effect devices for string-level monitoring.
- Industrial Automation:Motor drives and uninterruptible power supplies demand compact sensing for closed-loop control. German automotive component plants integrate these into robotic welding lines.
- Railway Signaling:Traction power supply monitoring requires immunity to 25 kV overhead line interference. Japanese Shinkansen expansion projects specify fiber optic transducers.
- Aerospace Systems:Flight-qualified devices must survive altitude, vibration, and temperature extremes. Brazilian regional jet programs source these from certified suppliers.
Power monitoring applications represent the largest installed base. Renewable energy systems are gaining share fastest as capacity additions accelerate.
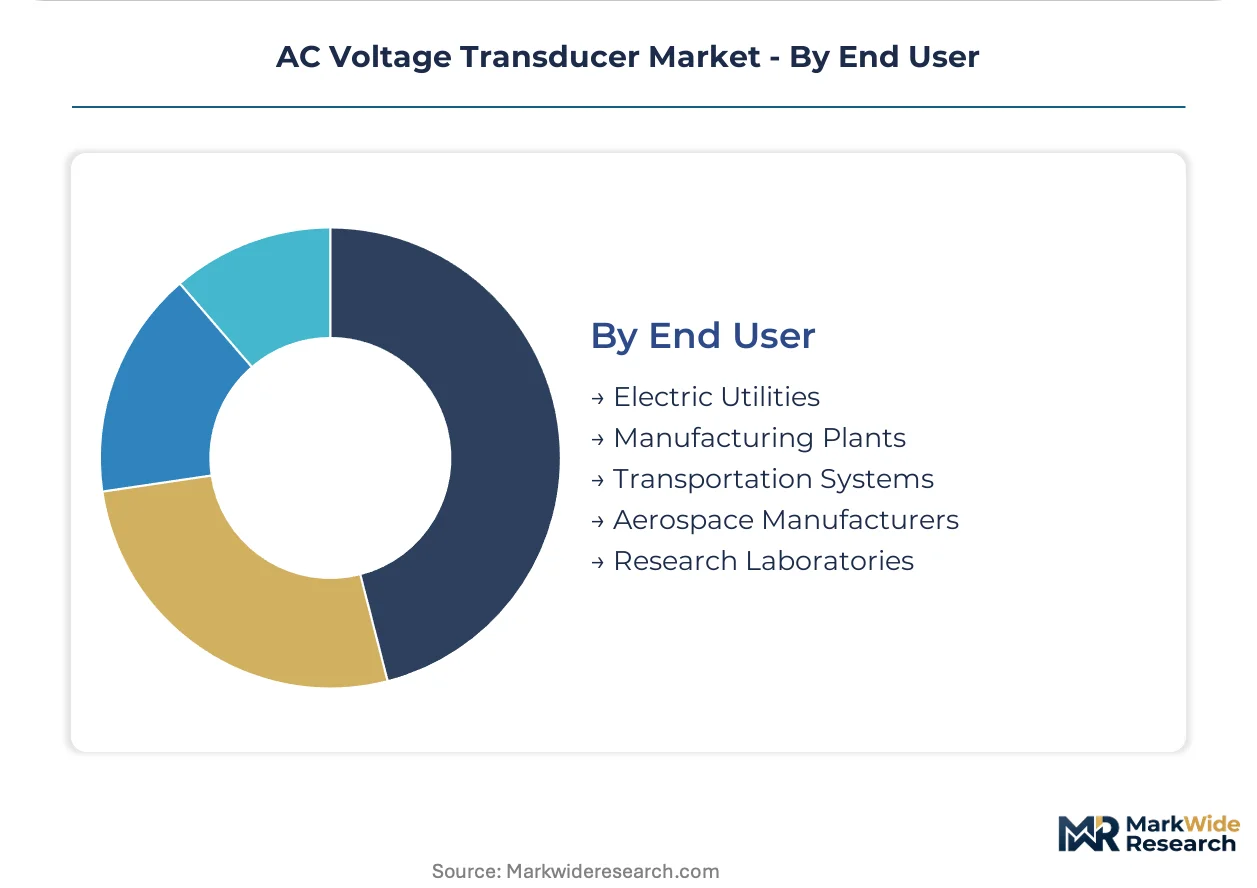
End User:
Customer type determines specification rigor, with electric utilities enforcing certified interoperability while manufacturing plants prioritize total cost of ownership and availability.
- Electric Utilities:Transmission and distribution operators mandate IEC 61850 Edition 2.1 compliance with third-party interoperability certification. State Grid Corporation of China procurement volumes dominate regional tender activity.
- Manufacturing Plants:Process industries and discrete manufacturing require maintenance-friendly designs with standard analog outputs. Petrochemical complexes in Saudi Arabia specify these for critical motor protection.
- Transportation Systems:Metro electrification and electric bus depot charging infrastructure need ruggedized sensing. Indian Railways deploys these for 25 kV AC traction substation upgrades.
- Aerospace Manufacturers:DO-160G environmental qualification and AS9100 traceability requirements filter supplier pools. Canadian regional aircraft programs source from pre-qualified component vendors.
- Research Laboratories:Plasma physics and pulsed power experiments demand nanosecond response and extreme voltage ratings. National fusion research facilities in South Korea procure custom-specified optical systems.
Electric utilities anchor procurement volume through multi-year framework agreements. Transportation systems are expanding most quickly as railway electrification and EV infrastructure investments intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys AC voltage transducers for state-directed smart grid buildouts, while the United States concentrates procurement on FERC-mandated synchrophasor upgrades. Germany and Japan emphasize railway traction and industrial automation applications.
China
State Grid Corporation tenders dominate procurement volumes for digital-output transducers with embedded GB/T protocol stacks. The National Energy Administration enforces smart meter interoperability standards that filter supplier eligibility. Manufacturing clusters in Jiangsu and Zhejiang provinces export Hall Effect devices for photovoltaic string monitoring systems.
United States
Bulk power operators under FERC Order 881 mandate synchronized phasor measurement capabilities for transmission congestion management. The Federal Energy Regulatory Commission dictates bandwidth and reporting latency specifications that force equipment refresh cycles. Texas and California utilities anchor demand through multi-year framework agreements for substation automation.
Germany
Railway traction OEMs specify fiber optic transducers for regenerative braking energy recovery in electrified corridors. The EU F-Gas Regulation accelerates substitution of gas-insulated switchgear with solid-state alternatives requiring compact voltage sensing. Industrial automation clusters in Bavaria and Baden-Württemberg integrate capacitive isolation devices into motor drive systems.
India
The Central Electricity Authority mandates harmonic distortion monitoring capabilities for grid connectivity compliance, filtering market access for transmission infrastructure suppliers. State electricity boards in Maharashtra and Gujarat tender for distribution transformer monitoring equipment. Domestic manufacturing in Tamil Nadu serves cost-sensitive industrial motor protection applications.
Japan
Shinkansen expansion projects specify fiber optic voltage transducers for immunity to 25 kV overhead line interference in traction power supply monitoring. METI industrial standards shape procurement criteria for precision isolation amplifiers. Nagoya and Osaka industrial corridors concentrate demand for compact sensing in robotic welding and automotive component production lines.
AC Voltage Transducer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the AC voltage transducer market. Vertically integrated multinationals control captive semiconductor fabrication for sensor accuracy tolerances, while component specialists occupy defensible niches in high-frequency switching applications. Three archetypes define competitive positioning: grid automation platform integrators, Hall Effect architecture specialists, and precision magnetic modulation providers. Capacity expansion and strategic partnerships represent the dominant competitive moves as IEC 61850 certification timelines compress product development windows.
Among Swiss and German industrial conglomerates, ABB and Siemens exemplify platform-integrated positioning through grid automation software ecosystems. LEM represents the specialist archetype, occupying a defensible niche in Hall Effect architectures for renewable energy inverter applications. These three companies anchor the competitive structure while mid-tier suppliers struggle with embedded firmware talent scarcity and protocol stack integration requirements.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Schneider Electric |
| Honeywell International |
| Eaton |
| Phoenix Contact |
| Analog Devices |
| LEM |
| CR Magnetics |
| Others |
Pricing and Supply Chain Analysis
Long-term framework agreements with State Grid Corporation of China lock in supply access for protection-grade transducers while anchoring price visibility across multi-year procurement cycles. These contracts insulate tier-one suppliers from spot-market volatility in precision isolation amplifiers while compressing margins for non-preferred vendors competing on price alone.
Pricing Analysis
After-sales service contracts and firmware update subscriptions now drive lifetime value more than initial hardware sales. Three-tier pricing structure across IEC 61850-certified protection grade, industrial process monitoring, and basic panel instrumentation segments reflects certification burden and bandwidth specifications. Cost compression in analog resistive divider architectures intensifies as Chinese manufacturers scale Hall Effect production for photovoltaic string monitoring. Electric utilities exhibit lowest price sensitivity due to interoperability mandates, while industrial motor control centers in Mexico and Vietnam prioritize total cost of ownership.
Supply Chain Analysis
Strategic stockpiling of ferrite cores and precision-wound magnetic components characterizes procurement behavior among Japanese and German OEMs serving railway traction applications. Captive semiconductor fabrication capacity concentrates in Taiwan, South Korea, and China for isolation amplifier die production. Copper price volatility and rare earth magnet availability constraints feed from mining output fluctuations in Chile and the Democratic Republic of Congo. Single-source vulnerability in East Asian foundry capacity exposes lead time volatility for protection-grade devices. Distribution runs through authorized industrial distributors and direct OEM relationships rather than commodity channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AC Voltage Transducer Market sits in early-cycle expansion as IEC 61850 protocol adoption forces simultaneous hardware and firmware replacement waves across installed base infrastructure. Grid modernization mandates in China and FERC synchrophasor standards in the United States create durable procurement tailwinds.
For Market Incumbents: Fortify protocol stack integration capabilities through embedded firmware talent acquisition in Bangalore and Shenzhen talent markets. Captive semiconductor fabrication for precision isolation amplifiers defends sensor accuracy tolerances against emerging SiC-based substitutes from semiconductor vendors bypassing traditional electromagnetic specialists. Deepen certification investment for evolving IEC 61850 Edition 2.1 requirements to maintain short-list eligibility in Chinese state grid tenders.
For New Entrants and Emerging Players: GB/T standard fast-track certification for digital-output transducers unlocks procurement access to Chinese distribution transformer monitoring tenders where incumbent relationships remain less entrenched. White-space concentration sits in Hall Effect architectures for 350kW-plus electric vehicle charging modules and harmonic distortion monitoring for Indian transmission infrastructure under CEA regulations. Direct engagement with inverter manufacturers for photovoltaic string monitoring bypasses utility procurement complexity.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier specialists with demonstrated IEC 61850 certification velocity and embedded software engineering benches rather than pure hardware legacy players. Long-term viability over the next decade hinges on simultaneous analog and digital design capabilities as product lifecycles compress. Acquisition targets should show protocol stack integration expertise and renewable energy inverter design wins. The signal to watch is certification backlog duration as a proxy for competitive positioning velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| IEC 61850 Certification Investment | State Grid Corporation tenders require GB/T protocol compatibility for short-list eligibility. |
| Backward Integration into Semiconductor Fabrication | Captive isolation amplifier production controls sensor accuracy tolerances against SiC substitutes. |
| Hall Effect Capacity Expansion | Photovoltaic string monitoring demand in Spain and Australia outstrips current specialist supply. |
| Embedded Firmware Talent Acquisition | Protocol stack integration scarcity compresses product development windows for digital variants. |
| Joint Venture with Railway Traction OEMs | Shinkansen and German electrified corridor projects specify fiber optic transducers for EMI immunity. |
Research Methodology
The analysis maps product architectures across analog, Hall Effect, digital, and fiber optic segments, each validated through substation automation engineers, inverter manufacturer procurement leads, railway traction system designers, and industrial motor control specialists. Primary interviews with utility planning officers and EPC contractors combined with secondary validation from FERC filings, IEC standard documentation, and state grid tender databases. Bottom-up unit economics triangulated against top-down grid investment forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, technology method, application sector, and end-user category with regional regulatory framework overlays. CAGRs derived from installed base replacement cycles and capacity addition pipelines. Forecast inputs incorporated smart meter deployment schedules under China's National Energy Administration and FERC Order 881 implementation timelines.
Decision-makers should treat outputs as directional under assumptions of sustained grid modernization investment and stable semiconductor fabrication capacity; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding protocol adoption velocity and rare earth magnet supply continuity. Revision becomes warranted when IEC 61850 certification backlog durations or copper price volatility cross thresholds that alter supplier competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.