
 Central Battery Systems Market | 2026-2036
Central Battery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Central Battery Systems Market Analytics
Chinese battery pack manufacturers is broadening output capacity for central battery systems serving Asia-Pacific emergency infrastructure. Schneider Electric leverages its integrated power management portfolio to anchor European market presence. ABB sustains technology leadership through advanced lithium-ion central battery architectures for critical facility applications.
Central battery systems are engineered power backup assemblies that distribute DC emergency supply through dedicated inverter and monitoring subsystems, typically rated for 24V to 110V output with centralized control topology. These systems serve as the backbone for life-safety electrical loads including egress illumination, fire detection circuits, and uninterruptible control power. Modular product configurations capture expanding share as facility managers prioritize scalable capacity expansion over fixed standalone installations. Lithium-ion technology leads growth trajectories given superior energy density and reduced footprint versus legacy lead-acid alternatives, though nickel-cadmium retains position in extreme temperature industrial deployments.
EU F-Gas Regulation and CE marking requirements under the MDR framework shape product compliance pathways for central battery systems deployed across European critical infrastructure. The US FAA and NHTSA standards indirectly influence battery transport and installation protocols for aviation and transit-adjacent facility applications. Stakeholders must monitor evolving chemistry-specific safety codes and energy storage fire suppression mandates as jurisdictions tighten installation requirements for high-capacity lithium-based central battery banks.
Market Dynamics
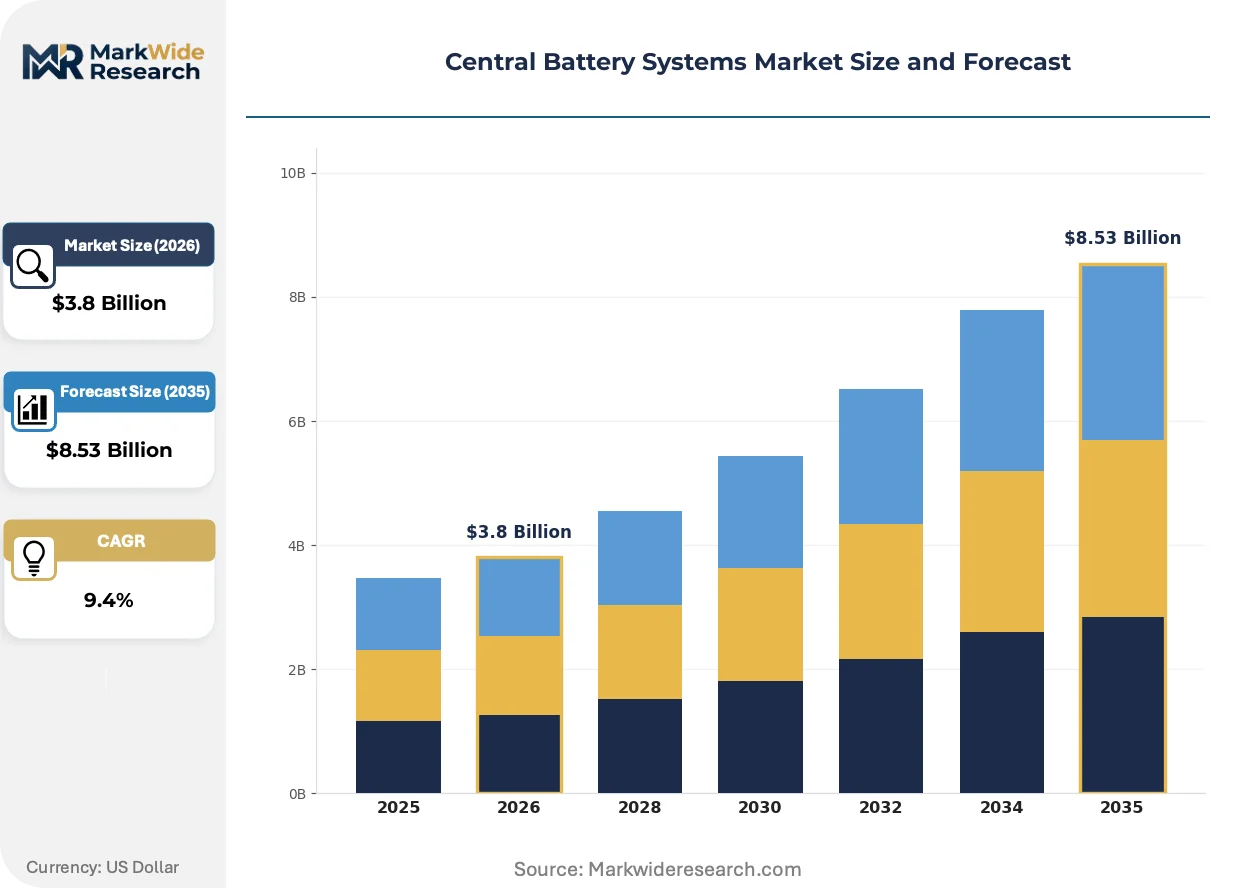
Modular lithium-ion architectures are compressing installation footprints while EU F-Gas Regulation and CE marking under MDR framework force chemistry-specific compliance investments across European critical infrastructure deployments.
Growth Catalysts
- EU Green Deal energy efficiency mandates:German data center operators are expanding backup power procurement to meet binding carbon reduction targets for facility operations.
- Smart battery monitoring integration:Nordic commercial building portfolios are replacing standalone units with networked systems enabling predictive maintenance and remote diagnostics.
- Asia-Pacific emergency infrastructure buildout:Chinese battery pack manufacturers are scaling dedicated production lines for centralized DC backup systems serving rail, healthcare, and municipal safety networks.
Market Restraints
- Lithium raw material concentration:Cathode active material supply chains concentrate in limited processing jurisdictions, exposing battery system costs to volatile commodity swings.
- Extreme temperature performance gaps:Nickel-cadmium retains mandatory specification in Arctic industrial deployments where lithium-ion thermal management fails.
- Transport classification friction:US FAA and NHTSA battery shipping protocols impose packaging and documentation burdens that extend project lead times for aviation-adjacent facilities.
Strategic Opportunities
- CE marking MDR pathway specialization:Compliance engineering services for medical-grade central battery installations represent uncaptured value in European healthcare construction.
- Microgrid DC coupling convergence:Integration of central battery systems with solar-plus-storage architectures creates new specification channels for commercial building energy managers.
- India PLI scheme localization:Domestic cell and pack manufacturing incentives under the country's production-linked incentive framework reduce import dependency for critical infrastructure projects.
Industry Challenges
- Lithium-based fire suppression certification:Jurisdictions are tightening installation codes for high-capacity battery banks, forcing redesign of enclosure and detection systems mid-project.
- Legacy lead-acid infrastructure retrofit:Footprint and ventilation requirements for new chemistries conflict with existing plant room configurations in aged commercial buildings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central Battery Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Modular, Combined, Smart Application: Emergency Lighting, UPS Systems, Fire Alarm, Security Systems End User: Commercial Buildings, Industrial Facilities, Residential Complexes, Hospitals Technology: Lithium-Ion, Lead-Acid, Nickel-Cadmium, Flow Batteries |
| Companies Covered | EATON, Schneider Electric, ABB, Powerguard, Ventilux, Teknoware, AWEX, Powervamp, Honeywell Gent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central Battery Systems Market Evolving Landscape
Intelligent power management software is embedding directly into hardware platforms, eroding the boundary between battery asset and building energy system while creating new specification criteria for facility managers.
Lithium iron phosphate cell chemistry is consolidating position as the dominant central battery platform for life-safety applications. Hospital and transportation facility operators specify phosphate systems for thermal stability margins. This chemistry is consolidating market share by compressing the viable specification window for nickel-manganese-cobalt alternatives in egress illumination and fire detection circuits.
EU F-Gas Regulation is phasing down fluorinated greenhouse gases used in battery thermal management systems. Manufacturers are redesigning cooling architectures to accommodate natural refrigerants or liquid cooling loops. Medical device central battery suppliers face the steepest redesign timelines given MDR conformity assessment requirements.
Facility managers are bundling central battery procurement with long-term service agreements covering cell replacement and capacity testing. Traditional equipment-only distributors are losing specification influence to integrated power service providers. German commercial building portfolios show the most advanced contracting structures, with ten-year performance guarantees now standard in major municipal tenders.
Central Battery Systems Market Segmentation
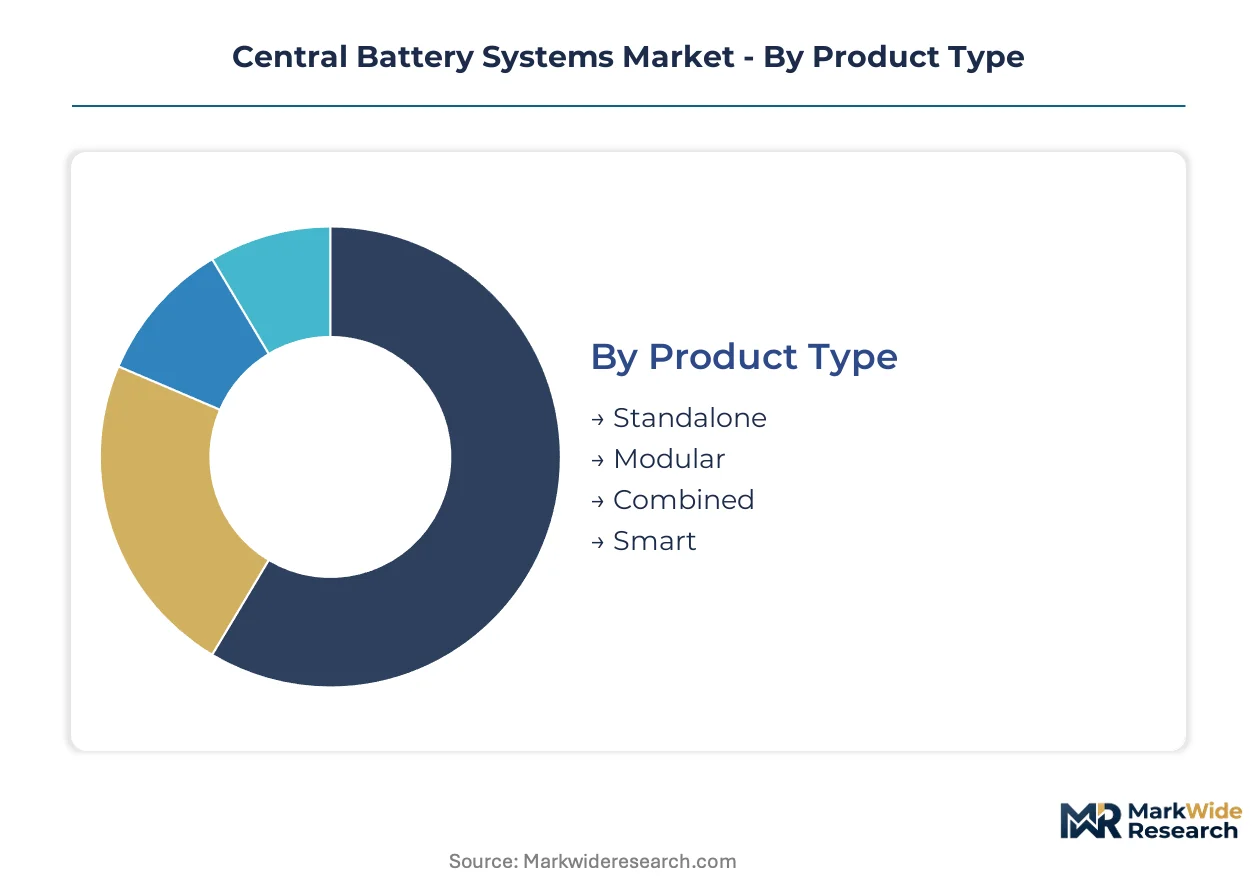
Central battery systems serve divergent facility requirements through distinct product architectures and chemistry platforms. Segmentation reveals how procurement patterns split between legacy infrastructure replacement and next-generation specification.
Product Type:
Replacement cycles vary dramatically across product architectures, with facility age and expansion plans driving format selection.
- Standalone:Self-contained units with fixed capacity ratings dominate aged commercial buildings where existing plant room dimensions constrain retrofit options. German municipal tenders still specify these for small-scale egress lighting in heritage structures.
- Modular:Scalable rack-mounted configurations allow capacity expansion without system replacement. Nordic data center operators prioritize these for phased backup power buildouts under EU Green Deal compliance timelines.
- Combined:Integrated inverter-battery assemblies reduce installation complexity for constrained mechanical spaces.
- Smart:Networked platforms with embedded monitoring and predictive diagnostics command specification from facility managers pursuing long-term service contracts.
Volume placements concentrate in Modular; the faster expansion belongs to Smart.
Application:
End-use requirements dictate voltage specifications, discharge duration, and regulatory certification burdens.
- Emergency Lighting:Life-safety egress illumination demands 90-minute minimum runtime under IEC standards. Hospital construction in France and Germany drives specification of central systems over distributed battery packs.
- UPS Systems:Uninterruptible power for critical IT loads requires seamless transfer and pure sine wave output. Data center operators in Frankfurt and Amsterdam specify lithium-ion central architectures for footprint compression.
- Fire Alarm:Dedicated 24V DC circuits for detection and notification devices mandate supervised power pathways.
- Security Systems:Access control and surveillance backup tolerates longer transfer times than life-safety loads.
Procurement volume clusters in Emergency Lighting; UPS Systems are climbing the fastest on data center construction.
End User:
Customer scale and risk tolerance create divergent purchasing patterns across facility types.
- Commercial Buildings:Office and retail portfolios prioritize total cost of ownership over capital expenditure. German commercial building managers now bundle ten-year performance guarantees with central battery procurement.
- Industrial Facilities:Manufacturing plants and process industries demand extreme temperature tolerance. Arctic industrial deployments in Norway and Finland retain nickel-cadmium specification where lithium-ion thermal management fails.
- Residential Complexes:High-rise apartment buildings require centralized emergency power for common area lighting and elevator rescue.
- Hospitals:Medical-grade installations face MDR conformity assessment and CE marking requirements under the EU framework.
Commercial Buildings dominate placement volumes; Hospitals show the steepest expansion trajectory on healthcare infrastructure investment.
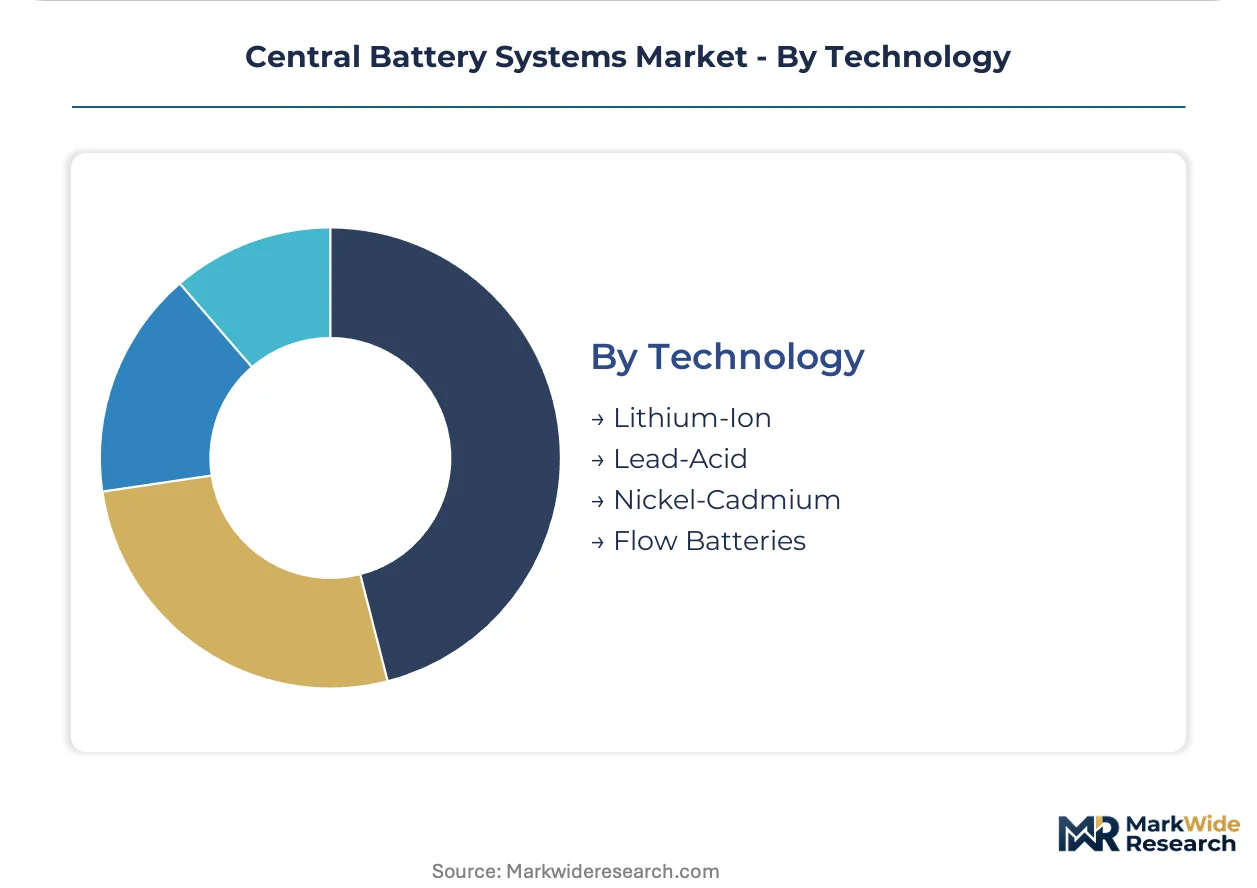
Technology:
Chemistry selection hinges on energy density, thermal stability, and operating environment constraints.
- Lithium-Ion:Lithium iron phosphate cells consolidate position for life-safety applications given thermal stability margins. Hospital and transportation facility operators specify phosphate systems for egress illumination and fire detection circuits.
- Lead-Acid:Mature technology with established recycling infrastructure retains position in cost-sensitive retrofits where footprint constraints are absent.
- Nickel-Cadmium:Extreme temperature performance sustains mandatory specification in Arctic industrial deployments.
- Flow Batteries:Aqueous electrolyte systems offer extended cycle life for applications with daily cycling requirements.
Lithium-Ion captures the dominant placement share; Flow Batteries are gaining share fastest in microgrid-coupled commercial installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium processing capacity in Jiangsu and Hunan provinces anchors Chinese supply chains for central battery cathode materials. This concentration shapes procurement patterns across emergency infrastructure markets worldwide.
United States
Data center construction in Northern Virginia and Dallas-Fort Worth drives specification of lithium-ion central architectures for backup power compression. FAA and NHTSA battery transport protocols impose documentation burdens on aviation-adjacent facility projects. Chicago commercial building portfolios show accelerated retrofit cycles as property managers pursue ten-year performance contracting structures.
Germany
Frankfurt and Amsterdam data center clusters prioritize modular central battery systems under binding EU Green Deal carbon reduction timelines. CE marking under the MDR framework shapes medical-grade installation compliance pathways. Bavarian municipal tenders now standardize smart battery monitoring integration for egress illumination networks.
China
Rail and healthcare infrastructure buildout in the Yangtze River Delta and Pearl River Delta sustains dedicated production line expansion. The country's dual carbon goals accelerate lithium iron phosphate specification for life-safety applications. Shenzhen battery pack manufacturers are scaling output for centralized DC backup serving municipal safety networks.
India
Hospital construction in Maharashtra and Karnataka drives medical-grade central battery procurement under domestic manufacturing incentives. The PLI scheme for cell and pack production reduces import dependency for critical infrastructure. Delhi-NCR commercial building managers are bundling long-term service agreements with central battery installations.
United Kingdom
London commercial building retrofits confront footprint constraints from legacy lead-acid plant room configurations. The country's national building safety regulations tighten installation codes for high-capacity lithium-based battery banks. Manchester and Birmingham facility managers specify networked smart systems enabling predictive maintenance protocols.
Central Battery Systems Market Competitive Landscape
Global majors compete with regional champions across technology integration and service bundling dimensions. The vendor base splits between integrated power management conglomerates and specialized emergency lighting fabricators. Three archetypes dominate: full-suite industrial electrification groups, life-safety system specialists, and battery-centric hardware pure-plays. Capacity expansion and strategic service contracting represent the dominant competitive vectors as hardware margins compress.
Within the integrated industrial electrification tier, Schneider Electric and ABB exemplify technology leadership through advanced lithium-ion architectures and power management portfolio breadth. Eaton occupies a position bridging emergency lighting specialization with broader electrical infrastructure capability. These three anchors demonstrate how scale-driven players leverage existing distribution networks to capture specification influence from facility managers pursuing long-term performance guarantees.
| Leading Market Players |
|---|
| EATON |
| Schneider Electric |
| ABB |
| Powerguard |
| Ventilux |
| Teknoware |
| AWEX |
| Powervamp |
| Honeywell Gent |
| Others |
Value Network & Pricing Analysis
Warranty-bundling divergence separates premium lithium-ion central battery suppliers from commodity lead-acid distributors across German and Nordic procurement channels. CE marking under the MDR framework and EU F-Gas Regulation compliance investments concentrate pricing power with integrated service providers who wrap ten-year performance guarantees into municipal tenders.
Pricing Analysis
Warranty and service-bundling structures dominate central battery procurement decisions across European healthcare and data center verticals. Three-tier pricing stratification across premium smart-monitored systems, standard modular architectures, and economy standalone units reflects certification grade differentiation and geographic delivery cost spreads. Pricing pressure intensifies in the lead-acid retrofit segment as facility managers confront footprint conflicts with legacy plant room configurations. Commercial building portfolios in Germany show least price sensitivity given long-term total cost of ownership frameworks, while cost-constrained residential complex developers in India drive commoditization at the economy tier.
Supply Chain Analysis
CE marking and MDR qualification gating restrict supplier participation in European medical-grade central battery installations to pre-certified manufacturers with established conformity assessment pathways. Cathode active material processing concentrates in Jiangsu and Hunan provinces of China, with South Korean and Japanese cell fabricators feeding premium lithium iron phosphate architectures. Supply chains draw from lithium carbonate, electrolyte solvents, and power electronics as core inputs. Single-source vulnerability in cathode precursor refining exposes project timelines to commodity volatility. Distribution runs through electrical infrastructure distributors and integrated power service providers with direct facility manager relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The central battery systems market functions as a cost-of-compliance arena where EU F-Gas Regulation and MDR framework investments erect barrier-to-entry moats favoring incumbent integrated power management conglomerates over hardware pure-plays.
For Market Incumbents: Cement technology leadership by deepening captive supply of lithium iron phosphate cells through backward integration into cathode material partnerships in China and South Korea. Expand smart monitoring software development to defend against emerging cloud-native energy management platforms threatening specification influence in Nordic commercial portfolios. Prioritize CE marking pathway specialization for medical-grade installations as German hospital construction accelerates. For New Entrants and Emerging Players: Enter via microgrid DC coupling convergence opportunities where solar-plus-storage integration creates specification whitespace outside traditional emergency lighting channels. Target Indian commercial building portfolios under PLI scheme localization incentives, where domestic cell manufacturing reduces import dependency and opens procurement access. Lead with predictive maintenance software subscriptions bundled with hardware to differentiate from established equipment-only distributors. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-cap specialists possessing captive lithium processing and established MDR conformity assessment capabilities given accelerating healthcare infrastructure investment. Monitor lithium raw material price volatility as the inflection signal for margin compression versus expansion across the battery system value chain. Favor targets with ten-year performance guarantee contracting structures already embedded in German municipal tender relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Materials | Captive lithium iron phosphate supply secures margin control against volatile commodity swings in Chinese processing hubs. |
| Smart Monitoring Platform Development | Predictive diagnostics software embeds battery assets into building energy management systems under EU Green Deal mandates. |
| CE Marking MDR Pathway Specialization | Medical-grade conformity assessment capabilities unlock German hospital construction procurement with premium pricing power. |
| Long-term Service Agreement Bundling | Ten-year performance guarantees shift revenue mix toward recurring streams in Frankfurt and Amsterdam data center clusters. |
| Microgrid DC Coupling Integration | Solar-plus-storage convergence creates new specification channels beyond traditional egress illumination applications. |
Research Methodology
Document review covered regulatory filings with EMA and FDA, IEC standard documentation, and EU F-Gas Regulation implementation guidelines, complemented by interviews with facility managers at German data center operators, Nordic commercial building portfolio directors, and Indian hospital procurement committees. Secondary validation drew from SEC 10-K disclosures of integrated power management conglomerates, customs trade data on lithium cell imports, and municipal tender databases across Bavaria and Hesse. Bottom-up project pipeline analysis triangulated against top-down market sizing from equipment shipment tracking.
Market size and growth trajectory outputs reflect segmentation modeling across product type, application, end user, and technology dimensions, with additional granularity on certification tier and service bundling structure. CAGRs were derived from fitted growth curves anchored to disclosed capacity expansion announcements and procurement contract values. Forecast inputs incorporated lithium raw material price indices, data center construction permits in Northern Virginia and Frankfurt, and PLI scheme utilization rates in Maharashtra and Karnataka.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium supply disruption scenarios or accelerated EU fire suppression code revisions for high-capacity battery banks. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Data Center Power Quality and Harmonics Monitoring Test Systems Market
Power Systems
Linear Voltage Regulators Market
Power Systems
Voltage Stabilizer System Market
Power Systems
Global Excitation Systems Market
Power Systems
Semiconductor Rectifier Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
Smart Junction Box and Power Distribution Box Systems Market
Power Systems
Piezoelectric Energy Harvesting System Market
Power Systems
Global Battery Thermal Management System Market
Power Systems
Generator Circuit Breaker Market
Power Systems
Train Auxiliary Rectifier Market
Power Systems
Nimh Rechargeable Battery Market
Power Systems
Switch Mode Power Supply (SMPS) Market
Power Systems
Power Electronics Market
Power Systems
Space DC-DC Converters Market
Power Systems
Shunt Voltage References Market