
 Modular Uninterrupted Power Supplies (UPS) Market | 2026-2036
Modular Uninterrupted Power Supplies (UPS) Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Uninterrupted Power Supplies (UPS) Market Foresight
Remote monitoring and predictive maintenance subscriptions is consolidating around hardware sales, blurring traditional procurement boundaries. Schneider Electric leverages its EcoStruxure platform to anchor recurring revenue streams alongside unit shipments. Eaton Corporation differentiates through service contracts that extend product lifecycles and lock in multi-year customer relationships. Huawei Technologies competes on integrated software-defined power management that reduces onsite engineering overhead.
Modular Uninterrupted Power Supplies are scalable power protection systems built from standardized, hot-swappable units that can be added or removed without system shutdown, typically operating at efficiencies above 96 percent in double-conversion online mode. These systems serve critical loads where continuous uptime is mandatory, including server racks, surgical suites, and process control loops. Three-Phase configurations dominate absolute revenue as hyperscale facilities push beyond 500 kW per rack, while Battery-Based technology anchors the installed base despite Flywheel systems gaining traction in short-duration ride-through applications. Rack-Mounted installation leads in new data center builds where floor space commands premium valuations.
The EPA Energy Star program and EU Ecodesign Directive enforce minimum efficiency thresholds that disqualify older transformer-based designs from new installations. IEC 62040-3 and UL 1778 certification requirements shape product development roadmaps and determine market access for cross-border suppliers. Buyers must weigh stranded asset risk against modular upgrade paths as efficiency standards tighten and lithium-ion battery chemistries displace traditional valve-regulated lead-acid configurations.
Market Dynamics
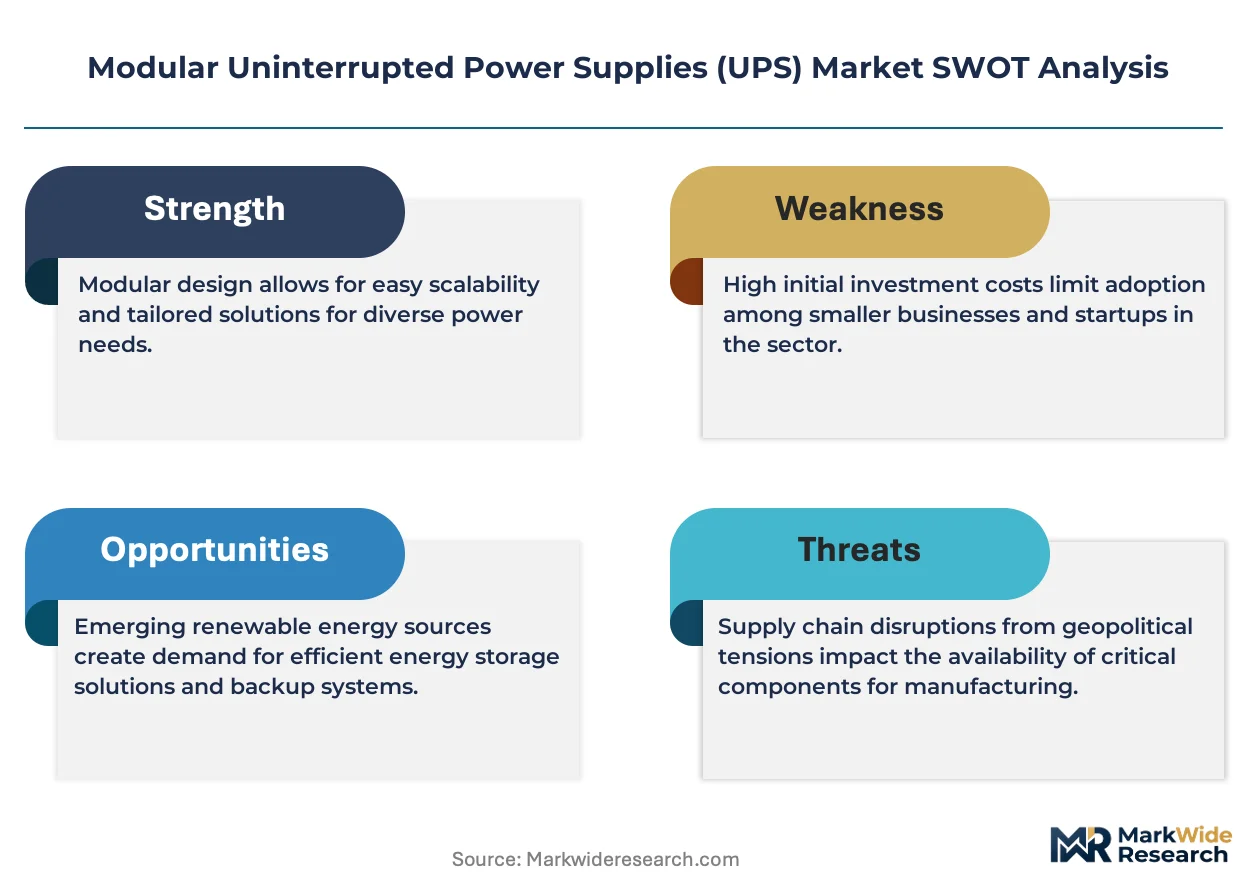
Hyperscale data center operators are forcing a step-change in power density per rack, driving procurement toward modular architectures that scale incrementally without facility shutdowns.
Growth Catalysts
- EPA Energy Star thresholds:Minimum efficiency mandates disqualify legacy transformer-based UPS from new installations, accelerating replacement cycles in commercial facilities.
- Cloud computing concentration:Colocation providers in Northern Virginia, Frankfurt, and Singapore are standardizing on rack-mounted modular units to match fluctuating tenant power requirements.
- Lithium-ion chemistry maturation:Battery energy density improvements enable 40-60% footprint reduction versus valve-regulated lead-acid, unlocking premium space in dense urban data halls.
Market Restraints
- Semiconductor supply concentration:IGBT and silicon carbide module production concentrates in East Asian foundries, exposing lead times to geopolitical friction.
- Copper and rare earth volatility:Winding materials and permanent magnets face price swings that compress margin predictability for system integrators.
- Flywheel substitution in short-duration:Kinetic energy storage captures 15-30 second ride-through applications, constraining battery UPS addressable market in industrial process control.
Strategic Opportunities
- Edge computing deployment wave:Distributed micro data centers in secondary US metros and European tier-2 cities lack purpose-built power infrastructure, creating greenfield modular UPS demand.
- EU Ecodesign Directive expansion:Upcoming efficiency tier requirements will render 2020-vintage systems non-compliant, triggering anticipated replacement demand in German and French industrial parks.
- Software-defined power convergence:Integration of UPS control planes with DCIM and building management systems opens recurring revenue streams through predictive analytics subscriptions.
Industry Challenges
- Power electronics engineering scarcity:Specialized talent in high-frequency conversion design and thermal management commands premium compensation, constraining R&D velocity for mid-tier suppliers.
- IEC 62040-3 certification timelines:Third-party validation for three-phase online topologies extends 8-14 months, delaying product launches and compressing effective sales windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Uninterrupted Power Supplies (UPS) Market |
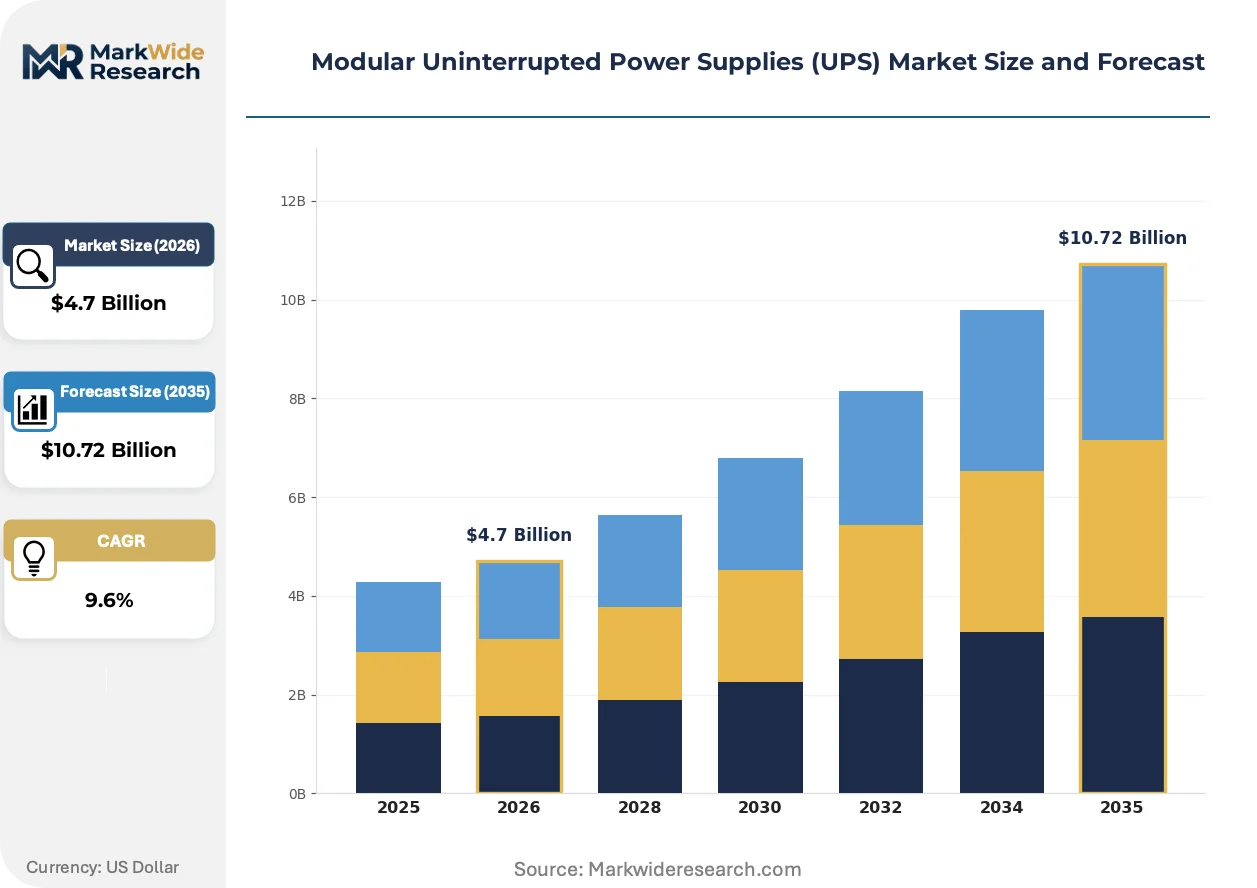
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $10.72 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Modular, Online Technology: Battery-Based, Flywheel, Hybrid, Fuel Cell End User: Data Centers, Healthcare Facilities, Industrial Plants, Telecommunications Installation: Rack-Mounted, Floor-Installed, Portable, Integrated |
| Companies Covered | Vertiv, Delta Electronics, Huawei Technologies, Kehua Data, Legrand, Schneider Electric, Eaton Corporation, KSTAR Science and Technology, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Uninterrupted Power Supplies (UPS) Market Shifts & Advancements
Power protection architecture is converging with intelligent building systems, eroding the boundary between standalone UPS hardware and integrated facility energy management platforms.
Silicon carbide power semiconductors are unifying inverter and rectifier stages into compact, high-frequency conversion blocks. Hyperscale operators in Dallas, Amsterdam, and Shanghai are specifying SiC-based units for new 1MW+ rack rows. The technology is unifying thermal and electrical design, collapsing form factors by 30-40% versus silicon IGBT predecessors.
EU Ecodesign Directive Lot 27 efficiency tiers are tightening standby loss thresholds for units above 10kVA. Manufacturers must redesign magnetics and control algorithms to meet 2027 requirements. Three-phase online double-conversion products face the steepest redesign burden, with German and Italian industrial buyers already filtering tenders to Tier 2-compliant models.
Buying committees are consolidating hardware and service procurement under single-source agreements that bundle installation, remote monitoring, and battery replacement. Systems integrators and direct manufacturer channels are displacing traditional electrical distributors for projects above 500kVA. This pattern concentrates in US hyperscale deployments where procurement teams prioritize operational expenditure predictability over capital cost minimization.
Modular Uninterrupted Power Supplies (UPS) Market Segmentation
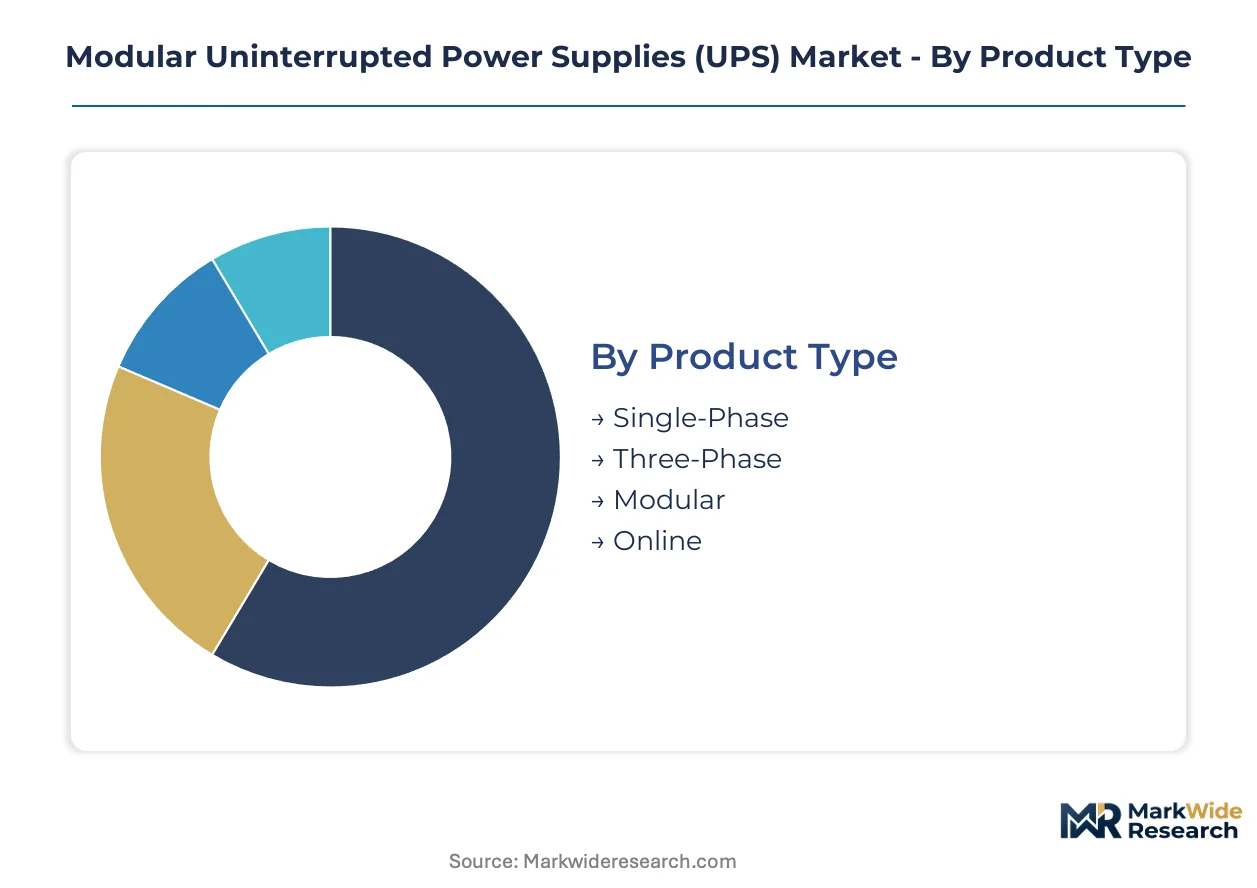
Modular UPS procurement decisions hinge on power density requirements, runtime duration, and facility constraints rather than capital cost alone. Buyers evaluate total cost of ownership across battery chemistry lifecycles, thermal management integration, and service contract structures. Each segmentation dimension reflects distinct engineering trade-offs between efficiency, footprint, and scalability.
Product Type:
Facility power density dictates phase configuration selection, with rack-level loads driving single-phase deployments and hyperscale rows demanding three-phase architectures.
- Single-Phase:Compact units serving sub-20kVA loads in edge computing closets and retail server rooms. Demand clusters in secondary US metros and European tier-2 cities where distributed micro data centers lack purpose-built infrastructure.
- Three-Phase:Modular blocks scaling beyond 500kW per rack row through hot-swappable power modules. Hyperscale operators in Northern Virginia, Frankfurt, and Singapore specify these for cloud and colocation builds where tenant power requirements fluctuate unpredictably.
- Modular:Standardized, hot-swappable units enabling capacity additions without system shutdown. Industrial plants in Germany and France favor this architecture for process control loops requiring continuous uptime during maintenance windows.
- Online:Double-conversion topology delivering conditioned power with zero transfer time. EPA Energy Star thresholds and EU Ecodesign Directive efficiency mandates accelerate displacement of line-interactive alternatives in new commercial installations.
Volume sits with Three-Phase configurations; growth tilts toward Modular architectures as facilities prioritize incremental scalability over upfront capacity overbuild.
Technology:
Energy storage chemistry determines footprint, runtime, and lifecycle economics, with lithium-ion maturation reshaping procurement patterns across installation types.
- Battery-Based:Dominant installed base using valve-regulated lead-acid or lithium-ion chemistries. Lithium-ion variants enable 40-60% footprint reduction, unlocking premium space in dense urban data halls across Dallas, Amsterdam, and Shanghai.
- Flywheel:Kinetic energy storage delivering 15-30 second ride-through for industrial process control. Manufacturing facilities in the US Midwest and German industrial parks deploy these for short-duration protection where generator startup latency is minimal.
- Hybrid:Combined battery-flywheel systems optimizing capital allocation across runtime tiers. Telecommunications central offices in hurricane-prone US Southeast regions specify these for extended grid outage resilience.
- Fuel Cell:Hydrogen or natural gas systems providing multi-hour autonomy without battery maintenance. Healthcare facilities in California and New York evaluate these for surgical suite backup where diesel generator emissions face regulatory constraints.
Revenue concentrates in Battery-Based systems; expansion accelerates fastest for Flywheel deployments in manufacturing ride-through applications.
End User:
Critical load characteristics—uptime requirements, power quality sensitivity, and regulatory oversight—shape vendor selection and service contract structures.
- Data Centers:Hyperscale and colocation facilities driving absolute demand volume. Cloud operators standardize on rack-mounted modular units with remote monitoring subscriptions to match fluctuating tenant deployments.
- Healthcare Facilities:Hospitals and surgical centers requiring IEC 60601-1 compliance for patient-connected equipment. US healthcare systems face Joint Commission accreditation pressure to replace aging static UPS with modular online systems.
- Industrial Plants:Process control and automation loads where power interruption triggers batch spoilage or equipment damage. German automotive manufacturing clusters specify three-phase modular architectures for production line protection.
- Telecommunications:5G edge nodes and central offices requiring -48VDC or AC compatibility. Tower operators in India and Southeast Asia prioritize fuel cell hybrids where grid reliability is inconsistent and diesel logistics are costly.
Absolute volume flows to Data Centers; healthcare replacement cycles and industrial edge expansion represent the steepest growth trajectories.
Installation:
Facility real estate economics and mobility requirements determine physical form factor, with floor space premiums driving vertical integration of power and cooling.
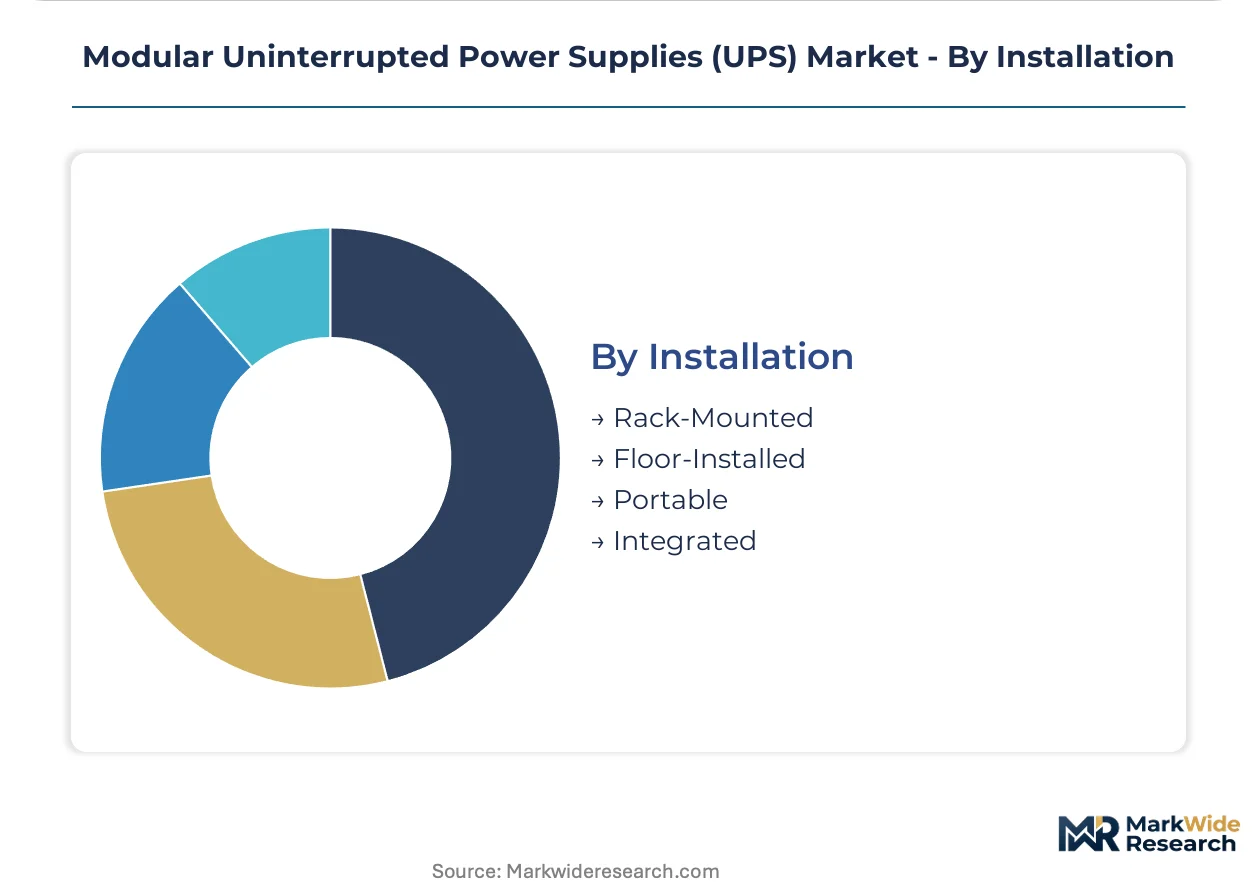
- Rack-Mounted:Integrated within IT equipment enclosures, eliminating dedicated electrical rooms. New builds in Singapore and Northern Virginia specify these exclusively where floor space commands premium valuations.
- Floor-Installed:Standalone cabinets for centralized power distribution in retrofit environments. Older industrial parks in the US Rust Belt and European manufacturing zones retain this architecture due to structural load constraints.
- Portable:Mobile units for temporary events, construction sites, or emergency response. Rental fleets serving US Gulf Coast hurricane recovery and German trade fair infrastructure represent concentrated demand.
- Integrated:Pre-engineered power modules combining UPS, distribution, and cooling in factory-tested enclosures. Hyperscale operators in Phoenix and Dublin deploy these to compress commissioning schedules for accelerated rack deployments.
Deployment volume centers on Rack-Mounted systems; Integrated solutions are climbing fastest as modular construction methods penetrate data center build programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's Data Center Alley hosts the densest concentration of hyperscale cloud capacity worldwide, driving modular UPS procurement volumes that exceed most national markets. Frankfurt's Mainova corridor and Singapore's Jurong Lake District anchor European and Asian demand respectively, with each metro processing billions in annual power infrastructure investment.
United States
Cloud operators in Ashburn, Virginia and Dallas, Texas are standardizing on rack-mounted modular architectures to match unpredictable tenant power ramps. EPA Energy Star thresholds now disqualify legacy transformer-based systems from federal procurement contracts. The Phoenix metro's emerging hyperscale cluster is compressing commissioning schedules through pre-integrated power modules combining UPS, distribution, and cooling.
Germany
Automotive manufacturing clusters in Bavaria and Baden-Württemberg specify three-phase modular UPS for production line protection during maintenance windows. The EU Ecodesign Directive's Lot 27 efficiency tiers are tightening standby loss thresholds, rendering 2020-vintage systems non-compliant for new industrial tenders. Frankfurt's colocation providers filter procurement to Tier 2-compliant models ahead of 2027 deadlines.
China
Hyperscale operators in Shanghai's Lingang New Area and Beijing's Daxing district specify silicon carbide-based units for 1MW+ rack rows. The country's dual carbon goals pressure legacy installations toward higher-efficiency replacement cycles. Shenzhen's edge computing deployment wave creates greenfield demand in secondary metros lacking purpose-built power infrastructure.
Singapore
Jurong Lake District and Tuas data center campuses command premium valuations for floor space, driving exclusive specification of rack-mounted systems. The Infocomm Media Development Authority's sustainability standards enforce minimum efficiency thresholds that accelerate displacement of line-interactive alternatives. Battery energy density improvements enable footprint reductions that unlock premium capacity in dense urban data halls.
India
Telecommunications tower operators in Maharashtra and Karnataka prioritize fuel cell hybrid systems where grid reliability is inconsistent and diesel logistics are costly. The Central Electricity Authority's power quality regulations shape procurement specifications for critical infrastructure. Mumbai's financial district and Bangalore's technology corridor are seeing accelerated modular UPS deployment for 5G edge nodes and central office modernization.
Modular Uninterrupted Power Supplies (UPS) Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the modular UPS market, with integrated power electronics manufacturers maintaining captive semiconductor sourcing while system integrators rely on third-party module procurement. The vendor base clusters around three strategic archetypes: diversified electrical conglomerates with building management integration capabilities, specialized power protection firms with deep service contract expertise, and emerging Asian suppliers competing on silicon carbide conversion technology. Consolidation pressures are intensifying as efficiency certification timelines extend 8-14 months, compressing effective sales windows for mid-tier entrants lacking established compliance pathways.
Among diversified electrical conglomerates, Schneider Electric, Eaton Corporation, and ABB occupy positions exemplifying distinct competitive vectors. Schneider Electric represents the integrated platform archetype, anchoring recurring revenue streams through software-defined power management convergence. Eaton Corporation exemplifies the lifecycle service model, extending product viability through multi-year maintenance contracts. ABB occupies a position within the industrial automation tier, leveraging process control expertise to penetrate manufacturing verticals. These three firms collectively illustrate how procurement consolidation under single-source agreements is displacing traditional electrical distribution channels for projects above 500kVA.
| Leading Market Players |
|---|
| Vertiv |
| Delta Electronics |
| Huawei Technologies |
| Kehua Data |
| Legrand |
| Schneider Electric |
| Eaton Corporation |
| KSTAR Science and Technology |
| ABB |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up power electronics specialists anchor supply discipline across East Asian semiconductor sourcing corridors, translating captive foundry relationships into pricing power that resists spot-market volatility. Their ownership structures reward margin defense through long-term offtake agreements with IGBT and silicon carbide module producers, compressing procurement cost variance for three-phase modular systems.
Pricing Analysis
Value-based pricing anchored to guaranteed uptime outcomes dominates hyperscale procurement, with colocation operators in Northern Virginia and Frankfurt paying premiums for 99.999% availability commitments. Three-tier pricing structure across premium, standard, and economy levels separates Tier 2 EU Ecodesign-compliant systems from legacy transformer-based alternatives. Cost compression in standard-tier rack-mounted units is intensifying because lithium-ion battery footprint advantages unlock space economics in dense urban data halls. Edge computing deployments in secondary US metros show highest price sensitivity, while healthcare facilities in California and New York exhibit lowest sensitivity due to Joint Commission accreditation pressures.
Supply Chain Analysis
Power electronics engineering talent scarcity in Taiwan, South Korea, and Japan constrains module production scaling despite foundry capacity availability. Silicon carbide wafer fabrication, copper winding materials, and rare earth permanent magnets feed from concentrated East Asian suppliers. Single-source vulnerability in silicon carbide substrate production exposes lead times to geopolitical friction. Distribution runs through direct manufacturer channels and systems integrators, displacing traditional electrical distributors for projects above 500kVA.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The modular UPS market sits in a silicon carbide transition phase, with wide-bandgap semiconductors displacing silicon IGBT predecessors in 1MW+ rack row specifications.
For Market Incumbents: Lock in multi-year service contracts that extend product lifecycles and capture recurring revenue streams before flywheel substitution erodes battery UPS share in short-duration industrial ride-through. Prioritize backward integration into silicon carbide module sourcing to defend margin position against commodity volatility in copper and rare earth inputs. Accelerate IEC 62040-3 certification pipelines to compress 8-14 month validation timelines that delay product launches. For New Entrants and Emerging Players: Silicon carbide-native conversion technology serves as the wedge for penetrating hyperscale operator specifications in Phoenix and Dublin where efficiency thresholds disqualify legacy designs. Target edge computing micro data centers in European tier-2 cities lacking purpose-built power infrastructure as the most penetrable white-space segment. Lead with software-defined power management integration that reduces onsite engineering overhead as the primary go-to-market angle. For Investors and Strategic Acquirers: EU Ecodesign Directive Lot 27 Tier 2 compliance deadlines are the leading indicator that replacement demand in German and French industrial parks will concentrate procurement among certified suppliers. Five-to-ten year viability favors diversified electrical conglomerates with building management integration capabilities and established compliance pathways. Watch IEC 62040-3 certification backlog clearance rates as the signal for effective sales window expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Conversion Technology Licensing | Enables 30-40% form factor reduction for hyperscale rack density requirements. |
| Long-term Service Contract Expansion | Locks in multi-year customer relationships alongside hardware shipments. |
| EU Ecodesign Tier 2 Certification Investment | Secures market access for German and French industrial tenders ahead of deadlines. |
| Edge Computing Geographic Expansion | Captures greenfield demand in secondary US metros lacking power infrastructure. |
| Software-Defined Power Platform Integration | Opens recurring revenue streams through predictive analytics subscriptions. |
Research Methodology
SEC filings from hyperscale cloud operators, EIA power infrastructure databases, and IEC certification registries formed the secondary backbone for demand quantification. Primary interviews with data center facility directors, power electronics procurement leads at colocation providers, and thermal management engineers at systems integrators validated capacity deployment timelines. Bottom-up and top-down triangulation cross-referenced module shipment data against rack-level power density specifications reported in facility planning disclosures.
Bottom-up modeling segmented revenue across phase configuration, energy storage chemistry, installation type, and end-use vertical throughout the forecast period. Top-down validation anchored total addressable market estimates to hyperscale capex disclosures from Northern Virginia, Frankfurt, and Singapore clusters. CAGRs were derived from installation volume trajectories tied to cloud computing concentration and regulatory replacement cycles. Silicon carbide adoption curves and lithium-ion battery chemistry maturation served as technology-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen semiconductor supply disruptions, abrupt tariff reconfigurations on East Asian module imports, and accelerated flywheel substitution in manufacturing ride-through applications. Forecasts reflect documented assumptions about efficiency standard enforcement timelines and battery chemistry cost trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Shunt Reactor Market
Power Systems
Piezoelectric Energy Harvesting System Market
Power Systems
Power Diode Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Shunt Voltage References Market
Power Systems
APAC Variable Frequency Drives Market
Power Systems
Global Pin Fin Heat Sink for IGBT Market
Power Systems
Charge Controller System Market
Power Systems
EV Power Module Market
Power Systems
Synchronous Condenser Market
Power Systems
Battery Cyclers Market
Power Systems
Thermal Management Systems Market
Power Systems
Global Flexible Batteries Market
Power Systems
Organic Fixed Power Capacitors Sales Market
Power Systems
Global Chip Power Inductor Market
Power Systems
Charge Pumps Market