
 Superconducting Magnet Systems Market | 2026-2036
Superconducting Magnet Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Superconducting Magnet Systems Market Insights
China's superconducting wire and magnet manufacturing base is narrowing the supply gap for domestic fusion reactors and export medical systems. Siemens Energy leverages cryogenic engineering depth to anchor European fusion projects. General Atomics sustains its position through proprietary Nb3Sn conductor production for high-field research magnets. Nexans Superconductors competes on long-length HTS tape manufacturing for grid and industrial applications.
Superconducting magnet systems employ cryogenically cooled coils—typically NbTi below 10 K or Nb3Sn and rare-earth barium copper oxide (REBCO) HTS tapes at higher temperatures—to generate persistent magnetic fields exceeding 10 tesla for particle steering, nuclear magnetic resonance signal capture, or plasma confinement. The primary commercial purpose centers on medical diagnostic imaging, where 1.5–3.0 tesla MRI magnets represent the dominant installed base. Medical imaging magnets occupy the largest revenue pool given hospital replacement cycles and emerging market fleet expansion, while particle accelerator magnets represent concentrated but lumpy demand tied to CERN, ITER, and national laboratory procurement schedules. Research institutions increasingly specify HTS-based systems for compact fusion devices, shifting technology segmentation toward higher-temperature architectures.
FDA 21 CFR Part 1020 regulates MRI system radiation safety and electromagnetic emissions for U.S. healthcare deployments, while EU MDR and CE marking govern magnet system conformity for European medical installations. China's NMPA and GB standards enforce comparable electromagnetic compatibility and clinical safety protocols, shaping product certification requirements for market access. ITER Organization procurement specifications and national nuclear safety frameworks further constrain supplier qualification for fusion-grade magnets. Stakeholders must monitor HTS conductor cost curves against helium supply volatility and evolving national fusion roadmaps to time capacity commitments.
Market Dynamics
High-temperature superconductor tape manufacturing is compressing cryogenic system footprints while China's fusion procurement corridors and FDA 21 CFR Part 1020 compliance timelines reshape supplier qualification requirements across medical and energy deployments.
Growth Catalysts
- ITER Organization procurement specifications:Fusion-grade magnet qualification standards are accelerating REBCO tape adoption for plasma confinement systems in European and Asian reactor projects.
- China's NMPA medical device registration pathways:Streamlined domestic certification for MRI superconducting magnets is expanding hospital fleet replacement cycles in tier-one cities.
- Helium-3 conservation protocols:Closed-cycle cryocooler integration is reducing liquid helium dependency for NbTi-based diagnostic imaging installations.
Market Restraints
- REBCO tape cost structure:Silver-alloy substrate processing keeps HTS conductor pricing at multiples of NbTi wire, constraining broad clinical adoption.
- Supply concentration risk:Rare-earth barium copper oxide deposition capacity clusters in East Asian substrate foundries, creating single-source vulnerability.
- EU MDR technical documentation:Extended conformity assessment timelines for active implantable medical devices delay European MRI system commercialization.
Strategic Opportunities
- Compact stellarator projects:Germany's Wendelstein-class reactor designs specify modular HTS coil architectures for distributed fusion research networks.
- Grid-scale superconducting fault current limiters:Utility procurement pilots in South Korea and Japan are validating long-length tape performance under grid fault conditions.
- Japan's METI carbon-neutral technology roadmap:Public-private funding for hydrogen-cooled superconducting systems supports industrial motor and generator retrofits.
Industry Challenges
- Cryogenic welding certification:Qualified technician pools for Nb3Sn joint fabrication remain shallow relative to fusion magnet installation schedules.
- Multi-physics simulation integration:Electromagnetic-thermal-structural coupled modeling for HTS coil quench behavior demands specialized finite-element expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superconducting Magnet Systems Market |
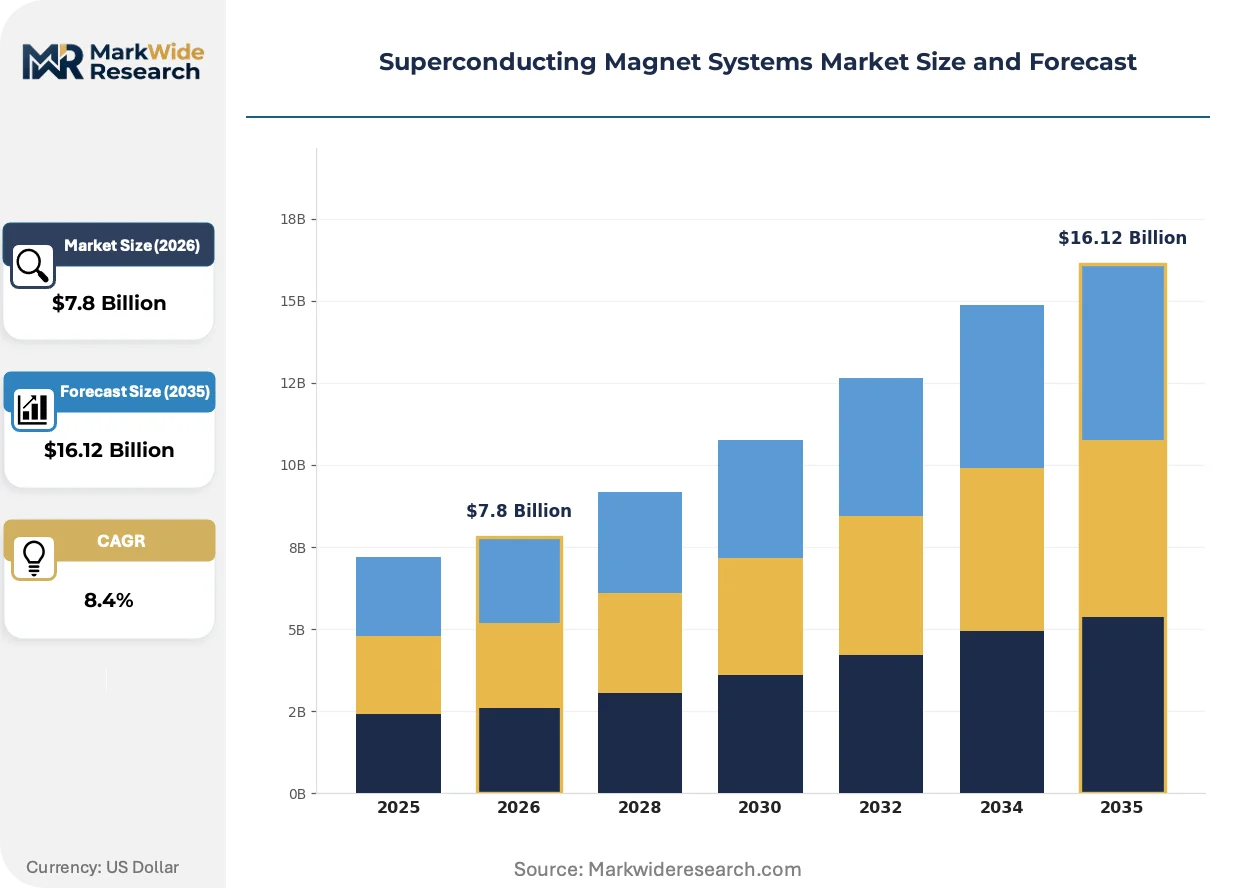
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Research Magnets, Medical Imaging Magnets, Particle Accelerator Magnets, Magnetic Resonance Imaging Magnets Application: Healthcare, Industrial Applications, Scientific Research, Energy Storage End User: Hospitals, Research Institutions, Manufacturing Plants, Educational Institutions Technology: Low-Temperature Superconductors, High-Temperature Superconductors, NbTi-based Systems, Nb3Sn-based Systems |
| Companies Covered | Siemens Energy, Southwire Company, General Atomics, Zenno Astronautics, Nexans Superconductors, Commonwealth Fusion Systems, Superconductor Technologies Inc., SuperQ Technologies, Chinese Academy of Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superconducting Magnet Systems Market Trends and Innovations
Computational magnet design and additive manufacturing of structural coils are compressing development cycles while regulatory frameworks for fusion safety and electromagnetic emissions tighten qualification standards.
REBCO-coated conductor architectures with artificial pinning centers are virtualizing the performance envelope previously exclusive to Nb3Sn at 4.2 K, enabling compact fusion devices to operate at 20–30 K with simplified cryogenics. Research institutions in the United States and Germany are specifying these tapes for high-field test magnets. The technology is virtualizing the capital cost barrier between laboratory-scale and reactor-scale magnetic confinement.
The EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants are forcing cryocooler manufacturers to specify helium-based or alternative working-fluid systems for superconducting magnet cooling. Industrial gas suppliers are retrofitting recovery infrastructure. European MRI OEMs face compressed timelines to requalify cooling subsystems before 2030 prohibition dates.
Hospital procurement committees are unbundling magnet system acquisitions from full-turnkey MRI installations, creating direct sourcing channels for superconducting coil refurbishment and cryostat maintenance. Independent service organizations are capturing aftermarket revenue previously retained by original equipment manufacturers. This pattern is most visible in North American and Western European healthcare systems with mature installed bases.
Superconducting Magnet Systems Market Segmentation
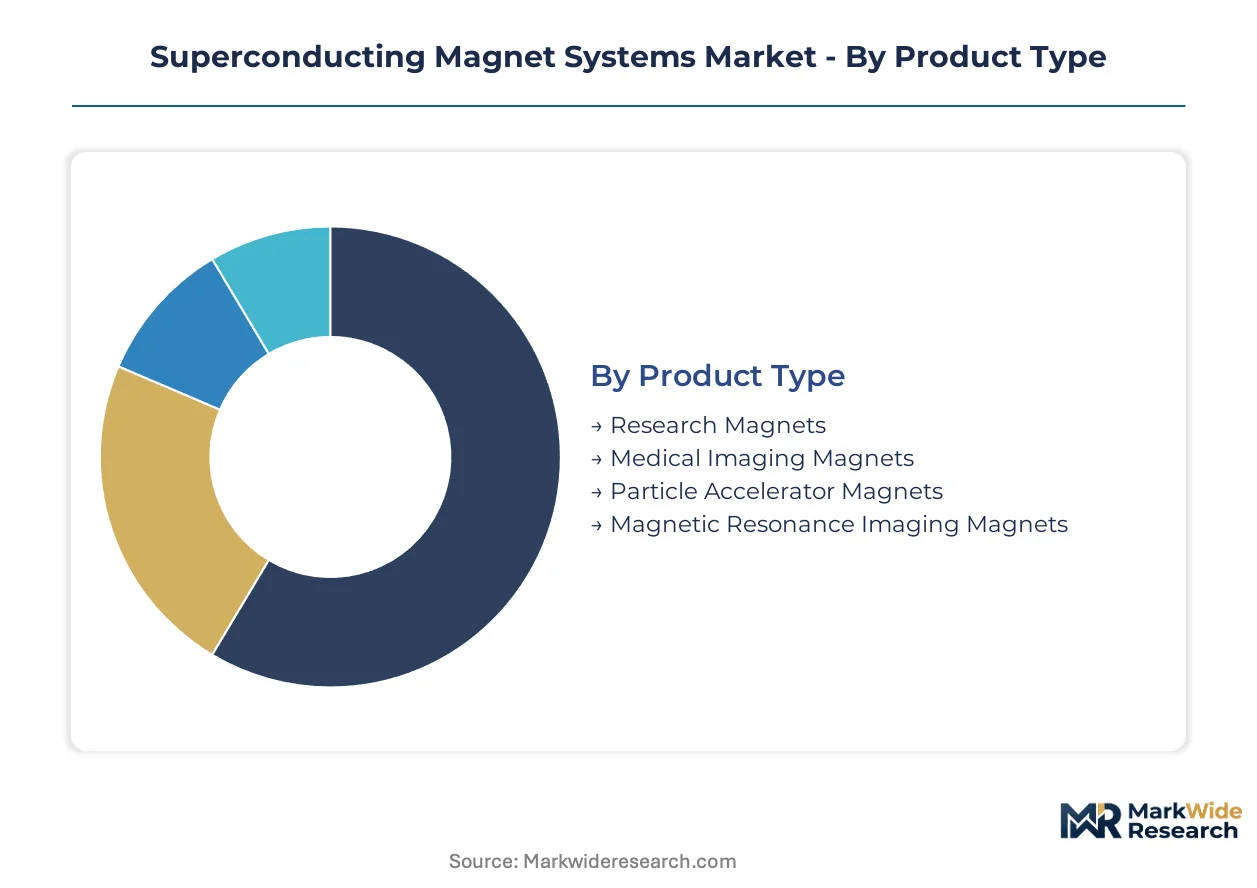
Superconducting magnet systems fragment across four distinct taxonomies that govern procurement patterns and supplier qualification. Product type determines cryogenic architecture and field strength specifications. Application context shapes regulatory pathways and maintenance protocols. End-user category dictates financing structures and replacement cycles. Technology selection locks in operating temperature regimes and helium dependency profiles.
Product Type:
Cost tier structures the product landscape, with field strength and cryogenic complexity driving capital expenditure stratification.
- Medical Imaging Magnets:NbTi-based solenoid designs operating at 1.5–3.0 tesla dominate hospital procurement. China's tier-one cities and India's metropolitan hospital networks are expanding fleet replacements, constrained by FDA 21 CFR Part 1020 electromagnetic emission limits and NMPA registration timelines.
- Research Magnets:Variable-field configurations up to 20 tesla serve materials characterization and condensed-matter physics. National laboratories in Germany, Japan, and the United States concentrate demand, with procurement tied to ITER Organization magnet qualification standards for high-field test beds.
- Particle Accelerator Magnets:Dipole and quadrupole arrays steer charged particle beams in synchrotron and collider facilities. CERN and Brookhaven National Laboratory procurement schedules generate lumpy, multi-year order cycles with exacting field uniformity specifications.
- Magnetic Resonance Imaging Magnets:Dedicated clinical diagnostic systems with optimized bore diameters for patient throughput. European hospital procurement committees are unbundling magnet acquisitions from turnkey installations, creating independent refurbishment channels.
Medical Imaging Magnets holds installed capacity. Research Magnets is rotating up the share rankings.
Application:
Volume concentration varies sharply by application, with healthcare absorbing steady replacement demand while energy storage remains pilot-scale.
- Healthcare:Diagnostic imaging and interventional MRI procedures account for the dominant installed base. China's NMPA streamlined registration pathways are accelerating domestic hospital fleet expansion, while EU MDR technical documentation requirements delay European commercialization timelines.
- Scientific Research:Materials science, chemistry, and physics laboratories deploy high-field systems for nuclear magnetic resonance spectroscopy. Germany's Wendelstein stellarator projects and MIT's compact fusion experiments are specifying HTS-based architectures, displacing conventional Nb3Sn for temperatures above 20 K.
- Industrial Applications:Magnetic separation, mineral processing, and semiconductor crystal growth utilize persistent-field systems. South Korean and Japanese utility pilots are validating superconducting fault current limiters for grid protection.
- Energy Storage:Superconducting magnetic energy storage systems buffer renewable intermittency. Japan's METI carbon-neutral technology roadmap is funding hydrogen-cooled industrial motor retrofits, though megawatt-scale deployment remains pre-commercial.
Healthcare captures the volume base. Scientific Research is climbing the fastest.
End User:
Customer type segmentation reveals divergent procurement rhythms, with hospitals operating on decade-long replacement cycles versus research institutions pursuing grant-funded upgrades.
- Hospitals:Acute care and specialized imaging centers prioritize 1.5 tesla workhorse systems and 3.0 tesla diagnostic platforms. North American and Western European healthcare systems with mature installed bases are driving independent service organization penetration for coil refurbishment.
- Research Institutions:National laboratories and university physics departments specify custom high-field configurations. ITER Organization procurement specifications and national nuclear safety frameworks constrain supplier qualification for fusion-grade magnet deliveries.
- Manufacturing Plants:Semiconductor foundries and materials processors deploy magnetic separation and quality control systems. Industrial gas suppliers are retrofitting helium recovery infrastructure to service these distributed installations.
- Educational Institutions:Teaching laboratories and undergraduate research facilities utilize compact, low-field demonstrator systems. Budget constraints favor refurbished or decommissioned hospital magnets with simplified cryogenics.
Hospitals anchor replacement demand. Research Institutions are gaining share fastest.
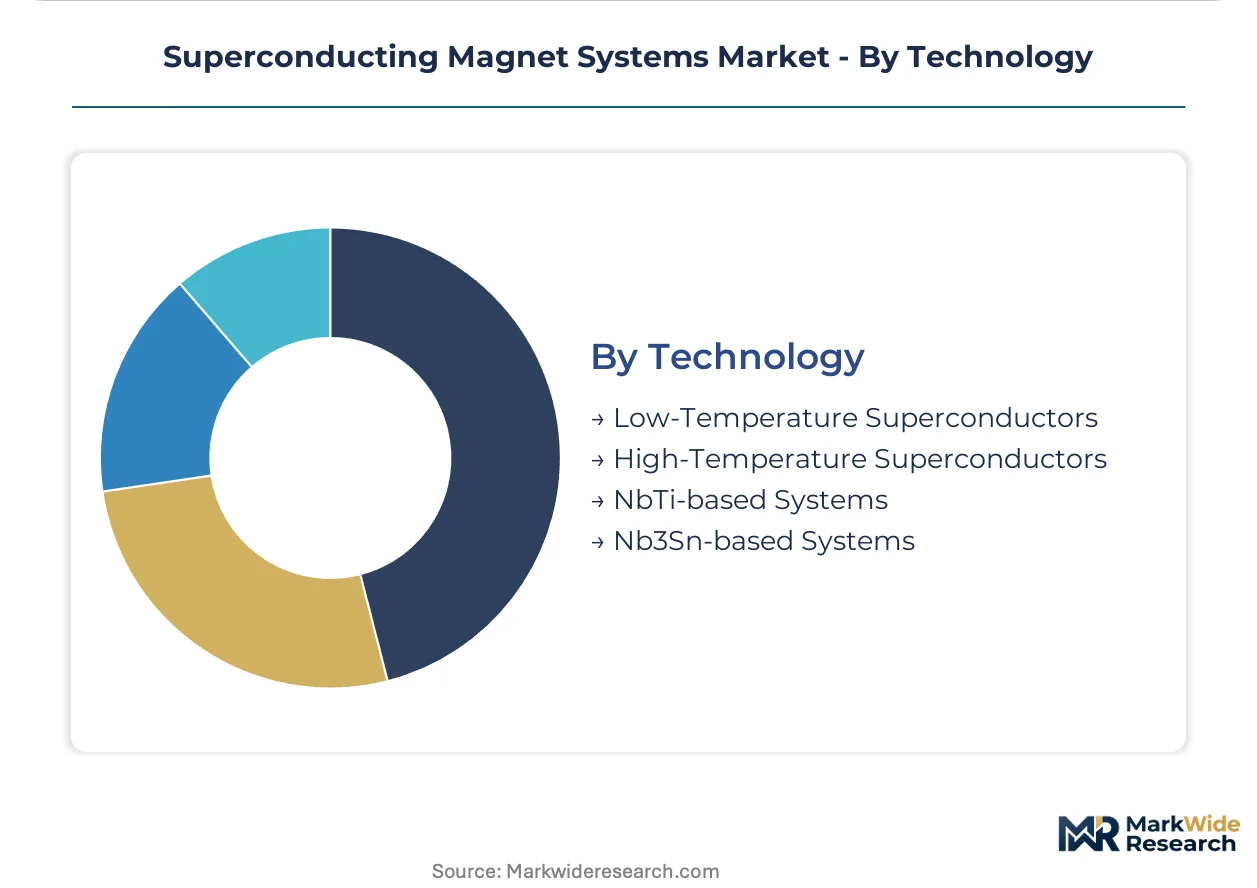
Technology:
Supply concentration defines the technology landscape, with rare-earth barium copper oxide deposition capacity clustering in East Asian substrate foundries.
- Low-Temperature Superconductors:Niobium-titanium alloys operating below 10 K with liquid helium or closed-cycle cryocoolers. FDA 21 CFR Part 1020 compliance and EU F-Gas Regulation phase-down schedules are forcing cooling subsystem requalification before prohibition dates.
- High-Temperature Superconductors:REBCO-coated conductors with artificial pinning centers enable operation at 20–30 K. Silver-alloy substrate processing keeps tape pricing at multiples of NbTi wire, constraining broad clinical adoption despite simplified cryogenics.
- NbTi-based Systems:Mature wire manufacturing infrastructure supports medical imaging and accelerator applications. Helium-3 conservation protocols are accelerating closed-cycle cryocooler integration to reduce liquid helium dependency.
- Nb3Sn-based Systems:Intermetallic compound conductors achieve 10–20 tesla fields for research and fusion applications. Qualified technician pools for cryogenic joint fabrication remain shallow relative to magnet installation schedules.
NbTi-based Systems holds installed capacity. High-Temperature Superconductors is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Superconducting wire deposition capacity clusters in East Asian substrate foundries, while European cryogenic engineering expertise anchors fusion magnet qualification. Hospital procurement corridors in tier-one cities across multiple continents are driving replacement cycle timing.
China
Fusion reactor procurement and domestic MRI fleet expansion are accelerating demand for both NbTi wire and REBCO tape. NMPA streamlined registration pathways are compressing certification timelines for hospital installations. Shanghai and Hefei industrial corridors concentrate superconducting conductor manufacturing for export medical systems and ITER-grade magnet deliveries.
United States
Compact fusion experiments and high-field research magnets are displacing conventional Nb3Sn architectures toward HTS-based systems. FDA 21 CFR Part 1020 electromagnetic emission limits shape MRI system compliance costs for domestic deployments. MIT and national laboratory clusters in Massachusetts and California are specifying artificial pinning center REBCO tapes for test magnet programs.
Germany
Wendelstein stellarator projects and materials science NMR facilities are driving modular HTS coil procurement. EU F-Gas Regulation phase-down schedules are forcing cryocooler subsystem requalification before 2030 prohibition dates. Bavarian and North Rhine-Westphalia industrial zones concentrate cryogenic engineering expertise for European fusion projects.
Japan
Grid-scale superconducting fault current limiter pilots and hydrogen-cooled industrial motor retrofits are validating long-length tape performance. METI carbon-neutral technology roadmap funding is supporting public-private development partnerships. Kansai and Chubu manufacturing corridors host substrate foundries and cryostat assembly operations.
South Korea
Utility procurement pilots for superconducting fault current limiters are testing REBCO tape durability under grid fault conditions. MFDS medical device regulations govern MRI system commercialization timelines for hospital networks. Seoul Capital Area and Busan-Ulsan industrial zones concentrate magnet system integration capacity for domestic and export markets.
Superconducting Magnet Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with conductor and cryostat manufacturing. The vendor base spans energy conglomerates with cryogenic engineering depth, national research institutions with captive magnet production, and specialized tape manufacturers with substrate deposition expertise. Three archetypes dominate: fusion-focused reactor builders, medical imaging OEMs with unbundled service strategies, and materials suppliers with long-length HTS tape capacity. Consolidation pressure is concentrating through strategic partnerships between tape foundries and magnet system integrators, while geographic expansion into China's procurement corridors represents the primary capacity commitment vector.
Among energy and industrial technology conglomerates, Siemens Energy exemplifies platform integration with cryogenic system expertise, while General Atomics occupies a position bridging research magnet production and fusion-grade conductor supply. Nexans Superconductors represents the long-length HTS tape manufacturing archetype for grid and industrial applications outside medical imaging.
| Leading Market Players |
|---|
| Siemens Energy |
| Southwire Company |
| General Atomics |
| Zenno Astronautics |
| Nexans Superconductors |
| Commonwealth Fusion Systems |
| Superconductor Technologies Inc. |
| SuperQ Technologies |
| Chinese Academy of Sciences |
| Others |
Pricing and Supply Chain Analysis
Silver-alloy substrate processing concentration in East Asian foundries determines both the premium-mid-economy pricing differentiation across REBCO tape tiers and the geographic clustering of magnet system integrators seeking backward integration into conductor supply.
Pricing Analysis
FDA 21 CFR Part 1020 dictates the pricing tier structure for MRI superconducting magnets across North American hospital procurement corridors. Three-tier pricing structure across premium, standard, and economy levels separates ITER-qualified fusion-grade systems from clinical diagnostic platforms and refurbished research magnets. Cost compression in standard-tier NbTi-based medical imaging systems is intensifying because European OEMs face EU F-Gas Regulation requalification deadlines. Academic research institutions exhibit the highest price sensitivity, while national fusion laboratories demonstrate inelastic demand for qualified high-field configurations.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for REBCO-coated conductor procurement. Manufacturing gravity centers on Japan, South Korea, and China for rare-earth barium copper oxide substrate deposition, while Germany and the United States anchor cryostat assembly and cryogenic subsystem integration. The supply chain draws from silver-alloy substrates, high-purity helium, and niobium-titanium wire as critical inputs. Distribution runs through magnet system integrators with captive service networks for hospital installations and direct procurement channels for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits defensive moat characteristics rooted in regulatory entrenchment, where ITER Organization qualification standards and FDA 510(k) pathways create multi-year certification barriers for new conductor suppliers.
For Market Incumbents: Harden fusion-grade magnet qualification portfolios against emerging HTS tape competitors by deepening captive REBCO deposition capacity in East Asian substrate foundries. Secure exclusive cryogenic welding technician certification pipelines to constrain installation capacity for rival Nb3Sn system builders. Lock in long-term helium supply agreements before conservation protocols tighten industrial gas allocation.
For New Entrants and Emerging Players: Build out independent service organization capabilities for coil refurbishment and cryostat maintenance in North American and Western European hospital markets with mature installed bases. Target educational institutions and budget-constrained research laboratories with refurbished 1.5 tesla MRI magnets as the most penetrable entry segment. Lead with unbundled magnet sourcing propositions that bypass incumbent OEM turnkey pricing.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors long-length HTS tape manufacturers with demonstrated artificial pinning center architectures. Five-to-ten year viability hinges on fusion energy commercialization timelines and helium supply chain restructuring. Monitor ITER Organization procurement award announcements as the primary inflection indicator for qualified supplier valuation step-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| REBCO Tape Capacity Expansion | Artificial pinning center deposition scale-up enables compact fusion device qualification for MIT and Commonwealth Fusion Systems test programs. |
| Cryogenic Welding Certification Pipeline | Qualified technician pools for Nb3Sn joint fabrication constrain General Atomics and Siemens Energy magnet installation schedules. |
| Helium Recovery Infrastructure Retrofit | Industrial gas suppliers capture aftermarket revenue from closed-cycle cryocooler integration mandated by EU F-Gas Regulation phase-down. |
| Hospital Magnet Unbundling Strategy | Independent service organizations displace OEM service revenue through direct coil refurbishment procurement in tier-one Chinese cities. |
| Fusion-Grade Qualification Investment | ITER Organization certification opens national laboratory procurement channels for high-field research magnet deliveries. |
Research Methodology
A spread of perspectives from magnet system design engineers, hospital biomedical equipment procurement managers, cryogenic subsystem specialists, and fusion energy program directors converged on the working assumptions for this analysis. Primary fieldwork combined structured interviews with secondary validation against ITER Organization procurement specifications, FDA 510(k) clearance databases, NMPA medical device registration filings, and EU MDR technical documentation requirements. Bottom-up unit economics for NbTi wire, REBCO tape, and cryostat assembly triangulated against top-down market sizing from national laboratory capital expenditure disclosures and hospital fleet replacement surveys.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by field strength tier, application context by regulatory pathway, end-user category by financing structure, and technology selection by operating temperature regime. CAGRs were derived from weighted average replacement cycle timing, grant-funded research procurement schedules, and fusion energy roadmap milestone phasing. Forecast inputs included helium market price trajectories, rare-earth element supply quotas, and HTS tape manufacturing yield curves.
Practitioners should monitor ITER construction milestone delays, NMPA registration pathway revisions, and East Asian rare-earth export quota announcements for early signals requiring forecast reassessment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Space DC-DC Converters Market
Power Systems
Burner Management System (BMS) Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Battery Racks Market
Power Systems
Liquid Cooling Systems Market
Power Systems
Modular Inverter Market
Power Systems
Asia-Pacific DC Distribution Networks Market
Power Systems
Automotive Power Semiconductor Market
Power Systems
Europe Shunt Reactors Market
Power Systems
Bypass Thyristor Market
Power Systems
Power Electronics for Electric Vehicle Market
Power Systems
Global Excitation Systems Market
Power Systems
Global Battery Thermal Management System Market
Power Systems
Battery Cyclers Market
Power Systems
Smart Junction Box and Power Distribution Box Systems Market
Power Systems
Power Supply and Charger Market