
 Batteries for Semiconductor Market | 2026-2036
Batteries for Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Batteries for Semiconductor Market Outlook
Direct supply channels between cell manufacturers and semiconductor fabs is fragmenting as foundries diversify backup power vendors to reduce concentration risk. Samsung SDI Co Ltd anchors high-density lithium-ion supply for Korean memory fabs, leveraging its vertical integration into cathode materials. Panasonic Corporation competes through solid-state R&D partnerships with Japanese equipment makers, while CATL extends its manufacturing scale to serve China's expanding wafer fabrication capacity.
Batteries for semiconductor applications are electrochemical energy storage systems engineered for sub-millisecond response times, typically operating at 48V or 400V DC with temperature tolerances spanning minus 40 to 60 degrees Celsius to maintain cleanroom environmental stability. Their primary purpose is eliminating voltage sags that corrupt lithography processes costing millions per interrupted wafer batch. Lithium-ion dominates installed base owing to energy density advantages in space-constrained subfab environments, whereas solid-state chemistries capture premium positioning where thermal runaway risks must approach zero. Application demand skews heavily toward industrial equipment, specifically ion implanters and EUV scanners, as consumer electronics represents a smaller adjacent segment with less stringent uptime requirements.
OSHA electrical safety standards and EPA hazardous material rules govern US fab battery installations, while REACH and RoHS compliance in Europe restrict cadmium and lead content in backup systems sold to semiconductor customers. South Korea's KOSHA industrial safety framework and Taiwan's Bureau of Standards, Metrology and Inspection enforce localized testing protocols that create non-tariff barriers for imported cells. Stakeholders must monitor how evolving cleanroom particulate standards intersect with battery ventilation requirements, as regulatory misalignment between jurisdictions threatens to fragment product certification pathways.
Market Dynamics
Foundry expansion in East Asian manufacturing clusters is outpacing grid infrastructure upgrades, forcing fabs to internalize power resilience through advanced battery architectures rather than relying on utility stability.
Growth Catalysts
- Sub-millisecond response requirements:EUV lithography systems cannot tolerate voltage sags exceeding 4 milliseconds, mandating battery-backed uninterruptible power supplies for all new fab construction.
- REACH and RoHS compliance:European restrictions on cadmium and lead content accelerate lithium-ion substitution in legacy nickel-cadmium backup installations.
- Hsinchu Science Park concentration:Taiwan's foundry hub generates concentrated procurement volume that justifies dedicated cell production lines and localized technical support infrastructure.
Market Restraints
- Cathode material cost volatility:Nickel and cobalt price swings compress margins for high-nickel NMC cell producers serving the semiconductor segment.
- Korean supplier concentration:Samsung SDI and LG Energy Solution control over 70 percent of premium lithium-ion supply for memory fabs, creating single-source vulnerability.
- Thermal runaway containment:Solid-state electrolyte manufacturing yields remain below commercial viability thresholds for large-format industrial applications.
Strategic Opportunities
- China wafer fabrication buildout:Domestic 300mm fab construction under MIIT industrial policy creates demand for localized battery supply chains.
- Solid-state lithium-metal convergence:Sulfide electrolyte architectures paired with lithium-metal anodes promise energy density gains for space-constrained subfab installations.
- Direct OEM contracting:Foundries are bypassing traditional distributor networks to negotiate cell supply agreements directly with manufacturers.
Industry Challenges
- Cleanroom ventilation integration:Battery off-gassing protocols must align with ISO 14644 particulate standards, complicating subfab layout engineering.
- Multi-jurisdiction certification:Cells require simultaneous KOSHA, BSMI, and UL 1973 approvals, extending qualification timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Batteries for Semiconductor Market |
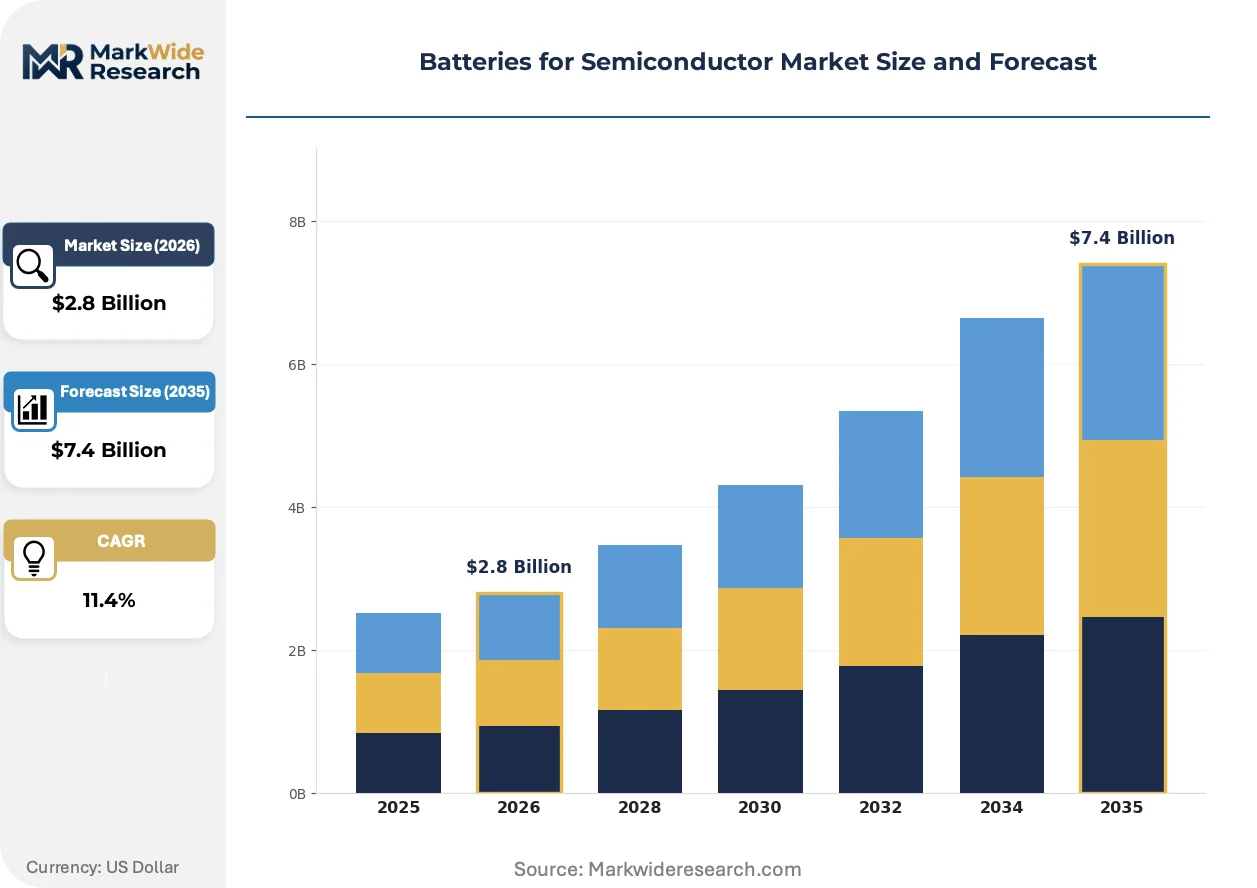
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Nickel-Cadmium, Lead-Acid, Solid-State Application: Consumer Electronics, Industrial Equipment, Automotive, Energy Storage Systems Technology: Rechargeable, Non-Rechargeable, Hybrid, Fuel Cell End User: Manufacturers, OEMs, Retailers, Research Institutions |
| Companies Covered | Samsung SDI Co Ltd, Panasonic Corporation, Sony Corporation, Varta AG, Toshiba Corporation, CATL, LG Energy Solution, BYD, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Batteries for Semiconductor Market Strategic Shifts
Solid-state electrochemistry and direct fab-to-cellmaker contracting are restructuring how backup power systems are specified, procured, and deployed in semiconductor manufacturing environments.
Sulfide-based solid-state batteries eliminate flammable liquid electrolytes while enabling lithium-metal anodes with theoretical energy density exceeding 400 Wh/kg. TSMC and Samsung Foundry have initiated pilot programs for subfab installations where thermal runaway risks approach zero. Conventional liquid-electrolyte lithium-ion architectures are rendering obsolete for premium lithography backup applications where safety margins dominate cost considerations.
South Korea's KOSHA industrial safety framework now mandates third-party thermal propagation testing for all battery systems installed in semiconductor facilities, exceeding baseline IEC 62619 requirements. This regulatory layering forces cell manufacturers to maintain separate product variants for Korean versus Taiwanese versus US deployments. Memory fabs in Yongin and Pyeongtaek face the steepest compliance burden as KOSHA inspectors enforce sub-5-minute emergency response protocols.
Long-term service agreements bundling cell replacement, predictive monitoring, and performance guarantees are displacing transactional equipment sales in foundry procurement. ASML and Applied Materials now specify battery subsystem vendors who can commit to 15-year total cost of ownership contracts. This contractual evolution is most pronounced in Taiwan's Hsinchu-Taichung corridor where foundry operators prioritize operational expenditure predictability over capital expenditure minimization.
Batteries for Semiconductor Market Segmentation
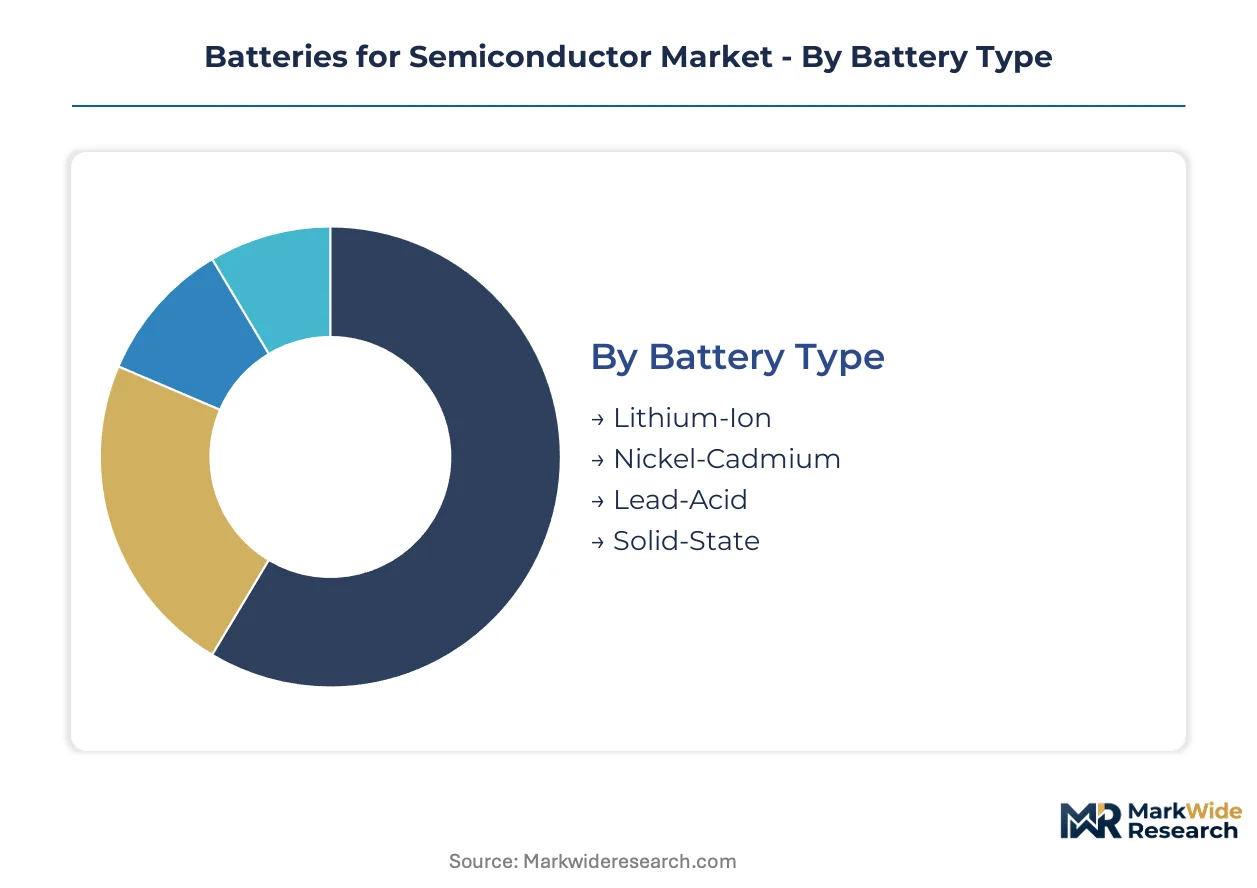
Semiconductor fabs specify batteries across multiple intersecting dimensions. Procurement teams balance electrochemical performance against cleanroom safety protocols while foundry expansion timelines compress vendor qualification windows.
Battery Type:
Mature liquid-electrolyte systems dominate installed base volumes as emerging solid-state architectures capture premium positioning.
- Lithium-Ion:High energy density (200-300 Wh/kg) suits space-constrained subfab installations beneath EUV scanners. Korean memory fabs in Yongin and Pyeongtaek anchor procurement concentration as foundry operators prioritize footprint efficiency over absolute safety margins.
- Solid-State:Sulfide electrolyte architectures paired with lithium-metal anodes eliminate thermal runaway risks. TSMC pilot programs in Hsinchu Science Park drive early adoption where lithography uptime justifies 40-60% cost premiums.
- Nickel-Cadmium:Legacy nickel-cadmium systems persist in older 200mm fabs with established maintenance protocols.
- Lead-Acid:Lead-acid remains confined to non-critical auxiliary loads where response time tolerances exceed 50 milliseconds.
Lithium-ion retains volume leadership; solid-state holds the steepest expansion curve.
Application:
Cost tier stratification separates mission-critical process equipment from peripheral facility loads.
- Industrial Equipment:Ion implanters and EUV scanners require sub-4-millisecond response times that only advanced lithium-ion or solid-state architectures deliver. Taiwan's foundry cluster generates concentrated demand as Hsinchu-Taichung corridor fabs expand 300mm capacity faster than grid stability improvements.
- Energy Storage Systems:Grid-tied battery installations buffer fabs against voltage sags from utility switching events. South Korean fab operators under KOSHA mandates deploy these systems for emergency load shedding during peak demand periods.
- Consumer Electronics:Semiconductor test equipment for mobile device chips uses standard-grade backup with less stringent uptime requirements.
- Automotive:Automotive-grade chip testing facilities require batteries meeting AEC-Q200 vibration standards.
Industrial equipment commands premium pricing tiers; energy storage systems are expanding most quickly as grid reliability concerns mount.
Technology:
Customer type determines procurement patterns across rechargeable versus single-use architectures.
- Rechargeable:Cyclability exceeding 5,000 deep discharges suits daily load-following operations in fabs with unstable grid connections. Chinese wafer fabrication buildout under MIIT policy creates demand for lithium iron phosphate variants with extended calendar life.
- Hybrid:Hybrid systems combining battery and ultracapacitor elements address pulsed power demands from stepper motor drives. Japanese equipment makers in Kyoto-Osaka corridor specify these for next-generation lithography platforms.
- Non-Rechargeable:Primary lithium thionyl chloride cells serve safety-critical emergency lighting in subfab environments.
- Fuel Cell:Hydrogen fuel cell backup occupies niche applications requiring multi-day autonomy beyond battery practical limits.
Rechargeable systems dominate procurement volumes; hybrid configurations gain share fastest as lithography power profiles grow more dynamic.
End User:
Supply concentration varies dramatically between direct fab operators and intermediary channels.
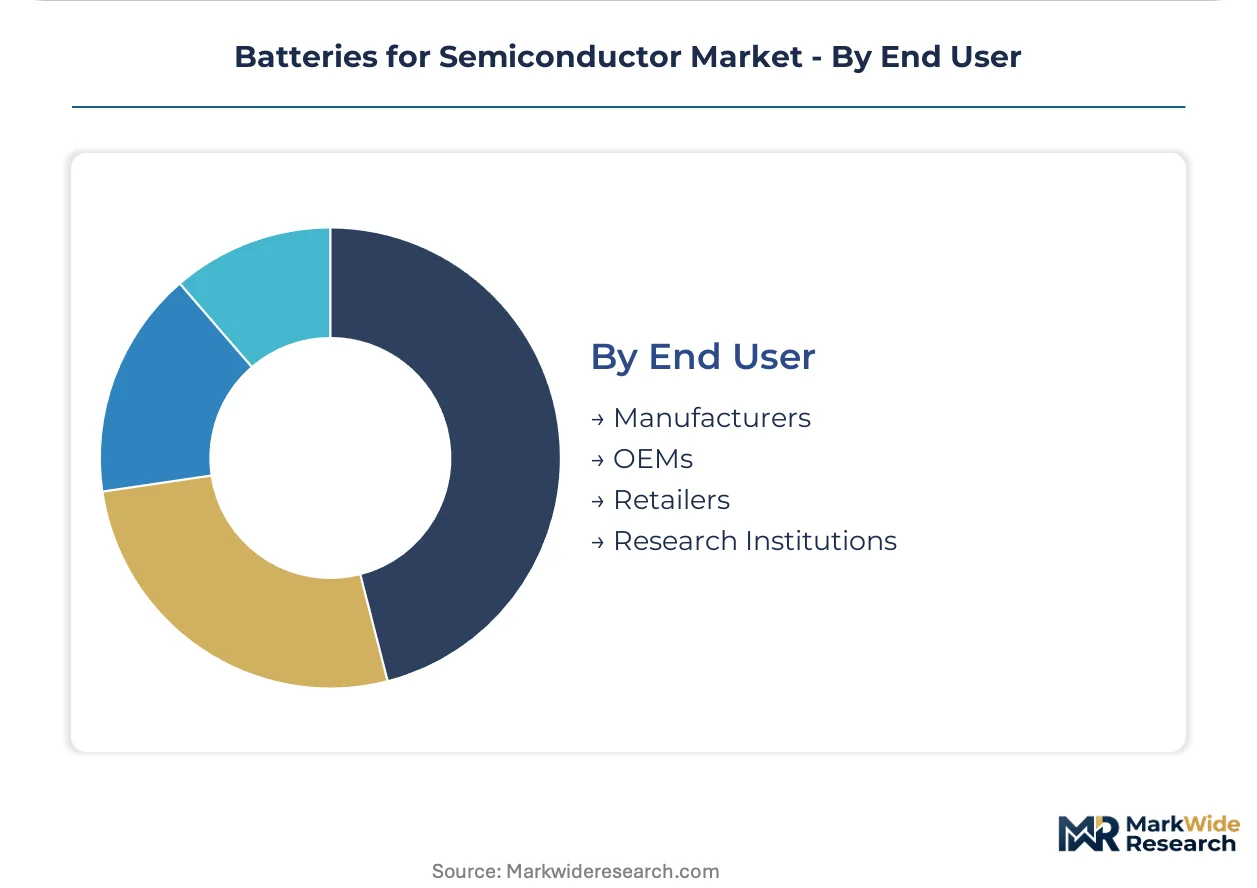
- Manufacturers:Integrated device manufacturers operating captive fabs negotiate long-term service agreements bundling cell replacement and predictive monitoring. Intel's Arizona and Oregon facilities exemplify this procurement mode with 15-year total cost of ownership contracts.
- OEMs:Applied Materials and ASML specify battery subsystems for equipment platforms sold globally. These vendors demand unified product variants certifiable across KOSHA, BSMI, and UL 1973 jurisdictions to avoid SKU proliferation.
- Research Institutions:University-affiliated nanofabrication centers purchase smaller quantities with relaxed qualification timelines.
- Retailers:Distributor channels serve maintenance-repair-operations demand in legacy fab installations.
Manufacturers drive absolute volume; OEMs are climbing the fastest as toolmakers internalize power subsystem responsibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hsinchu-Taichung science corridor anchors East Asian semiconductor fabrication capacity, while Arizona's Fab 52 complex and Saxony's Silicon Saxony cluster represent emerging Western production nodes dependent on specialized battery backup infrastructure.
Taiwan
EUV lithography deployment at TSMC's Fab 18 and Fab 20 drives sub-millisecond UPS procurement volumes unmatched elsewhere. Bureau of Standards, Metrology and Inspection enforces localized cell testing protocols that extend qualification timelines. Hsinchu Science Park concentrates demand where foundry expansion outpaces Taipower grid stability investments.
South Korea
Memory fab construction in Yongin and Pyeongtaek generates concentrated procurement for high-density lithium-ion architectures. KOSHA mandates third-party thermal propagation testing exceeding IEC 62619 baselines. Samsung Foundry's Pyeongtaek complex operates under sub-5-minute emergency response protocols that shape vendor selection criteria.
United States
CHIPS Act subsidies accelerate 300mm fab construction in Arizona, Ohio, and Texas with accompanying battery infrastructure requirements. OSHA electrical safety standards and EPA hazardous material rules govern installation protocols. Intel's Fab 52 in Chandler exemplifies long-term service agreement procurement bundling 15-year performance guarantees.
China
Domestic wafer fabrication buildout under MIIT industrial policy creates demand for localized lithium iron phosphate supply chains. GB standards and SAMR certification requirements favor domestic cell manufacturers. Yangtze River Delta clusters in Shanghai and Wuxi concentrate 300mm capacity expansion where grid instability necessitates advanced backup systems.
Japan
Equipment maker specifications from Kyoto-Osaka corridor tool vendors drive hybrid battery-ultracapacitor adoption for next-generation lithography platforms. METI cleanroom energy standards intersect with JIS certification pathways. Kumamoto's emerging fab cluster represents procurement growth as TSMC and Sony expand joint manufacturing capacity.
Batteries for Semiconductor Market Competitive Environment
On the supply side, the industry is consolidating around three strategic archetypes: vertically integrated material producers, solid-state technology specialists, and scale-driven manufacturing platforms. Korean conglomerates anchor premium lithium-ion supply through captive cathode production, while Japanese and Chinese competitors differentiate via sulfide electrolyte R&D partnerships and manufacturing scale respectively. Dominant competitive moves include direct OEM contracting arrangements that bypass distributor networks, and long-term service agreements bundling predictive monitoring with cell replacement commitments.
Within the Korean conglomerate tier, Samsung SDI Co Ltd and LG Energy Solution occupy positions representing vertical integration archetypes, while CATL exemplifies scale-driven manufacturing platforms serving China's domestic wafer fabrication expansion. Panasonic Corporation anchors Japanese solid-state development partnerships, occupying a specialist position distinct from volume-oriented competitors.
| Leading Market Players |
|---|
| Samsung SDI Co Ltd |
| Panasonic Corporation |
| Sony Corporation |
| Varta AG |
| Toshiba Corporation |
| CATL |
| LG Energy Solution |
| BYD |
| Infineon Technologies |
| Others |
Value Chain & Pricing Dynamics
The Kaohsiung-to-Busan maritime corridor channels cathode active material shipments that feed Korean and Taiwanese cell production, with freight cost volatility amplifying price spreads between premium solid-state architectures and commodity lithium-ion alternatives while fabs in Hsinchu and Yongin negotiate volume-based service agreements that compress distributor margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with premium tiers anchored by KOSHA-certified solid-state systems for Korean memory fabs and economy tiers serving legacy lead-acid replacements in auxiliary loads. Price differentiation rests on certification grade and after-sales service bundling, as 15-year total cost of ownership contracts command 25-40% markups over transactional equipment sales. Cost compression in standard-tier NMC cells is intensifying because nickel and cobalt price swings squeeze cathode producers. Research institutions and university nanofabrication centers exhibit highest price sensitivity, while integrated device manufacturers running captive fabs prioritize performance guarantees over unit economics.
Supply Chain Analysis
Export-control regimes restricting sulfide electrolyte precursor flows complicate solid-state battery scaling, particularly for Japanese equipment makers sourcing from Kyoto-Osaka corridor suppliers. Geographic supply concentrates in China, South Korea, and Japan, with cathode active materials drawing from Indonesian nickel and Chilean lithium processing. Raw material dependencies on cobalt hydroxide, lithium hexafluorophosphate, and ceramic-coated separators create single-source vulnerability when geopolitical tensions disrupt maritime lanes. Distribution runs through direct OEM contracting channels that bypass traditional electronics distributors, with ASML and Applied Materials specifying unified product variants certifiable across KOSHA, BSMI, and UL 1973 jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor battery procurement is shifting toward platform-economics dynamics where long-term service agreements function as interoperability layers binding cell manufacturers to fab operators, with ASML's 15-year performance guarantee specifications establishing the dominant ecosystem architecture.
For Market Incumbents: Pre-empt solid-state substitution by accelerating sulfide electrolyte pilot deployments before TSMC and Samsung Foundry finalize vendor qualifications for subfab installations. Samsung SDI and LG Energy Solution should deepen backward integration into Indonesian nickel processing to offset cathode cost volatility, while Panasonic must secure JIS-METI certification pathways ahead of Kumamoto fab cluster expansion. Threat of Chinese lithium iron phosphate scale players entering premium segments through MIIT-subsidized domestic supply chains demands defensive positioning.
For New Entrants and Emerging Players: Mid-market 200mm legacy fabs in Southeast Asia represent the most penetrable entry point, as these facilities face EUV upgrade pressure but retain nickel-cadmium infrastructure requiring lithium-ion substitution under REACH compliance timelines. Chinese wafer fabrication buildout under MIIT policy creates localized supply chain demand where CATL scale advantages are less entrenched. Go-to-market angle should emphasize rapid BSMI certification completion to compress qualification timelines against established Korean suppliers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors solid-state specialists with sulfide electrolyte intellectual property over commodity lithium-ion scale players, as thermal runaway elimination becomes non-negotiable for sub-5-minute emergency response protocols. Acquisition targets should demonstrate KOSHA pre-certification progress and existing pilot program relationships with TSMC or Samsung Foundry. Signal to monitor is KOSHA inspector enforcement intensity at Yongin and Pyeongtaek complexes, as regulatory layering beyond IEC 62619 baselines would accelerate premium-tier demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Pilot Deployment | TSMC and Samsung Foundry subfab programs validate sulfide electrolyte architectures for lithography backup. |
| Backward Integration into Cathode Materials | Samsung SDI's captive nickel processing insulates margin structure against Indonesian supply volatility. |
| Direct OEM Contracting Bypass | ASML and Applied Materials specifications eliminate distributor markups while unifying certification requirements. |
| 15-Year Service Agreement Bundling | Intel's Fab 52 procurement mode shifts foundry preference toward operational expenditure predictability. |
| Multi-Jurisdiction Certification Pre-Positioning | Unified KOSHA-BSMI-UL 1973 variants reduce SKU proliferation for equipment makers serving global fab networks. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from battery and equipment manufacturers, KOSHA inspection reports, and BSMI certification databases. Primary interviews incorporated fab engineering directors, cell manufacturer account executives serving Hsinchu-Taichung corridor, cleanroom ventilation specialists, and procurement leads at integrated device manufacturers. Bottom-up demand modeling from individual fab expansion projects was cross-checked against top-down capacity forecasts for 300mm wafer fabrication.
Forecast inputs span battery type segmentation, application criticality tiers, technology architecture choices, and end-user procurement modes across the projection horizon. Segmentation dimensions modeled include electrochemical chemistry, cleanroom integration requirements, response time specifications, and regional regulatory cluster variations. CAGRs were derived from installed base turnover rates and foundry construction timelines rather than extrapolated trend fitting. Industry-specific inputs incorporated EUV lithography deployment schedules and MIIT policy guidance for Chinese wafer fabrication capacity.
Stress conditions across nickel-cobalt price volatility, KOSHA regulatory layering intensity, and solid-state manufacturing yield trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts assume continued REACH and RoHS compliance timelines without abrupt cadmium or lead content restriction acceleration. Material shifts in sulfide electrolyte precursor export controls or Taipower grid stability investment delays would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
DC Power Supplies Market
Power Systems
Synchronous Condenser Market
Power Systems
Asia-Pacific IGBT and Super Junction MOSFET Market
Power Systems
DC-DC Converter Market
Power Systems
Central Battery Systems Market
Power Systems
Smart Power Strips Market
Power Systems
Traction Inverter Market
Power Systems
Europe Micro Inverter Market
Power Systems
Global Rugged Power Supply Market
Power Systems
String Inverter Market
Power Systems
Europe Variable Frequency Drive Market
Power Systems
Telecom Battery Market
Power Systems
Automotive Power Semiconductor Market
Power Systems
DC Stabilized Power Supply Market
Power Systems
Global Synchronous Motor Market
Power Systems
Battery Voltage Supervisor Market