
 Global Chip Power Inductor Market | 2026-2036
Global Chip Power Inductor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chip Power Inductor Market Analysis
Japanese ferrite and powdered iron producers is broadening capacity to serve electric vehicle inverter demand. Murata Manufacturing leverages its ceramic substrate integration to dominate high-frequency applications. TDK Corporation anchors magnetics R&D through its extensive patent portfolio in alloy powder formulations. Vishay Intertechnology competes on automotive AEC-Q200 qualification breadth across laminated and composite designs.
Chip power inductors are passive magnetic components, typically wound around ferrite or metal alloy cores and rated for currents from milliamps to tens of amps, that store energy in switching power supplies and filter ripple in DC-DC converters. They measure under 10 mm in most surface-mount configurations and operate at frequencies spanning hundreds of kilohertz to several megahertz in modern voltage regulator modules. Molded inductors command premium positioning due to superior thermal stability and shielding performance in dense PCB layouts. Powdered iron variants represent the fastest-expanding technology segment as saturation current requirements climb in automotive DC-DC stages. Flat-type products occupy mature margin pools in consumer electronics volume tiers where cost engineering dominates supplier selection.
Japan's METI enforces JIS standards on electromagnetic component efficiency and reliability grading, while China's MIIT mandates GB compliance for inductors deployed in domestic telecommunications infrastructure. The EU F-Gas Regulation indirectly shapes material choices by restricting fluorinated compounds in manufacturing processes. Stakeholders must monitor how REACH substance restrictions and evolving automotive functional safety standards redefine qualification timelines for new core material formulations.
Market Dynamics
Automotive electrification is compressing qualification timelines as OEMs demand inductors rated for 150°C ambient operation and 2 MHz switching frequencies in integrated power modules. Tier-1 suppliers now co-develop magnetics with semiconductor partners rather than sourcing catalog parts.
Growth Catalysts
- China's dual carbon goals:MIIT efficiency mandates for domestic telecommunications infrastructure are forcing upgrades to high-frequency ferrite cores in base station power supplies.
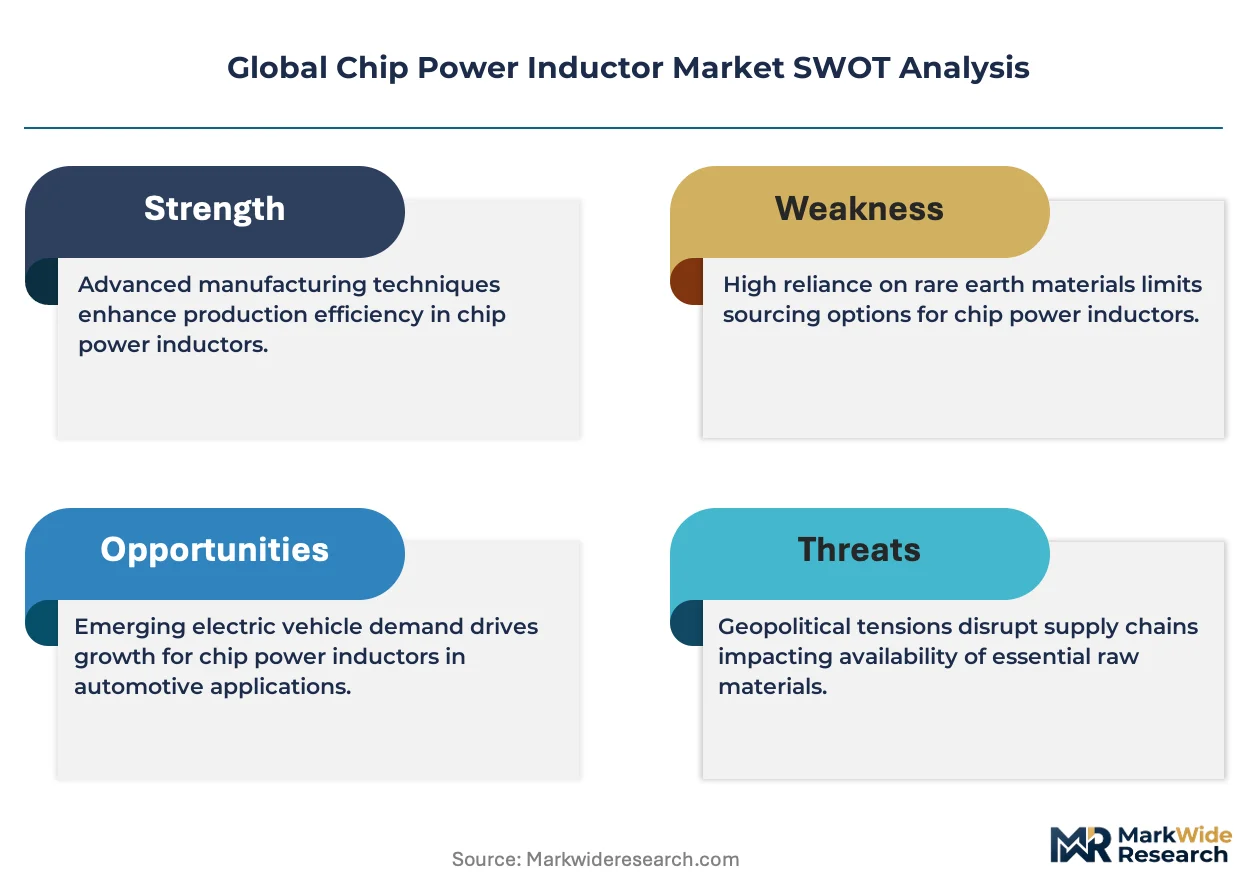
- Electric vehicle traction inverters:Automotive OEMs in Germany and Japan specify molded alloy powder inductors for DC-DC stages handling 48V to 12V conversion.
- Tokyo-Osaka manufacturing corridor:Concentrated magnetics R&D and powder metallurgy expertise accelerates prototype-to-production cycles for next-generation core formulations.
Market Restraints
- Raw material concentration:Rare earth element processing for high-permeability ferrites concentrates in Chinese smelting facilities, exposing buyers to export quota volatility.
- REACH substance restrictions:ECHA scrutiny of nickel and cobalt compounds in alloy powders extends qualification timelines for new automotive-grade formulations.
- Technical ceiling at megahertz frequencies:Core loss characteristics in traditional ferrites impose hard limits on miniaturization for multi-phase voltage regulator modules.
Strategic Opportunities
- India's PLI scheme for electronics:Contract manufacturers establishing surface-mount capacity in Tamil Nadu and Karnataka create localized demand for standard chip inductor supply.
- AI server power architectures:48V direct-to-chip conversion topologies in hyperscale data centers require high-current composite inductors with sub-milliohm DC resistance.
- EU F-Gas Regulation:Restrictions on fluorinated compounds in manufacturing processes incentivize dry pressing and sintering methods for ferrite core production.
Industry Challenges
- Magnetics design talent scarcity:Specialized expertise in distributed gap modeling and thermal-mechanical finite element analysis concentrates among retiring engineers in Japan and Germany.
- AEC-Q200 certification burden:Automotive functional safety requirements under ISO 26262 extend validation cycles to 18-24 months for new inductor families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chip Power Inductor Market |
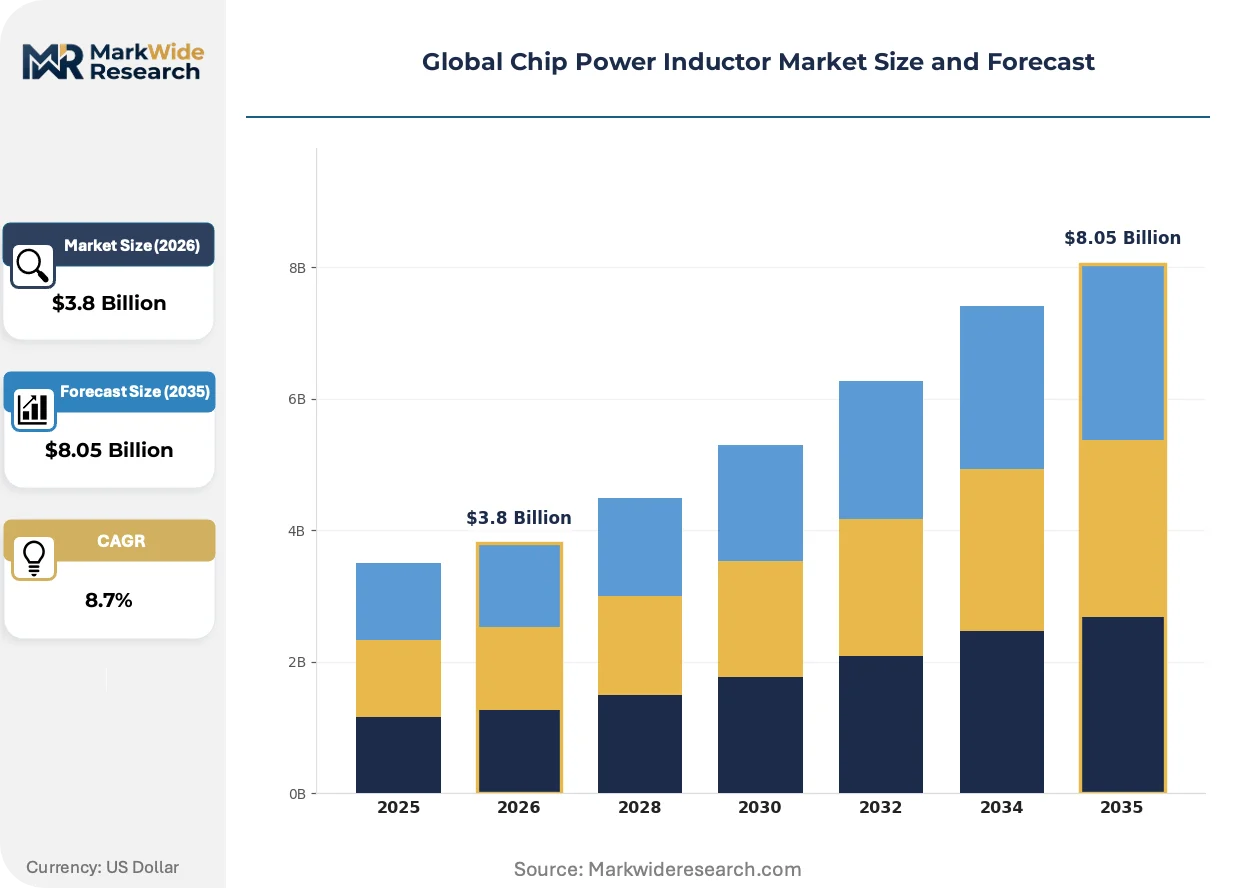
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat, Molded, Chip, Thru-Hole Technology: Ferrite, Powdered Iron, Laminated, Composite Application: Consumer Electronics, Automotive, Industrial Equipment, Telecommunications End User: OEMs, Distributors, Aftermarket Providers, Retailers |
| Companies Covered | Murata Manufacturing, TDK Corporation, Taiyo Yuden, Panasonic, Chilisin Electronics, Sumida Corporation, Shenzhen Sunlord Electronics, Vishay Intertechnology, Delta Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chip Power Inductor Market Emerging Trajectories
Magnetics technology is bifurcating between commodity ferrites for consumer electronics and engineered alloy composites for power-dense applications. Regulatory pressure on manufacturing chemistry and thermal performance specifications is accelerating process innovation.
Powdered iron cores with distributed air gap architectures are overtaking traditional ferrite designs in automotive DC-DC converters. Tier-1 suppliers specify these materials for 48V mild-hybrid systems requiring saturation currents above 30A. The technology is overtaking laminated steel alternatives by enabling 40% volume reduction in multi-phase buck regulators.
Japan's METI enforces revised JIS C 2560 standards for electromagnetic component reliability grading, mandating accelerated life testing protocols. The regulation forces suppliers to disclose core loss data at elevated temperatures. Automotive module manufacturers in Nagoya and Hiroshima prefectures now require JIS compliance documentation for all new inductor qualifications.
Consolidated procurement through semiconductor distributors is displacing direct OEM relationships for standard chip inductor volumes. Arrow Electronics and Avnet are capturing specification influence by bundling magnetics with MOSFET and controller portfolios. This channel shift concentrates most visible in Taiwanese contract manufacturers serving North American server OEMs.
Global Chip Power Inductor Market Segmentation
Chip power inductor segmentation reveals how magnetic component suppliers align manufacturing capabilities with divergent thermal, frequency, and current density requirements across end-use verticals. Product form factors and core material technologies command distinct qualification pathways and margin structures.
Product Type:
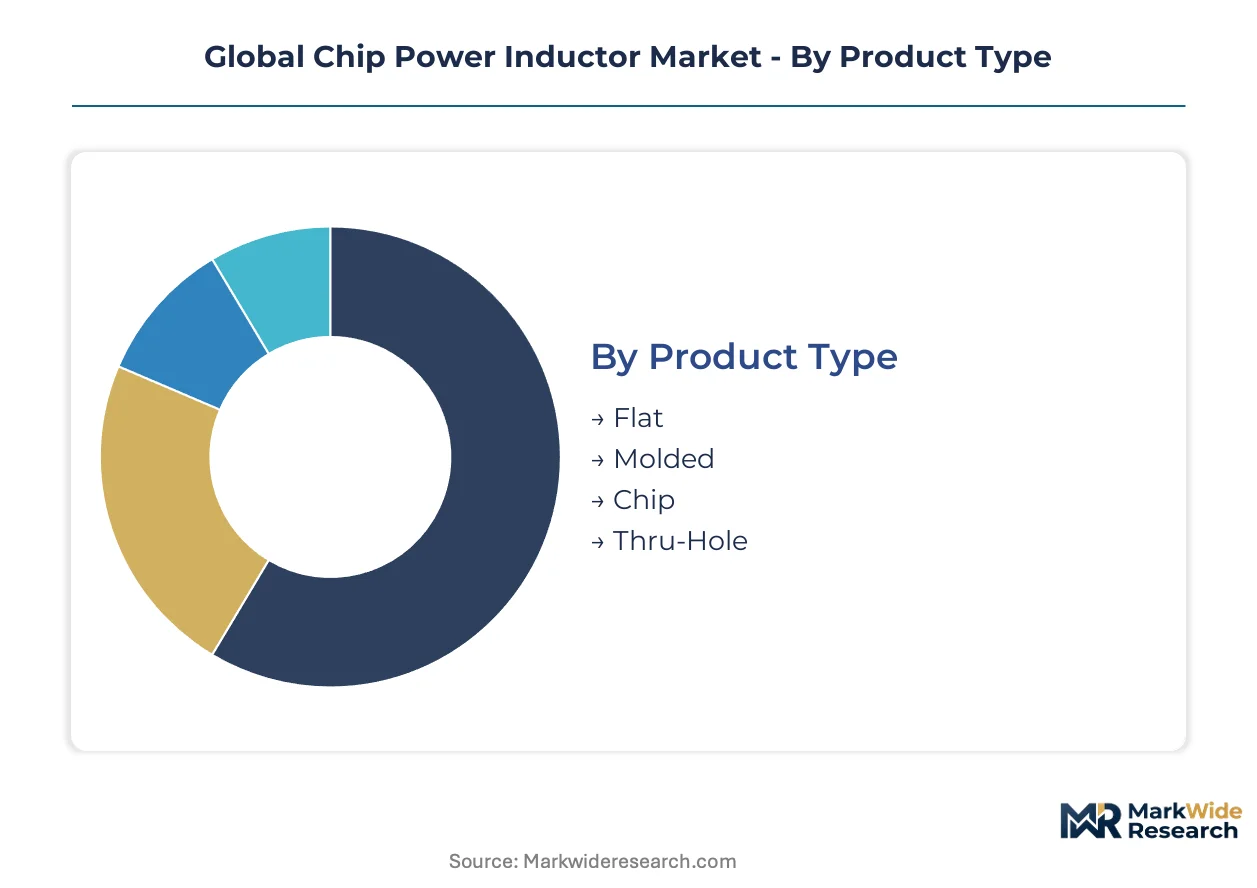
Physical construction determines thermal dissipation, electromagnetic shielding, and mounting compatibility in dense PCB assemblies.
- Molded:Encapsulated designs using thermally conductive compounds achieve superior heat spreading and reduced magnetic interference in multi-phase voltage regulators. Automotive DC-DC converters in Germany and Japan specify these for 150°C ambient operation and 2 MHz switching frequencies.
- Flat:Low-profile wound constructions dominate consumer electronics volume tiers where z-height constraints below 2mm override performance margins. Cost engineering pressures from Taiwanese contract manufacturers compress supplier selection to standardized ferrite cores.
- Chip:Surface-mount configurations under 10mm suit high-density telecom infrastructure and server motherboard deployments. MIIT efficiency mandates for China's domestic base station power supplies accelerate upgrades to high-frequency rated variants.
- Thru-Hole:Leaded constructions persist in industrial equipment requiring mechanical robustness against vibration and thermal cycling. Legacy manufacturing in Japan's Nagoya prefecture maintains capacity for these lower-automation products.
Molded leads on scale; Chip leads on momentum.
Technology:
Core material chemistry directly shapes saturation current limits, core loss characteristics, and qualification timelines under automotive functional safety standards.
- Powdered Iron:Distributed air gap architectures enable 40% volume reduction versus laminated alternatives in multi-phase buck regulators handling 30A+ saturation currents. Tier-1 suppliers specify these for 48V mild-hybrid DC-DC stages.
- Ferrite:Manganese-zinc and nickel-zinc formulations anchor high-frequency applications through low core loss at megahertz switching frequencies. METI's revised JIS C 2560 standards mandate accelerated life testing disclosure for these materials.
- Laminated:Stacked steel constructions serve cost-sensitive industrial motor drives and legacy power supplies. ECHA scrutiny of nickel compounds in alloy powders extends qualification timelines for automotive-grade iterations.
- Composite:Hybrid material systems combining ferrite and metal alloy properties target AI server 48V direct-to-chip conversion architectures. Sub-milliohm DC resistance specifications from hyperscale data center operators in the US and China concentrate demand.
Ferrite leads on scale; Powdered Iron leads on momentum.
Application:
End-use thermal environments and reliability specifications fragment procurement criteria across qualification-intensive automotive and cost-optimized consumer segments.
- Automotive:Electrification compresses development cycles as OEMs integrate inductors into integrated power modules. AEC-Q200 certification and ISO 26262 functional safety requirements extend validation to 18-24 months.
- Telecommunications:China's dual carbon goals and MIIT infrastructure mandates force base station power supply upgrades. High-frequency ferrite cores rated for elevated temperatures dominate procurement.
- Consumer Electronics:Smartphone and laptop manufacturers prioritize z-height minimization and unit cost over thermal margin. Shenzhen manufacturing clusters concentrate sourcing for these specifications.
- Industrial Equipment:Motor drives and automation systems demand vibration tolerance and extended operating lifecycles. EU F-Gas Regulation restrictions on fluorinated compounds incentivize dry pressing methods for core production.
Consumer Electronics leads on scale; Automotive leads on momentum.
End User:
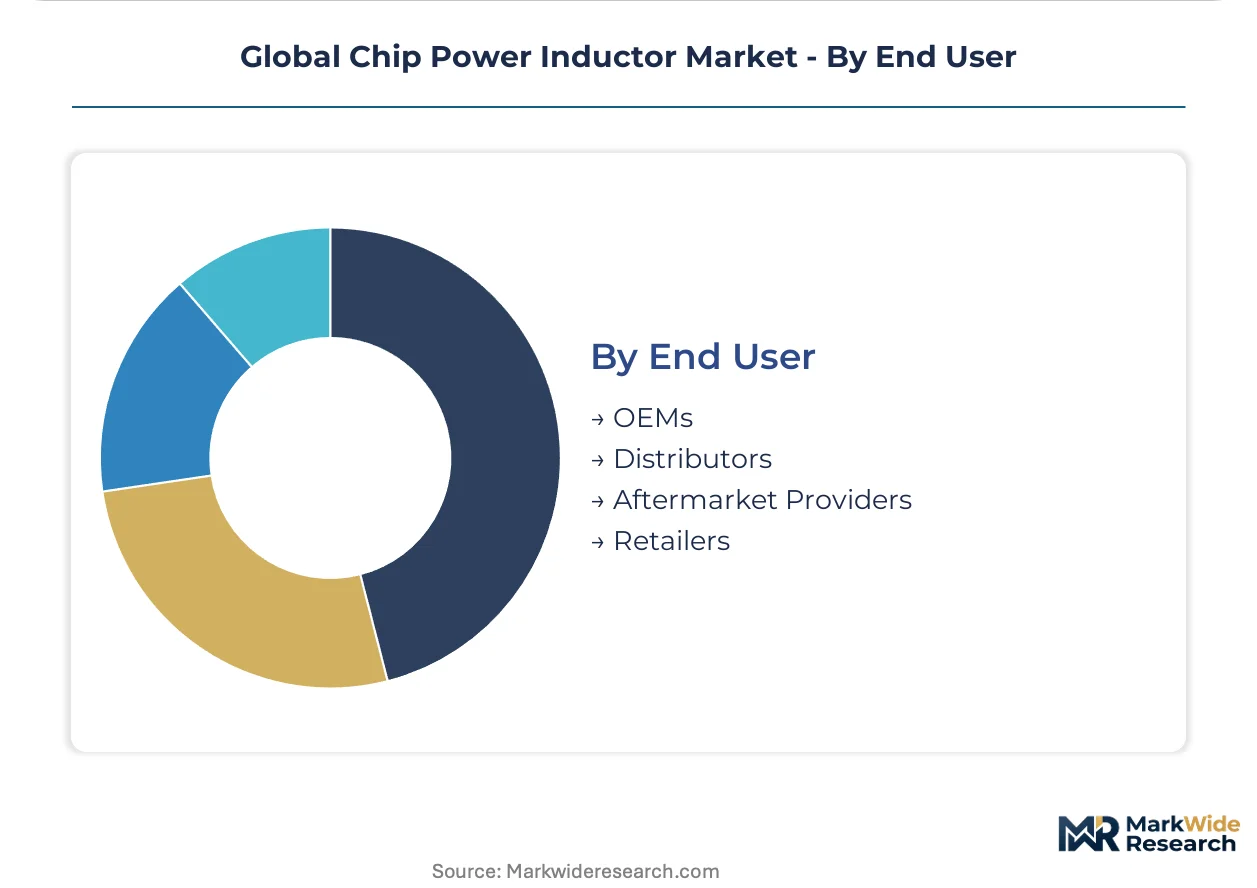
Channel structure determines specification influence, with semiconductor distributors displacing direct OEM relationships for standard volumes.
- OEMs:Automotive and server manufacturers co-develop magnetics with semiconductor partners rather than sourcing catalog parts. Direct collaboration concentrates in Germany, Japan, and US technology corridors.
- Distributors:Arrow Electronics and Avnet bundle inductors with MOSFET and controller portfolios. Taiwanese contract manufacturers serving North American server OEMs exhibit this channel shift most visibly.
- Aftermarket Providers:Repair and replacement demand for industrial equipment sustains thru-hole and legacy chip inductor supply. Regional distributors in India's Tamil Nadu and Karnataka serve emerging manufacturing capacity.
- Retailers:Electronics component retailers capture hobbyist and small-batch production demand. Online channels displace brick-and-mortar presence for standard value-tier products.
Distributors leads on scale; OEMs leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between jurisdictions are redirecting manufacturing investment. Japan's METI enforces stringent JIS C 2560 reliability standards, while China's MIIT mandates GB compliance with lighter administrative burden. This divergence concentrates high-specification production in Japanese industrial corridors and volume manufacturing in Chinese coastal clusters.
China
MIIT efficiency mandates for telecommunications infrastructure accelerate base station power supply upgrades. The country's dual carbon goals force procurement of high-frequency ferrite cores rated for elevated temperatures. Shenzhen manufacturing clusters concentrate sourcing for consumer electronics specifications where cost engineering dominates supplier selection.
Japan
METI enforces revised JIS C 2560 standards mandating accelerated life testing disclosure for electromagnetic components. Automotive module manufacturers in Nagoya and Hiroshima prefectures require JIS compliance documentation for all new inductor qualifications. The Tokyo-Osaka manufacturing corridor concentrates magnetics R&D and powder metallurgy expertise.
Germany
Automotive OEMs specify molded alloy powder inductors for 48V mild-hybrid DC-DC conversion stages. ECHA scrutiny of nickel and cobalt compounds under REACH extends qualification timelines for new automotive-grade formulations. Bavarian industrial zones anchor power electronics development for electrified drivetrains.
United States
Hyperscale data center operators require high-current composite inductors with sub-milliohm DC resistance for 48V direct-to-chip conversion. EPA and OSHA frameworks govern manufacturing chemistry without the substance restrictions of EU REACH. Texas and Arizona manufacturing corridors attract power magnetics assembly for server and telecommunications equipment.
India
PLI scheme incentives for electronics manufacturing establish surface-mount capacity in Tamil Nadu and Karnataka. The country's national telecommunications regulator mandates efficiency standards for base station infrastructure. Contract manufacturers in these states create localized demand for standard chip inductor supply chains.
Global Chip Power Inductor Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue automotive electrification and AI server power architectures. The market structures around three tiers: integrated passive component houses with ceramic substrate capabilities, specialized magnetics manufacturers with powder metallurgy expertise, and diversified electronics conglomerates with broad AEC-Q200 qualification breadth. Strategic moves concentrate on co-development partnerships with semiconductor vendors and capacity expansion for alloy powder core formulations.
Within the integrated passive tier, Murata Manufacturing and TDK Corporation exemplify archetypes combining materials science with high-frequency design capabilities. Vishay Intertechnology occupies a position spanning laminated and composite constructions with extensive automotive qualification portfolios. These three anchors represent distinct competitive vectors: ceramic integration, alloy powder R&D depth, and certification breadth across harsh-environment applications.
| Leading Market Players |
|---|
| Murata Manufacturing |
| TDK Corporation |
| Taiyo Yuden |
| Panasonic |
| Chilisin Electronics |
| Sumida Corporation |
| Shenzhen Sunlord Electronics |
| Vishay Intertechnology |
| Delta Electronics |
| Others |
Supply Flow & Price Mechanics
Family-owned Japanese powder metallurgy specialists anchor tier-one supply, translating multi-generational technical debt into pricing discipline that resists commoditization pressure from Shenzhen contract manufacturers. Their captive control over alloy formulation IP compresses distributor margins while sustaining premium positioning for AEC-Q200 qualified inductor families.
Pricing Analysis
Distributor margin compression now defines channel economics as Arrow Electronics and Avnet bundle magnetics with semiconductor portfolios. Three-tier pricing structure across premium molded alloy, standard ferrite chip, and economy flat-type constructions separates automotive-grade JIS-certified supply from Shenzhen-sourced consumer tiers. Pricing pressure stems from Taiwanese contract manufacturers consolidating procurement through volume tenders. Consumer electronics buyers exhibit highest price sensitivity, while automotive module manufacturers prioritize thermal qualification over unit cost.
Supply Chain Analysis
Refurbishment flows for industrial thru-hole inductors sustain aftermarket channels in India's Tamil Nadu corridor, creating secondary supply liquidity outside OEM-direct procurement. Manufacturing concentrates in Japan, China, and Germany, with rare earth ferrite processing tethered to Chinese smelting facilities. Powdered iron core production draws from nickel and cobalt alloy feedstocks subject to ECHA REACH scrutiny. Single-source vulnerability concentrates in high-permeability ferrite precursor supply. Distribution runs through semiconductor distributors for standard volumes and direct OEM partnerships for co-developed automotive magnetics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification and AI server power architectures position this market as a stable compounder, with component demand scaling linearly to inverter and voltage regulator module penetration.
For Market Incumbents: Anticipate margin erosion from consolidated procurement by Taiwanese contract manufacturers by deepening captive powder metallurgy capacity in Nagoya and Hiroshima prefectures. Accelerate JIS C 2560 certification documentation for next-generation alloy formulations ahead of METI disclosure mandates. Defensive priority rests on locking co-development partnerships with semiconductor vendors for integrated power modules.
For New Entrants and Emerging Players: Begin with India's PLI scheme electronics manufacturing clusters in Tamil Nadu and Karnataka, where localized surface-mount capacity creates demand without incumbent supply relationships. Target aftermarket refurbishment flows for industrial equipment requiring legacy thru-hole constructions. Go-to-market leverage centers on regional distributor partnerships bypassing Arrow-Avnet bundling power.
For Investors and Strategic Acquirers: Semiconductor vendors with integrated power module roadmaps are the most active acquirer in this space, seeking captive magnetics design capability. Long-term viability frames around five-to-ten year electrification and AI infrastructure buildout cycles. Acquisition targets should exhibit alloy powder R&D depth and existing AEC-Q200 qualification breadth. Monitor ECHA nickel compound restriction enforcement timelines as inflection signal for qualification timeline risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-Development Partnership with Semiconductor Vendors | Tier-1 automotive suppliers now integrate Murata and TDK magnetics directly into inverter modules rather than sourcing catalog parts. |
| Alloy Powder Core Capacity Expansion | Powdered iron formulations with distributed air gap architectures enable 40% volume reduction in 48V mild-hybrid DC-DC stages. |
| JIS C 2560 Certification Investment | METI accelerated life testing disclosure mandates force suppliers to document core loss data at elevated temperatures. |
| Backward Integration into Ferrite Precursor Supply | Rare earth element processing concentration in Chinese smelting facilities exposes buyers to export quota volatility. |
| Localized Manufacturing in India PLI Corridors | Contract manufacturers in Tamil Nadu and Karnataka create captive demand for standard chip inductor supply chains. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with magnetics design engineers, Tier-1 automotive procurement leads, semiconductor vendor platform architects, and Indian contract manufacturing operations heads. Secondary validation drew from MIIT infrastructure mandate filings, METI JIS standard revision notices, ECHA REACH substance restriction updates, and SEC disclosures from listed passive component manufacturers. Bottom-up demand modeling triangulated against top-down OEM production forecasts.
Segment-weighting applied product type, core material technology, end-use vertical, and geographic manufacturing cluster dimensions across the analysis window. CAGRs derived from inductor content-per-unit scaling in electric vehicle traction inverters and AI server voltage regulator modules. Forecast inputs incorporated switching frequency migration trends and thermal qualification timeline compression under AEC-Q200 and ISO 26262 requirements.
Several conditions sit outside the modeled scope, including unannounced semiconductor vendor platform cancellations and abrupt rare earth export quota restrictions. Forecasts reflect stated OEM electrification roadmaps and hyperscaler data center buildout plans. Practitioners should monitor ECHA nickel compound restriction enforcement and MIIT telecommunications efficiency mandate implementation pace for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Nimh Rechargeable Battery Market
Power Systems
Voltage Stabilizer System Market
Power Systems
North America Electric Vehicle Power Inverter Market
Power Systems
Thermoelectric Assemblies Market
Power Systems
Global Battery Thermal Management System Market
Power Systems
Gan-Powered Chargers Market
Power Systems
High Voltage Direct Current Power Supply Market
Power Systems
EV Power Module Market
Power Systems
Europe Micro Inverter Market
Power Systems
Flyback Transformer Market
Power Systems
Asia-Pacific Automotive DC-DC Converters Market
Power Systems
Series Reactor Market
Power Systems
Superconducting Magnet Systems Market
Power Systems
Battery Racks Market
Power Systems
Battery Balancer Market
Power Systems
Global Telecom Tower Power System Market