
 Surge Suppression IC Market | 2026-2036
Surge Suppression IC Market Size, Share, and Industry Trends Forecast 2026-2036
Surge Suppression IC Market Analytics
Authorized distributor networks for industrial semiconductors is tilting toward direct manufacturer engagement for high-volume surge suppression IC procurement. Texas Instruments leverages its broad analog portfolio to bundle protection devices with power management solutions, sustaining attach rates across automotive and telecom accounts. Infineon Technologies anchors its position through captive silicon carbide expertise that extends into integrated transient suppression for EV powertrains. STMicroelectronics competes by dominating European industrial automation channels with application-specific protection arrays.
A surge suppression IC is a monolithic or multi-die semiconductor device engineered to clamp transient overvoltages within nanoseconds, typically exhibiting response thresholds below one picofarad capacitance for high-speed data line integrity. These components safeguard downstream electronics from electrostatic discharge, lightning-induced surges, and inductive load switching events across voltage rails from sub-five-volt logic to kilovolt-class industrial bus architectures. TVS Diodes and Integrated Circuit Solutions command the deepest margin pools where automotive functional safety requirements and telecom backhaul density converge. Suppressors designed for Active Filtering architectures represent the fastest-expanding technology segment as 5G base stations and renewable energy inverters demand simultaneous EMI attenuation and surge immunity.
FCC Part 15 emissions rules in the United States, IEC 61000 immunity standards across European markets, and China GB/T 17626 test protocols collectively mandate certifiable surge withstand capability for equipment market access. Automotive OEMs now require ISO 7637-2 pulse 5b compliance as a baseline qualification, forcing tier-one suppliers to specify AEC-Q100 qualified suppression ICs in every module design. Stakeholders must monitor how regional divergence in electromagnetic compatibility enforcement reshapes qualification costs and factory allocation decisions.
Market Dynamics
Automotive electrification is compressing design cycles for board-level protection, forcing tier-one suppliers to requalify entire module portfolios under tightened ESD immunity protocols.
Growth Catalysts
- ISO 7637-2 Pulse 5b Mandates:Automotive OEMs now require load-dump protection compliance as baseline qualification, pulling AEC-Q100 certified suppressors into every powertrain module.
- China:Domestic EV production and 5G infrastructure buildouts consume the largest volume of TVS diodes and integrated suppressor devices globally.
- Silicon Carbide Integration:Wide-bandgap power electronics in EV inverters demand matched transient suppression with sub-picofarad capacitance budgets.
Market Restraints
- Wafer Supply Concentration:Advanced protection-grade silicon wafers concentrate among Japanese and Taiwanese foundries, exposing procurement to geographic disruption.
- Copper and Epoxy Resin Volatility:Lead frame materials and mold compounds face input cost swings that compress margin on standard-grade TVS devices.
- Discrete Component Substitution:Multi-chip module approaches in cost-sensitive consumer electronics displace monolithic suppression ICs with passive arrays.
Strategic Opportunities
- India:PLI scheme incentives for domestic semiconductor packaging create entry points for localized surge protection assembly serving telecom and automotive accounts.
- Active Filtering Convergence:5G base stations and solar inverters require simultaneous EMI attenuation and surge immunity, opening integrated multifunction architectures.
- Direct Manufacturer Engagement:High-volume automotive and telecom accounts are bypassing authorized distributors for contracted allocation with analog specialists.
Industry Challenges
- EMC Certification Timeline Compression:IEC 61000-4-5 retesting under revised immunity levels forces redesign cycles that collide with vehicle platform deadlines.
- Legacy Bus Integration:Industrial automation retrofits require suppressors that bridge kilovolt-class fieldbus architectures with modern low-voltage logic without signal degradation.
- Packaging Talent Scarcity:Flip-chip and wafer-level packaging expertise for high-speed protection devices concentrates among a narrow pool of analog-focused engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surge Suppression IC Market |
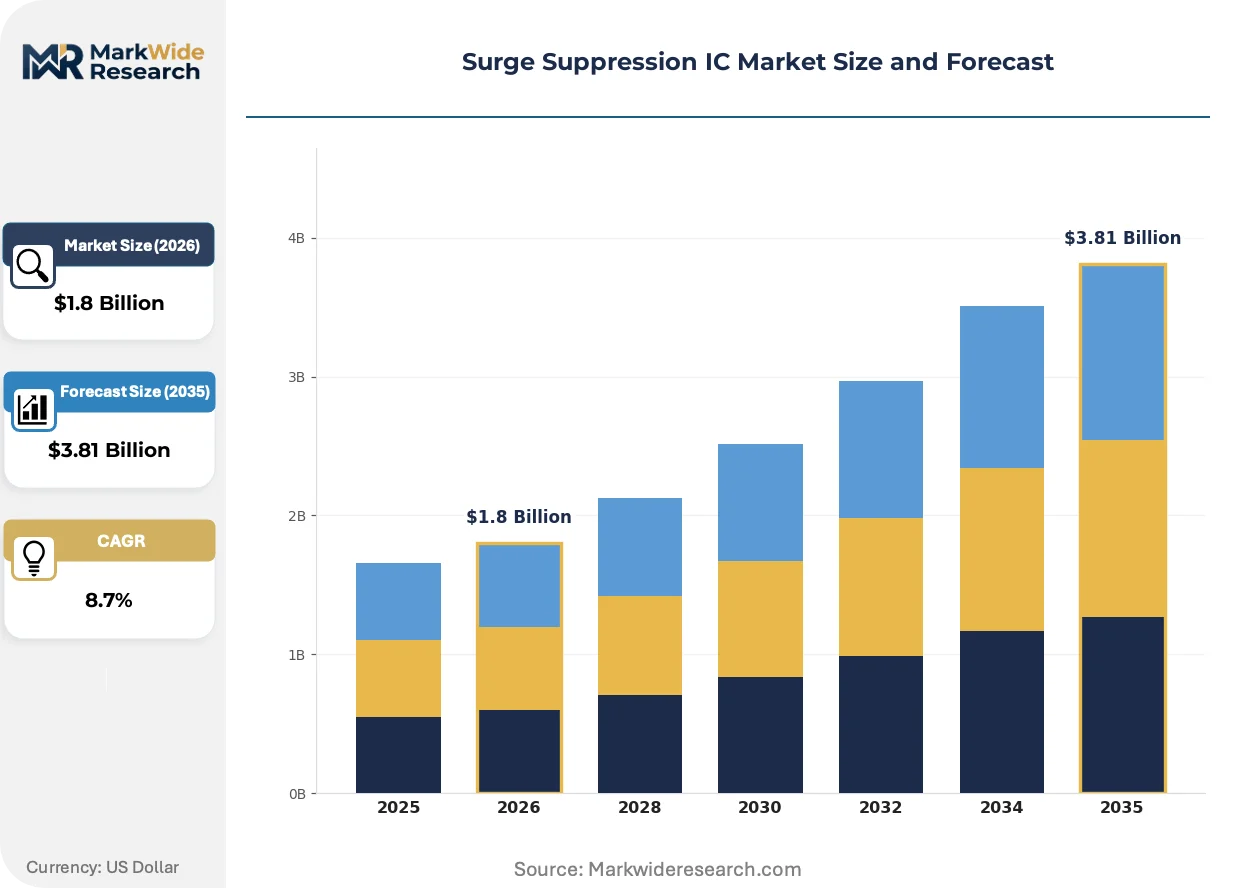
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TVS Diodes, MOVs, Gas Discharge Tubes, Suppressors Technology: Transient Voltage Suppression, Integrated Circuit Solutions, Inline Surge Protection, Active Filtering End User: Consumer Electronics, Industrial Equipment, Telecommunications, Automotive Application: Electrical Appliances, Data Communication, Power Systems, Renewable Energy |
| Companies Covered | Analog Devices, Texas Instruments, ON Semiconductor, STMicroelectronics, Infineon Technologies, NXP Semiconductors, Microchip Technology, Renesas Electronics, Littelfuse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surge Suppression IC Market Evolving Landscape
Protection semiconductor architectures are converging with power management and EMI mitigation, collapsing multiple discrete functions into single-die or multi-die solutions.
Automotive-qualified TVS arrays with integrated temperature sensing and fault reporting are digitizing protection from passive clamping to intelligent monitoring. Tier-one suppliers in Germany and Japan are adopting these devices for 800V EV architectures. This capability is digitizing how battery management systems isolate fault propagation across high-voltage domains.
China's GB/T 17626 test protocols now mandate higher surge withstand thresholds for grid-connected equipment than IEC baselines, forcing foreign suppliers to maintain dual qualification tracks. Industrial inverter and EV charger manufacturers targeting domestic Chinese sales must retest under these elevated levels. European suppliers are responding by pre-qualifying devices to both standards to preserve factory allocation flexibility.
Telecom equipment procurement is consolidating around direct long-term agreements with analog semiconductor manufacturers, displacing traditional distributor stocking models for high-reliability protection components. Base station OEMs in South Korea and Finland now contract quarterly volumes eighteen months forward. This pattern is most visible in 5G massive MIMO deployments where suppressor failure rates directly impact network availability SLAs.
Surge Suppression IC Market Segmentation
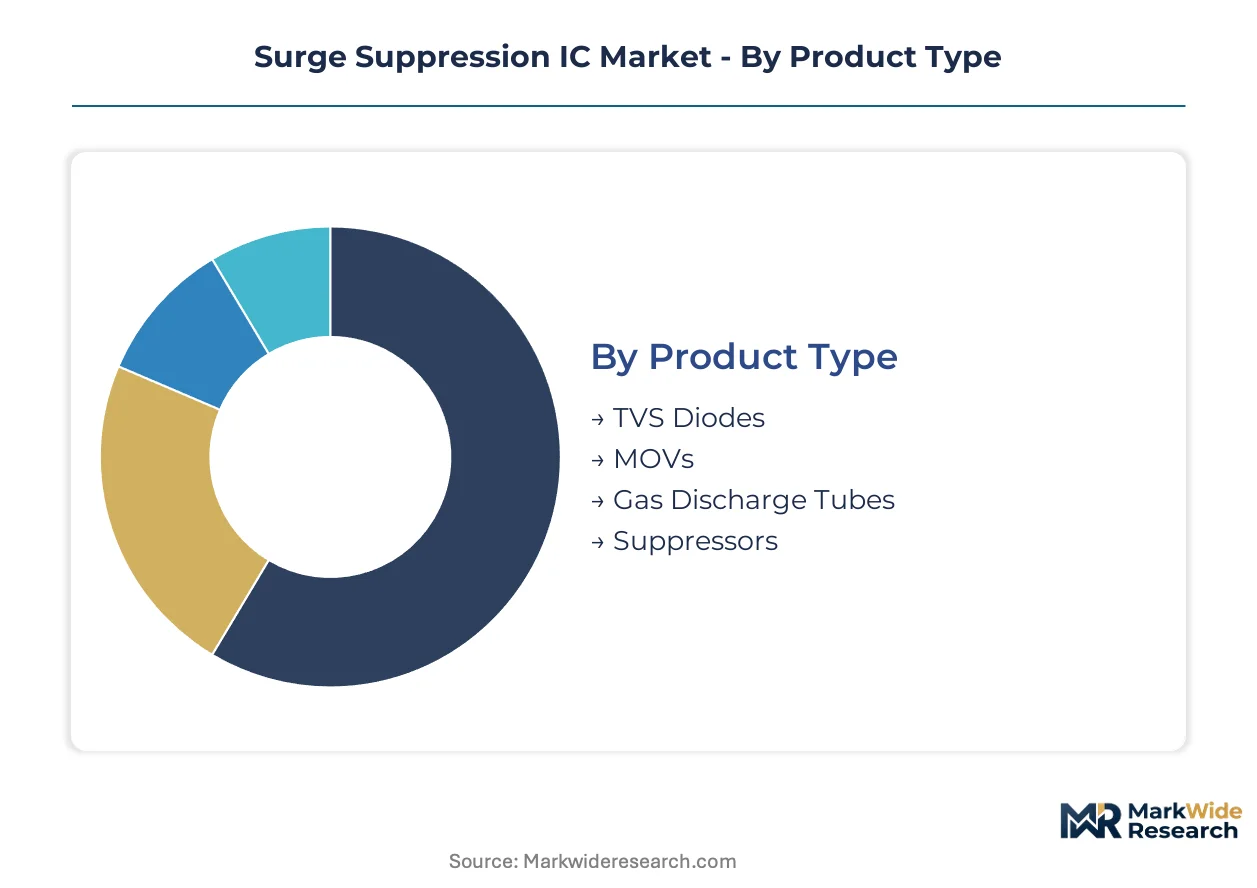
Surge suppression IC segmentation reveals how protection requirements diverge across voltage classes, response speeds, and functional safety tiers. Each dimension shapes procurement specifications, qualification protocols, and supplier selection criteria differently.
Product Type:
Use cases span from nanosecond-clamping data line protection to kilovolt-class industrial bus suppression, with material composition and package geometry determining fit.
- TVS Diodes:Silicon-based unidirectional or bidirectional clamps with sub-nanosecond response times and sub-picofarad capacitance options for high-speed signal integrity. Demand concentrates in automotive battery management systems and 5G base station RF chains where ISO 7637-2 and IEC 61000-4-5 compliance is mandatory. AEC-Q100 qualification requirements are compressing supplier qualification timelines.
- MOVs:Metal oxide varistors providing higher energy absorption for AC mains and industrial power entry points, with ceramic composition enabling multilayer surface-mount formats. China's grid infrastructure buildouts and EV charging station deployments consume the largest volumes, though thermal degradation under repeated surges limits lifetime-critical applications.
- Gas Discharge Tubes:Hermetically sealed spark gap devices handling surge currents exceeding tens of kiloamperes for telecommunications line protection and antenna feed systems.
- Suppressors:Hybrid or integrated multifunction devices combining clamping, filtering, and fault reporting in single-package solutions for space-constrained automotive modules.
Established volume favors TVS Diodes; emerging adoption favors Suppressors.
Technology:
Process maturity separates commodity protection from differentiated architectures where silicon carbide integration and active control loops command premium positioning.
- Transient Voltage Suppression:Established silicon TVS processes with well-characterized breakdown voltage distributions and temperature coefficients. Automotive powertrain modules in Germany and Japan specify these devices for 400V and 800V architectures where load-dump events demand predictable clamping behavior.
- Integrated Circuit Solutions:Monolithic or multi-die devices embedding protection with monitoring, self-test, or communication interfaces. Telecom equipment OEMs in South Korea are contracting direct allocation for these devices to meet 5G massive MIMO availability SLAs.
- Inline Surge Protection:Series-connected protection elements for applications where shunt clamping would disrupt signal or power continuity.
- Active Filtering:Converged EMI attenuation and surge immunity architectures using feedback control loops. These solutions are expanding most quickly in solar inverters and 5G base stations where simultaneous conducted emissions reduction and transient withstand are required.
Process scale favors Transient Voltage Suppression; functional integration favors Integrated Circuit Solutions.
End User:
Qualification intensity varies sharply across sectors, with automotive functional safety and telecom reliability standards filtering supplier participation.
- Consumer Electronics:Cost-sensitive applications including smartphones, laptops, and wearables where protection density per square millimeter dominates design decisions. Multi-chip module approaches often displace monolithic ICs in this tier.
- Industrial Equipment:Factory automation, motor drives, and process control systems requiring immunity to inductive load switching and lightning-induced transients. European industrial automation channels specify application-specific protection arrays with extended temperature ranges.
- Telecommunications:Base stations, data centers, and network infrastructure where failure rates directly impact service availability commitments. Direct manufacturer engagement is displacing distributor models for high-reliability procurement.
- Automotive:The most stringent qualification environment with ISO 7637-2 pulse 5b and AEC-Q100 requirements now baseline for every powertrain module. China's domestic EV production consumes the largest absolute volumes globally.
Procurement scale favors Automotive; margin structure favors Telecommunications.
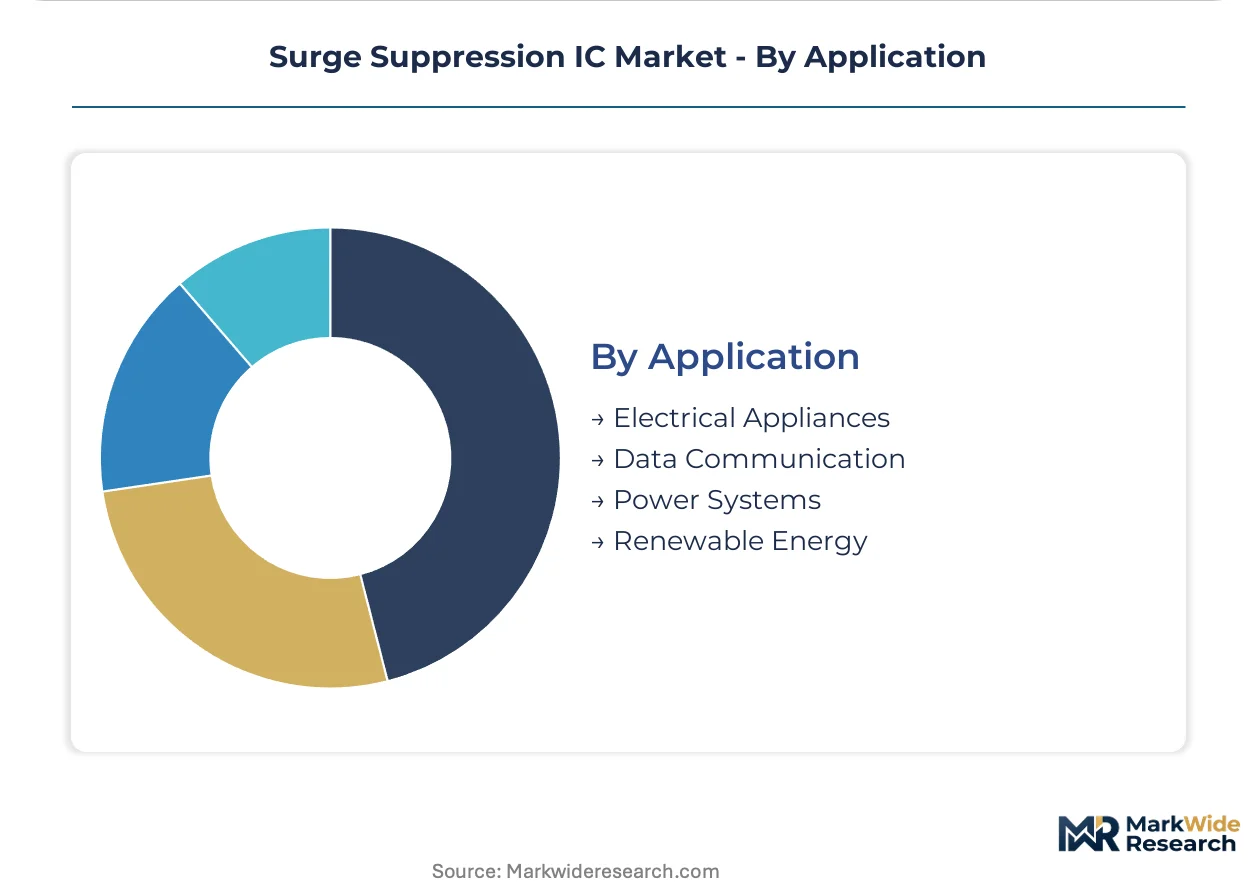
Application:
Voltage hierarchy and signal speed requirements create distinct protection architectures from mains-connected equipment to millimeter-wave data paths.
- Electrical Appliances:White goods and small appliances requiring IEC 61000-4-5 compliance for market access in Europe and GB/T 17626 certification in China. Standard-grade TVS devices dominate with price sensitivity limiting advanced feature adoption.
- Data Communication:High-speed interfaces including Ethernet, USB, and PCIe where capacitance budgets below one picofarad preserve signal integrity. Sub-picofarad TVS arrays from analog specialists attach to every port in enterprise equipment.
- Power Systems:AC-DC and DC-DC conversion stages where wide-bandgap semiconductors demand matched transient suppression with fast recovery characteristics.
- Renewable Energy:Solar inverters and wind turbine power electronics requiring simultaneous surge immunity and EMI attenuation. Active Filtering architectures are gaining share fastest in this segment as grid codes tighten emission and withstand requirements.
Unit volume favors Electrical Appliances; specification intensity favors Renewable Energy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government electrification mandates and infrastructure buildouts are redirecting procurement flows across major manufacturing economies. National regulators are tightening electromagnetic compatibility enforcement, forcing component suppliers to maintain multi-jurisdiction qualification tracks.
China
Domestic EV production and 5G infrastructure deployment absorb the largest absolute volumes of TVS diodes and integrated suppressor devices globally. MIIT enforces GB/T 17626 test protocols with surge withstand thresholds exceeding IEC baselines for grid-connected equipment. Shenzhen and Shanghai host the densest clusters of protection IC packaging facilities serving both automotive and telecom OEMs.
Germany
Automotive powertrain electrification and industrial automation retrofits drive specification intensity for AEC-Q100 qualified suppression arrays. KBA mandates ISO 7637-2 pulse 5b compliance as baseline for every powertrain module entering the market. Bavaria anchors European demand through BMW and Siemens supply networks requiring sub-picofarad capacitance budgets for 800V architectures.
United States
Data center expansion and renewable energy inverter deployments concentrate procurement for wide-bandgap matched protection devices. FCC Part 15 emissions rules mandate certifiable surge withstand capability for equipment market access. Texas and California house the primary analog semiconductor design centers serving domestic automotive and telecom accounts through direct manufacturer engagement.
Japan
Automotive functional safety requirements and telecom base station reliability standards filter supplier participation toward established analog specialists. METI oversees JIS standards alignment with IEC 61000 immunity protocols for industrial equipment exports. Nagoya and Tokyo industrial corridors specialize in flip-chip and wafer-level packaging for high-speed protection devices.
South Korea
5G massive MIMO deployments and EV battery management system production create contracted allocation demand eighteen months forward. MFDS harmonizes electromagnetic compatibility enforcement with international standards for medical-electronics convergence. Seoul Capital Area hosts Samsung and SK Hynix supplier networks specifying suppressor failure rates tied directly to network availability SLAs.
Surge Suppression IC Market Competitive Landscape
On the supply side, the industry is tiered between diversified analog conglomerates and specialized protection semiconductor architects. Tier-one suppliers command premium positioning through captive silicon carbide expertise and automotive qualification depth. Three archetypes dominate: broad-portfolio analog specialists bundling protection with power management, discrete component houses pivoting toward integrated multifunction architectures, and fabless designers outsourcing to protection-grade silicon foundries. Competitive intensity concentrates on M&A for silicon carbide capabilities and strategic partnerships for 5G base station direct allocation contracts.
Among diversified analog conglomerates, Texas Instruments, Infineon Technologies, and STMicroelectronics exemplify the bundling archetype where protection devices attach to broader power management solutions. These firms occupy positions sustained by automotive and telecom account relationships, with geographic footprints spanning German automotive corridors, American industrial centers, and European automation channels. Their competitive posture rests on qualification depth rather than discrete component cost positioning.
| Leading Market Players |
|---|
| Analog Devices |
| Texas Instruments |
| ON Semiconductor |
| STMicroelectronics |
| Infineon Technologies |
| NXP Semiconductors |
| Microchip Technology |
| Renesas Electronics |
| Littelfuse |
| Others |
Value Network & Pricing Analysis
The Yokohama-to-Long Beach maritime corridor carries silicon wafers and epoxy mold compounds whose freight cost volatility feeds directly into AEC-Q100 certified device premiums. Supply concentration in Japanese and Taiwanese foundries amplifies pricing power for automotive-grade suppressors while forcing European and American buyers into long-term allocation contracts.
Pricing Analysis
Certification level creates the primary spread between automotive AEC-Q100 qualified devices and standard-grade consumer electronics components. Automotive powertrain modules command premium-mid-economy pricing differentiation based on ISO 7637-2 pulse 5b compliance and sub-picofarad capacitance specifications. Cost compression in standard-grade TVS devices is intensifying because copper lead frame and epoxy resin input volatility squeezes margin pools. Consumer electronics OEMs exhibit highest price sensitivity, while telecom base station operators prioritize failure rate SLAs over unit cost.
Supply Chain Analysis
TSMC, United Microelectronics, and Japanese specialty foundries hold captive capacity for protection-grade silicon wafers. Manufacturing concentrates in Taiwan, Japan, and China, with advanced packaging expertise clustering in Nagoya and Shenzhen industrial corridors. Raw material dependencies include high-purity silicon substrates, copper alloy lead frames, and ceramic mold compounds. Single-source vulnerability in 200mm wafer supply exposes procurement to geographic disruption. Distribution runs through direct manufacturer engagement for high-volume automotive and telecom accounts, displacing traditional authorized distributor stocking models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat where AEC-Q100 and ISO 7637-2 qualification timelines create switching costs that lock tier-one automotive suppliers into established relationships.
For Market Incumbents: Build captive silicon carbide integration capabilities that extend protection architectures into wide-bandgap powertrain applications. Deepen backward integration into protection-grade wafer supply through strategic partnerships with Japanese foundries. Consolidate position by acquiring flip-chip packaging specialists in Nagoya and Seoul to address talent scarcity in high-speed device assembly. Fend off emerging fabless competitors by pre-qualifying devices to both IEC 61000-4-5 and China's elevated GB/T 17626 thresholds. For New Entrants and Emerging Players: Pursue white-space opportunities in India's PLI-scheme packaging corridors where localized surge protection assembly for telecom and automotive accounts lacks established analog specialists. Target renewable energy inverter manufacturers adopting Active Filtering architectures that combine EMI attenuation with surge immunity. Enter through design partnerships with solar inverter OEMs requiring simultaneous conducted emissions reduction and transient withstand capabilities rather than competing head-to-head in saturated automotive qualification channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates where protection semiconductor divisions represent non-core revenue pools with stranded automotive qualification expertise. Long-term viability hinges on regulatory entrenchment depth and silicon carbide technology integration rather than discrete component cost positioning. Monitor AEC-Q100 certification backlog durations as the inflection indicator for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Integration | Wide-bandgap expertise anchors positioning in 800V EV powertrain architectures. |
| Dual Standard Pre-Qualification | Simultaneous IEC and GB/T compliance preserves factory allocation flexibility for China-bound equipment. |
| Direct Manufacturer Engagement | Long-term contracts with Samsung and SK Hynix networks displace distributor stocking models. |
| Active Filtering Convergence | Integrated EMI and surge architectures capture solar inverter and 5G base station procurement. |
| Flip-Chip Packaging Scale-Up | Wafer-level assembly expertise concentrates in analog-focused engineering teams. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC semiconductor filings, MIIT equipment certification databases, and IEC standard revision records. Interviews with Tier 1 supplier procurement directors, analog semiconductor platform engineers, and automotive EMC test laboratory managers inform qualification timeline assumptions. Trade data from Japanese and Taiwanese customs authorities validates wafer shipment volumes. Bottom-up segment modeling triangulates against top-down semiconductor equipment spending forecasts.
Forecast inputs include vehicle electrification program announcements, 5G base station deployment schedules, and solar inverter installation targets across the analysis window. Segmentation models incorporate product type, technology architecture, end-use sector, and regional regulatory cluster. CAGRs derive from installed base growth rates and content-per-unit expansion in EV powertrain modules. Specific inputs capture ISO 7637-2 pulse 5b mandate adoption curves and GB/T 17626 threshold elevation timelines.
Sensitivities concentrate around wafer supply disruption, copper and epoxy resin commodity volatility, and automotive platform deadline compression. Forecasts reflect documented assumptions regarding electrification program execution and EMC enforcement harmonization. Quarterly review of AEC-Q100 certification queue lengths and foundry capacity utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Hitoxic Gas Detector Market
Detection and Regulation Devices
Electronic Article Surveillance Market
Detection and Regulation Devices
Filter Panels Market
Detection and Regulation Devices
Voltage Detection System Market
Detection and Regulation Devices
Duct Smoke Detectors Market
Detection and Regulation Devices
Ultraviolet Currency Detector Market
Detection and Regulation Devices
Carbon Monoxide (Co) Detector Market
Detection and Regulation Devices
Betavoltaic Device Market
Detection and Regulation Devices
Global a-Si X-Ray Flat Panel Detectors Market
Detection and Regulation Devices
US Pin and Sleeve Devices Market
Detection and Regulation Devices
Global Portable Gas Detector Market
Detection and Regulation Devices
Pyro Electric Infrared Detectors Market
Detection and Regulation Devices
Leak Detection Equipment Market
Detection and Regulation Devices
Photoionization Detectors Market
Detection and Regulation Devices
Latin America Trace Detection Market
Detection and Regulation Devices
South East Asia Gas Detection Device Market