
 Smartphone with Periscope Lens Market | 2026-2036
Smartphone with Periscope Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Smartphone with Periscope Lens Market Insights
Project finance tied to equipment leasing is fragmenting competitive entry barriers for periscope lens module production. Samsung Electronics leverages captive semiconductor foundry capacity to control image sensor supply. Xiaomi competes through aggressive geographic expansion across Southeast Asia and Latin America. OPPO differentiates via sustained R&D spending on folded-optics mechanical design.
A smartphone with periscope lens incorporates a prism-reflected optical path that redirects light through a rectangular lens stack oriented parallel to the device body, achieving 5x to 10x optical zoom within sub-10mm module thickness constraints. The primary commercial purpose is to deliver DSLR-comparable telephoto reach without protruding external lenses. Flagship tier products anchor current margin pools due to premium pricing tolerance and component cost absorption. Mid-range penetration is accelerating fastest as prism assembly yields improve and BOM costs decline. Content creator segment demand concentrates in online retail channels where specification comparison drives purchase decisions.
FCC equipment authorization in the United States and CE marking under EU MDR and RoHS directives shape electromagnetic compatibility and hazardous substance thresholds for imported optical modules. China's MIIT enforces GB standards for camera module interconnect protocols that influence regional design specifications. Japan's METI coordinates JIS standards for precision actuator mechanisms in prism stabilization systems. Stakeholders must monitor which regulatory jurisdiction first mandates repairability requirements for sealed optical assemblies, as this would force modular redesign across all price tiers.
Market Dynamics
Content creators now compress smartphone refresh cycles as their specification-driven purchasing supersedes carrier-subsidy timing, forcing OEMs to synchronize periscope lens module releases with influencer platform algorithm changes rather than traditional holiday retail calendars.
Growth Catalysts
- GB Standard Harmonization:China's MIIT certification convergence for optical interconnect protocols reduces regional SKU fragmentation, enabling module suppliers to consolidate production lines across domestic OEMs.
- Prism Assembly Yield Improvements:Automated active alignment systems for rectangular lens stacks cut defect rates in mid-range module manufacturing, expanding addressable volume beyond flagship tier absorption.
- Seoul Metropolitan Cluster Concentration:Samsung Electronics' captive semiconductor foundry and module assembly proximity compress sensor-to-lens integration timelines for Korean OEM supply.
Market Restraints
- Actuator Mechanism Input Cost Volatility:Voice coil motor precision components face rare earth magnet price swings tied to Chinese export quota administration.
- Single-Source Prism Supplier Risk:High-refractive-index glass prism manufacturing concentrates among Japanese optical specialists, creating geographic chokepoints for module assembly scaling.
- Folded-Optics Physical Limitation:Light-path length constraints in sub-10mm modules cap optical zoom range before digital cropping becomes necessary.
Strategic Opportunities
- Southeast Asia Online Retail Channel Expansion:E-commerce platforms in Vietnam and Indonesia bypass traditional carrier-dominated distribution, enabling specification comparison tools that highlight optical zoom capabilities.
- India PLI Scheme Incentive Capture:Production-linked incentives for electronics manufacturing attract module assembly investment to serve domestic OEMs and export markets.
- Computational Photography Convergence:AI-driven image stacking algorithms paired with periscope hardware extend effective zoom range without optical redesign, creating software-hardware bundled value.
Industry Challenges
- Active Alignment Technician Scarcity:Prism-to-sensor micron-precision calibration requires specialized optomechanical skills concentrated among East Asian equipment vendors.
- CE Marking Timeline Compression:EU MDR electromagnetic compatibility testing for sealed optical assemblies extends certification cycles as module complexity increases.
- Cross-Licensing Portfolio Complexity:Folded-optics mechanical design patents span Korean, Chinese, and Japanese assignees, complicating freedom-to-operate clearance for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smartphone with Periscope Lens Market |
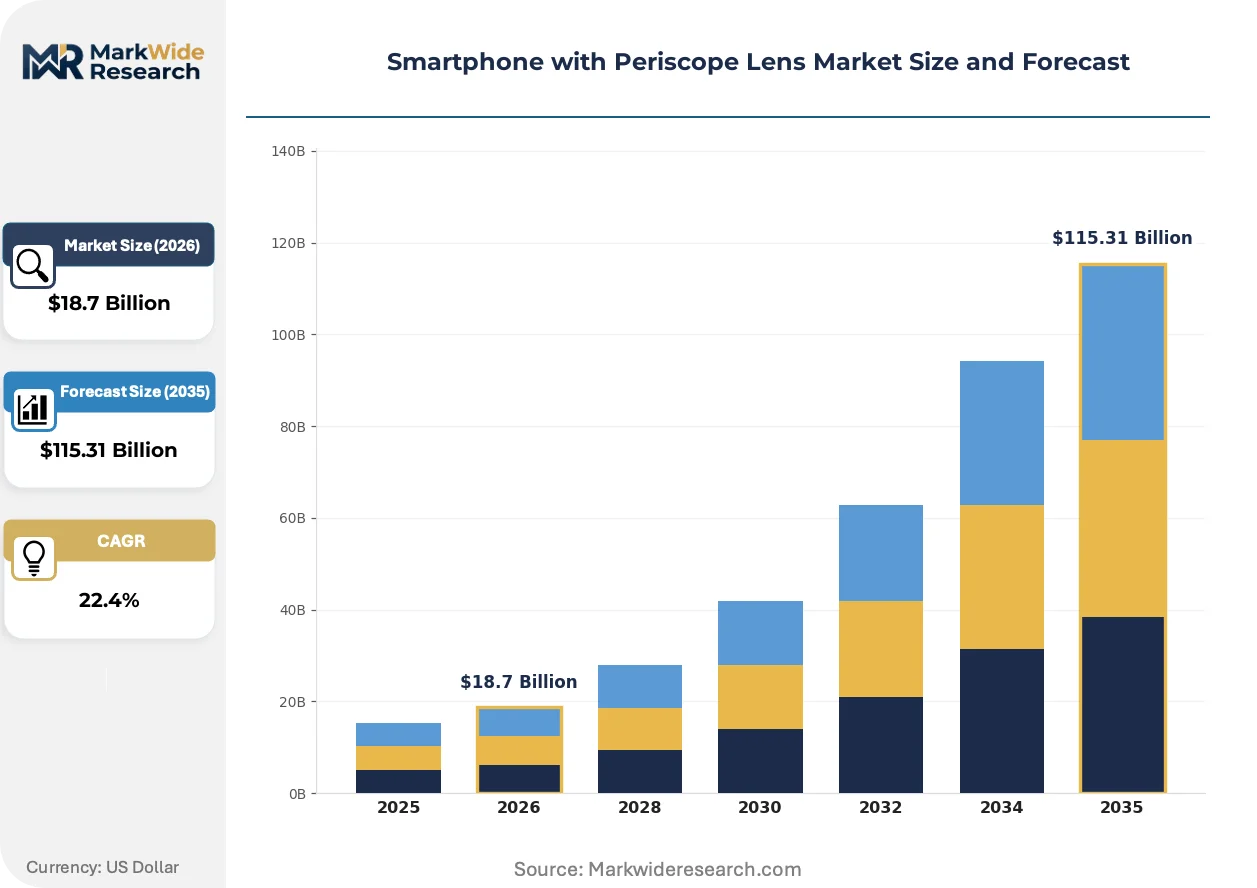
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flagship, Mid-range, Budget, Premium Camera Specifications: Zoom Capability, Aperture Size, Sensor Type, Stabilization System End User: Photography Enthusiasts, Professionals, Casual Users, Content Creators Distribution Channel: Online Retail, Offline Retail, Direct Sales, Telecom Providers |
| Companies Covered | Samsung Electronics, Huawei, OPPO, Vivo, Xiaomi, Apple, HONOR, Sony, Google, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smartphone with Periscope Lens Market Trends and Innovations
Computational image processing is virtualizing traditional optical functions, compressing the boundary between hardware lens capability and software-derived resolution. This convergence reshapes how OEMs allocate BOM budget across sensor, lens, and silicon components.
Continuous optical zoom mechanisms are virtualizing fixed-focal-length periscope architectures by enabling smooth magnification transitions without discrete lens switching. Flagship-tier OEMs in South Korea and China adopt liquid lens and deformable mirror prototypes for 2025-2026 product cycles. This technology is virtualizing the discrete 3x/5x/10x hardware tiers that previously segmented product lines, collapsing premium differentiation into unified optical ranges.
China's MIIT enforcement of updated GB standards for camera module interconnect protocols is mandating unified electrical interfaces across domestic OEM supply chains. Module suppliers must redesign flex cable and connector configurations to meet certification thresholds before commercial distribution. Mid-range smartphone assemblers face the steepest compliance adaptation costs as their legacy module inventories rotate.
Content creator procurement through direct-to-consumer online channels is fragmenting traditional carrier-retail distribution dominance for periscope-equipped devices. Specification comparison platforms and influencer unboxing content now drive purchase timing independent of subsidy contract renewal cycles. This behavioral shift concentrates in South Korea's Seoul metropolitan cluster and China's tier-one cities where creator economy density highest.
Smartphone with Periscope Lens Market Segmentation
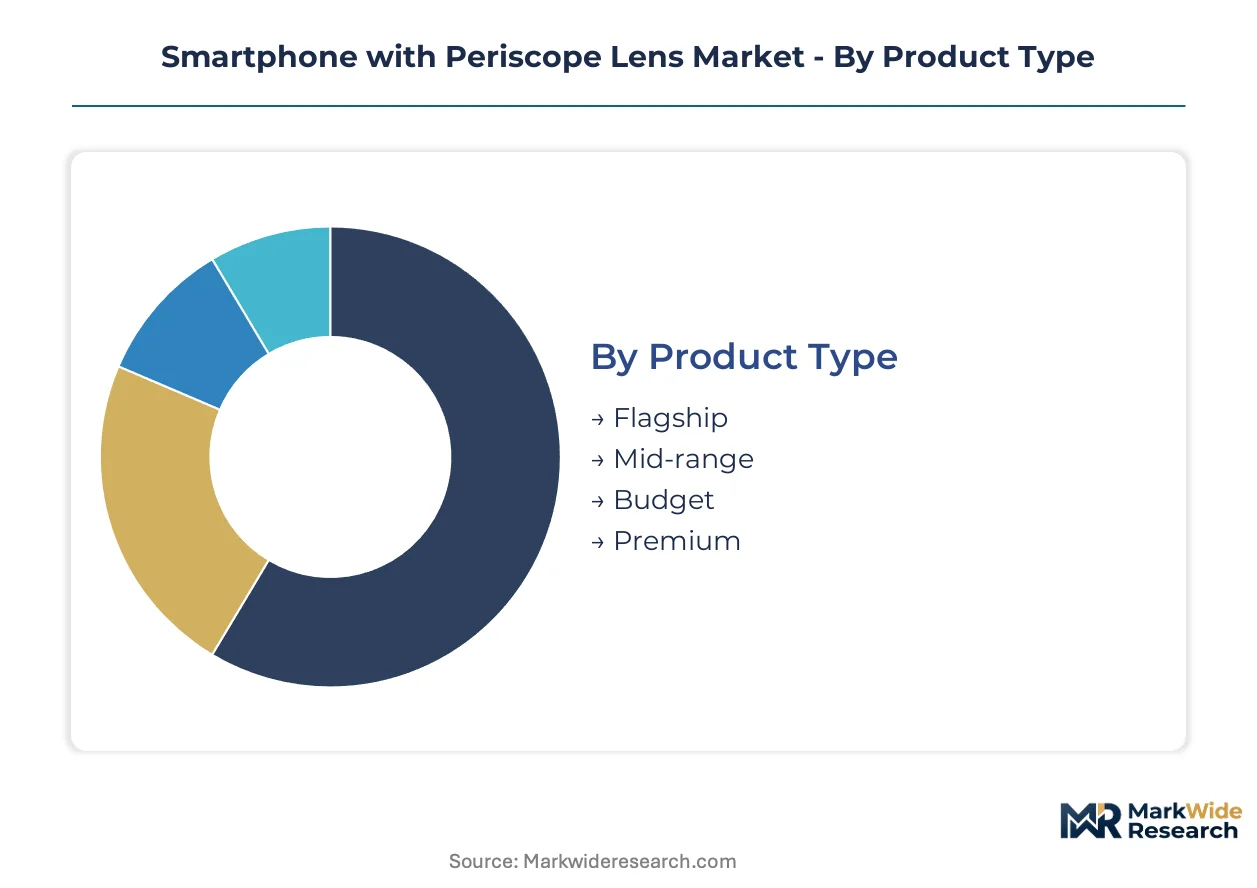
Periscope lens module configurations fragment across price-performance tiers, each demanding distinct after-sales service infrastructure. Flagship segments require specialized optical calibration support, while mid-range volumes stress standard warranty logistics. Understanding these service intensity gradients shapes supplier resource allocation and regional stocking strategies.
Product Type:
After-sales service intensity escalates with module complexity, creating divergent support infrastructure requirements across price tiers.
- Flagship:Modules incorporate multi-prism folded-optics with voice coil motor actuators demanding micron-precision recalibration. Samsung Electronics' Seoul metropolitan cluster anchors dedicated service center density for these assemblies. Service turnaround times compress to under 48 hours in South Korea and China's tier-one cities where creator economy users concentrate.
- Mid-range:Simplified dual-prism architectures reduce actuator count while maintaining 5x optical zoom. Demand concentrates in India's metropolitan clusters and Southeast Asian e-commerce corridors where specification comparison tools drive purchase decisions. Automated active alignment yield improvements are collapsing BOM differentials against flagship tiers.
- Budget:Fixed-focus periscope derivatives sacrifice zoom range for cost containment. Chinese domestic OEMs absorb volume through MIIT-certified module interconnect standardization.
- Premium:Ultra-thin module variants below 8mm thickness trade optical path length for industrial design. Japanese optical specialists supply high-refractive-index glass prisms for this tier.
By volume, Mid-range leads. By growth pace, Premium is ahead.
Camera Specifications:
Component specification tiers align with computational photography convergence trajectories reshaping hardware-software value allocation.
- Zoom Capability:Continuous optical zoom mechanisms are displacing discrete 3x/5x/10x hardware tiers through liquid lens prototypes. Flagship OEMs in South Korea and China pilot smooth magnification transitions for upcoming product cycles.
- Aperture Size:Larger f/2.4-f/2.8 apertures concentrate in professional-oriented devices where low-light telephoto performance commands premium positioning. Module thickness constraints limit aperture expansion in sub-10mm form factors.
- Sensor Type:Sony Semiconductor and Samsung Electronics captive foundry capacity dominate high-resolution stacked CMOS supply for periscope-optimized pixel architectures.
- Stabilization System:Sensor-shift and prism-shift hybrids require specialized active alignment technician skills concentrated among East Asian equipment vendors.
Zoom Capability commands R&D investment concentration. Stabilization System faces the steepest technician scarcity constraints.
End User:
User segment purchasing patterns are decoupling from carrier-subsidy calendars, compressing OEM release timing synchronization.
- Photography Enthusiasts:Specification-driven procurement through direct-to-consumer channels bypasses traditional retail. Seoul metropolitan cluster and China's tier-one cities exhibit highest creator economy density.
- Professionals:Broadcast journalists and commercial photographers demand FCC-certified electromagnetic compatibility and CE marking compliance for international assignment reliability.
- Casual Users:Carrier-dominated distribution persists for this segment where subsidy contract renewal cycles still govern refresh timing. Offline retail in India's tier-two cities absorbs volume.
- Content Creators:Algorithm-platform synchronization now dictates hardware refresh cycles ahead of holiday retail calendars. Influencer unboxing content drives specification comparison in Vietnam and Indonesia e-commerce channels.
Content Creators are gaining share fastest. Casual Users retain absolute volume leadership.
Distribution Channel:
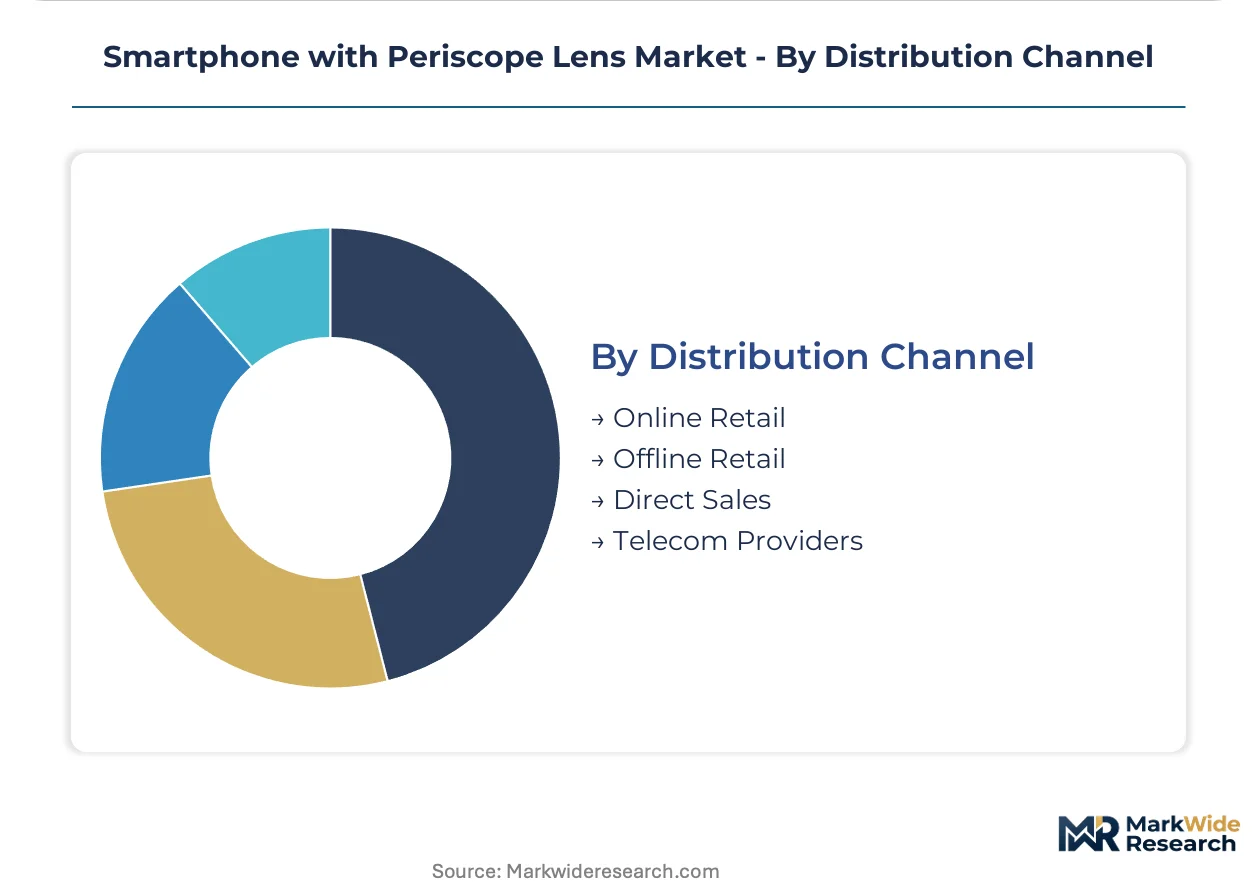
Channel configuration determines specification transparency and comparison tool availability, reshaping purchase decision dynamics.
- Online Retail:E-commerce platforms in Southeast Asia and Latin America enable direct specification comparison bypassing carrier sales associate intermediation. Xiaomi leverages this channel for geographic expansion.
- Offline Retail:Physical demonstration requirements persist for first-time periscope adopters evaluating zoom performance. India's multi-brand outlets concentrate mid-range volume.
- Direct Sales:OEM-owned flagship stores in Seoul and Shanghai anchor premium tier experience positioning. Samsung Electronics compresses sensor-to-lens integration timelines through captive supply proximity.
- Telecom Providers:Subsidy bundling retains dominance in Japan and South Korea where carrier infrastructure investment justifies contract lock-in. CE marking timeline compression for EU-bound devices complicates inventory planning.
Online Retail climbs the fastest. Telecom Providers maintain installed base concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT certification convergence for optical interconnect protocols is reshaping module supplier production consolidation across domestic OEM supply chains. South Korea's PLI-style incentives for camera module assembly attract component investment to the Seoul metropolitan cluster. India's electronics manufacturing incentives are drawing module assembly capacity to serve both domestic demand and export markets.
China
Domestic OEM procurement through MIIT-certified module suppliers compresses certification timelines for periscope lens integration. GB standards for camera module interconnect protocols mandate unified electrical interfaces that force flex cable redesigns. Shenzhen and Dongguan manufacturing clusters absorb mid-range module volume as prism assembly yields improve.
South Korea
Samsung Electronics' captive semiconductor foundry and module assembly proximity in the Seoul metropolitan cluster compress sensor-to-lens integration timelines. The national telecommunications regulator coordinates electromagnetic compatibility thresholds for 5G-enabled camera systems. Busan-Ulsan industrial corridor supports precision actuator component supply for voice coil motor manufacturing.
United States
FCC equipment authorization requirements for electromagnetic compatibility shape import thresholds for optical modules bound for flagship OEM distribution. Content creator demand through direct-to-consumer online channels bypasses traditional carrier-retail dominance. California's creator economy density concentrates specification-driven procurement independent of subsidy contract renewal cycles.
Japan
METI-coordinated JIS standards for precision actuator mechanisms in prism stabilization systems influence regional design specifications. High-refractive-index glass prism manufacturing concentrates among domestic optical specialists. Kyushu industrial zone anchors specialized active alignment equipment production for East Asian module assembly lines.
India
Production-linked incentive schemes for electronics manufacturing attract module assembly investment to serve domestic OEMs and Southeast Asian export markets. BIS certification requirements for camera module safety standards extend product launch timelines for international brands. Maharashtra and Karnataka manufacturing corridors absorb mid-range smartphone assembly volume as prism costs decline.
Smartphone with Periscope Lens Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: vertically integrated semiconductor-lens assemblers, modular component specialists, and algorithm-software bundlers. Competitive moves concentrate on captive foundry capacity expansion and cross-licensing portfolio accumulation for folded-optics mechanical design freedom-to-operate.
Within the integrated assembler tier, Samsung Electronics exemplifies captive supply chain control through in-house semiconductor foundry and module assembly proximity. OPPO and Xiaomi occupy positions emphasizing sustained mechanical design R&D and aggressive geographic expansion respectively. These three anchors represent divergent strategic vectors: supply chain verticality, optical innovation specialization, and scale-driven market penetration across emerging e-commerce corridors.
| Leading Market Players |
|---|
| Samsung Electronics |
| Huawei |
| OPPO |
| Vivo |
| Xiaomi |
| Apple |
| HONOR |
| Sony |
| Others |
Pricing and Supply Chain Analysis
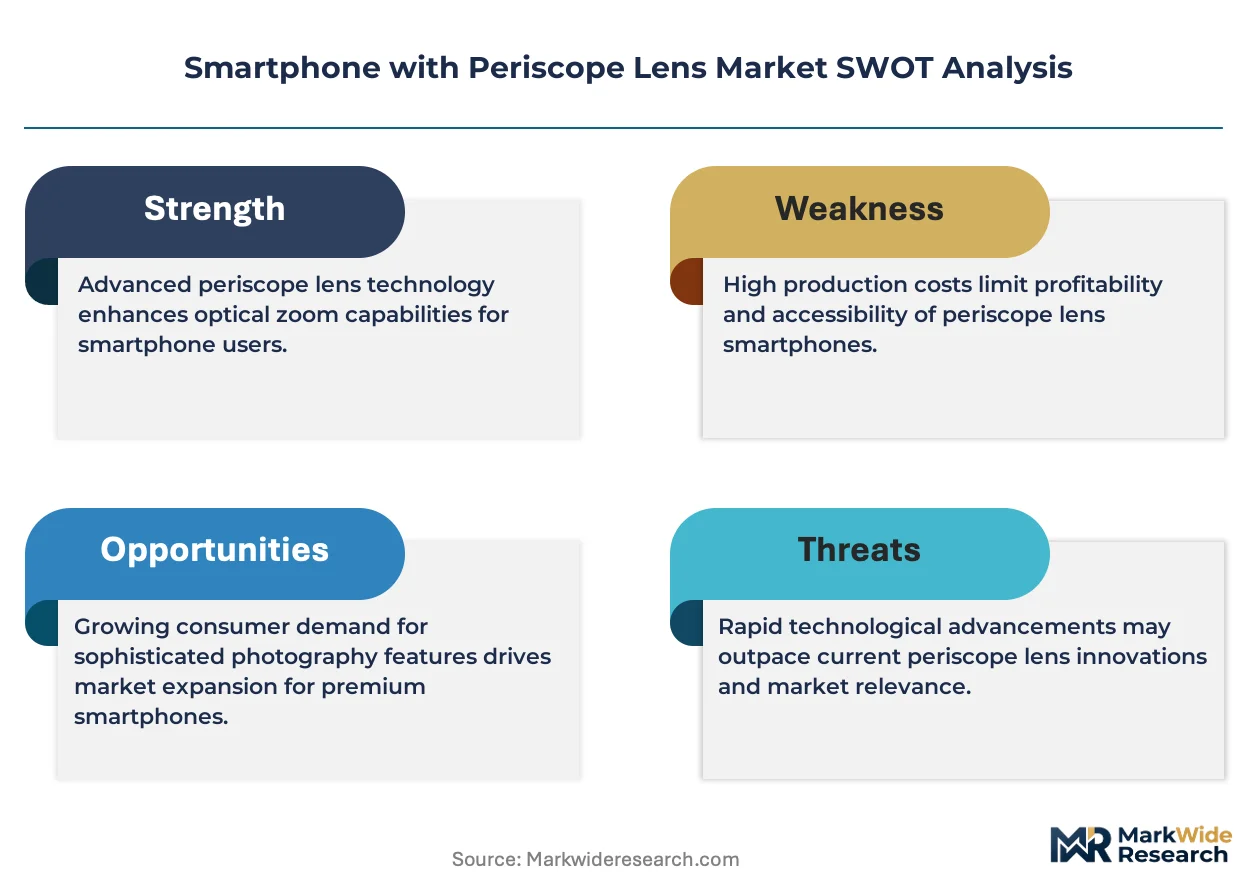
Single-source prism supplier risk for high-refractive-index glass manufacturing concentrates among Japanese optical specialists, compressing both pricing power for module assemblers and supply chain resilience across all tiers. This chokepoint forces OEMs to absorb input cost volatility into flagship margins while pushing mid-range producers toward simplified optical architectures.
Pricing Analysis
Certification level under China's MIIT GB standards and EU CE marking creates the primary spread between flagship and mid-range module tiers. Three-tier pricing structure across premium, standard, and economy levels reflects voice coil motor precision grades and active alignment calibration intensity. Cost compression in mid-range tiers intensifies because automated yield improvements collapse BOM differentials against legacy flagship positioning. Casual users in India's tier-two cities exhibit highest price sensitivity, while content creators in Seoul and Shanghai tolerate premium positioning for specification leadership.
Supply Chain Analysis
Extended payment terms from Korean and Chinese OEMs to module suppliers compress working capital cycles throughout the assembly tier. Manufacturing concentrates in South Korea's Seoul metropolitan cluster, China's Shenzhen-Dongguan corridor, and Japan's Kyushu industrial zone. Rare earth magnet voice coil components and high-refractive-index glass prisms constitute critical input dependencies. Single-source vulnerability for prism supply exposes assemblers to geographic concentration risk. Distribution runs through direct-to-consumer online channels in Southeast Asia and carrier-dominated retail in Japan and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prism assembly yield improvements are driving a cyclical recovery in mid-range module economics, compressing refresh cycles and expanding addressable volume beyond flagship absorption.
For Market Incumbents: Pre-empt computational photography convergence by deepening software-hardware bundled value before AI-driven image stacking virtualizes optical differentiation. Secure captive high-refractive-index glass prism supply through long-term offtake agreements with Japanese optical specialists. Expand active alignment technician training pipelines to alleviate East Asian equipment vendor concentration.
For New Entrants and Emerging Players: Pursue India's PLI scheme incentive capture for module assembly investment serving domestic OEMs and Southeast Asian export corridors. Target Vietnam and Indonesia e-commerce platforms where specification comparison tools bypass carrier intermediation. Lead with computational photography integration partnerships rather than optical hardware scale.
For Investors and Strategic Acquirers: EU repairability mandate discussions for sealed optical assemblies reshape the acquisition landscape toward modular design capabilities. Position for five-to-ten year viability around component suppliers with GB standard pre-certification and folded-optics patent clearance. Monitor China's MIIT enforcement timeline for interconnect protocol harmonization as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Prism Assembly Yield Automation | Automated active alignment systems cut defect rates in mid-range manufacturing, expanding volume. |
| Computational Photography Integration | AI-driven image stacking algorithms extend effective zoom range without optical redesign investment. |
| GB Standard Pre-Certification | MIIT-certified module interconnect protocols compress commercialization timelines for domestic OEM supply. |
| Continuous Optical Zoom Prototyping | Liquid lens and deformable mirror prototypes virtualize discrete hardware tiers for flagship positioning. |
| Southeast Asia E-Channel Expansion | Online retail platforms in Vietnam and Indonesia enable specification-driven procurement bypassing carriers. |
Research Methodology
A standing panel of camera module procurement executives, optical design engineers, active alignment equipment vendors, and MIIT certification consultants provided ongoing calibration across primary fieldwork. Secondary validation drew from MIIT certification filings, Korean semiconductor foundry capex disclosures, EU CE marking registries, and customs trade data for optical component flows. Bottom-up module shipment estimates triangulated against top-down OEM smartphone production forecasts.
Scenario-bracketing around prism assembly yield trajectories and computational photography adoption curves anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product tier, zoom capability specification, end-user archetype, and regional regulatory cluster. CAGRs derived from unit volume projections against average selling price evolution through the forecast period. Industry-specific inputs incorporated voice coil motor precision component pricing and rare earth magnet quota administration patterns.
Sensitivities concentrate around Chinese export quota volatility for rare earth magnets, EU repairability mandate timing, and computational photography substitution rates. Forecasts reflect documented assumptions on yield improvement trajectories and OEM platform standardization decisions. Macroeconomic contraction in creator economy advertising spend, regulatory deviation on optical assembly sealing requirements, or breakthrough liquid lens commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Latin America IP Camera Market
Imaging
Silent Scan Technology Market
Imaging
Near-Infrared Fluorescence Imaging System Market
Imaging
Global Camera Module Market
Imaging
Handheld Imaging Systems Market
Imaging
Stacked CMOS Image Sensor Market
Imaging
Latin America Surveillance Analog Camera Market
Imaging
Vision Processing Unit Market
Imaging
Pocket Video Camera Market
Imaging
North America Multi Camera Vision Inspection Systems Market
Imaging
TDI Camera Market
Imaging
Thermal Imaging Camera Market
Imaging
Contact Image Sensor Market
Imaging
Visualiser Market
Imaging
Photoacoustic Tomography Market
Imaging
Image Signal Processor and Vision Processor Market