
 Gel Imaging Documentation Market | 2026-2036
Gel Imaging Documentation Market Size, Share, and Industry Trends Forecast 2026-2036
Gel Imaging Documentation Market Foresight
Academic research funding consolidation across major universities is pivoting procurement toward multi-user, shared-platform contracts rather than individual lab purchases. Thermo Fisher Scientific leverages its installed base of thermal cyclers and sequencing systems to bundle gel imaging into broader workflow agreements. Bio-Rad Laboratories anchors its position through proprietary Image Lab software ecosystems that lock in repeat consumables revenue. Azure Biosystems differentiates via chemiluminescence detection sensitivity that rivals film-based methods for western blot quantification.
Gel imaging documentation systems integrate cooled CCD or CMOS sensors with narrow-band LED or laser excitation sources to capture fluorescence, chemiluminescence, or colorimetric signals from electrophoretically separated nucleic acids and proteins. These instruments typically achieve 16-bit dynamic range with pixel resolutions from 4 to 16 megapixels, enabling quantitative band analysis for molecular weight determination and relative expression profiling. Digital gel imaging systems command the largest revenue share due to replacement demand for aging film darkrooms, while imaging software represents the fastest-expanding margin pool as vendors shift toward subscription-based analysis platforms. Pharmaceutical research applications absorb disproportionate capital spending as GMP-compliant documentation becomes mandatory for biologics characterization submissions.
FDA 21 CFR Part 11 compliance requirements shape software architecture decisions for US-market systems, forcing audit trails and electronic signature workflows into core product design. The EU MDR and REACH chemical substance restrictions constrain illuminator component sourcing and fluorescent dye compatibility matrices for European deployments. Japan's PMDA medical device software classification adds a third regulatory layer for vendors seeking Asian market access. Stakeholders must monitor evolving data integrity enforcement patterns across FDA warning letters and EMA inspection findings to anticipate compliance-driven upgrade cycles.
Market Dynamics
Academic funding consolidation and biologics manufacturing compliance mandates are compressing procurement cycles while elevating software audit requirements above hardware specifications in vendor selection criteria.
Growth Catalysts
- Biologics GMP documentation:FDA 21 CFR Part 11 mandates electronic record-keeping for biologics characterization submissions, forcing pharmaceutical labs to replace film-based workflows with validated digital imaging platforms.
- CRISPR workflow standardization:Gene editing labs in Boston and San Diego corridors require high-throughput gel documentation for guide RNA validation, driving coordinated multi-system procurement.
- EU MDR diagnostic reclassification:The Medical Device Regulation elevates gel imaging systems to Class IIa status, compelling European clinical research organizations to upgrade to compliant platforms.
Market Restraints
- CCD sensor supply concentration:Cooled imaging sensor fabrication concentrates among Japanese and South Korean semiconductor foundries, exposing vendors to single-source disruption risk.
- Fluorophore REACH compliance costs:ECHA substance restrictions on ethidium bromide and SYBR dyes force reformulation of illumination compatibility matrices, raising R&D overhead.
- Darkroom infrastructure sunk costs:Legacy film development facilities in established academic institutions create institutional inertia against digital migration despite operational inefficiency.
Strategic Opportunities
- Cloud-native analysis platforms:Subscription-based image analysis software unbundles from hardware sales, creating recurring revenue streams independent of capital equipment cycles.
- Cell and gene therapy QC integration:Automated gel imaging for CAR-T vector confirmation represents an emerging application with limited incumbent vendor presence.
- India PLI scheme leverage:Production-linked incentives for medical device manufacturing enable cost-competitive assembly for domestic and export markets.
Industry Challenges
- 21 CFR Part 11 validation expertise:Pharmaceutical customers require vendor-supported IQ/OQ/PQ documentation packages, straining field service engineering capacity.
- Multi-instrument workflow integration:Gel imaging systems must interface with liquid handlers and LIMS platforms, demanding API standardization that vendors have not harmonized.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gel Imaging Documentation Market |
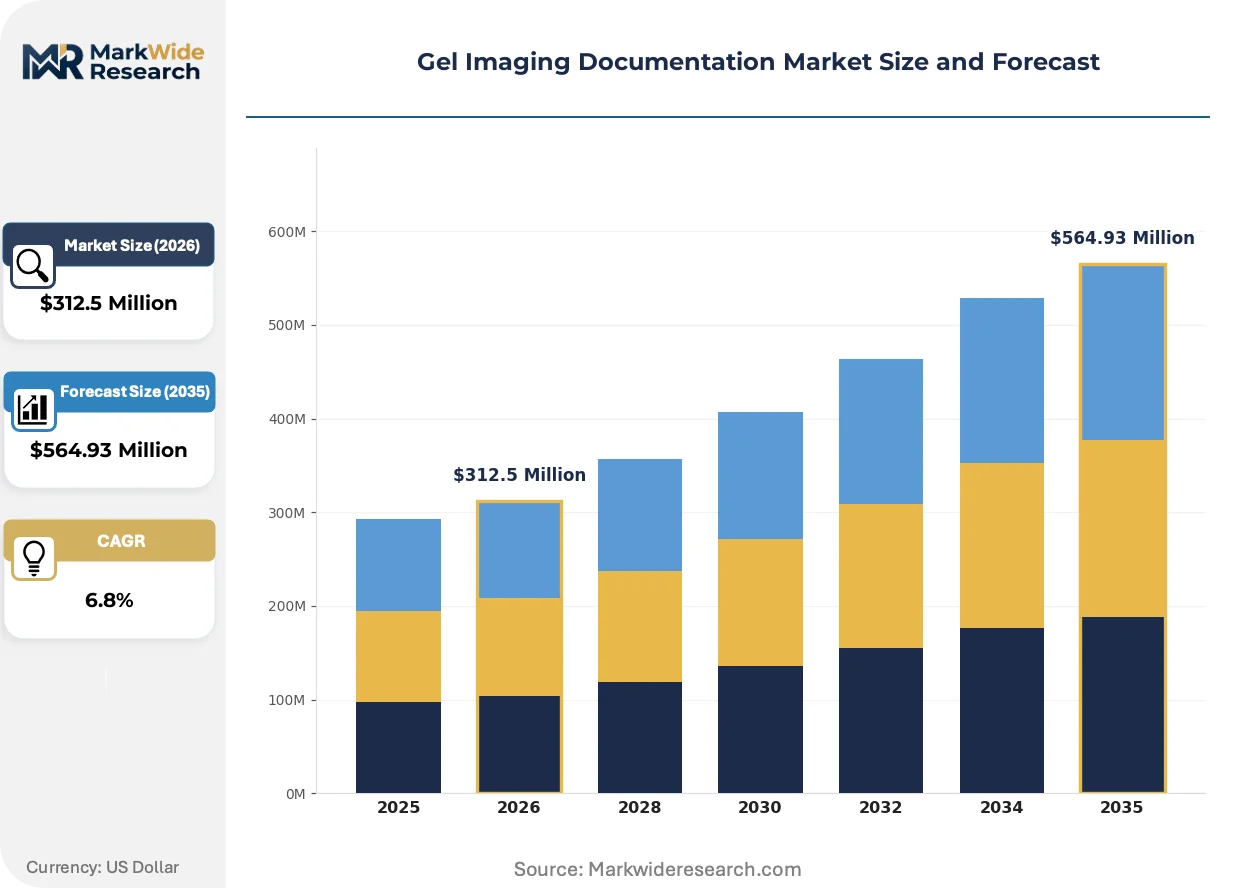
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Gel Imaging Systems, UV Transilluminators, Imaging Software, Gel Documentation Systems Application: Molecular Biology, Pharmaceutical Research, Diagnostic Laboratories, Forensic Science End User: Academic Institutions, Biotechnology Companies, Clinical Laboratories, Research Organizations Technology: CCD Imaging, LED Illumination, Gel Electrophoresis, High-Resolution Imaging |
| Companies Covered | Agilent Technologies, Analytik Jena, Thermo Fisher Scientific, PerkinElmer, Azure Biosystems, Bio-Rad Laboratories, Syngene International, Cleaver Scientific, GE HealthCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gel Imaging Documentation Market Shifts & Advancements
CMOS sensor architectures and AI-assisted band quantification are compressing the performance gap between entry-level and premium systems while regulatory data integrity enforcement hardens software requirements.
Deep-cooled sCMOS sensors with 95% quantum efficiency at 600nm are unifying sensitivity benchmarks previously segmented between CCD-based premium systems and CMOS economy units. Pharmaceutical QC labs adopt these sensors for low-abundance protein detection without film-based confirmation. The technology is unifying the product tier structure, compressing price differentiation that previously sustained three distinct hardware categories.
EMA inspection findings on data integrity deficiencies are tightening audit trail requirements for electronic signature workflows in European-deployed systems. The EU MDR's post-market surveillance obligations now extend to software updates, treating algorithm changes as device modifications. Small molecule CROs in Germany and Switzerland are responding by pre-validating analysis templates to minimize post-installation configuration drift.
Shared-platform service contracts are displacing individual lab capital purchases in consolidated academic medical centers. University procurement offices negotiate enterprise licenses covering imaging hardware, software seats, and consumables across multiple departments. This pattern concentrates most visibly in NIH-funded institutions where indirect cost recovery rules favor operational expenditure over capital depreciation.
Gel Imaging Documentation Market Segmentation
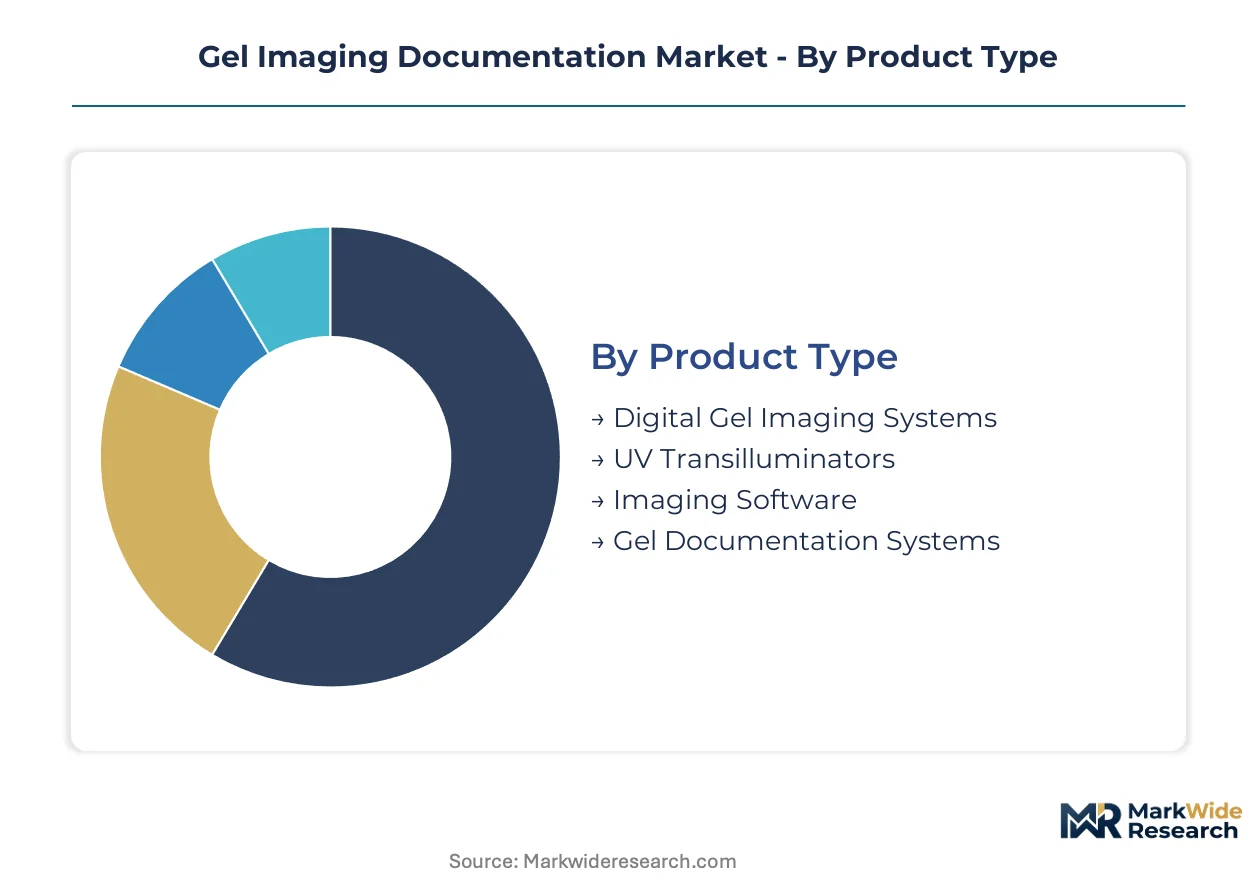
Segmentation in gel imaging documentation reveals how procurement authority concentrates among multi-site academic consortia and how software unbundling is rewriting vendor economics. Understanding these divisions exposes where capital expenditure flows and where recurring revenue pools form.
Product Type:
Supply concentration in cooled sensor fabrication and LED illuminator modules shapes competitive positioning across hardware tiers, with software margins increasingly detached from instrument sales.
- Digital Gel Imaging Systems:Cooled CCD or sCMOS sensors with 16-bit dynamic range capture fluorescence and chemiluminescence signals for quantitative band analysis. Pharmaceutical QC labs in the United States absorb disproportionate capital spending as FDA 21 CFR Part 11 compliance mandates replace film darkrooms with validated digital workflows.
- Imaging Software:Subscription-based analysis platforms with AI-assisted band quantification and electronic signature workflows generate recurring revenue independent of hardware replacement cycles. Academic medical centers in Boston and San Diego corridors favor enterprise licenses covering multi-department deployments.
- UV Transilluminators:Narrow-band LED excitation sources for ethidium bromide and SYBR Green visualization face REACH compliance constraints on dye compatibility.
- Gel Documentation Systems:Integrated hardware-software packages with automated exposure optimization serve high-throughput CRISPR validation workflows.
Today's leader: Digital Gel Imaging Systems. Tomorrow's challenger: Imaging Software.
Application:
Cost tier stratification separates GMP-validated pharmaceutical deployments from research-grade academic installations, with diagnostic laboratories occupying a compliance-intensive middle ground.
- Pharmaceutical Research:Biologics characterization submissions require audit-trailed documentation with IQ/OQ/PQ validation packages. FDA enforcement patterns on data integrity deficiencies drive replacement demand for aging film-based systems.
- Molecular Biology:Gene editing and next-generation sequencing workflows demand high-throughput gel documentation for nucleic acid verification. CRISPR labs concentrate procurement in coordinated multi-system purchases.
- Diagnostic Laboratories:EU MDR Class IIa reclassification elevates compliance thresholds for clinical research organizations in Germany and Switzerland.
- Forensic Science:DNA profiling protocols require chain-of-custody documentation with tamper-evident electronic records.
Pharmaceutical Research commands premium pricing. Molecular Biology expands most quickly.
End User:
Customer type determines contract structure, with consolidated academic procurement offices negotiating shared-platform agreements while biotechnology companies prioritize workflow integration.
- Academic Institutions:NIH-funded universities leverage indirect cost recovery rules to favor operational expenditure over capital depreciation. Multi-user shared-platform contracts displace individual lab purchases.
- Biotechnology Companies:CRISPR and cell therapy developers in Boston and San Diego corridors require automated imaging for CAR-T vector confirmation with LIMS integration.
- Clinical Laboratories:EU MDR compliance mandates upgrade cycles for European clinical research organizations.
- Research Organizations:Government and non-profit labs face funding consolidation pressures compressing procurement timelines.
Academic Institutions anchor volume. Biotechnology Companies drive specification escalation.
Technology:
Maturity gradients separate established CCD architectures from emerging CMOS alternatives, with illumination technology constrained by chemical substance regulations.
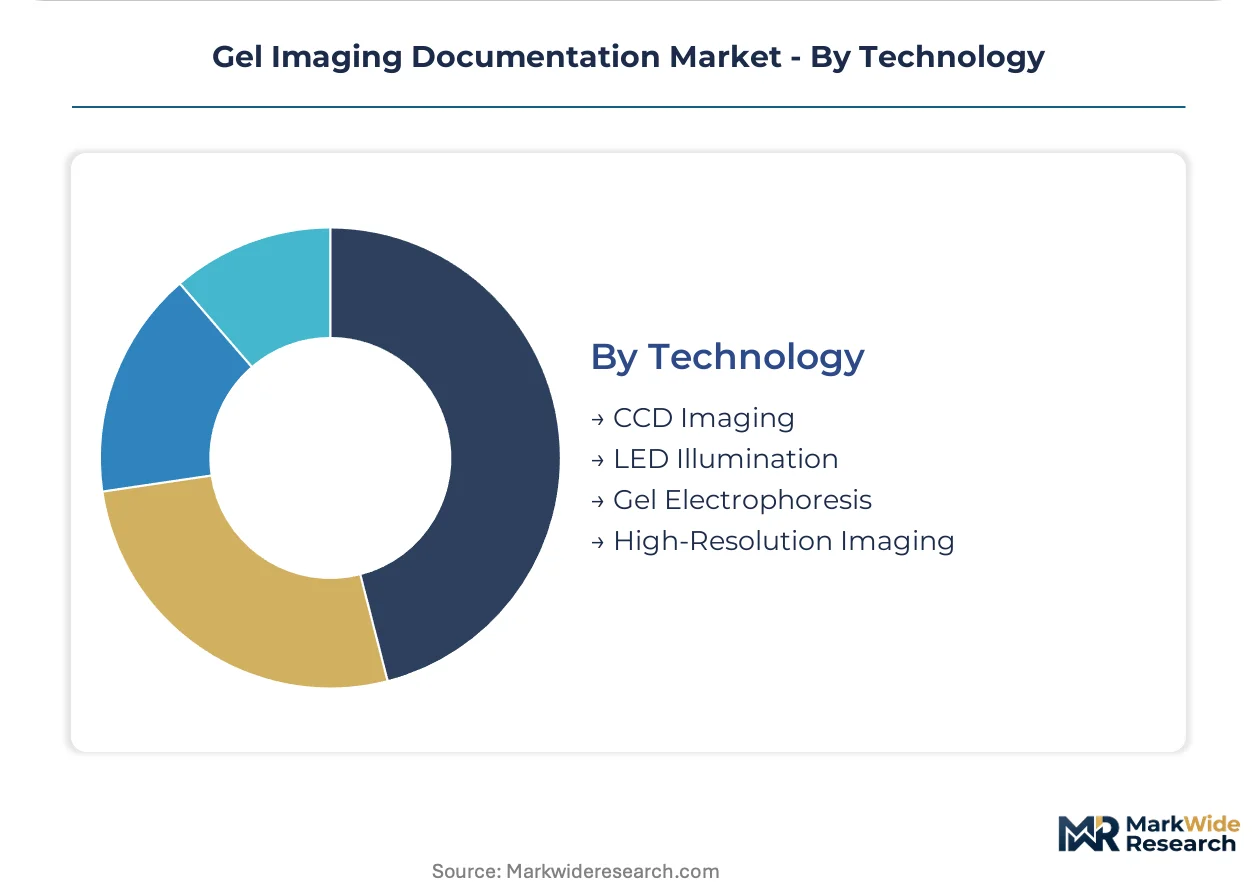
- CCD Imaging:Deep-cooled sensors with 95% quantum efficiency at 600nm remain the sensitivity benchmark for low-abundance protein detection. Japanese and South Korean foundry concentration creates single-source disruption exposure.
- High-Resolution Imaging:sCMOS architectures with 4-16 megapixel resolution unify performance tiers previously segmented between premium CCD and economy CMOS systems.
- LED Illumination:Narrow-band excitation sources face ECHA restrictions on fluorophore compatibility matrices.
- Gel Electrophoresis:Separation technology upstream of imaging capture, with voltage control and buffer systems affecting signal quality.
CCD Imaging defends installed base. High-Resolution Imaging gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States outspends Germany on pharmaceutical-grade imaging systems, yet both markets face divergent compliance timelines that reshape procurement calendars. Japan's PMDA software classification adds regulatory complexity absent in North American deployments. India's production-linked incentive scheme is attracting assembly investment for cost-competitive regional supply.
United States
FDA 21 CFR Part 11 mandates electronic record-keeping for biologics characterization, forcing replacement of film darkrooms in pharmaceutical QC labs. The Boston and San Diego biotech corridors concentrate CRISPR validation workflows requiring high-throughput gel documentation. NIH-funded academic medical centers favor operational expenditure structures over capital depreciation.
Germany
EMA inspection findings on data integrity deficiencies tighten audit trail requirements for electronic signature workflows. The EU MDR elevates gel imaging systems to Class IIa status, compelling clinical research organizations to upgrade platforms. Small molecule CROs in Baden-Württemberg and Bavaria pre-validate analysis templates to minimize configuration drift.
Japan
PMDA medical device software classification creates a third regulatory layer for vendors seeking market access. Domestic pharmaceutical manufacturers prioritize GMP-compliant documentation for biologics submissions. The Kanto region around Tokyo anchors demand from established genomic research institutes.
India
Production-linked incentives for medical device manufacturing enable cost-competitive assembly for domestic and export markets. CDSCO regulatory harmonization efforts align with international standards for diagnostic equipment classification. Karnataka and Telangana host emerging cell therapy development clusters requiring QC imaging infrastructure.
Switzerland
Swissmedic enforcement patterns on data integrity drive upgrade cycles for biologics manufacturing documentation. REACH chemical substance restrictions constrain fluorophore compatibility matrices for illumination systems. Basel's pharmaceutical research concentration absorbs premium-tier validated imaging platforms.
Gel Imaging Documentation Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three hardware tiers that are compressing as CMOS sensor performance unifies. The vendor base clusters around instrumentation conglomerates with workflow bundling power, imaging specialists with software ecosystem lock-in, and regional fabricators with cost-competitive assembly. M&A activity concentrates on software platform acquisitions, while strategic partnerships target LIMS integration APIs.
Within the instrumentation conglomerate tier, Thermo Fisher Scientific and Agilent Technologies occupy positions that leverage thermal cycler and sequencing installed bases for workflow bundling. Bio-Rad Laboratories exemplifies the software-ecosystem specialist archetype through proprietary analysis platform strategies that secure repeat consumables revenue. Azure Biosystems represents the sensitivity-focused pure-play segment competing on chemiluminescence detection benchmarks.
| Leading Market Players |
|---|
| Agilent Technologies |
| Analytik Jena |
| Thermo Fisher Scientific |
| PerkinElmer |
| Azure Biosystems |
| Bio-Rad Laboratories |
| Syngene International |
| Cleaver Scientific |
| GE HealthCare |
| Others |
Supply & Pricing Matrix
Captive sensor fabrication in Japanese and South Korean foundries anchors both supply security and pricing power for premium-tier gel imaging systems, while modular LED illuminator sourcing from contract manufacturers enables cost flexibility at lower tiers. This integration choice separates vendors competing on sensitivity benchmarks from those racing toward subscription software margins.
Pricing Analysis
Capacity additions in India under the PLI scheme are reshaping price floors for mid-tier digital gel imaging systems, compressing the premium-economy gap that previously sustained three distinct hardware categories. Pricing stratifies across FDA-validated pharmaceutical tiers, academic shared-platform bundles, and research-grade entry units, with certification level driving the widest spreads. Cost compression in CMOS-based systems is intensifying because sCMOS quantum efficiency gains erase the CCD sensitivity premium. Academic consortia exhibit highest price sensitivity, while pharmaceutical QC labs absorb premium pricing for 21 CFR Part 11 compliance packages.
Supply Chain Analysis
Freight costs for cooled sensor modules from Japanese foundries to German assembly plants elevate landed costs for EU-bound pharmaceutical-grade systems. Component sourcing draws from South Korea for sCMOS sensors, Taiwan for precision optics, and China for LED illuminator assemblies. Single-source vulnerability concentrates in deep-cooled CCD fabrication, where two Japanese foundries control premium-tier supply. Distribution runs through direct vendor field service teams for validated pharmaceutical deployments, with academic consortia served through regional distribution partners bundling hardware, software seats, and consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in gel imaging documentation rests on software unbundling and the shift from capital equipment sales toward recurring subscription revenue, with cloud-native analysis platforms capturing value previously locked in hardware depreciation cycles.
For Market Incumbents: Hedge against CMOS sensor commoditization by deepening software ecosystem lock-in through proprietary analysis templates and LIMS integration APIs. Thermo Fisher Scientific's workflow bundling model and Bio-Rad's consumables revenue streams demonstrate how installed base leverage defends against pure-play specialists attacking on chemiluminescence sensitivity benchmarks. Field service engineering capacity for IQ/OQ/PQ validation packages represents the critical constraint to monitor.
For New Entrants and Emerging Players: Regional distributors with CRISPR workflow expertise offer the fastest channel to penetrate Boston and San Diego biotech corridors without competing head-to-head against conglomerate bundling power. White-space targets include automated CAR-T vector confirmation imaging and cloud-native analysis platforms for academic shared-platform contracts. A software-first go-to-market angle unburdened by captive sensor fabrication investments sidesteps the capital intensity that constrains hardware-focused entrants.
For Investors and Strategic Acquirers: Roll-up economics work for imaging software specialists because fragmented academic procurement offices increasingly demand enterprise licenses spanning multiple departments and instruments. Long-term viability favors vendors with recurring revenue exposure decoupled from capital equipment replacement cycles. The signal to watch is FDA warning letter patterns on data integrity enforcement, which accelerate compliance-driven upgrade demand disproportionately benefiting validated-platform vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Analysis Platform Launch | Subscription revenue from Boston academic consortia displaces perpetual license dependence. |
| LIMS Integration Partnership | API standardization with Thermo Fisher Scientific's sample management systems secures workflow anchoring. |
| India PLI Scheme Manufacturing Footprint | Cost-competitive assembly for domestic Indian cell therapy clusters and export markets. |
| EU MDR Class IIa Certification Pathway | Swissmedic and EMA compliance unlocks German CRO upgrade cycles and Basel pharmaceutical demand. |
| sCMOS Sensor Architecture Transition | 95% quantum efficiency unification erases CCD premium tier, compressing three-tier hardware structure. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biomedical engineers at NIH-funded academic medical centers, GPO contracts managers at consolidated procurement offices, regulatory affairs leads at pharmaceutical QC labs, and aftermarket service heads at instrumentation vendors. Secondary validation drew from FDA 510(k) filings, EMA medical device registration databases, hospital procurement contract disclosures, and EU MDR technical documentation. Bottom-up instrument shipment modeling and top-down expenditure flow analysis triangulated market sizing across the projection horizon.
Segment-weighted forecasting applied differential growth assumptions across pharmaceutical research, molecular biology, diagnostic laboratory, and forensic science applications, with technology tier splits between CCD and sCMOS architectures modeled separately. Deployment mode segmentation captured capital purchase versus operational expenditure structures, while regional regulatory clusters shaped compliance-driven replacement timing. CAGRs derived from instrument replacement cycle analysis, software subscription conversion rates, and biologics manufacturing capacity expansion pipelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA data integrity enforcement intensity, EU MDR post-market surveillance implementation, and CCD foundry supply disruption scenarios. Forecasts reflect assumptions about academic funding consolidation trajectories and cloud software adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Asia Pacific Industrial Computed Tomography Market
Imaging
Handheld Imaging Devices Market
Imaging
Hybrid Imaging Market
Imaging
APAC Thermal Imaging Systems Market
Imaging
Global High-Speed Digital Camera Market
Imaging
North America Image Sensors Market
Imaging
IP Camera Market
Imaging
3D Sensing and Imaging Market
Imaging
Live Cell Imaging Market
Imaging
Micro-Magnetic Resonance Imaging Market
Imaging
Asia Pacific Smartphone Camera Module Market
Imaging
Camera Lens Market
Imaging
Global Flow Imaging Microscopy/Dynamic Image Analysis Market
Imaging
Industrial Machine Vision Market
Imaging
Phosphor Screen Scanner Market
Imaging
Digital Camera Market