
 HDD Head Assembly Market | 2026-2036
HDD Head Assembly Market Size, Share, and Industry Trends Forecast 2026-2036
HDD Head Assembly Market Insights
Modular bundling of read/write heads with suspension assemblies is consolidating procurement patterns across enterprise storage vendors. TDK leverages its vertical integration across slider fabrication and magnet assembly to sustain pricing power in high-capacity drives. Seagate Technology anchors North American supply through captive manufacturing in Minnesota and Northern Ireland. Western Digital Corporation competes by specializing in energy-assisted magnetic recording head stacks for nearline applications.
The HDD head assembly comprises the slider, suspension, read/write head, actuator arm, and magnet assembly that together position nanoscale transducers above rotating magnetic media with fly heights below one nanometer. Giant magnetoresistive and tunneling magnetoresistive thin-film stacks enable areal densities exceeding one terabit per square inch for mass data retention. Voice coil motor technology still dominates enterprise deployments where seek latency requirements remain stringent, though piezoelectric fine-positioning stages are gaining share in high-vibration data center environments. Cloud storage facilities represent the fastest-growing deployment environment as hyperscalers expand cold and warm tier capacity, while desktop computer applications mature and contract.
FCC equipment authorization rules in the United States govern electromagnetic emissions from integrated drive electronics, while China's MIIT enforces GB standards for energy consumption and noise in information technology equipment. REACH substance restrictions in Europe limit certain lubricants and coatings used in slider air-bearing surfaces, forcing reformulation of protective films. Stakeholders must monitor how evolving areal density roadmaps intersect with regulatory timelines for hazardous material phase-outs and carbon-intensity disclosures.
Market Dynamics
Helium-sealed drive platforms are consolidating component procurement, forcing head assembly vendors to bundle sliders, suspensions, and magnet assemblies into unified subsystems rather than discrete parts.
Growth Catalysts
- Cloud storage expansion:Hyperscalers in the United States, China, and Japan are commissioning multi-exabyte facilities that demand high-capacity nearline drives with energy-assisted magnetic recording heads.
- MIIT dual carbon mandates:China's energy-efficiency standards for data center equipment are accelerating replacement cycles of legacy air-filled drives with helium-sealed alternatives that integrate advanced head assemblies.
- Areal density roadmaps:Tunneling magnetoresistive thin-film stacks are enabling terabit-per-square-inch densities that extend HDD competitiveness against solid-state storage in cold-tier applications.
Market Restraints
- Rare earth magnet supply concentration:Neodymium-iron-boron magnet assemblies depend heavily on Chinese rare earth processing, creating geopolitical exposure for voice coil motor production.
- Sub-nanometer fly height tolerances:Manufacturing yield losses escalate as slider air-bearing surfaces require atomic-scale uniformity, compressing margins at leading-edge nodes.
- REACH substance restrictions:European reformulation mandates for perfluoropolyether lubricants and protective coatings are forcing costly qualification cycles for slider surface treatments.
Strategic Opportunities
- Piezoelectric fine-positioning stages:High-vibration data center environments in Singapore and the Netherlands are creating demand for dual-stage actuation that supplements voice coil motors with piezoelectric elements.
- Modular refurbishment programs:Circular economy frameworks in the European Union are incentivizing head stack assembly remanufacturing for secondary storage applications.
- Energy-assisted recording convergence:Integration of microwave-assisted magnetic recording with heat-assisted magnetic recording is opening pathways to 4 terabit-per-square-inch areal densities for 2030s archive storage.
Industry Challenges
- Cleanroom lithography talent scarcity:Slider fabrication requires expertise in thin-film sputtering and photolithography that competes with semiconductor fabs for skilled technicians in Minnesota and Northern Ireland.
- Multi-year certification timelines:FCC equipment authorization for integrated drive electronics and MIIT GB standard compliance for acoustic emissions extend product validation cycles before commercial deployment.
- Legacy actuator arm integration:New head stack designs must maintain mechanical compatibility with existing voice coil motor infrastructures, constraining form factor innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HDD Head Assembly Market |
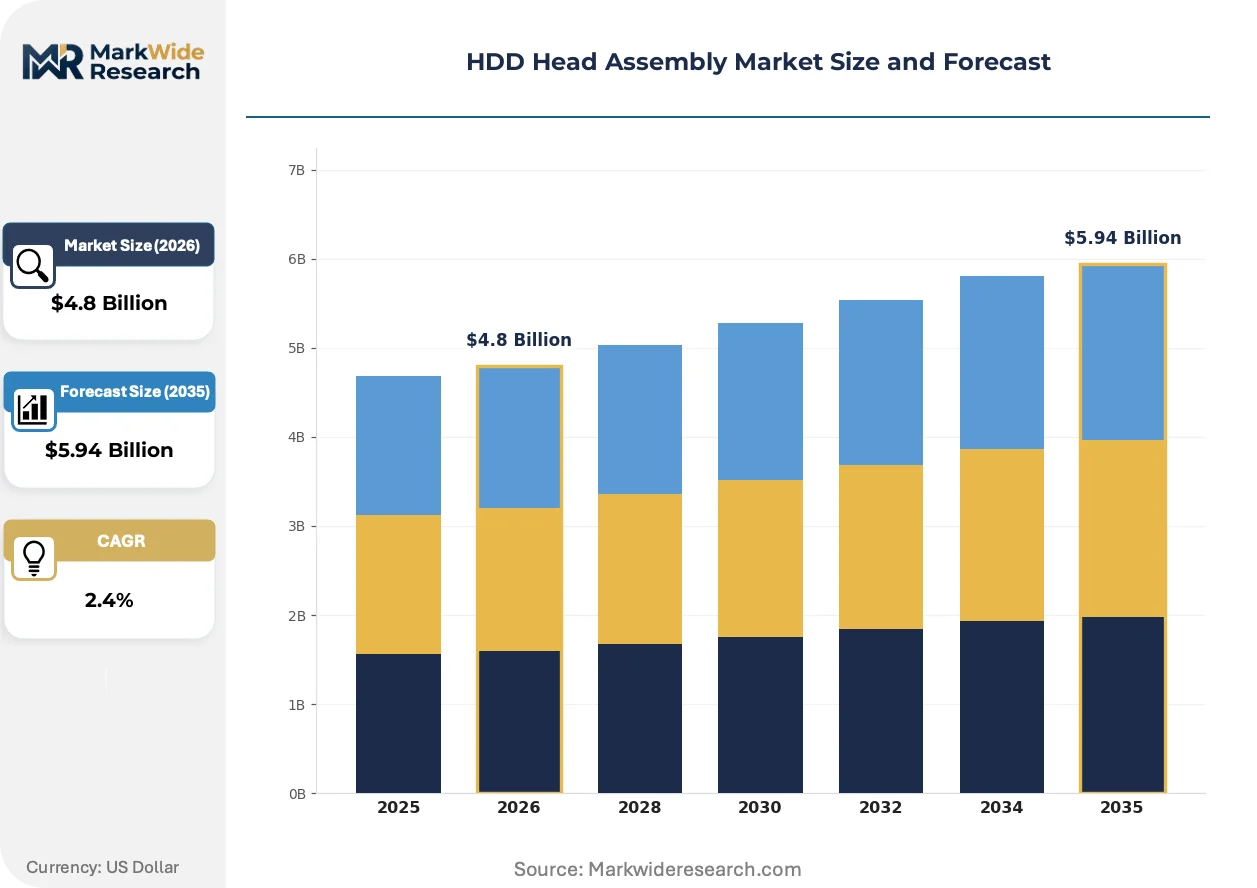
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $5.94 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Slider, Suspension, Read/Write Head, Actuator Arm, Magnet Assembly Technology: Voice Coil Motor, Piezoelectric, Electrostatic, Magnetoresistive, Giant Magnetoresistive End User Industry: Data Centers, Consumer Electronics, Aerospace Systems, Telecommunications, Financial Services Deployment Environment: Enterprise Storage, Desktop Computers, Laptops, Portable Storage Devices, Cloud Storage Facilities |
| Companies Covered | TDK, Seagate Technology, Western Digital Corporation, Hitachi Vantara, Shenzhen Kaifa Technology, Toshiba Electronic Devices & Storage, Samsung Electronics, Hewlett Packard Enterprise, Lenovo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HDD Head Assembly Market Trends and Innovations
Advanced positioning technologies and regulatory pressure on data center energy intensity are reshaping how head assemblies are designed, tested, and deployed across enterprise storage ecosystems.
Energy-assisted magnetic recording head stacks are unifying microwave and heat-assisted modalities to push areal densities beyond current tunneling magnetoresistive limits. Cloud storage operators in the United States are qualifying these unified heads for 30-terabyte nearline drives scheduled for volume deployment. This unification is compressing the competitive window for pure-play magnetic recording technologies that lack auxiliary energy assistance.
China's MIIT dual carbon goals are tightening GB standard enforcement for information technology equipment energy consumption and noise emissions. Domestic data center operators must now document carbon-intensity metrics for storage hardware procurements, favoring helium-sealed drives with lower watt-per-terabyte profiles. Head assembly vendors are redesigning actuator arm geometries to reduce seek power draw while maintaining sub-millisecond latency specifications.
Hyperscalers are consolidating direct procurement relationships with captive head assembly manufacturers, bypassing traditional drive OEM distribution channels. This concentration is visible most acutely in United States cloud campuses where Meta, Microsoft, and Amazon Web Services negotiate multi-year supply agreements for bundled slider-suspension-magnet subsystems. The shift is displacing component distributors and forcing assembly houses to maintain dedicated account engineering teams for each hyperscaler.
HDD Head Assembly Market Segmentation
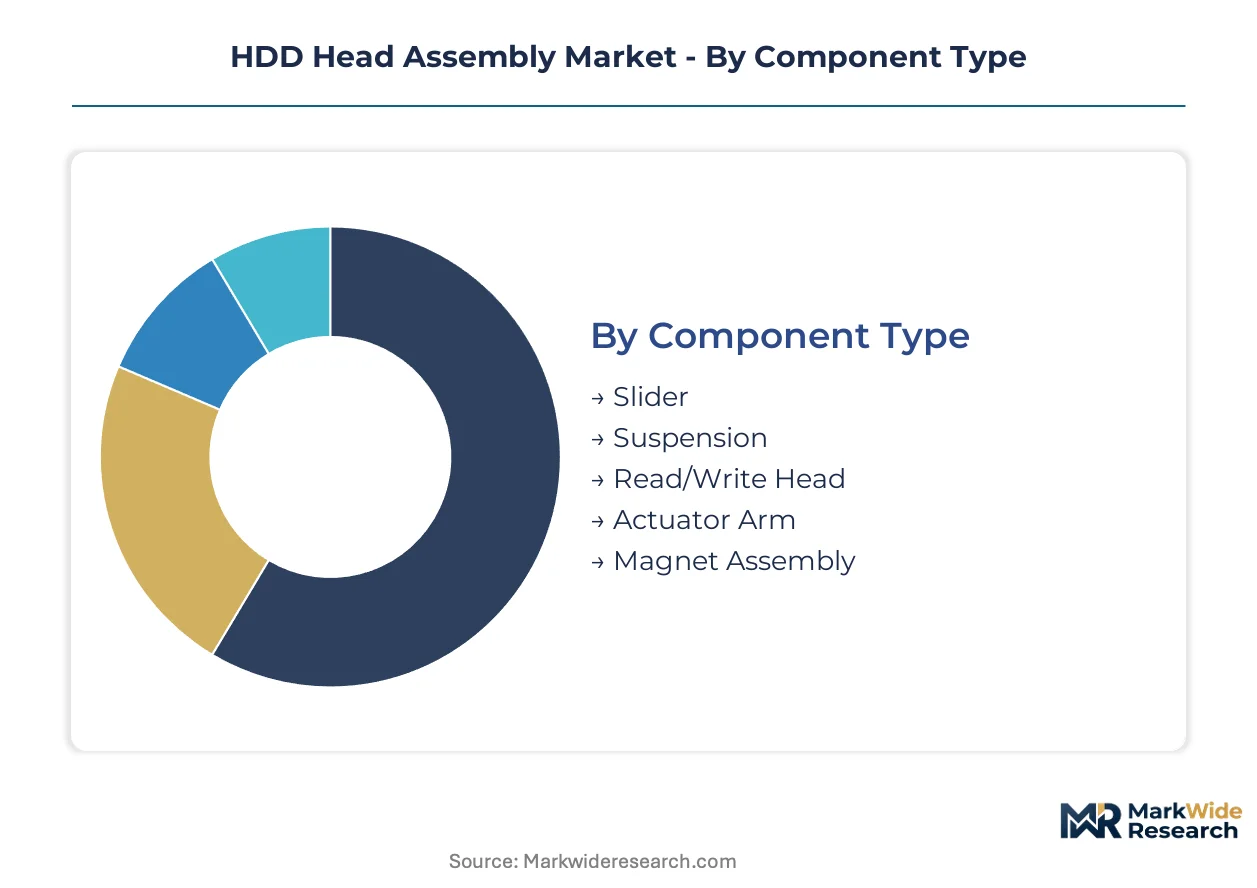
Head assembly procurement patterns diverge sharply across component hierarchies, with capital intensity concentrating in upstream fabrication stages. Understanding where investment requirements cluster helps suppliers align capacity planning with margin capture opportunities.
Component Type:
Slider fabrication demands the heaviest upfront capital allocation due to cleanroom lithography infrastructure and thin-film sputtering equipment.
- Slider:Silicon carbide or aluminum titanium carbide substrates undergo photolithographic patterning to form air-bearing surfaces with sub-nanometer flatness tolerances. Cloud storage facilities in the United States and China absorb the majority of advanced slider output as hyperscalers commission helium-sealed nearline drives with 30-terabyte capacities.
- Read/Write Head:Tunneling magnetoresistive thin-film stacks stack cobalt-iron-boron alloys with magnesium oxide tunnel barriers to achieve terabit-per-square-inch areal densities. Enterprise storage vendors bundle these heads with suspension assemblies, compressing margins for discrete component suppliers.
- Suspension:Stainless steel or laminate structures position the slider above rotating media while maintaining gram-level load forces.
- Actuator Arm:Aluminum alloy castings house voice coil motor windings and pivot bearings for radial positioning across disk surfaces.
- Magnet Assembly:Neodymium-iron-boron permanent magnets generate voice coil motor torque for seek operations.
Slider and read/write head production absorb the bulk of installed capacity; magnet assembly output is expanding most quickly as dual-stage actuation proliferates.
Technology:
Cost tier stratification separates mature voice coil motor deployments from emerging piezoelectric fine-positioning systems commanding premium pricing.
- Voice Coil Motor:Electromagnetic actuation using copper windings and permanent magnets delivers sub-millisecond seek latencies for enterprise workloads. Data centers across Japan and the United States standardize on this technology for primary storage tiers where response time consistency outweighs power efficiency trade-offs.
- Piezoelectric:Lead zirconate titanate elements enable nanometer-scale secondary positioning to compensate for vibration-induced track misregistration. High-vibration environments in Singapore and the Netherlands are driving qualification cycles for these dual-stage configurations.
- Giant Magnetoresistive:Spin-valve structures with alternating ferromagnetic and non-magnetic layers detect magnetic flux transitions in legacy drive architectures.
- Magnetoresistive:Anisotropic magnetoresistance-based sensing provides lower areal density capability for cost-optimized storage applications.
- Electrostatic:Capacitive force generation offers theoretical positioning precision but remains confined to laboratory demonstrations due to contamination sensitivity.
Voice coil motor technology retains dominant share of unit volume; piezoelectric adoption is climbing the fastest among emerging modalities.
End User Industry:
Application-specific reliability requirements create divergent qualification timelines and margin structures across customer verticals.
- Data Centers:Hyperscale operators specify helium-sealed drive platforms with energy-assisted magnetic recording heads for cold and warm tier expansion. China's MIIT dual carbon mandates are accelerating domestic data center procurement of watt-per-terabyte-optimized storage hardware.
- Consumer Electronics:External hard drive and desktop replacement demand continues contracting as solid-state storage displaces rotating media in client computing.
- Financial Services:Regulatory retention requirements sustain demand for archival-grade drives with extended warranty terms and bit-error-rate guarantees.
- Telecommunications:Edge computing nodes require vibration-tolerant head assemblies for distributed content delivery infrastructure.
- Aerospace Systems:Radiation-hardened and extended-temperature-range specifications apply to flight data recorders and satellite storage payloads.
Data center procurement absorbs the bulk of high-capacity head assembly output; telecommunications edge deployment is gaining share fastest.
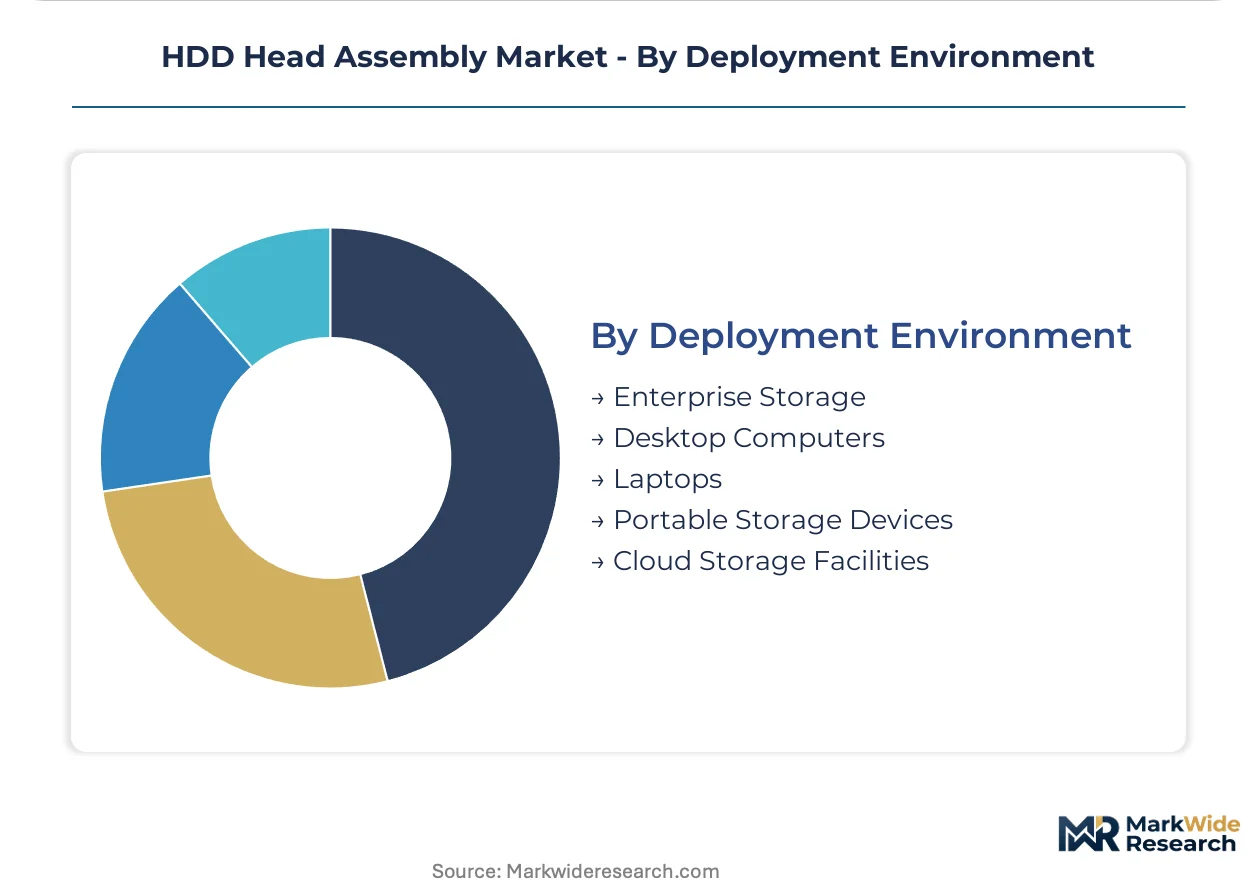
Deployment Environment:
Volume concentration in cloud storage facilities contrasts with declining unit economics in mature client computing segments.
- Cloud Storage Facilities:Multi-exabyte campuses operated by Meta, Microsoft, and Amazon Web Services negotiate direct supply agreements for bundled slider-suspension-magnet subsystems. These facilities bypass traditional drive OEM channels, forcing assembly houses to maintain dedicated account engineering teams.
- Enterprise Storage:Nearline drive arrays for backup and disaster recovery sustain demand for 7200-RPM platforms with energy-assisted recording heads.
- Desktop Computers:Unit shipments decline as client workloads migrate to cloud and solid-state storage.
- Laptops:Mobile computing form factors have nearly eliminated 2.5-inch HDD adoption outside ultra-low-cost segments.
- Portable Storage Devices:External USB drives retain niche demand for offline backup and physical data transfer applications.
Cloud storage facilities command the steepest expansion trajectory; desktop computer deployment contracts most sharply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in the United States, Japan, and China while hyperscale consumption clusters in cloud corridors across the same three markets. Component fabrication requires cleanroom infrastructure and rare earth magnet supply chains that favor established industrial bases. Procurement patterns diverge between captive production for drive OEMs and merchant supply to data center operators.
United States
Hyperscalers Meta, Microsoft, and Amazon Web Services commission multi-exabyte cloud campuses that absorb advanced head stack assemblies for helium-sealed nearline drives. FCC equipment authorization rules govern electromagnetic emissions from integrated drive electronics, extending validation timelines for new product introductions. Minnesota hosts captive slider fabrication facilities serving Seagate Technology's North American supply requirements.
China
Domestic data center operators under MIIT dual carbon mandates accelerate replacement of legacy air-filled drives with watt-per-terabyte-optimized helium platforms. GB standards for energy consumption and noise emissions now require documented carbon-intensity metrics in storage hardware procurements. Shenzhen Kaifa Technology anchors merchant supply capacity in the Pearl River Delta region.
Japan
TDK leverages vertical integration across slider fabrication and magnet assembly to sustain pricing power in high-capacity drive segments. METI industrial policy supports domestic production of advanced magnetic recording components amid supply chain security concerns. Tokyo-Osaka corridor facilities specialize in tunneling magnetoresistive thin-film stack production for terabit-density applications.
Ireland
Northern Ireland hosts Seagate Technology captive manufacturing operations supplying European enterprise storage demand. REACH substance restrictions force reformulation of perfluoropolyether lubricants and protective coatings used in slider air-bearing surfaces. Dublin data center clusters qualify refurbished head stack assemblies under circular economy frameworks.
Singapore
High-vibration data center environments drive qualification of piezoelectric fine-positioning stages that supplement voice coil motor actuation. Tropical climate conditions stress thermal management in sealed drive platforms, favoring advanced head assemblies with reduced power dissipation. Changi North cloud corridor operators negotiate direct procurement agreements bypassing traditional OEM channels.
HDD Head Assembly Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists controlling upstream slider fabrication and downstream magnet assembly. Three to five captive manufacturers supply internal drive production while a shrinking merchant tier serves secondary refurbishment markets. Strategic archetypes separate integrated component-stack suppliers from pure-play suspension houses and rare earth magnet processors. Capacity expansion and strategic partnerships dominate competitive moves as vendors secure multi-year hyperscaler agreements.
Within the integrated-component tier, TDK and Seagate Technology exemplify archetypes of captive supply chain control. TDK represents the diversified materials-and-components conglomerate with upstream reach into thin-film deposition equipment. Seagate Technology anchors the drive-OEM-with-captive-assembly model. Western Digital Corporation occupies a position between these poles, sourcing select components while retaining in-house head stack design. Shenzhen Kaifa Technology sits within the emerging merchant tier serving Chinese domestic demand.
| Leading Market Players |
|---|
| TDK |
| Seagate Technology |
| Western Digital Corporation |
| Hitachi Vantara |
| Shenzhen Kaifa Technology |
| Toshiba Electronic Devices & Storage |
| Samsung Electronics |
| Hewlett Packard Enterprise |
| Lenovo Group |
| Others |
Pricing and Supply Chain Analysis
Neodymium-iron-boron magnet costs cascade from Chinese rare earth processing facilities through voice coil motor assemblies to final head stack pricing tiers. Buyers in United States cloud campuses negotiate multi-year offtake agreements that lock in volume discounts while absorbing commodity volatility through indexed contract clauses. GB standard compliance costs for MIIT carbon-intensity documentation add qualification premiums that separate helium-sealed platform suppliers from legacy air-filled drive component vendors.
Pricing Analysis
Margin tightening in high-capacity slider fabrication reflects yield losses at sub-nanometer flatness tolerances that compress returns on cleanroom lithography investment. Three-tier pricing structure across premium, standard, and economy levels separates energy-assisted magnetic recording head stacks from tunneling magnetoresitive legacy designs and giant magnetoresitive archive-grade units. Price differentiation hinges on areal density certification and volume scale, with hyperscalers commanding steepest discounts through direct procurement bypassing OEM markups. Cloud storage operators exhibit highest price sensitivity due to exabyte-scale procurement volumes, while aerospace systems buyers prioritize radiation-hardened specifications over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from United States hyperscalers require qualified secondary suppliers for slider and suspension subassemblies beyond primary TDK or captive Seagate channels. Manufacturing concentrates in Japan, China, and the United States, with rare earth magnet processing anchored in Chinese domestic supply chains. Raw material dependencies span neodymium-iron-boron permanent magnets, silicon carbide slider substrates, and cobalt-iron-boron thin-film alloys. Single-source vulnerability in Chinese rare earth processing creates geopolitical exposure for voice coil motor torque specifications. Distribution runs through direct account engineering teams serving Meta, Microsoft, and Amazon Web Services, displacing traditional component distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Energy-assisted magnetic recording convergence is displacing pure-play tunneling magnetoresitive head stacks, compressing the competitive window for legacy technology suppliers. Incumbents must secure positioning before microwave and heat-assisted unification reaches volume deployment in hyperscale facilities.
For Market Incumbents: Lock in multi-year direct supply agreements with United States and Chinese hyperscalers before piezoelectric fine-positioning stages reach mainstream qualification. Defend against merchant-tier encroachment by Shenzhen Kaifa Technology through captive backward integration into thin-film sputtering equipment and magnet assembly winding. Prioritize R&D allocation toward 4 terabit-per-square-inch areal density roadmaps that extend HDD competitiveness against solid-state storage in cold-tier applications. For New Entrants and Emerging Players: Secondary refurbishment markets in European Union circular economy frameworks offer the most penetrable entry point for remanufactured head stack assemblies serving disaster recovery and archival storage tiers. Target telecommunications edge computing nodes in Singapore and Netherlands high-vibration environments with piezoelectric dual-stage actuation configurations that supplement legacy voice coil motor infrastructure. Pursue qualification partnerships with regional data center operators seeking carbon-intensity documentation under MIIT dual carbon mandates. For Investors and Strategic Acquirers: Seagate Technology's captive manufacturing footprint expansion in Northern Ireland is the leading indicator that European supply chain regionalization is accelerating beyond tariff exposure mitigation. Long-term viability over the next decade hinges on areal density roadmap execution rather than unit volume growth, favoring acquisition targets with proven thin-film stack deposition expertise over pure-play suspension houses. Watch for FCC equipment authorization timeline compression as the inflection signal for new product introduction velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Helium-Sealed Platform Integration | Unifies slider, suspension, and magnet procurement into single subsystem contracts with hyperscalers. |
| Piezoelectric Stage Qualification | Enables dual-stage actuation penetration in Singapore and Netherlands high-vibration data center corridors. |
| Rare Earth Magnet Supply Agreement | Secures neodymium-iron-boron torque specifications against Chinese processing concentration risk. |
| Energy-Assisted Recording Convergence | Combines microwave and heat-assisted modalities for 4 terabit-per-square-inch density targets. |
| Circular Economy Refurbishment Program | Qualifies remanufactured head stacks under EU frameworks for secondary storage applications. |
Research Methodology
Multi-period observation of hyperscaler capex disclosures, areal density roadmap announcements, and MIIT regulatory filing timelines anchored the trend analysis, supplemented by interviews with head stack design engineers, data center procurement officers, thin-film deposition equipment specialists, and voice coil motor manufacturing directors. Secondary validation drew from FCC equipment authorization databases, SEC 10-K supply chain disclosures, Japanese METI industrial policy white papers, and Chinese GB standard revision notices. Bottom-up component demand modeling triangulated against top-down cloud storage capacity expansion forecasts.
Segment-weighting across component type, technology modality, end user industry, and deployment environment distributed value projections throughout the modeling period. Voice coil motor and piezoelectric actuation splits reflected seek latency specifications versus vibration tolerance requirements. Cloud storage facility procurement patterns carried highest weight given hyperscaler direct supply agreement concentration. CAGRs derived from rolling average capacity expansion rates across United States, Chinese, and Japanese multi-exabyte campuses.
Revisions become necessary when rare earth export restrictions materialize, helium supply constraints emerge, or solid-state storage cost-per-terabyte curves steepen beyond projected crossover thresholds. Deviation in FCC or MIIT certification timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
USB 3.1 Flash Drive Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market
Data Storage
Germany Data Center Storage Market
Data Storage
Ceph Storage Solutions Market
Data Storage
Next-Generation Storage Market
Data Storage
Holographic Versatile Disc (HVD) Market
Data Storage
Global Digital Storage Devices Market
Data Storage
Hardware Storage Market
Data Storage
NAND Flash Memory Market
Data Storage
Ireland Data Center Storage Market
Data Storage
Powered Storage Devices Market
Data Storage
Zoned Flash Market
Data Storage
Data Storage Market
Data Storage
Recordable Optical Disc Market
Data Storage
Optical Disk Market
Data Storage
Middle East Data Center Storage Market