
 Europe Image Sensors Market | 2026-2036
Europe Image Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Image Sensors Market Foresight
Multi-source wafer supply is restructuring procurement patterns across European image sensor vendors. STMicroelectronics leverages its Grenoble R&D footprint to sustain CCD-to-CMOS transition programs. Sony Semiconductor Solutions anchors high-resolution CMOS flows for automotive tier-1s in France and Germany. ON Semiconductor Corporation competes through specialized low-light architectures for security and medical endpoints.
Europe image sensors are solid-state optoelectronic devices converting photonic signals into electrical output, typically fabricated on silicon wafers with microlens arrays and backside-illuminated architectures achieving quantum efficiencies above 80% in visible spectra. Their primary commercial purpose spans machine vision, autonomous navigation, and diagnostic imaging where spatial resolution and frame rate determine system performance. CMOS technology dominates unit economics and design flexibility across automotive and consumer applications, while CCD retains niche positioning in scientific instrumentation where read noise specifications justify higher bill-of-material costs. Security Systems applications show structural acceleration as EU border infrastructure and smart city programs expand camera density requirements.
EMA medical device frameworks, ECE R79 automotive camera mandates, and RoHS substance restrictions collectively shape product qualification pathways and market access conditions for sensor vendors serving European buyers. REACH compliance obligations on semiconductor materials further constrain supply base options for manufacturers without in-house chemical stewardship programs. Stakeholders must monitor convergence between EU AI Act algorithmic transparency requirements and emerging functional safety standards for vision systems in autonomous platforms.
Market Dynamics
Camera-based ADAS mandates under ECE R79 are forcing automotive OEMs to triple vision system counts per vehicle, restructuring silicon procurement toward automotive-grade CMOS flows.
Growth Catalysts
- ECE R79 Camera Mandates:European automotive OEMs must deploy surround-view and driver-monitoring systems, creating guaranteed offtake for 2+ megapixel automotive sensors through 2030.
- EU Border Infrastructure Modernization:Schengen perimeter expansion drives thermal and visible-spectrum camera density at ports and crossings, lifting security segment demand.
- Backside-Illuminated Architectures:Quantum efficiency gains above 80% in low-light conditions enable medical endoscopy and surgical navigation upgrades across European hospital networks.
Market Restraints
- 300mm Wafer Supply Concentration:Foundry capacity for automotive-qualified CIS processes concentrates in East Asian facilities, exposing European fabless designers to allocation risk.
- REACH Chemical Compliance:Substance restrictions on semiconductor materials constrain photoresist and cleaning chemical sourcing, extending qualification timelines for new sensor designs.
- CCD Legacy Installed Base:Scientific instrumentation retains CCD architectures for ultra-low read noise applications, fragmenting R&D resources across two technology platforms.
Strategic Opportunities
- EU AI Act Algorithmic Transparency:Vision system documentation requirements create service revenue streams for sensor vendors offering embedded metadata and traceability features.
- Central European Medical Device Manufacturing:Poland and Czech Republic emerging as contract manufacturing locations for diagnostic imaging equipment, pulling sensor distribution eastward.
- Event-Based Sensor Fusion:Convergence of frame-based CMOS with dynamic vision sensors enables sub-millisecond latency for autonomous emergency braking systems.
Industry Challenges
- Automotive Functional Safety Certification:ISO 26262 ASIL-B/D qualification for image sensors demands 18-24 month validation cycles, compressing product refresh windows.
- Multi-Wafer Source Integration:Qualifying identical sensor designs across 200mm and 300mm foundry flows requires process tuning that degrades yield parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Image Sensors Market |
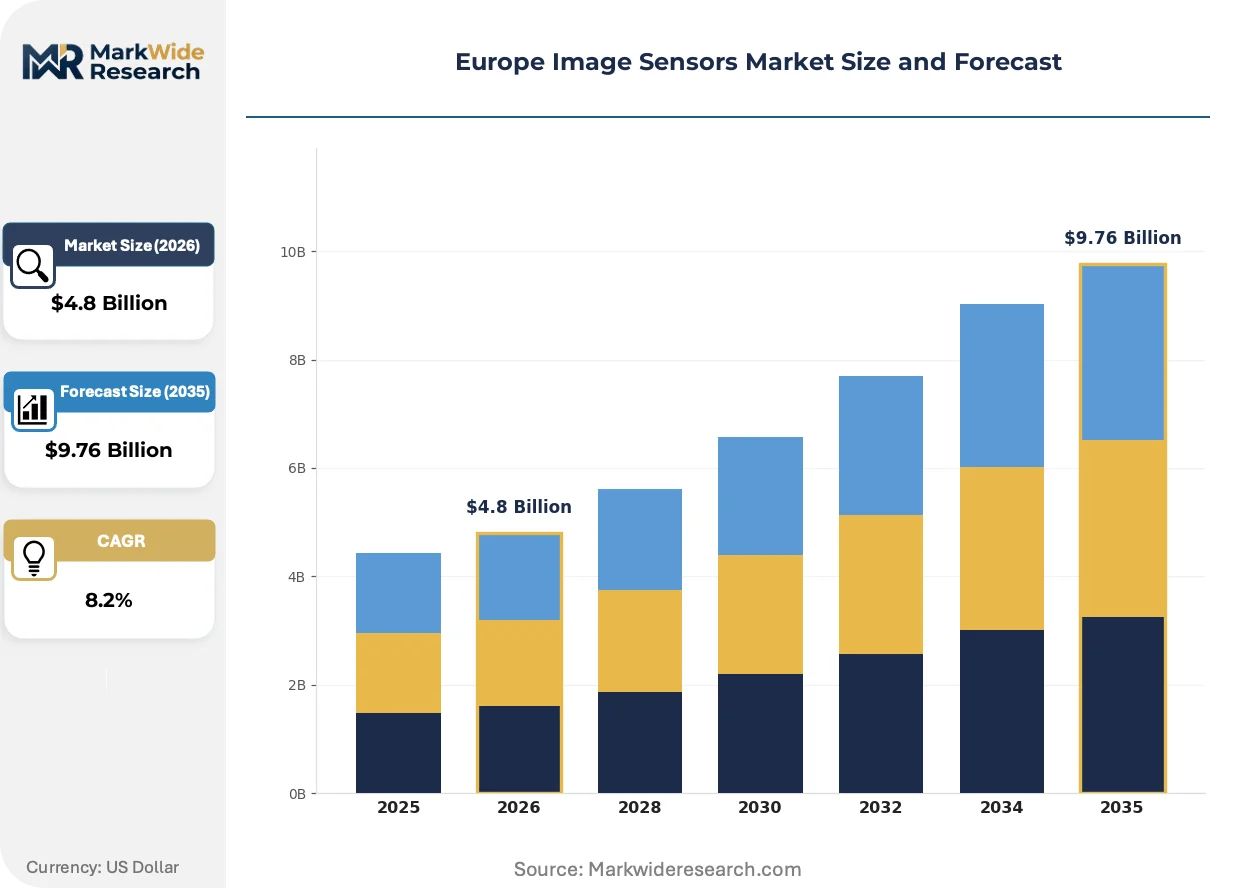
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CMOS, CCD, APU, PID Application: Automotive Systems, Consumer Electronics, Medical Devices, Security Systems Technology: Analog, Digital, Hybrid, Noise Reduction End User: Manufacturers, OEMs, Distributors, Research Institutions |
| Companies Covered | Sony Semiconductor Solutions, STMicroelectronics, Samsung Electronics Co., Ltd., OmniVision Technologies, Inc., ON Semiconductor Corporation, Canon Inc., Panasonic Holdings Corporation, NXP Semiconductors N.V., Teledyne Technologies Incorporated, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Image Sensors Market Shifts & Advancements
Stacked CMOS architectures and EU regulatory mandates are compressing the technology roadmap, forcing vendors to integrate processing intelligence at the pixel level while navigating compliance complexity.
Backside-illuminated stacked CMOS is consolidating high-performance segments by embedding DRAM and AI accelerators beneath the photodiode layer. Automotive tier-1s in Germany and France are adopting these flows for 8-megapixel surround-view cameras. The architecture is consolidating bill-of-material counts by eliminating external image signal processors.
EU AI Act algorithmic transparency requirements are reshaping vision system documentation obligations. Sensor vendors must now embed provenance metadata and decision-logging capabilities at the hardware level. Medical imaging and autonomous driving segments face the steepest compliance ramps, with French and German notified bodies issuing draft guidance.
Long-term supply agreements are displacing spot-market wafer procurement among European sensor designers. Tier-1 automotive suppliers are locking 3-5 year foundry capacity reservations to secure automotive-grade CIS output. Bavaria and Baden-Württemberg automotive clusters exhibit the tightest contract penetration, with security and medical buyers following suit.
Europe Image Sensors Market Segmentation
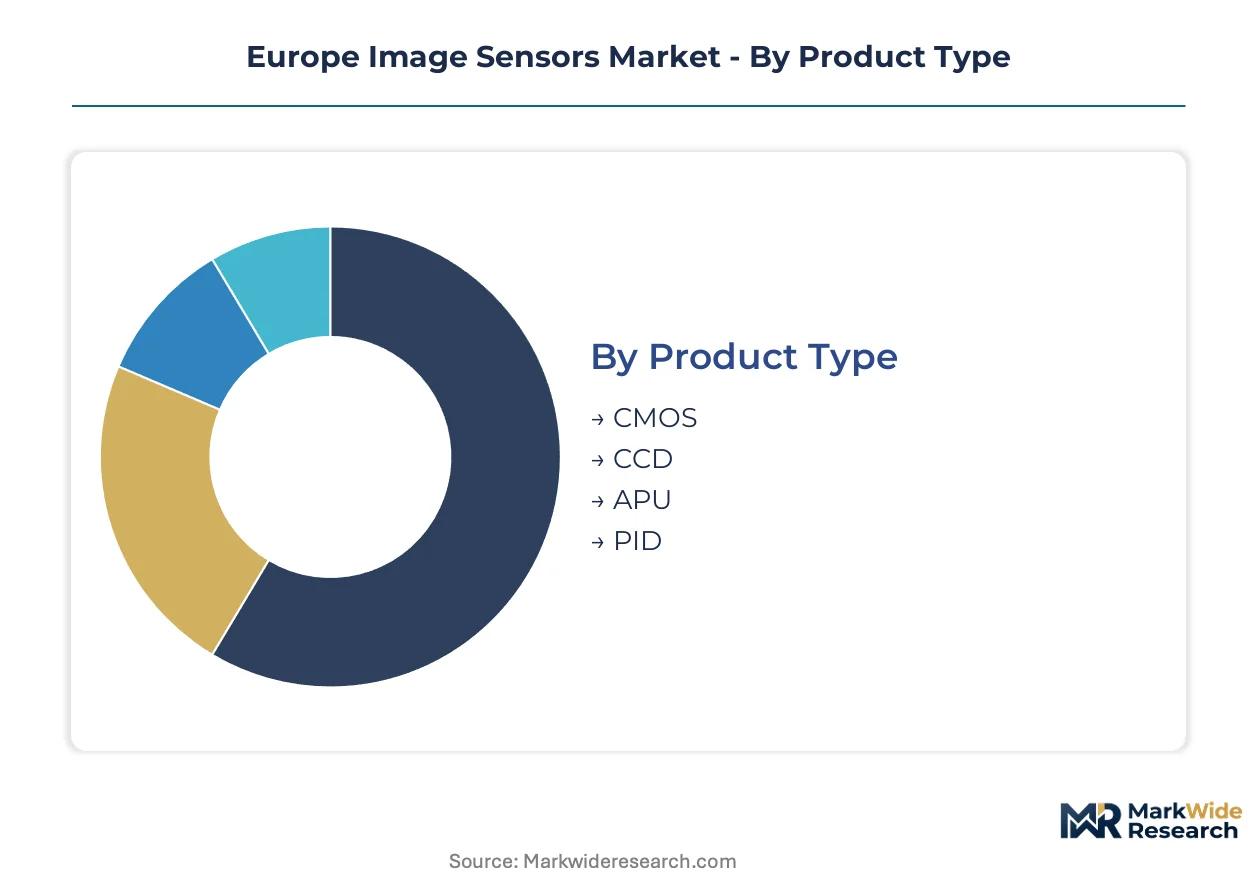
Europe Image Sensors Market segmentation reveals how ECE R79 automotive mandates, MDR medical certification, and EU AI Act transparency requirements create divergent qualification burdens across product categories. Each segment carries distinct regulatory pathways that reshape vendor R&D allocation and customer procurement priorities.
Product Type:
CMOS and CCD architectures face divergent REACH substance restrictions and automotive functional safety certification timelines under ISO 26262.
- CMOS:Backside-illuminated stacked architectures dominate Bavaria and Baden-Württemberg automotive clusters, embedding DRAM and AI accelerators beneath photodiode layers to eliminate external image signal processors. German OEM surround-view camera programs drive guaranteed offtake for 2+ megapixel automotive-grade flows through the forecast window.
- CCD:Scientific instrumentation in France and Germany retains charge-coupled devices for ultra-low read noise specifications below 3 electrons, fragmenting R&D resources across two technology platforms despite declining unit economics.
- APU:Application processing units integrate vision compute at the sensor edge for EU AI Act algorithmic transparency requirements.
- PID:Photon imaging detectors serve niche medical fluorescence microscopy with specialized quantum efficiency profiles.
Leading the category by volume: CMOS. Growing fastest: APU.
Application:
Cost tier stratification separates premium medical imaging from high-volume automotive and security deployments.
- Automotive Systems:ECE R79 mandates force German and French OEMs to triple vision system counts per vehicle, restructuring silicon procurement toward automotive-grade CIS processes with 18-24 month ISO 26262 ASIL-B/D validation cycles.
- Security Systems:Schengen perimeter expansion and smart city programs across Poland and Czech Republic drive thermal and visible-spectrum camera density at ports and crossings.
- Medical Devices:EMA MDR frameworks and backside-illuminated quantum efficiency gains above 80% enable endoscopy and surgical navigation upgrades across European hospital networks.
- Consumer Electronics:Smartphone and wearable demand concentrates in contract manufacturing hubs with shorter qualification timelines.
Highest certification burden: Medical Devices. Steepest volume expansion: Security Systems.
Technology:
Margin structure separates analog legacy flows from digital stacked architectures requiring 300mm foundry investment.
- Digital:Stacked CMOS with embedded AI accelerators commands premium positioning in German tier-1 automotive supply chains, consolidating bill-of-material counts while meeting EU AI Act metadata provenance requirements.
- Noise Reduction:Advanced algorithms for low-light medical and security endpoints differentiate sensor vendors competing on specification sheets rather than pixel count alone.
- Analog:Legacy readout circuits persist in cost-sensitive industrial vision applications.
- Hybrid:Mixed-signal architectures bridge frame-based CMOS with event-based dynamic vision sensors for sub-millisecond autonomous emergency braking latency.
Widest margin capture: Digital. Fastest technology transition: Hybrid.
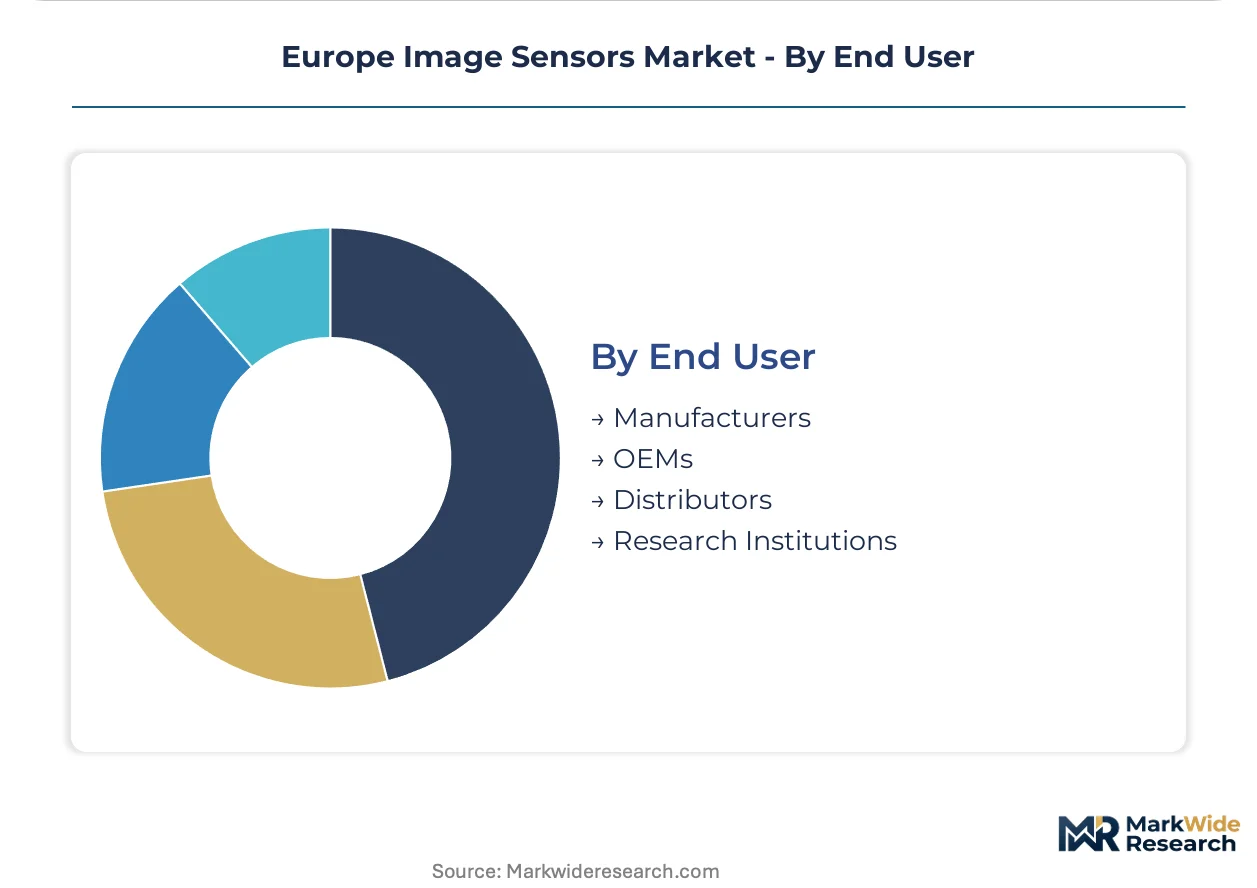
End User:
Supply concentration varies sharply between captive OEM sensor design teams and fragmented distributor networks serving research institutions.
- OEMs:German and French automotive manufacturers lock 3-5 year foundry capacity reservations for automotive-grade CIS output, displacing spot-market procurement with long-term supply agreements.
- Manufacturers:Medical device contract manufacturers in Poland and Czech Republic pull sensor distribution eastward from traditional Western European logistics hubs.
- Distributors:Security and industrial vision channels face allocation risk from 300mm wafer supply concentration in East Asian facilities.
- Research Institutions:Scientific instrumentation buyers retain CCD procurement for ultra-low read noise applications with extended qualification tolerance.
Tightest supply security: OEMs. Most price-sensitive procurement: Research Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer supply from German and French foundry partnerships anchors European image sensor production networks. Bavaria and Baden-Württemberg automotive clusters concentrate demand for automotive-grade CMOS flows. ECE R79 mandates and EU AI Act compliance requirements reshape procurement patterns across the continent.
Germany
Bavaria and Baden-Württemberg automotive clusters drive guaranteed offtake for 2+ megapixel automotive sensors through German OEM surround-view camera programs. ECE R79 mandates force manufacturers to triple vision system counts per vehicle, restructuring silicon procurement toward automotive-grade CIS processes with 18-24 month ISO 26262 ASIL-B/D validation cycles. Stuttgart and Munich anchor tier-1 supplier engineering centers.
France
Île-de-France hosts Sony Semiconductor Solutions operations serving high-resolution CMOS flows for automotive tier-1s. ANSM and CNIL guidance on EU AI Act algorithmic transparency requirements reshape medical imaging and autonomous driving compliance ramps. Grenoble sustains STMicroelectronics CCD-to-CMOS transition programs with captive R&D infrastructure.
United Kingdom
London and Southeast England concentrate security system integrators responding to Schengen perimeter expansion demands for thermal and visible-spectrum camera density. MHRA medical device frameworks align with EMA MDR requirements for diagnostic imaging equipment qualification. Cambridge and Oxford scientific instrumentation clusters retain CCD procurement for ultra-low read noise applications.
Poland
Contract manufacturing locations for diagnostic imaging equipment pull sensor distribution eastward from traditional Western European logistics hubs. EU border infrastructure modernization programs drive camera deployment at eastern Schengen crossings. Warsaw and Kraków emerging as medical device assembly centers under EMA MDR frameworks.
Netherlands
Eindhoven Region semiconductor equipment ecosystem supports backside-illuminated stacked CMOS process development. REACH chemical compliance obligations on semiconductor materials constrain photoresist and cleaning chemical sourcing for sensor designers. Rotterdam and Amsterdam logistics hubs manage wafer allocation risk from 300mm foundry concentration.
Europe Image Sensors Market Competitive Landscape
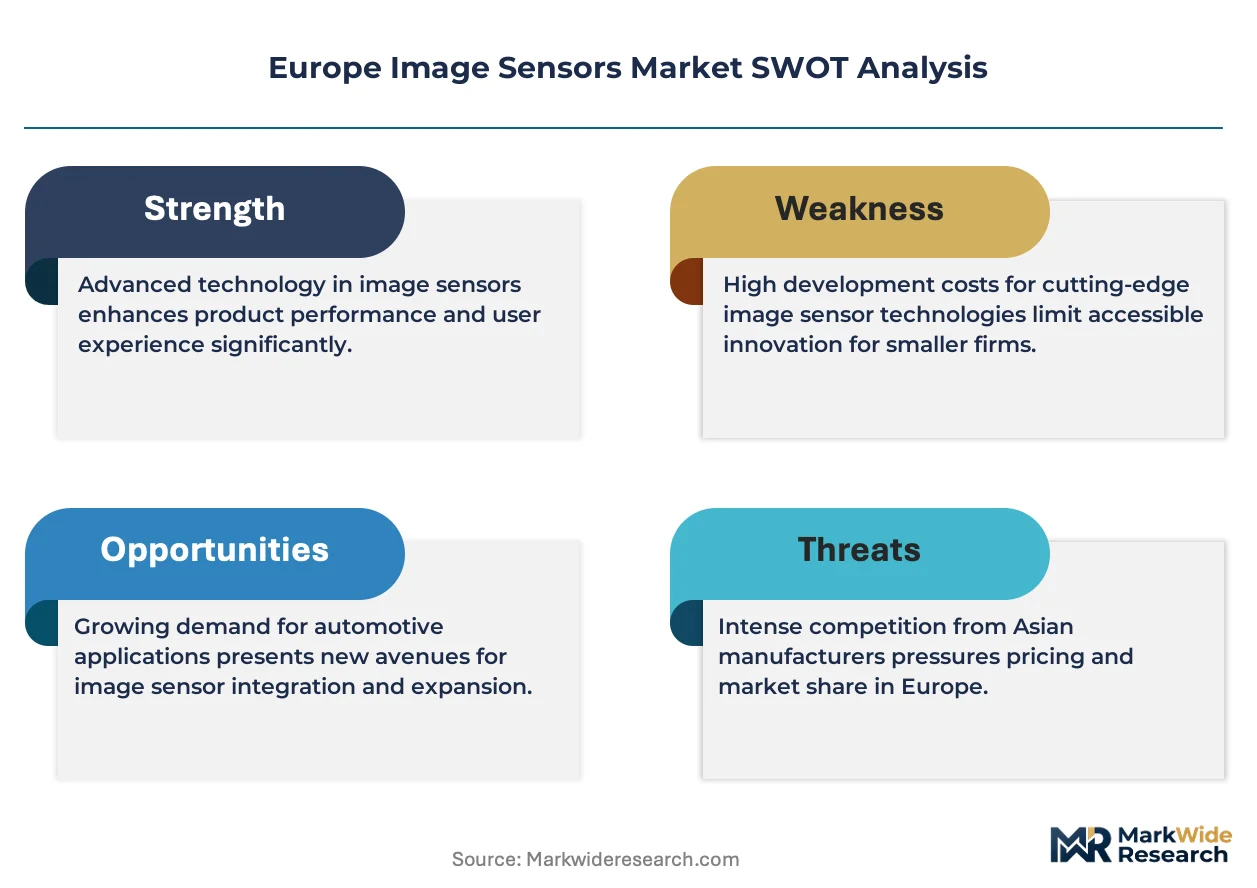
Global majors compete with regional champions across technology licensing and foundry capacity reservation dimensions. The vendor base stratifies between captive IDM flows and fabless designers dependent on East Asian foundry allocation. Three archetypes dominate: integrated device manufacturers with captive fabs, fabless specialists licensing process technology, and diversified electronics conglomerates leveraging vertical scale. Competitive moves concentrate on long-term supply agreements displacing spot-market procurement and embedded AI accelerator integration at the pixel level.
Among diversified electronics conglomerates, Samsung Electronics Co., Ltd. exemplifies scale-driven vertical integration into semiconductor manufacturing. STMicroelectronics and Sony Semiconductor Solutions occupy positions spanning the integrated device manufacturer and specialized component supplier archetypes respectively. ON Semiconductor Corporation represents the fabless-specialist tier competing through differentiated low-light architectures. These three anchors demonstrate how geographic R&D footprint and foundry partnership depth determine competitive positioning under EU regulatory compliance requirements.
| Leading Market Players |
|---|
| Sony Semiconductor Solutions |
| STMicroelectronics |
| Samsung Electronics Co., Ltd. |
| OmniVision Technologies, Inc. |
| ON Semiconductor Corporation |
| Canon Inc. |
| Panasonic Holdings Corporation |
| NXP Semiconductors N.V. |
| Teledyne Technologies Incorporated |
| Others |
Supply & Pricing Matrix
ECE R79 camera mandates are forcing German and French automotive OEMs to lock multi-year foundry capacity reservations, compelling suppliers to restructure pricing around guaranteed offtake volumes rather than spot-market flexibility. This procurement shift concentrates pricing power with IDMs holding captive automotive-grade CIS flows while squeezing margin buffers for fabless designers competing on specification differentiation.
Pricing Analysis
Extended warranty and ISO 26262 compliance documentation bundles now separate premium automotive-grade sensors from unbundled industrial offerings. Three-tier pricing structure across automotive-certified, medical-grade, and security-economy levels reflects divergence in validation cycle investments. Pricing pressure stems from 300mm wafer allocation constraints favoring volume buyers with long-term contracts. Research institutions exhibit highest price sensitivity due to CCD legacy dependence and extended replacement timelines.
Supply Chain Analysis
Dual-sourcing requirements from Bavaria and Baden-Württemberg automotive clusters mandate qualification across both 200mm and 300mm foundry flows, complicating yield parity maintenance. Wafer supply concentrates in Taiwan, South Korea, and Japan, with photoresist and specialty chemical inputs drawing from German and Dutch chemical stewardship programs. Single-source vulnerability runs through East Asian foundry concentration for automotive-qualified CIS processes. Distribution runs through tier-1 automotive supplier engineering centers in Stuttgart and Munich, with security channels following distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European image sensor market is becoming a vertical-integration race where captive foundry partnerships and in-house AI accelerator design determine competitive viability. Players are pursuing upstream control over 300mm automotive-qualified wafer allocation to secure margin capture against fabless competitors.
For Market Incumbents: Deploy long-term foundry capacity reservations to lock automotive-grade CIS output before allocation tightening accelerates. Consolidate R&D resources toward stacked CMOS with embedded DRAM to eliminate external image signal processor dependency. Defend against emerging event-based sensor fusion substitutes by accelerating sub-millisecond latency roadmaps. For New Entrants and Emerging Players: Tier-2 automotive suppliers in Central Europe represent the most penetrable channel partner type for fabless designers lacking IDM scale. Target medical device contract manufacturers in Poland and Czech Republic where MDR qualification timelines create specification windows for differentiated low-light architectures. Pursue security system integrators responding to Schengen perimeter expansion as a volume ramp pathway. For Investors and Strategic Acquirers: The window for entry favors fabless specialists with differentiated low-light IP and established tier-1 automotive qualification relationships. Long-term viability hinges on acquisition targets possessing embedded AI accelerator design capabilities and REACH chemical stewardship programs. Watch for inflection where EU AI Act algorithmic transparency requirements trigger hardware-level metadata provenance mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Foundry Capacity Reservation | Locks automotive-grade CIS output for ECE R79 compliance ramps in German OEM programs. |
| Stacked CMOS Architecture Development | Embeds DRAM beneath photodiode layers to eliminate external image signal processors for tier-1s. |
| EU AI Act Compliance Integration | Hardware-level metadata provenance features capture service revenue from French and German notified body guidance. |
| Central European Manufacturing Footprint | Poland and Czech Republic contract manufacturing pulls sensor distribution eastward from Western logistics hubs. |
| Event-Based Sensor Fusion Partnership | Dynamic vision sensor convergence enables sub-millisecond latency for autonomous emergency braking systems. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with tier-1 automotive supplier procurement managers, medical device biomedical engineers, and semiconductor foundry planning officers combined with ECHA REACH substance databases, EMA MDR submission records, and vehicle production registration data. Bottom-up sensor shipment estimates and top-down automotive vision system content analysis provided triangulation across modeling approaches.
Data-stream reconciliation across product type, application, technology, and end-user dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by automotive camera mandate compliance schedules, medical device upgrade cycles, and security infrastructure deployment timelines. Forecast inputs incorporated ECE R79 implementation phasing, EU AI Act algorithmic transparency draft guidance, and 300mm wafer foundry capacity expansion announcements.
Caveats apply where foundry allocation disruptions, REACH substance restriction expansions, or ISO 26262 validation timeline extensions could materially shift the outlook. Deviation in East Asian wafer supply concentration or EU regulatory enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Digital Image Processing Market
Imaging
Digital Camera Market
Imaging
Global Acoustic Cameras Market
Imaging
China Electron Microscopy Market
Imaging
Global Cell Imagers Market
Imaging
Global Computed Radiography Market
Imaging
Wearable IP Camera Market
Imaging
Microscopic Camera Market
Imaging
Europe Hyperspectral Imaging Market
Imaging
Short-Wave Infrared (SWIR) Camera Market
Imaging
IP Camera Market
Imaging
Uncooled Infrared Imaging Market
Imaging
Digital Microscope Market
Imaging
Hyperspectral Imaging Market
Imaging
Borescope Market
Imaging
Hybrid Imaging Systems Market