
 Semiconductor Microscopes Market | 2026-2036
Semiconductor Microscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Microscopes Market Outlook
REACH compliance is consolidating the cost-of-entry calculus for European semiconductor equipment procurement, forcing microscope vendors to certify materials traceability across their supply chains. KLA Corporation leverages its installed base of e-beam inspection systems to sustain premium positioning in advanced node metrology. Applied Materials anchors its microscope portfolio through integration with broader process control suites, while Zeiss Group differentiates via proprietary extreme ultraviolet optics expertise.
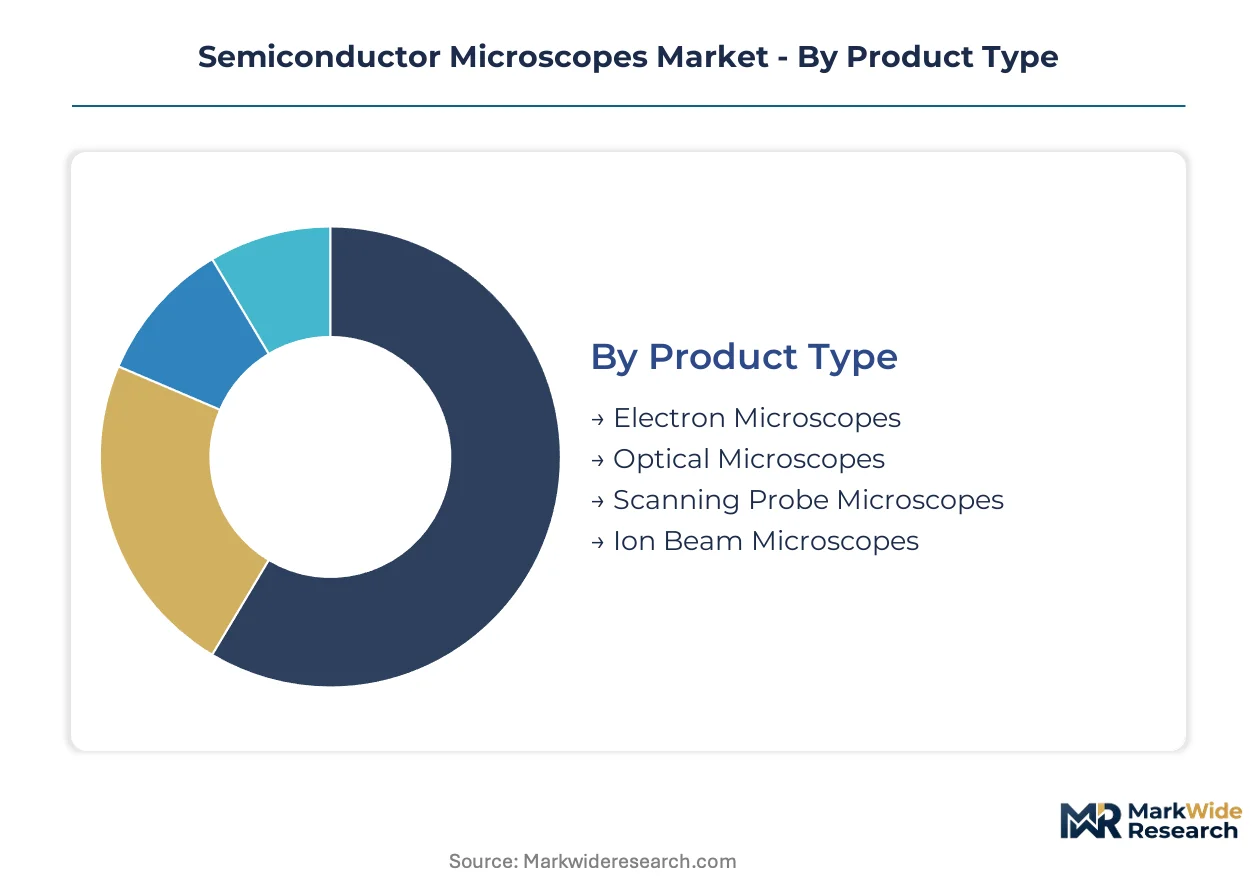
Semiconductor microscopes are precision instruments employing electron beams, photons, or physical probes to resolve features at sub-nanometer scales, with electron microscopes typically operating at accelerating voltages between one and thirty kilovolts to image transistor architectures and detect crystallographic defects. Their primary commercial purpose centers on guaranteeing yield and reliability across wafer fabrication, packaging, and final test operations. Electron microscopes command the largest revenue share among product types due to their indispensability for transistor-level failure analysis, while scanning probe microscopes represent the fastest-expanding category as atomic force microscopy penetrates three-dimensional NAND and gate-all-around device characterization. Application demand concentrates heaviest in failure analysis workflows, though device metrology is accelerating as multipatterning and backside power delivery architectures multiply the measurement points per wafer.
The EU AI Act and CE marking requirements are reshaping product documentation and algorithmic transparency obligations for automated defect classification systems embedded in microscope platforms. FDA oversight of semiconductor components destined for medical devices further tightens traceability standards for US-bound equipment. Japan's METI semiconductor revitalization framework and South Korea's K-Semiconductor Belt strategy are channeling public funding toward domestic microscopy R&D capacity. Stakeholders must weigh localization incentives against the concentration of specialized electron optics manufacturing in Germany and Japan when configuring regional service and supply architectures.
Market Dynamics
Node migration below three nanometers is compressing metrology windows and forcing packaging facilities to triple inspection points per wafer, restructuring procurement priorities toward multi-modal microscopy platforms.
Growth Catalysts
- Advanced Packaging Proliferation:Heterogeneous integration and chiplet architectures multiply interconnect inspection requirements, pulling electron microscopy capacity into OSAT facilities previously reliant on optical methods.
- EU Chips Act Capital Flows:European fabrication subsidies are accelerating cleanroom buildouts in Dresden and Leuven, directly expanding the installed base of high-resolution failure analysis equipment.
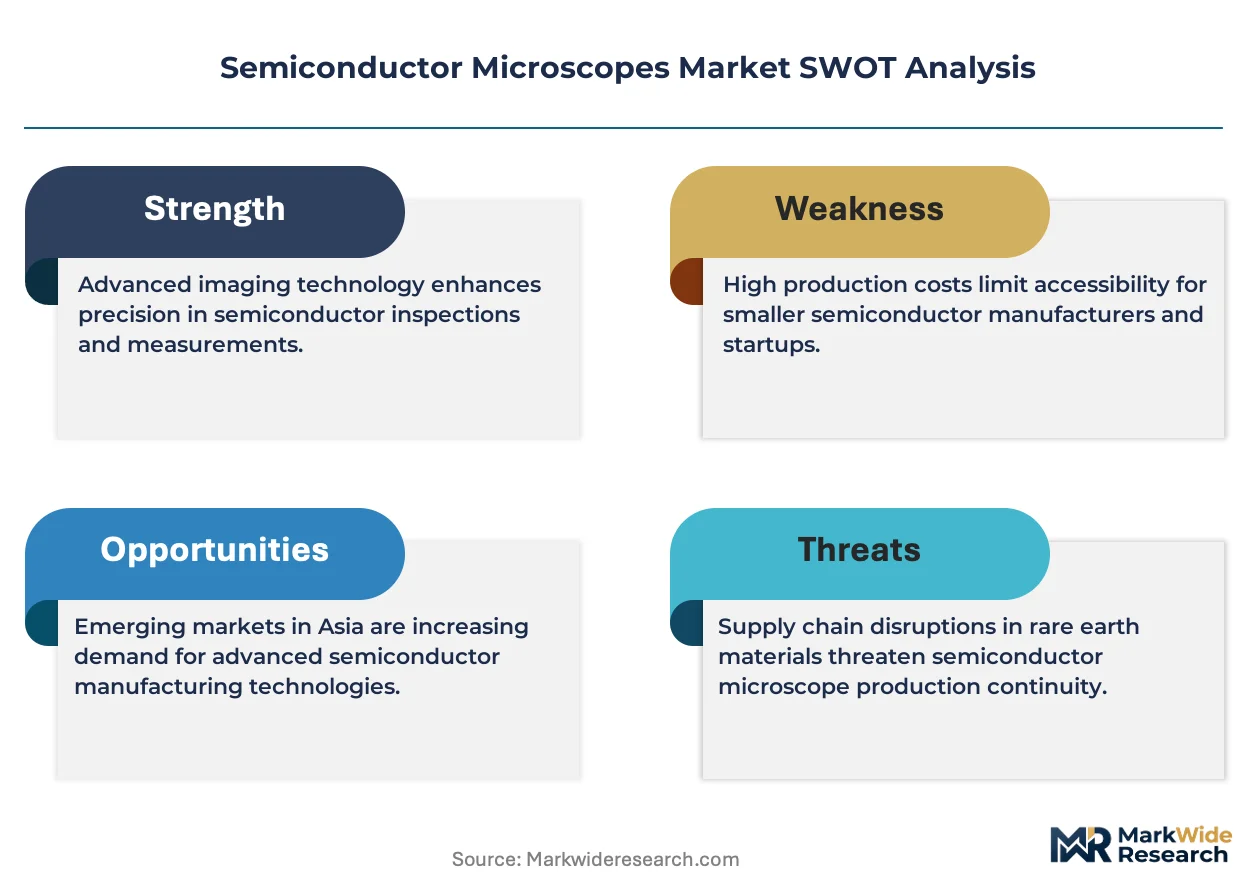
- Gate-All-Around Transition:Three-dimensional transistor geometries require atomic-scale sidewall roughness characterization, extending scanning probe microscopy penetration from R&D into production metrology.
Market Restraints
- Specialized Electron Optics Supply Concentration:Precision electromagnetic lens manufacturing concentrates in Jena and Tokyo, creating single-source vulnerability for microscope vendors outside these clusters.
- Helium Ion Source Scarcity:Gas field ionization sources for sub-nanometer imaging face feedstock constraints and export licensing friction, limiting helium ion microscope deployment timelines.
- REACH Compliance Cost Burden:ECHA substance restrictions on rare earth magnet coatings and electronic component materials add certification overhead to European-bound equipment, compressing vendor margins.
Strategic Opportunities
- India Semiconductor Mission Incentives:PLI scheme disbursements for domestic fab construction in Gujarat and Assam create first-mover advantage for microscopy vendors establishing local service infrastructure.
- AI-Accelerated Defect Classification:Automated image segmentation algorithms embedded in microscope platforms reduce human analyst bottlenecks, opening subscription-based software revenue streams.
- Backside Power Delivery Metrology:Buried power rail architectures require through-silicon via inspection at novel angles, expanding addressable equipment spend per wafer start.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:Semiconductor microscopy operations require simultaneous expertise in solid-state physics, vacuum engineering, and machine learning pipelines, elongating hiring cycles.
- Multi-Modal Integration Complexity:Correlative workflows combining electron, ion, and probe microscopy demand data format standardization that remains incomplete across vendor ecosystems.
- CE Marking Timeline Compression:EU AI Act documentation requirements for automated classification algorithms extend product certification cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Microscopes Market |
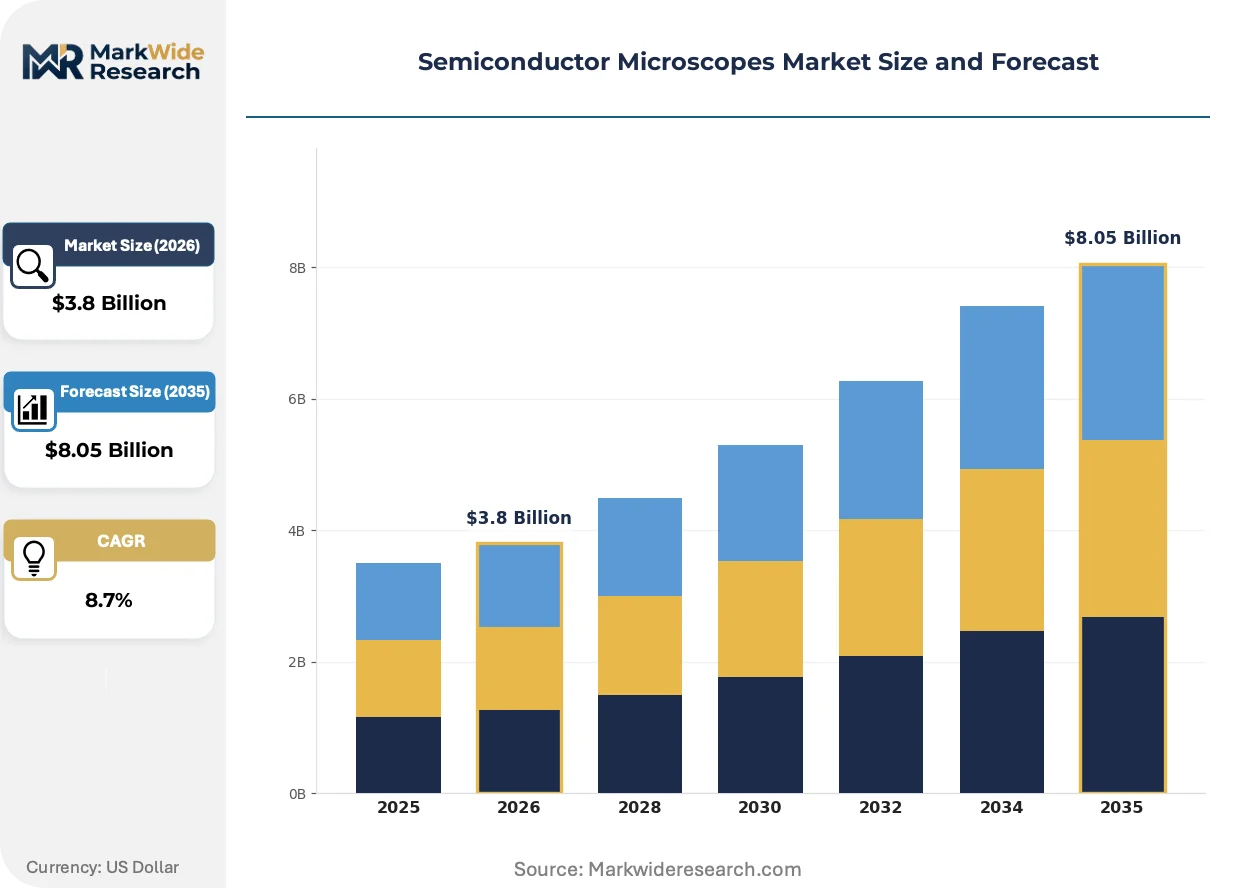
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electron Microscopes, Optical Microscopes, Scanning Probe Microscopes, Ion Beam Microscopes Technology: Transmission Electron Microscopy, Scanning Electron Microscopy, Atomic Force Microscopy, Scanning Tunneling Microscopy End User: Semiconductor Manufacturers, Research Institutions, University Labs, Quality Control Laboratories Application: Failure Analysis, Materials Characterization, Device Metrology, Microfabrication |
| Companies Covered | KLA Corporation, Applied Materials, ASML Holding, Hitachi High-Tech Corporation, JEOL Ltd, Thermo Fisher Scientific, Nikon Corporation, Zeiss Group, Leica Microsystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Microscopes Market Strategic Shifts
Instrumentation convergence and algorithmic automation are compressing the boundary between imaging and actionable process control, shifting microscope platforms from diagnostic tools to real-time yield management nodes.
Machine learning inference at the microscope edge is rewriting how quickly defect classification propagates back to lithography and etch tools. Memory manufacturers in Korea and Taiwan are deploying these capabilities at production scale, collapsing the feedback loop from hours to minutes and enabling wafer-level routing decisions without human analyst intervention.
REACH substance restrictions and RoHS recast directives are tightening material disclosure requirements for electron microscope components entering European fabs. Vendors must now document full supply chain provenance for magnetic alloys and ceramic insulators, with non-compliant shipments facing customs detention at Rotterdam and Hamburg terminals.
Memory and logic buyers are consolidating vendor relationships around platforms offering unified service contracts spanning multiple imaging modalities. This preference shift favors suppliers with captive refurbishment capabilities in Singapore and Arizona, where rapid ion source replacement and column alignment restore tool availability within forty-eight hours rather than the two-week industry average.
Semiconductor Microscopes Market Segmentation
Semiconductor microscopy procurement splits sharply between standardized platforms for high-volume production lines and heavily customized configurations for R&D and failure analysis workflows. Understanding these divides reveals where vendors can command premium pricing versus where cost competition dominates.
Product Type:
Standardization intensity varies dramatically across this category, with production-line tools requiring minimal configuration while analytical platforms demand extensive customization for specific failure modes.
- Electron Microscopes:These platforms deploy electron beams at one to thirty kilovolts to resolve transistor architectures and crystallographic defects at sub-nanometer scales. Foundries in Taiwan and Korea concentrate procurement here for yield-critical failure analysis, driven by node migration below three nanometers that compresses metrology tolerances.
- Optical Microscopes:Visible-light systems handle rapid wafer inspection at lower magnification where throughput trumps resolution. OSAT facilities in Malaysia and Vietnam favor these for packaging inspection, constrained by their inability to resolve features below the diffraction limit as interconnect pitches shrink.
- Scanning Probe Microscopes:Atomic force and scanning tunneling variants map surface topology at atomic resolution for three-dimensional NAND and gate-all-around characterization.
- Ion Beam Microscopes:Focused helium and gallium ion systems enable site-specific cross-sectioning and nanofabrication for detailed failure analysis.
Most installed capacity flows through Electron Microscopes. Expansion is steepest in Scanning Probe Microscopes as production metrology absorbs atomic-scale characterization previously confined to R&D.
Technology:
Cost tiering separates transmission architectures requiring million-dollar investments from scanning variants accessible to mid-scale research budgets.
- Transmission Electron Microscopy:TEM systems transmit electrons through ultra-thin specimens to resolve atomic lattice structures and interface defects. Leading-edge logic manufacturers in Taiwan deploy these for gate-all-around transistor validation, facing throughput constraints from complex sample preparation requirements.
- Scanning Electron Microscopy:SEM platforms raster electron beams across surfaces to generate topographical and compositional maps at nanometer resolution. Memory fabs in Korea and China standardize on these for routine defect inspection, benefiting from faster imaging cycles that match production line speeds.
- Atomic Force Microscopy:AFM probes physically scan surfaces to measure topography, roughness, and electrical properties at atomic scales.
- Scanning Tunneling Microscopy:STM systems exploit quantum tunneling currents to image conductive surfaces with sub-angstrom precision.
SEM platforms dominate current installed base. AFM is climbing the fastest as three-dimensional device architectures multiply surface characterization requirements.
End User:
Customer type determines service intensity, with commercial fabs demanding twenty-four-hour uptime guarantees while academic users prioritize flexibility over speed.
- Semiconductor Manufacturers:Integrated device manufacturers and foundries operate microscopy suites at production scale for inline process control and excursion response. Intel's Oregon and Arizona campuses maintain captive electron microscopy capacity, driven by internal metrology demands that exceed external service availability.
- Research Institutions:National laboratories and corporate R&D centers pursue pre-competitive characterization for node generations beyond current production. IMEC in Leuven and CEA-Leti in Grenoble concentrate advanced microscopy for European semiconductor research consortia, constrained by funding cycles that lag commercial procurement.
- University Labs:Academic facilities train specialists and explore novel imaging modalities with limited capital budgets.
- Quality Control Laboratories:Third-party testing houses provide failure analysis services to fabless designers and smaller manufacturers.
Semiconductor Manufacturers absorb the majority of high-end platform shipments. University Labs are gaining share fastest as workforce development initiatives expand microscopy training infrastructure.
Application:
Volume distribution favors diagnostic workflows over process development, though metrology applications are accelerating with multipatterning complexity.
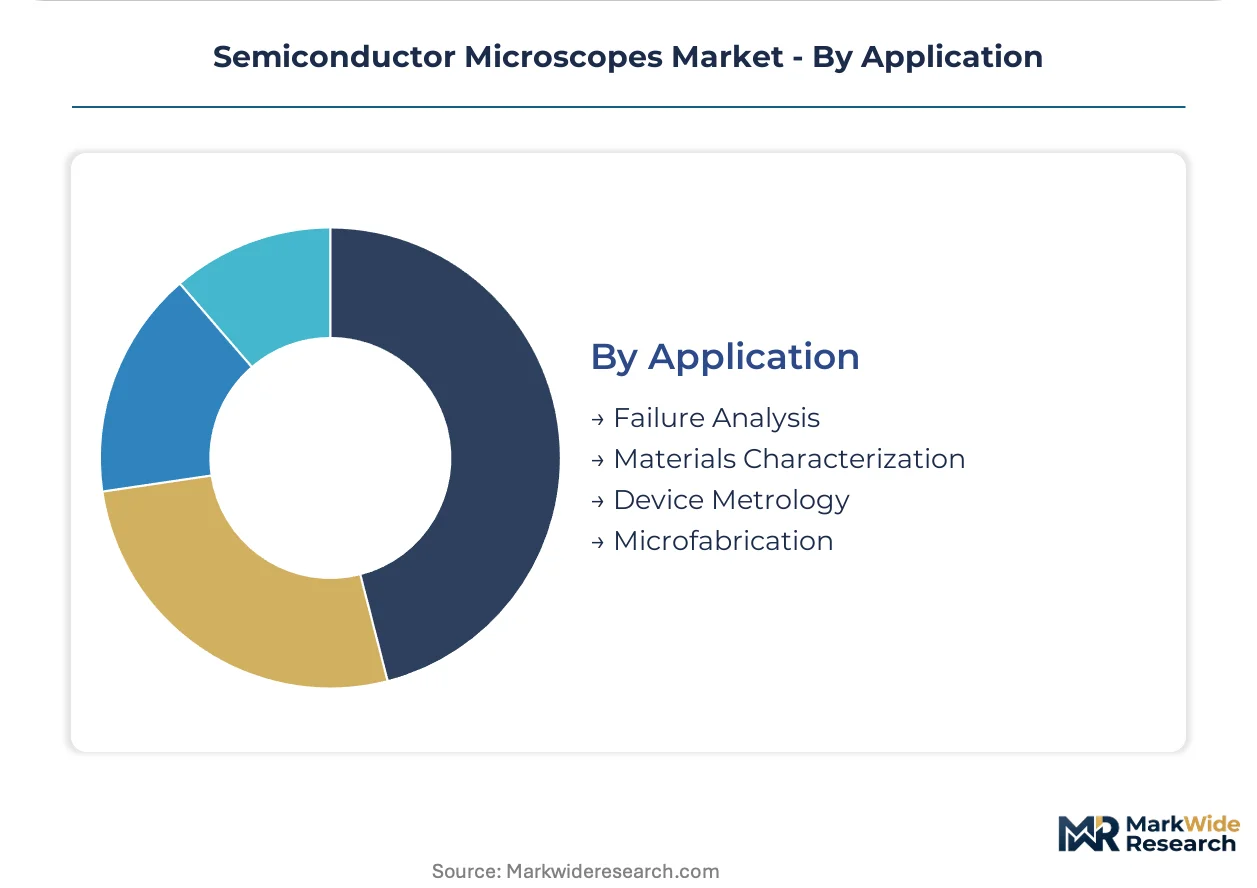
- Failure Analysis:Root-cause investigation of yield excursions and reliability failures consumes the largest microscopy capacity across commercial fabs. Samsung's Pyeongtaek and Taylor facilities dedicate electron microscopy floors to rapid defect turnaround, driven by the financial exposure of single-day production holds at advanced nodes.
- Device Metrology:Critical dimension measurement and overlay verification for process control now require multi-modal microscopy as optical methods reach resolution limits. TSMC's Nanjing and Kaohsiung plants deploy hybrid electron-probe systems, constrained by the algorithmic complexity of correlating measurements across platforms.
- Materials Characterization:Crystallographic and compositional analysis supports process development and supplier qualification.
- Microfabrication:Direct-write lithography and mask repair using focused ion beams serves prototyping and low-volume production.
Failure Analysis commands the deepest installed base. Device Metrology shows the steepest expansion trajectory as backside power delivery and gate-all-around architectures multiply measurement points per wafer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized electron optics engineers cluster in Jena and Tokyo, anchoring the supply base for precision electromagnetic lens manufacturing that underpins microscope production worldwide.
United States
Intel's captive electron microscopy capacity in Oregon and Arizona drives domestic demand for advanced failure analysis platforms. FDA oversight of semiconductor components destined for medical devices tightens traceability standards for US-bound equipment. The Pacific Northwest hosts concentrated service infrastructure supporting rapid ion source replacement and column alignment.
Germany
Zeiss Group's proprietary extreme ultraviolet optics expertise sustains premium positioning in European metrology procurement. ECHA substance restrictions on rare earth magnet coatings add certification overhead to equipment bound for Dresden and Leuven cleanroom buildouts. Jena remains the densest concentration of precision electromagnetic lens manufacturing outside Asia.
Japan
Hitachi High-Tech and JEOL anchor domestic electron microscope production serving memory fabs across Korea and Taiwan. METI's semiconductor revitalization framework channels public funding toward domestic microscopy R&D capacity. Tokyo-based precision component suppliers face helium ion source feedstock constraints that limit sub-nanometer imaging deployment timelines.
South Korea
Samsung's Pyeongtaek and Taylor facilities dedicate electron microscopy floors to rapid defect turnaround for gate-all-around transistor validation. The K-Semiconductor Belt strategy directs capital toward expanding domestic characterization infrastructure. Busan-Ulsan clusters concentrate scanning probe microscopy adoption for three-dimensional NAND production metrology.
Taiwan
TSMC's Nanjing and Kaohsiung plants deploy hybrid electron-probe systems for backside power delivery metrology at advanced nodes. The island maintains the densest concentration of installed electron microscopy capacity for semiconductor failure analysis globally. Hsinchu Science Park anchors correlative microscopy workflows combining multiple imaging modalities.
Semiconductor Microscopes Market Competitive Environment
The competitive structure tilts toward technology-integrated conglomerates with captive process control suites. Three tiers separate premium metrology specialists from mid-scale analytical platform vendors and regional service providers. Dominant competitive moves include strategic partnerships for multi-modal workflow integration and geographic expansion through localized refurbishment capabilities.
Within the premium-tier vector, KLA Corporation and Applied Materials exemplify the integrated-process-control archetype, while Zeiss Group occupies a position representing specialized optics expertise. These three anchors demonstrate how vendor consolidation around unified service contracts favors suppliers with captive refurbishment capabilities in Singapore and Arizona.
| Leading Market Players |
|---|
| KLA Corporation |
| Applied Materials |
| ASML Holding |
| Hitachi High-Tech Corporation |
| JEOL Ltd |
| Thermo Fisher Scientific |
| Nikon Corporation |
| Zeiss Group |
| Leica Microsystems |
| Others |
Value Chain & Pricing Dynamics
Multi-year service contracts from foundries in Taiwan and Korea are forcing microscope vendors to absorb upfront certification costs for EU REACH compliance, compressing margins on European-bound equipment while elevating total cost of ownership for buyers lacking captive refurbishment infrastructure.
Pricing Analysis
Bundled service contracts covering ion source replacement and column alignment command premium positioning against unbundled equipment-only transactions. Three-tier pricing structure across premium, standard, and economy levels separates vendors with Singapore refurbishment hubs from regional service providers. Cost compression in the standard tier is intensifying because ECHA substance documentation requirements add four to six months to certification cycles. OSAT facilities in Malaysia and Vietnam exhibit highest price sensitivity; Intel's captive microscopy suites in Oregon and Arizona demonstrate lowest.
Supply Chain Analysis
Precision electromagnetic lens engineers cluster in Jena and Tokyo, creating workforce bottlenecks that constrain column manufacturing capacity for vendors outside these clusters. Supply draws from Germany, Japan, and the United States for electron optics, with helium gas field ionization sources and rare earth magnet coatings as critical dependencies. Single-source vulnerability in Jena-based lens production exposes vendors to export licensing friction. Distribution runs through direct sales teams for foundry customers and regional distributors for academic and quality control laboratory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU AI Act documentation requirements for automated defect classification systems extend product certification timelines and deepen vendor moats.
For Market Incumbents: Acquire captive refurbishment capabilities in Singapore and Arizona to compress service response from two weeks to forty-eight hours. Deepen backward integration into precision electromagnetic lens manufacturing to reduce Jena and Tokyo dependency. Counter emerging entrants from China's domestic equipment push by pre-empting K-Semiconductor Belt qualification pathways. For New Entrants and Emerging Players: University labs expanding microscopy training infrastructure under workforce development initiatives represent the most penetrable buyer archetype with limited incumbent service entanglement. Target India's Gujarat and Assam fab clusters where PLI scheme disbursements are accelerating first-mover infrastructure buildouts. Lead with AI-accelerated defect classification software subscriptions to bypass capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale analytical platform vendors possessing multi-modal workflow integration capabilities and European CE marking completion. Five-to-ten year viability hinges on correlative microscopy data format standardization leadership. Watch helium ion source feedstock constraint resolution as inflection indicator for sub-nanometer imaging deployment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Modal Platform Integration | Correlative workflows combining electron, ion, and probe microscopy unify service contracts for memory and logic buyers. |
| AI-Accelerated Defect Classification | Edge inference algorithms at TSMC's Nanjing and Kaohsiung plants collapse feedback loops from hours to minutes. |
| Localized Refurbishment Hub Expansion | Singapore and Arizona facilities restore tool availability within forty-eight hours versus industry-standard two-week timelines. |
| REACH Compliance Certification Pre-Investment | Early ECHA substance documentation completion captures Dresden and Leuven cleanroom buildout procurement windows. |
| Helium Ion Source Supply Securement | Gas field ionization feedstock agreements with Tokyo-based suppliers bypass export licensing bottlenecks for sub-nanometer platforms. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with fab metrology directors, electron optics engineers, vacuum system specialists, and aftermarket service heads alongside secondary validation from SEC filings, ECHA substance restriction databases, and national semiconductor revitalization framework disclosures. Bottom-up wafer start projections and top-down equipment spend ratios were triangulated against vendor shipment records.
Granularity-level modeling disaggregated revenue across product type, technology architecture, end-user category, and application workflow, with additional dimensioning by regional fab construction pipeline status. CAGRs were derived from fitted growth curves applied to node migration timelines and packaging technology transition assumptions. Forecast inputs incorporated EU Chips Act capital disbursement schedules and gate-all-around transistor characterization requirements.
Inputs from foundry capital expenditure announcements and national laboratory procurement records were available through the study window; gaps in confidential vendor pricing data introduce uncertainty bands around premium-tier market share estimates. Forecasts reflect documented assumptions regarding node migration velocity and helium source supply normalization. Material deviation in EU AI Act implementation timelines or Jena lens manufacturing capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Medical X-Ray Detectors Market
Imaging
Global 4K Camera Market
Imaging
Facial Recognition Machine Market
Imaging
Machine Vision System and Services Market
Imaging
Vision Processing Unit Market
Imaging
Ingaas Image Sensor Market
Imaging
Digital Movie Cameras Market
Imaging
Photography Ring Flash Market
Imaging
Europe Thermal Imaging Systems Market
Imaging
Image Intensifier Market
Imaging
Hybrid Imaging Systems Market
Imaging
Event Camera Market
Imaging
AI-Based Fever Detection Camera Market
Imaging
Weatherproof Camera Market
Imaging
Global Ingaas Camera Market
Imaging
Global Image Sensors Market