
 Digital Image Processing Market | 2026-2036
Digital Image Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Image Processing Market Analytics
GPU foundry capacity in Taiwan and South Korea is shifting toward inference-optimized architectures for real-time image analysis workloads. NVIDIA Corporation leverages its CUDA ecosystem to dominate datacenter training deployments for computer vision models. Intel Corporation competes through OpenVINO toolkit integration with embedded vision systems at the edge. Sony Corporation anchors high-end sensor supply for medical and defense imaging platforms with proprietary backside-illuminated CMOS designs.
Digital image processing encompasses algorithms and hardware systems that acquire, enhance, analyze, and reconstruct visual data through mathematical operations on pixel arrays, typically handling 8-bit to 16-bit depth per channel at frame rates exceeding 60 fps for industrial applications. Its primary purpose spans diagnostic assistance in healthcare, automated defect detection in manufacturing, and situational awareness in defense and surveillance systems. Medical imaging applications command premium pricing due to regulatory validation burdens and diagnostic liability requirements. Cloud-based deployment is expanding fastest among mid-sized manufacturers seeking scalable machine vision without capital-intensive on-premises infrastructure. Embedded systems sustain margin pools in automotive and drone applications where latency constraints prohibit cloud round-trips.
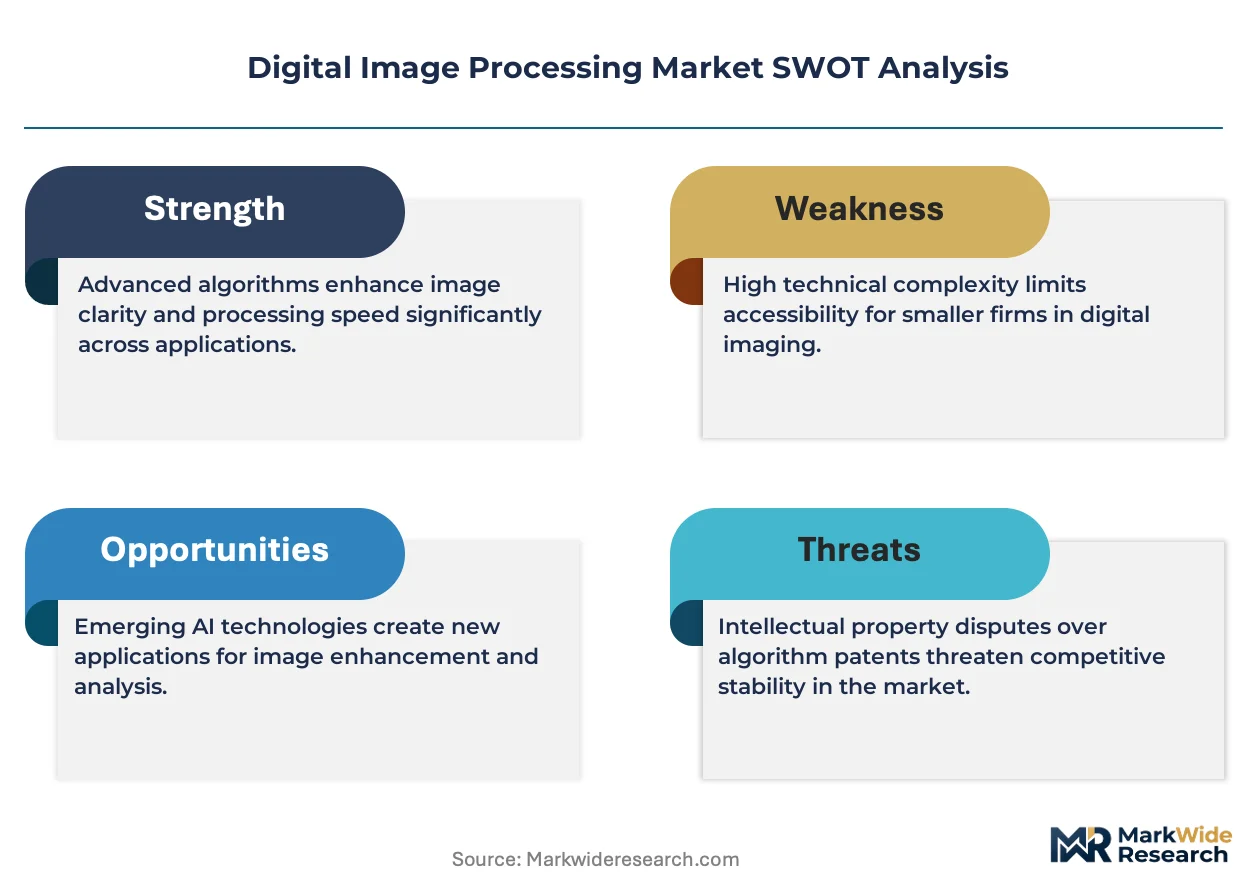
FDA software-as-medical-device guidelines and the EU AI Act impose pre-market algorithm validation requirements that lengthen product development cycles for clinical imaging vendors. ISO 13485 quality management standards and IEC 62304 medical device software frameworks shape supplier qualification criteria across European and North American procurement channels. Stakeholders must monitor divergence between FDA's risk-based classification approach and the EU's conformity assessment procedures for AI-enabled diagnostic tools.
Market Dynamics
GPU wafer allocation toward inference-optimized architectures is compressing development timelines for real-time medical and industrial vision systems, while algorithm validation burdens under the EU AI Act and FDA software-as-medical-device frameworks lengthen commercialization cycles for clinical deployment.
Growth Catalysts
- Smart manufacturing zones in China:Machine vision inspection systems replace manual quality control lines across automotive and electronics assembly plants, driving hardware refresh cycles.
- FDA software-as-medical-device framework:Clarified validation pathways reduce regulatory uncertainty for algorithm developers, accelerating clinical imaging product submissions.
- Backside-illuminated CMOS sensor advances:Proprietary designs from Japanese and Korean suppliers enable low-light diagnostic imaging with reduced noise floors.
Market Restraints
- GPU foundry concentration:Taiwan and South Korea fabrication facilities control advanced node capacity for vision processing silicon, creating single-source vulnerability.
- Algorithm validation costs:IEC 62304 medical device software compliance requires extensive documentation and testing, elevating development overhead for clinical applications.
- Cloud latency constraints:Industrial inspection and autonomous vehicle applications cannot tolerate round-trip delays, limiting cloud-based deployment options.
Strategic Opportunities
- EU AI Act compliance services:Conformity assessment procedures for AI-enabled diagnostic tools create adjacent revenue streams for validation consultancies.
- Edge inference hardware:Embedded vision systems in drones and agricultural machinery demand low-power accelerators with sub-50ms processing latency.
- ISO 13485 certification gaps:Mid-sized manufacturers in India and Southeast Asia lack quality management infrastructure, opening supplier qualification advisory markets.
Industry Challenges
- Cross-functional talent scarcity:Computer vision engineering requires simultaneous expertise in signal processing, regulatory affairs, and domain-specific clinical or manufacturing knowledge.
- Legacy system integration:Hospital radiology departments and automotive assembly lines operate decades-old hardware with proprietary interfaces, complicating retrofit deployments.
- Patent thickets around convolutional architectures:Licensing complexity for fundamental neural network operations elevates legal risk for algorithm developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Image Processing Market |
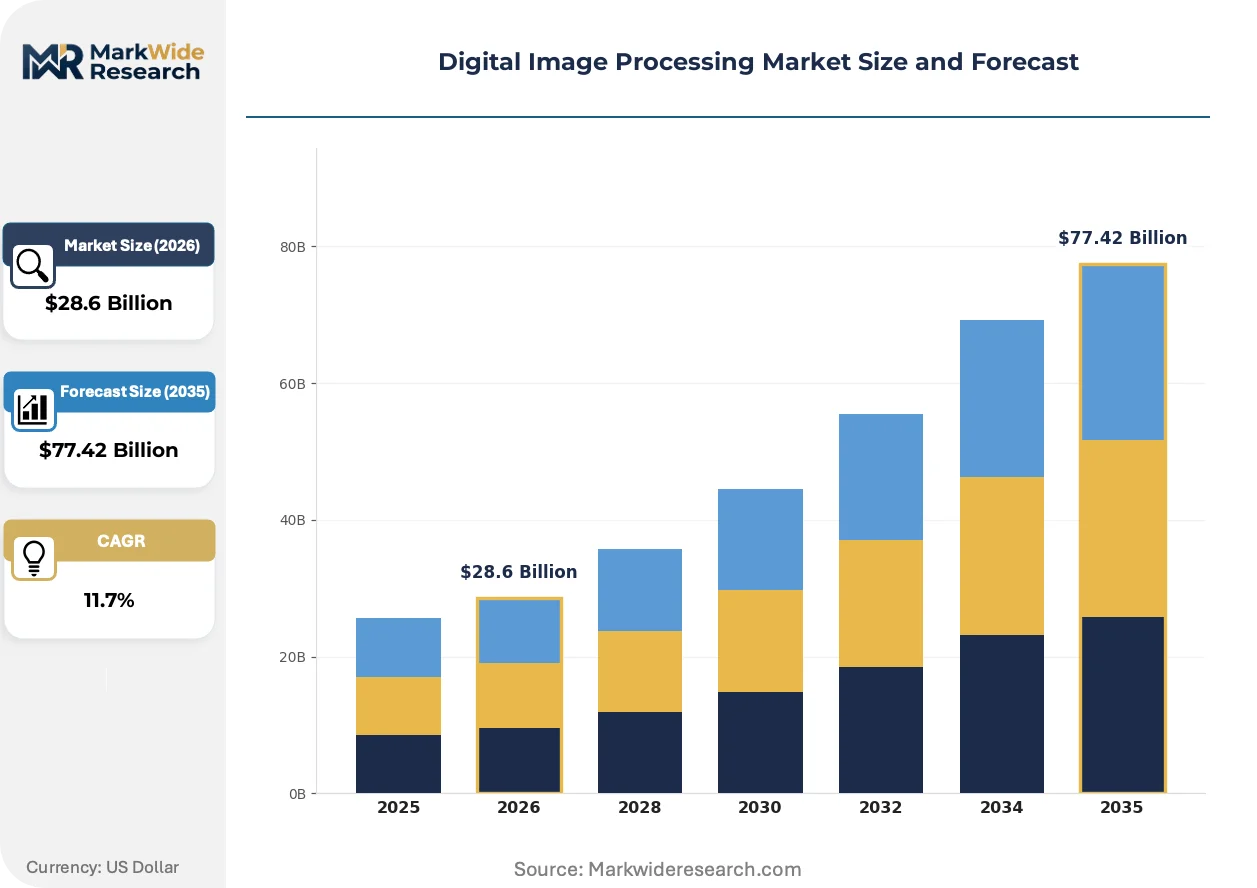
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $77.42 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Medical Imaging, Remote Sensing, Video Surveillance, Image Classification Technology: Machine Learning, Computer Vision, Neural Networks, Image Segmentation End User: Healthcare, Defense, Manufacturing, Entertainment Deployment: On-Premises, Cloud-Based, Hybrid, Embedded Systems |
| Companies Covered | NVIDIA Corporation, Microsoft Corporation, Canon Inc., Samsung Electronics, Cognex Corporation, Intel Corporation, Sony Corporation, Panasonic Corporation, Teledyne Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Image Processing Market Evolving Landscape
Processing architectures are migrating from datacenter training clusters toward distributed edge nodes, while regulatory frameworks harden validation requirements for autonomous decision systems in safety-critical applications.
Event-based vision sensors are absorbing temporal redundancy from conventional frame-based acquisition. Automotive tier-1 suppliers and drone manufacturers adopt silicon retinas for sub-millisecond motion detection. The technology is absorbing market share from high-speed CMOS arrays in collision avoidance and industrial monitoring segments.
EU AI Act risk classification tiers are mandating conformity assessments for diagnostic algorithms before clinical deployment. Medical device manufacturers must document training data provenance and performance across demographic subgroups. European imaging vendors are restructuring product development cycles to accommodate notified body review timelines.
Subscription-based machine vision platforms are displacing perpetual license models among mid-sized manufacturers. Cloud-native inspection tools allow quality teams to scale compute resources seasonally without capital expenditure. This shift concentrates most visibly in North American contract electronics manufacturers serving volatile consumer hardware demand.
Digital Image Processing Market Segmentation
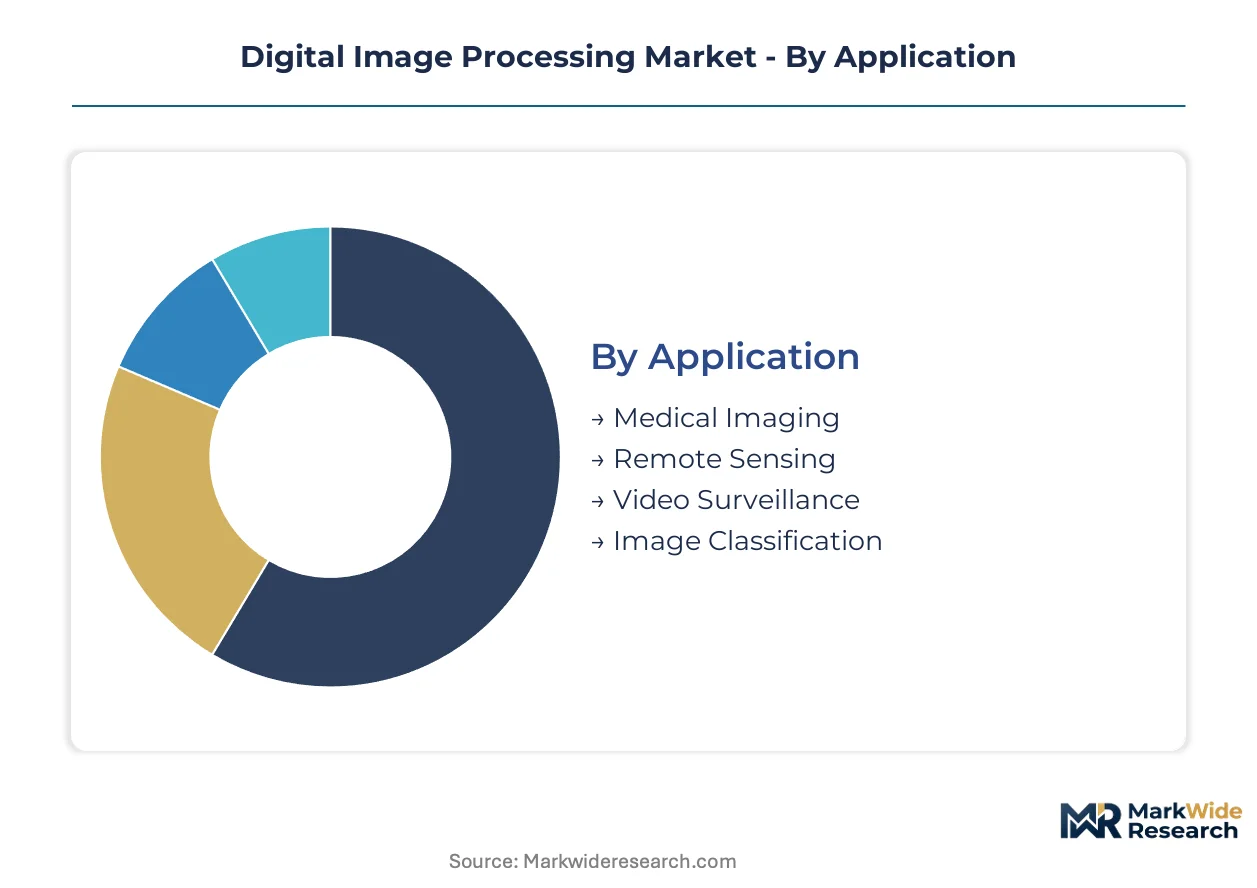
Digital image processing markets fragment across four critical dimensions that determine procurement patterns and margin structures. Application requirements dictate hardware specifications, while deployment architecture choices reflect latency tolerance and capital availability. Technology selection separates inference-optimized from training-heavy workloads.
Application:
Medical imaging commands premium pricing due to diagnostic liability and regulatory validation burdens, while remote sensing and surveillance compete on volume throughput.
- Medical Imaging:Diagnostic radiology and pathology workflows demand 16-bit depth processing at sub-100ms latency for real-time surgical guidance. FDA software-as-medical-device frameworks and EU AI Act conformity assessments lengthen development cycles but sustain pricing power in North American and European hospital procurement channels.
- Remote Sensing:Satellite and aerial imagery analysis processes multispectral data arrays for agricultural monitoring and mineral exploration. China's smart manufacturing zones and Australian mining operations drive hardware refresh cycles for high-resolution terrain mapping systems.
- Video Surveillance:Urban security networks and critical infrastructure protection require 24/7 operational reliability with edge preprocessing to reduce bandwidth costs.
- Image Classification:Automated sorting and content tagging applications prioritize throughput volume over pixel-level precision in logistics and media archiving sectors.
Today's leader: Medical Imaging. Tomorrow's challenger: Remote Sensing.
Technology:
Computer vision and neural networks absorb the majority of R&D investment, with machine learning toolkits lowering entry barriers for mid-sized developers.
- Machine Learning:Supervised and unsupervised training pipelines enable pattern recognition across manufacturing defect detection and agricultural yield forecasting. TensorFlow and PyTorch ecosystems dominate cloud-based development environments, though embedded deployment requires quantization-aware training for ARM-based edge accelerators.
- Computer Vision:Traditional feature extraction and geometric analysis algorithms persist in automotive ADAS and industrial metrology where interpretability requirements exceed neural network black-box tolerance. OpenCV integration with real-time operating systems sustains deployment in legacy manufacturing lines.
- Neural Networks:Convolutional and transformer architectures achieve state-of-the-art accuracy in diagnostic imaging but demand GPU clusters for training.
- Image Segmentation:Instance and semantic partitioning algorithms separate foreground objects from background clutter in robotic manipulation and satellite imagery analysis.
Neural networks capture development mindshare. Computer vision retains deployment share where explainability governs procurement.
End User:
Healthcare and defense procurement channels prioritize validation documentation over unit cost, while manufacturing and entertainment segments optimize for capital efficiency.
- Healthcare:Hospital radiology departments and diagnostic imaging centers require IEC 62304-compliant software documentation and ISO 13485-certified quality management systems. PMDA in Japan and Health Canada impose parallel validation requirements that extend commercialization timelines but protect incumbent positions.
- Defense:Military imaging platforms demand hardened electronics with radiation tolerance and anti-tamper specifications for satellite and unmanned vehicle payloads. ITAR and EAR export controls fragment supplier bases across NATO and allied procurement channels.
- Manufacturing:Automotive and electronics assembly plants replace manual inspection with machine vision systems to achieve six-sigma quality targets.
- Entertainment:Streaming platforms and game studios leverage real-time rendering and facial capture for content production pipelines.
Healthcare anchors revenue per unit. Manufacturing scales unit volume.
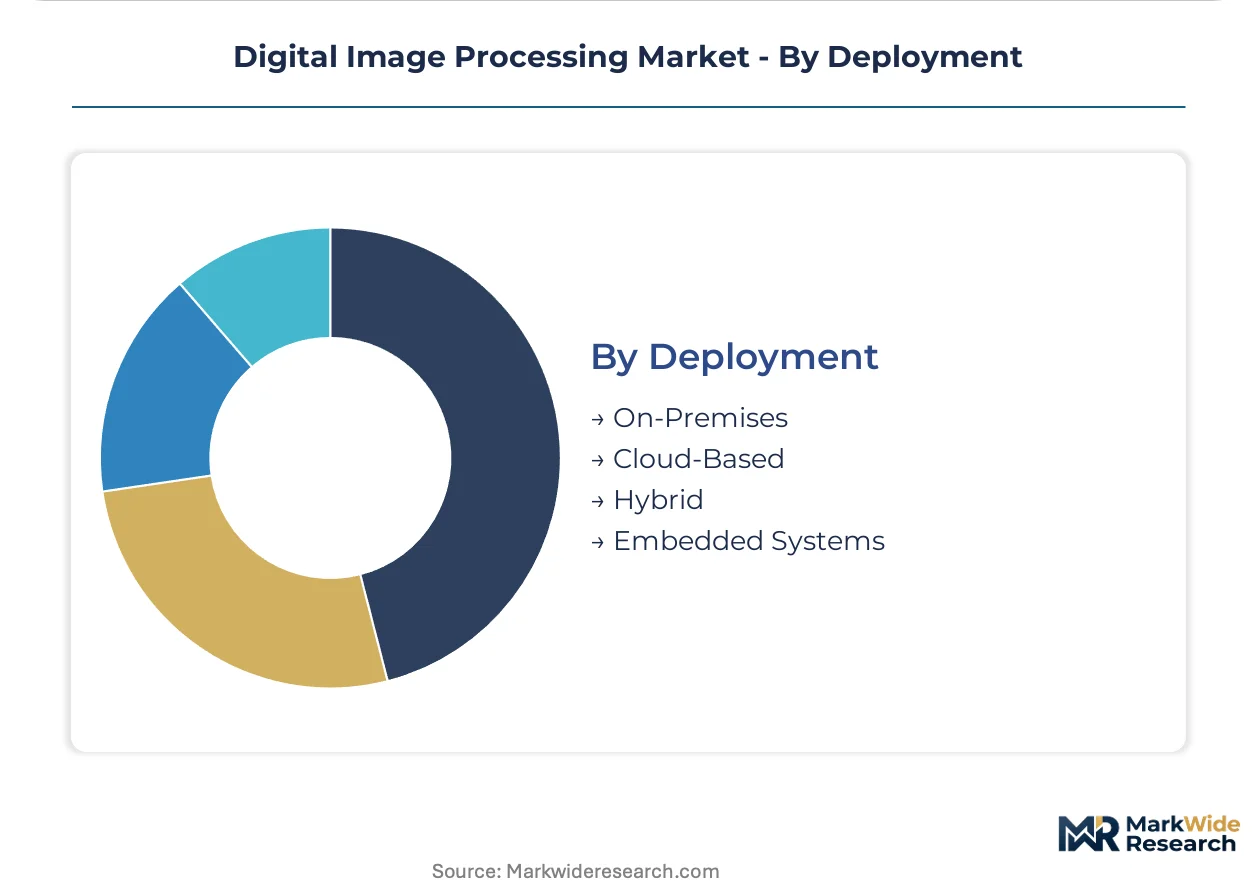
Deployment:
Cloud-based platforms gain traction among mid-sized manufacturers seeking scalable inspection capacity without datacenter investment, though latency constraints preserve embedded system demand.
- On-Premises:Enterprise datacenter deployments retain sensitive medical and defense imaging workloads within organizational security perimeters. HIPAA-covered entities in the US and GDPR-regulated European healthcare providers mandate local data residency for patient diagnostic records.
- Cloud-Based:Subscription machine vision platforms allow contract electronics manufacturers to scale compute resources seasonally. AWS, Azure, and Google Cloud compete for North American manufacturing workloads with pre-trained model marketplaces.
- Hybrid:Edge preprocessing with cloud aggregation balances latency requirements against storage economics in distributed retail and logistics networks.
- Embedded Systems:Low-power accelerators in drones and agricultural machinery enforce sub-50ms inference latency without network connectivity.
Embedded systems defend margin pools. Cloud deployment climbs fastest among capital-constrained entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting algorithm development toward jurisdictions with streamlined validation pathways. Foundry capacity constraints in Taiwan and South Korea are forcing imaging hardware vendors to diversify procurement across Southeast Asian assembly nodes.
United States
FDA software-as-medical-device frameworks clarify validation pathways for clinical imaging algorithms, reducing regulatory uncertainty for developers. HIPAA-covered entities mandate local data residency for patient diagnostic records, preserving on-premises deployment share. Hospital procurement in the Greater Boston and San Francisco Bay Area corridors favors IEC 62304-compliant vendors with established quality management systems.
China
Smart manufacturing zones in Guangdong and Jiangsu provinces replace manual quality control with machine vision inspection at automotive and electronics assembly plants. MIIT industrial upgrading programs subsidize domestic vision system adoption. Yangtze River Delta fabrication clusters expand GPU wafer starts to serve medical imaging equipment manufacturers targeting ASEAN export markets.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg deploy real-time defect detection for six-sigma quality targets in EV battery assembly. CE marking under EU AI Act risk classification tiers mandates conformity assessments for diagnostic algorithms before clinical deployment. Stuttgart and Munich industrial clusters anchor precision metrology supply chains for European machine vision procurement.
Japan
PMDA parallel validation requirements extend commercialization timelines but protect incumbent positions in diagnostic imaging. METI technology roadmaps prioritize low-power edge accelerators for agricultural and drone applications. Kanto and Kansai manufacturing belts sustain demand for backside-illuminated CMOS sensors in medical and defense imaging platforms.
South Korea
Semiconductor fabrication facilities expand GPU wafer starts to serve real-time medical and industrial vision systems. MFDS medical device software frameworks align with international IEC 62304 standards for regional market access. Seoul Capital Area and Busan-Ulsan electronics corridors concentrate machine vision R&D for automotive tier-1 suppliers.
Digital Image Processing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue edge inference specialization and regulatory compliance services. The vendor base stratifies across three tiers: GPU foundry-dependent hardware suppliers, sensor-integrated platform vendors, and algorithm-centric software providers. Dominant competitive moves include strategic partnerships for foundry capacity allocation and portfolio diversification into adjacent medical device validation services.
Within the GPU-accelerated tier, NVIDIA Corporation and Intel Corporation exemplify divergent ecosystem strategies. NVIDIA leverages its CUDA platform dominance for datacenter training deployments. Intel competes through toolkit integration with embedded vision systems. Sony Corporation anchors the sensor-integrated segment with proprietary CMOS designs for medical and defense imaging platforms.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Microsoft Corporation |
| Canon Inc. |
| Samsung Electronics |
| Cognex Corporation |
| Intel Corporation |
| Sony Corporation |
| Panasonic Corporation |
| Teledyne Technologies |
| Others |
Value Network & Pricing Analysis
FDA software-as-medical-device validation requirements and EU AI Act conformity assessments are forcing clinical imaging vendors to absorb extensive documentation and testing costs, compressing margins at the mid-tier while premium-tier suppliers pass compliance burdens through to hospital procurement channels.
Pricing Analysis
Distributor margins for machine vision hardware compress toward single digits as direct-to-OEM channels expand in automotive and electronics manufacturing. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated diagnostic algorithms from uncertified industrial inspection tools, with certification-grade software commanding multiples over unvalidated alternatives. Pricing pressure stems from GPU foundry concentration in Taiwan and South Korea, where wafer allocation bottlenecks elevate silicon input costs. Contract electronics manufacturers in North America exhibit highest price sensitivity, while hospital radiology departments prioritize validation documentation over unit cost.
Supply Chain Analysis
GPU wafer supply rests on fabrication facilities in Taiwan and South Korea, with advanced node capacity for vision processing silicon drawing from concentrated foundry networks. Backside-illuminated CMOS sensors, specialized photoresists, and inference-optimized accelerator chips constitute critical input dependencies. Single-source vulnerability around Taiwan Strait logistics elevates supply chain risk for medical imaging equipment manufacturers. Distribution runs through authorized distributors for defense and healthcare procurement channels, while industrial segments shift toward direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in algorithm validation services and edge inference hardware, where compliance cost absorption and low-latency premium pricing offset GPU foundry cost pressures.
For Market Incumbents: To counter emerging entrants in subscription-based machine vision platforms, incumbents should deepen backward integration into sensor-integrated platform design and secure captive foundry capacity allocation through multi-year wafer agreements. FDA and EU AI Act validation infrastructure investments create defensive moats against unqualified competitors. For New Entrants and Emerging Players: The price-point gap between premium FDA-validated diagnostic tools and uncertified industrial inspection systems creates white-space opportunity in mid-tier manufacturing segments lacking ISO 13485 infrastructure. Agricultural machinery vision and drone-based inspection represent most penetrable applications, with go-to-market traction through channel partnerships with existing embedded systems distributors. For Investors and Strategic Acquirers: Asymmetric upside sits with edge inference hardware specialists possessing sub-50ms latency architectures and established automotive tier-1 supplier relationships. Long-term viability favors acquisition targets with dual-use technology spanning medical and industrial validation pathways. GPU foundry capacity reallocation announcements serve as critical inflection indicators for hardware vendor margin trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment Investment | Notified body relationships accelerate clinical deployment timelines for European hospital procurement. |
| Edge Inference Hardware Development | Sub-50ms latency architectures capture drone and agricultural machinery premium pricing tiers. |
| Foundry Capacity Allocation Agreement | Multi-year wafer commitments insulate against Taiwan Strait logistics disruption risks. |
| ISO 13485 Certification Infrastructure Buildout | Quality management systems unlock hospital radiology department procurement channels. |
| Subscription Platform Migration | Cloud-native inspection tools scale with contract electronics manufacturer seasonal demand volatility. |
Research Methodology
Multiple input streams — primary interviews with biomedical engineers and GPO contracts managers, regulatory filings with FDA and notified bodies, GPU foundry capacity disclosures, and hospital procurement databases — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from SEC filings of vision system vendors, hyperscaler capex reports, and customs trade data for imaging equipment imports.
Historical shipment patterns were cross-referenced against panel input from machine vision R&D directors and automotive tier-1 supplier procurement leads across the analysis window. Segmentation modeling encompassed application type, deployment architecture, technology stack, and end-user industry, with CAGRs derived from weighted regression against foundry capacity expansion timelines and regulatory validation pipeline data. Edge inference latency benchmarks and cloud infrastructure spending trajectories informed hardware-software split projections.
Caveats apply where GPU foundry capacity reallocation, EU AI Act enforcement intensity, or FDA software-as-medical-device guidance revisions could materially shift the outlook. A small set of named triggers — Taiwan Strait logistics disruption, notified body backlog accumulation, and automotive EV battery assembly automation acceleration — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Handheld Imaging Devices Market
Imaging
Macroscopic Imaging Systems Market
Imaging
Middle East and Africa Hyperspectral Imaging Systems Market
Imaging
Camera Lens Market
Imaging
Pico Projector Market
Imaging
Brain Imaging and Neuroimaging Market
Imaging
Hyperspectral Imaging Market
Imaging
Machine Vision System Market
Imaging
Digital Camera Market
Imaging
Global Camera Module Market
Imaging
Biophotonics Market
Imaging
Virtual Reality Camera Market
Imaging
Frame Grabber Market
Imaging
Global Backscatter X-Ray Devices Market
Imaging
Ent Cameras Market
Imaging
Europe CT Market