
 Global Automotive Imaging Market | 2026-2036
Global Automotive Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Imaging Market Foresight
The gap between premium multi-camera architectures and commodity single-sensor modules is shifting from a feature distinction to a safety-mandated divide. Sony Group Corporation leverages its stacked CMOS expertise to dominate high-resolution front-view applications for Level 2+ autonomy. STMicroelectronics anchors the mid-tier with time-of-flight integration for cabin monitoring, while OmniVision Technologies, Inc. competes aggressively on cost in emerging-market rear-view replacements.
Automotive imaging encompasses solid-state and scanning sensor systems that capture, process, and interpret visual and spatial data for vehicle perception, typically operating across wavelength ranges from near-infrared through visible spectrum with resolution thresholds exceeding two megapixels for forward-facing safety functions. Camera-based segments now lead unit volume as automakers consolidate surround-view and ADAS feeds onto shared processing domains, while LiDAR occupies the fastest-expanding value pool as highway-speed autonomy programs demand centimeter-range precision at extended distances. HD cameras and driver monitoring cameras concentrate margin capture where regulatory compliance creates captive demand for DMS-equipped cabins.
NHTSA in the United States and Euro NCAP in Europe now mandate specific camera performance thresholds for pedestrian detection and driver attention monitoring, effectively gatekeeping market access for non-compliant suppliers. Japan's METI coordinates domestic standards alignment with UNECE regulations to preserve export competitiveness for its tier-1 imaging ecosystem. Stakeholders must monitor whether China's SAMR accelerates mandatory in-cabin imaging timelines beyond current voluntary guidelines, as this would reshape capacity allocation across sensor fabs and lens foundries.
Market Dynamics
Camera consolidation onto centralized compute domains is compressing supplier margins while elevating software-defined imaging stacks as the primary value capture layer.
Growth Catalysts
- Euro NCAP pedestrian detection mandates:Tier-1 suppliers in Germany and South Korea are scaling surround-view production to meet 2026 safety rating thresholds.
- Level 2+ autonomy proliferation:Highway-speed partial automation programs across Japan and the United States are pulling high-resolution front-view sensors into mid-tier vehicle segments.
- Silicon carbide packaging:Thermal management advances in power electronics are enabling denser image signal processor integration within engine-compartment camera modules.
Market Restraints
- Wafer allocation constraints:Automotive CMOS image sensors compete with smartphone and industrial vision for 300mm foundry capacity at TSMC and Samsung.
- Lens assembly labor intensity:Precision glass molding and active alignment processes concentrate in Japanese and German optics clusters with limited geographic diversification.
- Functional safety certification overhead:ISO 26262 ASIL-B through ASIL-D compliance adds 18-24 month qualification timelines for new sensor introductions.
Strategic Opportunities
- India domestic vehicle production:Local assembly growth under PLI scheme incentives creates captive demand for cost-optimized rear-view and surround-view modules.
- In-cabin wellness monitoring:Vital sign detection through near-infrared imaging opens incremental sensor slots beyond regulatory-minimum driver monitoring.
- LiDAR-camera fusion architectures:Solid-state scanning systems and high-dynamic-range imagers are converging on shared perception pipelines for urban autonomy.
Industry Challenges
- Embedded vision software talent scarcity:Algorithm optimization for neural network inference on edge devices outpaces university pipeline output in Germany, Japan, and the United States.
- Legacy vehicle electrical architecture integration:CAN-FD and Ethernet-AVB protocol mismatches complicate retrofit of advanced imaging systems into existing nameplates.
- Patent thicket navigation:CMOS pixel design, lens actuator mechanisms, and HDR processing techniques overlap across Sony, Samsung, and OmniVision portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Imaging Market |
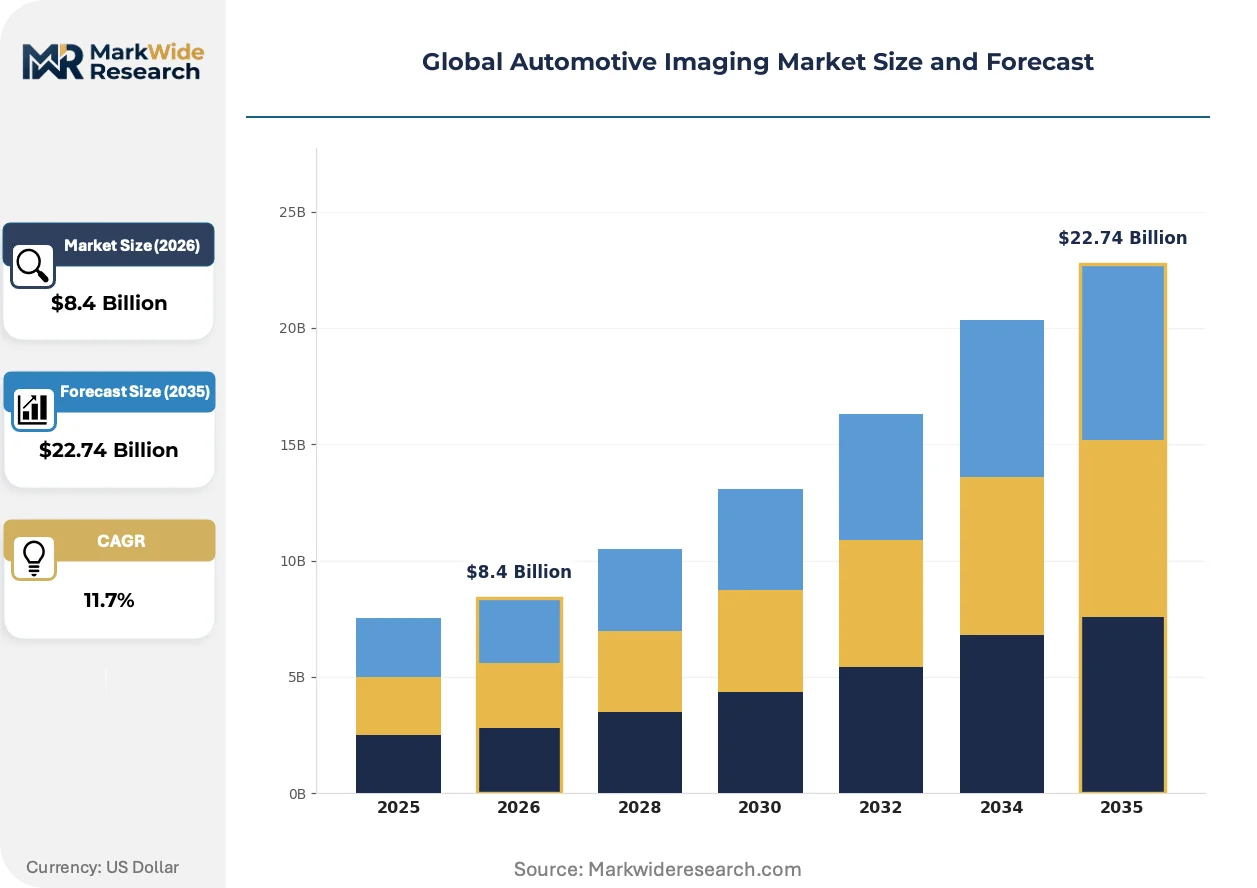
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LiDAR, Radar, Ultrasonic, Camera, Inertial Measurement Unit, Infrared Application: Advanced Driver Assistance Systems, Parking Assistance, Navigation Mapping, Collision Avoidance, Blind Spot Detection, Night Vision Product Type: Front View Cameras, Rear View Cameras, Surround View Systems, Driver Monitoring Cameras, Gesture Recognition Cameras, HD Cameras End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Samsung Electronics Co., Ltd., STMicroelectronics, Sony Group Corporation, Infineon Technologies AG, DENSO Corporation, ON Semiconductor Corporation, Continental AG, NXP Semiconductors N.V., OmniVision Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Imaging Market Shifts & Advancements
Software-defined perception stacks are decoupling hardware refresh cycles from vehicle platform lifespans, compressing traditional tier-1 supplier control points.
Time-of-flight sensors for cabin occupancy detection are modularizing across shared domain controller architectures. Tier-1 integrators in South Korea and Germany are consolidating discrete DMS and OMS functions onto unified processing substrates. This compression eliminates redundant image signal processors and accelerates over-the-air feature activation timelines.
NHTSA updated FMVSS 127 pedestrian automatic emergency braking requirements are mandating specific low-light detection performance thresholds. United States market access now depends on sensor qualification against standardized nighttime test scenarios. Front-view camera suppliers are prioritizing high-sensitivity pixel designs and supplemental near-infrared illumination to secure platform wins with Detroit-based OEMs.
Fleet operators in the United States and Germany are unbundling imaging hardware from software service contracts. Commercial vehicle buyers now procure camera modules separately from perception software subscriptions. This disaggregation pressures traditional tier-1 bundled pricing and opens direct procurement channels between OEMs and semiconductor vendors.
Global Automotive Imaging Market Segmentation
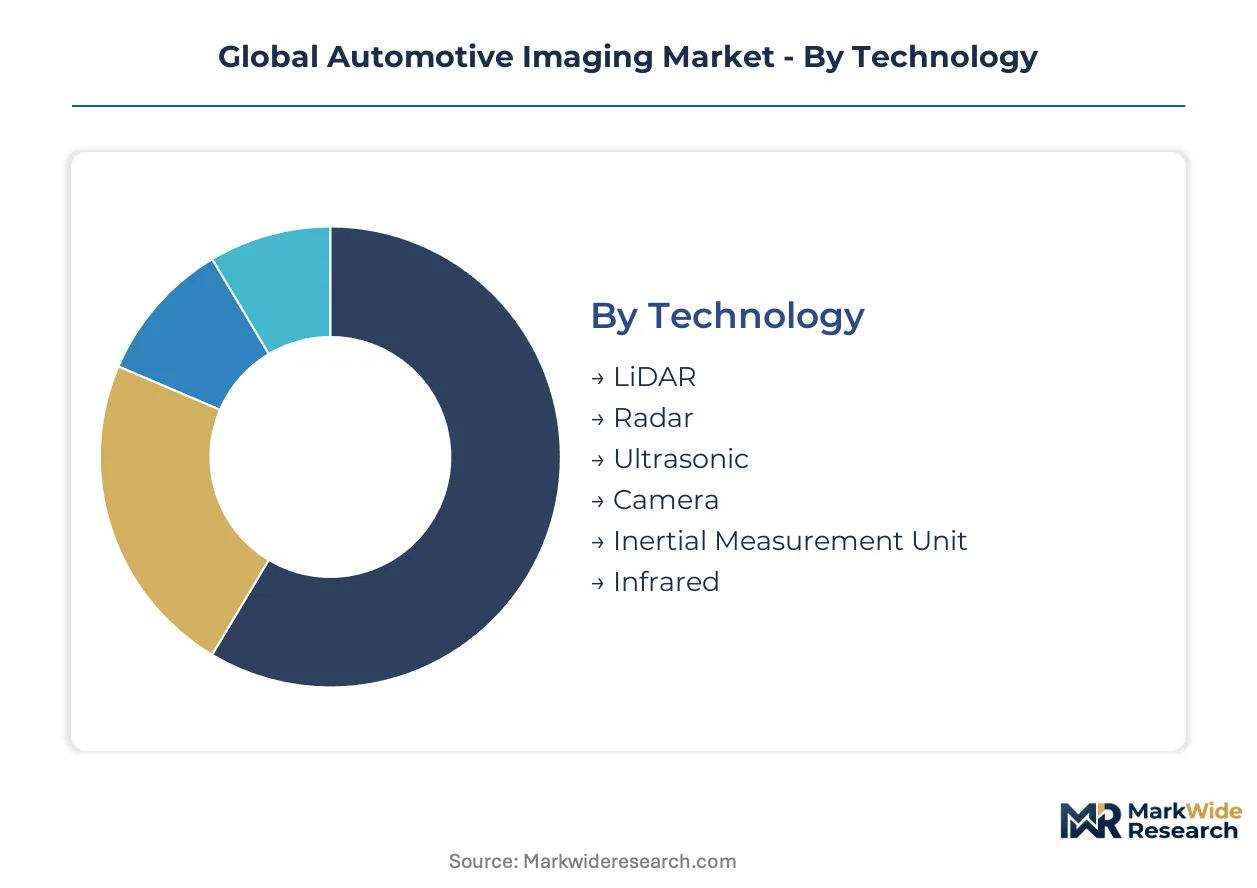
Imaging modality selection determines thermal budgets, processing loads, and software architecture across vehicle platforms. Segmentation clarity helps suppliers align R&D pipelines with regulatory-mandated performance tiers and OEM consolidation strategies.
Technology:
Resolution, range precision, and weather tolerance differentiate sensing modalities for distinct safety functions.
- LiDAR:Solid-state and scanning architectures emit pulsed laser light to construct centimeter-accurate 3D point clouds at highway distances. Highway-speed autonomy programs in the United States and Germany are pulling MEMS-based and flash LiDAR into series production for urban robotaxi fleets.
- Camera:CMOS image sensors capture visible and near-infrared wavelengths for lane keeping, traffic sign recognition, and pedestrian detection. Euro NCAP pedestrian detection mandates are forcing 2-megapixel minimum resolution upgrades across German and South Korean tier-1 supply chains.
- Radar:77 GHz and 79 GHz frequency-modulated continuous-wave systems penetrate fog and precipitation for adaptive cruise control. Cost-optimized corner radar modules are proliferating in mid-tier vehicle segments from Indian and Brazilian assembly plants.
- Ultrasonic:Piezoelectric transducers emit high-frequency acoustic pulses for sub-10-meter proximity detection. Parking assistance functions in compact urban vehicles across Japan and Italy rely on ultrasonic arrays for low-speed maneuvering.
- Infrared:Thermal imagers detect long-wave radiation from pedestrians and animals beyond headlight illumination range. Night vision options in premium German nameplates use germanium lens assemblies with limited supplier diversification.
- Inertial Measurement Unit:Accelerometer and gyroscope fusion enables dead reckoning when GPS signals degrade. Tunnel navigation and urban canyon positioning in Chinese and Swiss metropolitan markets drive IMU integration with camera odometry.
Mature deployment sits with ultrasonic and radar modules. Newer deployment is concentrated in solid-state LiDAR and high-dynamic-range camera stacks.
Application:
Functional safety integrity levels and neural network training data requirements vary sharply across use cases.
- Advanced Driver Assistance Systems:Forward-facing camera and radar fusion enables lane centering, adaptive cruise control, and emergency braking. NHTSA FMVSS 127 pedestrian automatic emergency braking rules are mandating specific nighttime detection thresholds for US market access.
- Collision Avoidance:Cross-traffic alert and intersection assistance combine corner radar with surround-view camera feeds. Japanese OEMs are integrating collision avoidance stacks with vehicle-to-infrastructure communication in Tokyo and Osaka deployment zones.
- Driver Monitoring Systems:Near-infrared cameras track gaze direction, eyelid closure, and head pose for drowsiness detection. Euro NCAP safety rating protocols now penalize vehicles lacking DMS-equipped cabins.
- Parking Assistance:Ultrasonic and camera fusion enables automated perpendicular and parallel parking maneuvers. Cost-optimized rear-view camera modules from Indian tier-1 suppliers are penetrating domestic vehicle assembly under PLI scheme incentives.
- Blind Spot Detection:Short-range radar and camera monitoring cover lateral zones outside mirror visibility. German commercial vehicle mandates require blind spot detection for urban delivery trucks in Berlin and Munich metropolitan areas.
- Navigation Mapping:Camera-based simultaneous localization and mapping generates high-definition road network data. Chinese autonomous driving developers are deploying mapping fleets across Shenzhen and Shanghai to refresh cloud-based navigation layers.
Regulatory pressure concentrates investment in ADAS and DMS functions. Fleet operators are expanding navigation mapping and parking assistance as software-subscription revenue streams.
Product Type:
Optical specification and mechanical packaging determine thermal management requirements and lens supply chain sourcing.
- Surround View Systems:Four-camera arrays stitched into seamless 360-degree bird's-eye visualization require sub-pixel calibration and shared domain controller processing. German luxury OEMs are mandating surround view as standard equipment across all nameplates.
- HD Cameras:8-megapixel and higher resolution front-view sensors with 120 dB dynamic range capture lane markings against direct solar glare. Japanese tier-1 integrators are qualifying HDR imagers against METI-aligned UNECE performance standards.
- Driver Monitoring Cameras:Near-infrared global shutter sensors with 940 nanometer illumination penetrate sunglasses for gaze tracking. South Korean module assemblers are consolidating DMS and occupant monitoring onto unified processing substrates.
- Front View Cameras:Single or stereo configurations for lane departure warning and traffic sign recognition. Mid-tier vehicle segments in Brazil and Thailand are adopting front-view cameras as standard equipment.
- Rear View Cameras:Wide-angle imagers with dynamic parking guidelines for reverse maneuvering. US FMVSS 111 rear visibility mandates have saturated this segment with commodity sensor modules.
- Gesture Recognition Cameras:Time-of-flight and structured light sensors enable cabin control through hand movements. German premium nameplates deploy gesture recognition for infotainment interface control.
Volume concentration sits with rear-view and front-view commodity modules. Value capture is climbing fastest in HD front-view and integrated surround-view architectures.
End User:
Procurement authority and software integration responsibility are shifting between tiers as domain centralization accelerates.
- OEMs:Vehicle manufacturers specify imaging performance thresholds and qualify tier-1 module suppliers. Detroit-based OEMs are unbundling camera hardware from perception software to enable direct semiconductor procurement.
- Tier-1 Suppliers:Continental, Bosch, and Denso integrate sensors, lenses, and image signal processors into sealed modules. German and Japanese tier-1 clusters dominate surround-view and ADAS camera assembly.
- Vehicle Assemblers:Contract manufacturers and joint venture production facilities install imaging systems on assembly lines. Indian domestic vehicle production growth is pulling cost-optimized imaging modules into Chennai and Pune assembly plants.
- Aftermarket Providers:Independent distributors supply replacement cameras and retrofit kits for collision repair and fleet upgrades. US commercial vehicle fleet operators are procuring aftermarket driver monitoring retrofits to reduce insurance premiums.
Procurement authority concentrates with tier-1 suppliers for sealed modules. OEMs are reclaiming direct semiconductor relationships for software-defined imaging stacks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors automotive imaging supply chains through dense tier-1 supplier clustering around Mercedes-Benz and Porsche headquarters. German camera module integrators supply surround-view systems to assembly plants across Europe and export markets.
United States
Detroit-based OEM procurement teams unbundle camera hardware from perception software to enable direct semiconductor sourcing. NHTSA FMVSS 127 pedestrian automatic emergency braking rules mandate specific nighttime detection thresholds for market access. Michigan and Ohio assembly corridors pull high-resolution front-view sensors into mid-tier truck and SUV nameplates.
Germany
Euro NCAP pedestrian detection mandates force 2-megapixel minimum resolution upgrades across tier-1 supply chains. KBA type-approval processes enforce UNECE-aligned imaging performance standards for series production. Bavarian optics clusters around Munich concentrate precision glass molding and active alignment processes for luxury surround-view modules.
Japan
METI coordinates domestic standards alignment with UNECE regulations to preserve export competitiveness for tier-1 imaging ecosystems. Highway-speed partial automation programs pull high-resolution front-view sensors into domestic and export vehicle segments. Nagoya-based module assemblers consolidate DMS and occupant monitoring onto unified processing substrates.
South Korea
Hyundai and Kia platform strategies mandate surround-view systems as standard equipment across vehicle tiers. MFDS-aligned automotive component regulations support domestic supplier qualification for export markets. Seoul-Incheon corridor module houses scale production of cost-optimized rear-view and surround-view cameras for Asian and North American assembly plants.
China
Shenzhen and Shanghai autonomous driving developers deploy mapping fleets to refresh cloud-based navigation layers with camera-based SLAM data. SAMR voluntary in-cabin imaging guidelines may accelerate mandatory timelines beyond current standards. Yangtze River Delta sensor fabs allocate capacity for domestic EV platform camera demand.
Global Automotive Imaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across resolution tiers and functional safety certification levels. The vendor base concentrates around semiconductor specialists with captive CMOS fabrication and tier-1 integrators with sealed module assembly expertise. Three archetypes dominate: stacked-CMOS specialists, time-of-flight integrators, and cost-optimized sensor suppliers. Competitive moves center on domain controller consolidation partnerships and direct OEM semiconductor procurement channels.
Among Asian semiconductor specialists, Samsung Electronics Co., Ltd. and Sony Group Corporation occupy positions at the high-resolution frontier, while OmniVision Technologies, Inc. anchors the cost-optimized tier for emerging-market rear-view replacements. STMicroelectronics exemplifies the European time-of-flight integration archetype for cabin monitoring applications. Continental AG and DENSO Corporation represent tier-1 module integrators with geographic clustering around German and Japanese vehicle assembly corridors.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| STMicroelectronics |
| Sony Group Corporation |
| Infineon Technologies AG |
| DENSO Corporation |
| ON Semiconductor Corporation |
| Continental AG |
| NXP Semiconductors N.V. |
| OmniVision Technologies, Inc. |
| Others |
Supply & Pricing Matrix
Precision glass molding labor costs in Bavarian and Nagoya optics clusters cascade through tier-1 module assembly into OEM procurement tiers, with active alignment throughput constraints preserving premium pricing for surround-view architectures while commoditized rear-view sensors face cost compression from Indian PLI-scheme entrants.
Pricing Analysis
Functional safety certification tiers anchor value-based pricing across the automotive imaging landscape. Three-tier pricing structure across ASIL-D certified, ASIL-B compliant, and non-safety-critical economy levels separates premium multi-camera domain controllers from commodity single-sensor modules. Pricing pressure stems from OEM unbundling of hardware and software procurement, compressing traditional tier-1 bundled margins. Fleet operators exhibit highest price sensitivity in aftermarket retrofit segments, while luxury German OEMs maintain lowest sensitivity for DMS-equipped cabin compliance.
Supply Chain Analysis
Precision optics technician scarcity in Munich and Osaka manufacturing corridors constrains active alignment capacity for high-resolution camera modules. Supply concentrates in Germany, Japan, and South Korea for tier-1 module integration, with Taiwan and South Korea anchoring CMOS image sensor fabrication. Raw material dependencies span germanium substrates for thermal imagers, specialty glass for automotive-grade lenses, and silicon carbide for power-integrated camera modules. Single-source vulnerability sits with Japanese precision glass molding equipment. Distribution runs through sealed module procurement contracts between tier-1 integrators and OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity allocation for automotive-grade CMOS sensors at TSMC and Samsung constrains supply elasticity, with 300mm wafer competition from smartphone and industrial vision segments propping pricing power for qualified suppliers.
For Market Incumbents: Hedge against domain controller consolidation by securing direct semiconductor procurement relationships with Detroit-based and Stuttgart-based OEMs. Prioritize ISO 26262 ASIL-D certification investment to defend margin position against emerging Chinese sensor fabs. Capacity expansion in Indian tier-2 cities captures PLI-scheme vehicle assembly growth. For New Entrants and Emerging Players: Direct-to-OEM software licensing routes bypass tier-1 module integration barriers for perception stack providers. Target cost-optimized rear-view and surround-view module supply to Indian domestic vehicle assemblers in Chennai and Pune. White-space exists in fleet aftermarket DMS retrofits for US commercial vehicle operators seeking insurance premium reductions. For Investors and Strategic Acquirers: Distressed-cycle entries favor time-of-flight cabin monitoring specialists with METI-aligned UNECE qualification in Japan's Nagoya corridor. Long-term viability hinges on software-defined imaging stack control points rather than hardware module assembly. Watch for SAMR mandatory in-cabin imaging timeline acceleration as inflection signal for capacity reallocation toward Chinese EV platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Domain Controller Consolidation Partnership | Unifies DMS and OMS processing onto shared substrates with South Korean tier-1 integrators. |
| Direct Semiconductor Procurement Channel | Enables Detroit OEMs to source Sony and Samsung CMOS sensors outside tier-1 bundled contracts. |
| ASIL-D Functional Safety Certification | Qualifies suppliers for Euro NCAP-mandated pedestrian detection camera programs in Germany. |
| Indian Manufacturing Footprint Expansion | Captures PLI-scheme incentives for cost-optimized rear-view module assembly in Pune. |
| LiDAR-Camera Fusion Architecture Development | Converges solid-state scanning with HDR imagers for urban robotaxi fleets in the United States. |
Research Methodology
SEC 10-K filings, vehicle production databases, and Euro NCAP technical protocols formed the secondary backbone, supplemented by customs records and tier-1 supplier annual reports. Primary interviews with OEM platform engineers, tier-1 procurement directors, aftermarket distributors, and semiconductor fab planning officers validated demand assumptions. Bottom-up unit volume estimates triangulated against top-down OEM production forecasts across the analysis window.
Historical trendline analysis of camera content per vehicle progression informed projection modeling across technology, application, product type, and end-user segmentation dimensions. CAGRs derived from regression-adjusted growth rates incorporating regulatory mandate timelines and OEM platform lifecycle transitions. Forecast inputs included NHTSA FMVSS rulemaking schedules and Euro NCAP safety rating protocol evolution.
The model holds under stable foundry capacity allocation and regulatory timeline adherence; deviation in SAMR mandatory imaging mandates or TSMC automotive wafer prioritization would shift supply-demand balance. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
In Vivo Imaging Systems Market
Imaging
Holotomographic Imaging Market
Imaging
High-Resolution 3D X-Ray Microscopy Market
Imaging
Global Panoramic Camera Market
Imaging
Holographic Imaging Market
Imaging
Digital Imaging Market
Imaging
Japan Digital X-Ray Market
Imaging
Wide Field Imaging Devices Market
Imaging
Global Acoustic Cameras Market
Imaging
Document Imaging Market
Imaging
Global Trail Camera Market
Imaging
Machine Vision System and Services Market
Imaging
Photography Ring Flash Market
Imaging
CCD Image Sensors Market
Imaging
Industrial Machine Vision Market
Imaging
Hyper Spectral Imaging System Market