
 Americas Sterility Testing Market | 2026-2036
Americas Sterility Testing Market Size, Share, and Industry Trends Forecast 2026-2036
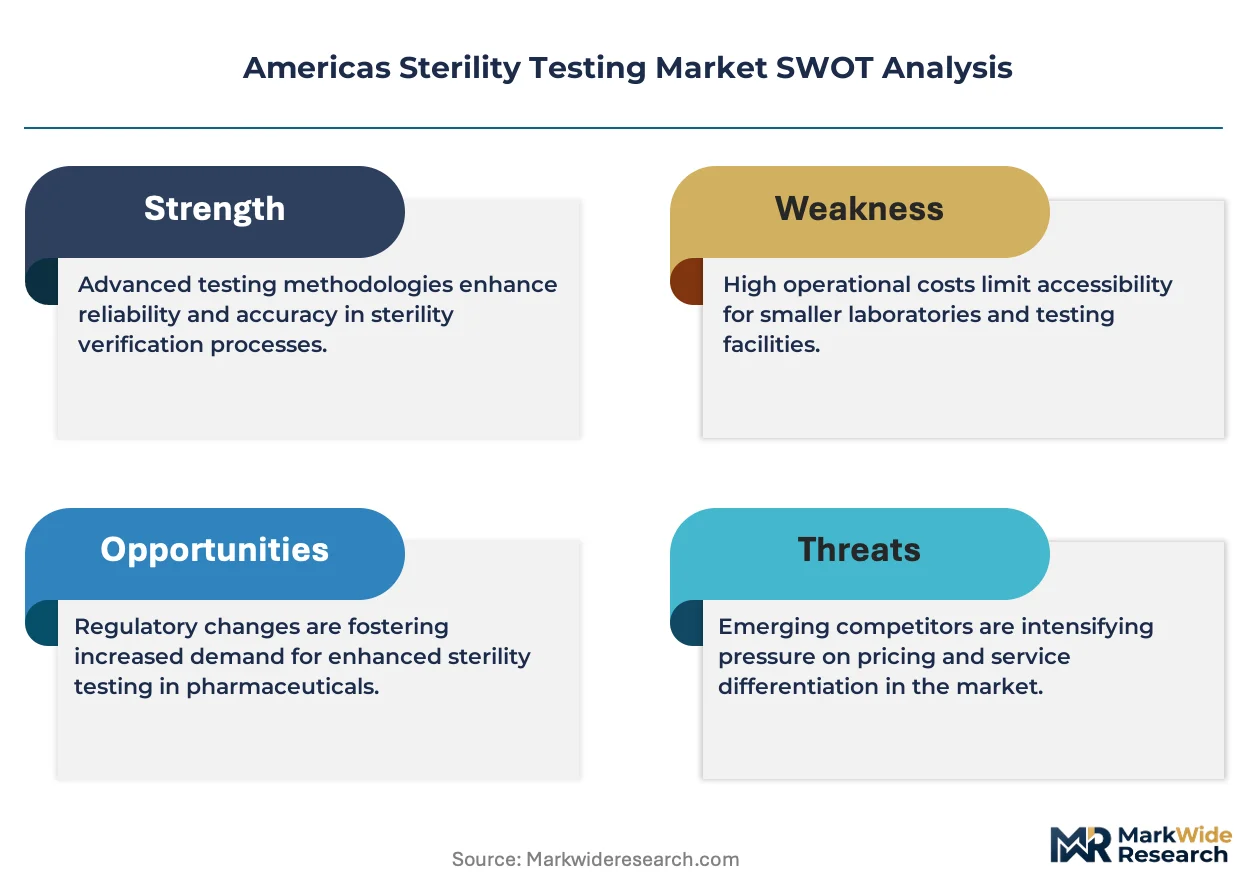
Americas Sterility Testing Market Analysis
Buyer concentration among large biopharmaceutical sponsors is repositioning contract testing demand toward full-service providers with integrated quality systems. Charles River Laboratories leverages its North American laboratory network to anchor end-to-end sterility programs for complex biologics. Thermo Fisher Scientific competes through captive supply of rapid detection platforms bundled with testing services. SGS SA differentiates by navigating multi-jurisdictional regulatory submissions across FDA and ANVISA jurisdictions.
Sterility testing encompasses validated microbiological methods designed to detect viable contaminating microorganisms in pharmaceuticals, medical devices, and cell therapies, typically requiring incubation periods and aseptic technique controls to achieve sterility assurance levels of 10^-6. Membrane filtration dominates parenteral drug applications where product inhibition of microbial growth complicates direct inoculation methods. Rapid tests are displacing culture-based protocols in release testing scenarios where automation reduces human intervention and accelerates batch disposition timelines. Filtration technology occupies the core infrastructure layer across both traditional and accelerated sterility workflows.
FDA enforces sterility testing requirements under 21 CFR 211 and USP chapters, while ANVISA applies Resolution RDC 17/2010 for biological product sterility in Brazil, collectively elevating documentation and validation burdens for market participants. ISO 14698 and USP provide harmonized frameworks for cleanroom environmental monitoring that underpin sterility assurance programs. Stakeholders must decide whether to build in-house rapid method capabilities or outsource to contract laboratories with validated platform portfolios.
Market Dynamics
Rapid microbiological methods are compressing batch release timelines and forcing capital reallocation across pharmaceutical quality control networks throughout the Americas.
Growth Catalysts
- FDA 21 CFR 211 Enforcement:Heightened inspection frequency for aseptic processing facilities drives validation spending on alternative microbiological methods.
- Cell Therapy Manufacturing:Autologous and allogeneic cell therapy producers require accelerated sterility release protocols incompatible with 14-day culture periods.
- Boston-Research Triangle Corridor:Biologics manufacturing concentration creates localized demand density for integrated testing and environmental monitoring services.
Market Restraints
- Reference Culture Media Supply:Concentrated sourcing of dehydrated culture media from European suppliers introduces tariff and currency volatility into testing cost structures.
- ANVISA Validation Burden:Brazil's Resolution RDC 17/2010 requires extensive method equivalence studies that extend platform adoption timelines by 18-24 months.
- ATP Bioluminescence Limitations:Enzyme-based rapid methods face specificity constraints with slow-growing environmental isolates in cleanroom monitoring applications.
Strategic Opportunities
- Mexico Regulatory Alignment:COFEPRIS adoption of USP harmonized sterility chapters creates pathway for rapid method transfer from US parent facilities.
- Continuous Manufacturing Integration:Real-time release testing architectures enable in-line microbiological detection converging with process analytical technology platforms.
- Environmental Monitoring Outsourcing:Cleanroom viable particle surveillance shifts from in-house microbiology labs to specialized contract service providers.
Industry Challenges
- Rapid Method Validation Expertise:Shortage of statisticians and microbiologists capable of designing equivalence studies per USP 1223 guidelines constrains platform deployment.
- Legacy LIMS Integration:Paper-based batch records and disconnected data systems impede automated sterility test data integrity compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Sterility Testing Market |
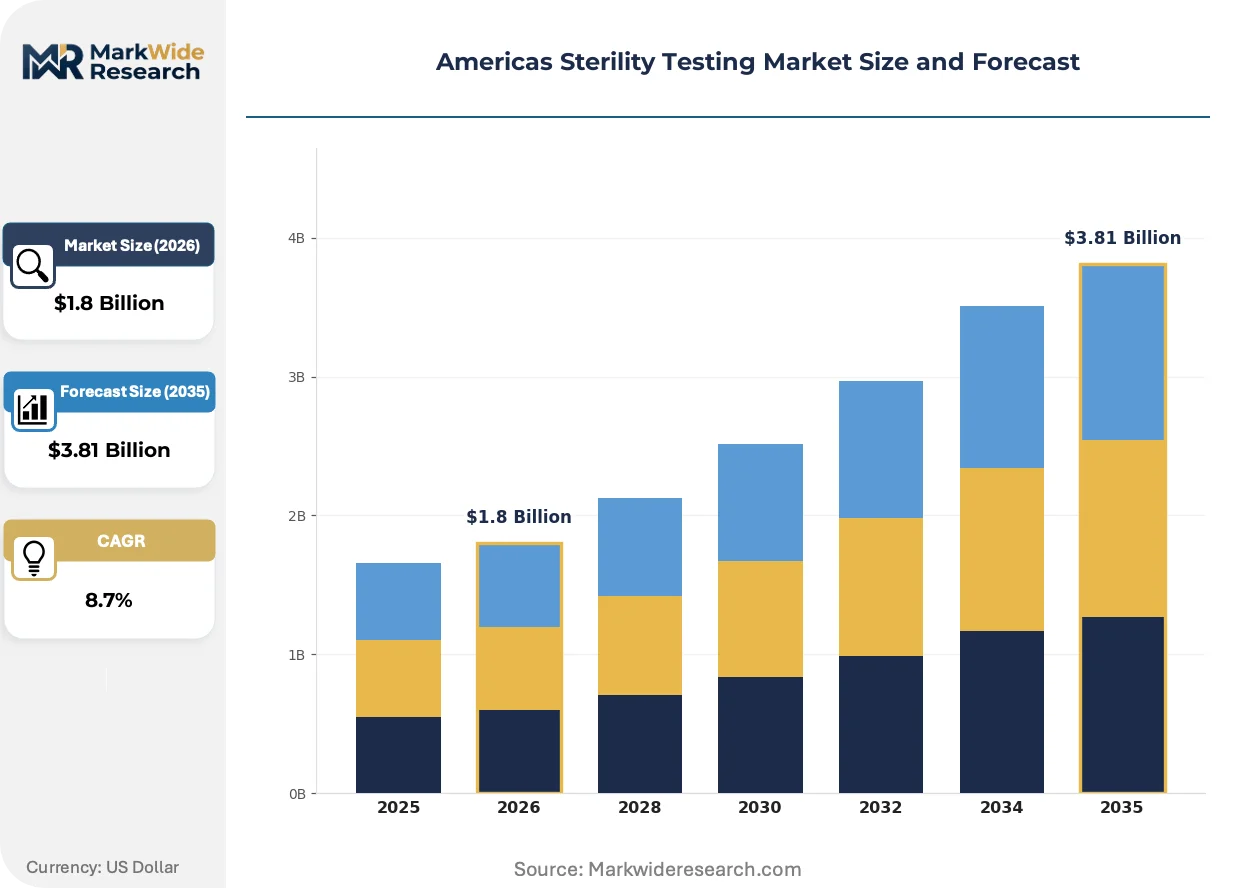
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filtration, Direct Transfer, Culture-Based Tests, Rapid Tests Application: Pharmaceuticals, Biotechnology, Medical Devices, Cosmetics End User: Contract Research Organizations, Hospitals, Laboratories, Manufacturing Facilities Technology: Filtration Technology, Automation, Optical Testing, Microbial Detection |
| Companies Covered | Charles River Laboratories, Thermo Fisher Scientific, SGS SA, STERIS, Nelson Laboratories, Pacific Biolabs, Boston Analytical, Laboratory Corporation of America Holdings, Pace Analytical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Sterility Testing Market Emerging Trajectories
Automation architectures are reconfiguring laboratory workforce deployment while regulatory pressure on data integrity accelerates platform consolidation decisions across pharmaceutical quality organizations.
Automated membrane filtration systems with robotic sample handling are overtaking manual sterility test setups in high-volume parenteral drug facilities. Large molecule manufacturers in the United States are adopting these platforms at replacement cycle points to reduce human intervention during critical aseptic manipulations. This transition is compressing technician staffing models while elevating equipment qualification and maintenance capabilities within quality departments.
FDA's draft guidance on rapid microbiological methods for sterile products is clarifying submission pathways for alternative sterility test platforms. The industrial consequence is reduced regulatory uncertainty for ATP bioluminescence, flow cytometry, and nucleic acid amplification-based systems. Biologics sponsors in Massachusetts and North Carolina are responding with coordinated method development programs targeting supplemental New Drug Application filings.
Centralized procurement of sterility testing services through master service agreements is consolidating vendor relationships among mid-cap pharmaceutical sponsors. Multi-product facilities are replacing transactional testing contracts with multi-year partnerships bundling environmental monitoring, sterility testing, and endotoxin detection. This pattern is most visible among emerging biotech sponsors in the Research Triangle lacking captive microbiology infrastructure.
Americas Sterility Testing Market Segmentation
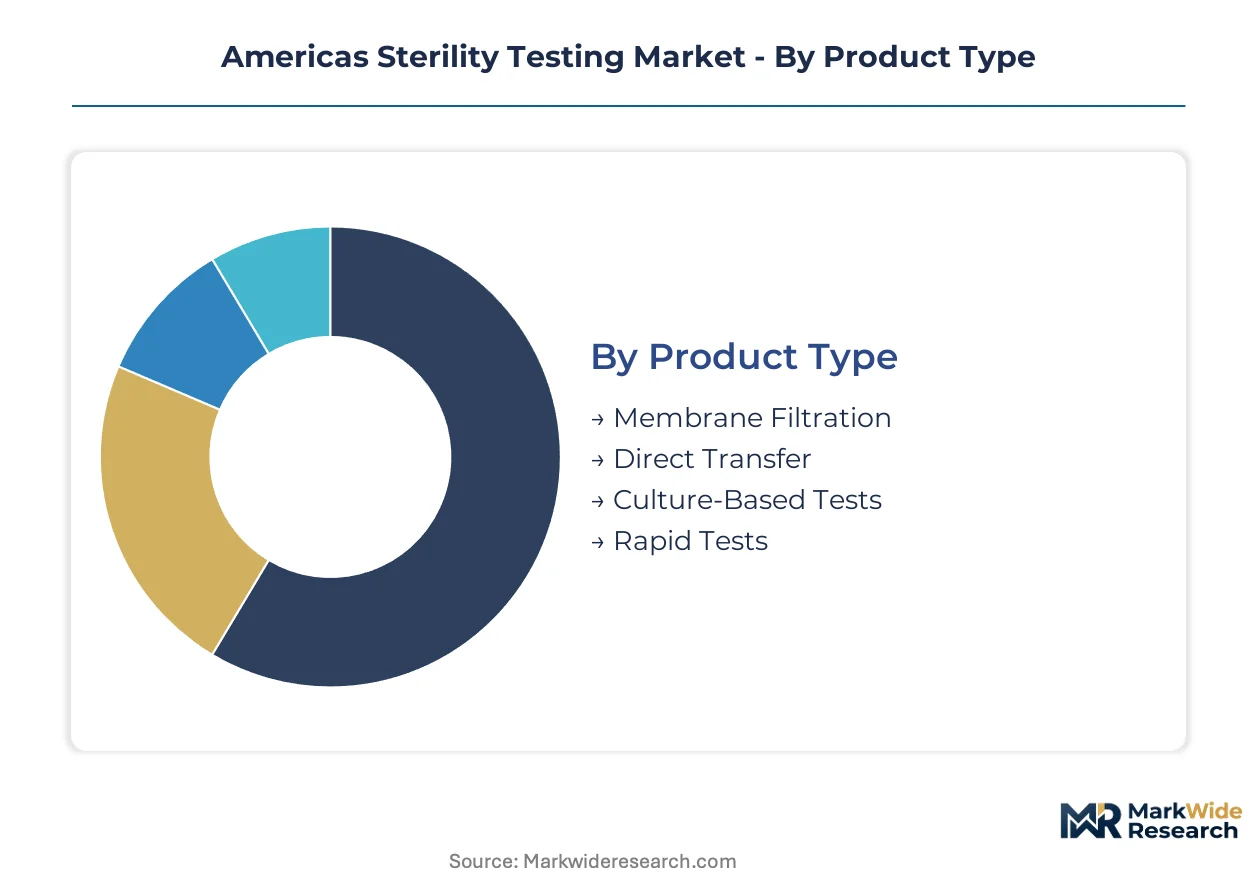
Segmentation in the Americas sterility testing market reveals how technology choices, regulatory pathways, and end-user capabilities create divergent procurement patterns across pharmaceutical quality networks. Understanding these divides enables vendors to align platform development with specific validation requirements and capital deployment cycles.
Product Type:
Membrane filtration technology anchors the core infrastructure layer, with specification choices directly determining downstream workflow automation potential and regulatory submission complexity.
- Membrane Filtration:Dominates parenteral drug applications where product inhibition of microbial growth complicates direct inoculation methods. United States biologics manufacturers in the Boston corridor deploy these systems for high-volume monoclonal antibody release testing under FDA 21 CFR 211 protocols.
- Rapid Tests:ATP bioluminescence and nucleic acid amplification platforms compress batch release timelines from 14 days to 48-72 hours. Cell therapy producers in North Carolina require these accelerated protocols for autologous product viability windows.
- Direct Transfer:Applied to medical devices and simple aqueous formulations where product characteristics permit direct microbial inoculation without filtration barriers.
- Culture-Based Tests:Remains the regulatory reference standard for method equivalence studies under USP 71, anchoring validation protocols for alternative microbiological methods.
Mature deployment sits with membrane filtration systems in legacy parenteral facilities. Newer deployment is concentrated in rapid test platforms for cell therapy and continuous manufacturing architectures.
Application:
Application segmentation tracks how sterility assurance requirements scale with product complexity and patient exposure risk, creating tiered pricing for validation depth and documentation burden.
- Pharmaceuticals:Injectable drugs and ophthalmic preparations demand the most rigorous sterility assurance levels, with FDA enforcement driving validation spending on alternative microbiological methods. Parenteral manufacturers face the highest documentation burdens under USP 71 and 21 CFR 211.
- Biotechnology:Recombinant proteins, vaccines, and gene therapies require specialized rapid release protocols incompatible with traditional incubation periods. Massachusetts and North Carolina biotech clusters are expanding quality control budgets for automated sterility platforms.
- Medical Devices:Implantable and sterile surgical instruments follow ISO 11137 and USP 71 guidelines, with ethylene oxide sterilization validation creating secondary microbiological testing demand.
- Cosmetics:Preservative efficacy testing and sterility claims for eye-area products fall under FDA cosmetic regulations with lighter validation requirements than pharmaceutical applications.
Biotechnology applications are climbing the fastest as cell therapy manufacturing scales. Cosmetics testing represents the most price-sensitive segment with compressed margins and limited automation adoption.
End User:
End-user segmentation captures the build-versus-outsource decision calculus that determines whether sterility testing remains captive or migrates to specialized service providers.
- Contract Research Organizations:Charles River Laboratories and Thermo Fisher Scientific anchor end-to-end sterility programs through integrated North American laboratory networks, capturing demand from emerging biotech sponsors lacking captive microbiology infrastructure.
- Manufacturing Facilities:Large biopharmaceutical sponsors maintain in-house rapid method capabilities with dedicated statisticians for USP 1223 equivalence studies, particularly around Boston and the Research Triangle.
- Laboratories:Hospital and independent clinical labs perform environmental monitoring and compounding pharmacy sterility testing with lighter regulatory documentation requirements.
- Hospitals:In-house pharmacy compounding operations follow USP 797 guidelines for sterile preparations, creating localized demand for rapid microbial detection in patient-critical scenarios.
Contract research organizations are gaining share fastest among mid-cap sponsors consolidating vendor relationships through master service agreements. Manufacturing facilities retain the most complex method development capabilities in-house.
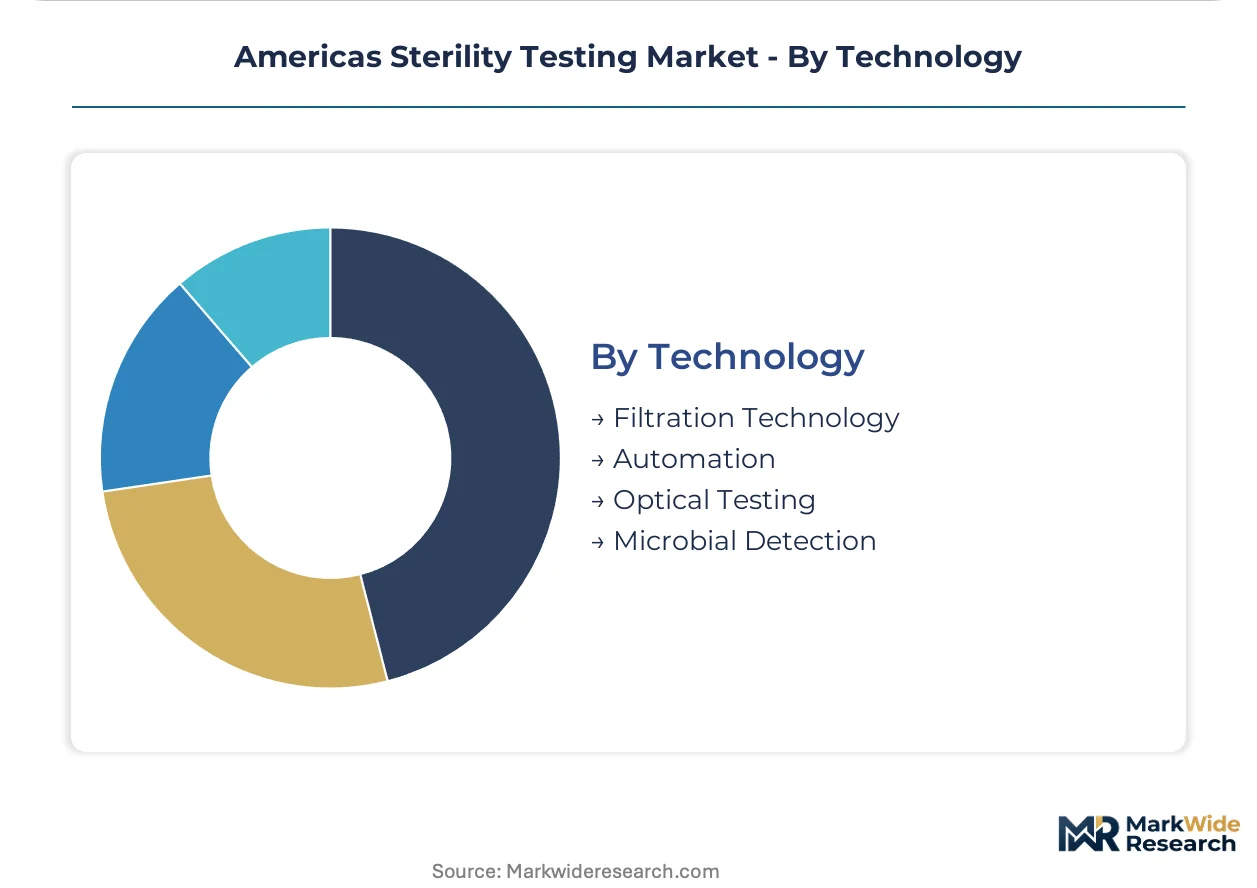
Technology:
Technology segmentation reflects the automation frontier where robotic sample handling and real-time data integrity are displacing manual interventions and paper-based batch records.
- Filtration Technology:Automated membrane filtration systems with robotic handling are overtaking manual setups in high-volume United States parenteral facilities, compressing technician staffing models while elevating equipment qualification requirements.
- Automation:Integrated platforms combining sample preparation, incubation, and detection reduce human intervention during critical aseptic manipulations, addressing FDA data integrity enforcement priorities.
- Optical Testing:Flow cytometry and laser-induced fluorescence systems enable rapid microbial enumeration without culture-based growth requirements.
- Microbial Detection:ATP bioluminescence and nucleic acid amplification methods face specificity constraints with slow-growing environmental isolates in cleanroom monitoring applications.
Filtration technology anchors the installed base across traditional workflows. Automation platforms are expanding most quickly as facilities replace manual systems at capital refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for sterility testing concentrates in the United States pharmaceutical corridor, with Boston and North Carolina anchoring biologics manufacturing investment. Regulatory enforcement by FDA and ANVISA is elevating validation spending across the hemisphere.
United States
FDA 21 CFR 211 enforcement drives validation spending on alternative microbiological methods among parenteral drug manufacturers. The Research Triangle and Greater Boston clusters anchor cell therapy production requiring accelerated sterility release protocols. Charles River Laboratories and Thermo Fisher Scientific maintain integrated laboratory networks serving these concentrated demand centers.
Brazil
ANVISA Resolution RDC 17/2010 imposes extensive method equivalence studies that extend rapid platform adoption timelines. São Paulo state hosts the majority of domestic biological product manufacturing subject to sterility assurance requirements. European suppliers dominate reference culture media sourcing, introducing currency volatility into local testing cost structures.
Mexico
COFEPRIS adoption of harmonized USP sterility chapters creates regulatory pathways for rapid method transfer from US parent facilities. The Bajío Region and Mexico City Metro concentrate pharmaceutical manufacturing investment requiring environmental monitoring services. Contract testing demand is shifting toward full-service providers with multi-jurisdictional capabilities.
Canada
Health Canada alignment with FDA sterility guidance accelerates validation protocols for biologics exporters serving the US market. Ontario and Quebec provinces host the majority of domestic parenteral drug manufacturing capacity. Environmental monitoring outsourcing is gaining traction among mid-cap sponsors lacking captive microbiology infrastructure.
Americas Sterility Testing Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue rapid microbiological method platforms and integrated quality system offerings. The vendor base clusters around three strategic archetypes: full-service contract laboratories with North American networks, captive platform suppliers bundling detection technology with testing services, and specialized providers navigating multi-jurisdictional regulatory submissions. Consolidation is accelerating through master service agreements that bundle environmental monitoring with sterility and endotoxin testing. Geographic expansion into Brazil and Mexico represents the dominant competitive vector as sponsors seek validated partners across FDA and ANVISA jurisdictions.
Among North American-based service providers, Charles River Laboratories, Thermo Fisher Scientific, and SGS SA exemplify the three dominant competitive archetypes. Charles River occupies a position representing the full-service laboratory model with integrated end-to-end sterility programs. Thermo Fisher exemplifies the captive platform strategy through bundled rapid detection technology and testing services. SGS SA represents the multi-jurisdictional navigation specialist, with capabilities spanning FDA and ANVISA regulatory frameworks.
| Leading Market Players |
|---|
| Charles River Laboratories |
| Thermo Fisher Scientific |
| SGS SA |
| STERIS |
| Nelson Laboratories |
| Pacific Biolabs |
| Boston Analytical |
| Laboratory Corporation of America Holdings |
| Pace Analytical |
| Others |
Supply Flow & Price Mechanics
Consolidated procurement through master service agreements among mid-cap biopharmaceutical sponsors is forcing contract testing providers to absorb validation costs upfront, compressing margins on rapid method platforms while elevating pricing power for integrated quality system bundles.
Pricing Analysis
High-volume transactional testing commands thinner margins than multi-year partnership contracts bundling environmental monitoring, sterility testing, and endotoxin detection. Price differentiation hinges on USP 1223 equivalence study documentation depth and FDA submission support breadth. Cost compression in rapid ATP bioluminescence platforms is intensifying as European reference culture media suppliers pass through currency volatility. Emerging biotech sponsors in the Research Triangle exhibit the highest price sensitivity; large biologics manufacturers around Boston prioritize validation speed over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for dehydrated culture media and reference microbial strains are mandated by FDA 21 CFR 211 documentation standards, yet European suppliers in Germany, the United Kingdom, and France retain dominant positions in the Americas market. Critical inputs include gamma-irradiated filtration membranes, ATP detection reagents, and nucleic acid amplification master mixes. Tariff exposure on European-sourced media introduces margin volatility for contract laboratories operating on fixed-fee master service agreements. Distribution runs through direct manufacturer-to-laboratory channels for high-value automated platforms, with consumables flowing through specialized life science distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified rapid method validation expertise functions as the binding capacity constraint across the Americas sterility testing market, propping pricing for statisticians and microbiologists capable of USP 1223 equivalence study design.
For Market Incumbents: Cement platform consolidation advantages by acquiring specialized environmental monitoring service providers in Brazil and Mexico ahead of ANVISA enforcement intensification. Expand captive rapid detection technology portfolios through backward integration into ATP reagent manufacturing, neutralizing European supplier currency volatility. For New Entrants and Emerging Players: The mid-tier pricing gap between premium full-service contract laboratories and economy-tier hospital pharmacy testing creates white-space opportunity for automated membrane filtration platform leasing models targeting mid-cap parenteral manufacturers. Penetration potential concentrates in the Bajío Region of Mexico, where COFEPRIS harmonization enables rapid method transfer from US parent facilities without full validation burden. For Investors and Strategic Acquirers: Re-rating potential sits with contract laboratories possessing validated rapid method portfolios across FDA and ANVISA jurisdictions given cell therapy manufacturing scale-up across the Boston-Research Triangle corridor. Long-term viability favors acquisition targets with integrated environmental monitoring capabilities and multi-year master service agreement backlogs. The signal to watch is ANVISA Resolution RDC 17/2010 amendment timelines, which would accelerate rapid platform adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Rapid Method Validation Partnership | USP 1223 equivalence study capabilities differentiate contract laboratories serving cell therapy producers in North Carolina. |
| Multi-Jurisdictional Regulatory Certification | Dual FDA-ANVISA qualification expands addressable market for testing providers serving multinational biologics sponsors. |
| Automated Platform Deployment | Robotic membrane filtration systems reduce technician staffing costs while addressing FDA data integrity enforcement priorities. |
| Environmental Monitoring Outsourcing | Cleanroom viable particle surveillance shifts from in-house microbiology labs to specialized contract service providers. |
| Reference Culture Media Backward Integration | In-house production of dehydrated culture media neutralizes European supplier tariff and currency volatility exposure. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by structured interviews with quality control directors, regulatory affairs leads, contract laboratory procurement managers, and sterility test platform engineers at biopharmaceutical manufacturers across the United States, Brazil, Mexico, and Canada. FDA 483 inspection observations, ANVISA Resolution RDC 17/2010 guidance documents, USP chapter revisions, and ISO 14698 cleanroom standards provided secondary validation. Bottom-up facility-level capacity estimates were triangulated against top-down market sizing derived from trade flows.
Segment-level modeling tracked membrane filtration, rapid test, and culture-based technology platforms across pharmaceutical, biotechnology, medical device, and cosmetics applications. End-user segmentation captured contract research organizations, manufacturing facilities, independent laboratories, and hospital pharmacy compounding operations. CAGRs were derived from regression analysis of historical quality control spending patterns and projected biologics manufacturing capacity expansion across the analysis window. Cell therapy autologous product viability windows and continuous manufacturing real-time release architectures provided industry-specific demand drivers.
Inputs from FDA inspection databases and ANVISA biological product registration records were available through the study window; gaps in private contract laboratory pricing disclosures introduce uncertainty bands around service revenue estimates. Forecasts reflect assumptions regarding regulatory enforcement intensity and rapid method equivalence study approval timelines. Deviation in ANVISA Resolution RDC 17/2010 amendment schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market
Testing Services
Adenovirus Testing Market
Testing Services
Ovulation Test Kit Market
Testing Services
Rapid Antigen Testing Market
Testing Services
Fecal Pancreatic Elastase Testing Market
Testing Services
Arthropod-Borne Viral Infections Testing Market
Testing Services
Skin Perfusion Pressure Testing Devices Market
Testing Services
ATP Assays Market
Testing Services
Gastrointestinal Testing Panels Market
Testing Services
Europe Medical Device Testing Market
Testing Services
Blood Testing Market
Testing Services
D-Dimer Testing Market
Testing Services
Mono Rapid Testing Market
Testing Services
Global Biological Safety Testing Market
Testing Services
Vaginal Panel Testing Market
Testing Services
Breath Biopsy Testing Market