
 Continuous Tablet Manufacturing At-Line Quality Test Systems Market | 2026-2036
Continuous Tablet Manufacturing At-Line Quality Test Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Tablet Manufacturing At-Line Quality Test Systems Market Insights
FDA's Process Analytical Technology initiative is expanding the cost-of-entry calculus for quality test systems in continuous tablet manufacturing. Thermo Fisher Scientific leverages its spectroscopy portfolio to anchor integrated at-line solutions across major pharmaceutical hubs. Bruker Corporation specializes in Raman and NIR platforms that compete on precision for content uniformity applications. GEA Group sustains its position through backward integration into production line engineering, controlling the interface between manufacturing equipment and quality instrumentation.
Continuous tablet manufacturing at-line quality test systems comprise spectroscopic and imaging instruments deployed directly on production lines to measure critical quality attributes without interrupting material flow. Near-infrared spectroscopy dominates real-time moisture and active pharmaceutical ingredient quantification, operating at wavelengths between 780 and 2500 nanometers with chemometric model-driven analysis. Raman spectroscopy captures the fastest-growing segment as pharmaceutical manufacturers seek molecular fingerprinting for polymorph identification without sample preparation. Integrated production line systems command the deepest margin pools by embedding sensors within Fette Compacting and Glatt continuous processing equipment, reducing validation overhead compared with standalone retrofits.
FDA's Quality by Design framework and EMA's ICH Q13 implementation together shape validation requirements for real-time release testing across both markets. The EPA regulates solvent emissions from coating processes, indirectly driving demand for at-line coating thickness analysis that minimizes rework and material waste. Germany's national pharmaceutical regulator enforces stringent batch documentation standards that favor cloud-connected platforms with automated data integrity safeguards. Stakeholders must monitor how evolving pharmacopeial standards for continuous manufacturing will redefine calibration protocols and sensor qualification timelines.
Market Dynamics
ICH Q13 guidelines are compressing validation timelines for real-time release testing, forcing pharmaceutical manufacturers to restructure quality assurance workflows around spectroscopic at-line integration rather than offline laboratory verification.
Growth Catalysts
- FDA Process Analytical Technology:The initiative mandates real-time quality verification during manufacturing, compelling facilities to deploy NIR and Raman sensors directly on continuous processing lines.
- Continuous manufacturing adoption:Pharmaceutical producers in Germany and Switzerland are retrofitting batch facilities with integrated at-line systems to reduce cycle times and material waste.
- Cloud-connected data integrity:Automated batch documentation platforms with audit trails satisfy German national pharmaceutical regulator requirements for continuous process verification.
Market Restraints
- Capital intensity:Integrated production line systems require substantial upfront investment in validated sensor hardware and chemometric model development.
- Technical limitation:Polymorph identification accuracy degrades for complex multi-component formulations without extensive spectral libraries.
- Regulatory friction:EMA's evolving ICH Q13 implementation timelines create uncertainty in sensor qualification protocols across European manufacturing sites.
Strategic Opportunities
- Underpenetrated geography:Indian pharmaceutical manufacturers under CDSCO oversight are beginning pilot programs for continuous tablet manufacturing with at-line quality verification.
- Technology convergence:Hybrid Raman-NIR platforms combined with machine vision imaging enable simultaneous chemical and physical attribute monitoring.
- Regulatory tailwind:EPA solvent emission regulations indirectly accelerate demand for at-line coating thickness analysis to minimize rework and material waste.
Industry Challenges
- Chemometric expertise scarcity:Facilities lack personnel trained in multivariate calibration development and spectral preprocessing for pharmaceutical applications.
- Legacy system integration:Retrofitting at-line sensors into existing Fette Compacting and Glatt equipment requires extensive validation documentation and production downtime.
- Calibration maintenance burden:Spectral models drift with raw material variability, demanding continuous revalidation cycles that strain quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Tablet Manufacturing At-Line Quality Test Systems Market |
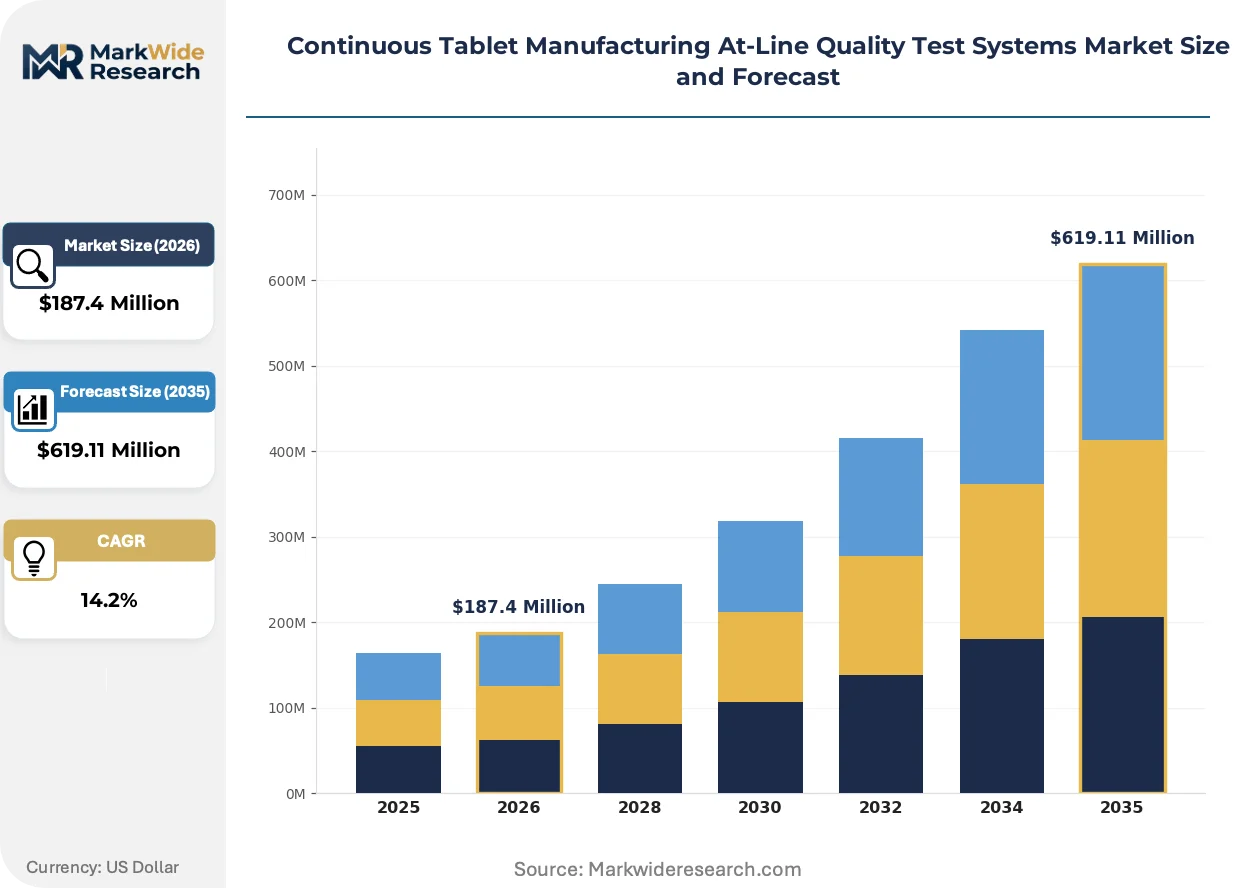
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Near-Infrared Spectroscopy, Terahertz Spectroscopy, Raman Spectroscopy, X-Ray Inspection, Optical Imaging Application: Tablet Weight Verification, Coating Thickness Analysis, Content Uniformity, Defect Detection, Disintegration Testing End User: Pharmaceutical Manufacturers, Contract Manufacturing Organizations, Research Laboratories, Biotechnology Companies Deployment: Standalone Systems, Integrated Production Line Systems, Portable Instruments, Cloud-Connected Platforms |
| Companies Covered | Thermo Fisher Scientific, Bruker Corporation, SOTAX Group, Fette Compacting, GEA Group, Siemens, Glatt, Endress+Hauser, Sensum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Tablet Manufacturing At-Line Quality Test Systems Market Trends and Innovations
Spectroscopic sensing architectures are converging with production line automation, compressing the gap between manufacturing execution and quality verification. This integration is redefining how pharmaceutical facilities structure their technical workforce and capital deployment priorities.
Machine vision inspection is integrating with spectroscopic platforms to enable simultaneous chemical composition and physical defect detection on continuous tablet lines. Large-scale pharmaceutical manufacturers in Switzerland are deploying these hybrid systems to satisfy Swissmedic documentation requirements for comprehensive critical quality attribute coverage. The technology is integrating process analytical capabilities directly into tablet press feedback loops, enabling real-time compression force adjustment based on API uniformity measurements.
EMA's phased ICH Q13 implementation is mandating enhanced process understanding documentation for continuous manufacturing submissions, elevating the role of at-line sensor validation in regulatory approvals. Pharmaceutical facilities must now demonstrate robust chemometric model performance across design space variations before commercial authorization. German manufacturers are responding by investing in cloud-based data integrity platforms that automate audit trail generation for regulatory inspections.
Equipment procurement patterns are consolidating around integrated vendor relationships rather than standalone instrument purchases. Pharmaceutical quality directors now prioritize single-source accountability for sensor hardware, installation qualification, and ongoing calibration support. This preference shift is most pronounced in North American facilities where FDA inspection intensity rewards streamlined validation documentation and reduced supplier management overhead.
Continuous Tablet Manufacturing At-Line Quality Test Systems Market Segmentation
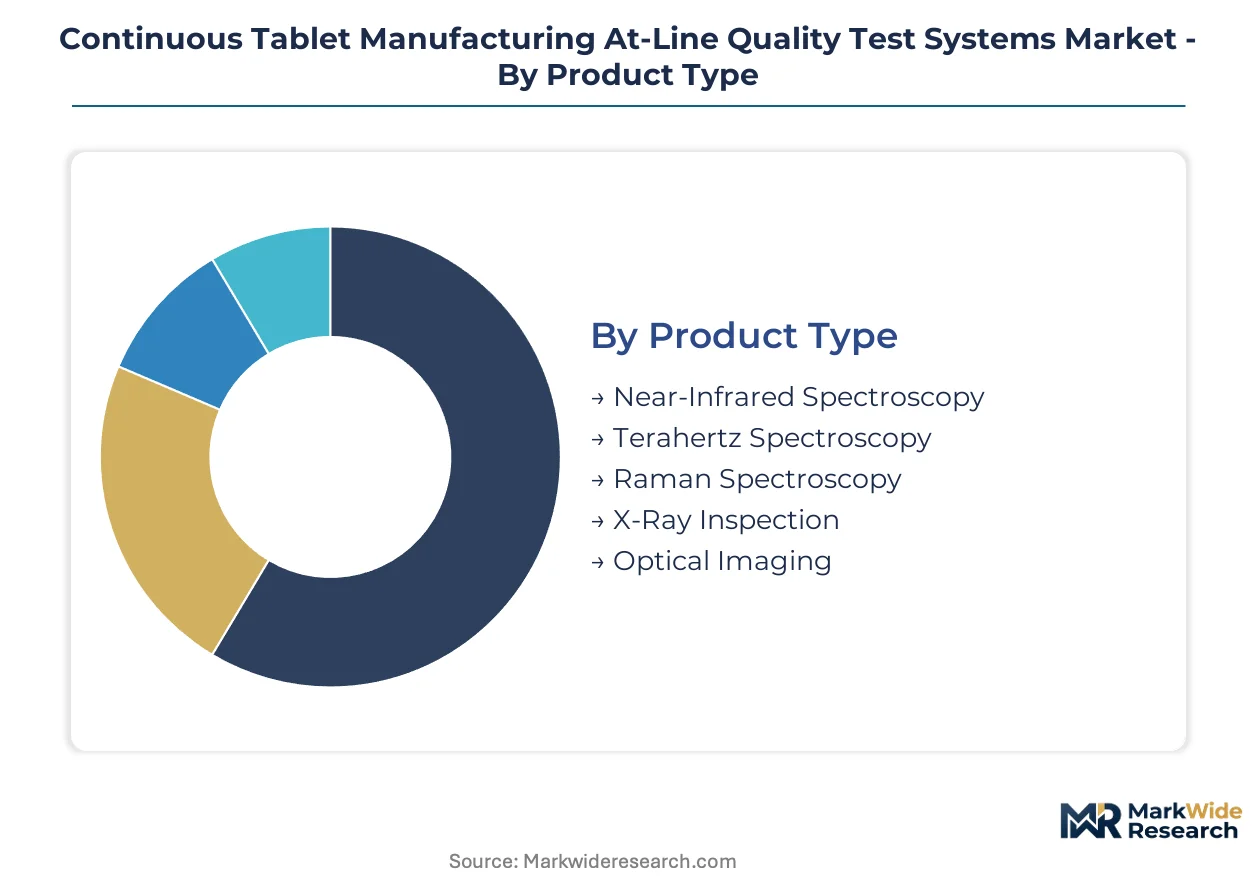
Segmentation in continuous tablet manufacturing at-line quality test systems reveals how technology specialization, deployment architecture, and end-user scale determine purchasing patterns. Each dimension carries distinct margin profiles and regulatory validation requirements.
Product Type:
The customization-to-standardization spectrum runs from application-specific spectroscopic platforms to general-purpose imaging systems with modular configurations.
- Near-Infrared Spectroscopy:Operating between 780 and 2500 nanometers, NIR systems dominate real-time moisture and API quantification through chemometric model-driven analysis. Demand concentrates in Germany and Switzerland where advanced spectroscopy integration is most mature, driven by FDA Process Analytical Technology mandates for real-time release testing.
- Raman Spectroscopy:Molecular fingerprinting capability enables polymorph identification without sample preparation, capturing the steepest expansion trajectory as pharmaceutical manufacturers seek enhanced process understanding. Swissmedic documentation requirements for comprehensive critical quality attribute coverage accelerate deployment in Switzerland.
- Terahertz Spectroscopy:Emerging platform for coating thickness analysis with non-destructive penetration capability.
- X-Ray Inspection:Standardized hardware for tablet weight verification and foreign particle detection.
- Optical Imaging:Modular visual inspection systems for surface defect characterization.
Most installed capacity flows through Near-Infrared Spectroscopy. Expansion is steepest in Raman Spectroscopy.
Application:
Cost tier separation distinguishes high-margin analytical applications from commoditized physical verification tasks.
- Content Uniformity:Chemometrically demanding application requiring validated spectral libraries and multivariate calibration development. Pharmaceutical manufacturers in North America prioritize this capability to satisfy FDA Quality by Design framework requirements for real-time release testing.
- Coating Thickness Analysis:EPA solvent emission regulations indirectly accelerate demand as at-line measurement minimizes rework and material waste. German facilities under stringent national pharmaceutical regulator standards favor cloud-connected platforms with automated data integrity safeguards.
- Tablet Weight Verification:Standardized physical measurement with lower technical barrier.
- Defect Detection:Machine vision integration enabling simultaneous chemical and physical attribute monitoring.
- Disintegration Testing:Specialized application with limited continuous manufacturing compatibility.
Content Uniformity commands the deepest margin pools. Coating Thickness Analysis is gaining share fastest.
End User:
Customer type determines procurement complexity, with integrated vendor relationships preferred by large-scale manufacturers versus modular purchases by smaller facilities.
- Pharmaceutical Manufacturers:Primary demand source with capital-intensive integrated production line deployments. North American facilities reward streamlined validation documentation and reduced supplier management overhead through single-source accountability for sensor hardware and ongoing calibration support.
- Contract Manufacturing Organizations:Flexible deployment requirements favoring portable instruments and cloud-connected platforms.
- Research Laboratories:Standalone spectroscopic systems for method development and chemometric model training.
- Biotechnology Companies:Emerging segment piloting continuous manufacturing with at-line quality verification under evolving regulatory frameworks.
Pharmaceutical Manufacturers absorb the majority of installed systems. Contract Manufacturing Organizations are expanding most quickly.
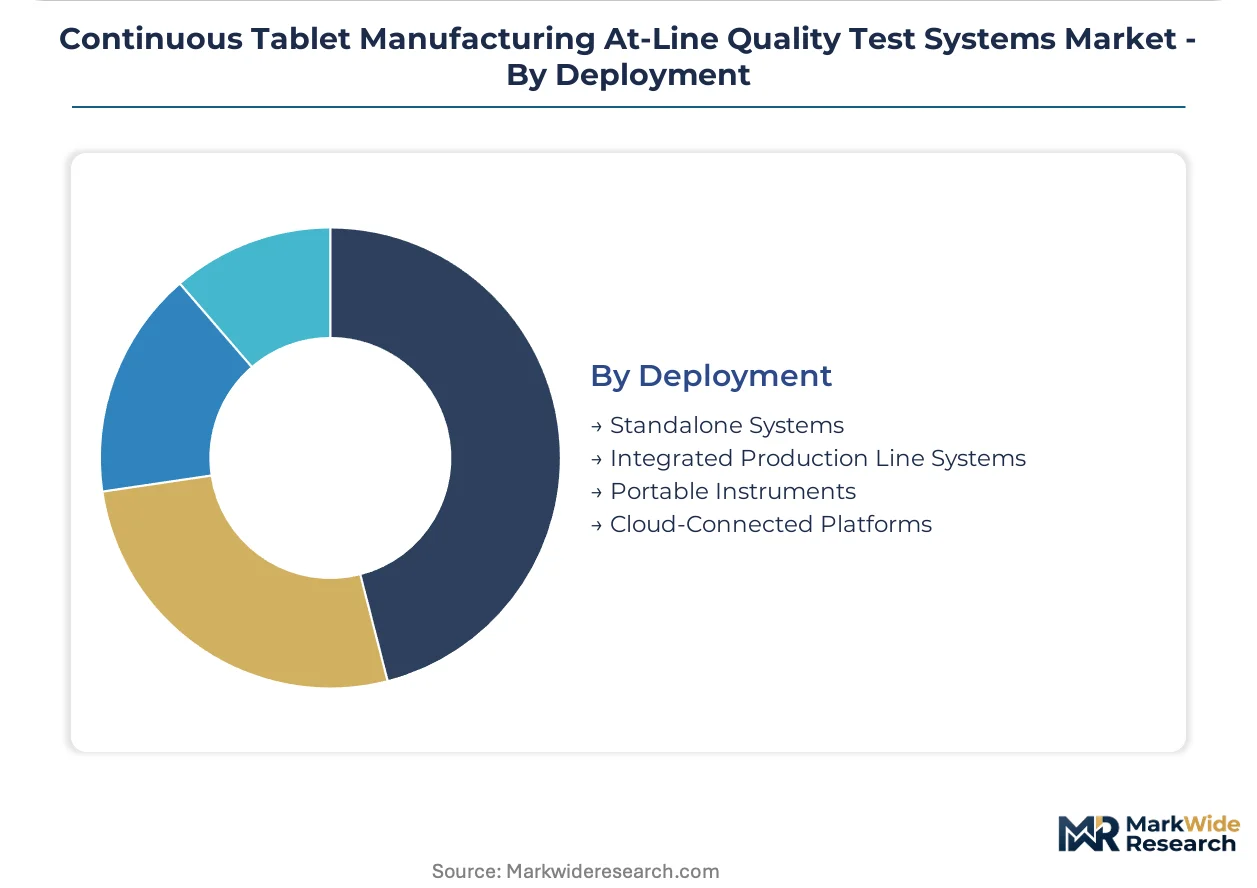
Deployment:
Maturity differentiation separates validated integrated architectures from emerging cloud-native platforms.
- Integrated Production Line Systems:Embedded sensors within Fette Compacting and Glatt continuous processing equipment reduce validation overhead compared with standalone retrofits. Equipment procurement patterns consolidate around these configurations as quality directors prioritize installation qualification and ongoing calibration support from single vendors.
- Cloud-Connected Platforms:Automated batch documentation with audit trail generation satisfies German national pharmaceutical regulator requirements. Indian pharmaceutical manufacturers under CDSCO oversight are beginning pilot programs utilizing these platforms for continuous process verification.
- Standalone Systems:Retrofit option for existing batch facilities with extensive validation documentation requirements.
- Portable Instruments:Limited deployment for troubleshooting and method transfer applications.
Integrated Production Line Systems carry the heaviest installed base. Cloud-Connected Platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemometricians and process analytical scientists concentrate in Basel, Boston, and Hyderabad, anchoring the geographic distribution of continuous manufacturing expertise.
United States
FDA Process Analytical Technology mandates drive pharmaceutical manufacturers toward real-time release testing architectures. The agency's Quality by Design framework compresses validation timelines for spectroscopic sensor deployment. Greater Boston hosts dense clusters of contract research organizations piloting hybrid Raman-NIR platforms for content uniformity applications.
Germany
The national pharmaceutical regulator enforces stringent batch documentation standards favoring cloud-connected platforms with automated audit trails. ICH Q13 implementation timelines accelerate retrofit investments in continuous processing equipment. North Rhine-Westphalia concentrates integrated production line engineering capabilities linking Fette Compacting hardware with at-line instrumentation.
Switzerland
Swissmedic documentation requirements for comprehensive critical quality attribute coverage elevate machine vision-spectroscopy hybrid adoption. Precision manufacturing heritage supports advanced spectroscopy integration for polymorph identification. Basel anchors pharmaceutical innovation clusters where real-time compression force adjustment based on API uniformity measurements is being commercialized.
India
CDSCO oversight is expanding pilot programs for continuous tablet manufacturing with at-line quality verification among export-oriented generic producers. The country's national pharmaceutical regulator is aligning inspection protocols with ICH Q13 guidance. Hyderabad and Ahmedabad host contract manufacturing organizations testing cloud-connected platforms for automated batch documentation.
United Kingdom
EMA's evolving ICH Q13 implementation creates regulatory friction that delays sensor qualification protocols at manufacturing sites. MHRA guidance on continuous process verification is stabilizing procurement patterns for integrated production line systems. Southeast England maintains research laboratory concentrations developing chemometric models for multinational pharmaceutical sponsors.
Continuous Tablet Manufacturing At-Line Quality Test Systems Market Competitive Landscape
The competitive structure tilts toward diversified analytical instrumentation conglomerates with spectroscopy portfolios. Three to five integrated production line engineering groups control interface architectures between manufacturing equipment and quality sensors. Two dominant competitive moves are emerging: backward integration into production line engineering by sensor vendors, and strategic partnerships between equipment manufacturers and cloud data integrity platforms.
Within the diversified instrumentation tier, Thermo Fisher Scientific and Bruker Corporation exemplify contrasting specialization vectors. Thermo Fisher Scientific leverages its spectroscopy breadth to anchor integrated at-line solutions. Bruker Corporation occupies a position emphasizing Raman and NIR precision for content uniformity applications. GEA Group represents the production line engineering archetype, controlling sensor-manufacturing equipment interfaces through backward integration into continuous processing hardware.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bruker Corporation |
| SOTAX Group |
| Fette Compacting |
| GEA Group |
| Siemens |
| Glatt |
| Endress+Hauser |
| Sensum |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical manufacturers' preference for single-source vendor accountability in North America is compressing supplier margins and forcing spectroscopy vendors to bundle calibration support with hardware sales. This procurement consolidation concentrates pricing power with integrated production line engineering groups while elevating total cost of ownership as the dominant purchasing criterion.
Pricing Analysis
Bundled service contracts versus unbundled instrument-only purchases define the pricing architecture across deployment tiers. Three-tier pricing structure across premium, standard, and economy levels separates integrated production line systems with full validation support from standalone retrofits and portable troubleshooting units. Price differentiation hinges on chemometric model development depth and FDA installation qualification documentation completeness. Cost compression in the standalone tier is intensifying because Indian and Southeast Asian manufacturers are qualifying lower-cost NIR platform suppliers. Contract manufacturing organizations exhibit highest price sensitivity due to flexible batch volumes, while Swiss and German pharmaceutical manufacturers prioritize premium tiers for regulatory inspection readiness.
Supply Chain Analysis
Dual-sourcing requirements embedded in FDA quality system regulations compel pharmaceutical manufacturers to qualify backup suppliers for critical spectroscopic components, fragmenting component procurement across vendors. Optical sensor manufacturing concentrates in Germany, Switzerland, and the United States, with grating and detector fabrication anchored in specialized photonics clusters. Raw material dependencies span high-purity optical substrates, semiconductor-grade InGaAs detectors, and rare-earth doped fiber for NIR sources. Single-source vulnerability persists in Fourier-transform interferometer assemblies where German and Swiss vendors control proprietary designs. Distribution runs through qualified system integrators who manage installation qualification and ongoing calibration support rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market has entered a late-cycle quality phase where pharmaceutical manufacturers now prioritize validated chemometric performance over raw instrument specifications. This specification shift favors vendors with backward integration into model development and cloud data integrity platforms.
For Market Incumbents: Anticipate margin compression from emerging hybrid Raman-NIR platform specialists by deepening captive supply of chemometric software and automated model maintenance services. Consolidation leverage exists in acquiring cloud data integrity platforms to satisfy German national pharmaceutical regulator documentation requirements. Threat substitution from machine vision-spectroscopy convergence demands accelerated R&D in real-time compression force feedback integration. For New Entrants and Emerging Players: Portable Raman platforms for polymorph identification present a technology-first wedge into contract manufacturing organizations in India and Southeast Asia. White-space concentration exists in cloud-connected platforms for CDSCO-oversight facilities piloting continuous manufacturing. Target research laboratories with standalone systems for method development as the lowest-barrier entry path before production line integration. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap spectroscopy specialists possessing validated pharmaceutical customer relationships but lacking production line engineering integration. Long-term viability over a five-to-ten year window rests on regulatory tailwind durability for real-time release testing adoption. Watch EMA ICH Q13 implementation timeline acceleration as the primary inflection signal for European retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chemometric Software | Captures recurring revenue from spectral model maintenance and revalidation cycles. |
| Cloud Data Integrity Platform Acquisition | Satisfies German national pharmaceutical regulator automated audit trail mandates. |
| Hybrid Raman-NIR Platform Development | Enables simultaneous polymorph identification and content uniformity verification. |
| Indian Market Pilot Program Partnership | Positions vendors for CDSCO-aligned continuous manufacturing adoption curves. |
| Machine Vision Integration Partnership | Addresses Swissmedic comprehensive critical quality attribute coverage requirements. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's pharmaceutical manufacturing clusters. Primary interviews with quality assurance directors, process analytical scientists, regulatory affairs leads, and contract manufacturing procurement officers were combined with secondary validation from FDA guidance documents, EMA ICH Q13 implementation updates, and national pharmaceutical regulator inspection protocols. Bottom-up triangulation against top-down market sizing was performed using equipment procurement databases and continuous processing line installation records.
Granularity-level modeling deployed separate forecast modules for spectroscopy technology type, deployment architecture, and end-user scale across the projection horizon. Segmentation dimensions included product type, application, end user, and deployment mode, with additional modeling for regional regulatory cluster variations. CAGRs were derived from regression analysis of historical adoption curves and regulatory mandate implementation schedules. Industry-specific inputs encompassed ICH Q13 guideline adoption timelines and EPA solvent emission regulation enforcement intensity.
The model holds under stable FDA Process Analytical Technology enforcement and gradual EMA ICH Q13 implementation; deviation in regulatory inspection intensity or accelerated CDSCO alignment with international standards would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Forensic Testing Services Market
Testing Services
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market
Testing Services
Global Specimen Validity Testing Market
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
Lipase Testing Reagents Market
Testing Services
North America Endotoxin and Pyrogen Testing Market
Testing Services
Nipah Virus (Niv) Infection Testing Market
Testing Services
Helicobacter Pylori Testing Market
Testing Services
Global Virology Testing Market
Testing Services
Global Newborn Screening Market
Testing Services
Global HPV Testing and Pap Test Market
Testing Services
Global Sleep Testing Services Market
Testing Services
Lab Screening Test Kit Market
Testing Services
Anderson Cascade Impactor Market
Testing Services
Toxicology Testing Services Market
Testing Services
Urodynamic Testing Market