
 Toxicology Drug Screening Market | 2026-2036
Toxicology Drug Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Toxicology Drug Screening Market Outlook
Project finance and equipment leasing for high-throughput mass spectrometry platforms is rewriting competitive entry barriers, allowing mid-sized laboratories to deploy capital-intensive confirmatory testing without balance-sheet strain. Laboratory Corporation of America Holdings anchors its position through captive patient-service center networks that control specimen collection logistics. Quest Diagnostics leverages its national account relationships with Fortune 500 employers to secure multi-year workplace testing contracts. Thermo Fisher Scientific dominates reagent supply through backward integration into consumables manufacturing.
Toxicology drug screening encompasses analytical methods and services designed to detect pharmaceutical compounds, illicit substances, and their metabolites in biological matrices, typically employing immunoassay presumptive testing followed by chromatographic confirmation at cutoff concentrations specified by regulatory guidelines. The primary commercial purpose spans employment compliance, forensic investigation, clinical overdose management, and sports anti-doping programs. Immunoassays occupy the highest volume tier in workplace and point-of-care settings where speed and cost efficiency outweigh specificity requirements. Mass spectrometry captures the premium margin pool in forensic and clinical reference laboratories where definitive quantitation and legal defensibility command price premiums. Bioanalytical services are expanding fastest among contract research organizations supporting pharmaceutical toxicokinetic studies for regulatory submission.
FDA oversight of in vitro diagnostic devices, SAMR registration requirements for imported assay kits in China, and the EU's In Vitro Diagnostic Regulation collectively shape product registration timelines, analytical performance claims, and market access pathways for manufacturers. OSHA workplace safety standards and DOT federal testing mandates in the United States directly determine panel configurations, cutoff thresholds, and chain-of-custody documentation that laboratories must maintain. Stakeholders must monitor how evolving state cannabis legislation fragments testing requirements across jurisdictions while synthetic opioid proliferation pressures laboratories to expand target compound menus without extending turnaround times.
Market Dynamics
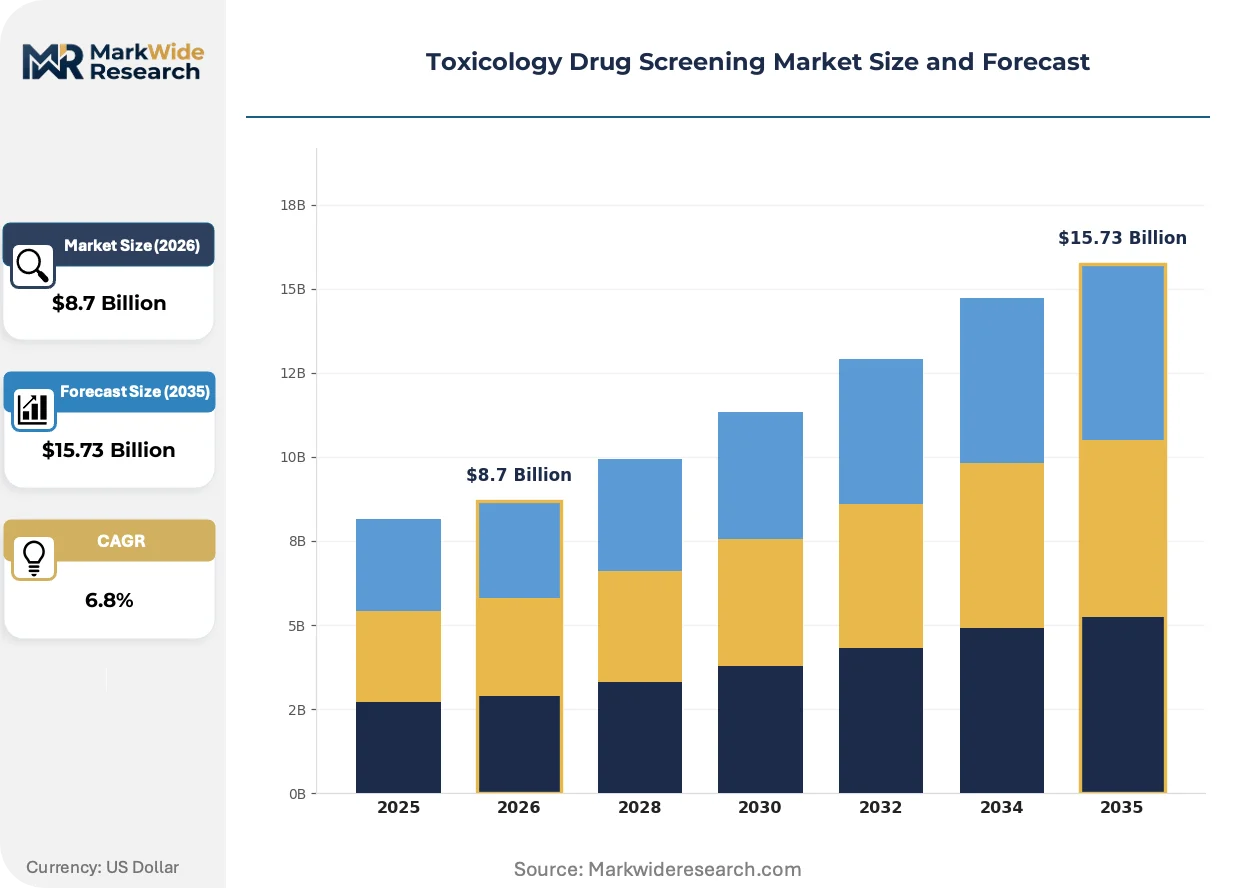
Mass spectrometry platform leasing is compressing capital barriers for mid-sized laboratories, enabling confirmatory testing deployment without balance-sheet strain while federal contractor mandates and state cannabis legalization fragment testing protocols across United States jurisdictions.
Growth Catalysts
- OSHA workplace safety standards:Manufacturing and logistics employers are expanding panel testing requirements to meet federal compliance thresholds, driving volume in industrial settings.
- Mass spectrometry throughput gains:High-resolution accurate mass platforms are reducing confirmatory testing turnaround times from days to hours in forensic reference laboratories.
- China SAMR registration pathways:Streamlined import procedures for in vitro diagnostic assay kits are accelerating commercial kit availability in the world's second-largest healthcare market.
Market Restraints
- Helium supply concentration:Mass spectrometry operations depend on helium carrier gas where United States federal reserve sales dominate global supply, creating input cost volatility.
- EU IVD-R analytical validation burden:Extended performance verification timelines for commercial assay kits are delaying product launches and freezing smaller manufacturers from European market access.
- Immunoassay specificity ceiling:Cross-reactivity with structural analogs limits presumptive testing reliability, forcing costly chromatographic confirmation for legally defensible results.
Strategic Opportunities
- Contract research organization expansion:Pharmaceutical toxicokinetic studies for regulatory submission represent underpenetrated demand within bioanalytical services.
- Point-of-care oral fluid testing:Non-invasive specimen collection is displacing urine-based protocols in pre-employment screening across United States transportation and warehousing sectors.
- Synthetic opioid panel expansion:Fentanyl analog proliferation is mandating broader compound menus without turnaround time extension, favoring laboratories with flexible mass spectrometry methods.
Industry Challenges
- Mass spectrometry operator scarcity:Clinical laboratories face acute recruitment pressure for analytical chemists capable of method development and regulatory documentation.
- Chain-of-custody system integration:Electronic documentation platforms must interface with legacy laboratory information management systems without compromising legal admissibility standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toxicology Drug Screening Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassays, Chromatography, Mass Spectrometry, Bioanalytical Services Sample Type: Urine, Blood, Saliva, Hair End User: Laboratories, Hospitals, Rehabilitation Centers, Research Institutions Test Method: Rapid Testing, Confirmatory Testing, Point-of-Care Testing, Laboratory Testing |
| Companies Covered | Laboratory Corporation of America Holdings, Quest Diagnostics Incorporated, Thermo Fisher Scientific Inc., Abbott Laboratories, Danaher, Agilent Technologies, Inc, Bio-Rad Laboratories, Inc, Eurofins Scientific, OraSure Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toxicology Drug Screening Market Strategic Shifts
Artificial intelligence is penetrating analytical interpretation workflows, cloud-based data management is restructuring laboratory connectivity, and specimen collection logistics are fragmenting as decentralized testing models gain regulatory traction.
Liquid chromatography-tandem mass spectrometry is digitizing confirmatory testing workflows through automated peak integration and machine-learning-assisted compound identification. Clinical reference laboratories in the United States are adopting these platforms at accelerating replacement cycles, compressing the technical labor component of high-complexity testing while elevating throughput capacity for forensic casework.
The EU In Vitro Diagnostic Regulation is elevating analytical validation standards for commercial immunoassay kits, mandating extended clinical performance studies that smaller manufacturers cannot fund. European reference laboratories are responding by consolidating kit procurement around established suppliers with captive regulatory affairs capabilities, narrowing the vendor base for presumptive screening reagents.
Employer self-collection models are disrupting third-party collection site networks as oral fluid testing devices receive regulatory clearance for unsupervised specimen acquisition. Transportation and logistics employers in the United States are piloting direct-to-laboratory shipping protocols, eliminating collection site fees while compressing screening program administrative overhead.
Toxicology Drug Screening Market Segmentation
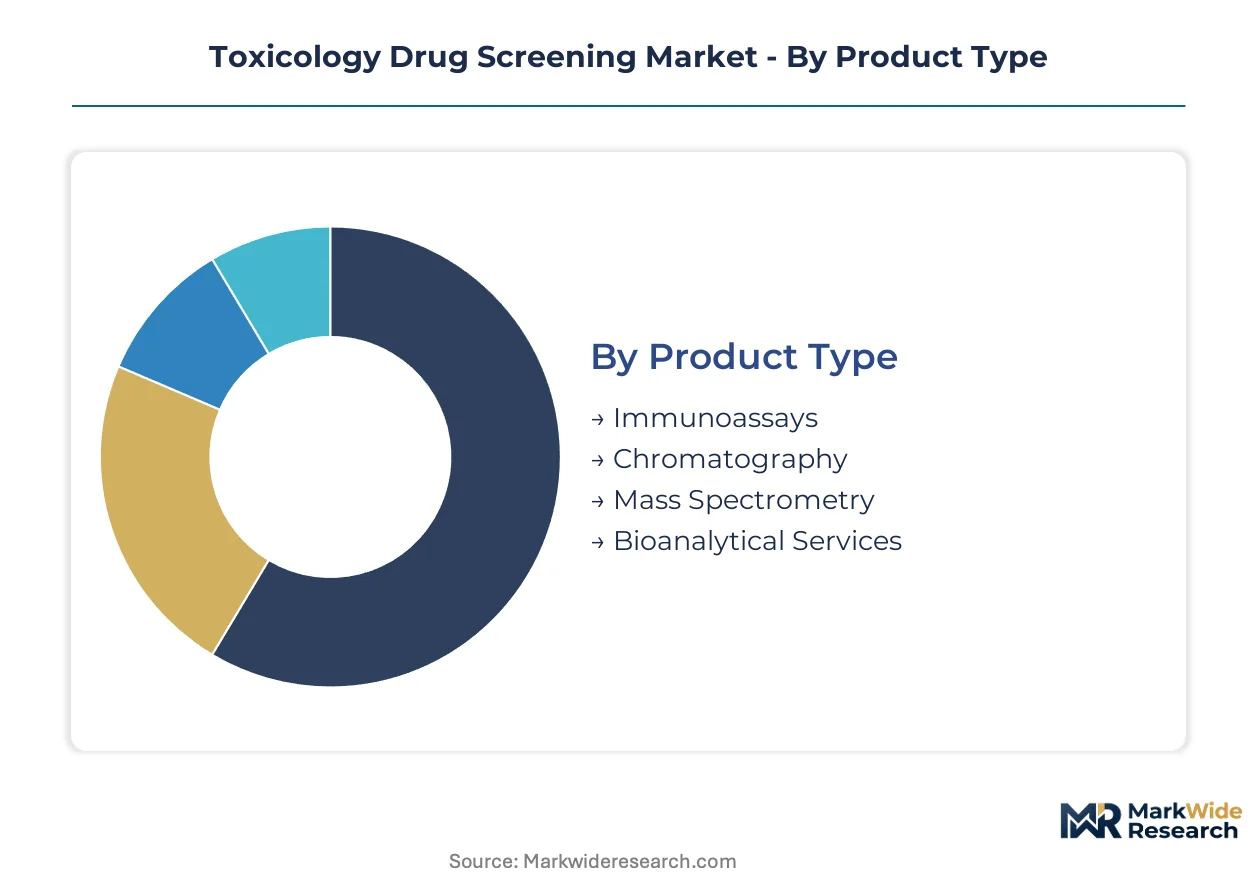
Technology selection in toxicology screening hinges on turnaround requirements, legal defensibility standards, and specimen matrix characteristics. Each segment category exhibits distinct procurement cycles, with some platforms turning over in 3-5 years while others persist for 15+ years in validated laboratory workflows.
Product Type:
Replacement cycles vary dramatically: immunoassay analyzers refresh fastest at 4-6 years while mass spectrometry platforms extend 10-15 years with incremental source and detector upgrades.
- Immunoassays:Enzyme-mediated competitive binding assays deliver presumptive results within minutes using antibody-antigen specificity for common drug classes. Workplace screening programs in United States manufacturing and logistics sectors deploy these at highest volume, though cross-reactivity with structural analogs forces costly chromatographic confirmation for legally defensible employment actions.
- Mass Spectrometry:High-resolution accurate mass platforms separate and identify compounds based on mass-to-charge ratios with definitive quantitation capabilities. Forensic reference laboratories and clinical toxicology services concentrate investment here, where federal contractor mandates and state cannabis legalization fragment protocols across jurisdictions and demand flexible method expansion.
- Chromatography:Gas and liquid chromatography systems separate complex biological matrices prior to detection, typically coupled with mass spectrometry for confirmatory workflows.
- Bioanalytical Services:Contract laboratory capabilities supporting pharmaceutical toxicokinetic studies for regulatory submission represent specialized demand with extended study timelines.
Immunoassays dominate installed base across workplace and point-of-care settings. Mass spectrometry is where expansion concentrates as laboratories upgrade confirmatory capacity.
Sample Type:
Collection logistics and detection windows shape procurement patterns, with urine maintaining lowest per-test cost and oral fluid gaining fastest regulatory traction for non-invasive protocols.
- Urine:The standard matrix for federally regulated workplace testing programs offers extended detection windows for most drug classes and established chain-of-custody protocols. United States DOT-mandated testing and OSHA-compliant industrial programs drive sustained volume, though observed collection requirements add administrative overhead and privacy concerns.
- Saliva:Oral fluid collection eliminates bathroom facilities and gender-specific observation protocols, enabling employer self-collection models. Transportation and warehousing employers in United States jurisdictions pilot direct-to-laboratory shipping, eliminating third-party collection site fees while compressing program administration.
- Blood:Invasive venipuncture limits application to clinical overdose management and forensic impairment investigations where recent exposure confirmation is critical.
- Hair:Keratin-incorporated metabolites provide 90-day retrospective detection windows, serving forensic and legal markets with low turnaround urgency.
Urine captures the highest test volume across regulated workplace programs. Saliva is climbing fastest as oral fluid devices gain FDA clearance for unsupervised collection.
End User:
Capital intensity and regulatory compliance requirements separate institutional buyers, with reference laboratories investing most heavily in multi-platform confirmatory infrastructure.
- Laboratories:Independent and hospital-affiliated reference laboratories perform the majority of federally mandated and forensic testing, requiring CAP accreditation and SAMHSA certification for defensible results.
- Hospitals:Emergency departments and clinical toxicology services require rapid turnaround for overdose management, balancing speed against definitive identification needs.
- Rehabilitation Centers:Treatment monitoring programs demand frequent, cost-effective screening with flexible panel configurations tailored to patient history.
- Research Institutions:Academic and pharmaceutical research laboratories drive demand for bioanalytical method development and validation services.
Laboratories command the largest equipment procurement budgets. Rehabilitation centers represent the steepest expansion trajectory as substance use treatment access expands.
Test Method:
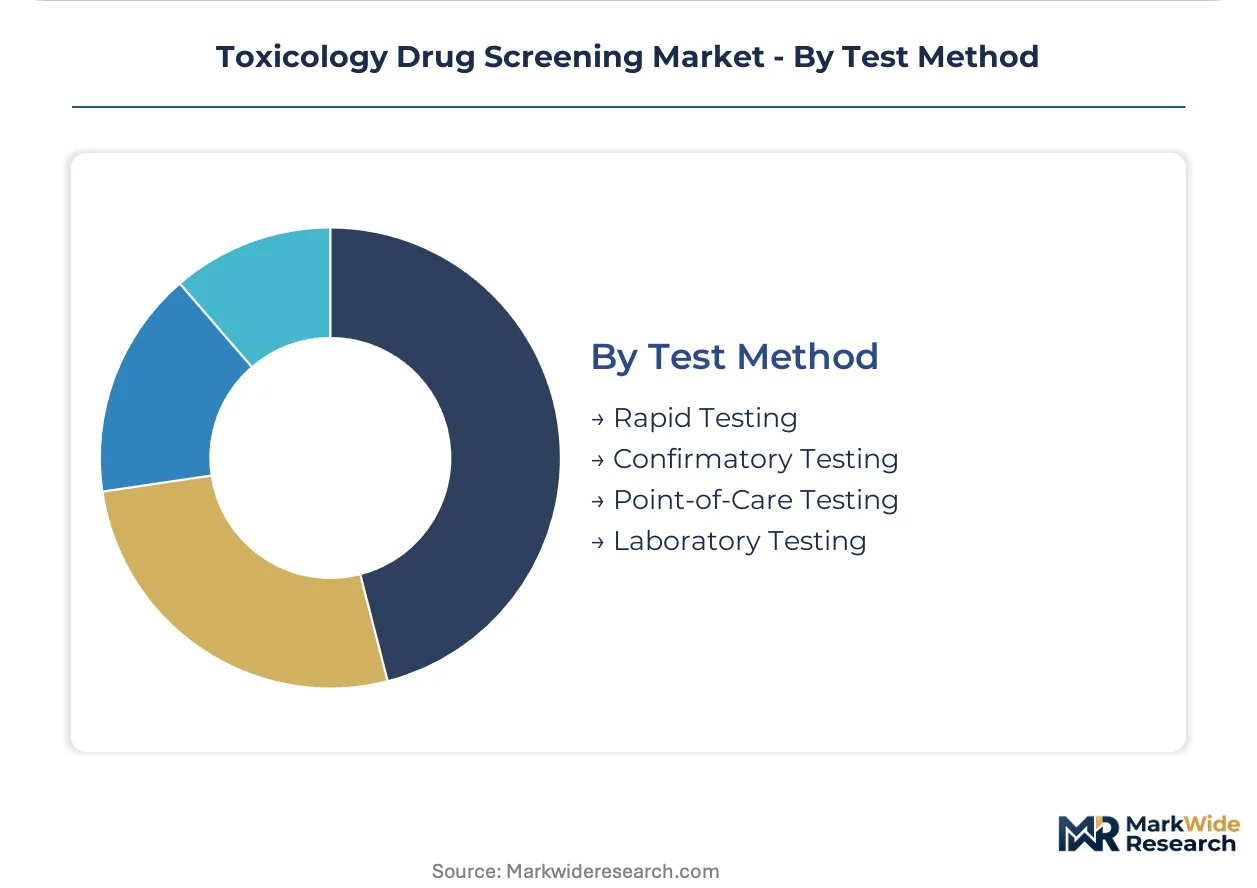
Speed-versus-certainty tradeoffs segment procurement, with rapid testing serving immediate decision needs and confirmatory testing reserved for contested or high-stakes outcomes.
- Rapid Testing:Lateral flow and handheld immunoassay devices deliver presumptive results at the point of collection, serving pre-employment and random screening programs with same-day hiring decisions.
- Confirmatory Testing:Chromatographic and mass spectrometric methods provide legally defensible quantitative results with metabolite identification, mandatory for contested federal workplace tests and forensic proceedings.
- Point-of-Care Testing:CLIA-waived devices enable non-laboratory settings to perform waived complexity testing, expanding access in occupational health clinics and correctional facilities.
- Laboratory Testing:Centralized high-complexity processing captures economies of scale for high-volume screening programs with standardized panel configurations.
Confirmatory testing commands premium pricing per sample. Point-of-care testing is gaining share fastest as regulatory clearance expands permissible settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in toxicology drug screening equipment and reagents tilt heavily toward import-dependent regions, with the United States and Germany running structural deficits in mass spectrometry components while China and India expand domestic assay kit manufacturing capacity.
United States
Federal contractor mandates and state-level cannabis legalization create dual-track screening protocols across jurisdictions. OSHA workplace safety standards and DOT federal testing mandates determine panel configurations and cutoff thresholds. Reference laboratories in North Carolina and California concentrate confirmatory testing capacity for Fortune 500 employer programs.
Germany
Industrial employers in automotive and chemical manufacturing expand workplace panel testing to meet federal compliance thresholds. The EU In Vitro Diagnostic Regulation elevates analytical validation standards for commercial assay kits. Forensic laboratories in Baden-Württemberg and Bavaria deploy high-resolution mass spectrometry for legally defensible employment actions.
China
Domestic pharmaceutical toxicokinetic studies drive demand for bioanalytical services supporting regulatory submission. SAMR registration requirements for imported assay kits shape market access pathways for foreign manufacturers. Contract research organizations in Shanghai and Suzhou build captive mass spectrometry capacity for multinational drug development programs.
India
Substance use treatment access expansion fuels rehabilitation center screening program growth. CDSCO oversight of in vitro diagnostic devices governs product registration timelines for commercial kit manufacturers. Bioanalytical service providers in Hyderabad and Bangalore capture outsourcing demand from European and North American pharmaceutical sponsors.
United Kingdom
Forensic science services and clinical toxicology departments upgrade confirmatory testing infrastructure. The Medicines and Healthcare products Regulatory Agency oversees device performance claims for point-of-care screening devices. Reference laboratories in London and Manchester consolidate procurement around established immunoassay suppliers with captive regulatory affairs capabilities.
Toxicology Drug Screening Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers: national laboratory networks controlling specimen collection logistics, diversified life science conglomerates dominating reagent supply through backward integration into consumables manufacturing, and specialized diagnostic device manufacturers capturing point-of-care regulatory clearances. Competitive dynamics center on multi-year workplace testing contract capture and mass spectrometry platform leasing arrangements that compress capital barriers for mid-sized laboratories.
Within the national laboratory network tier, Laboratory Corporation of America Holdings and Quest Diagnostics exemplify scale-driven service consolidation. Thermo Fisher Scientific occupies a position as the anchor reagent supplier with integrated consumables manufacturing. These three entities represent the dominant competitive archetypes: captive logistics control, national account relationship leverage, and upstream supply integration.
| Leading Market Players |
|---|
| Laboratory Corporation of America Holdings |
| Quest Diagnostics Incorporated |
| Thermo Fisher Scientific Inc. |
| Abbott Laboratories |
| Danaher |
| Agilent Technologies, Inc |
| Bio-Rad Laboratories, Inc |
| Eurofins Scientific |
| OraSure Technologies, Inc. |
| Others |
Value Chain & Pricing Dynamics
Helium reserve concentration in the United States federal system anchors input cost volatility for mass spectrometry operations, compressing margin pools at forensic reference laboratories while elevating pricing power for reagent suppliers with captive consumables manufacturing.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in toxicology screening. Premium tiers attach to high-resolution accurate mass platforms with SAMHSA certification, while economy tiers serve CLIA-waived point-of-care devices. Price differentiation hinges on analytical specificity grade and after-sales service bundling. Cost compression in presumptive immunoassay kits is intensifying because of EU IVD-R compliance investments. Rehabilitation centers exhibit highest price sensitivity; federal contractor testing programs show lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for diagnostic assay kit procurement. Manufacturing concentrates in the United States, Germany, and China for mass spectrometry platforms, reagent production, and consumables assembly respectively. Raw material dependencies span helium carrier gas, high-purity solvents, and antibody reagents. Single-source vulnerability persists for helium feedstock from the United States federal reserve. Distribution runs through national laboratory networks with captive specimen collection logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Toxicology drug screening sits in early-cycle expansion as oral fluid testing gains FDA clearance for unsupervised collection, unlocking employer self-collection models across transportation and logistics sectors.
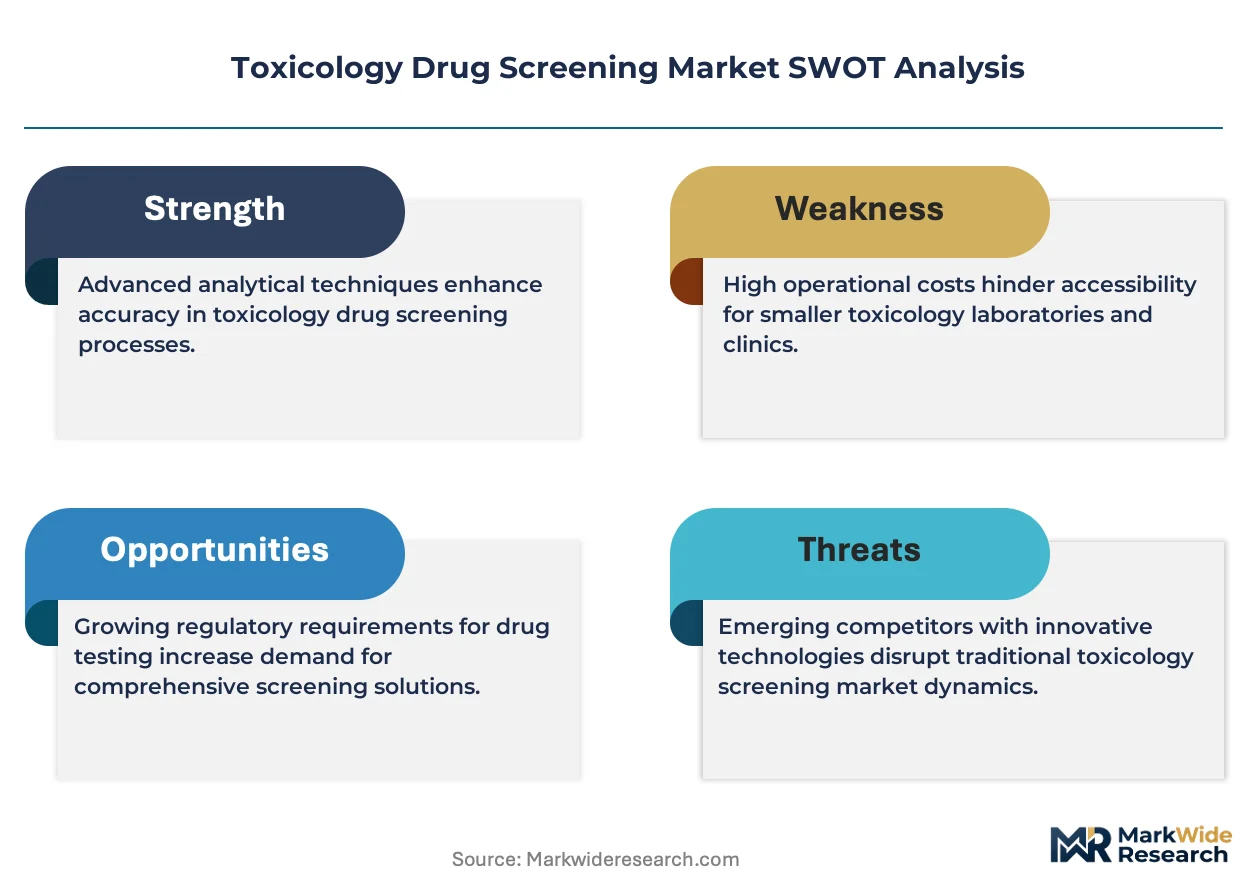
For Market Incumbents: Build regulatory certification moats by securing EU IVD-R compliance for immunoassay kits and SAMHSA certification for confirmatory methods. Incumbent laboratories should deepen backward integration into consumables manufacturing to offset reagent cost volatility, while expanding captive patient-service center networks to lock in Fortune 500 national accounts against emerging CRO competitors. For New Entrants and Emerging Players: Mid-sized independent laboratories in United States states with fragmented cannabis legalization protocols represent the most penetrable entry point for mass spectrometry platform leasing. New entrants should target contract research organization toxicokinetic services for pharmaceutical sponsors, leveraging streamlined SAMR registration pathways to access Chinese bioanalytical demand. Direct-to-laboratory oral fluid shipping protocols offer a defensible go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward specialized diagnostic device manufacturers with point-of-care regulatory clearances and captive mass spectrometry capacity in high-growth jurisdictions. Long-term viability over the next decade rests on synthetic opioid panel flexibility and AI-integrated analytical interpretation. The signal to watch is employer migration from urine-based to oral fluid protocols as a penetration inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Mass Spectrometry Platform Leasing | Compresses capital barriers for mid-sized laboratories seeking confirmatory testing capacity without balance-sheet strain. |
| EU IVD-R Compliance Investment | Freezes smaller manufacturers from European market access while consolidating procurement around established suppliers. |
| Oral Fluid Device FDA Clearance | Enables employer self-collection models that eliminate third-party collection site fees in transportation sectors. |
| Synthetic Opioid Panel Expansion | Fentanyl analog proliferation mandates broader compound menus favoring laboratories with flexible LC-MS/MS methods. |
| AI-Assisted Peak Integration | Automated interpretation workflows compress technical labor components while elevating forensic casework throughput. |
Study Parameters
A standing panel of clinical laboratory directors, regulatory affairs specialists at IVD manufacturers, forensic toxicologists, and employer occupational health managers provided ongoing calibration. Primary fieldwork combined structured interviews with these stakeholders and secondary validation against FDA 510(k) filings, SAMHSA certification records, EU IVD-R technical documentation, and OSHA workplace safety standards. Bottom-up equipment installation data and top-down healthcare expenditure estimates were triangulated to anchor market sizing.
Scenario-bracketing framed the analytical approach across the projection horizon, with volume and value outputs reflecting segmentation by technology platform, specimen matrix, end-user institution type, and test method complexity. CAGRs were derived from equipment replacement cycle analysis and testing volume elasticity to regulatory mandate expansion. Industry-specific inputs included mass spectrometry throughput gains, oral fluid device regulatory clearance timelines, and synthetic opioid analog proliferation rates.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement policy, helium commodity pricing, or cross-border trade friction would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Syphilis Testing Market
Testing Services
Biological Safety Testing Products and Services Market
Testing Services
Legionnaire Disease Testing Market
Testing Services
US & Europe Extractable and Leachable Testing Services Market
Testing Services
Pancreatic Elastase Testing Market
Testing Services
Mycological Testing Market
Testing Services
Global Legionella Testing Market
Testing Services
At-Home Testing Market
Testing Services
Instrument Calibration Services Market
Testing Services
Drug Screening Laboratory Service Market
Testing Services
CRO Mass Spectroscopy Services Market
Testing Services
United States Esoteric Testing Market
Testing Services
United States Hospital Acquired Disease Testing Market
Testing Services
Medical Device Analytical Testing Outsourcing Market
Testing Services
Global Immunoprecipitation Testing Market
Testing Services
Hemotransmissive Infections Testing Market