
 Europe Antimicrobial Susceptibility Testing Market | 2026-2036
Europe Antimicrobial Susceptibility Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Antimicrobial Susceptibility Testing Market Foresight
Germany's diagnostic manufacturing corridor is reshaping supply dynamics for antimicrobial susceptibility testing across Europe. bioMérieux SA leverages its automated systems portfolio to anchor high-throughput hospital contracts in Western Europe. Thermo Fisher Scientific Inc competes through integrated molecular workflows that extend from sample prep to resistance gene detection. Danaher Corporation differentiates via phenotypic platform specialization that sustains recurring consumable revenue streams.
Antimicrobial susceptibility testing encompasses laboratory methods that determine bacterial response to specific antimicrobial agents, employing disk diffusion zones, minimum inhibitory concentration thresholds, or mass spectrometry protein profiling to guide therapeutic selection. Automated systems now dominate capital procurement in European hospitals due to throughput demands and staffing constraints, while molecular methods capture fastest-growing adoption as resistance gene detection requirements expand beyond traditional culture-based workflows. Phenotypic methods retain volume leadership in smaller diagnostic labs where infrastructure investment remains limited.
EMA device oversight and the EU MDR framework elevate clinical evidence requirements for AST system approvals, compressing timelines for manufacturers seeking CE-marked placement. The EU Green Deal chemical restrictions and REACH substance regulations increasingly influence reagent composition decisions, particularly for chromogenic media formulations. Stakeholders must monitor evolving EUCAST breakpoint revisions and national AMR action plans that reshape testing protocols and reimbursement eligibility across member states.
Market Dynamics
EU MDR compliance deadlines and EUCAST breakpoint revisions are compressing equipment replacement cycles across European clinical diagnostics, forcing laboratories to accelerate capital expenditure timelines while simultaneously retraining staff on new protocols.
Growth Catalysts
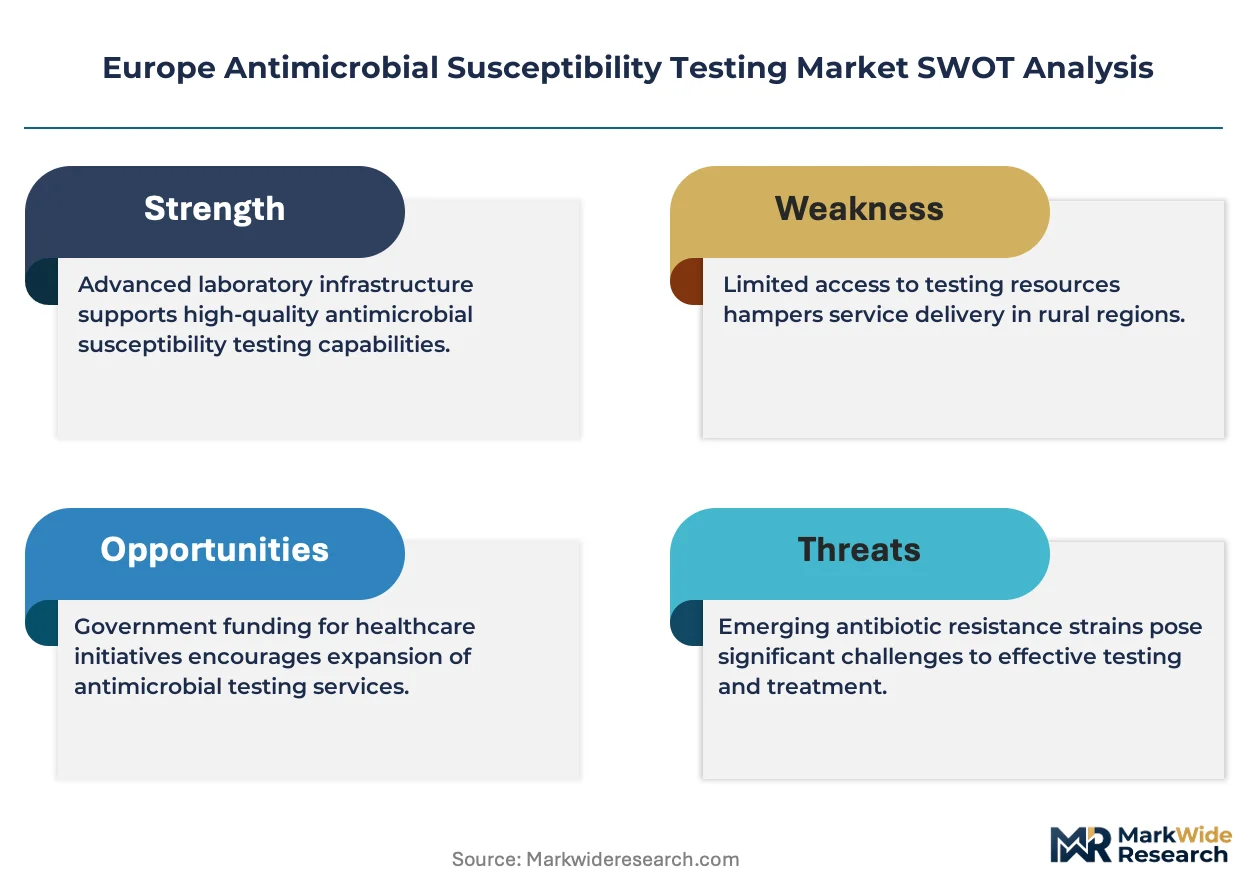
- EU Green Deal chemical restrictions:REACH substance regulations are accelerating reagent reformulation investments, creating replacement demand for chromogenic media and antimicrobial panels that meet tightened environmental standards.
- Hospital consolidation in Germany:Centralized laboratory networks in North Rhine-Westphalia and Bavaria are aggregating testing volumes, driving procurement of high-throughput automated systems that serve multiple facilities.
- Molecular resistance gene detection:Carbapenemase and ESBL screening mandates are expanding beyond reference laboratories into routine hospital workflows, pulling adoption of PCR and mass spectrometry platforms.
Market Restraints
- CE marking timeline compression:EU MDR clinical evidence requirements have extended device approval durations by 12-18 months, freezing new entrant market access and concentrating share among established manufacturers with notified body relationships.
- Reagent supply concentration:Chromogenic media production clusters in southern Germany and northern France create geographic vulnerability to single-source dependencies for critical susceptibility testing consumables.
- Culture-based workflow persistence:Smaller diagnostic laboratories in Portugal, Greece, and eastern European member states lack infrastructure capital for automated platform migration, capping addressable market expansion.
Strategic Opportunities
- Poland and Romania hospital modernization:EU cohesion fund allocations for healthcare infrastructure are financing first-time automated AST system installations in regional laboratories previously dependent on manual disk diffusion.
- Integrated antimicrobial stewardship software:Convergence of susceptibility testing data with pharmacy information systems and electronic health records is creating bundled platform opportunities that extend vendor relationships beyond hardware.
- National AMR action plan procurement mandates:France's 2022-2025 national strategy and the UK's five-year action plan are embedding resistance surveillance requirements into hospital accreditation standards, mandating testing capability expansion.
Industry Challenges
- Clinical microbiologist workforce scarcity:Training program contraction across Spain, Italy, and the United Kingdom has created personnel bottlenecks that limit laboratory throughput expansion regardless of equipment capacity.
- EUCAST breakpoint implementation lag:National reference laboratories in Belgium, the Netherlands, and Nordic member states operate on asynchronous revision adoption schedules, fragmenting standardization and complicating multi-site laboratory network compliance.
- Legacy system integration complexity:Hospital information system heterogeneity in the United Kingdom's NHS trusts and Germany's fragmented hospital landscape impedes seamless data flow from new AST platforms to centralized surveillance databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Antimicrobial Susceptibility Testing Market |
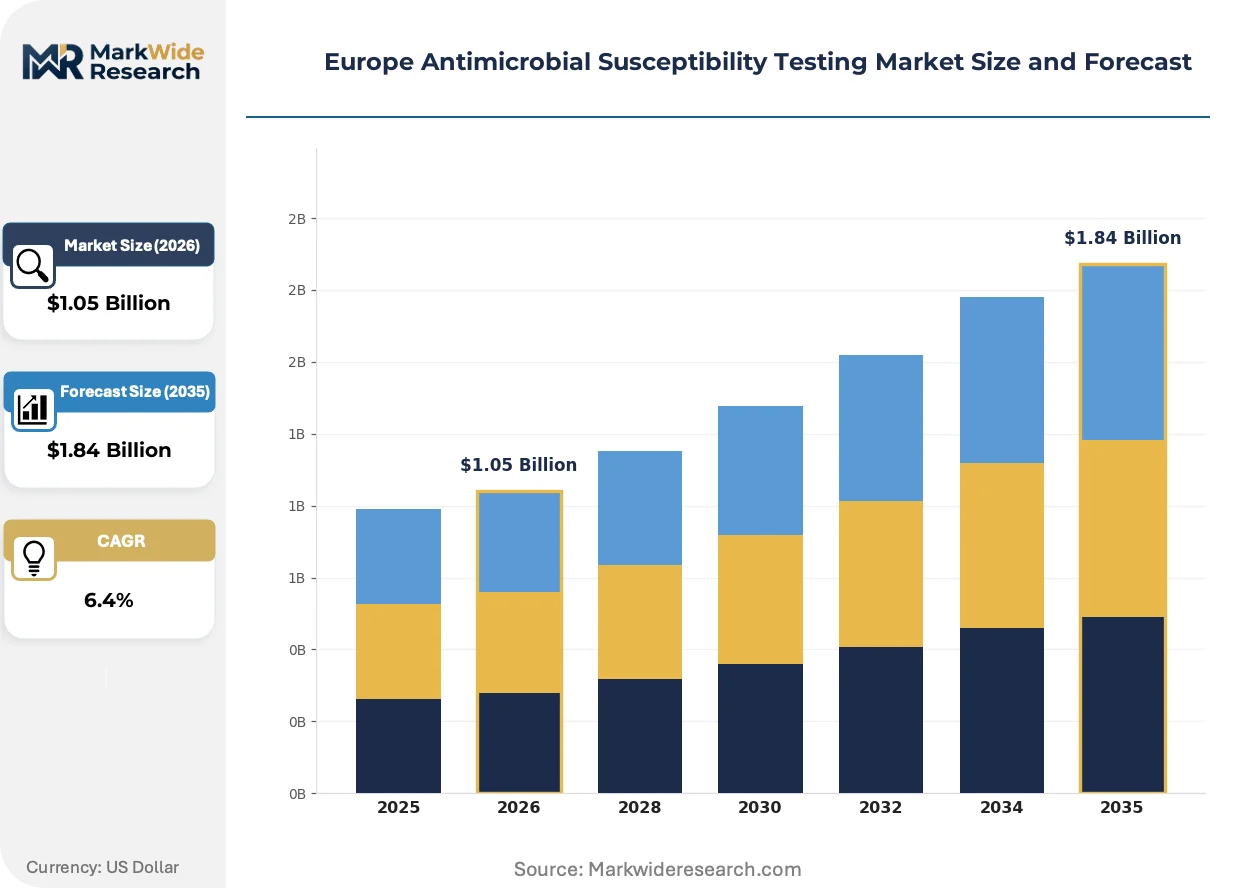
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disk Diffusion, Broth Dilution, E-Test, Automated Systems Application: Clinical Diagnostics, Research Laboratories, Pharmaceutical Industry, Veterinary End User: Hospitals, Diagnostic Labs, Academic Institutions, Contract Research Organizations Technology: Molecular Methods, Phenotypic Methods, Genotypic Methods, Mass Spectrometry |
| Companies Covered | bioMérieux SA, Thermo Fisher Scientific Inc, Becton Dickinson and Company, Danaher Corporation, Bio-Rad Laboratories Inc, Merck KGaA, HiMedia Laboratories, Alifax S.r.l., Liofilchem S.r.l., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Antimicrobial Susceptibility Testing Market Shifts & Advancements
Digital pathology interfaces and artificial intelligence-assisted zone reading are compressing turnaround times for susceptibility results, while regulatory pressure on chemical reagents accelerates reformulation investments across the supply base.
Mass spectrometry-based microbial identification paired with automated susceptibility testing is digitizing resistance profiling workflows in large European reference laboratories. University hospital networks in Heidelberg, Paris, and London have adopted integrated MALDI-TOF AST platforms that eliminate manual colony picking and accelerate result generation. This convergence is digitizing the traditional microbiology workflow, compressing the interval between sample receipt and therapeutic guidance from 48-72 hours toward same-day reporting.
EU MDR Article 10 clinical evaluation requirements and post-market surveillance obligations are elevating documentation burdens for AST device manufacturers seeking CE-marked placement. The regulation mandates systematic literature reviews and clinical performance studies that smaller diagnostic companies lack resources to execute, producing consolidation pressure among notified bodies and extending approval timelines. Western European manufacturers with established quality management systems are absorbing these compliance costs into premium pricing, while eastern European and mid-cap competitors face market access barriers.
Hospital procurement departments are unbundling service contracts from capital equipment purchases, separating preventive maintenance, reagent supply, and software updates into competitively tendered standalone agreements. Nordic hospital procurement consortiums in Sweden, Denmark, and Norway have pioneered this disaggregation, using framework agreements to benchmark service pricing across multiple vendors. This behavioral shift is most visible in the United Kingdom's NHS Supply Chain and Germany's university hospital purchasing cooperatives, where total cost of ownership modeling now dominates capital allocation decisions over upfront equipment pricing.
Europe Antimicrobial Susceptibility Testing Market Segmentation
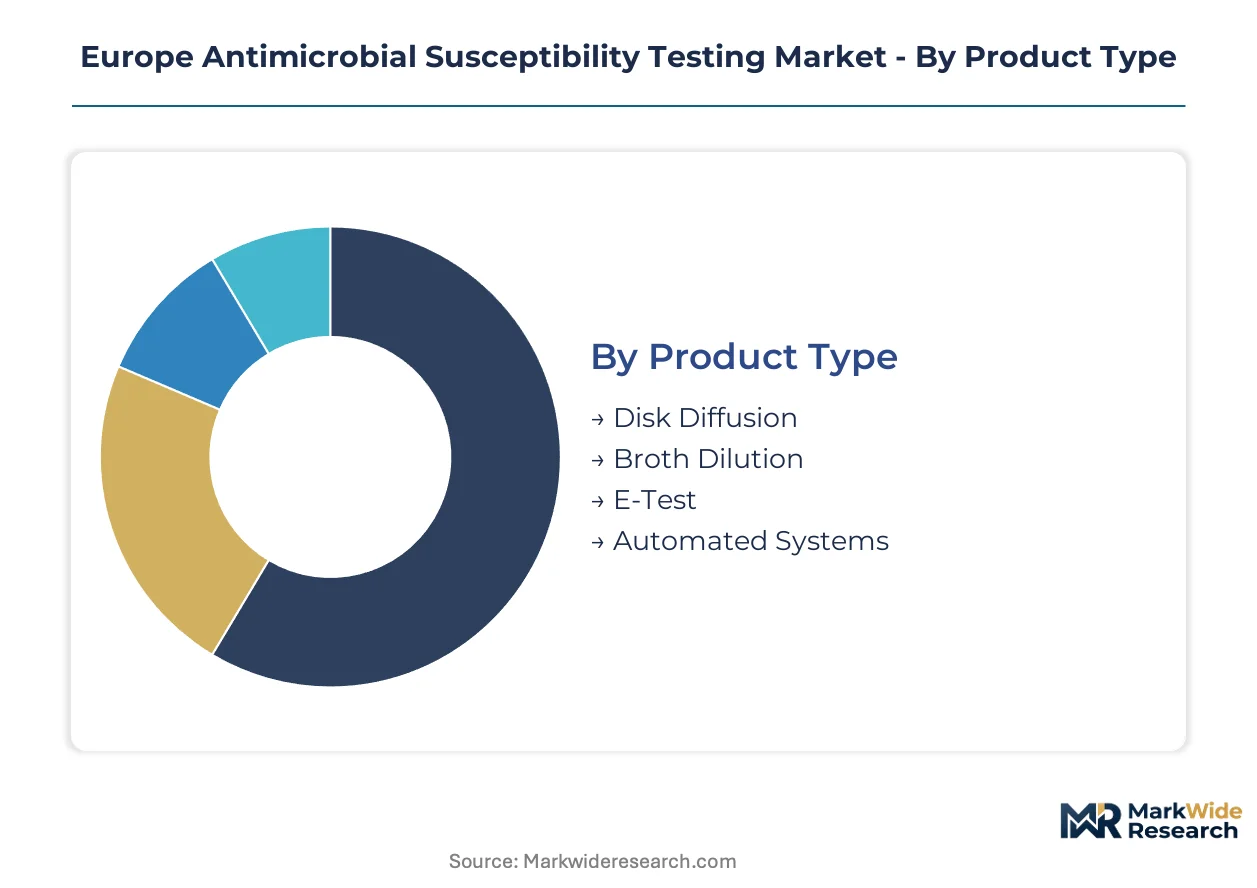
AST procurement patterns across Europe fragment sharply by infrastructure maturity and resistance surveillance mandates. Testing modality selection tracks directly to laboratory capital budgets, regulatory reporting obligations, and the prevalence of multidrug-resistant organisms in catchment populations.
Product Type:
Cost tier stratification determines equipment penetration across European healthcare systems, with capital intensity creating distinct procurement clusters between automated and manual platforms.
- Automated Systems:Integrated walk-away platforms process hundreds of samples daily with minimal technologist intervention. Hospital networks in Germany's North Rhine-Westphalia and Bavaria regions deploy these systems across consolidated laboratory hubs serving multiple facilities under single management.
- Disk Diffusion:Manual Kirby-Bauer methodology requires trained microbiologists to measure inhibition zones against standardized charts. Diagnostic laboratories in Portugal, Greece, and eastern European member states retain this approach where infrastructure investment remains constrained by reimbursement ceilings.
- Broth Dilution:Macro and micro-dilution protocols establish minimum inhibitory concentration values through visual or photometric endpoint detection. Reference laboratories employ these methods for breakpoint validation and quality control.
- E-Test:Gradient diffusion strips deliver quantitative MIC results on agar plates without specialized instrumentation. Smaller hospital laboratories in France and Italy utilize E-Test for targeted resistance confirmation.
Automated Systems holds installed capacity. E-Test is rotating up the share rankings.
Application:
Customer type concentration varies by the stringency of resistance surveillance requirements embedded in national accreditation standards.
- Clinical Diagnostics:Hospital-based microbiology laboratories process bloodstream, respiratory, and urinary isolates for therapeutic guidance. France's national AMR action plan and the UK's five-year strategy mandate expanded testing capability in acute care settings.
- Research Laboratories:Academic medical centers in Heidelberg, Paris, and London conduct resistance mechanism characterization and novel agent evaluation. EU cohesion fund allocations increasingly support antimicrobial resistance research infrastructure.
- Pharmaceutical Industry:Contract testing organizations support clinical trial antimicrobial efficacy endpoints and resistance surveillance for new molecular entities. EMA device oversight elevates documentation burdens for supporting laboratory qualification.
- Veterinary:Livestock and companion animal diagnostic laboratories monitor resistance in zoonotic pathogens under EU Green Deal chemical restrictions and REACH substance regulations.
Clinical Diagnostics anchors volume concentration. Research Laboratories is climbing the fastest as EU funding priorities shift.
End User:
Volume distribution across customer categories reflects the consolidation trajectory of European healthcare delivery and the outsourcing of specialized testing.
- Hospitals:Acute care institutions maintain 24-hour microbiology coverage for sepsis management and surgical prophylaxis optimization. University hospital purchasing cooperatives in Germany and NHS Supply Chain in the United Kingdom dominate capital procurement aggregation.
- Diagnostic Labs:Independent and hospital-affiliated reference laboratories handle overflow testing and specialized resistance profiling. Nordic hospital procurement consortiums in Sweden, Denmark, and Norway benchmark service pricing across multiple vendors.
- Academic Institutions:Medical school microbiology departments train workforce personnel while conducting resistance surveillance research. Training program contraction across Spain, Italy, and the United Kingdom has created personnel bottlenecks.
- Contract Research Organizations:Specialized service providers execute antimicrobial development studies under GLP and GMP frameworks. EUCAST breakpoint implementation lag fragments standardization across multi-site study networks.
Hospitals command the dominant share. Diagnostic Labs is gaining share fastest through network consolidation.
Technology:
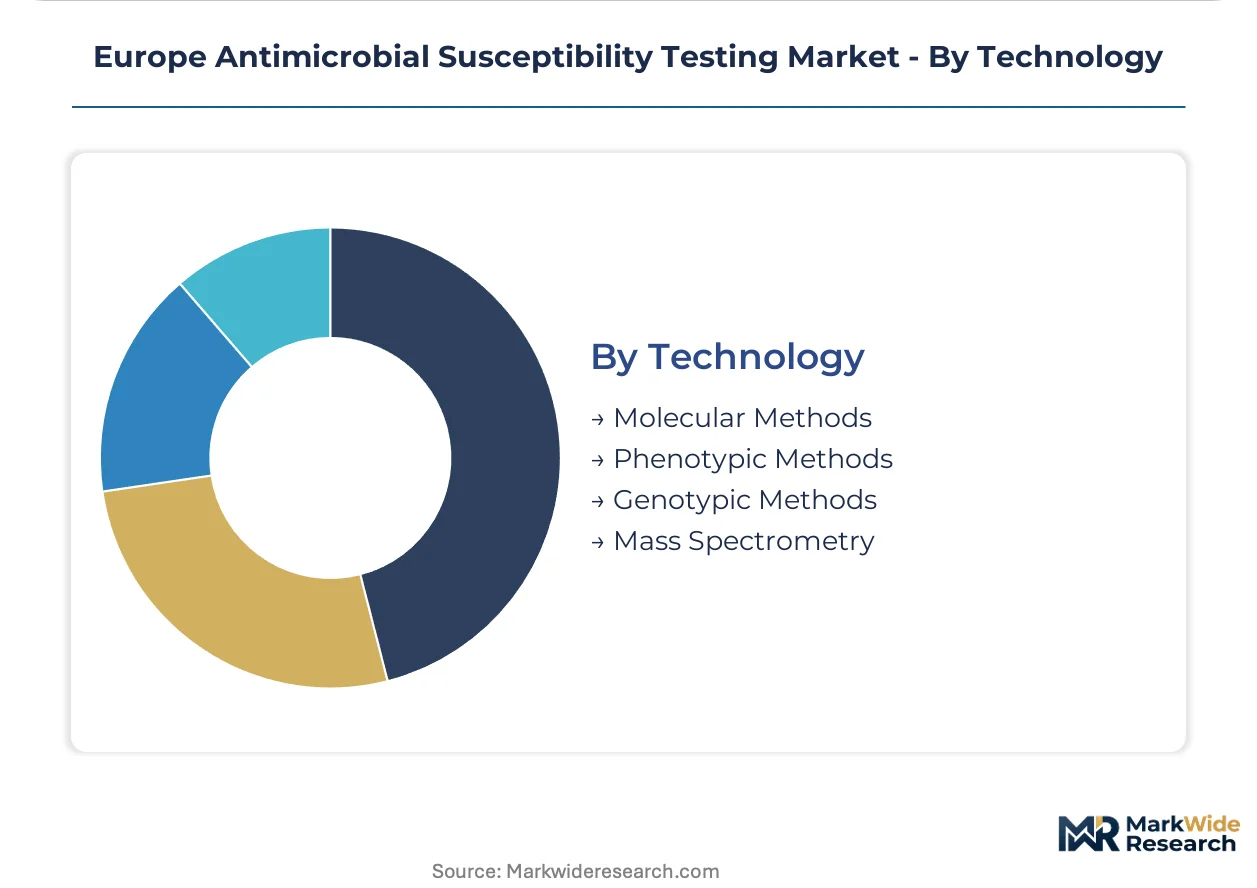
Maturity differentiation separates established culture-based workflows from emerging molecular platforms capturing resistance gene detection mandates.
- Phenotypic Methods:Growth-based susceptibility determination remains the reference standard for therapeutic breakpoint correlation. Smaller diagnostic laboratories depend on these methods where automated platform migration exceeds capital allocation.
- Molecular Methods:PCR and hybridization platforms detect carbapenemase, ESBL, and MRSA resistance determinants directly from clinical specimens. Carbapenemase and ESBL screening mandates are expanding beyond reference laboratories into routine hospital workflows.
- Genotypic Methods:DNA sequencing and microarray technologies characterize resistance mechanisms for epidemiological tracking and outbreak investigation. National reference laboratories employ these methods for surveillance database contribution.
- Mass Spectrometry:MALDI-TOF platforms identify microorganisms through protein profiling and increasingly integrate with automated susceptibility testing. University hospital networks have adopted integrated MALDI-TOF AST platforms that digitize resistance profiling workflows.
Phenotypic Methods retains installed base dominance. Molecular Methods is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA device oversight and EU MDR compliance deadlines anchor strategic positioning across European diagnostics. National AMR action plans and hospital consolidation trajectories reshape procurement patterns in member states with varying infrastructure maturity.
Germany
North Rhine-Westphalia and Bavaria host centralized laboratory networks aggregating testing volumes across multiple facilities. The EU MDR framework compresses equipment replacement cycles while elevating clinical evidence requirements for CE-marked placement. Heidelberg's university hospital corridor drives adoption of integrated MALDI-TOF AST platforms digitizing resistance profiling workflows.
France
France's 2022-2025 national AMR strategy embeds resistance surveillance requirements into hospital accreditation standards. ANSM regulatory alignment with EUCAST breakpoint revisions mandates protocol updates across clinical diagnostics laboratories. The Paris university hospital network concentrates advanced molecular testing capacity for carbapenemase and ESBL screening expansion.
United Kingdom
NHS Supply Chain aggregation dominates capital procurement for acute care microbiology coverage. The UK's five-year AMR action plan mandates testing capability expansion in sepsis management and surgical prophylaxis optimization. NHS trust information system heterogeneity impedes seamless data flow from new AST platforms to centralized surveillance databases.
Poland
EU cohesion fund allocations finance first-time automated AST system installations in regional laboratories previously dependent on manual disk diffusion. EUCAST breakpoint implementation creates compliance timelines for national reference laboratory alignment. Warsaw and Kraków hospital modernization programs anchor eastern European infrastructure upgrading.
Netherlands
Asynchronous EUCAST breakpoint adoption schedules fragment standardization across multi-site laboratory networks. National reference laboratory protocols operate on revision timelines distinct from neighboring Belgium and Nordic member states. Rotterdam and Amsterdam diagnostic hubs concentrate quality control capacity for breakpoint validation services.
Europe Antimicrobial Susceptibility Testing Market Competitive Landscape
Full-system integrators and specialized platform developers split the market across capital equipment and consumable revenue streams. The vendor base concentrates among established manufacturers with notified body relationships capable of absorbing EU MDR documentation burdens. Strategic archetypes span automated walk-away platform specialists, molecular workflow integrators, and phenotypic method purists. Dominant competitive moves include service contract unbundling from capital purchases and antimicrobial stewardship software bundling to extend vendor relationships beyond hardware.
Among French diagnostics conglomerates, bioMérieux SA anchors the automated systems tier through high-throughput hospital contracts. Thermo Fisher Scientific Inc exemplifies the molecular workflow integrator archetype with sample-to-result resistance gene detection platforms. Danaher Corporation occupies the phenotypic platform specialization position sustaining recurring consumable revenue streams. These three entities represent distinct strategic postures within a market where EU MDR clinical evidence requirements have frozen new entrant access and extended approval timelines by 12-18 months.
| Leading Market Players |
|---|
| bioMérieux SA |
| Thermo Fisher Scientific Inc |
| Becton Dickinson and Company |
| Danaher Corporation |
| Bio-Rad Laboratories Inc |
| Merck KGaA |
| HiMedia Laboratories |
| Alifax S.r.l. |
| Liofilchem S.r.l. |
| Others |
Supply & Pricing Matrix
Chromogenic media production clusters in southern Germany and northern France concentrate upstream supply for critical susceptibility testing consumables, anchoring margin pools among automated system manufacturers who bundle reagent supply into long-term service contracts. This geographic feedstock concentration shapes pricing power dynamics across European diagnostics procurement.
Pricing Analysis
Western European hospital networks pay 15-25% premiums over eastern European counterparts for identical automated AST platforms, reflecting bundled service contracts and EU MDR compliance documentation costs. Three-tier pricing structure across premium, standard, and economy levels separates university hospital cooperatives from regional diagnostic labs and manual-methodology holdouts. Pricing pressure stems from NHS Supply Chain and Nordic procurement consortiums unbundling service agreements from capital purchases. Smaller diagnostic laboratories in Portugal and Greece exhibit highest price sensitivity, while German university hospital purchasing cooperatives prioritize total cost of ownership over upfront equipment expenditure.
Supply Chain Analysis
Upstream feedstock for antimicrobial panels and chromogenic media draws from specialized chemical manufacturers concentrated in Germany, France, and Switzerland. Critical inputs include antibiotic reference standards, agar base materials, and indicator dyes subject to REACH substance restrictions. Single-source vulnerability pervades proprietary reagent formulations locked to specific automated platforms. Distribution runs through authorized distributor networks serving hospital procurement departments and diagnostic laboratory chains, with direct manufacturer relationships reserved for high-volume consolidated networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as molecular resistance gene detection mandates penetrate routine hospital workflows beyond reference laboratories, creating sustained platform replacement demand across the forecast horizon.
For Market Incumbents: Entrench platform stickiness through antimicrobial stewardship software integration that embeds susceptibility data into pharmacy information systems and electronic health records. Deepen reagent supply agreements with multi-year consumable commitments that raise switching costs for hospital networks. Defend against emerging molecular workflow competitors by accelerating MALDI-TOF AST platform deployment in university hospital corridors where digitization investments concentrate. For New Entrants and Emerging Players: Pursue white-space opportunity in Poland and Romania where EU cohesion fund hospital modernization programs finance first-time automated system installations without incumbent legacy entanglement. Target regional diagnostic laboratories in eastern European member states with manual-to-automated migration pathways and simplified compliance documentation. Lead with phenotypic platform specialization that sustains recurring consumable revenue without competing directly against integrated molecular workflow giants. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap phenotypic platform specialists with established notified body relationships and recurring consumable revenue streams that absorb EU MDR documentation burdens. Long-term viability favors vendors with antimicrobial stewardship software capabilities that extend relationships beyond hardware replacement cycles. Watch EUCAST breakpoint revision implementation timelines as inflection indicators for laboratory protocol update spending.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements compress approval timelines and freeze new entrant access. |
| Hospital System Partnership | Consolidated laboratory networks in North Rhine-Westphalia aggregate procurement for multi-facility contracts. |
| Software Companion Development | Antimicrobial stewardship integration embeds platforms into pharmacy information systems and EHR workflows. |
| Reimbursement Strategy | National AMR action plans in France and the UK mandate testing capability expansion in accreditation standards. |
| Reagent Supply Agreement | Long-term consumable commitments raise switching costs and sustain recurring revenue through platform lifecycles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EMA device filings, EUCAST breakpoint documentation, hospital procurement databases, and national AMR action plans across member states. Clinical microbiologists, hospital purchasing committee members, biomedical engineers, and diagnostic laboratory directors provided structured input on equipment replacement timelines and protocol adoption patterns. Bottom-up installation base modeling triangulates against top-down market sizing derived from GPO contract values and notified body registration data.
Forecast inputs incorporate automated system penetration rates, molecular method adoption curves, and reagent consumption per installed platform across the projection horizon. Segmentation dimensions include testing modality, application type, end-user category, and technology tier. CAGRs derive from equipment replacement cycle compression under EU MDR deadlines and resistance gene detection mandate expansion. Industry-specific inputs capture EUCAST breakpoint implementation lag effects and national reimbursement pathway evolution.
Macroeconomic conditions sit as an overlay; deviation in EU cohesion fund allocation levels or healthcare infrastructure spending priorities would shift the trajectory for eastern European modernization programs. Forecasts reflect assumptions regarding regulatory timeline adherence and laboratory workforce availability. Cross-checking against EMA notified body registration databases and national procurement disclosure records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Medical Device Testing, Inspection, and Certification Market
Testing Services
Antimicrobial Susceptibility Testing Market
Testing Services
Global Roadside Drug Testing Devices Market
Testing Services
US Independent Diagnostic Testing Facility Market
Testing Services
Global Cannabis Testing Market
Testing Services
Special Coagulation Tests Market
Testing Services
Paediatric and Neonatal Testing Kits Market
Testing Services
Monkeypox Testing Market
Testing Services
Self-Urinary Infection Testing Market
Testing Services
United States Esoteric Testing Market
Testing Services
Pharmaceutical Dosage Form Testing Systems Market
Testing Services
United States Testing, Inspection, and Certification (TIC) Market
Testing Services
Helicobacter Pylori Testing Market
Testing Services
Toxicity Testing Outsourcing Market
Testing Services
Cell Line Authentication and Characterization Tests Market
Testing Services
Employer and Workplace Drug Testing Market