
 Nicotine Testing Market | 2026-2036
Nicotine Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Nicotine Testing Market Analytics
CLIA-waived certification is redrawing competitive boundaries for point-of-care nicotine testing. AlcoPro leverages its distribution network across occupational health channels. LifeSign LLC anchors its position through rapid immunoassay strip manufacturing. PTS Diagnostics differentiates via integrated reader systems that reduce operator error in workplace settings.
Nicotine testing encompasses biochemical assays that detect cotinine, the primary metabolite of nicotine, in biological specimens using cutoff concentrations typically set at 10 ng/mL for urine and 1 ng/mL for serum to distinguish active use from passive exposure. These tests serve employment screening, insurance risk assessment, and smoking cessation program verification. Urine-based immunoassays occupy the largest volume share due to cost efficiency and established laboratory infrastructure, while saliva testing gains traction in onsite workplace programs requiring rapid turnaround. Chromatography methods capture premium pricing in forensic applications where legal defensibility demands mass spectrometry confirmation.
FDA oversees in vitro diagnostic device clearances for nicotine testing kits, while OSHA workplace health standards influence employer testing protocols and frequency requirements. The Centers for Medicare and Medicaid Services governs CLIA laboratory certification tiers that determine where testing may legally occur. Stakeholders must monitor evolving state-level privacy legislation that restricts biological specimen retention and mandates employee notification procedures.
Market Dynamics
CLIA-waived certification requirements are compressing the competitive field for point-of-care nicotine testing, forcing manufacturers to consolidate laboratory partnerships or invest in reader-integrated systems that eliminate operator variability.
Growth Catalysts
- Employer wellness mandates:Corporate tobacco-free workplace policies in the United States are expanding screening frequency beyond pre-employment to annual verification cycles.
- OSHA respiratory protection standards:Updated workplace health surveillance rules are triggering nicotine testing for workers in hazardous environments requiring respirator fit certification.
- Saliva-based immunoassay advancement:Rapid oral fluid detection technology is enabling same-result workplace programs without laboratory logistics.
Market Restraints
- Antibody supply concentration:High-affinity monoclonal antibody production for cotinine detection concentrates among three specialized bioreagent suppliers in Germany and the United States.
- FDA 510(k) pathway friction:Substantial equivalence demonstrations for novel detection platforms require 12-18 month review cycles that delay commercialization.
- Oral fluid substitution vulnerability:Saliva testing faces credibility challenges in forensic settings where chain-of-custody requirements favor urine or serum matrices.
Strategic Opportunities
- Insurance underwriting integration:Life insurers in Japan and South Korea are piloting cotinine verification for smoker-nonsmoker rate classification.
- Smoking cessation program verification:Digital health platforms are embedding home-collection nicotine testing for remote biochemical confirmation of abstinence.
- Chromatography-reader convergence:Miniaturized mass spectrometry modules are approaching point-of-care dimensions for legally defensible workplace confirmation testing.
Industry Challenges
- Cross-reactivity biochemistry:Structurally similar alkaloids in nicotine replacement therapies generate false-positive signals that erode test specificity.
- CLIA personnel qualification gaps:Waived testing still requires trained operators, and occupational health departments face turnover in certified medical technicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nicotine Testing Market |
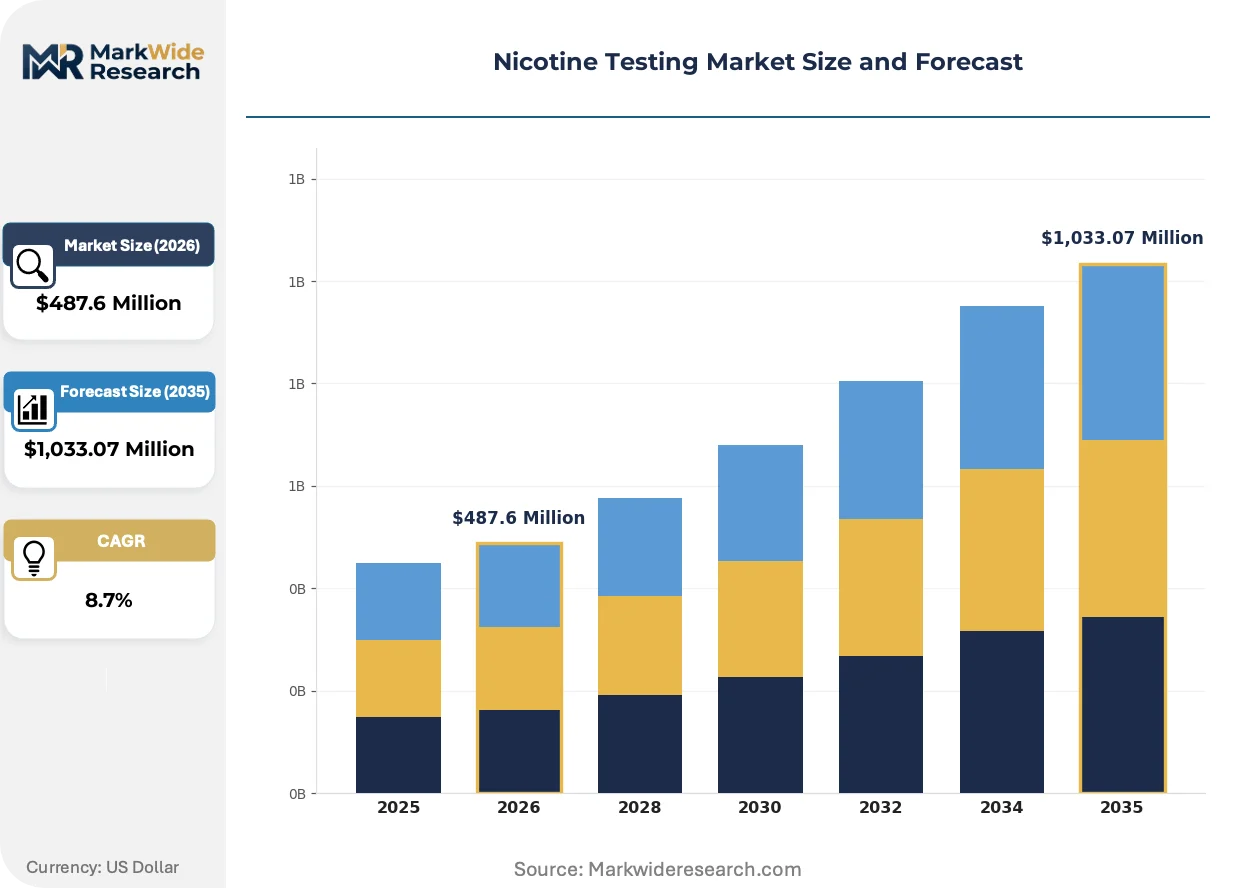
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urine Test, Blood Test, Saliva Test, Hair Test End User: Hospitals, Diagnostic Laboratories, Research Institutions, Government Agencies Technology: Immunoassays, Chromatography, Spectrometry, Molecular Diagnostics Application: Clinical Testing, Workplace Testing, Forensic Testing, Substance Abuse Programs |
| Companies Covered | AlcoPro, Nano-Ditech Corp, LifeSign LLC, PTS Diagnostics, ALFA Scientific Designs, LumiQuick Diagnostics, DFI, Cliawaived, Jant Pharmacal Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nicotine Testing Market Evolving Landscape
Detection modality diversification is fragmenting the traditional urine-immunoassay dominance as employers and clinicians demand faster, less invasive specimen collection with equivalent analytical reliability.
Fluorescence-based lateral flow assays are supplanting colorimetric strip readers in high-throughput occupational health settings. Large self-insured employers in manufacturing and logistics sectors are adopting these systems for same-shift result turnaround. The technology is compressing the price premium between rapid point-of-care devices and laboratory send-out testing.
EU MDR classification changes are redefining in vitro diagnostic device conformity assessment pathways for nicotine testing kits sold in European Economic Area markets. Manufacturers must now engage notified bodies for quality management system audits that previously relied on self-certification. Smaller kit producers are withdrawing from EU distribution rather than absorbing notified body fees exceeding €50,000 annually.
Direct-to-consumer collection kits are disrupting the traditional clinical channel for smoking cessation verification. Telehealth platforms in the United States are shipping saliva collection devices with prepaid laboratory return logistics, bypassing occupational health clinics and primary care offices. This channel shift is most pronounced among Medicaid-managed care plans seeking to document tobacco cessation for quality metric reporting.
Nicotine Testing Market Segmentation
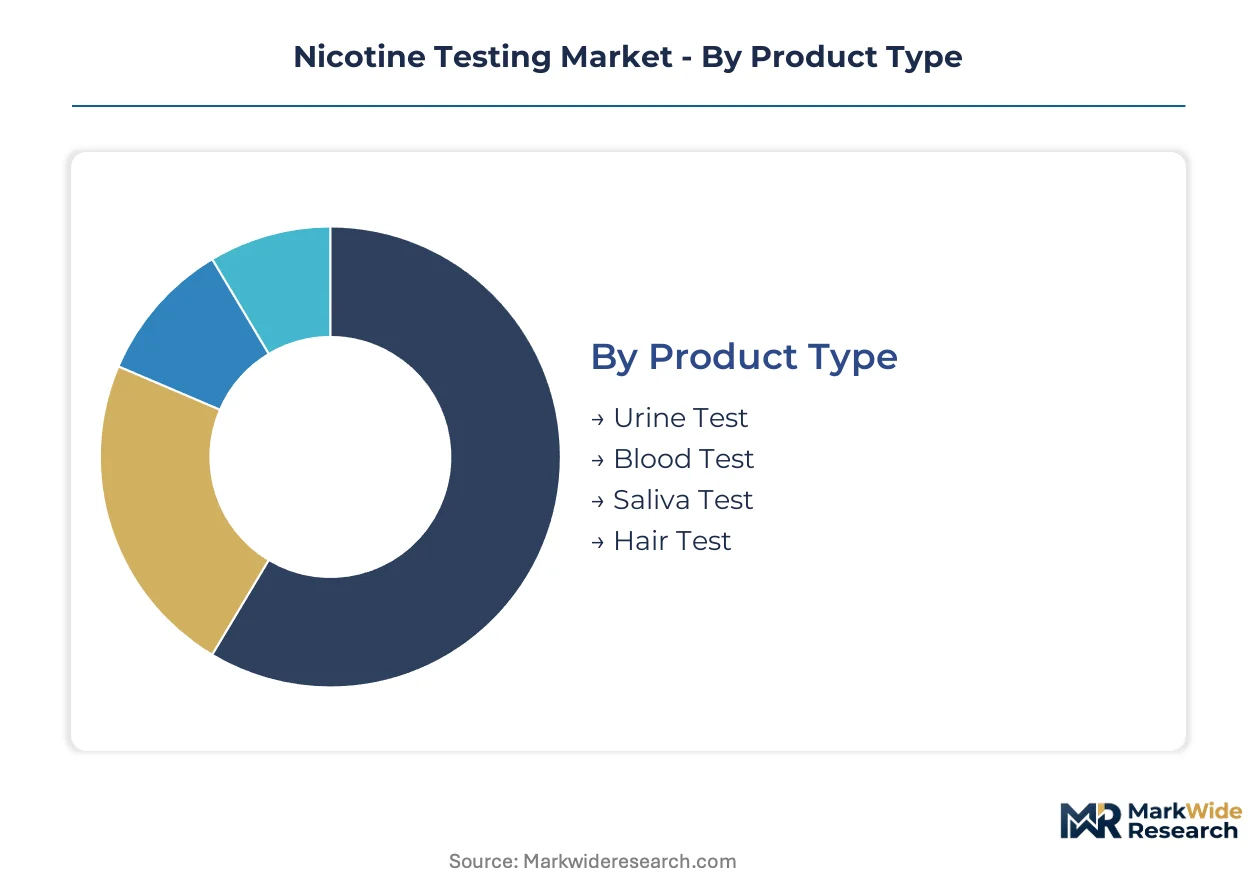
Nicotine testing segments diverge sharply by margin structure and regulatory burden. Product type determines manufacturing economics, while end-user concentration shapes distribution channel requirements.
Product Type:
Margin pools concentrate in rapid-result formats that bypass laboratory infrastructure and capture CLIA-waived premium pricing.
- Saliva Test:Oral fluid collection eliminates chain-of-custody complexity and enables same-shift workplace screening. Manufacturing margins expand as employers in United States logistics and manufacturing sectors adopt reader-integrated fluorescence systems for on-site verification.
- Urine Test:Immunoassay strips dominate volume through established laboratory infrastructure and cost efficiency. Demand concentrates in pre-employment screening programs where United States corporate wellness mandates drive high-throughput processing.
- Blood Test:Serum cotinine detection at 1 ng/mL cutoff provides definitive quantification for insurance underwriting.
- Hair Test:Extended detection window captures chronic use patterns for forensic custody disputes.
Urine test holds installed capacity. Saliva test is rotating up the share rankings.
End User:
Procurement authority and reimbursement pathways fragment demand across institutional buyers with divergent technical specifications.
- Diagnostic Laboratories:High-throughput processors serve employer wellness contracts and insurance verification. Volume concentrates in United States reference laboratories with CLIA-certified capacity and automated immunoassay workflows.
- Government Agencies:Forensic laboratories and public health departments mandate mass spectrometry confirmation. Procurement in United States federal and state facilities requires FDA-cleared devices with documented chain-of-custody protocols.
- Hospitals:Clinical cotinine testing supports smoking cessation program enrollment and respiratory therapy planning.
- Research Institutions:Academic studies require standardized metabolite quantification for epidemiological smoking research.
Diagnostic laboratories hold installed capacity. Government agencies are rotating up the share rankings.
Technology:
Regulatory clearance tiers and capital intensity stratify competitive positioning across detection methodologies.
- Immunoassays:Lateral flow and enzyme-linked formats deliver rapid qualitative screening at lowest unit cost. Demand concentrates in United States occupational health clinics where CLIA-waived status enables non-laboratory operation.
- Chromatography:Liquid and gas chromatography with mass spectrometry detection provides legally defensible quantitative confirmation. Premium pricing sustains margins in forensic applications where United States court standards require analytical specificity.
- Spectrometry:Fluorescence and absorbance readers automate strip interpretation for high-throughput settings.
- Molecular Diagnostics:PCR-based nicotine metabolite genotyping remains experimental for pharmacogenomic applications.
Immunoassays hold installed capacity. Chromatography is rotating up the share rankings.
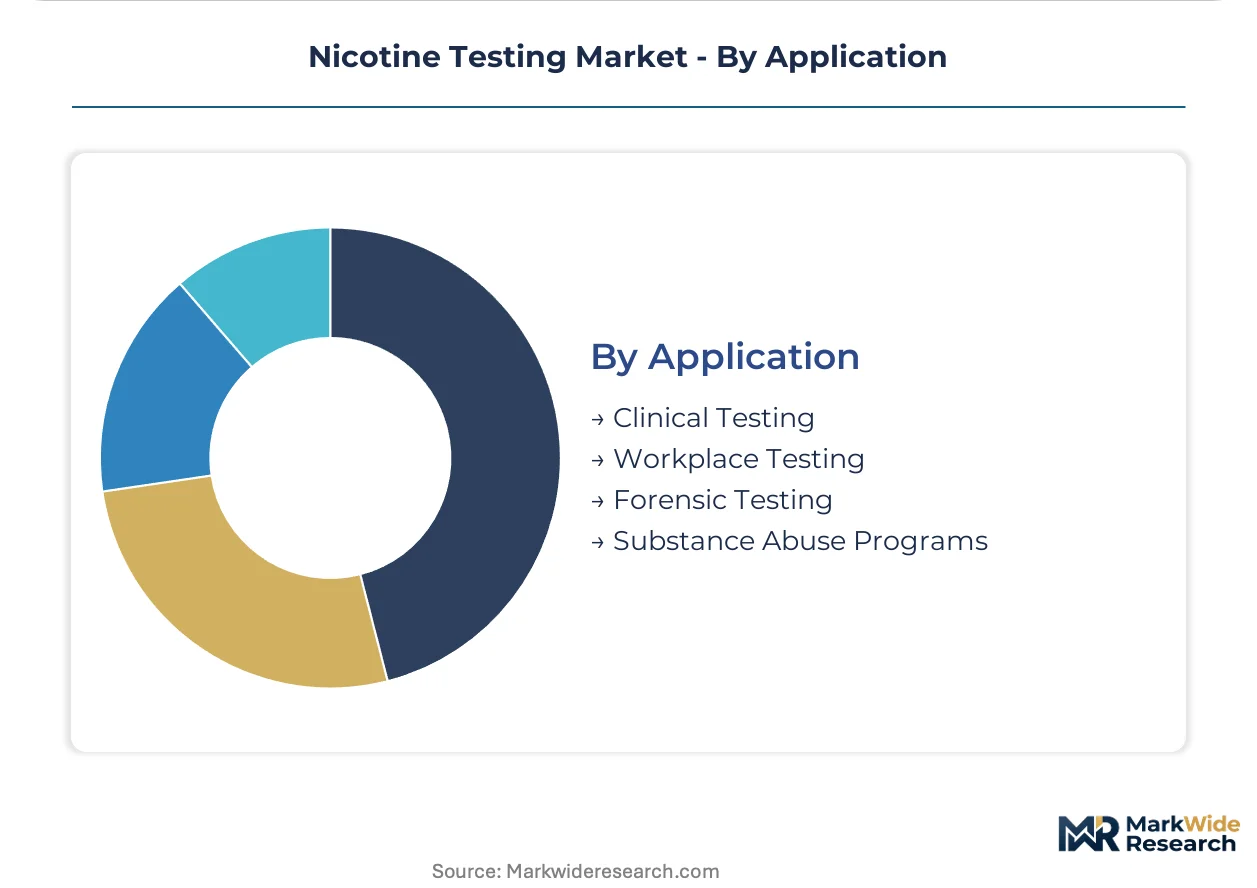
Application:
Legal defensibility requirements and testing frequency create divergent margin profiles across use cases.
- Workplace Testing:Corporate tobacco-free policies and OSHA respiratory protection standards drive recurring screening volume. United States self-insured employers in manufacturing and logistics sectors adopt fluorescence-based systems for annual verification cycles.
- Forensic Testing:Chain-of-custody documentation and court-admissible results command premium pricing. Demand concentrates in United States family law and criminal proceedings where metabolite quantification determines compliance with court-ordered abstinence.
- Clinical Testing:Hospital-based cessation programs require rapid turnaround for patient counseling.
- Substance Abuse Programs:Rehabilitation facilities monitor abstinence through scheduled urine screening protocols.
Workplace testing holds installed capacity. Forensic testing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer mandates and insurance underwriting practices concentrate nicotine testing demand in specific national markets, with regulatory frameworks determining where point-of-care devices may legally operate outside laboratory settings.
United States
Corporate wellness departments at self-insured manufacturers and logistics firms drive recurring screening volume through annual verification cycles. OSHA respiratory protection standards mandate cotinine testing for workers requiring respirator fit certification in hazardous environments. The Southeast industrial corridor spanning Georgia and Tennessee hosts dense occupational health clinic networks serving automotive and warehousing employers.
Germany
Statutory health insurers pilot biochemically verified smoking cessation programs with documented abstinence requirements for premium reductions. EU MDR classification changes force notified body engagement for quality management system audits that previously relied on self-certification. The Rhine-Ruhr metropolitan region concentrates diagnostic laboratory capacity serving employer wellness contracts across Benelux markets.
Japan
Life insurers deploy cotinine verification for smoker-nonsmoker rate classification in pilot underwriting programs. METI industrial standards influence workplace health surveillance protocols for manufacturing sector employers. The Osaka-Kobe industrial zone anchors rapid immunoassay strip distribution networks serving occupational health departments.
United Kingdom
NHS smoking cessation services integrate home-collection cotinine testing for remote biochemical confirmation of abstinence. MHRA device regulations align with EU MDR conformity assessment pathways for in vitro diagnostic clearances. The Greater Manchester health innovation cluster hosts telehealth platforms shipping saliva collection devices with prepaid laboratory logistics.
South Korea
MFDS pharmaceutical regulator oversees in vitro diagnostic device registrations for nicotine testing kits entering the domestic market. National health insurance expansion drives demand for verified cessation program enrollment in corporate employee benefit schemes. The Seoul Capital Area concentrates diagnostic laboratory automation serving high-throughput employer screening contracts.
Nicotine Testing Market Competitive Landscape
Player mix skews toward specialized diagnostic manufacturers with CLIA-waived certification capabilities and occupational health distribution networks. The competitive field compresses as regulatory barriers force consolidation around reader-integrated systems that eliminate operator variability. Three archetypes dominate: rapid immunoassay strip producers, fluorescence-based lateral flow system integrators, and chromatography confirmation specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves, with manufacturers seeking laboratory alliances or distribution agreements to secure channel access.
Within the point-of-care certification tier, AlcoPro, LifeSign LLC, and PTS Diagnostics exemplify positioning strategies around regulatory clearance and workplace channel penetration. AlcoPro occupies a position tied to occupational health distribution networks. LifeSign LLC anchors rapid immunoassay manufacturing capabilities. PTS Diagnostics sits within the reader-integrated system segment addressing operator error reduction in high-throughput settings.
| Leading Market Players |
|---|
| AlcoPro |
| Nano-Ditech Corp |
| LifeSign LLC |
| PTS Diagnostics |
| ALFA Scientific Designs |
| LumiQuick Diagnostics |
| DFI |
| Cliawaived |
| Jant Pharmacal Corporation |
| Others |
Value Network & Pricing Analysis
High-volume immunoassay strip manufacturing in the United States and Germany generates scale economies that compress unit costs and elevate price floors for CLIA-waived certification tiers. Capacity utilization rates above 85% at specialized bioreagent facilities in these markets directly determine pricing power for rapid point-of-care devices, while smaller manufacturers absorb margin erosion or exit.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA 510(k)-cleared devices commanding 40-60% markups over self-certified laboratory-use products. Three-tier pricing structure across premium, standard, and economy levels stratifies by analytical specificity and reader integration. Cost compression in the economy tier is intensifying because antibody supply concentration among German and United States bioreagent suppliers limits substitution options. Self-insured employers in United States manufacturing sectors demonstrate lowest price sensitivity, while independent occupational health clinics exhibit highest sensitivity to per-test costs.
Supply Chain Analysis
Germany and the United States anchor high-affinity monoclonal antibody production for cotinine detection, with three specialized bioreagent suppliers controlling upstream reagent supply. Manufacturing draws from nitrocellulose membrane substrates sourced from Asian converters, enzyme conjugates from European specialty chemical houses, and plastic housing components from Mexican injection molders. Single-source vulnerability concentrates in antibody supply chains, where qualification timelines exceed 18 months for alternative suppliers. Distribution runs through occupational health equipment distributors serving corporate wellness departments, with direct-to-telehealth platform sales emerging as an alternative channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reader-integrated fluorescence systems are consolidating platform economics around interoperability standards that favor incumbent certification holders and marginalize standalone strip manufacturers. Digital health platform embedding represents the decisive ecosystem shift, as telehealth verification workflows restructure channel access.
For Market Incumbents: Fortify CLIA-waived certification portfolios through backward integration into antibody production or captive supply agreements with German and United States bioreagent specialists. Channel control via exclusive distributor relationships in the Southeast United States industrial corridor defends against direct-to-consumer kit displacement. Certification investment in EU MDR notified body engagement preserves European Economic Area market access as smaller competitors withdraw. For New Entrants and Emerging Players: Anchor in direct-to-consumer collection kit distribution through telehealth platform partnerships, where regulatory barriers remain lower than point-of-care device clearance. White-space concentration sits with Medicaid-managed care plans seeking documented tobacco cessation metrics, and with Japanese and South Korean life insurers piloting cotinine verification for rate classification. Go-to-market execution through prepaid logistics integration with home-collection workflows bypasses incumbent occupational health clinic networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among reader-integrated system manufacturers with annual calibration and consumable attachment. Long-term viability across the analysis window favors acquisition targets possessing both CLIA-waived certification and fluorescence-based lateral flow manufacturing capability. The signal to watch as inflection indicator is FDA clearance pathway friction duration, where 12-18 month review cycles compress new entrant funding runways and create distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Certification Investment | FDA clearance enables non-laboratory operation in United States occupational health settings. |
| Antibody Supply Agreement | Long-term contracts with German bioreagent suppliers secure high-affinity monoclonal production capacity. |
| Telehealth Platform Partnership | Integration with United States Medicaid-managed care plans opens direct-to-consumer verification channels. |
| EU MDR Notified Body Engagement | Quality management system audits preserve European Economic Area market access against competitor withdrawal. |
| Fluorescence Reader Development | Automated strip interpretation reduces operator error in high-throughput manufacturing sector screening programs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with diagnostic laboratory directors, occupational health clinic managers, CLIA compliance officers, and bioreagent manufacturing executives. Secondary validation incorporated FDA 510(k) clearance databases, CLIA certification registries, CMS Medicare laboratory payment schedules, and OSHA respiratory protection standard guidance documents. Bottom-up and top-down triangulation reconciled unit shipment estimates with aggregate market value assessments.
Across the analysis window, the forecasting framework modeled nicotine testing demand through segmentation dimensions spanning product type, end-user institution, detection technology, and application use case. CAGRs were derived from regression analysis against employer wellness mandate adoption curves and insurance underwriting integration timelines. Industry-specific forecast inputs incorporated OSHA regulatory update schedules and EU MDR implementation phase transitions.
Material uncertainties — antibody supply disruption, FDA review cycle extension, state-level privacy legislation expansion — sit outside the modeled envelope. Forecasts reflect assumptions around CLIA-waived certification maintenance and occupational health clinic network stability. Recalibration cycles align with material shifts in employer mandate adoption and telehealth platform reimbursement policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
North America Endotoxin and Pyrogen Testing Market
Testing Services
Blood Pressure Test Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market
Testing Services
Biological Indicator Incubators Market
Testing Services
Global Biologics Safety Testing Market
Testing Services
Viral Vector Integrity and Potency Analytics Test Instruments Market
Testing Services
Europe Esoteric Testing Market
Testing Services
Global Biological Safety Testing Market
Testing Services
Aerospace and Life Science Testing Certification Market
Testing Services
Global Endocrine Testing Market
Testing Services
Anticoagulant Therapeutic Drug Monitoring Assay Kits Market
Testing Services
At-Home Testing Market
Testing Services
United States Esoteric Testing Market
Testing Services
Sports Drug Testing Market
Testing Services
Comprehensive Metabolic Panel (CMP) Testing Market
Testing Services
Global Virology Testing Market