
 Over-The-Counter Tests Market | 2026-2036
Over-The-Counter Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Over-The-Counter Tests Market Intelligence
The integration of digital health platforms with diagnostic devices is decoupling the one-time sale of a test from ongoing health management services. This shift creates recurring revenue opportunities beyond the initial hardware purchase. Abbott Laboratories leverages its established brand in continuous glucose monitoring to capture this trend. F. Hoffmann-La Roche AG competes with a diverse portfolio spanning multiple health conditions, while Quidel Corporation specializes in rapid infectious disease diagnostics.
Over-the-counter tests are diagnostic assays designed for direct consumer use without a prescription, enabling early detection and monitoring. These tests often utilize lateral flow immunoassay or electrochemical sensor technologies to detect specific biomarkers from samples like blood or saliva. While glucose monitors and pregnancy tests constitute mature product segments, demand for cholesterol and allergy tests is expanding rapidly. The distribution landscape is also shifting, with online retailers gaining significant share from traditional pharmacies and supermarkets due to convenience.
Regulatory frameworks like the US FDA's 510(k) clearance process, Europe's CE marking under the Medical Devices Regulation (MDR), and China's NMPA approvals govern market access. These agencies mandate stringent performance validation, clear consumer labeling, and robust post-market surveillance for all consumer diagnostics. Successfully navigating these varied and evolving international regulatory pathways will determine future market leadership and commercial success.
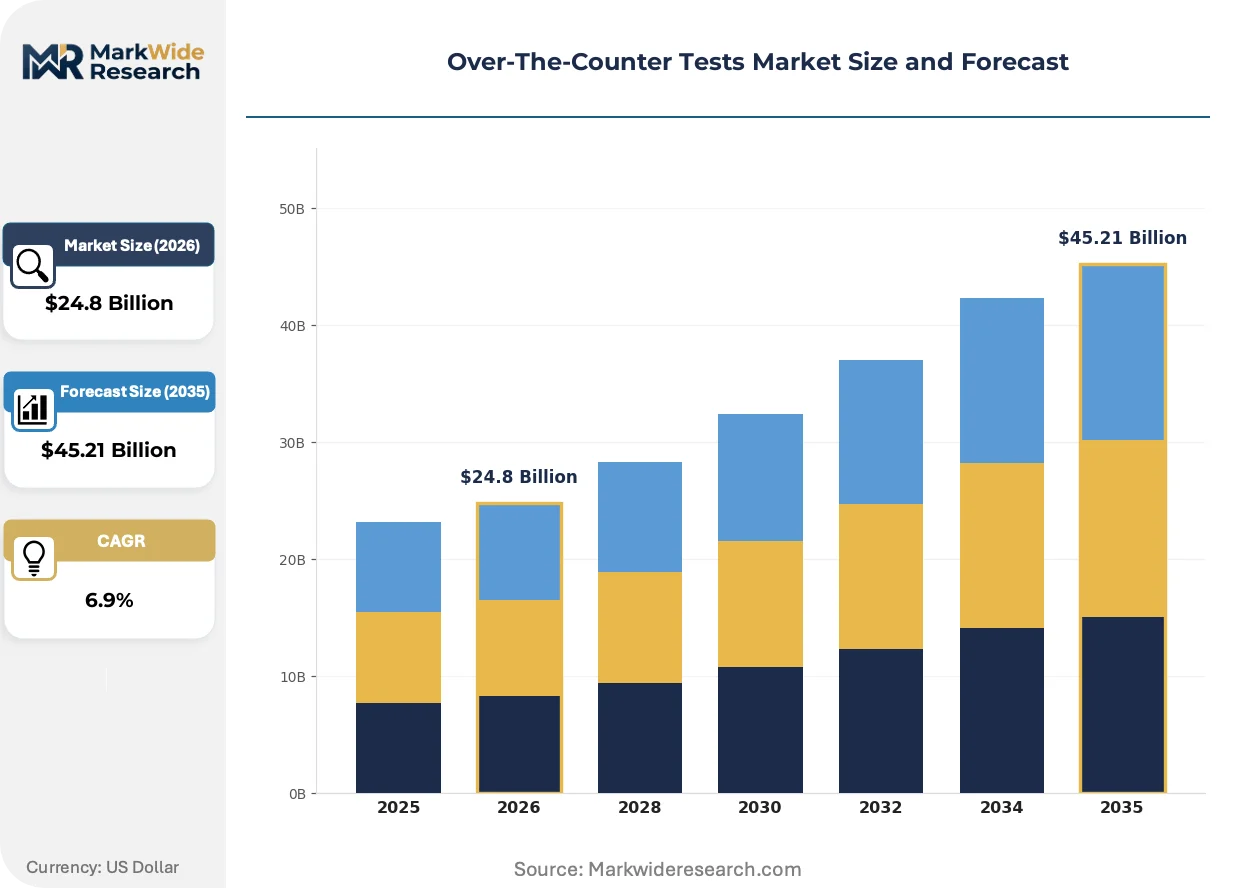
Market Dynamics
The fundamental market structure is being reshaped by the consumerization of healthcare, where demand for self-management of health is intersecting with regulatory frameworks, like those from the FDA and EMA, that are adapting to decentralize diagnostic testing.
Growth Catalysts
- Favorable Regulatory Policies:The FDA's Emergency Use Authorization (EUA) pathway, refined during public health crises, has created a faster route to market for infectious disease tests, setting a precedent for future rapid approvals.
- Demographic Shifts:Aging populations in developed nations like Japan and Germany are driving sustained demand for at-home monitoring tools for chronic conditions such as diabetes, hypertension, and cardiovascular disease.
- Technological Advancement:The miniaturization of electrochemical sensors and advancements in microfluidics are enabling the development of more accurate, affordable, and user-friendly tests for analytes like cholesterol and uric acid.
Market Restraints
- Accuracy and Reliability Concerns:A persistent consumer perception of lower accuracy for certain OTC tests compared to professional laboratory-based assays limits adoption, especially for diagnostics tied to serious health conditions.
- Reimbursement Complexity:Inconsistent and often absent reimbursement frameworks for OTC tests across national healthcare systems, particularly within various European Union member states, creates significant market access and pricing hurdles.
- Reagent Supply Chain Bottlenecks:The supply of critical raw materials, such as high-purity enzymes and monoclonal antibodies, is concentrated among a small number of specialized producers, creating risks of price volatility and shortages.
Strategic Opportunities
- Underserved Geographic Markets:Significant growth potential exists in introducing established products like fertility and infectious disease tests into large, underpenetrated emerging economies such as India and Brazil.
- Expansion into Wellness Testing:Developing tests for non-clinical applications, including monitoring nutritional deficiencies like Vitamin D or iron levels, opens a new consumer wellness segment outside of traditional disease diagnostics.
- Telehealth Integration:Pairing OTC diagnostic kits with virtual physician consultations in markets like the United States creates a novel service model for guided testing, interpretation, and immediate clinical follow-up.
Industry Challenges
- Data Privacy and Security:For connected devices, ensuring robust cybersecurity and compliance with data protection regulations like HIPAA in the US and GDPR in Europe presents a significant operational and financial challenge.
- Consumer Usability:Designing tests and instructions that are simple enough to prevent user error in sample collection or result interpretation is a constant challenge that directly impacts product efficacy and safety.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Over-The-Counter Tests Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $45.21 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pregnancy Tests, Glucose Monitors, Cholesterol Tests, Allergy Tests Application: Personal Health Monitoring, Disease Prevention, Symptom Management, Health Diagnosis Distribution Channel: Pharmacies, Supermarkets, Online Retailers, Health Stores Customer Type: Home Users, Healthcare Providers, Retail Pharmacies, Laboratories |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche AG, Becton Dickinson and Company, OraSure Technologies Inc, Quidel Corporation, AccuBioTech Co., Ltd., SD Biosensor Inc., Sinocare Inc., Eurofins Scientific Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Over-The-Counter Tests Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of diagnostic hardware with digital health platforms. This integration is transforming discrete, single-point tests into sources of continuous data for proactive personal health management.
Multiplex assay technology allows for the simultaneous detection of several biomarkers from a single sample using advanced lateral flow designs. Consumers managing complex or comorbid conditions are adopting these for more efficient at-home screening. This technology is expanding into combination panels for respiratory illnesses and broad allergy screenings, moving beyond the limitations of single-analyte tests.
Europe's Medical Devices Regulation (MDR) imposes more stringent requirements for clinical evidence, quality management, and post-market surveillance on all diagnostic manufacturers. This regulatory shift increases development costs and lengthens time-to-market, creating higher barriers to entry. Self-tests for novel biomarkers and infectious diseases face the most intense scrutiny, compelling firms to invest heavily in performance validation to obtain a CE mark.
Subscription-based delivery models are gaining significant traction, particularly for tests that require regular and repeated use. This direct-to-consumer channel disrupts traditional retail by offering automated replenishment for products like glucose test strips and ovulation kits. This purchasing behavior is most advanced in the United States and is seeing accelerated adoption across Western Europe for managing chronic health conditions.
Over-The-Counter Tests Market Segmentation
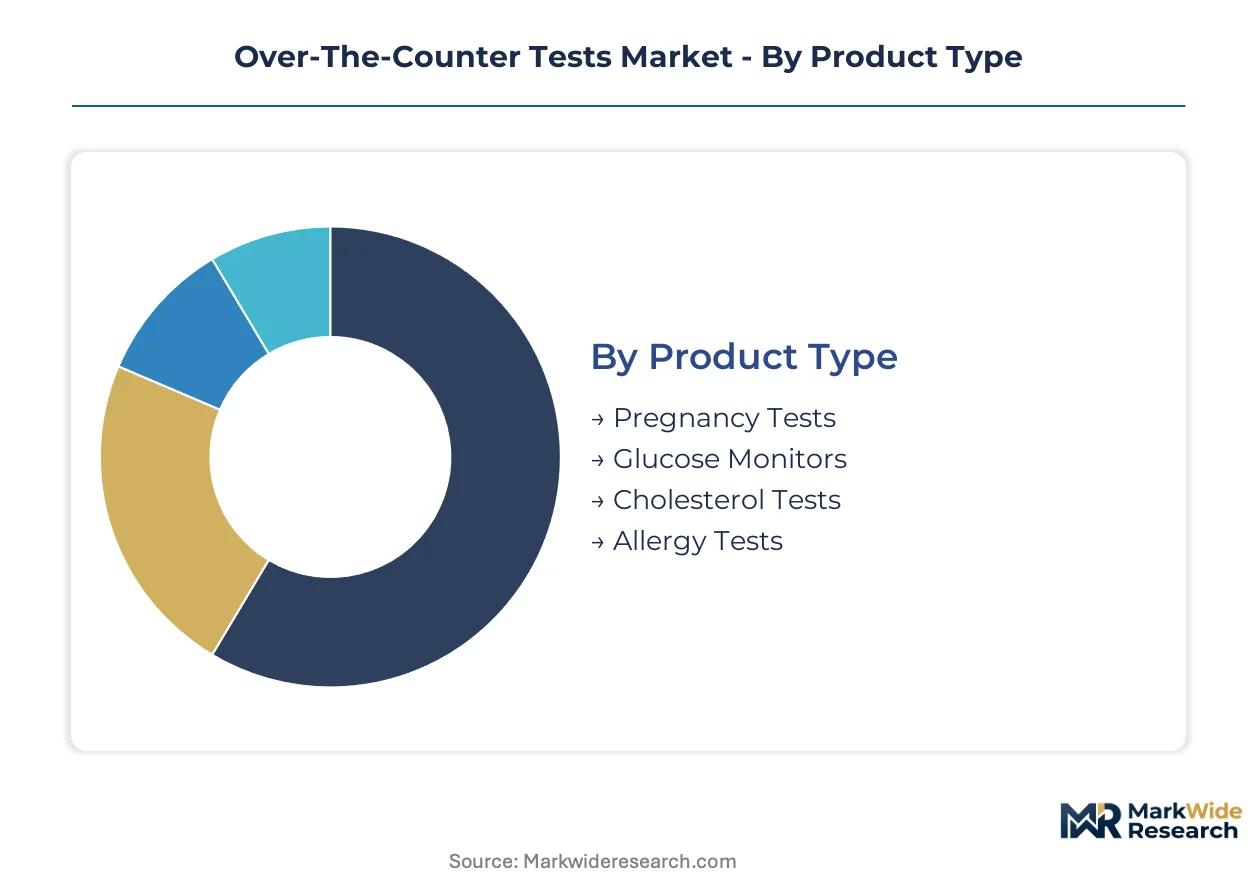
The Over-The-Counter Tests Market is segmented to provide a granular view of consumer preferences, technological adoption, and distribution dynamics. Understanding these distinct segments allows for targeted product development and strategic market entry, reflecting the diverse needs of end-users and the varied applications of diagnostic assays.
Product Type:
Buyer motivations for over-the-counter tests vary significantly by the specific product type, reflecting diverse health concerns and monitoring needs.
- Glucose Monitors:These devices utilize electrochemical sensors to accurately measure blood glucose levels from a small blood sample. Demand concentrates in developed nations like Germany and the United States, driven by aging populations managing chronic conditions such as diabetes.
- Pregnancy Tests:Lateral flow immunoassays are employed to detect human chorionic gonadotropin (hCG) in urine, indicating pregnancy. Demand remains consistently high globally, supported by their accessibility, rapid results, and privacy.
- Cholesterol Tests:These tests often use electrochemical methods to screen for lipid levels, aiding in cardiovascular risk assessment for health-conscious consumers.
- Allergy Tests:Diagnostic kits identify specific allergens through blood or saliva samples, helping consumers manage sensitivities and environmental triggers.
Glucose Monitors lead volumes today; Allergy Tests are gaining share fastest.
Application:
The intended application significantly influences the adoption patterns and regulatory scrutiny for over-the-counter tests.
- Personal Health Monitoring:This application involves the continuous tracking of physiological parameters for managing chronic conditions or general wellness. Demand is concentrating in the United States, driven by consumer preference for self-managed health solutions and digital health integration.
- Health Diagnosis:This segment focuses on the early detection of specific medical conditions, often using biomarker analysis. This application requires stringent performance validation under frameworks like the FDA's 510(k) clearance and Europe's MDR.
- Disease Prevention:These applications focus on identifying risk factors or early markers to avert the onset of illness, often through lifestyle management.
- Symptom Management:Tests in this segment help individuals understand and respond to ongoing health symptoms, such as identifying causes of discomfort.
Personal Health Monitoring applications command the largest share, while Health Diagnosis sees rapid expansion.
Distribution Channel:
Convenience and accessibility define consumer channel preference for over-the-counter tests, impacting market reach and pricing.
- Online Retailers:E-commerce platforms provide broad product selection, competitive pricing, and home delivery convenience. This channel is gaining significant share from traditional pharmacies, particularly in the United States and across Western Europe.
- Pharmacies:Traditional brick-and-mortar drugstores offer immediate product availability and the option for professional advice. This channel benefits from established consumer trust and robust logistics networks.
- Supermarkets:Grocery stores provide high foot traffic and broad consumer access for basic and high-volume OTC tests, often integrating health and wellness aisles.
- Health Stores:Specialized retail outlets often cater to wellness-focused consumers, offering niche diagnostic products and supplementary health items.
Online Retailers are rapidly displacing traditional channels, though Pharmacies retain a substantial volume.
Customer Type:
The customer type dictates specific requirements for product design, packaging, and regulatory pathways within the OTC test market.
- Home Users:These are individuals purchasing tests for self-diagnosis, personal health monitoring, or wellness screening. This segment drives demand for user-friendly designs and clear instructions to minimize potential user error.
- Retail Pharmacies:These entities procure tests for direct sale to consumers through their physical and online storefronts. They act as a critical touchpoint, influencing brand perception and product accessibility.
- Healthcare Providers:Physicians and clinics may use OTC-like tests for initial screening, patient education, or as part of a telehealth consultation model.
- Laboratories:While primarily using professional-grade equipment, some laboratories process consumer-collected samples submitted via specialized OTC kits for more complex analysis.
Home Users represent the core demand, while Retail Pharmacies are crucial for market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While consumer preference for self-managed health drives demand in the United States, an aging population sustains the need for at-home monitoring tools in Germany. Both nations represent significant revenue streams for over-the-counter test manufacturers. Regulatory adaptations support market decentralization.
United States
Demand for self-managed health solutions concentrates in the United States, particularly for chronic disease monitoring. The FDA's evolving regulatory framework, including 510(k) clearance, shapes market access. Major pharmaceutical and diagnostics companies in the Boston-Cambridge biotech hub develop next-generation at-home tests.
Germany
An aging population in Germany drives sustained demand for at-home monitoring tools, especially for diabetes and cardiovascular conditions. Europe's CE marking under the Medical Devices Regulation (MDR) mandates stringent performance validation. Munich's medical technology cluster innovates electrochemical sensors for user-friendly diagnostics.
Japan
Japan's significant aging demographic creates a continuous need for accessible at-home diagnostic tools for chronic illnesses. The PMDA ensures rigorous quality and safety standards for over-the-counter medical devices. Pharmaceutical and diagnostic firms around Tokyo invest in miniaturized test development.
China
Consumer health awareness and a large population fuel demand for over-the-counter tests in China. The NMPA approvals govern market entry, focusing on local manufacturing and distribution. Shanghai's burgeoning biotech sector develops rapid infectious disease diagnostics for domestic and international markets.
India
Underpenetrated markets in India offer significant growth potential for established products like fertility and infectious disease tests. The CDSCO regulates diagnostic kits, emphasizing affordability and accessibility. Bengaluru's technology ecosystem supports digital health platform integration with diagnostic devices.
Over-The-Counter Tests Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, creating a tiered market structure. Large multinational corporations often dominate mature product categories like glucose monitoring and pregnancy tests, leveraging established consumer trust. Smaller, agile firms frequently specialize in niche diagnostics or rapid infectious disease kits, seeking faster market entry. Competitive moves include significant portfolio diversification into new health conditions and strategic partnerships for digital health platform integration and expanded distribution.
Among the established industry leaders, Abbott Laboratories exemplifies a strategy of leveraging a strong brand presence in continuous glucose monitoring to capture recurring revenue from ongoing health management services. F. Hoffmann-La Roche AG, a Swiss AG, occupies a position with a diverse portfolio spanning multiple health conditions, representing broad diagnostic capabilities. Quidel Corporation, a US-based entity, anchors the rapid infectious disease diagnostics segment, focusing on specialized test kits. These companies collectively illustrate the varied approaches to market leadership, from broad-spectrum offerings to specialized diagnostic solutions, influencing overall market direction.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche AG |
| Becton Dickinson and Company |
| OraSure Technologies Inc |
| Quidel Corporation |
| AccuBioTech Co., Ltd. |
| SD Biosensor Inc. |
| Sinocare Inc. |
| Eurofins Scientific Group |
| Others |
Cost & Logistics Intelligence
Specialized R&D talent in Boston-Cambridge drives premium product pricing, reflecting high development costs. This labor-cost differential contributes to wider pricing-tier spreads across diagnostic categories.
Pricing Analysis
Capacity additions in Chinese manufacturing facilities are reshaping price floors for high-volume OTC tests. The dominant pricing structure remains per-unit transactional, though subscription models are gaining traction for repeat-use products like glucose strips. Price differentiation stems from stringent regulatory certifications like FDA 510(k) clearance and established brand premiums. Pricing softness reflects intense competition from online retailers. Home Users are particularly price-sensitive for routine self-diagnostics, while Healthcare Providers prioritize reliability over marginal cost savings for initial screenings.
Supply Chain Analysis
The availability of skilled labor in Germany's medical technology cluster influences the supply chain for advanced electrochemical sensors. Geographic supply concentration for key components like high-purity enzymes and monoclonal antibodies rests in China and India. These critical raw materials present single-source vulnerability, creating a structural supply chain risk. Distribution runs through a hybrid model, with online retailers gaining share from traditional pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
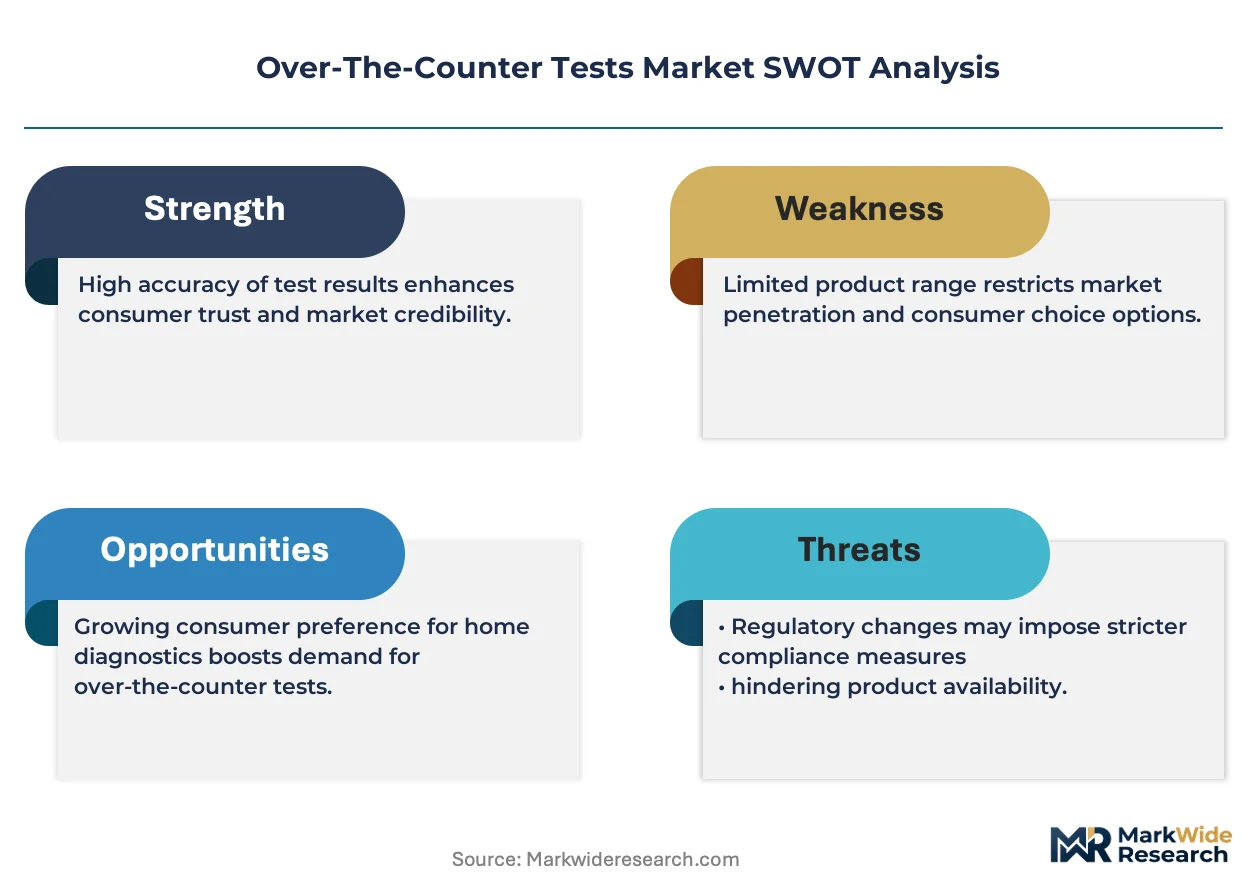
The Over-The-Counter Tests Market functions as a regulatory compounder, with the FDA's evolving framework for at-home diagnostics driving sustained demand. This regulatory adaptation accelerates consumer preference for self-managed health solutions.
For Market Incumbents: Deepen vertical integration into critical raw material production to mitigate reagent supply chain bottlenecks. Consolidate market share in mature segments like glucose monitoring through strategic acquisitions, countering emerging entrant archetypes. Invest in digital health platform integration to capture recurring revenue opportunities beyond initial hardware sales. Enhance R&D into multiplex assay technology, addressing consumer demand for comprehensive wellness testing.
For New Entrants and Emerging Players: Capture underserved geographic markets like India and Brazil by introducing established fertility and infectious disease tests. Target the wellness testing segment for non-clinical applications such as Vitamin D or iron level monitoring, which remains highly penetrable. A go-to-market angle focused on telehealth integration, offering guided testing and interpretation, provides a novel service model. Emphasize user-friendly designs to minimize error for Home Users.
For Investors and Strategic Acquirers: Large pharmaceutical and diagnostics companies are the most active acquirers in this space, seeking to diversify portfolios. The long-term viability of the market remains strong over a ten-year window, driven by demographic shifts and consumerization of healthcare. Target archetype companies specializing in novel biomarker detection or robust digital health platforms. The signal to watch is the acceleration of reimbursement frameworks for OTC tests across major economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Health Platform Integration | Connects diagnostic hardware with ongoing health management services, creating recurring revenue for Abbott Laboratories. |
| Multiplex Assay Technology Development | Allows simultaneous detection of multiple biomarkers from a single sample, expanding applications for Quidel Corporation. |
| Targeted Geographic Expansion | Introduces established products into underpenetrated emerging economies like India, driving new demand. |
| Regulatory Pathway Investment | Navigating CE marking under Europe's MDR ensures market access and validates product performance for F. Hoffmann-La Roche AG. |
| Subscription-Based Delivery Models | Disrupts traditional retail channels by offering automated replenishment for repeat-use products like glucose test strips. |
Research Approach
Bottom-up consumer preference modeling reconciled against top-down manufacturer production tracking forms the analytical core for this study. Primary interviews with R&D directors, regulatory affairs specialists, retail pharmacy buyers, and telehealth platform executives provided qualitative insights. Secondary validation drew from FDA filings, EMA submissions, industry association reports, and financial disclosures of key players. This triangulation ensures a robust and comprehensive market view.
Historical trendline analysis established foundational growth trajectories across the analysis window. The market was segmented by product type, application, distribution channel, and customer type, alongside regulatory approval status. Compound Annual Growth Rates were derived through regression analysis of historical data and projected forward using a proprietary growth algorithm. Key forecast inputs included evolving regulatory frameworks and demographic shifts in aging populations.
Regulatory policy changes, unexpected technological breakthroughs, and significant shifts in consumer perception are the dominant revision risks. Forecasts reflect assumptions regarding market stability and current competitive dynamics. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Service Laboratory Market
Testing Services
Genetic Toxicology Testing Market
Testing Services
IVD Quality Control Market
Testing Services
Europe Medical Device Testing Market
Testing Services
Global Metabolic Testing Market
Testing Services
Infusion Toxicology Services Market
Testing Services
Anderson Cascade Impactor Market
Testing Services
Global Drug Abuse Testing Market
Testing Services
Special Coagulation Tests Market
Testing Services
Target-Based ADME/ Tox Assay Market
Testing Services
Global IVD Regulatory Affairs Outsourcing Market
Testing Services
Allergy Tester Market
Testing Services
Global Laboratory Proficiency Testing Market
Testing Services
Medical Device Testing, Inspection, and Certification Market
Testing Services
North America Testing Inspection and Certification (TIC) Market
Testing Services
Global Mycoplasma Testing Market