
 In-Vitro Toxicology Testing Market | 2026-2036
In-Vitro Toxicology Testing Market Size, Share, and Industry Trends Forecast 2026-2036
In-Vitro Toxicology Testing Market Intelligence
The capability gap between high-throughput automation specialists and legacy assay providers is reorganizing competitive dynamics in in-vitro toxicology testing. Thermo Fisher Scientific leverages integrated mass spectrometry workflows to sustain technology leadership across pharmaceutical safety applications. Charles River Laboratories International anchors its position through captive biorepository networks that dominate preclinical toxicology service delivery. Eurofins Scientific competes via geographic density of accredited laboratories across European chemical risk assessment corridors.
In-vitro toxicology testing encompasses cell-based, tissue-based, and biochemical methodologies that evaluate substance safety outside living organisms, typically employing human-derived hepatocyte cultures, reconstructed epidermis models, or engineered cardiac microtissues to predict organ-specific injury mechanisms. Cell-based assays command the largest revenue share due to regulatory acceptance for skin and eye irritation endpoints, while organ-on-a-chip platforms represent the fastest-expanding segment as microfluidic liver and lung models displace animal studies in chronic toxicity protocols. Pharmaceutical safety applications generate the deepest margin pools, driven by FDA-mandated IND-enabling studies that require GLP-compliant data packages.
EPA and FDA frameworks in the United States, alongside ECHA REACH requirements in Europe, mandate systematic replacement of vertebrate testing where validated alternatives exist, directly expanding procurement of high-throughput screening and 3D cell culture platforms. The EU Green Deal chemicals strategy and emerging FDA Modernization Act provisions are converging on human-relevant model standards that reshape product development roadmaps. Stakeholders must monitor regulatory qualification timelines for novel organ-on-a-chip submissions to anticipate which platform investments will secure priority market access.
Market Dynamics
Organ-on-a-chip platforms are compressing validation timelines for chronic toxicity protocols, forcing contract research organizations to reconfigure laboratory infrastructure around microfluidic integration.
Growth Catalysts
- REACH compliance mandates:ECHA requirements in Europe systematically phase out vertebrate testing for skin and eye irritation endpoints, expanding procurement of reconstructed human epidermis models.
- Pharmaceutical safety departments:Contract research organizations accelerate adoption of 3D hepatocyte cultures to meet FDA IND-enabling study demands with GLP-compliant data packages.
- Germany's chemical manufacturing density:Regulatory stringency combined with industrial cluster concentration creates sustained demand for high-throughput screening platforms.
Market Restraints
- Primary human hepatocyte supply volatility:Donor tissue availability constraints create batch-to-batch variability that complicates assay standardization.
- Microfluidic consumable costs:Proprietary chip architectures from dominant suppliers lock laboratories into elevated per-test pricing structures.
- OECD validation backlog:Formal regulatory acceptance for novel organ-on-a-chip platforms faces multi-year qualification timelines that delay commercial deployment.
Strategic Opportunities
- Cardiac microtissue applications:Preclinical cardiotoxicity screening represents an underpenetrated endpoint where engineered heart tissues displace hERG channel assays.
- EPA New Approach Methodologies:Federal mandates for reduced mammalian testing create procurement incentives for lung-on-a-chip platforms in inhalation toxicology.
- Biorepository integration:Captive cell banking networks enable longitudinal studies that differentiate service providers through specimen traceability.
Industry Challenges
- Microfluidic engineering talent scarcity:Cross-functional expertise spanning cell biology and chip fabrication remains concentrated in a limited geographic pool.
- Legacy LIMS integration friction:Data architecture from 1990s-era laboratory systems resists seamless incorporation of real-time perfusion monitoring outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Vitro Toxicology Testing Market |
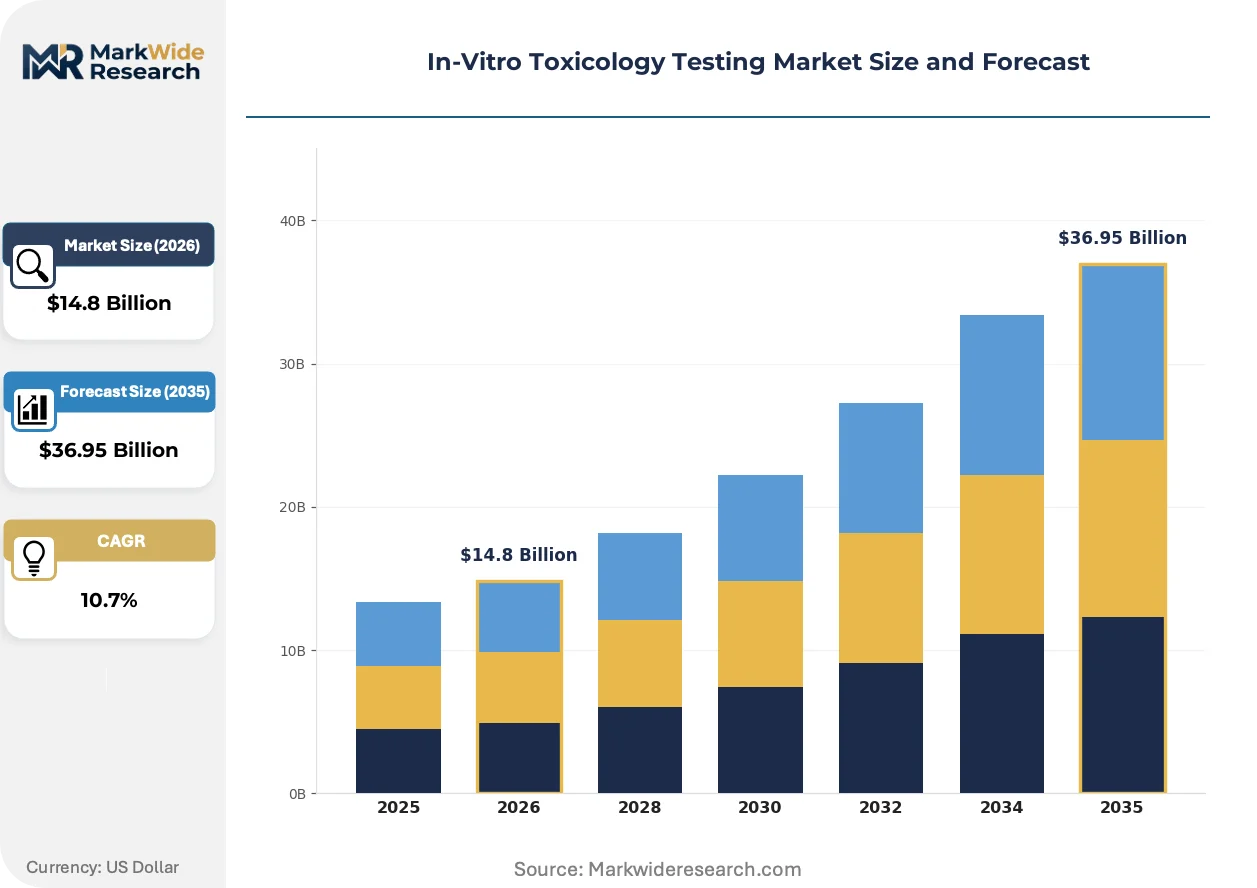
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $36.95 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell-based Assays, Tissue Models, Biochemical Assays, High-Throughput Screening, Organ-on-a-Chip Application: Pharmaceutical Safety, Cosmetic Testing, Chemical Risk Assessment, Environmental Toxicity, Food Safety Evaluation Technology: 3D Cell Culture, Microfluidics, Automated Imaging, Mass Spectrometry, Genomic Profiling End User: Contract Research Organizations, Academic Laboratories, Independent Testing Facilities, Government Agencies |
| Companies Covered | Charles River Laboratories International, Thermo Fisher Scientific, Merck KGaA, Eurofins Scientific, Agilent Technologies, Bio-Rad Laboratories, SGS, Laboratory Corporation of America Holdings, Catalent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Vitro Toxicology Testing Market Strategic Shifts & Innovations
Microphysiological systems are compressing the boundary between preclinical screening and clinical translation, redefining what constitutes sufficient safety evidence for regulatory submission.
Multi-organ microphysiological systems linking liver, kidney, and intestinal models through microfluidic circulation are displacing standalone single-organ assays in chronic toxicity protocols. Pharmaceutical safety groups at mid-tier contract research organizations now specify these platforms in half of new method development contracts. The shift is compressing the addressable market for legacy 2D hepatocyte monocultures.
EU Green Deal chemicals strategy provisions are mandating human-relevant model standards that reshape product development roadmaps for industrial chemical registrants. ECHA guidance documents now explicitly reference organ-on-a-chip data in weight-of-evidence submissions. German chemical manufacturers are responding by pre-qualifying microfluidic liver models for REACH dossier preparation.
Consolidated procurement through centralized toxicology service agreements is displacing decentralized laboratory selection by individual therapeutic program teams. Large pharmaceutical manufacturers now mandate preferred provider networks that standardize assay platforms across development portfolios. This concentration is most visible in Massachusetts and California, where biopharma headquarters operations dictate global laboratory selection criteria.
In-Vitro Toxicology Testing Market Segmentation
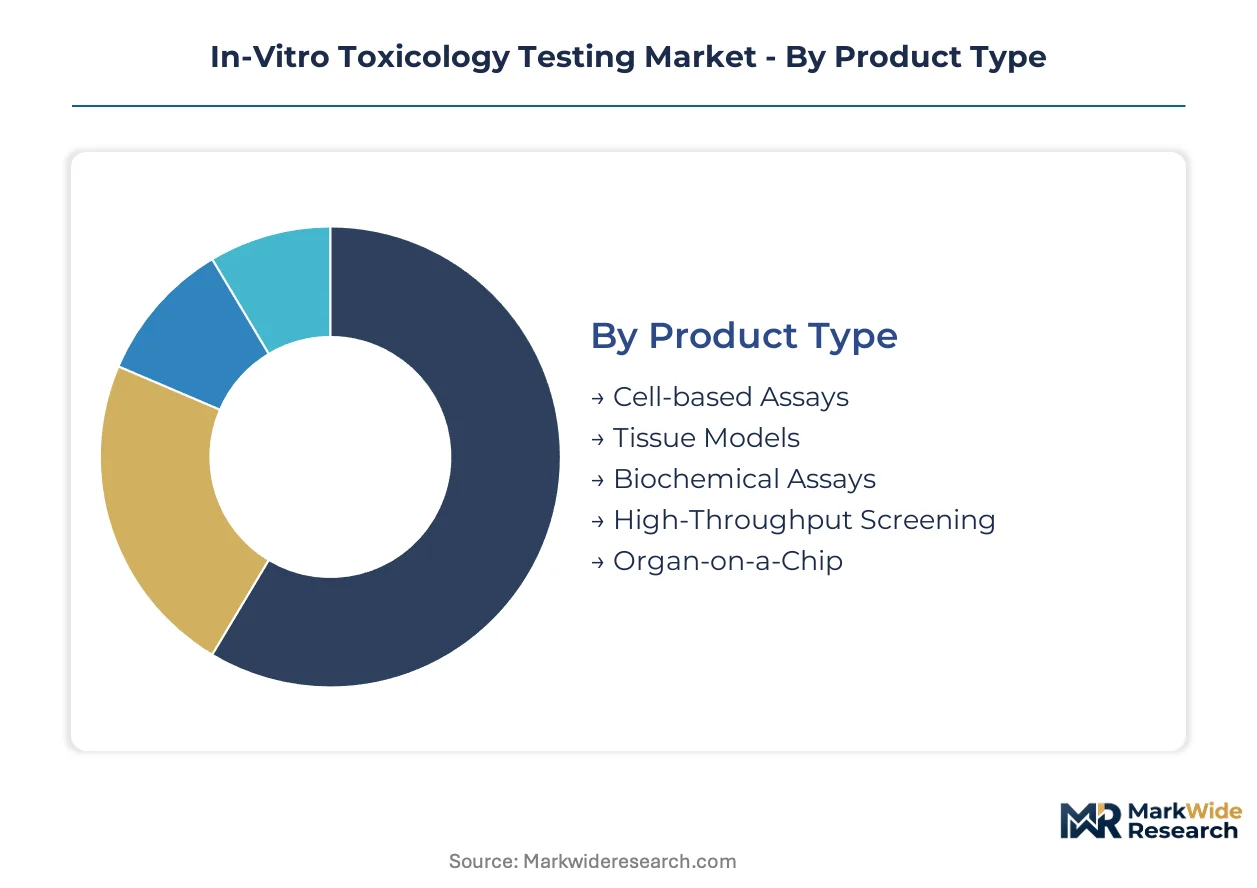
Segmentation in in-vitro toxicology testing reveals how procurement channels favor specific technical formats. Pharmaceutical safety departments route high-value contracts through CROs with integrated platform capabilities, while chemical registrants direct compliance spending toward accredited testing facilities with regulatory pre-qualification.
Product Type:
Channel distribution varies sharply across product categories, with pharmaceutical safety teams consolidating spend on integrated platforms while chemical manufacturers distribute procurement across specialized assay providers.
- Cell-based Assays:Hepatocyte cultures and reconstructed epidermis models dominate current procurement volumes. FDA and ECHA acceptance for skin and eye irritation endpoints channels demand through CROs with GLP certification in Germany and Massachusetts.
- Organ-on-a-Chip:Microfluidic liver and lung platforms command premium pricing in chronic toxicity protocols. REACH dossier preparation in Germany and IND-enabling studies for FDA submission drive fastest expansion in this category.
- Tissue Models:Engineered cardiac microtissues and intestinal constructs serve specialized endpoints.
- Biochemical Assays:Enzyme inhibition and receptor binding tests support mechanistic hazard identification.
- High-Throughput Screening:Automated plate-based systems handle early-stage compound triage for pharmaceutical portfolios.
By volume, cell-based assays lead procurement. By expansion trajectory, organ-on-a-chip platforms are climbing the fastest.
Application:
Cost tiers separate applications by data package complexity, with pharmaceutical safety commanding premium pricing for GLP-compliant submissions while cosmetic testing operates under tighter margin constraints.
- Pharmaceutical Safety:IND-enabling toxicology studies require comprehensive organ-specific injury data. FDA mandates for hERG channel and hepatotoxicity screening concentrate procurement with CROs possessing captive biorepository networks.
- Chemical Risk Assessment:REACH compliance and EPA New Approach Methodologies drive systematic replacement of vertebrate studies. German chemical manufacturers pre-qualify microfluidic platforms for dossier preparation.
- Cosmetic Testing:EU and UK prohibitions on animal testing for finished products channel demand toward reconstructed human epidermis models.
- Environmental Toxicity:EPA mandates for reduced mammalian testing expand procurement of fish embryo and algae-based assays.
- Food Safety Evaluation:EFSA guidelines and FDA food contact notifications require migration and genotoxicity screening.
Pharmaceutical safety generates deepest margins. Chemical risk assessment is gaining share fastest as regulatory deadlines approach.
Technology:
Customer maturity determines technology adoption curves, with large pharmaceutical manufacturers leading on automated imaging while mid-tier CROs lag on microfluidic integration.
- 3D Cell Culture:Spheroid and organoid formats improve metabolic competence over 2D monocultures. Hepatocyte spheroid adoption concentrates in Massachusetts and California headquarters operations that dictate global laboratory standards.
- Microfluidics:Perfusion systems maintain tissue viability over extended culture periods. Supply constraints on engineering talent limit deployment to specialist CROs with dedicated microfabrication partnerships.
- Automated Imaging:High-content screening platforms quantify morphological endpoints at scale.
- Mass Spectrometry:Integrated metabolomics workflows support mechanistic toxicology investigations.
- Genomic Profiling:Transcriptomic signatures enable pathway-based hazard prediction.
Automated imaging holds widest installed base. Microfluidics shows steepest expansion trajectory among emerging platforms.
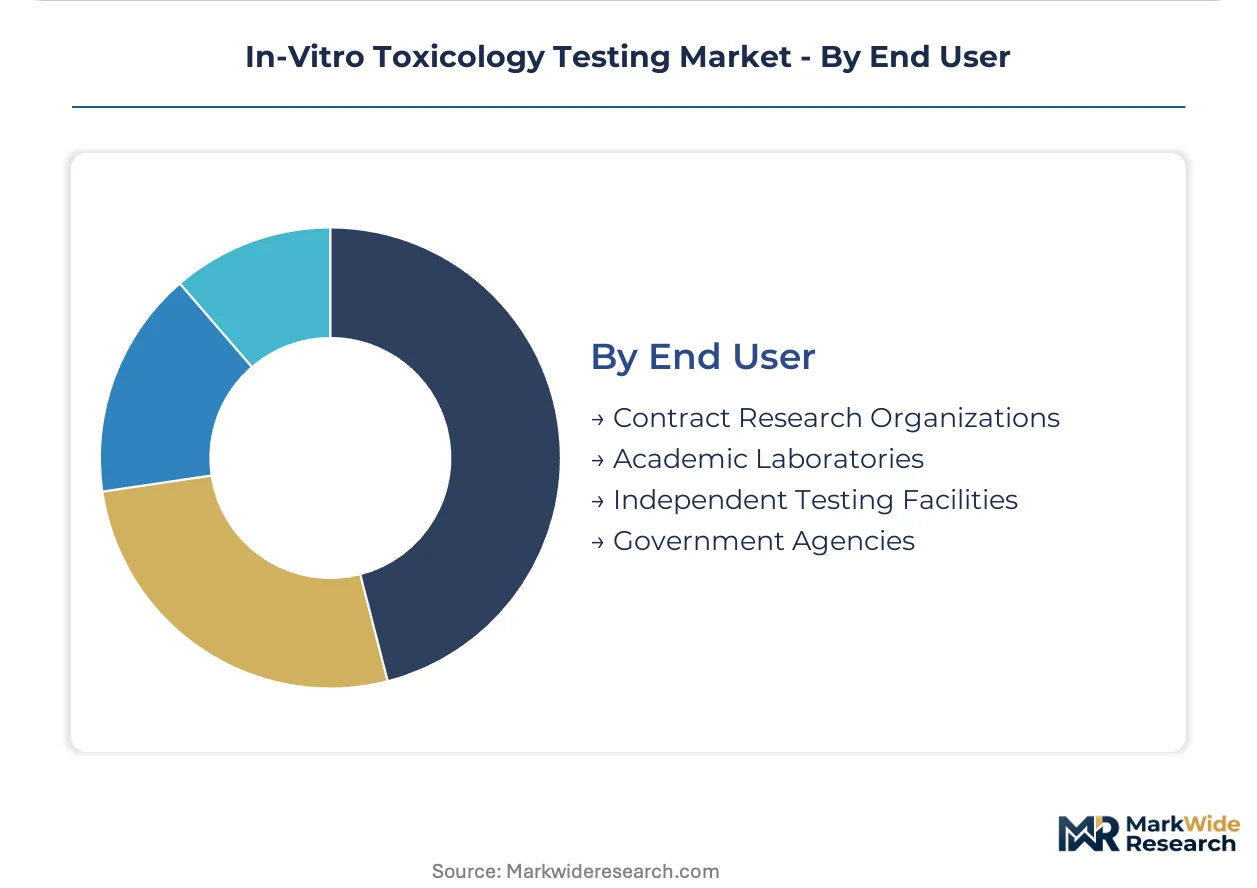
End User:
Geographic concentration of end users shapes regional platform preferences, with German chemical clusters driving organ-on-a-chip qualification while US biopharma corridors favor integrated screening workflows.
- Contract Research Organizations:Full-service toxicology providers manage end-to-end safety packages. Preferred provider networks at large pharmaceutical manufacturers consolidate procurement with CROs possessing multi-organ microphysiological capabilities.
- Academic Laboratories:Research institutions pioneer organ-on-a-chip validation for regulatory qualification. ECHA and EPA collaborative programs channel funding toward university-based method development.
- Independent Testing Facilities:Specialized laboratories serve regional chemical and cosmetic registrants.
- Government Agencies:EPA and ECHA reference laboratories conduct alternative method validation.
CROs command largest revenue share. Academic laboratories are expanding fastest as qualification partnerships multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany absorb premium pricing for organ-on-a-chip platforms without volume erosion, while procurement teams in India and Southeast Asia negotiate aggressively on per-test costs for legacy cell-based assays.
United States
FDA IND-enabling study requirements and EPA New Approach Methodologies drive sustained procurement of high-throughput screening platforms. The FDA Modernization Act provisions accelerate human-relevant model qualification timelines. Massachusetts and California biopharma headquarters operations dictate global laboratory selection criteria for preferred provider networks.
Germany
REACH dossier preparation deadlines and chemical manufacturing cluster density concentrate demand for microfluidic liver models. ECHA guidance documents explicitly reference organ-on-a-chip data in weight-of-evidence submissions. BASF and Bayer pre-qualification programs in Ludwigshafen and Leverkusen validate platforms for regulatory submission.
United Kingdom
Cosmetic testing prohibitions and pharmaceutical safety outsourcing sustain CRO revenue pools. UK REACH transitional measures maintain alignment with ECHA alternative method acceptance criteria. London and Cambridge service providers capture pan-European contracts through GLP certification.
China
NMPA pharmacovigilance reforms and domestic biopharma expansion create procurement growth for hepatocyte-based assays. National toxicology reference laboratories accelerate validation of 3D cell culture platforms. Shanghai and Suzhou CRO clusters invest in automated imaging infrastructure to serve multinational sponsor mandates.
India
CDSCO bioequivalence study volume expansion and contract research cost arbitrage attract pharmaceutical safety outsourcing. Central Drugs Standard Control Organization alignment with ICH guidelines elevates data package standards. Hyderabad and Bangalore service providers upgrade GLP facilities to capture US and European sponsor contracts.
In-Vitro Toxicology Testing Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier that competes on assay-specific expertise or geographic accreditation density. The upper tier commands preferred provider status through captive biorepository networks and multi-organ microphysiological capabilities. Three archetypes dominate: full-service CROs with end-to-end safety packages, technology-integrated platform providers with proprietary consumable lock-in, and accredited testing facilities with regulatory pre-qualification. Consolidation pressure manifests through strategic partnerships for microfluidic engineering access and vertical integration into primary human tissue sourcing.
Within the integrated platform tier, Thermo Fisher Scientific and Charles River Laboratories International exemplify divergent approaches to technology leadership. Thermo Fisher anchors its position through mass spectrometry workflow integration across pharmaceutical safety applications. Charles River occupies a position defined by biorepository network scale and preclinical toxicology service delivery dominance. Eurofins Scientific sits within the geographic density archetype, competing through accredited laboratory concentration across European chemical risk assessment corridors.
| Leading Market Players |
|---|
| Charles River Laboratories International |
| Thermo Fisher Scientific |
| Merck KGaA |
| Eurofins Scientific |
| Agilent Technologies |
| Bio-Rad Laboratories |
| SGS |
| Laboratory Corporation of America Holdings |
| Catalent |
| Others |
Cost & Logistics Intelligence
Biorepository network scale economies in hepatocyte sourcing compress per-assay costs for integrated CROs while fragmenting price-setting power among specialized assay providers. Capacity utilization at captive cell banking facilities in Massachusetts and Germany anchors premium pricing tiers for GLP-compliant safety packages, whereas spot-market hepatocyte procurement forces margin compression on mid-tier laboratories without long-term donor agreements.
Pricing Analysis
Consumable service contracts and extended platform licensing agreements drive lifetime value beyond initial instrument placement. Three-tier pricing structure across premium GLP-certified, standard research-grade, and economy screening tiers separates pharmaceutical safety departments from chemical registrants and academic laboratories. Cost compression in research-grade hepatocyte assays is intensifying because donor tissue spot markets expand supply volatility. Chemical manufacturers in Germany exhibit lowest price sensitivity due to REACH compliance deadlines, while cosmetic testing laboratories in India negotiate aggressively on per-test costs for reconstructed epidermis models.
Supply Chain Analysis
Strategic stockpiling of primary human hepatocytes dominates procurement strategy among integrated CROs, whereas just-in-tissue sourcing prevails in academic and mid-tier service laboratories. Supply concentration in the United States, Germany, and China anchors global hepatocyte biorepository networks, with proprietary chip architectures from microfluidic specialists drawing from concentrated engineering talent pools in Massachusetts and California. Single-source vulnerability on microfluidic consumables creates supply chain risk for laboratories locked into dominant platform ecosystems. Distribution runs through centralized toxicology service agreements that consolidate procurement with preferred provider networks at large pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through preferred provider networks at large pharmaceutical manufacturers, fragmenting laboratory selection authority that previously resided with individual therapeutic program teams. This consolidation reshapes competitive dynamics toward integrated platform capabilities and away from specialized assay providers.
For Market Incumbents: Compound defensive positioning through captive biorepository network expansion and multi-organ microphysiological capability integration. Threat from organ-on-a-chip platform specialists demands backward integration into primary human tissue sourcing to secure hepatocyte supply chains. Leverage GLP certification investment as a channel control mechanism to lock preferred provider status with consolidated pharmaceutical procurement teams.
For New Entrants and Emerging Players: Anchor in cardiac microtissue applications where engineered heart tissues displace legacy hERG channel assays with limited incumbent platform lock-in. White-space targets include EPA New Approach Methodologies procurement for lung-on-a-chip platforms in inhalation toxicology, and mid-tier CRO microfluidic engineering partnerships where talent scarcity constrains rapid incumbent response. Go-to-market angle should emphasize regulatory pre-qualification support for REACH dossier preparation in German chemical manufacturing clusters.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-integrated CROs with biorepository scale over point-solution assay providers facing margin compression. Long-term viability across the analysis window rests on regulatory qualification timelines for novel organ-on-a-chip submissions that determine which platform investments secure priority market access. Acquisition target archetype: specialist microfluidic CROs with ECHA collaborative validation partnerships. Signal to watch is OECD test guideline adoption velocity for multi-organ microphysiological systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Biorepository Network Expansion | Captive hepatocyte sourcing secures supply chain control against donor tissue volatility. |
| Multi-Organ Microphysiological Integration | Linked liver-kidney-intestinal models displace standalone assays in chronic toxicity protocols. |
| Regulatory Pre-Qualification Investment | ECHA and EPA collaborative programs accelerate platform acceptance for REACH dossiers. |
| Microfluidic Engineering Partnership | Dedicated fabrication alliances overcome talent scarcity constraining platform deployment. |
| Preferred Provider Network Consolidation | Centralized procurement agreements lock long-term contracts with pharmaceutical safety departments. |
Research Approach
Cross-validation between primary field engagement with contract research organization toxicology directors and secondary analysis of ECHA guidance documents anchors the qualitative findings. Drug development executives, regulatory affairs leads at pharmaceutical manufacturers, laboratory procurement managers, and academic method validation specialists contributed structured input. FDA Modernization Act provisions, EPA New Approach Methodologies frameworks, REACH compliance timelines, and OECD test guideline development records provided secondary validation. Bottom-up assay platform adoption estimates and top-down market sizing triangulate volume and value outputs.
Sensitivity analysis on regulatory qualification timelines and hepatocyte supply volatility informs projection robustness. Segmentation dimensions span product type, application, technology, and end user, with geographic regulatory cluster and GLP certification tier as additional modeling variables. CAGRs derive from fitted growth curves across the projection horizon, incorporating IND-enabling study volume trends and chemical registration deadline density as industry-specific forecast inputs.
Material uncertainties — OECD validation backlog delays, primary human hepatocyte donor availability shocks, and microfluidic consumable cost inflation — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory acceptance velocity for novel organ-on-a-chip platforms. Revision becomes warranted when ECHA or EPA test guideline adoption crosses thresholds that accelerate or retard commercial deployment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Global Molecular Quality Controls Market
Testing Services
Europe Esoteric Testing Market
Testing Services
Fertility and Pregnancy Rapid Test Kits Market
Testing Services
Biological Indicator Incubators Market
Testing Services
Comprehensive Metabolic Panel (CMP) Testing Market
Testing Services
Global HPV Testing and Pap Test Market
Testing Services
Passive Dosimetry Equipment and Service Market
Testing Services
Global Enteric Disease Testing Market
Testing Services
Global Metabolic Testing Market
Testing Services
Global Sterility Testing Market
Testing Services
Blood Borne Testing Market
Testing Services
Human Papilloma Virus Testing Market
Testing Services
Global Diagnostic Testing Market
Testing Services
Ovulation Testing Kits Market
Testing Services
Antibiotic Susceptibility Testing Market