
 Sickle Cell Disease Market | 2026-2036
Sickle Cell Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Sickle Cell Disease Market Intelligence
The capital-intensity divergence between gene therapy developers and small-molecule manufacturers is rotating competitive investment toward manufacturing scale-up and vector production capabilities. Novartis AG leverages its established hematology infrastructure to sustain commercial reach across European and North American treatment centers. Bluebird Bio, Inc. anchors its position through in-house lentiviral vector manufacturing that controls supply constraints for curative therapies. CRISPR Therapeutics differentiates by specializing in ex vivo gene-editing platforms that compete on durability claims against viral vector alternatives.
Sickle cell disease denotes an inherited hemoglobinopathy caused by a point mutation substituting valine for glutamic acid at the sixth position of the beta-globin chain, producing polymerized hemoglobin S under deoxygenation that distorts erythrocytes into sickled forms and precipitates vaso-occlusive crises, hemolytic anemia, and progressive end-organ damage. Pharmacotherapy retains the largest patient volume today, though gene therapy segments capture disproportionate value per patient as payers negotiate outcomes-based arrangements for one-time curative interventions. Hospital pharmacy channels dominate distribution for infused and inpatient-administered therapies, while retail and online pharmacy penetration expands for oral chronic medications like voxelotor and L-glutamine.
The FDA's accelerated approval framework and orphan drug exclusivity provisions shape development economics, while the EMA's PRIME designation and EU Health Technology Assessment convergence influence European market access timelines for novel modalities. Reimbursement authorities in France, Germany, and England are piloting annuity-based payment structures to address gene therapy affordability at the national level. Stakeholders must monitor how Medicaid managed care organizations in the United States structure gene therapy coverage policies, as these decisions will determine whether curative treatments reach the publicly insured patient majority.
Market Dynamics
Gene therapy manufacturing capacity constraints are compressing competitive timelines as developers race to secure lentiviral vector supply before payer coverage policies solidify around outcomes-based reimbursement models.
Growth Catalysts
- FDA Accelerated Approval:Compressed review timelines for gene therapies enable earlier commercial entry for disease-modifying interventions, reducing development risk for curative modalities.
- Medicaid Expansion:Extended coverage mandates in multiple US states have built the largest diagnosed and insured patient pool globally, concentrating addressable demand.
- Newborn Screening Mandates:Universal screening protocols identify patients at birth, enabling early intervention and lifetime value capture for chronic therapy providers.
Market Restraints
- Vector Manufacturing Bottleneck:Lentiviral vector production concentrates among a handful of contract manufacturers, creating supply risk for gene therapy developers.
- Gene Therapy Cost Structure:One-time curative interventions carry price tags that strain national reimbursement frameworks and Medicaid managed care budgets.
- Specialized Infusion Infrastructure:Treatment administration requires dedicated sickle cell infusion centers, limiting geographic accessibility for rural patient populations.
Strategic Opportunities
- Annuity-Based Payment Models:France, Germany, and England are piloting installment structures for gene therapies, spreading fiscal burden across budget cycles.
- Ex Vivo Gene Editing:CRISPR-based platforms offer manufacturing advantages over viral vectors, creating white space for non-viral curative approaches.
- Retail Pharmacy Penetration:Oral chronic medications like voxelotor and L-glutamine are expanding beyond hospital channels into community pharmacy networks.
Industry Challenges
- Cell Processing Workforce Gap:Gene therapy manufacturing requires specialized technicians for apheresis and cell handling, with training pipelines lagging demand.
- HTA Convergence Complexity:EU Health Technology Assessment alignment creates multi-jurisdictional evidence requirements that extend market access timelines.
- Vector Supply Security:In-house vector production demands capital-intensive cleanroom infrastructure that mid-cap developers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sickle Cell Disease Market |
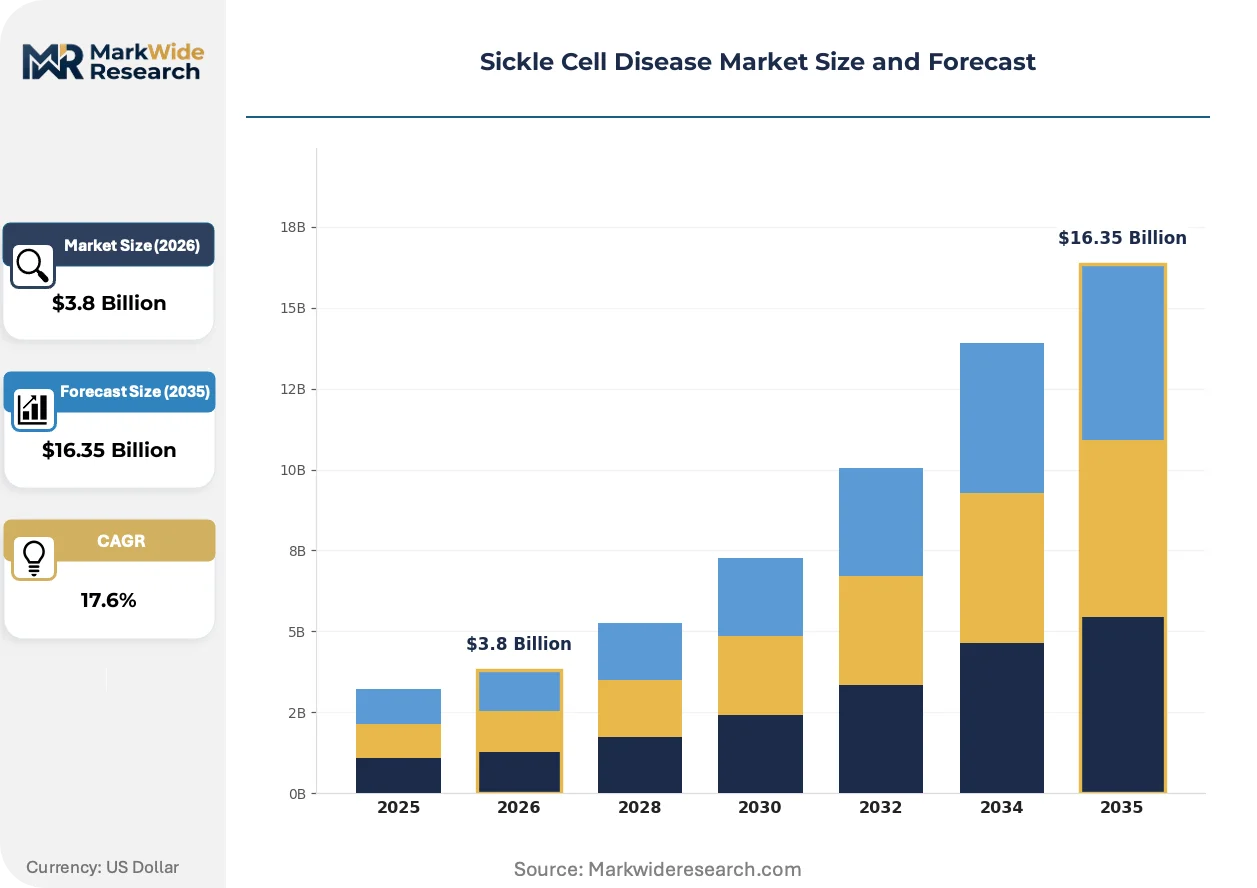
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Transfusion, Pharmacotherapy, Gene Therapy, Stem Cell Transplant End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Therapy Area: Pain Management, Infection Prevention, Disease-Modifying Therapy, Symptomatic Treatment Distribution Channel: Online Pharmacy, Retail Pharmacy, Hospital Pharmacy, Direct Sales |
| Companies Covered | Novartis AG, Bluebird Bio, Inc., Pfizer Inc., CRISPR Therapeutics, Bristol-Myers Squibb Company, Vertex Pharmaceuticals Inc., Emmaus Medical, Inc., Global Blood Therapeutics, Inc., GlycoMimetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sickle Cell Disease Market Strategic Shifts & Innovations
Therapeutic modality diversification is splitting competitive investment between incremental small-molecule improvements and transformative gene-editing platforms with divergent manufacturing and commercial requirements.
Gene editing is fragmenting the curative therapy landscape as CRISPR-based ex vivo platforms compete with lentiviral vector gene addition approaches on durability and manufacturing scalability claims. Academic medical centers and dedicated sickle cell centers are piloting these technologies for patient selection and long-term follow-up protocols. The technology is fragmenting previously unified payer negotiations into product-specific coverage determinations based on mechanism-of-action evidence packages.
EMA's PRIME designation and parallel EU Health Technology Assessment convergence are compressing European market access timelines for novel modalities while raising evidence thresholds. Manufacturers must now synchronize clinical trial endpoints across multiple national reimbursement authorities. Gene therapy developers targeting European commercialization are restructuring regulatory strategies around centralized HTA submissions rather than sequential national filings.
Hospital systems are consolidating sickle cell care into dedicated infusion centers to capture gene therapy administration revenue and reduce emergency department utilization. This channel concentration shifts purchasing influence from individual physicians to pharmacy and therapeutics committees with formal technology assessment processes. The United States exhibits the most pronounced consolidation, with major academic medical centers in Georgia, California, and New York establishing regional referral networks.
Sickle Cell Disease Market Segmentation
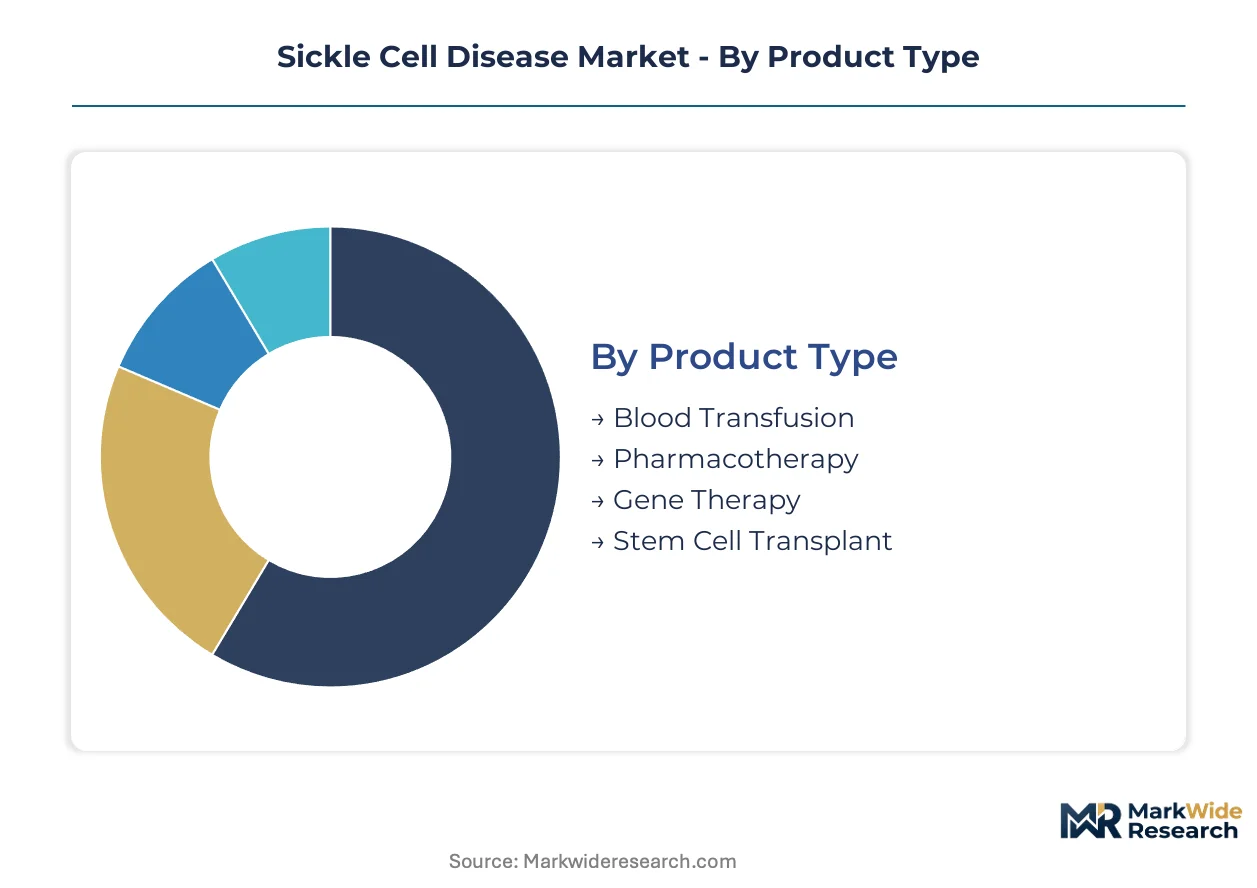
Segmentation in the sickle cell disease market reveals divergent regulatory pathways and reimbursement structures that determine commercial viability across therapeutic modalities. Treatment modality selection directly shapes manufacturing investment, distribution infrastructure, and payer negotiation leverage.
Product Type:
FDA accelerated approval pathways and EMA PRIME designation create tiered regulatory timelines that advantage certain modalities over others in market entry sequencing.
- Gene Therapy:Ex vivo and in vivo gene-editing platforms deliver potentially curative outcomes through single-dose administration. Payer negotiations in France, Germany, and England are piloting annuity-based payment structures to accommodate price points that strain national reimbursement frameworks.
- Pharmacotherapy:Oral and infused small-molecule agents including hemoglobin polymerization inhibitors and anti-sickling agents manage chronic symptoms and reduce vaso-occlusive crisis frequency. Medicaid managed care organizations in the United States structure coverage policies around chronic therapy formularies, concentrating demand in states with expanded eligibility.
- Blood Transfusion:Red cell exchange and simple transfusion protocols address acute complications and stroke prevention in high-risk pediatric populations.
- Stem Cell Transplant:Allogeneic hematopoietic stem cell transplantation from matched sibling donors offers curative potential for eligible patients with severe disease phenotypes.
Established volume favors Pharmacotherapy; emerging adoption favors Gene Therapy.
End User:
Site-of-care economics and reimbursement rate differentials are concentrating investment in specific care delivery settings.
- Hospitals:Academic medical centers and dedicated sickle cell infusion centers administer infused therapies, gene therapy conditioning regimens, and manage acute vaso-occlusive crises. Major systems in Georgia, California, and New York are establishing regional referral networks to capture gene therapy administration revenue.
- Clinics:Outpatient hematology clinics provide chronic disease monitoring, transfusion services, and transition care for adolescent patients. These settings balance reimbursement rates against specialized staffing requirements.
- Homecare:Home infusion services and nursing support extend treatment access for patients in rural geographies distant from specialized centers.
- Rehabilitation Centers:Post-acute facilities address functional recovery following stroke, avascular necrosis, and other sickle cell complications.
Reimbursement rates favor Hospitals; geographic accessibility gains favor Homecare.
Therapy Area:
Clinical endpoint requirements and evidence generation costs vary substantially across therapeutic objectives.
- Disease-Modifying Therapy:Interventions targeting underlying disease pathology, including gene therapies and agents that increase fetal hemoglobin production. FDA orphan drug exclusivity provisions and outcomes-based reimbursement pilots shape development economics.
- Pain Management:Opioid and non-opioid analgesic protocols, including patient-controlled analgesia for acute vaso-occlusive crises. Hospital emergency departments remain the dominant site for severe episode management.
- Infection Prevention:Antibiotic prophylaxis, immunization protocols, and splenic dysfunction management reduce life-threatening infectious complications in pediatric and adult populations.
- Symptomatic Treatment:Supportive care addressing anemia-related fatigue, priapism, leg ulcers, and other chronic manifestations.
Regulatory scrutiny favors Disease-Modifying Therapy; volume concentration favors Pain Management.
Distribution Channel:
Product characteristics and administration requirements dictate channel selection and margin structure.
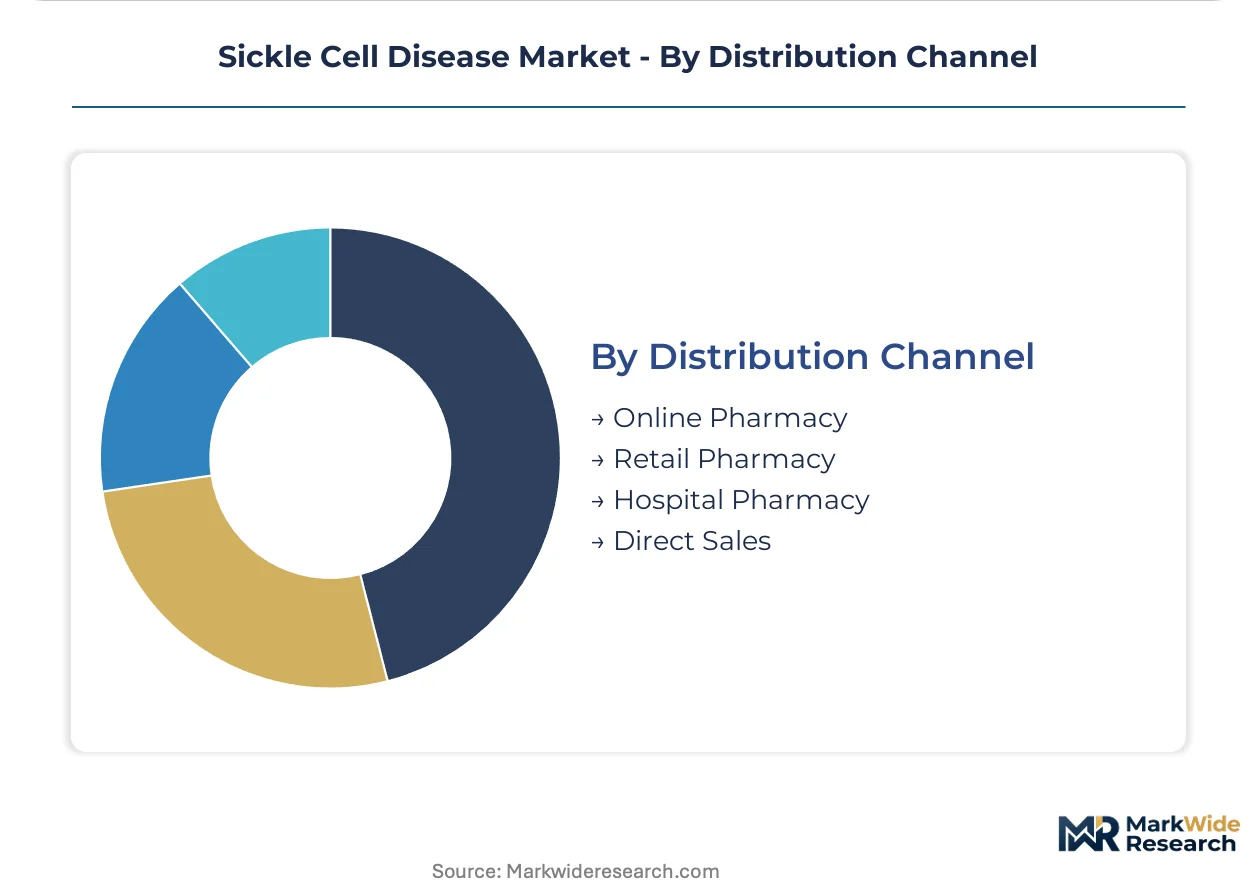
- Hospital Pharmacy:Captures infused therapies, gene therapy products, and inpatient-administered agents requiring specialized handling. Pharmacy and therapeutics committees exert growing purchasing influence as care consolidates into dedicated centers.
- Retail Pharmacy:Oral chronic medications including hemoglobin polymerization inhibitors and amino acid supplements are expanding into community pharmacy networks. Voxelotor and L-glutamine prescriptions drive volume migration from hospital to retail settings.
- Online Pharmacy:Mail-order and digital platforms serve stable chronic prescriptions with refill predictability.
- Direct Sales:Manufacturer-to-provider arrangements for gene therapies and specialized biologics with restricted distribution requirements.
Margin protection favors Direct Sales; patient convenience expansion favors Online Pharmacy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies, with Medicaid-managed care states in the United States absorbing curative therapy costs while emerging markets remain dependent on donor-funded chronic care programs.
United States
Medicaid expansion across 40 states has created the world's largest insured sickle cell patient pool, with newborn screening mandates in all 50 states identifying cases at birth. FDA accelerated approval pathways compress gene therapy review timelines, enabling earlier commercial entry. Major academic medical centers in Georgia, California, and New York operate dedicated infusion centers that capture gene therapy administration revenue.
United Kingdom
NHS England's specialized commissioning framework concentrates sickle cell care in designated treatment centers across London, Birmingham, and Manchester. NICE technology appraisals determine reimbursement for novel therapies, with outcomes-based payment pilots underway for curative interventions. The National Haemoglobinopathy Registry tracks patient outcomes to support HTA submissions.
Germany
G-BA benefit assessments govern market access for disease-modifying therapies, with orphan drug status providing pricing advantages for manufacturers. University hospitals in Berlin, Hamburg, and Munich maintain hematology centers of excellence with gene therapy administration capabilities. The country's statutory health insurance system spreads treatment costs across 73 million insured lives.
France
ANSM regulates gene therapy products under the ATU early access framework, while HAS evaluates clinical benefit for reimbursement listing. The French sickle cell network centers care in Paris, Lyon, and Marseille, with overseas territories in the Caribbean and Indian Ocean contributing disproportionate patient volumes. Pilot annuity-based payment structures address gene therapy affordability.
Brazil
ANVISA's regulatory framework for advanced therapies is evolving to accommodate gene therapy submissions, with reliance on importation for specialized treatments. SUS provides universal coverage for chronic care, though access to curative modalities remains limited to private insurance and academic research protocols. Reference centers in São Paulo, Rio de Janeiro, and Minas Gerais coordinate national care.
Sickle Cell Disease Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding lentiviral vector manufacturing capabilities and the lower tier competing on small-molecule formulations. The market structure separates gene therapy developers with in-house production assets from manufacturers dependent on contract supply. Three archetypes dominate: large-cap diversified pharmaceuticals with hematology infrastructure, mid-cap gene therapy specialists with captive vector capacity, and emerging ex vivo gene-editing platforms. Competitive moves concentrate on securing manufacturing scale and structuring outcomes-based payer contracts.
Within the integrated pharmaceutical tier, Novartis AG leverages established hematology infrastructure across European and North American treatment centers. Bluebird Bio, Inc. exemplifies the captive manufacturing archetype through in-house lentiviral vector production that controls supply constraints. CRISPR Therapeutics occupies a position in the ex vivo gene-editing segment, competing on manufacturing scalability claims against viral vector alternatives.
| Leading Market Players |
|---|
| Novartis AG |
| Bluebird Bio, Inc. |
| Pfizer Inc. |
| CRISPR Therapeutics |
| Bristol-Myers Squibb Company |
| Vertex Pharmaceuticals Inc. |
| Emmaus Medical, Inc. |
| Global Blood Therapeutics, Inc. |
| GlycoMimetics |
| Others |
Cost & Logistics Intelligence
Ninety-to-one-hundred-twenty-day vector manufacturing lead times concentrate pricing power among lentiviral producers in the United States and Europe, while gene therapy developers absorb cost pass-through through outcomes-based contract structures. This inventory intensity ties payment model innovation directly to supply security investments.
Pricing Analysis
Outcomes-based reimbursement and long-term follow-up service contracts drive lifetime value for gene therapy developers, with annuity structures spreading fiscal burden across budget cycles. Three-tier pricing separates curative gene therapies from chronic small-molecule agents from supportive care interventions, with FDA orphan drug exclusivity providing pricing advantages for disease-modifying modalities. Cost compression in viral vector supply chains is intensifying as developers compete for limited contract manufacturing slots. Medicaid managed care organizations exhibit highest price sensitivity; private payers with risk-sharing frameworks show lowest.
Supply Chain Analysis
Inventory lead times of four to six months for lentiviral vectors concentrate supply risk among United States, United Kingdom, and German contract manufacturers with GMP-certified cleanroom infrastructure. Gene therapy production draws from plasmid DNA, cell culture media, and specialized apheresis collection systems as critical inputs. Single-source vulnerability in vector production creates bottleneck exposure for mid-cap developers without captive manufacturing. Distribution runs through hospital pharmacy channels for infused therapies, with direct manufacturer-to-provider arrangements for gene therapies with restricted handling requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sickle cell disease therapeutics represent an early-cycle expansion story, with FDA accelerated approval pathways compressing development timelines and enabling earlier commercial entry for disease-modifying interventions.
For Market Incumbents: Fortify vector manufacturing capacity through in-house cleanroom investments or exclusive contract manufacturing arrangements to secure supply before payer coverage policies solidify. Lock in preferred provider status with dedicated sickle cell infusion centers in Georgia, California, and New York through outcomes-based partnership structures. Defensive consolidation around lentiviral production assets counters emerging ex vivo gene-editing platforms.
For New Entrants and Emerging Players: Lead with non-viral delivery platforms targeting the manufacturing scalability white space created by vector supply constraints. Prioritize Medicaid expansion states with established newborn screening infrastructure for initial geographic penetration. Partner with academic medical centers for patient selection and long-term follow-up protocols as the go-to-market anchor.
For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical hematology divisions with underutilized gene therapy assets. The five-to-ten year viability window favors developers with demonstrated durability data and established payer contracts over preclinical platforms. Watch FDA gene therapy approval velocity as the inflection indicator for manufacturing capacity investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | In-house lentiviral vector production at Bluebird Bio controls supply constraints for curative therapies. |
| Regulatory Approval Pathway | FDA accelerated approval compresses review timelines for CRISPR Therapeutics' ex vivo gene-editing platform. |
| Hospital System Partnership | Academic medical centers in Georgia and California establish regional referral networks for gene therapy administration. |
| Reimbursement Strategy | Annuity-based payment pilots in France, Germany, and England address gene therapy affordability at national levels. |
| Pipeline Diversification | Vertex Pharmaceuticals advances small-molecule fetal hemoglobin inducers alongside gene therapy investments. |
Research Approach
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases anchors the qualitative findings. Bottom-up patient volume estimates and top-down reimbursement expenditure analysis triangulate market sizing across treatment modalities.
Sensitivity analysis around vector manufacturing capacity assumptions, payer coverage adoption curves, and gene therapy durability endpoints shapes the analytical framework across the projection horizon. Segmentation dimensions include treatment modality, administration route, site of care, and regional regulatory cluster. CAGRs derive from patient population growth, therapy penetration rates, and pricing evolution for chronic versus curative interventions.
Forecasts assume regulatory continuity in FDA accelerated approval and EMA PRIME designation regimes; material policy shifts would require re-modeling. Gene therapy manufacturing bottlenecks, Medicaid managed care coverage determinations, and HTA convergence timelines represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Malignant Lymphoma Market
Hematology
AL Amyloidosis Therapeutics Market
Hematology
Graft vs Host Disease Market
Hematology
At-Home Hematology Testing Market
Hematology
Global Hodgkin Lymphoma Treatment Market
Hematology
Hypereosinophilic Syndrome Market
Hematology
Radiation-Induced Myelosuppression Treatment Market
Hematology
Hemocytometer Market
Hematology
Graft Versus Host Disease (Gvhd) Treatment Market
Hematology
Bleeding Disorders Therapeutics Market
Hematology
Hairy Cell Leukemia Treatment Market
Hematology
Hemostatic Spray Market
Hematology
Anemia Drugs Market
Hematology
Febrile Neutropenia Market
Hematology
Global Hemoglobin Meter Market