
 Hemoglobinopathies Treatment Market | 2026-2036
Hemoglobinopathies Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hemoglobinopathies Treatment Market Outlook
Gene therapy manufacturing expertise is bifurcating the competitive landscape into firms with in-house viral vector capacity and those dependent on contract manufacturers. Novartis AG leverages its established cell and gene therapy infrastructure to sustain production scale for sickle cell interventions. bluebird bio anchors its position through specialized lentiviral vector platforms tailored to beta-thalassemia applications. Vertex Pharmaceuticals differentiates via CRISPR-edited autologous stem cell programs that compete directly with viral-based alternatives.
Hemoglobinopathies treatment encompasses therapeutic interventions targeting inherited hemoglobin disorders, including pharmacologic agents that modify fetal hemoglobin expression, transfusion protocols maintaining adequate oxygen-carrying capacity, and gene-editing modalities correcting beta-globin mutations at the DNA level. The primary purpose spans symptom mitigation, complication prevention, and curative intent through hematopoietic stem cell modification. Gene therapy represents the fastest-expanding segment as one-time administration models displace chronic transfusion dependence, while blood transfusion retains the largest patient volume base across thalassemia and sickle cell disease applications. Hydroxyurea occupies a mature, cost-sensitive position with established oral delivery routes, though iron chelation therapy commands significant margin pools due to lifelong administration requirements in heavily transfused populations.
FDA accelerated approval pathways and EMA adaptive licensing frameworks compress development timelines for novel hemoglobinopathy therapeutics, while WHO prequalification standards shape access dynamics in low-income endemic regions. The EU AI Act and GDPR impose data governance requirements on real-world evidence collection for gene therapy long-term follow-up, influencing trial design and post-market surveillance obligations. Stakeholders must monitor regulatory divergence between adaptive licensing systems and traditional evidentiary standards as reimbursement negotiations increasingly hinge on outcomes-based frameworks rather than conventional clinical endpoints.
Market Dynamics
Gene therapy manufacturing scale-up is compressing commercialization timelines while fragmenting competitive advantage between vector producers and therapy developers. The shift from chronic transfusion models to one-time curative interventions is restructuring reimbursement negotiations and patient access pathways across national health systems.
Growth Catalysts
- EMA Adaptive Licensing:Conditional approval frameworks compress phase III-to-market intervals for beta-thalassemia gene therapies, enabling earlier revenue recognition for developers.
- Newborn Screening Mandates:Saudi Arabia's national hemoglobinopathy screening program expands addressable patient pools through systematic identification of sickle cell and thalassemia cases at birth.
- CRISPR Editing Platforms:Autologous stem cell modification technologies reduce allogeneic donor dependency, broadening curative intervention eligibility beyond matched-sibling transplant candidates.
Market Restraints
- Viral Vector Supply Concentration:Lentiviral and AAV manufacturing capacity clusters among three contract development organizations, creating single-source risks for late-stage gene therapy programs.
- Plasmid DNA Input Volatility:GMP-grade plasmid supply constraints extend viral vector production lead times, delaying clinical trial enrollment and commercial batch release.
- Allogeneic Transplant Substitution:Matched unrelated donor registries and haploidentical protocols retain cost advantages for pediatric patients with available donors, limiting gene therapy addressable markets.
Strategic Opportunities
- Sub-Saharan Africa Penetration:WHO prequalification pathways for simplified transfusion protocols and oral iron chelators address the highest sickle cell disease prevalence region with minimal current biologic intervention.
- Real-World Evidence Monetization:EU AI Act-compliant registry infrastructure enables outcomes-based pricing negotiations with French and German statutory health insurers for gene therapy long-term follow-up.
- Point-of-Care Gene Editing:Ex vivo CRISPR processing at regional transplantation centers eliminates centralized manufacturing logistics, expanding treatment access to non-urban hematology centers.
Industry Challenges
- Vector Bioprocess Engineering Talent Scarcity:Viral vector upstream and downstream optimization requires specialized cell culture expertise that outpaces current biologics manufacturing training pipelines.
- Cross-Border Sample Logistics:GDPR and HIPAA divergences complicate international shipment of patient-derived hematopoietic stem cells for centralized gene editing processing, extending vein-to-vein timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemoglobinopathies Treatment Market |
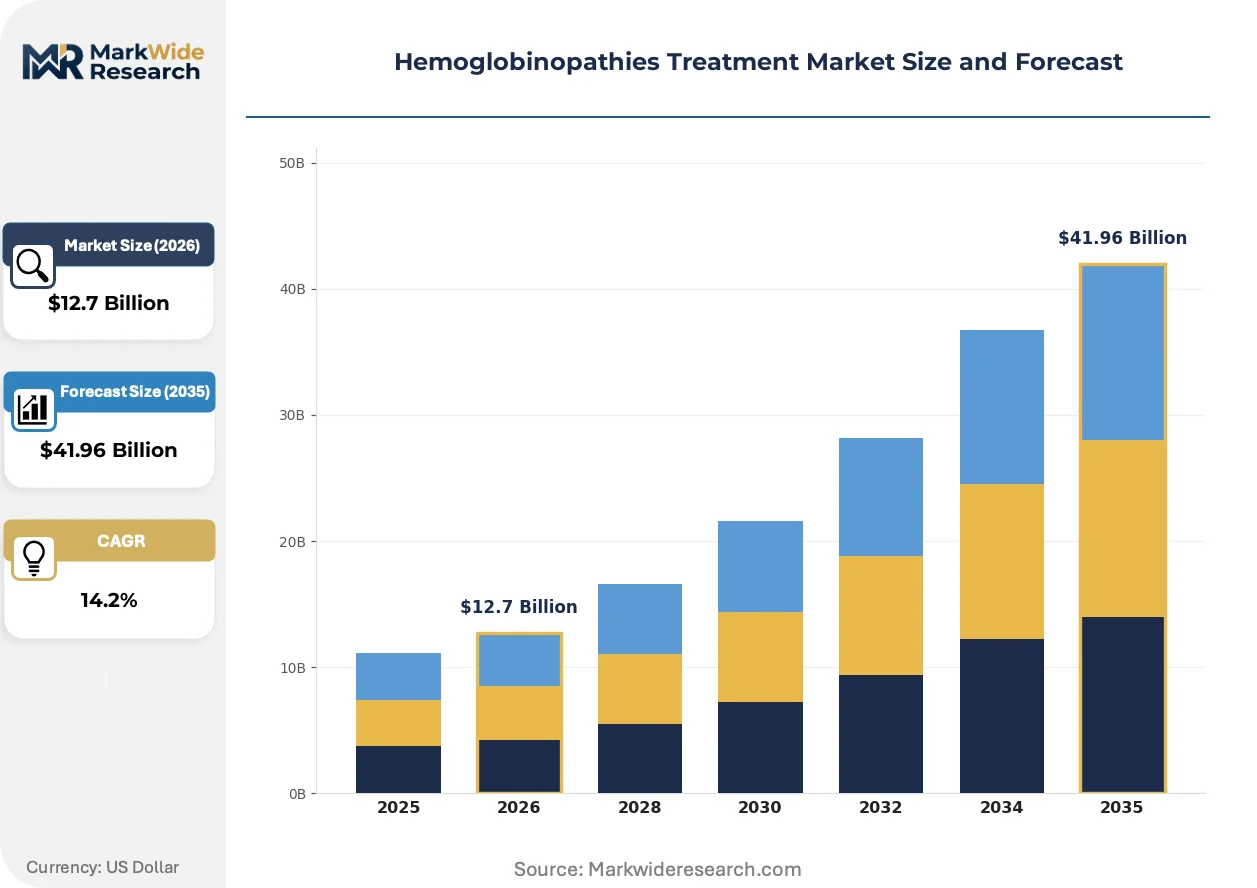
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $41.96 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Transfusion, Iron Chelation Therapy, Gene Therapy, Hydroxyurea End User: Hospitals, Specialty Clinics, Homecare Settings, Blood Banks Delivery Mode: Oral, Injectable, Intravenous, Subcutaneous Application: Thalassemia, Sickle Cell Disease, Anemia, Others |
| Companies Covered | Novartis AG, bluebird bio, Sanofi SA, Pfizer Inc., Global Blood Therapeutics, Emmaus Life Sciences, Vertex Pharmaceuticals, Sangamo Therapeutics, Agios Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemoglobinopathies Treatment Market Strategic Shifts
Next-generation manufacturing modalities and adaptive regulatory frameworks are compressing development cycles while fragmenting traditional competitive moats. The convergence of cell processing automation with real-world evidence infrastructure is reshaping how curative therapies achieve market access and reimbursement.
CRISPR-Cas9 editing systems are miniaturizing through electroporation-based ribonucleoprotein delivery, eliminating viral vector packaging constraints. Pediatric hematology centers in the United States are adopting these electroporation workflows for ex vivo stem cell modification, reducing manufacturing complexity and enabling same-facility processing. This vector-free approach is compressing production costs and accelerating site certification timelines for academic medical centers.
REACH and EU AI Act data governance requirements are mandating algorithmic transparency for real-world evidence platforms tracking gene therapy durability. Pharmaceutical sponsors must now document training data provenance and model validation protocols for longitudinal patient registries used in adaptive licensing submissions. French and German reimbursement authorities are leveraging these structured datasets to negotiate indication-specific pricing rather than therapy-class benchmarks.
Hospital-at-home transfusion models are displacing traditional infusion center dependence for chronic thalassemia patients. Home nursing networks and portable infusion pumps enable deferasirox-chelated patients to receive erythrocyte transfusions outside tertiary hospital settings, reducing facility overhead and travel burden. Saudi Arabia's sovereign health funds are piloting these decentralized protocols to expand capacity at specialized hemoglobinopathy centers in Riyadh and Jeddah.
Hemoglobinopathies Treatment Market Segmentation
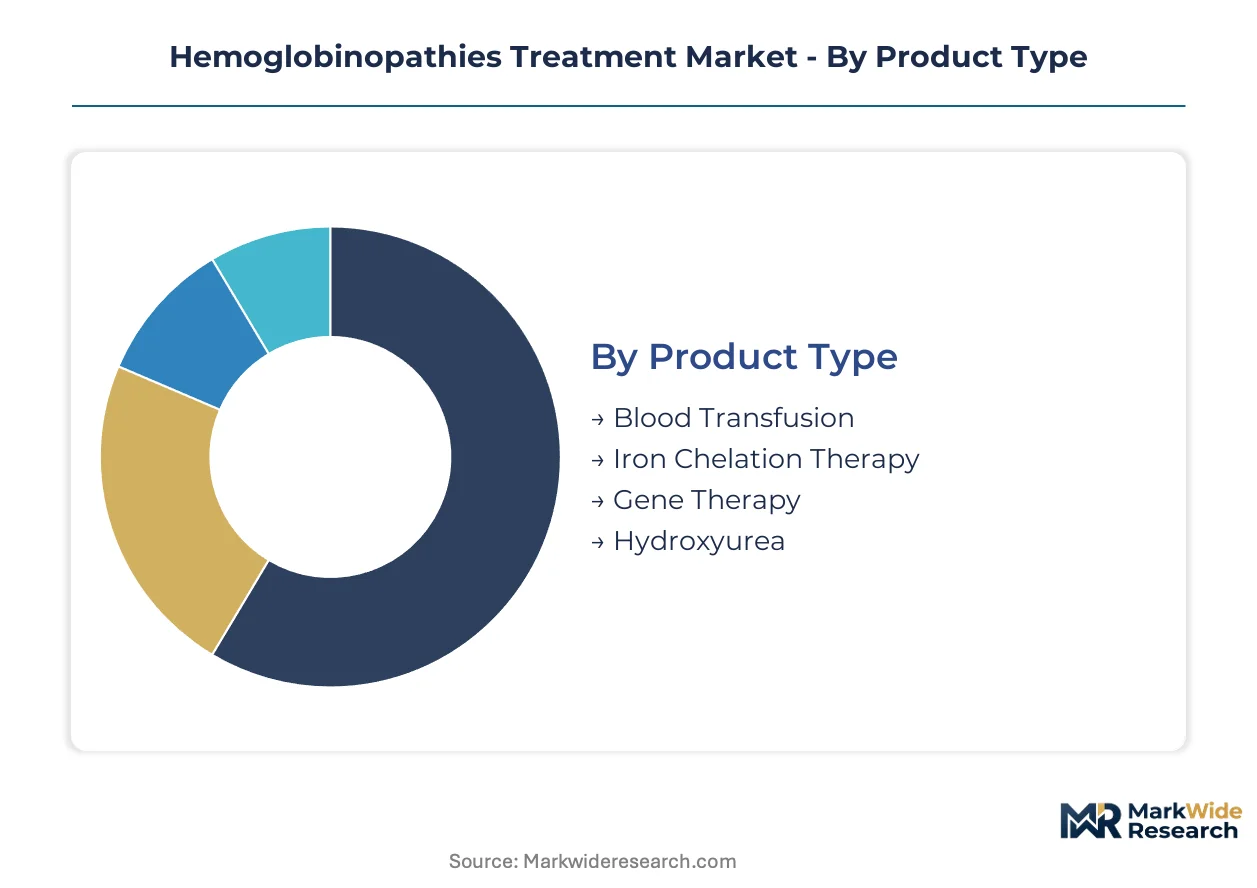
Segmentation in hemoglobinopathies treatment reveals how regulatory pathways, reimbursement structures, and patient acuity reshape commercial priorities across therapeutic modalities. Each dimension exposes distinct margin architectures and access barriers that determine competitive positioning.
Product Type:
FDA accelerated approval and EMA adaptive licensing create divergent commercialization timelines across therapeutic categories, compressing gene therapy development while extending transfusion protocol standardization.
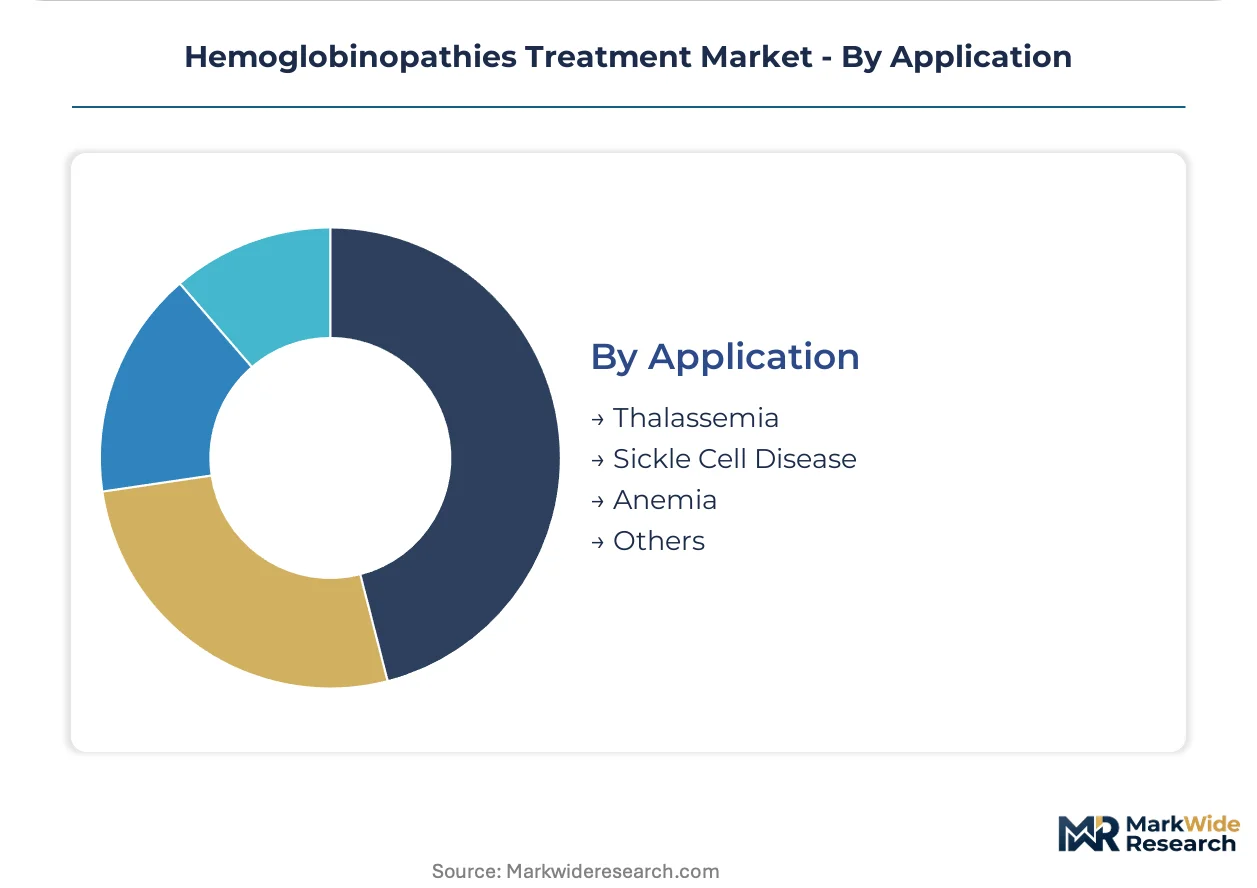
- Gene Therapy:CRISPR-edited and lentiviral-based autologous stem cell modifications deliver one-time curative intent. Demand concentrates at pediatric hematology centers in the United States where payer innovation agreements accommodate outcomes-based pricing for durable transfusion independence.
- Blood Transfusion:Chronic erythrocyte replacement protocols maintain oxygen-carrying capacity in thalassemia major and sickle cell disease complications. Volume clusters in Saudi Arabia's national screening program catchment areas and French tertiary referral networks where sovereign health funds underwrite lifelong transfusion dependence.
- Iron Chelation Therapy:Deferasirox, deferiprone, and deferoxamine formulations manage transfusional hemosiderosis through oral and parenteral routes.
- Hydroxyurea:Oral fetal hemoglobin inducer with established sickle cell disease efficacy profiles and generic cost structures.
Established volume favors blood transfusion; emerging adoption favors gene therapy.
End User:
Site-of-care economics and regulatory certification requirements fragment patient flow across institutional settings with divergent reimbursement rates and therapy administration capabilities.
- Hospitals:Tertiary academic medical centers anchor curative intervention delivery through integrated stem cell transplantation and gene therapy processing units. Demand clusters at US pediatric hematology centers and Saudi specialized hemoglobinopathy facilities in Riyadh and Jeddah where infrastructure investment matches complex case acuity.
- Homecare Settings:Hospital-at-home transfusion models and subcutaneous iron chelation administration shift chronic therapy outside traditional infusion centers. Expansion concentrates in French and German statutory health insurance networks piloting decentralized capacity relief.
- Specialty Clinics:Dedicated hemoglobinopathy centers coordinate multidisciplinary care including transfusion, chelation, and genetic counseling services.
- Blood Banks:Collection, processing, and distribution infrastructure supports erythrocyte transfusion supply chains with phenotype-matched donor programs.
Margin concentration sits with hospitals; access expansion favors homecare settings.
Delivery Mode:
Route of administration determines manufacturing complexity, cold chain requirements, and patient compliance profiles that reshape competitive moats across therapeutic categories.
- Intravenous:Direct vascular delivery enables high-volume erythrocyte transfusion and continuous iron chelation infusion in acute settings. Demand concentrates in Saudi Arabia's centralized hemoglobinopathy centers managing thalassemia major patient volumes through protocol standardization.
- Oral:Deferasirox and hydroxyurea tablets support chronic outpatient management with minimal supervision requirements. Adoption accelerates in Sub-Saharan Africa WHO prequalification pathways where simplified supply chains address highest sickle cell disease prevalence.
- Injectable:Subcutaneous deferoxamine and intramuscular formulations accommodate patient populations with venous access limitations.
- Subcutaneous:Continuous infusion pump compatibility enables ambulatory iron chelation without hospital tethering.
Compliance convenience favors oral routes; acute intervention capacity favors intravenous delivery.
Application:
Disease-specific pathophysiology and complication profiles determine therapeutic modality selection, with mutation type and transfusion history reshaping treatment algorithms.
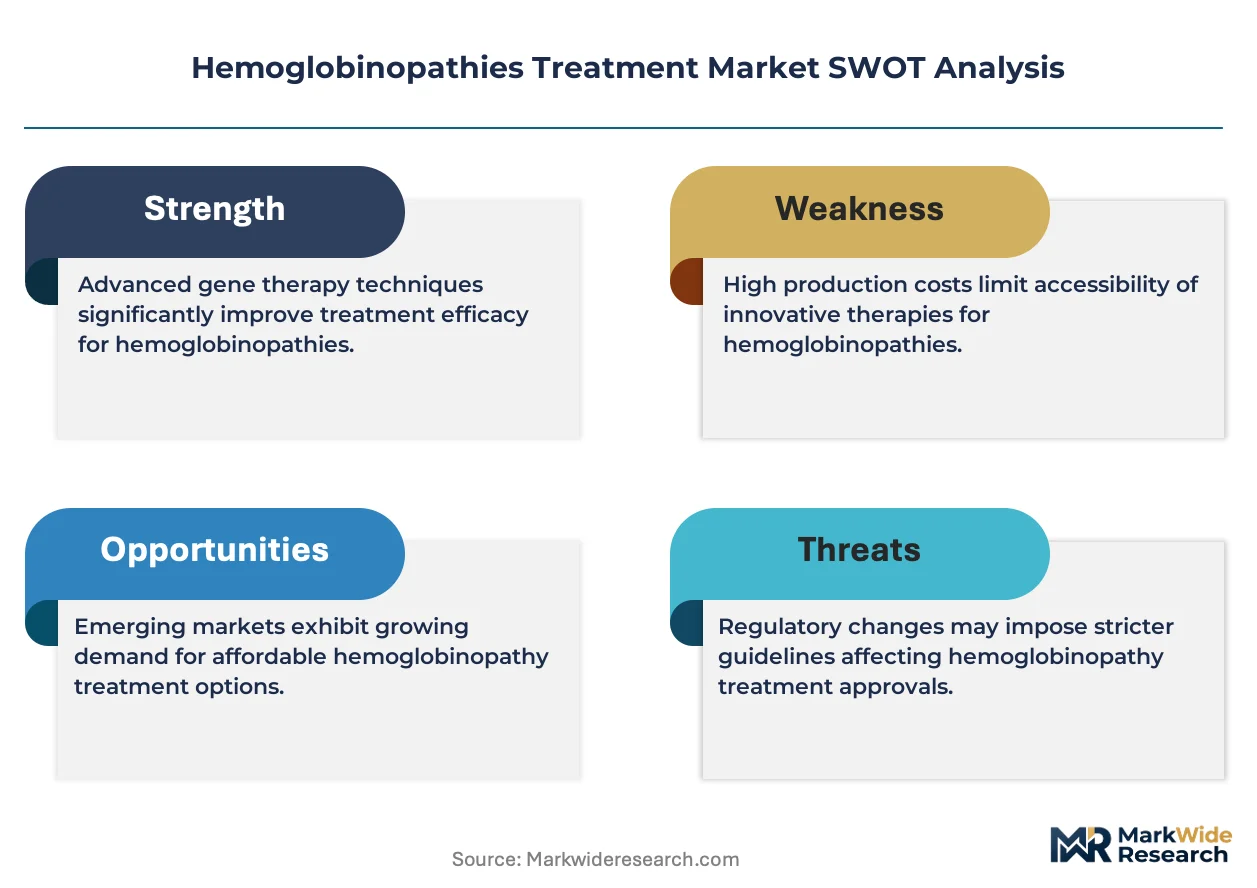
- Thalassemia:Beta-globin chain imbalance drives ineffective erythropoiesis and transfusion dependence in major forms. Curative intervention demand concentrates in Mediterranean basin populations and Saudi Arabia where carrier screening and national registries identify candidates for gene therapy and allogeneic transplant.
- Sickle Cell Disease:Polymerization-induced vaso-occlusion generates acute pain crises and chronic organ damage. Pediatric gene therapy eligibility expands at US centers utilizing CRISPR-edited autologous stem cells to eliminate matched-sibling donor requirements.
- Anemia:Secondary hemoglobin disorders from nutritional deficiency or chronic disease require differentiated diagnostic and therapeutic approaches.
- Others:Rare hemoglobin variants and compound heterozygous conditions with atypical clinical presentations.
Transfusion volume concentration favors thalassemia; curative technology adoption favors sickle cell disease.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways anchor the United States as the dominant geography, while EMA adaptive licensing and sovereign health funds reshape access across Europe and the Middle East.
United States
Pediatric hematology centers in Boston and Philadelphia drive CRISPR-edited autologous stem cell adoption, eliminating matched-sibling donor requirements for sickle cell disease. FDA's accelerated approval framework compresses phase III-to-market intervals for beta-thalassemia gene therapies. Manufacturing clusters concentrate in Research Triangle Park and the Greater Boston biotech corridor where viral vector capacity anchors production scale.
Saudi Arabia
National newborn screening mandates systematically identify sickle cell and thalassemia cases at birth, expanding addressable patient pools through sovereign health fund underwriting. SFDA registration pathways align with WHO prequalification standards to streamline biologic access. Specialized hemoglobinopathy centers in Riyadh and Jeddah pilot hospital-at-home transfusion models to decentralize chronic care capacity.
France
Statutory health insurance networks pilot decentralized homecare transfusion protocols for chronic thalassemia patients, reducing facility overhead at tertiary centers. ANSM and CNIL oversight of EU AI Act data governance mandates algorithmic transparency for gene therapy registries used in adaptive licensing. The Paris-Saclay medical cluster anchors real-world evidence infrastructure for outcomes-based pricing negotiations.
Germany
G-BA reimbursement authorities leverage structured longitudinal datasets to negotiate indication-specific gene therapy pricing rather than therapy-class benchmarks. REACH compliance requirements shape viral vector bioprocess engineering standards for imported biologics. The Rhine-Ruhr metropolitan region concentrates hematology referral networks managing thalassemia major patient volumes through protocol standardization.
India
CDSCO regulatory harmonization with WHO prequalification pathways accelerates simplified transfusion protocol and oral iron chelator access for the highest sickle cell disease prevalence region. BIS standards for medical device quality govern portable infusion pump deployment in homecare settings. Mumbai and Delhi-NCR anchor diagnostic and transfusion infrastructure serving beta-thalassemia clusters in Maharashtra and Gujarat.
Hemoglobinopathies Treatment Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with vector manufacturing capability bifurcating competitive advantage between in-house producers and contract-dependent developers. The landscape concentrates around three strategic archetypes: diversified pharmaceutical conglomerates with cell and gene therapy infrastructure, dedicated biotech platforms specialized in lentiviral delivery systems, and CRISPR-edited autologous stem cell innovators. Dominant competitive moves include strategic partnerships securing viral vector supply commitments and geographic expansion into sovereign health fund markets with systematic newborn screening.
Within the integrated pharmaceutical tier, Novartis AG and Sanofi SA occupy positions anchored by established biologics manufacturing scale and cell therapy infrastructure. bluebird bio and Vertex Pharmaceuticals exemplify the specialist archetype, with the former representing dedicated lentiviral vector platforms and the latter anchoring CRISPR-edited autologous stem cell programs. These four entities collectively illustrate how manufacturing depth and editing modality selection reshape competitive positioning across FDA and EMA approval pathways.
| Leading Market Players |
|---|
| Novartis AG |
| bluebird bio |
| Sanofi SA |
| Pfizer Inc. |
| Global Blood Therapeutics |
| Emmaus Life Sciences |
| Vertex Pharmaceuticals |
| Sangamo Therapeutics |
| Agios Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Ninety-day viral vector production lead times concentrate pricing power among three contract development organizations with captive GMP-grade plasmid supply, while gene therapy developers absorb cost pass-throughs that compress margins on curative interventions. This supply bottleneck reshapes procurement negotiations across pediatric hematology centers in the United States and specialized hemoglobinopathy facilities in Saudi Arabia.
Pricing Analysis
Gene therapy pricing spreads by more than threefold between Boston academic medical centers negotiating outcomes-based contracts and Saudi sovereign health fund procurement through centralized tenders. Three-tier pricing structure across premium CRISPR-edited autologous programs, standard lentiviral vector therapies, and economy-positioned chronic transfusion protocols reflects manufacturing complexity and durability guarantees. Pricing pressure stems from hospital-at-home transfusion models displacing facility-based revenue, with French statutory health insurers demanding indication-specific benchmarks rather than therapy-class rates. Pediatric hematology centers exhibit lowest price sensitivity due to payer innovation agreements, while Sub-Saharan Africa procurement through WHO prequalification pathways faces acute cost constraints.
Supply Chain Analysis
Container availability constraints on trans-Atlantic trade lanes extend cold-chain shipment timelines for patient-derived hematopoietic stem cells, complicating centralized gene editing logistics. Viral vector manufacturing concentrates in the United States, Germany, and Singapore, with GMP-grade plasmid supply anchored in North American and European facilities. Gene therapy production draws from specialized cell culture media, synthetic guide RNA, and electroporation consumables with limited secondary sourcing. Single-source vulnerability pervades lentiviral packaging cell lines, where patent-protected master cell banks restrict manufacturing transfer. Distribution runs through regional transplantation centers certified for ex vivo processing, with vein-to-vein coordination managed by dedicated logistics partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored by regulatory entrenchment: FDA accelerated approval and EMA adaptive licensing frameworks create multi-year head starts for first movers that compound through real-world evidence generation and payer contract lock-in.
For Market Incumbents: Shield market position by securing exclusive viral vector supply commitments from the three dominant contract manufacturers, locking out late-stage competitors from GMP-grade plasmid allocation. Accelerate backward integration into electroporation-based processing at regional transplantation centers, reducing dependence on centralized CDMO capacity that emerging CRISPR-edited programs threaten to displace. For New Entrants and Emerging Players: FDA breakthrough therapy designation serves as the fastest certification fast-track for gene therapy candidates, compressing development timelines against entrenched lentiviral platforms. Sub-Saharan Africa presents the most penetrable geography, where WHO prequalification pathways for simplified oral iron chelators address the highest sickle cell disease prevalence with minimal biologic competition. Partner with sovereign health funds in Saudi Arabia and Gulf states piloting hospital-at-home transfusion models, leveraging their infrastructure investment appetite to bypass saturated US pediatric hematology center networks. For Investors and Strategic Acquirers: Long-term, this sits as a manufacturing-capability play because viral vector bioprocess engineering talent scarcity will persist, making in-house production capacity the scarce asset that determines which gene therapy platforms achieve commercial scale. Target acquisition profiles center on mid-cap developers with validated CRISPR editing workflows but lacking captive manufacturing, as these become forced sellers when CDMO queues extend. The signal to watch is EMA conditional approval conversion rates to full authorization, which will separate durable revenue streams from stranded regulatory assets.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive viral vector capacity insulates against CDMO queue delays that threaten commercial launch timelines. |
| Regulatory Approval Pathway | FDA accelerated approval compresses phase III-to-market intervals for beta-thalassemia gene therapies. |
| Licensing Agreement | Electroporation technology licenses from academic medical centers reduce vector packaging dependence. |
| Reimbursement Strategy | Outcomes-based contracts with French and German statutory insurers enable indication-specific pricing. |
| Pipeline Diversification | CRISPR-edited programs for sickle cell disease expand addressable markets beyond matched-sibling donor limits. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted to anchor market sizing, including pediatric hematology center directors, gene therapy manufacturing executives, regulatory affairs leads at EMA and FDA, hospital procurement managers, and payer access specialists at French and German statutory health insurers. Secondary validation drew from FDA filings, EMA adaptive licensing submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient flow modeling across newborn screening programs triangulated against top-down revenue estimates from sovereign health fund disclosures.
Across the analysis window, forecasts employed a segmented analytical framework spanning therapeutic modality, disease application, delivery route, and regional regulatory cluster. CAGRs were derived from patient cohort projections by screening program penetration and therapy adoption curves, with gene therapy manufacturing capacity expansion schedules and viral vector supply constraints serving as critical industry-specific inputs.
Decision-makers should treat outputs as directional under assumptions of stable regulatory pathway differentiation and sustained sovereign health fund underwriting; material deviation would warrant model refresh. Specific risks include EMA conditional approval withdrawal rates, viral vector manufacturing contamination events, and CRISPR editing durability data that revises reimbursement negotiations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Sickle Cell Disease Market
Hematology
Hairy Cell Leukemia Treatment Market
Hematology
Global Hodgkin Lymphoma Treatment Market
Hematology
Hemoglobin Testing Systems Market
Hematology
Global Hematopoietic Stem Cell Transplantation Market
Hematology
At-Home Hematology Testing Market
Hematology
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market
Hematology
Global Disposable Hemoperfusion Market
Hematology
Polycythemia Vera Market
Hematology
Global Hemoglobin Meter Market
Hematology
Sickle Cell Anemia Market
Hematology
Global Bleeding Disorders Market
Hematology
Global Sickle Cell Disease Treatment Market
Hematology
Hemocytometer Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Marginal Zone Lymphoma Treatment Market