
 Sickle Cell Anemia Market | 2026-2036
Sickle Cell Anemia Market Size, Share, and Industry Trends Forecast 2026-2036
Sickle Cell Anemia Market Outlook
Outcome-based reimbursement for gene therapy is decoupling treatment costs from traditional pharmaceutical pricing models. Novartis AG leverages its established rare disease infrastructure to anchor European market access for novel therapeutics. Bluebird Bio, Inc. specializes in lentiviral vector manufacturing at scale, sustaining its position in curative approach development. CRISPR Therapeutics competes through allogeneic gene-editing platforms that reduce patient-specific production complexity.
Sickle cell anemia constitutes a hereditary hemoglobinopathy characterized by a point mutation in the HBB gene producing hemoglobin S, which polymerizes under deoxygenation to form sickle-shaped erythrocytes with markedly reduced deformability. The condition primarily serves hematology and transfusion medicine through chronic vaso-occlusive crisis management and end-organ damage prevention. Gene therapy now leads product type expansion as curative approaches displace chronic symptomatic treatment in eligible patient populations, while hydroxyurea maintains volume dominance across pediatric and adult maintenance protocols. Pain management and blood transfusions retain substantial revenue share in hospital and clinic delivery modes where IV administration infrastructure supports acute intervention workflows.
The FDA's Breakthrough Therapy designation and Orphan Drug incentives structure commercial entry timelines for developers targeting this indication, while EMA's PRIME eligibility extends parallel European acceleration pathways. WHO inclusion of sickle cell disease in its global strategy for neglected tropical diseases elevates funding visibility for endemic regions. Stakeholders must monitor real-world evidence generation requirements as payers condition coverage on long-term durability outcomes for single-administration gene therapies.
Market Dynamics
Gene therapy commercialization is restructuring the Sickle Cell Anemia Market around single-administration curative protocols, forcing chronic treatment providers to defend revenue streams against durable remission claims and outcome-based contracting frameworks.
Growth Catalysts
- FDA Breakthrough Therapy designation:Accelerated review timelines compress development-to-revenue cycles for gene-editing candidates targeting beta-globin pathway modification.
- Specialty hospital expansion:United States academic medical centers are building dedicated sickle cell infusion centers with apheresis capability to support autologous stem cell collection workflows.
- Lentiviral vector manufacturing:Scalable production platforms for ex vivo gene delivery are reducing per-patient production costs below legacy autologous thresholds.
Market Restraints
- Plasma-derived reagent costs:Fetal bovine serum and human AB serum price volatility constrains ex vivo cell culture economics for autologous therapies.
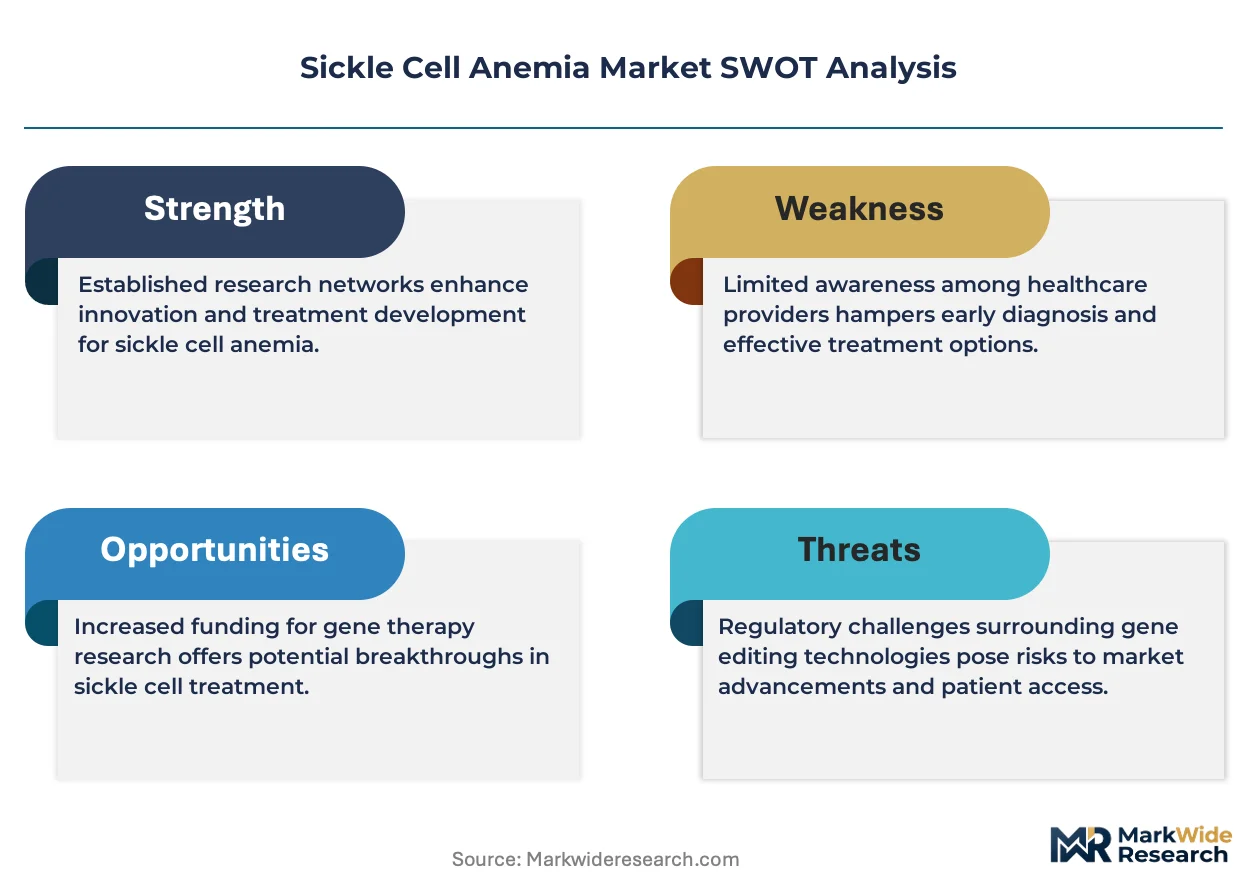
- Single-site production concentration:Lentiviral vector manufacturing clusters in Massachusetts and North Carolina create geographic supply vulnerability for European and Asian treatment centers.
- Allogeneic immune compatibility barriers:HLA-matching requirements for donor-derived stem cell sources limit eligible patient pools in ethnically diverse populations.
Strategic Opportunities
- Nigeria healthcare infrastructure:Federal Ministry of Health sickle cell screening mandates create demand for point-of-care diagnostic and chronic management protocols.
- India newborn screening expansion:National Health Mission integration of hemoglobinopathy testing opens pediatric early-intervention markets in Maharashtra and Tamil Nadu.
- EMA PRIME eligibility:Parallel European acceleration pathways enable synchronized US-EU launch timelines for developers with existing FDA breakthrough status.
Industry Challenges
- Vector manufacturing workforce scarcity:GMP-grade cell therapy production technicians with aseptic processing certification command premium compensation in biotech hubs.
- Long-term durability evidence generation:Payers condition coverage decisions on five-to-ten-year follow-up data that exceeds current clinical trial observation windows.
- Apheresis center capacity constraints:Stem cell collection infrastructure bottlenecks limit patient throughput for autologous gene therapy protocols during peak demand periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sickle Cell Anemia Market |
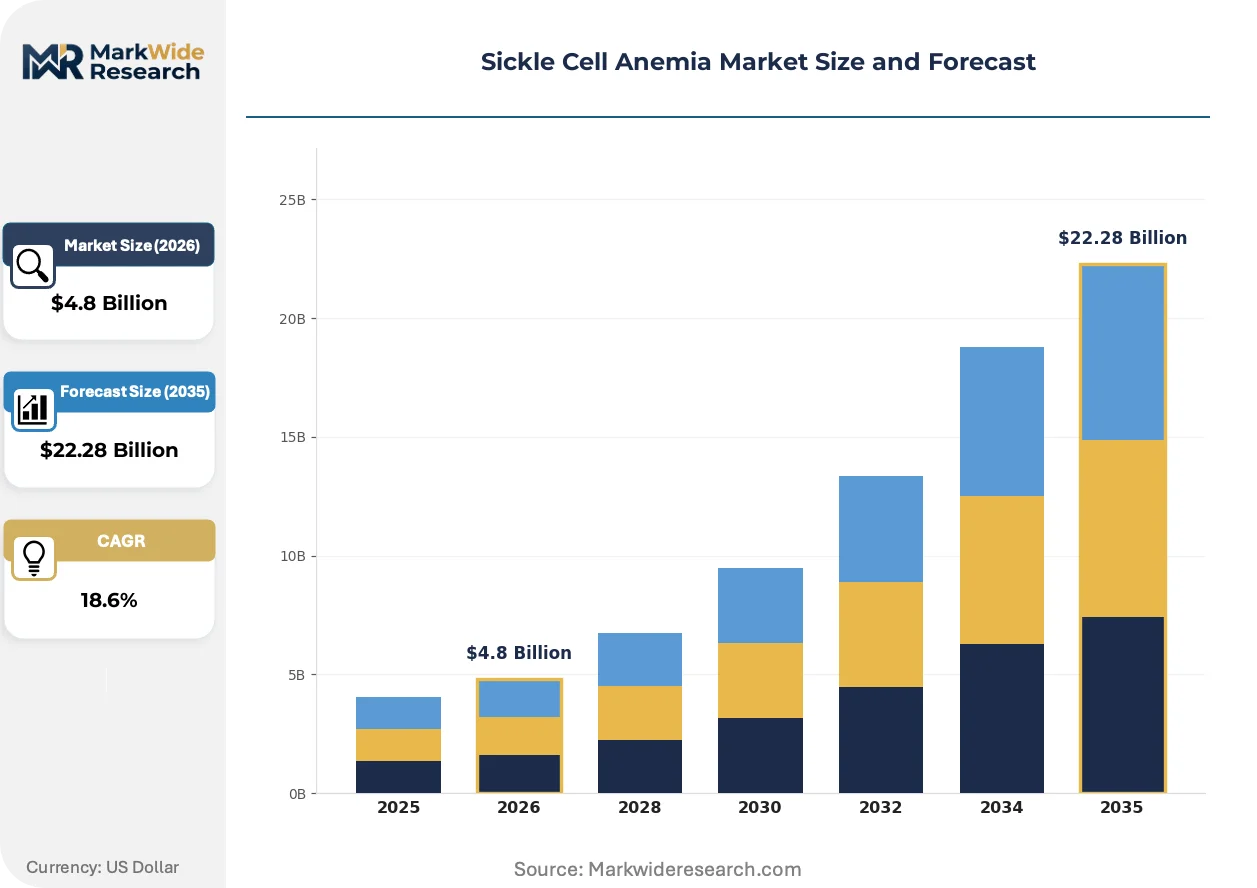
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydroxyurea, Blood Transfusions, Gene Therapy, Pain Management End User: Hospitals, Clinics, Homecare, Research Institutions Delivery Mode: Injectables, Oral Medications, IV Administration, Transfusions Treatment Strategy: Preventive Care, Symptomatic Treatment, Curative Approaches, Palliative Care |
| Companies Covered | Novartis AG, Pfizer Inc., Bluebird Bio, Inc., Global Blood Therapeutics, Inc., Emmaus Medical, Inc., CRISPR Therapeutics, Vertex Pharmaceuticals Inc., Bristol-Myers Squibb Company, Agios Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sickle Cell Anemia Market Strategic Shifts
Curative modalities are compressing the addressable market for chronic symptomatic treatments while simultaneously expanding total market value through premium pricing for durable remission outcomes.
CRISPR-Cas9 ex vivo gene editing is decentralizing patient access by enabling treatment at regional transplant centers rather than requiring travel to specialized gene therapy hubs. Community oncology networks in Texas and Florida are adopting the platform for sickle cell protocols. This geographic diffusion is compressing the historical concentration of curative treatment capacity.
EMA's PRIME designation pathway is accelerating European market entry timelines for developers with existing FDA breakthrough therapy status. The framework enables rolling scientific advice and accelerated assessment that compresses regulatory lag. Developers targeting sickle cell indications are leveraging parallel submissions to synchronize US and EU commercialization.
Specialty pharmacy distribution for gene therapy is displacing traditional wholesale channels for high-value single-administration treatments. Payers are mandating white-gloved logistics with temperature-controlled chain-of-custody documentation. This channel shift is most visible in United States commercial insurance networks where pharmacy benefit managers control access.
Sickle Cell Anemia Market Segmentation
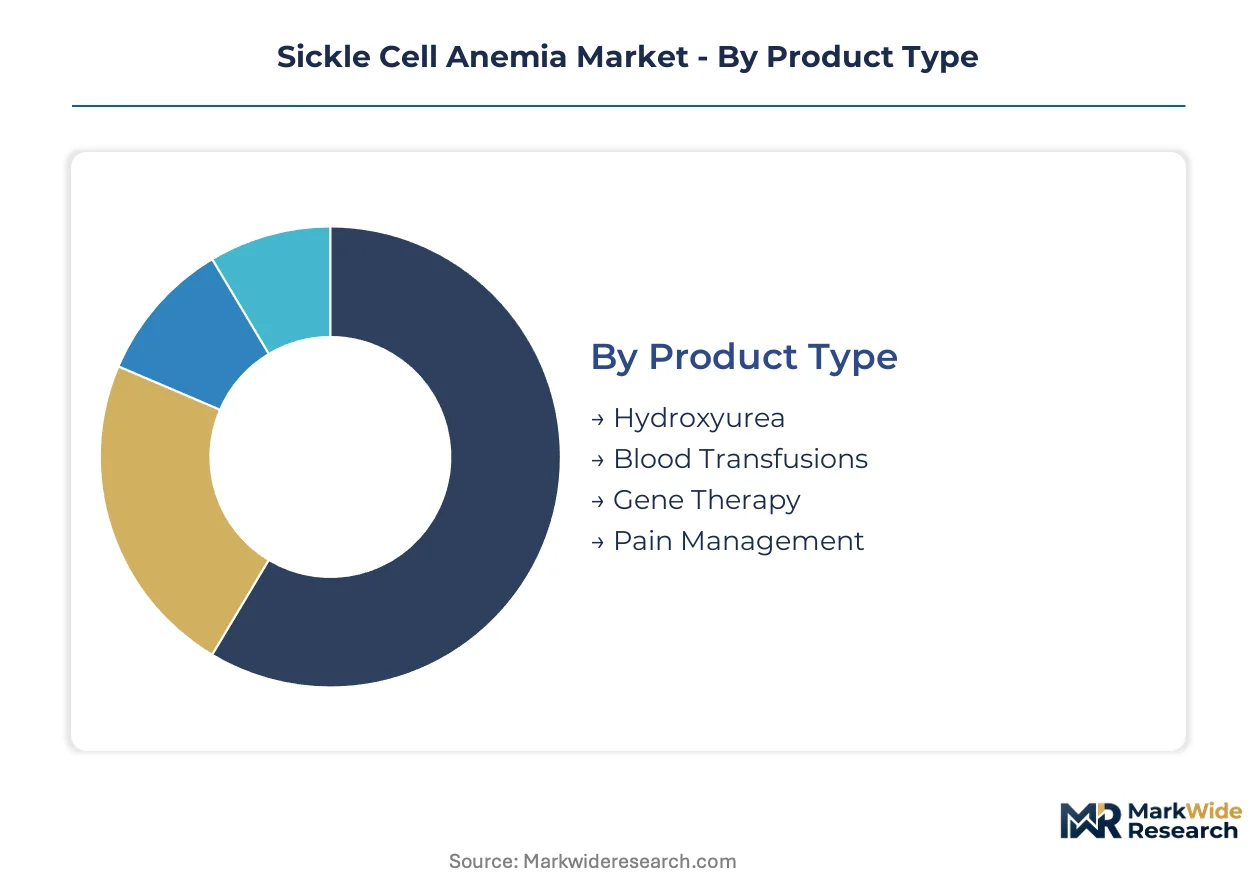
Sickle cell anemia treatment markets fragment across curative versus chronic modalities, with gene therapy disrupting legacy revenue pools while hydroxyurea and transfusion protocols defend volume share. Segmentation reveals where infrastructure investments concentrate and which delivery modes command premium positioning.
Product Type:
Vector manufacturing scale and reimbursement durability separate premium curative offerings from maintenance therapies.
- Gene Therapy:Lentiviral and CRISPR-based ex vivo editing protocols deliver functional beta-globin restoration. Demand clusters at academic medical centers in Boston and Research Triangle Park where GMP manufacturing infrastructure supports autologous stem cell workflows.
- Hydroxyurea:Oral ribonucleotide reductase inhibitor remains the pharmacologic backbone for fetal hemoglobin induction. Volume concentrates in pediatric protocols across Nigeria and India where newborn screening expansion drives early intervention uptake.
- Blood Transfusions:Chronic transfusion programs for stroke prevention and acute chest syndrome management.
- Pain Management:IV opioids and non-steroidal protocols for vaso-occlusive crisis intervention.
Mature deployment sits with Hydroxyurea. Newer deployment is concentrated in Gene Therapy.
End User:
Site-of-care economics and reimbursement complexity determine where high-value single-administration therapies versus chronic protocols concentrate.
- Hospitals:Academic medical centers with apheresis capability and stem cell transplant accreditation anchor curative therapy delivery. Johns Hopkins, Vanderbilt, and University of Pennsylvania have built dedicated sickle cell infusion centers with on-site vector manufacturing partnerships.
- Clinics:Community hematology practices manage chronic transfusion and hydroxyurea titration. Federally qualified health centers in Atlanta and Houston handle disproportionate sickle cell patient volumes under 340B pricing.
- Homecare:Subcutaneous deferoxamine infusion and oral hydroxyurea maintenance.
- Research Institutions:NIH Clinical Center and academic consortia host early-phase gene editing trials.
Revenue concentration sits with Hospitals. Patient volume leadership sits with Clinics.
Delivery Mode:
Administration complexity and cold-chain requirements segment pricing power across routes.
- IV Administration:Continuous infusion protocols for pain crisis and chelation therapy require nursing supervision. Demand concentrates in hospital-based infusion centers where prior authorization workflows for gene therapy reimbursement are pre-negotiated with commercial payers.
- Transfusions:Chronic exchange transfusion programs for secondary stroke prevention. Sickle cell disease-specific blood banking networks in London and Paris maintain phenotype-matched inventory for alloimmunization-prone patients.
- Injectables:Subcutaneous deferoxamine and L-glutamine powder for reconstitution.
- Oral Medications:Hydroxyurea capsules and voxelotor tablets for hemoglobin S polymerization inhibition.
Technical sophistication sits with IV Administration. Volume accessibility sits with Oral Medications.
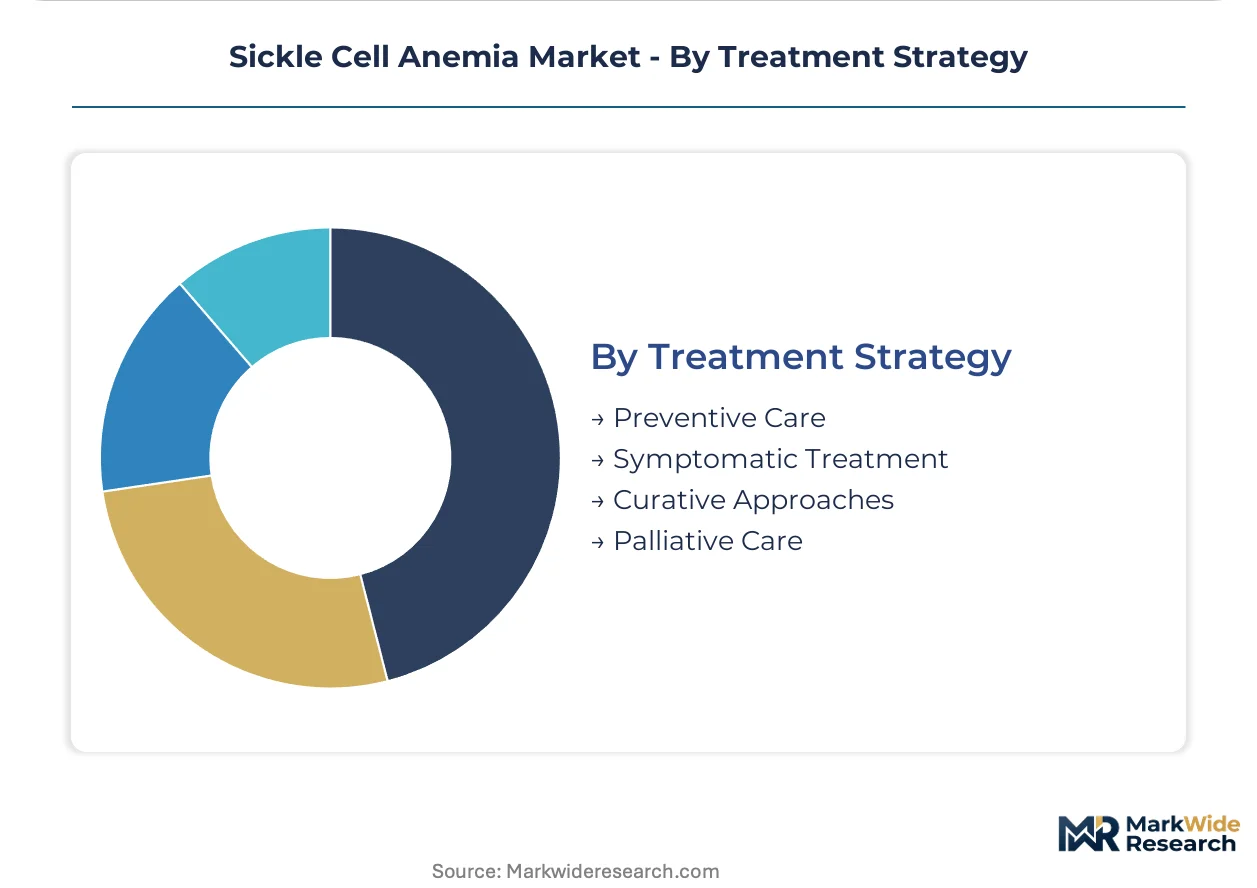
Treatment Strategy:
Clinical outcome durability and payer evidence requirements structure investment priority across therapeutic intent categories.
- Curative Approaches:Autologous stem cell gene editing and allogeneic transplant protocols target disease modification at the hematopoietic stem cell level. EMA PRIME and FDA Breakthrough Therapy designations have compressed development timelines for beta-globin gene addition strategies.
- Preventive Care:Transcranial Doppler screening and penicillin prophylaxis for pediatric patients. Nigerian federal screening mandates and Indian National Health Mission integration are expanding addressable populations for early detection protocols.
- Symptomatic Treatment:Vaso-occlusive crisis management and acute chest syndrome protocols.
- Palliative Care:End-stage organ failure support and pain optimization in advanced disease.
Evidence generation investment sits with Curative Approaches. Population reach sits with Preventive Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors gene therapy infrastructure with Massachusetts General Hospital and Dana-Farber Cancer Institute hosting lentiviral vector manufacturing partnerships. Johns Hopkins in Baltimore and Vanderbilt in Nashville have replicated this academic medical center model. The geographic diffusion of curative capacity is reshaping patient access patterns across multiple countries.
United States
Specialty hospital expansion drives demand as academic medical centers in Boston, Baltimore, and Nashville build dedicated sickle cell infusion centers with apheresis capability. FDA Breakthrough Therapy designation accelerates development timelines for gene-editing candidates. Johns Hopkins Medicine anchors curative therapy delivery with on-site stem cell collection workflows.
Nigeria
Federal Ministry of Health sickle cell screening mandates create demand for point-of-care diagnostics and chronic management protocols. WHO inclusion of sickle cell disease in global neglected tropical disease strategy elevates funding visibility. Lagos and Abuja concentrate pediatric early-intervention capacity under National Health Insurance Scheme integration.
India
National Health Mission integration of hemoglobinopathy testing opens pediatric markets in Maharashtra and Tamil Nadu. CDSCO fast-track pathways for orphan drugs compress regulatory timelines for imported gene therapies. Mumbai and Chennai anchor diagnostic infrastructure with state-level newborn screening program expansion.
Germany
EMA PRIME eligibility enables synchronized US-EU launch timelines for developers with existing FDA breakthrough status. Federal Ministry of Health rare disease funding supports specialized treatment centers in Berlin and Munich. Charité – Universitätsmedizin Berlin anchors European gene therapy trial participation.
United Kingdom
NHS England specialized commissioning for haemoglobinopathy services concentrates curative therapy access at designated treatment centers. MHRA innovative licensing pathways accelerate market entry for gene-editing products. London and Birmingham host phenotype-matched blood banking networks for alloimmunization-prone patients.
Sickle Cell Anemia Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the Sickle Cell Anemia Market. The vendor base separates into integrated pharmaceutical conglomerates with rare disease infrastructure, specialized gene therapy developers with vector manufacturing capability, and emerging biotech firms with platform technologies. Three strategic archetypes dominate: established rare disease players leveraging existing payer relationships, gene-editing specialists competing on manufacturing scale, and platform technology companies pursuing allogeneic approaches. Competitive moves concentrate on strategic partnerships for vector supply security and geographic expansion into African and South Asian markets.
Among established rare disease players, Novartis AG exemplifies the integrated pharmaceutical archetype with European market access infrastructure. Bluebird Bio, Inc. occupies a position within the gene therapy specialist tier, representing lentiviral vector manufacturing at scale. CRISPR Therapeutics anchors the platform technology segment, exemplifying allogeneic gene-editing approaches that reduce patient-specific production complexity.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Bluebird Bio, Inc. |
| Global Blood Therapeutics, Inc. |
| Emmaus Medical, Inc. |
| CRISPR Therapeutics |
| Vertex Pharmaceuticals Inc. |
| Bristol-Myers Squibb Company |
| Agios Pharmaceuticals, Inc. |
| Others |
Value Chain & Pricing Dynamics
Payer mandates for five-to-ten-year durability evidence are forcing gene therapy developers to absorb extended follow-up costs, compressing margins and pushing pricing models toward outcome-based contracts that tie reimbursement to sustained clinical benefit.
Pricing Analysis
Margin tightening in curative therapy tiers reflects the shift from chronic treatment revenue streams to single-administration gene editing protocols with premium upfront pricing contingent on long-term remission outcomes. Three-tier pricing structure across premium gene therapies, standard maintenance protocols, and economy symptomatic treatments stratifies by clinical outcome durability and manufacturing complexity. Cost-down pressure on lentiviral vector production accelerates because autologous stem cell workflows require patient-specific manufacturing with limited batch scale economies. Hospital procurement committees demonstrate highest price sensitivity for chronic maintenance therapies, while specialty pharmacy networks accept premium pricing for FDA Breakthrough Therapy-designated curative approaches.
Supply Chain Analysis
Fetal bovine serum and human AB serum supply rests on concentrated North American and European biotechnology reagent producers, creating input dependencies for ex vivo cell culture workflows essential to autologous gene therapy manufacturing. Lentiviral vector production clusters in Massachusetts and North Carolina, with apheresis equipment sourcing from Germany and Japan. Single-site manufacturing concentration presents geographic supply vulnerability for European and Asian treatment centers requiring temperature-controlled logistics chains. Distribution runs through specialty pharmacy channels with white-gloved cold-chain custody documentation mandated by commercial payers for high-value single-administration therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy commercialization is consolidating competitive position around manufacturing scale and payer access infrastructure, forcing chronic treatment specialists to defend revenue against durable remission claims or exit the indication entirely.
For Market Incumbents: Extend manufacturing partnerships with academic medical centers to secure apheresis capacity and stem cell collection workflows before regional transplant centers decentralize patient access. Lock in vector supply agreements with GMP-grade production facilities in Research Triangle Park and Boston to preempt allogeneic platform competitors from capturing manufacturing slots. Outcome-based contracting with commercial pharmacy benefit managers represents the critical lever for defending premium pricing against hydroxyurea volume erosion. For New Entrants and Emerging Players: Specialty hospital networks in Texas and Florida present the most penetrable channel for CRISPR-based decentralized treatment protocols, as community oncology infrastructure expands beyond traditional academic medical center hubs. Nigerian federal screening mandates and Indian National Health Mission integration create white-space demand for point-of-care diagnostics and early-intervention chronic management platforms. A licensing-focused go-to-market angle with established rare disease infrastructure partners accelerates market access without captive manufacturing investment. For Investors and Strategic Acquirers: The window for entry favors platform technology companies with allogeneic gene-editing capabilities that reduce patient-specific production complexity and enable scalable manufacturing economics. Long-term viability hinges on five-to-ten-year durability data generation that satisfies payer coverage conditions for single-administration therapies. Watch FDA and EMA regulatory precedent for outcome-based reimbursement frameworks as the primary inflection signal for gene therapy valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Lentiviral vector production expansion at GMP facilities reduces per-patient costs below legacy autologous thresholds. |
| Regulatory Approval Pathway | EMA PRIME eligibility enables synchronized US-EU launch timelines for developers with existing FDA breakthrough status. |
| Hospital System Partnership | Academic medical center alliances secure apheresis capacity and stem cell collection infrastructure for patient throughput. |
| Reimbursement Strategy | Outcome-based contracts with commercial payers tie gene therapy pricing to durable remission evidence over extended follow-up periods. |
| Pipeline Diversification | Allogeneic platform expansion reduces manufacturing complexity and enables treatment at regional transplant centers beyond specialized hubs. |
Study Parameters
Document review covered FDA Breakthrough Therapy designation filings, EMA PRIME eligibility submissions, ClinicalTrials.gov gene therapy protocols, and hospital procurement databases, complemented by interviews with gene therapy development executives, regulatory affairs leads, formulary directors at commercial payers, and hospital procurement managers overseeing sickle cell infusion center operations. Secondary validation drew from CMS Medicare reimbursement data, specialty pharmacy distribution records, and WHO sickle cell disease strategy documentation. Bottom-up patient population estimates across Nigeria, India, and the United States triangulated against top-down market value projections.
Market sizing outputs reflect segmentation across curative versus chronic treatment modalities, gene therapy vector types, delivery mode administration complexity, and regional regulatory clusters spanning FDA, EMA, CDSCO, and national health ministry pathways. CAGRs were derived from patient eligibility expansion, newborn screening program rollout timelines, and manufacturing capacity buildout trajectories. Forecast inputs incorporated lentiviral vector production scale economics, apheresis center capacity constraints, and payer evidence requirements for long-term durability outcomes.
Several conditions sit outside the modeled scope, including unforeseen regulatory reversals on accelerated approval pathways, vector manufacturing contamination events, and geopolitical disruptions to fetal bovine serum supply chains. Forecasts reflect assumptions about sustained clinical benefit durability that exceed current trial observation windows. A small set of named triggers warrants ongoing watch: FDA and EMA precedent on outcome-based reimbursement, CRISPR platform safety signals, and Nigerian federal health insurance scheme expansion velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Blood Disorder Therapeutics Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Hairy Cell Leukemia Treatment Market
Hematology
Blood Plasma Market
Hematology
Heparin-Induced Thrombocytopenia (HIT) Treatment Market
Hematology
Global Bleeding Disorders Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Aplastic Anemia Treatment Market
Hematology
Rare Hematology Market
Hematology
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market
Hematology
Hemoglobinopathy Treatment Drug Market
Hematology
Bleeding Disorders Therapeutics Market
Hematology
Graft Versus Host Disease (Gvhd) Treatment Market
Hematology
Warm Autoimmune Hemolytic Anemia (WAIHA) Treatment Market
Hematology
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market
Hematology
Febrile Neutropenia Market