
 Ige Allergy Blood Tests Market | 2026-2036
Ige Allergy Blood Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Ige Allergy Blood Tests Market Outlook
European diagnostic reagent manufacturers is pivoting toward automated IgE assay platforms that reduce manual batch processing. Siemens Healthineers leverages its installed base of immunoanalyzers to sustain recurring consumable revenue across hospital laboratories. Thermo Fisher Scientific anchors its position through vertical integration into allergen extract production and assay development. Danaher Corporation competes on workflow density, embedding IgE testing within broader immunology panels on integrated instruments.
IgE allergy blood tests quantify serum immunoglobulin E levels against specific allergens using labeled antibody detection systems, with ImmunoCAP fluorescence enzyme immunoassay representing the clinical gold standard due to its broad allergen menu and standardized calibration. The primary commercial purpose centers on identifying type I hypersensitivity triggers to guide avoidance strategies and immunotherapy selection. ImmunoCAP assays dominate laboratory revenue given their regulatory clearance depth and reimbursement anchoring, while point-of-care testing emerges as the fastest-expanding delivery mode as CLIA-waived instruments penetrate physician offices. ELISA formats retain share in research laboratories and lower-throughput settings where capital constraints limit automated platform adoption.
FDA 510(k) pathways and CLIA complexity categorization shape market access timelines for novel IgE assays in the United States, while the EU In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for allergen-specific test kits entering European markets. The EPA and OSHA maintain secondary influence through laboratory chemical handling standards that affect reagent formulation and waste disposal protocols. Stakeholders must monitor evolving payer coverage policies for component-resolved diagnostics versus whole-allergen screening as laboratories weigh assay menu investments against reimbursement uncertainty.
Market Dynamics
The transition from centralized laboratory processing to distributed point-of-care testing is restructuring capital deployment and consumable economics across the IgE allergy diagnostics sector.
Growth Catalysts
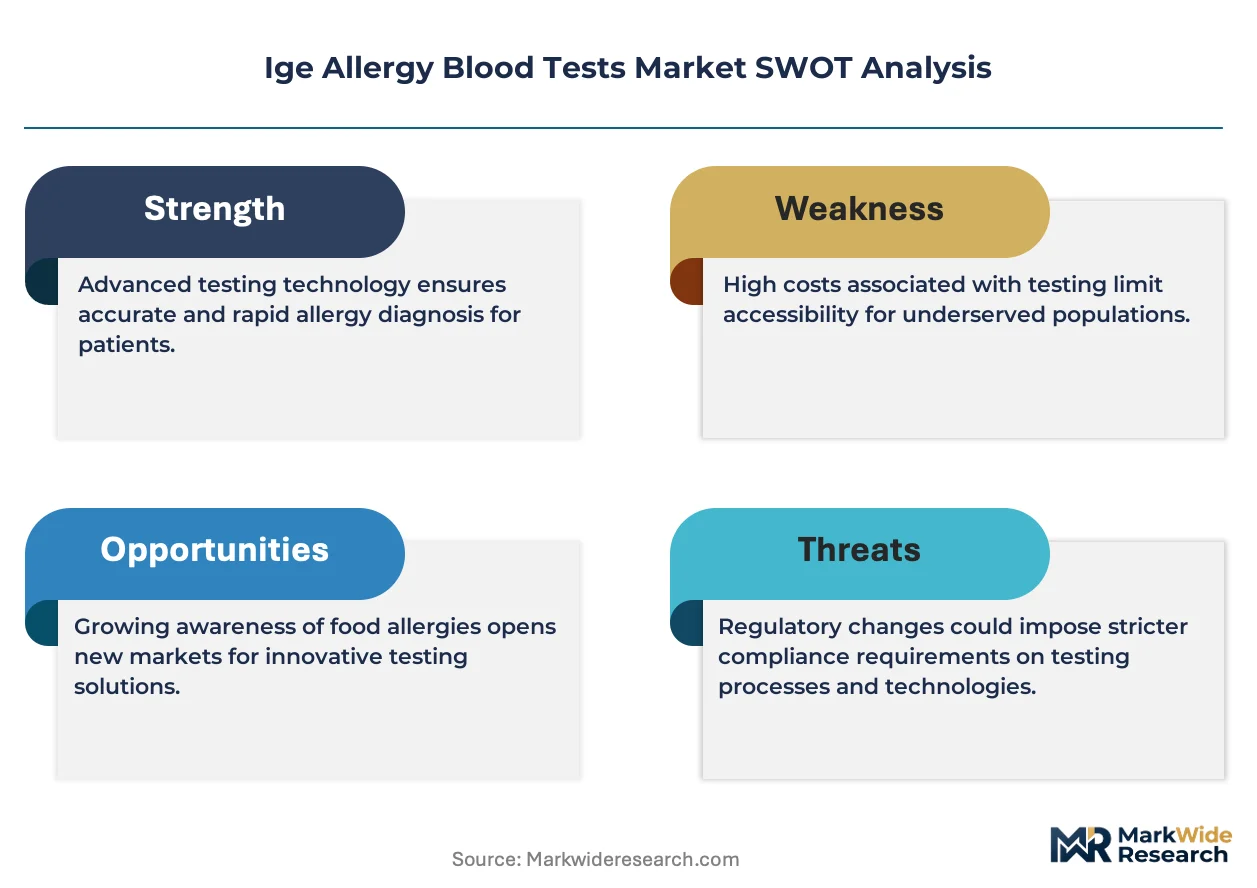
- CLIA Complexity Waivers:The FDA's streamlined 510(k) pathway for moderate-complexity test systems is accelerating physician office adoption of compact immunoassay platforms.
- Component-Resolved Diagnostics:Molecular allergen profiling enables precise immunotherapy selection, driving reagent menu expansion among hospital-based reference laboratories.
- Germany:Statutory health insurance reimbursement for specific IgE quantification supports routine screening protocols in outpatient pulmonology practices.
Market Restraints
- Reagent Supply Concentration:Allergen extract production clusters among a limited set of European and North American specialty chemical suppliers, creating single-source vulnerability.
- EU MDR Compliance Burden:The In Vitro Diagnostic Regulation's clinical evidence requirements extend market access timelines by 18-24 months for novel allergen-specific assays.
- Serological Test Substitution:Skin prick testing retains cost advantage in pediatric populations where venipuncture tolerance limits blood-based screening penetration.
Strategic Opportunities
- Japan:Underpenetrated rural prefectures present whitespace for mobile phlebotomy services linked to centralized laboratory networks.
- Telemedicine Integration:Remote consultation platforms are embedding at-home sample collection kits, creating direct-to-patient distribution channels bypassing traditional referral networks.
- ISO 15189 Accreditation Mandates:Emerging laboratory quality standards in Asia-Pacific markets are forcing facility upgrades that favor automated platform vendors.
Industry Challenges
- Cross-Reactivity Interpretation:Allergen homology complicates result reporting, requiring specialized clinical immunology expertise that strains laboratory staffing.
- Legacy LIS Integration:Hospital information system interoperability gaps complicate bidirectional data exchange between point-of-care instruments and electronic health records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ige Allergy Blood Tests Market |
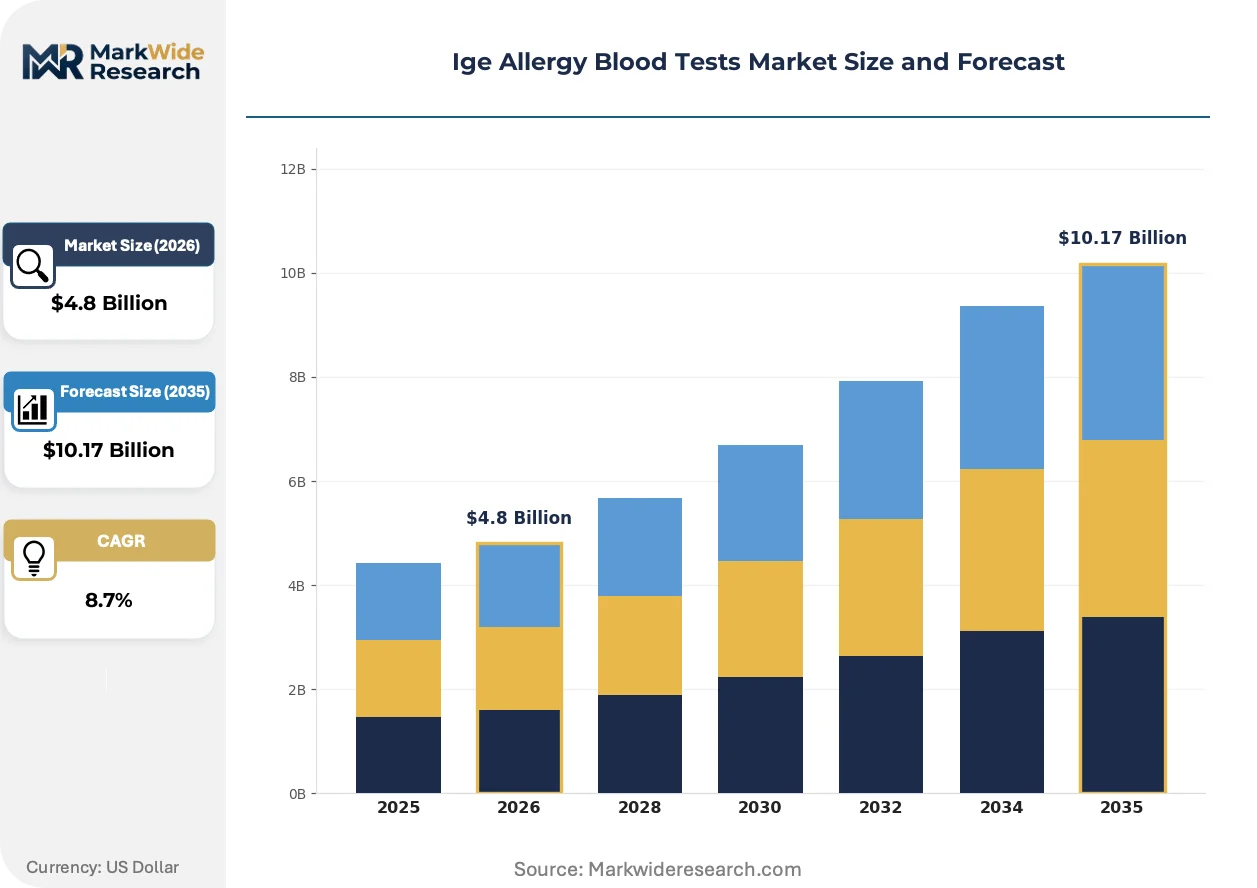
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ImmunoCAP, RAST, ELISA, Western Blot Delivery Mode: Laboratory Testing, Point-of-Care Testing, At-Home Testing, Mobile Testing Customer Type: Hospitals, Diagnostic Centers, Research Laboratories, Home Users Therapy Area: Dermatology, Pulmonology, Immunology, Pediatrics |
| Companies Covered | Thermo Fisher Scientific, Siemens Healthineers, Danaher Corporation, Abbott Laboratories, Omega Diagnostics Group PLC, HYCOR Biomedical, Bio-Rad Laboratories, bioMérieux SA, PerkinElmer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ige Allergy Blood Tests Market Strategic Shifts
Multiplexed detection architectures and regulatory harmonization efforts are compressing test turnaround times while expanding the clinical utility of serum IgE profiling beyond traditional allergy diagnosis.
Multiplex microarray platforms are integrating semiconductor-based photodetection to simultaneously quantify IgE responses against 100+ allergen components from a single serum sample. Academic medical centers in the United States and Switzerland are adopting these systems for complex polysensitized patient workups. The technology is integrating proteomic-scale data generation into routine clinical workflows, shifting competitive advantage toward informatics-capable vendors.
The EU In Vitro Diagnostic Regulation's performance evaluation requirements are forcing manufacturers to generate clinical evidence across diverse European populations. Siemens Healthineers and Thermo Fisher Scientific have expanded post-market surveillance infrastructure to capture real-world assay performance data. Smaller reagent developers without dedicated regulatory affairs capacity are outsourcing notified body interactions to specialized consultancies.
Allergists are consolidating procurement through group purchasing organizations to secure volume-based pricing on automated platform contracts. Independent diagnostic laboratories in Germany and the United Kingdom are responding by unbundelling reagent supply from instrument service agreements, creating spot-market purchasing flexibility. This behavior is most visible in high-throughput urban reference laboratories where test volumes justify dedicated supply chain personnel.
Ige Allergy Blood Tests Market Segmentation
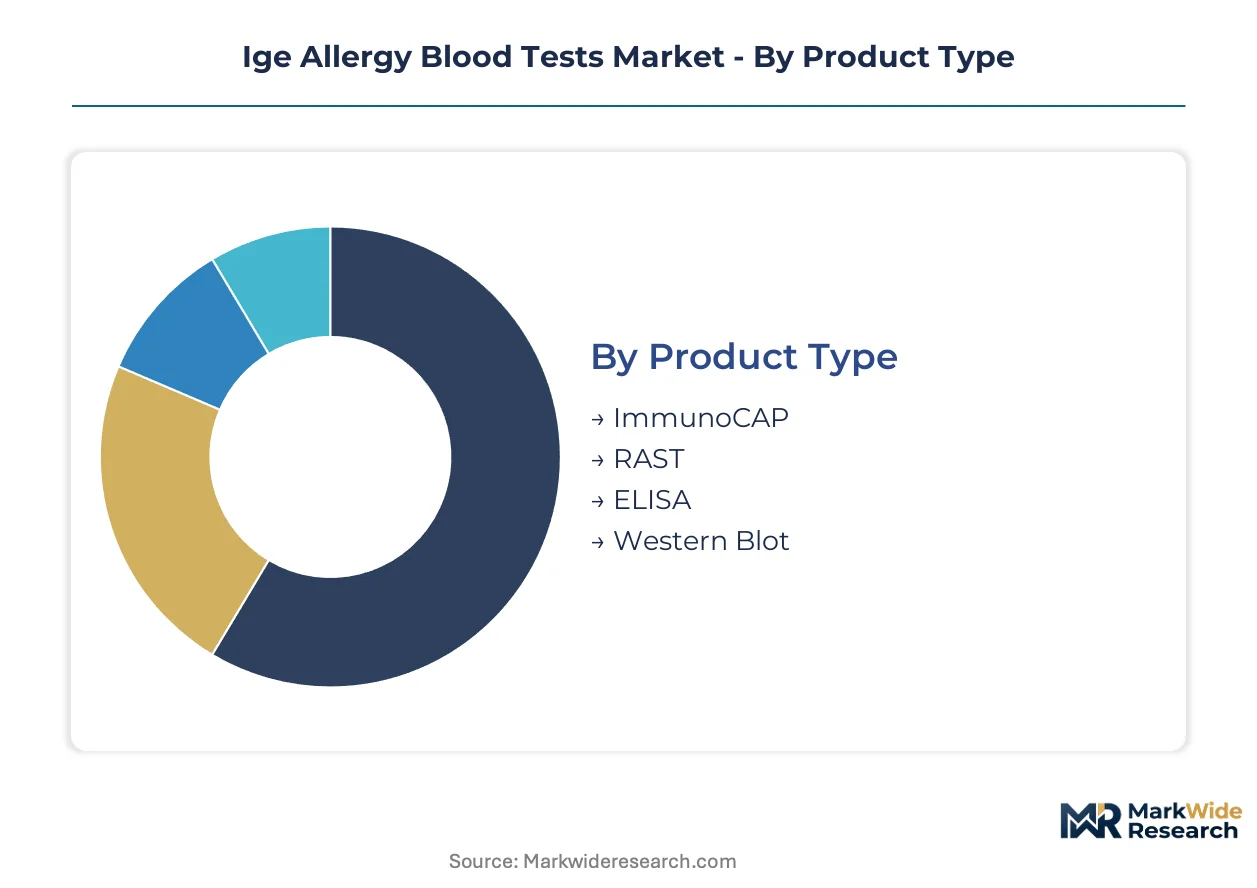
IgE allergy diagnostics fragment across multiple technical and commercial dimensions. Each segmentation axis reveals distinct margin structures, regulatory pathways, and customer procurement behaviors that shape vendor strategy.
Product Type:
Customization-to-standardization tension runs deepest here, with fluorescence enzyme immunoassay platforms representing the engineered endpoint of decades of regulatory investment.
- ImmunoCAP:Fluorescence enzyme immunoassay with standardized allergen panels and calibrated IgE quantification against WHO reference standards. Demand concentrates in hospital reference laboratories in the United States and Germany where FDA 510(k) and CE-IVD clearance depth anchor reimbursement contracts.
- RAST:Radioallergosorbent test using radiolabeled anti-IgE antibodies; declining share but retained in legacy laboratory installations where capital replacement cycles lag. Research laboratories in Japan continue limited deployment for historical protocol continuity.
- ELISA:Enzyme-linked immunosorbent assay formats with lower capital barriers; academic medical centers and lower-throughput settings where automated platform economics fail to justify investment.
- Western Blot:Membrane-based allergen detection for component-resolved diagnostics; specialized immunology laboratories investigating cross-reactive protein epitopes.
Leading the category by volume: ImmunoCAP. Expanding most quickly: ELISA in resource-constrained settings.
Delivery Mode:
Proximity to the patient determines capital intensity, with distributed models compressing per-test economics through volume aggregation.
- Laboratory Testing:Centralized high-throughput immunoanalyzers processing 100+ samples hourly; hospital and independent reference laboratories in urban United States and German markets where batch efficiency dominates unit economics.
- Point-of-Care Testing:CLIA-waived compact instruments in allergist and pulmonologist offices; fastest-expanding delivery mode as Siemens and Thermo Fisher deploy cartridge-based systems with 15-minute turnaround.
- At-Home Testing:Finger-prick capillary collection kits with mail-back logistics; direct-to-consumer channels bypassing traditional referral networks through telemedicine platform integration.
- Mobile Testing:Phlebotomy-equipped vehicles serving rural prefectures in Japan and underserved United States counties; centralized laboratory networks capturing geographic whitespace without fixed facility investment.
Dominant by revenue: Laboratory Testing. Steepest expansion trajectory: Point-of-Care Testing.
Customer Type:
Procurement sophistication separates institutional buyers from individual consumers, with group purchasing organizations consolidating hospital and diagnostic center demand.
- Hospitals:Integrated health systems with dedicated immunology departments; academic medical centers in Switzerland and the United States driving multiplex microarray adoption for complex polysensitized cases.
- Diagnostic Centers:Independent reference laboratories unbundling reagent supply from instrument service agreements; Germany and United Kingdom urban facilities with dedicated supply chain personnel negotiating spot-market pricing.
- Research Laboratories:Academic and pharmaceutical investigation sites; ELISA and Western Blot retention driven by protocol flexibility and publication comparability requirements.
- Home Users:Direct-to-consumer segment emerging through telemedicine-integrated sample collection; regulatory ambiguity around self-interpreted results limiting menu breadth.
Highest absolute spend: Hospitals. Gaining share fastest: Diagnostic Centers through GPO consolidation.
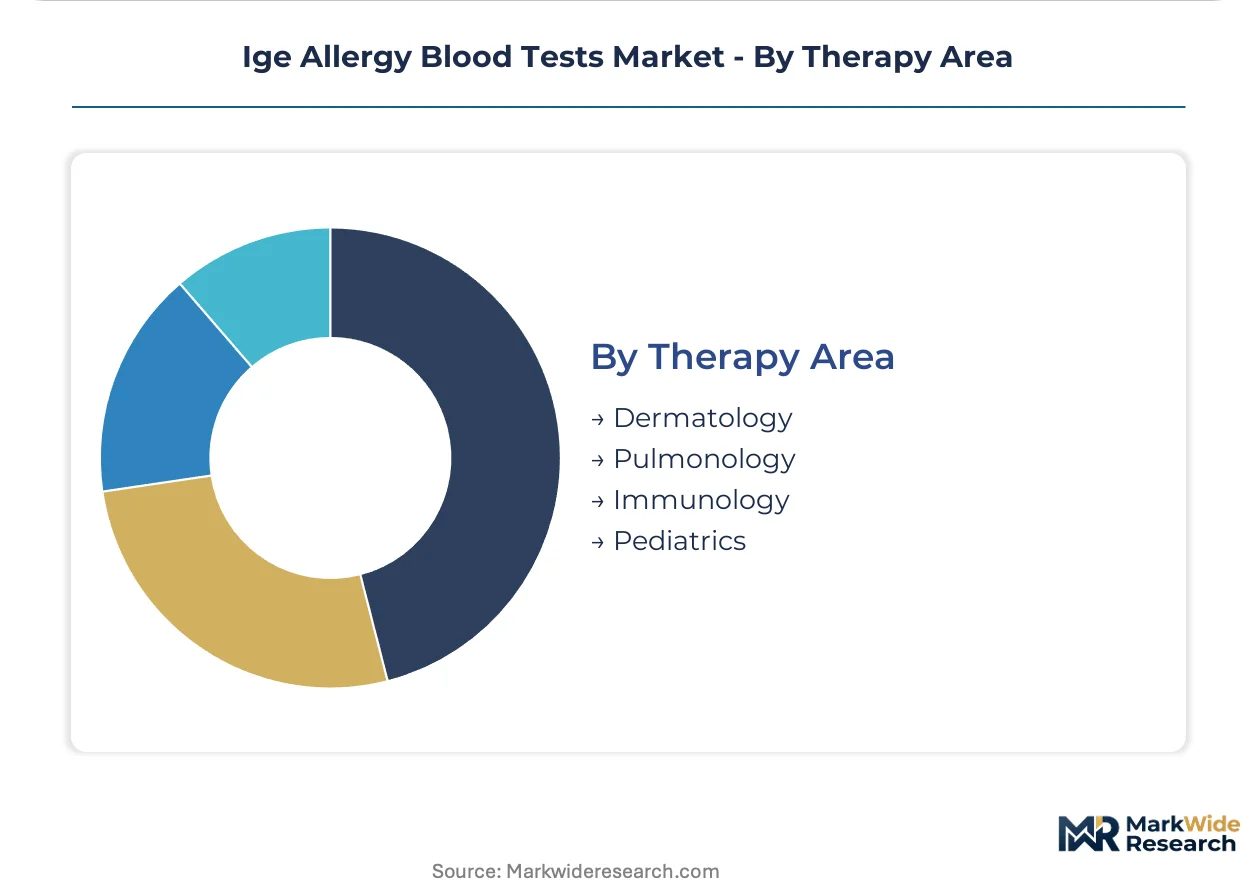
Therapy Area:
Clinical specialization determines test menu depth, with pulmonology and immunology practices driving component-resolved diagnostic adoption.
- Pulmonology:Respiratory allergen panels for asthma and allergic rhinitis management; German statutory health insurance reimbursement supporting routine specific IgE quantification in outpatient practices.
- Immunology:Complex polysensitized patient workups leveraging multiplex microarray platforms; academic medical centers in the United States and Switzerland integrating proteomic-scale data generation.
- Dermatology:Contact and atopic dermatitis allergen identification; patch test correlation driving limited serum IgE utility in eczematous conditions.
- Pediatrics:Venipuncture tolerance constraints favoring skin prick testing substitution; blood-based screening concentrated in severe atopic cases where specific IgE thresholds guide immunotherapy initiation.
Largest addressable population: Pulmonology. Climbing the fastest: Immunology through molecular allergen profiling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Allergen extract production clusters in specialized European and North American chemical facilities anchor geographic demand for IgE quantification platforms. Laboratory infrastructure density and statutory reimbursement frameworks determine test penetration rates across national markets.
United States
Academic medical centers in Boston and the Research Triangle drive multiplex microarray adoption for complex polysensitized patient workups. FDA 510(k) pathways and CLIA complexity waivers accelerate point-of-care instrument deployment in allergist offices. Siemens Healthineers and Thermo Fisher Scientific maintain instrument installed bases across hospital reference laboratories in urban corridors.
Germany
Statutory health insurance reimbursement for specific IgE quantification supports routine screening in outpatient pulmonology practices throughout Bavaria and North Rhine-Westphalia. EU MDR compliance requirements extend market access timelines for novel allergen-specific assays entering European markets. Independent diagnostic laboratories in Berlin and Hamburg unbundle reagent supply from instrument service agreements.
Japan
Venipuncture tolerance constraints in pediatric populations limit blood-based screening penetration outside severe atopic cases. PMDA regulatory frameworks govern in vitro diagnostic market entry for automated immunoassay platforms. Underpenetrated rural prefectures present whitespace for mobile phlebotomy services linked to centralized laboratory networks in the Kanto region.
Switzerland
Academic medical centers in Zurich and Geneva adopt semiconductor-based photodetection systems for proteomic-scale IgE data generation. Swissmedic maintains stringent clinical evidence requirements for allergen-specific test kits. Component-resolved diagnostics adoption concentrates in university hospital immunology departments serving complex polysensitized referrals from surrounding cantons.
United Kingdom
Independent reference laboratories in Greater London negotiate spot-market purchasing flexibility for high-throughput urban facilities. NHS reimbursement policies shape test menu investments against coverage uncertainty for component-resolved versus whole-allergen screening. Allergist consolidation through group purchasing organizations compresses pricing on automated platform contracts across Southeast England.
Ige Allergy Blood Tests Market Competitive Environment
Global majors compete with regional champions across regulatory clearance depth and installed base economics. The vendor base separates into fluorescence enzyme immunoassay specialists, diversified diagnostics conglomerates, and point-of-care instrument developers. Three archetypes dominate: platform-integrated multinationals leveraging consumable recurring revenue, allergen extract producers with backward integration into assay development, and workflow-density competitors embedding IgE testing within broader immunology panels. Competitive moves concentrate on CLIA-waived instrument deployment and multiplexed detection architecture licensing.
Among diversified diagnostics conglomerates, Thermo Fisher Scientific and Siemens Healthineers exemplify platform-integrated positioning through immunoanalyzer installed bases and recurring consumable revenue streams. Danaher Corporation occupies a position emphasizing workflow density and immunology panel integration. These three entities anchor competitive dynamics in hospital reference laboratory procurement, where group purchasing organization consolidation and unbundled reagent supply negotiations reshape contract structures.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Siemens Healthineers |
| Danaher Corporation |
| Abbott Laboratories |
| Omega Diagnostics Group PLC |
| HYCOR Biomedical |
| Bio-Rad Laboratories |
| bioMérieux SA |
| PerkinElmer Inc. |
| Others |
Value Chain & Pricing Dynamics
Allergen extract production costs in specialized European chemical facilities cascade through three distinct pricing tiers, with purified recombinant protein inputs commanding premium positioning against whole-allergen reagents in hospital procurement contracts.
Pricing Analysis
Service bundling separates instrument placement agreements from standalone reagent supply, with Siemens Healthineers and Thermo Fisher Scientific embedding multi-year maintenance contracts into automated platform leases while independent German laboratories negotiate unbundled spot-market purchasing for consumables. Three-tier pricing structure across premium, standard, and economy levels reflects calibration depth against WHO reference standards and allergen panel breadth. Cost compression in the economy tier intensifies because CLIA-waived point-of-care instruments from Abbott and Danaher compete on per-test economics. Diagnostic centers exhibit highest price sensitivity through group purchasing organization consolidation, while academic medical centers in Switzerland and the United States demonstrate lowest sensitivity given grant-funded multiplex microarray adoption.
Supply Chain Analysis
Specialized immunochemistry workforce availability in Germany, Switzerland, and the eastern United States constrains allergen extract manufacturing scale-up, with Phadia's Uppsala facility and Thermo Fisher's solid-phase synthesis operations drawing from limited pools of protein purification specialists. Allergen extract production rests on purified natural source materials, recombinant DNA-derived proteins, and fluorescence-labeled detection antibodies. Single-source vulnerability concentrates in European specialty chemical suppliers for rare allergen components. Distribution runs through direct vendor-to-laboratory contracts for automated platforms, with secondary reagent supply channeled through diagnostic distribution networks in urban United States and German corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IgE allergy diagnostics sector is consolidating around automated platform vendors with regulatory clearance depth, with EU MDR compliance costs forcing smaller reagent developers toward acquisition or exit.
For Market Incumbents: Cement recurring revenue streams by locking in hospital reference laboratory instrument placements through embedded service agreements that complicate competitive displacement. Expand multiplex microarray menu breadth to capture complex polysensitized case volume from academic medical centers before component-resolved diagnostics commoditizes. Threatened by unbundled reagent purchasing behavior among German and United Kingdom independent laboratories, prioritize backward integration into allergen extract production to defend consumable margin structure. For New Entrants and Emerging Players: FDA CLIA complexity waivers in the United States open a window for compact point-of-care instrument development targeting allergist office penetration with 15-minute turnaround cartridge systems. Telemedicine-integrated at-home sample collection kits represent the most penetrable whitespace, bypassing traditional referral network gatekeepers through direct-to-patient channels. Japan's underpenetrated rural prefectures offer geographic entry point via mobile phlebotomy service partnerships with Kanto region centralized laboratories. For Investors and Strategic Acquirers: Notified body outsourcing announcements from smaller European reagent developers is the leading indicator that EU MDR compliance burden has reached critical pressure for sub-scale players. Long-term viability favors automated platform vendors with installed base economics and consumable recurring revenue over pure reagent developers facing regulatory cost escalation. Target acquisition archetype: regional immunoassay specialists with existing CE-IVD clearance portfolios and established allergen extract supply relationships. Signal to monitor: consolidation of group purchasing organization contracts among United States hospital systems compressing pricing on Siemens and Thermo Fisher platforms.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Instrument Development | FDA streamlined pathways accelerate point-of-care deployment in allergist offices. |
| Allergen Extract Backward Integration | In-house protein purification secures consumable supply against European specialty chemical concentration. |
| Multiplex Microarray Menu Expansion | Semiconductor-based photodetection captures complex polysensitized case volume from academic centers. |
| Telemedicine Platform Partnership | Direct-to-patient sample collection kits bypass traditional laboratory referral networks. |
| EU MDR Post-Market Surveillance Buildout | Real-world performance data capture satisfies stricter clinical evidence requirements for allergen-specific assays. |
Study Parameters
Document review covered FDA 510(k) filings, EU MDR technical documentation, and hospital procurement database records, complemented by interviews with clinical laboratory directors, allergist practice administrators, diagnostic reagent procurement managers, and regulatory affairs specialists at IVD manufacturers. Secondary validation drew from CMS Medicare reimbursement schedules, GPO contract disclosure filings, and PMDA marketing authorization databases. Bottom-up test volume modeling triangulated against top-down market sizing from instrument installed base estimates.
Market value outputs across the projection horizon reflect segment-level pricing stratification by delivery mode, product type, and customer archetype, with CAGRs derived from regression analysis of historical instrument placement cycles and consumable pull-through rates. Segmentation dimensions modeled encompass assay technology, delivery mode proximity to patient, customer procurement sophistication, and clinical specialty application. Forecast inputs incorporated CLIA waiver approval velocity, EU MDR transition timelines, and statutory reimbursement policy shifts in Germany and Japan.
The model assumes a particular technology adoption path; alternative pathways for multiplex microarray versus singleplex ImmunoCAP would alter the outlook for informatics-capable vendors versus established platform incumbents. Forecasts reflect assumptions around regulatory clearance maintenance, allergen extract supply continuity, and point-of-care instrument reliability metrics. Material deviation in FDA CLIA waiver grant rates or EU notified body capacity constraints warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Antibiotic Residue Test Kits Market
Testing Services
Pyrogen Testing Market
Testing Services
Addison Disease Testing Market
Testing Services
Global ADME Toxicology Testing Market
Testing Services
North America Testing Inspection and Certification (TIC) Market
Testing Services
Employer and Workplace Drug Testing Market
Testing Services
Allergy Tester Market
Testing Services
Special Coagulation Tests Market
Testing Services
Fertility Testing Market
Testing Services
Global Ovulation Test Market
Testing Services
Target-Based ADME/ Tox Assay Market
Testing Services
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market
Testing Services
Drug Screening Laboratory Service Market
Testing Services
Redox Meter Market
Testing Services
Specific Protein Testing Market
Testing Services
Alcohol Breathalyzer and Drug Testing Equipment Market