
 Shelf-Stable Soup Market | 2026-2036
Shelf-Stable Soup Market Size, Share, and Industry Trends Forecast 2026-2036
Shelf-Stable Soup Market Analytics
Private-label premiumization is rewriting margin distribution across the shelf-stable soup category. Nestlé SA leverages its global R&D infrastructure to sustain innovation pipelines in reduced-sodium and clean-label formulations. Campbell Soup Company anchors its position through deep channel control in North American retail, while Kraft Heinz Company competes aggressively on price-positioned comfort varieties in mass-market grocery.
Shelf-stable soup comprises thermally processed, hermetically sealed broths and prepared meals with water activity below 0.85, retorted at 121°C to achieve commercial sterility without refrigeration. The category serves primarily as a convenient meal solution for households, institutions, and emergency preparedness stockpiles where cold-chain infrastructure is limited or cost-prohibitive. Canned soup still occupies the largest revenue pool despite slower volume growth, while pouch formats are capturing faster expansion through lighter shipping weights and microwave-ready convenience. Vegetable-based ingredient types are gaining shelf space as plant-forward dietary patterns reshape retail assortment priorities.
The FDA governs acidified and low-acid food regulations under 21 CFR Parts 108, 113, and 114, mandating scheduled thermal process filings that raise compliance barriers for new entrants. USDA organic certification and Non-GMO Project verification increasingly function as market-access gatekeepers for premium-positioned lines. Stakeholders must monitor evolving front-of-package disclosure mandates and sodium threshold enforcement, as these rules will determine which formulations retain retail distribution and which face delisting pressure.
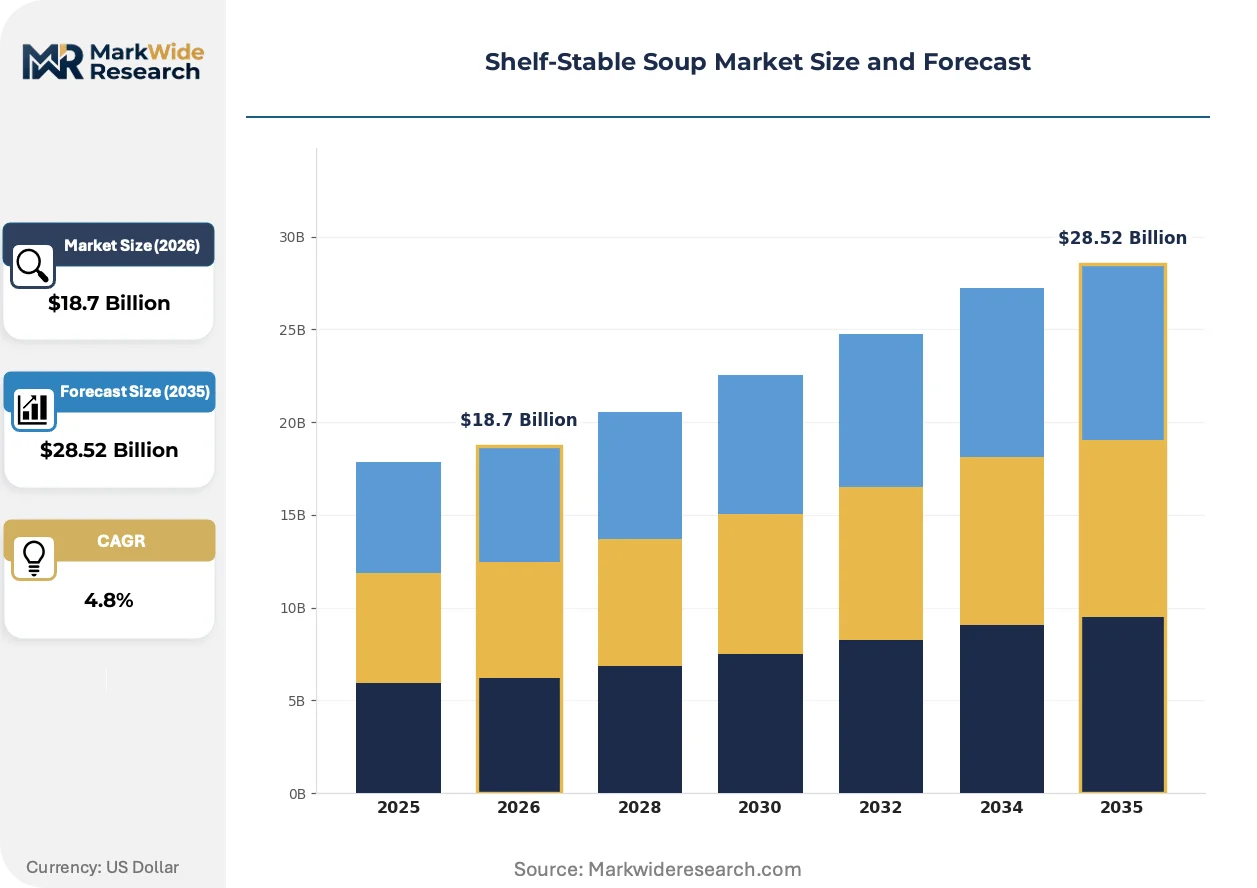
Market Dynamics
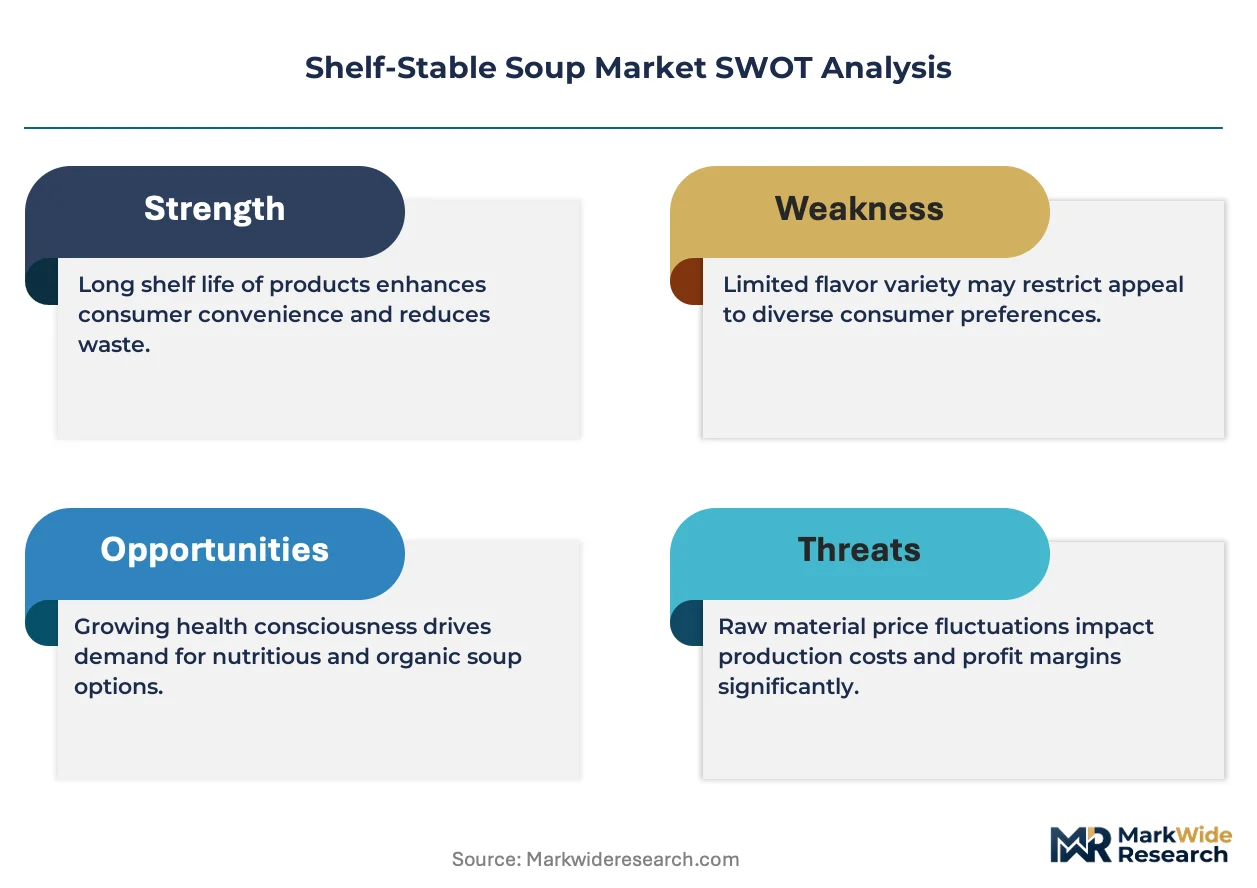
Front-of-package sodium disclosure mandates and dual-pressure thermal processing requirements are compressing formulation flexibility while elevating compliance costs for mid-tier manufacturers.
Growth Catalysts
- Meal Kit Channel Penetration:Direct-to-consumer subscription services are absorbing shelf-stable soup SKUs as pantry-stocking behavior migrates toward curated convenience bundles.
- FDA Sodium Reduction Targets:The agency's voluntary targets are accelerating clean-label R&D investments, rewarding early movers with preferred retail placement.
- Retort Pouch Technology:Lighter shipping weights and microwave-ready formats are capturing logistics cost savings and younger household adoption.
Market Restraints
- Aluminum Can Input Volatility:Primary metal price swings and tariff exposure on imported sheet stock compress margin predictability for canned-format specialists.
- Thermal Process Filing Burden:FDA 21 CFR Part 113 scheduled process requirements create multi-month approval timelines that deter SKU proliferation.
- Fresh-Refrigerated Substitution:Chilled soup segments in premium grocery are capturing trade-up demand from health-conscious households.
Strategic Opportunities
- USDA Organic Certification Tailwind:Federal procurement preference for certified organic products opens institutional channel access for compliant suppliers.
- Emergency Preparedness Stockpiling:Federal and state-level disaster relief contracting represents underpenetrated volume for multi-year shelf-life formats.
- Plant-Forward Formulation Convergence:Pea protein and legume broth bases paired with retort technology unlock clean-label protein positioning.
Industry Challenges
- Retort Operator Skill Scarcity:Specialized thermal process authority certification requirements constrain production scaling for regional manufacturers.
- Legacy Canning Line Retrofit Costs:Transitioning steel-body assets to aluminum or pouch formats demands capital intensity that mid-caps struggle to finance.
- Front-of-Package Label Compliance:Evolving FDA disclosure templates force recurring packaging redesign cycles and inventory write-offs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shelf-Stable Soup Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Soup, Pouch Soup, Ready-to-Eat Soup, Instant Soup Ingredient Type: Vegetable-Based, Meat-Based, Seafood-Based, Legume-Based End User: Retail Consumers, Food Service Providers, Institutions, Meal Kit Services Packaging Type: Glass Jar, Tetra Pak, Metal Can, Plastic Pouch |
| Companies Covered | General Mills Inc., Nestlé SA, Kraft Heinz Company, Pacific Foods, Unilever PLC, Campbell Soup Company, Conagra Brands Inc., Nona Lim, Tabatchnick Fine Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shelf-Stable Soup Market Evolving Landscape
Aseptic processing advances and alternative protein hydrolysis are converging to redefine acceptable taste thresholds in reduced-sodium formulations, while regulatory disclosure mandates accelerate packaging format experimentation.
High-pressure processing (HPP) adjuncts to traditional retort cycles are rendering obsolete the flavor degradation trade-offs that previously constrained sodium reduction targets. Clean-label soup developers are piloting HPP-assisted thermal treatments that preserve volatile aromatic compounds. The technology is compressing the reformulation timeline for premium-positioned lines.
The FDA's updated front-of-package nutrition labeling proposal is forcing disclosure architecture redesigns across low-acid canned food portfolios. Manufacturers must reallocate label real estate to sodium and added-sugar callouts. Pouch formats with expanded graphic panels are capturing disproportionate R&D investment as a direct response.
Pantry consolidation behavior among US households is displacing single-serve impulse purchases with multi-pack value configurations. Club channel buyers are negotiating exclusive multi-can bundles that absorb warehouse shelf space. This pattern concentrates volume with suppliers capable of co-manufacturing at private-label scale.
Shelf-Stable Soup Market Segmentation
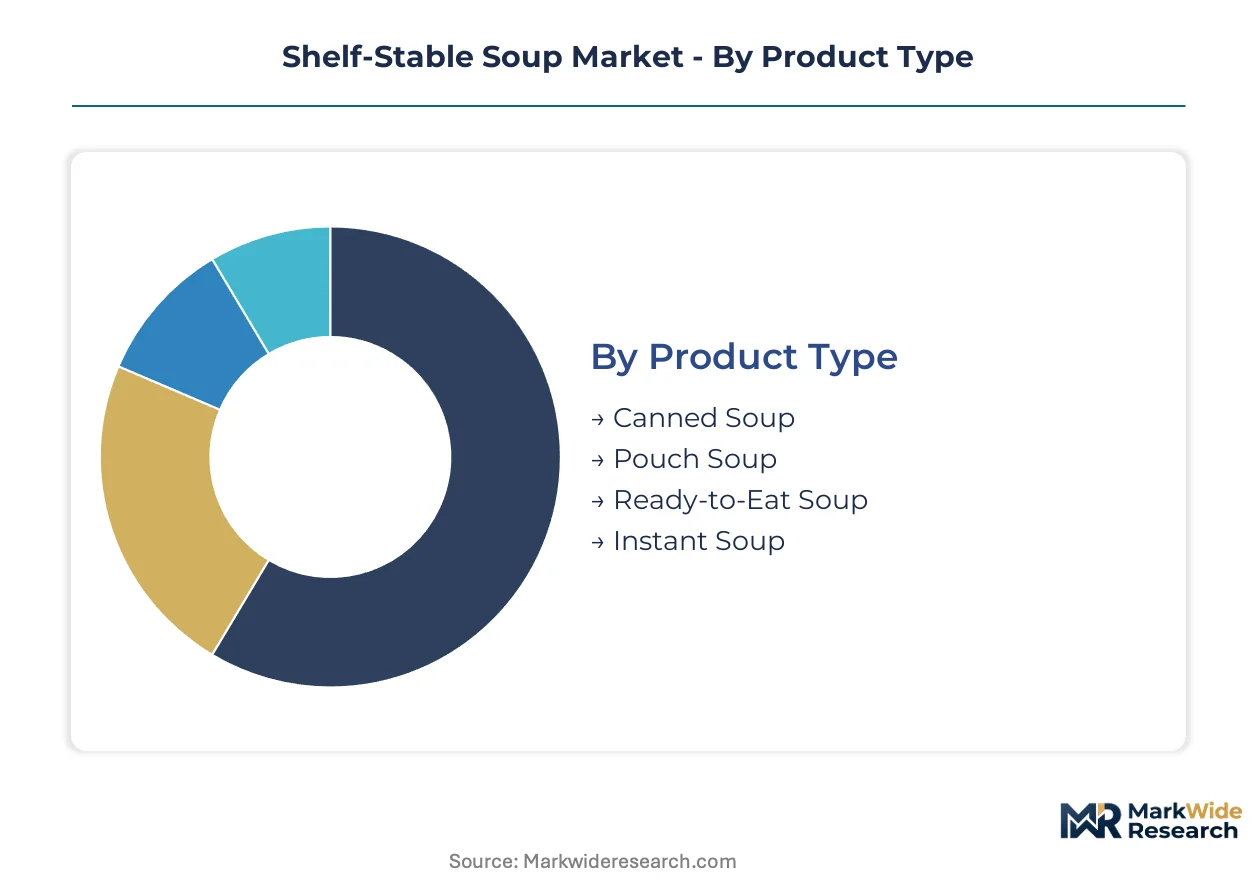
Segmentation in shelf-stable soup reveals divergent velocity profiles across formats and channels. Canned formats turn inventory slowly through pantry-stocking behavior while pouch and meal kit integrations cycle faster through subscription replenishment models.
Product Type:
Cycle times vary dramatically across formats, with retort pouches and instant varieties rotating fastest through e-commerce and convenience channels while canned soup sits longest in household inventory.
- Canned Soup:Hermetically sealed steel or aluminum containers retorted at 121°C for commercial sterility. Demand concentrates in US mass-market retail and federal emergency stockpile contracts where multi-year shelf stability overrides format preference. Aluminum input volatility compresses margin predictability for specialists.
- Pouch Soup:Flexible laminated films with retort sterilization enabling microwave-ready consumption. Younger US households and direct-to-subscription services absorb volume fastest due to lighter shipping weights and disposal convenience. Logistics cost savings accelerate R&D investment.
- Ready-to-Eat Soup:Pre-heated formulations requiring minimal preparation. Institutional channels and workplace food service in US urban centers prioritize portion-controlled formats.
- Instant Soup:Dehydrated or condensed bases requiring water addition. College demographics and camping/outdoor retail in US mountain states sustain niche demand.
Canned soup anchors the volume base while pouch formats gain share at the steepest rate.
Ingredient Type:
Cost tier differentiation separates commodity protein inputs from premium-positioned plant-forward formulations commanding certification premiums.
- Vegetable-Based:Broths and purees from tomato, squash, mushroom, and root vegetable bases. Clean-label positioning in US premium grocery and USDA organic channels rewards reduced-sodium formulations. FDA disclosure mandates favor front-of-package vegetable density callouts.
- Legume-Based:Pea, lentil, and bean protein broths paired with retort technology. Plant-forward dietary adoption in US coastal metro areas drives fastest expansion among protein alternatives. Pea protein hydrolysates unlock umami depth without sodium loading.
- Meat-Based:Chicken, beef, and pork bone broths with traditional comfort positioning. Midwest US retail and institutional healthcare channels maintain steady offtake despite dietary shift headwinds.
- Seafood-Based:Clam chowder, bisque, and fish stock varieties. New England and Pacific Northwest US regional preferences sustain concentrated demand with limited geographic extension.
Vegetable-based formulations anchor the volume base while legume-based recipes expand most quickly through premium positioning.
End User:
Customer type determines order cadence and specification stringency, from household pantry replenishment to institutional procurement compliance.
- Retail Consumers:Individual households purchasing through grocery, club, and e-commerce channels. US pantry consolidation behavior shifts volume toward multi-pack configurations negotiated by club buyers.
- Meal Kit Services:Curated subscription boxes incorporating shelf-stable soup as pantry components. Direct-to-consumer logistics in US metropolitan corridors absorb SKUs fastest through bundled convenience positioning.
- Food Service Providers:Restaurants, cafeterias, and hospitality operations. Post-pandemic recovery in US urban food service drives portion-controlled format demand.
- Institutions:Schools, hospitals, military, and correctional facilities. Federal procurement preference for USDA organic certification opens access for compliant suppliers.
Retail consumers anchor the volume base while meal kit services climb the fastest through subscription model penetration.
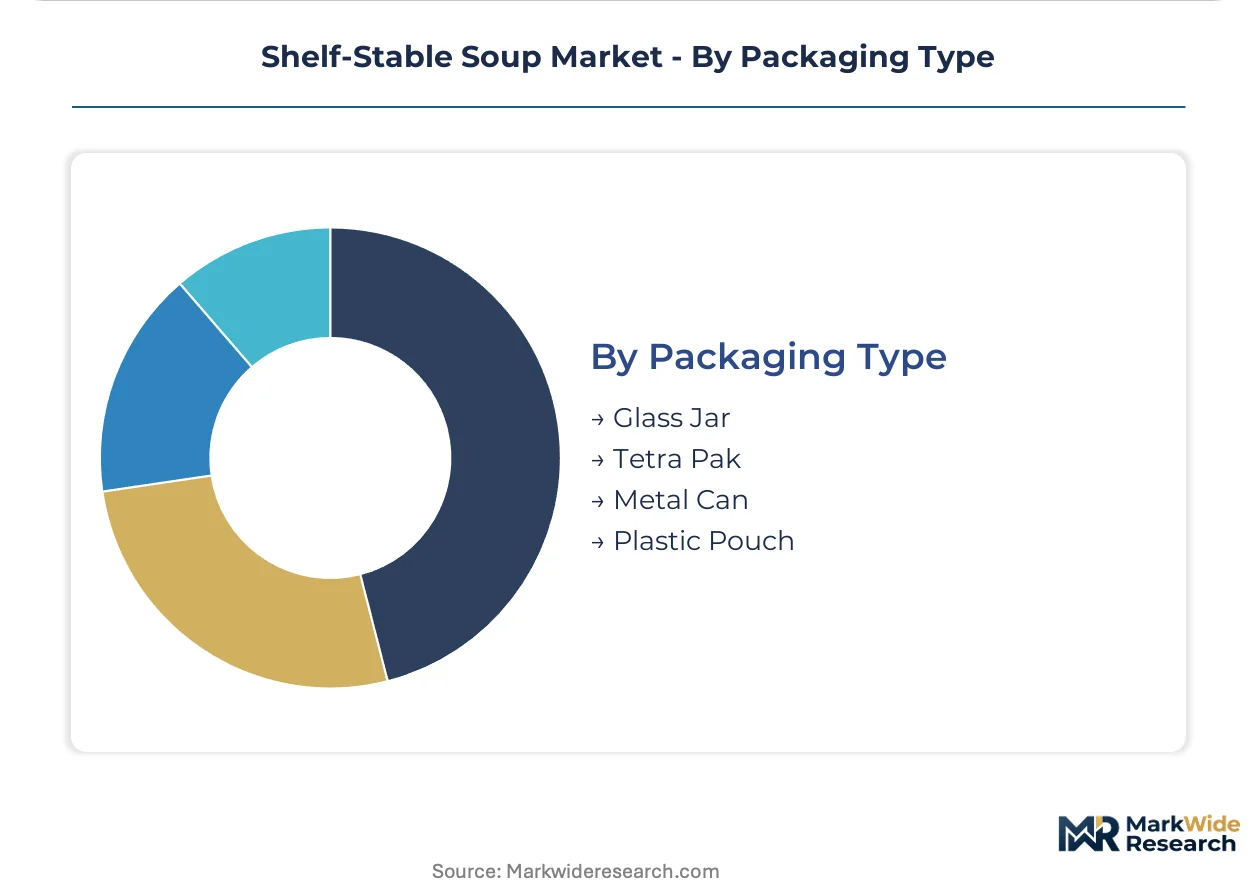
Packaging Type:
Supply concentration and capital intensity separate legacy metal formats from emerging flexible and aseptic alternatives.
- Metal Can:Tinplate or aluminum two-piece containers with established filling and seaming infrastructure. US retail shelf space allocation and emergency preparedness stockpiling sustain dominant position despite weight disadvantages.
- Plastic Pouch:Multi-layer laminated films with spout or tear-notch features. Microwave-ready convenience and reduced shipping cube attract US e-commerce fulfillment optimization.
- Tetra Pak:Aseptic carton formats with extended ambient stability. Limited penetration in US soup category constrained by retort compatibility and consumer familiarity gaps.
- Glass Jar:Heat-tempered containers for premium-positioned organic and specialty varieties. Whole Foods and regional US natural channel placement rewards visual transparency and perceived quality.
Metal can formats anchor the volume base while plastic pouch configurations gain share fastest through logistics and convenience advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. US households absorb premium pouch formats with minimal volume drop-off, while emerging-market buyers trade down aggressively when aluminum input costs spike.
United States
Pantry consolidation behavior and meal kit subscription penetration drive pouch-format adoption fastest. FDA sodium reduction targets and front-of-package labeling mandates compress formulation flexibility for domestic manufacturers. Chicago and Cincinnati anchor Midwest canning infrastructure, while California's Central Valley supplies vegetable inputs for clean-label lines.
Germany
Discount retail dominance at Aldi and Lidl enforces price-positioned private-label supremacy. EFSA clean-label guidelines and EU Green Deal packaging sustainability requirements elevate compliance costs. The Rhine-Ruhr industrial corridor hosts retort pouch conversion specialists serving pan-European distribution.
China
Instant soup powder formats retain volume leadership despite pouch growth in tier-one cities. SAMR food safety regulations and GB standards for thermal-processed foods create multi-month approval barriers. Yangtze River Delta manufacturing clusters around Shanghai concentrate aseptic filling capacity for export markets.
Japan
Single-serve retort pouch formats dominate convenience store channels with minimal price sensitivity. METI energy-efficiency standards for food processing equipment accelerate legacy canning line obsolescence. Kansai region Osaka-based co-manufacturers specialize in reduced-sodium umami formulations.
United Kingdom
Club channel consolidation at Tesco and Sainsbury's shifts volume toward multi-pack configurations. FSA salt reduction targets and upcoming HFSS advertising restrictions reshape retail assortment priorities. Greater Manchester hosts private-label soup manufacturing for pan-European grocers.
Shelf-Stable Soup Market Competitive Landscape
Multinational packaged-food conglomerates and private-label specialists split the market into distinct capability tiers. Consolidation pressure concentrates volume among three to four global operators with retort infrastructure scale, while mid-tier regional manufacturers defend position through co-manufacturing relationships. Strategic archetypes separate R&D-driven clean-label innovators from price-positioned comfort-variety suppliers. Dominant competitive moves include backward integration into aluminum can sheet supply and exclusive multi-year club channel bundle negotiations.
Within the multinational tier, Nestlé SA and Kraft Heinz Company exemplify divergent strategic postures toward sodium reduction and format innovation. Campbell Soup Company anchors North American channel control through deep retail relationships. Among emerging-format specialists, Nona Lim represents the plant-forward, pouch-native archetype targeting subscription and natural-channel placement.
| Leading Market Players |
|---|
| General Mills Inc. |
| Nestlé SA |
| Kraft Heinz Company |
| Pacific Foods |
| Unilever PLC |
| Campbell Soup Company |
| Conagra Brands Inc. |
| Nona Lim |
| Tabatchnick Fine Foods |
| Others |
Value Network & Pricing Analysis
Aluminum can sheet concentration in the US Midwest and imported Southeast Asian supply tiers directly determines margin retention for canned-format specialists, with price volatility propagating fastest to private-label portfolios lacking long-term offtake hedges. Pouch-format premiums absorb logistics cost savings while shielding against metal input swings.
Pricing Analysis
After-sales contract manufacturing and co-packing service agreements drive lifetime value for mid-tier brands lacking in-house retort infrastructure. Three-tier pricing structure across premium clean-label, standard conventional, and economy private-label levels stratifies the category, with USDA organic certification and reduced-sodium R&D investment as primary differentiation levers. Pricing pressure stems from aluminum tariff exposure and energy cost pass-throughs in thermal processing. Club channel buyers exhibit lowest price sensitivity through volume-commitment negotiations, while mass-market grocery shoppers trade down aggressively during input cost spikes.
Supply Chain Analysis
Co-manufacturing concentration among Midwest retort operators and California Central Valley vegetable processors holds effective capacity hostage for emerging brands seeking USDA organic runs. Geographic supply anchors in the United States, with secondary concentration in Germany's Rhine-Ruhr corridor for European pouch conversion and China's Yangtze River Delta for aseptic component sourcing. Raw material dependencies center on aluminum sheet stock, laminated film substrates, and vegetable protein isolates. Single-source vulnerability in qualified retort operator certification constrains production scaling. Distribution runs through club channel consolidation, direct-to-subscription fulfillment, and institutional procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Meal kit subscription penetration represents an early-cycle expansion vector, with curated convenience bundles absorbing shelf-stable soup SKUs faster than traditional retail replenishment cycles.
For Market Incumbents: Entrench channel control through exclusive multi-year club bundle negotiations and backward integration into aluminum sheet supply to insulate margin pools from tariff volatility. Retort operator certification scarcity threatens production scaling for regional competitors; deepen captive thermal process authority capacity in Midwest manufacturing clusters. FDA sodium reduction mandates favor early movers with clean-label R&D pipelines already validated for front-of-package placement. For New Entrants and Emerging Players: Pursue emergency preparedness stockpiling contracts as underpenetrated federal and state procurement volume, where multi-year shelf-life specifications match existing retort capabilities. Meal kit services represent the most penetrable end-use channel for pouch-native formats with microwave-ready convenience positioning. Anchor go-to-market strategy through direct-to-subscription logistics partnerships in US metropolitan corridors rather than contested retail shelf space. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pouch-format conversion lines as legacy canning asset obsolescence accelerates, compressing entry multiples for flexible-format specialists. Long-term viability over a 5-10 year window favors plant-forward formulation platforms with USDA organic certification and retort pouch technology integration. Acquisition targets should display co-manufacturing relationships with established thermal process authority. Monitor aluminum price futures and FDA front-of-package rulemaking as dual inflection indicators for margin compression and compliance cost escalations.| Strategic Initiative | Industry Significance |
|---|---|
| Retort Pouch Capacity Expansion | Lighter shipping weights capture logistics savings for direct-to-subscription channels. |
| USDA Organic Certification Investment | Federal procurement preference opens institutional access for compliant suppliers. |
| Backward Integration into Aluminum Supply | Captive sheet sourcing insulates margin predictability from tariff exposure. |
| Meal Kit Service Partnership | Curated bundle placement displaces traditional pantry-stocking behavior. |
| Reduced-Sodium R&D Pipeline | FDA disclosure mandates reward early clean-label movers with preferred retail placement. |
Research Methodology
A standing panel of category buyers at club and mass-market retailers, thermal process authority certification specialists, co-manufacturing procurement leads, and meal kit service supply chain directors provided ongoing calibration across the study period. Primary interview insights were cross-validated against secondary sources including FDA 21 CFR filing databases, USDA organic certification registries, customs aluminum trade records, and Nielsen retail audit data. Bottom-up SKU velocity modeling and top-down category value triangulation converged on segment-level estimates.
Scenario bracketing around aluminum price volatility bands, FDA sodium enforcement timelines, and meal kit subscription penetration curves anchored the analytical framework. Segmentation dimensions modeled included product format, ingredient type, end-use channel, and packaging technology across the projection horizon. CAGRs were derived from category value trajectories adjusted for input cost pass-through elasticities and channel mix shifts. Forecast inputs incorporated retort pouch adoption rates and clean-label certification premiums specific to shelf-stable soup.
Sensitivities concentrate around aluminum tariff policy shifts, FDA front-of-package rulemaking finalization, and retort operator labor availability constraints. Forecasts reflect documented assumptions regarding pantry consolidation persistence and meal kit channel absorption capacity. Quarterly review of aluminum futures pricing, USDA organic certification application backlogs, and club channel buyer negotiation cycles is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
India Spray Dried Food Market
Processed Foods
Chocolate Filling Market
Processed Foods
High-Pressure Processing (HPP) Foods Market
Processed Foods
Global Malted Milk Market
Processed Foods
Fresh Pasta Market
Processed Foods
Europe Processed Egg Market
Processed Foods
India Ready to Mix Food Market
Processed Foods
Asia-Pacific Food Spread Market
Processed Foods
Ready to Cook Market
Processed Foods
United States Processed Meat Market
Processed Foods
Fat Free Food Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
Africa Soup Market
Processed Foods
Global Pasta Market
Processed Foods
Egg White Cubes Market
Processed Foods
Fat Free Soup Market