
 Ready to Cook Market | 2026-2036
Ready to Cook Market Size, Share, and Industry Trends Forecast 2026-2036
Ready to Cook Market Outlook
Restaurant procurement is pivoting toward chilled and shelf-stable ready to cook formats as labor costs and turnover pressure commercial kitchens. Nestlé leverages its frozen pizza and pasta manufacturing scale across European and Latin American plants. Conagra Brands anchors its position in North American retail through Banquet and Healthy Choice lines. McCain Foods dominates potato-based ready to cook categories with proprietary freezing technology that preserves texture through reheating.
Ready to cook products are pre-processed food formulations requiring controlled thermal treatment, standardized moisture content, and specified water activity levels for microbial stability; they are manufactured through blast freezing, retort sterilization, or modified atmosphere packaging to deliver finished meals requiring minimal consumer preparation time. Frozen product types lead value contribution due to extended shelf life and established cold chain infrastructure, though meal kits capture the fastest structural expansion as subscription models and recipe personalization deepen household engagement. Shelf-stable formats occupy mature margin pools in institutional channels where storage flexibility outweighs freshness premiums.
The FDA enforces nutrition labeling and pathogen control standards under FSMA for ready to cook products distributed in the United States, while the FSSAI mandates additive limits and hygiene certifications for Indian market access. The USDA's inspection protocols for meat-based ready to cook items create compliance thresholds that specialized vegetarian and grain-based producers circumvent. Stakeholders must monitor evolving front-of-pack labeling requirements and carbon footprint disclosure obligations as procurement criteria across retail and foodservice channels tighten.
Market Dynamics
Dual-income urban households in India and Brazil are compressing meal preparation windows, forcing retailers to reconfigure shelf space toward frozen and chilled ready to cook formats that require sub-zero logistics.
Growth Catalysts
- PLI scheme infrastructure:India's Production Linked Incentive scheme for food processing is expanding cold storage capacity, reducing spoilage rates for temperature-sensitive ready to cook products distributed through modern trade channels.
- FSMA pathogen protocols:The FDA's updated hazard analysis requirements are standardizing safety benchmarks, enabling compliant manufacturers to access institutional foodservice contracts previously blocked by liability concerns.
- Blast freezing precision:Advanced cryogenic tunnel systems are preserving cellular structure in vegetable and protein matrices, extending sensory shelf life without chemical preservatives.
Market Restraints
- Natural gas price volatility:Blast freezing and refrigerated transport depend on energy-intensive compression cycles; European and Asian manufacturers face margin compression from input cost spikes.
- Cold chain fragmentation:Last-mile refrigeration gaps in tier-two Indian cities and Indonesian archipelago logistics limit penetration of frozen ready to cook formats outside metropolitan cores.
- Retort sterilization trade-offs:Shelf-stable formats sacrifice texture and nutrient density for ambient distribution, creating permanent quality disadvantages versus fresh-prepared alternatives in premium channels.
Strategic Opportunities
- Brazilian northeast expansion:Underpenetrated urban corridors from Recife to Fortaleza lack frozen ready to cook availability despite rising disposable incomes and working female participation rates.
- Meal kit subscription convergence:Recipe personalization algorithms paired with pre-portioned ingredient packs are capturing household engagement through direct-to-door logistics.
- FSSAI front-of-pack labeling:India's mandatory nutritional disclosure rules favor reformulated low-sodium variants, creating first-mover positioning for compliant domestic manufacturers.
Industry Challenges
- Food safety auditor scarcity:Qualified HACCP certification specialists remain concentrated in Mumbai, Delhi, and Bangalore, delaying plant approvals for regional expansion.
- Legacy ERP integration:Batch traceability requirements under FSMA and FSSAI conflict with analog inventory systems at mid-tier co-manufacturers, forcing costly software migrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready to Cook Market |
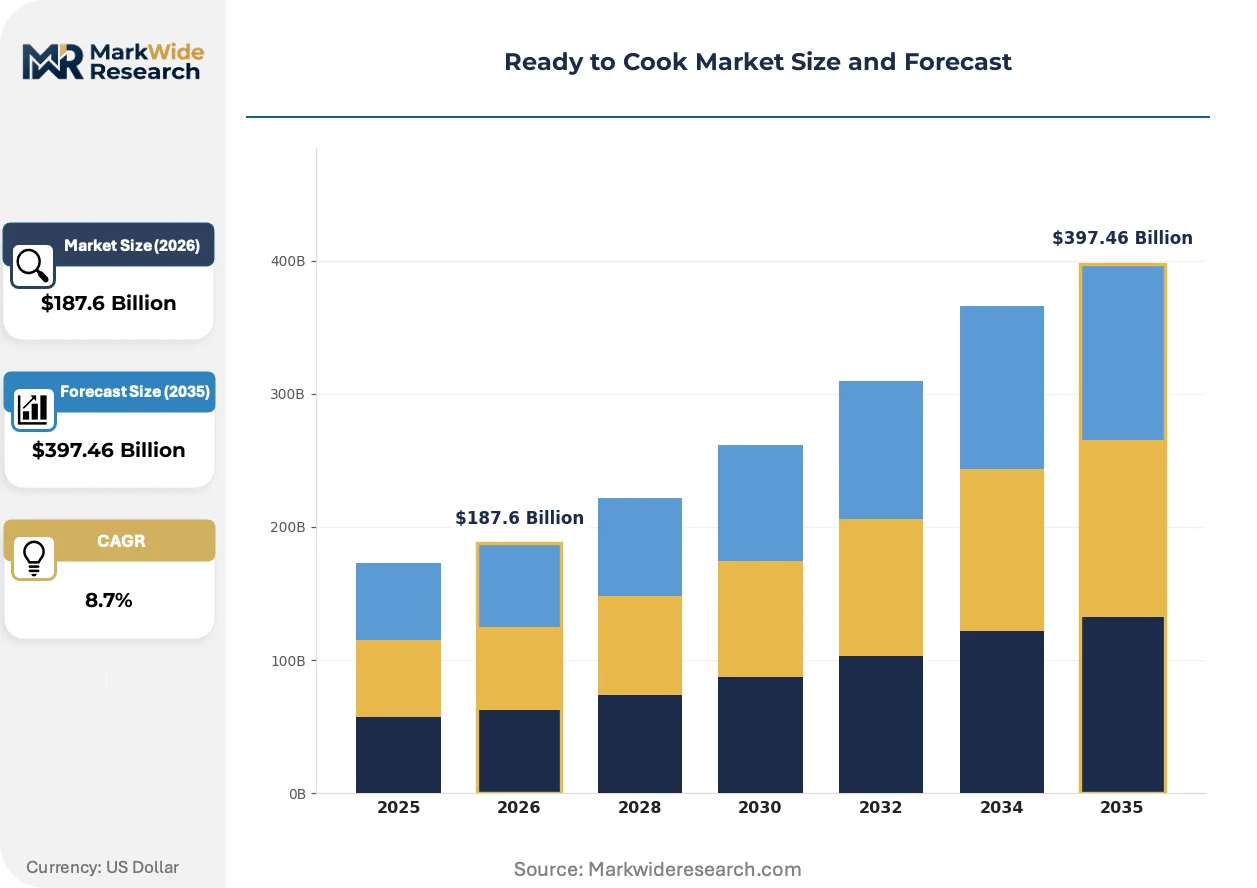
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $397.46 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen, Chilled, Shelf-stable, Meal Kits Ingredient Type: Vegetarian, Meat-based, Seafood, Grain Distribution Channel: Online, Supermarkets, Convenience Stores, Direct Sales End User: Households, Restaurants, Cafeterias, Catering Services |
| Companies Covered | Nestlé, Conagra Brands, General Mills, Kraft Heinz, Tyson Foods, Campbell Soup Company, Unilever, McCain Foods, Nomad Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready to Cook Market Strategic Shifts
Automation and regulatory disclosure mandates are compressing production timelines while fragmenting distribution channels beyond traditional retail. Manufacturers must now synchronize formulation, packaging, and logistics around real-time consumer data.
High-pressure processing technology is automating microbial reduction in chilled ready to cook proteins without thermal degradation. Premium retailers in Germany and Japan are adopting HPP-treated meal components to extend refrigerated shelf life from seven to forty-five days. This shift is automating quality assurance workflows previously dependent on manual sampling.
The EU's Corporate Sustainability Reporting Directive is mandating carbon footprint disclosure across packaged food value chains. Ready to cook manufacturers must now calculate Scope 3 emissions from agricultural inputs through retail distribution. Frozen potato-based and grain-heavy formats face particular scrutiny due to energy-intensive freezing and transport requirements.
Direct-to-consumer subscription models are displacing supermarket center-store placement as the primary customer acquisition channel. Young urban households in Seoul, Toronto, and Sydney prefer algorithm-curated meal kits delivered weekly over aisle browsing. This behavioral pivot forces legacy manufacturers to build in-house digital commerce capabilities or surrender margin to platform intermediaries.
Ready to Cook Market Segmentation
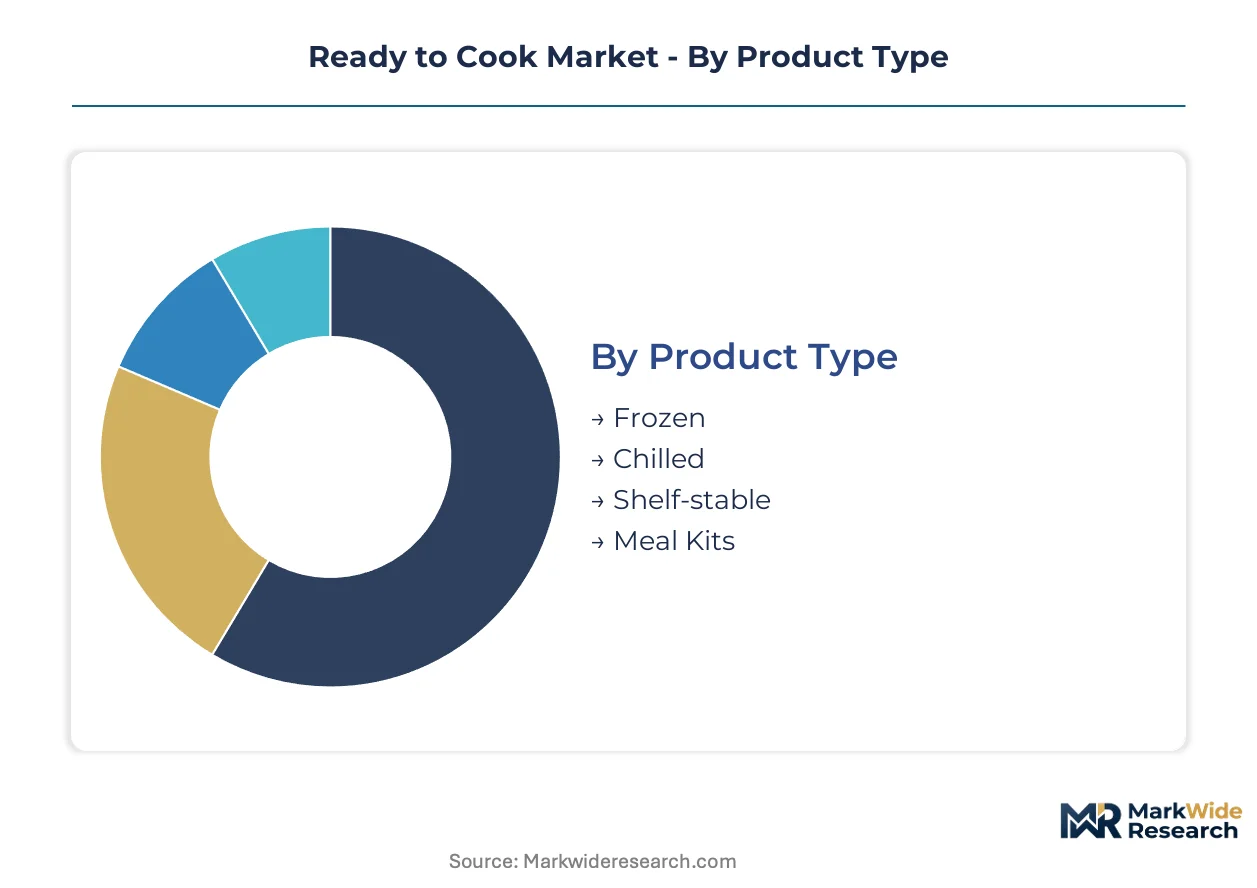
Segmentation in the ready to cook market reveals divergent margin structures and logistics requirements across temperature-controlled and ambient formats. Manufacturers configure production assets and cold chain partnerships differently depending on which segments they target, creating distinct competitive moats.
Product Type:
Frozen formats dominate volume throughput while meal kits command premium pricing and direct consumer relationships.
- Frozen:Blast-frozen formulations with specified water activity levels and sub-zero storage requirements. Demand concentrates in urban Indian and Brazilian households where dual-income compression eliminates meal preparation time; PLI scheme cold storage expansion is reducing spoilage rates in tier-one cities.
- Meal Kits:Pre-portioned ingredient packs with recipe cards and algorithm-curated menu rotations. Subscription models in Seoul, Toronto, and Sydney are displacing supermarket center-store browsing among young urban households seeking convenience without sacrificing cooking participation.
- Chilled:Refrigerated products with seven to forty-five day shelf life depending on HPP treatment. German and Japanese premium retailers favor these for sensory freshness advantages over frozen alternatives.
- Shelf-stable:Retort-sterilized or modified atmosphere packaged items requiring no cold chain. Institutional cafeterias and catering services in regions with fragmented last-mile refrigeration rely on these for storage flexibility.
Today's leader: Frozen. Tomorrow's challenger: Meal Kits.
Ingredient Type:
Plant-based formulations navigate cleaner regulatory pathways while animal proteins face stricter inspection protocols.
- Vegetarian:Grain, legume, and vegetable matrices with lower water activity and reduced microbial load. Indian manufacturers leverage FSSAI compliance advantages to accelerate regional plant approvals where HACCP auditor scarcity delays meat-based facility certifications.
- Meat-based:Poultry, beef, and pork formulations requiring USDA or equivalent inspection protocols. US foodservice procurement pivots toward these for restaurant kitchen labor cost reduction, though FSMA pathogen control mandates raise compliance thresholds.
- Seafood:Fish and shellfish products with specialized freezing requirements for texture preservation. Supply concentrates in coastal processing clusters with proximate cold chain infrastructure.
- Grain:Rice, pasta, and cereal-based formats with extended ambient stability. European CSRD carbon footprint disclosures particularly scrutinize these for agricultural input emissions.
Vegetarian segments gain share fastest where regulatory complexity blocks animal protein competitors.
Distribution Channel:
Channel selection determines margin capture versus volume scale trade-offs for ready to cook manufacturers.
- Online:Direct-to-consumer platforms and third-party delivery aggregators. Algorithm-curated subscription models build household engagement data that informs formulation decisions.
- Supermarkets:Center-store frozen aisles and chilled deli sections. Shelf space reconfiguration in Indian and Brazilian modern trade channels favors temperature-controlled formats.
- Convenience Stores:Grab-and-go chilled and shelf-stable items for immediate consumption. Urban density in East Asian megacities supports high-frequency replenishment models.
- Direct Sales:Institutional contracts with restaurant groups, hotel chains, and corporate cafeterias. FSMA-compliant manufacturers access foodservice contracts previously blocked by liability concerns.
Online channels expand most quickly as legacy manufacturers build in-house digital commerce capabilities.
End User:
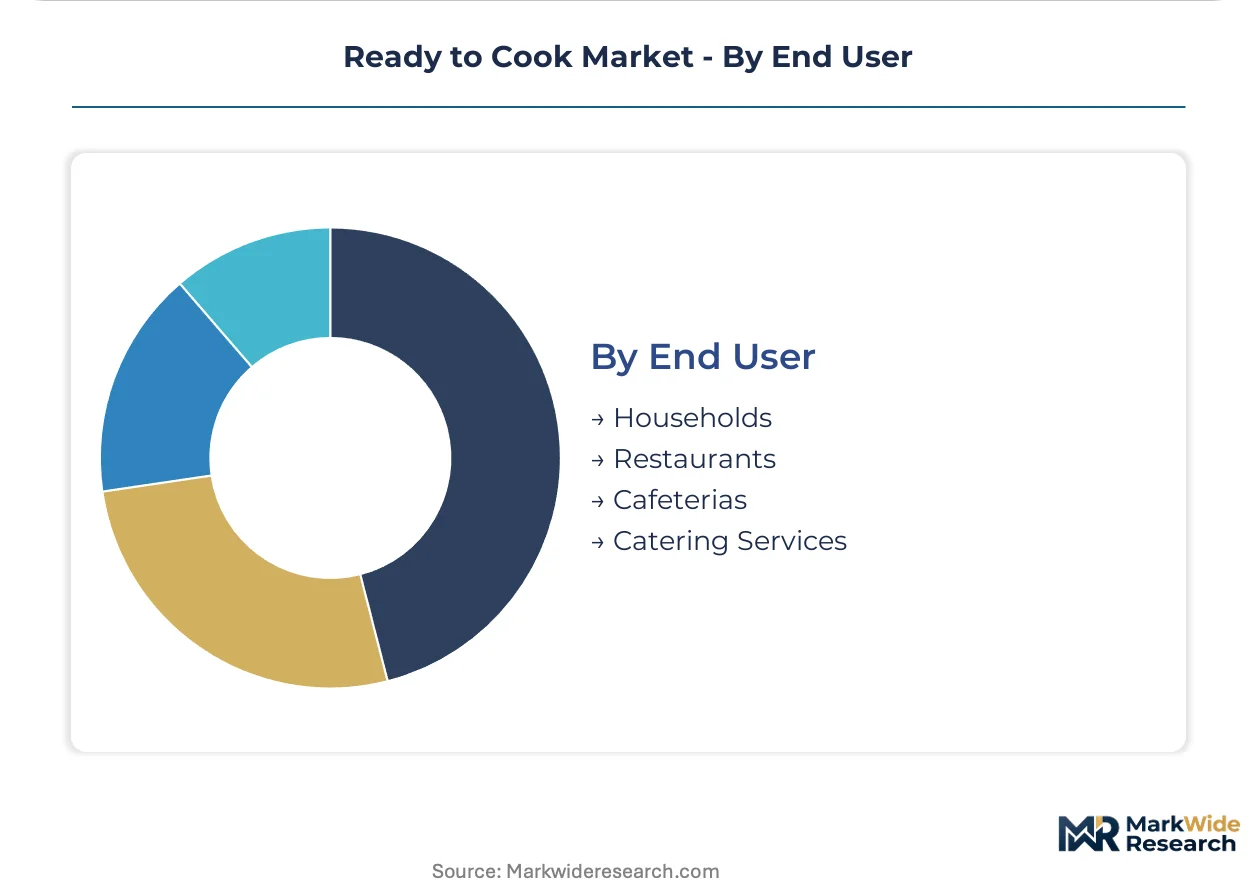
End-use segmentation separates household convenience seekers from commercial kitchen efficiency buyers.
- Households:Individual and family units prioritizing preparation time reduction. Brazilian northeast urban corridors from Recife to Fortaleza show rising penetration potential despite current underavailability.
- Restaurants:Commercial kitchens responding to labor cost and turnover pressure. Chilled and shelf-stable formats reduce line-cook headcount requirements.
- Cafeterias:Institutional feeding operations in corporate, educational, and healthcare settings. Shelf-stable formats dominate where storage flexibility outweighs freshness premiums.
- Catering Services:Event and mobile food providers requiring batch consistency and transport stability. Ambient distribution capabilities determine supplier selection.
Restaurants drive commercial segment growth as labor economics force kitchen automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian cold chain infrastructure expansion under the PLI scheme is redrawing production geography for temperature-sensitive ready to cook formats. Urban household adoption concentrates in metropolitan corridors where dual-income compression eliminates meal preparation time.
United States
Restaurant procurement pivots toward chilled and shelf-stable formats as labor costs and turnover pressure commercial kitchens. The FDA's updated Nutrition Facts labeling and FSMA pathogen protocols reshape formulation requirements and standardize safety benchmarks for institutional foodservice contracts. Chicago and Dallas processing clusters anchor North American frozen pizza and pasta manufacturing scale.
India
Working dual-income households in Mumbai, Delhi, and Bangalore accelerate frozen and meal kit penetration through modern trade channels. The PLI scheme for food processing expands cold storage capacity and reduces spoilage rates for temperature-sensitive products distributed through organized retail. HACCP certification specialists remain concentrated in Mumbai, Delhi, and Bangalore, delaying plant approvals for regional expansion.
Brazil
Urban corridors from Recife to Fortaleza show rising disposable incomes and working female participation rates despite current underavailability of frozen ready to cook formats. ANVISA regulatory frameworks govern additive limits and hygiene certifications for domestic market access. São Paulo anchors national production capacity for grain-heavy and shelf-stable institutional formats.
Germany
Premium retailers adopt high-pressure processing technology for chilled ready to cook proteins to extend refrigerated shelf life from seven to forty-five days. The EU's Corporate Sustainability Reporting Directive mandates carbon footprint disclosure across packaged food value chains, scrutinizing frozen formats for energy-intensive freezing and transport requirements. Berlin and Hamburg processing clusters lead algorithm-curated subscription model experimentation for direct-to-consumer meal kits.
Japan
Young urban households in Tokyo and Osaka prefer algorithm-curated meal kits delivered weekly over supermarket aisle browsing. METI standards and consumer preference for sensory freshness drive adoption of HPP-treated chilled formats over frozen alternatives. The Kanto and Kansai metropolitan corridors concentrate domestic manufacturing and direct-to-door logistics infrastructure.
Ready to Cook Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers reconfigure blast freezing and retort sterilization assets around regional cold chain maturity. The vendor base stratifies across multinational conglomerates with captive distribution networks, mid-tier co-manufacturers serving private label contracts, and direct-to-consumer specialists building algorithm-driven subscription platforms. Strategic archetypes include scale-driven frozen format producers, meal kit platform operators, and institutional shelf-stable suppliers. M&A activity and vertical integration into cold chain logistics represent the dominant competitive moves as procurement criteria tighten around carbon footprint disclosure and batch traceability.
Among North American packaged food conglomerates, Nestlé, Conagra Brands, and McCain Foods exemplify distinct strategic archetypes. Nestlé represents multinational manufacturing scale across European and Latin American frozen pizza and pasta plants. Conagra Brands anchors retail positioning through legacy frozen and shelf-stable lines distributed through North American supermarket channels. McCain Foods occupies a specialist position in potato-based categories, with proprietary freezing technology serving as a competitive differentiator for texture preservation through reheating cycles.
| Leading Market Players |
|---|
| Nestlé |
| Conagra Brands |
| General Mills |
| Kraft Heinz |
| Tyson Foods |
| Campbell Soup Company |
| Unilever |
| McCain Foods |
| Nomad Foods |
| Others |
Value Chain & Pricing Dynamics
Premium-mid-economy pricing differentiation across frozen, chilled, and shelf-stable formats feeds directly into divergent supply chain footprints, with blast freezing infrastructure anchoring premium tier margins in India and Brazil while retort sterilization networks serve ambient distribution at compressed returns.
Pricing Analysis
Input-cost pass-through from natural gas compression cycles and cryogenic tunnel operations is intensifying margin pressure on frozen format producers, particularly across European and Asian manufacturing clusters. Three-tier pricing structure across premium HPP-treated chilled, standard blast-frozen, and economy retort-sterilized levels separates sensory fidelity from storage convenience. Cost compression in the frozen tier is accelerating due to cold chain fragmentation in tier-two Indian cities and Indonesian archipelago logistics. Institutional cafeterias exhibit highest price sensitivity, while direct-to-consumer meal kit subscribers absorb premium positioning for algorithm-curated personalization.
Supply Chain Analysis
Direct-to-restaurant channels handle commercial kitchen demand through chilled and shelf-stable formats, while direct-to-consumer platforms manage meal kit subscription logistics. Manufacturing concentrates in India, Brazil, and Germany, with cold storage expansion under India's PLI scheme reducing spoilage rates in metropolitan corridors. Raw material dependencies center on cryogenic gases, specialized packaging films, and temperature-controlled transport assets. Single-source vulnerability in qualified HACCP auditor availability delays plant approvals for regional expansion beyond Mumbai, Delhi, and Bangalore. Distribution runs through supermarket center-store frozen aisles, online subscription platforms, and institutional procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in premium chilled formats and direct-to-consumer meal kit platforms, driven by algorithm-curated personalization that commands pricing power above commodity frozen alternatives.
For Market Incumbents: Cement category ownership in potato-based and grain-heavy segments through proprietary freezing technology that preserves texture through reheating cycles. Invest in captive cold chain logistics to offset natural gas price volatility and reduce third-party transport margin leakage. Counter direct-to-consumer subscription threats by building in-house digital commerce capabilities or acquiring algorithm-driven platform specialists. For New Entrants and Emerging Players: Underpenetrated urban households in Brazil's northeast corridor from Recife to Fortaleza offer immediate white-space opportunity given rising disposable incomes and working female participation rates without commensurate frozen ready to cook availability. Target FSSAI-compliant low-sodium reformulations for first-mover positioning in India's mandatory front-of-pack labeling environment. Launch through direct-to-door subscription models to bypass supermarket slotting fee barriers and capture household engagement data. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier co-manufacturers possessing FSMA-compliant batch traceability systems and regional cold chain partnerships in underpenetrated Indian tier-two cities. Long-term viability over the analysis window favors specialists with algorithm-curated meal kit platforms and HPP-treated chilled format capabilities. Watch FSSAI enforcement patterns and PLI scheme cold storage disbursement velocity as inflection indicators for regional penetration feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cold Chain Logistics | Captive transport assets reduce exposure to natural gas price volatility across European and Asian corridors. |
| Meal Kit Platform Acquisition | Algorithm-curated subscription models displace supermarket center-store browsing among young urban households. |
| HPP Technology Licensing | High-pressure processing extends chilled shelf life from seven to forty-five days for German and Japanese premium retailers. |
| FSSAI Compliance Certification | Mandatory front-of-pack labeling favors reformulated low-sodium variants for first-mover domestic positioning. |
| PLI Scheme Cold Storage Partnership | India's Production Linked Incentive infrastructure expansion reduces spoilage rates in tier-one metropolitan distribution. |
Study Parameters
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combined with secondary validation. Interviews with frozen food manufacturing executives, cold chain logistics operators, supermarket category buyers, FSSAI compliance consultants, and restaurant procurement directors informed demand-side and supply-side dynamics. Secondary sources include FDA FSMA guidance documents, FSSAI additive limit notifications, EU CSRD disclosure frameworks, PLI scheme administrative data, and customs records for cryogenic equipment imports. Bottom-up segment sizing triangulates against top-down macroeconomic consumption patterns.
Granularity-level modeling disaggregates volume and value across product type, ingredient type, distribution channel, and end user dimensions, with additional segmentation by regional cold chain maturity tiers. CAGRs derive from fitted trend analysis incorporating urban household formation rates, working female labor force participation, and cold storage capacity expansion schedules. Industry-specific forecast inputs include natural gas price trajectories for blast freezing economics and meal kit subscription churn rates by metropolitan density.
Inputs from regulatory filing databases and cold chain infrastructure project registries were available through the study window; gaps in real-time HACCP auditor availability data introduce uncertainty bands around Indian regional expansion timelines. Forecasts reflect documented assumptions regarding PLI scheme disbursement velocity and FSSAI enforcement intensity. Periodic stress-testing of base assumptions is recommended given commodity price volatility and evolving front-of-pack labeling obligations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Broth Market
Processed Foods
Low Fat Vegetable Soups Market
Processed Foods
Global Malted Milk Market
Processed Foods
Margarine Market
Processed Foods
Processed Meat Market
Processed Foods
Fermented Food and Drinks Market
Processed Foods
Pates Market
Processed Foods
Low Fat Puddings Market
Processed Foods
Middle East and Africa Processed Meat Market
Processed Foods
Chocolate Filling Market
Processed Foods
South America Soup Market
Processed Foods
Potato Soup Market
Processed Foods
Spray Cheese Market
Processed Foods
Europe Soup Market
Processed Foods
Asia-Pacific Soup Market
Processed Foods
Casual Marinated Products Market