
 High-Pressure Processing (HPP) Foods Market | 2026-2036
High-Pressure Processing (HPP) Foods Market Size, Share, and Industry Trends Forecast 2026-2036
High-Pressure Processing (HPP) Foods Market Analysis
Aftermarket service revenue for HPP equipment refurbishment and spare-part logistics is tilting margin pools away from initial system sales toward recurring lifecycle income. Avure Technologies dominates installed-base maintenance contracts across North American juice processors. Hormel Foods leverages captive HPP lines to sustain premium positioning in clean-label deli meats. Suja Life anchors California's cold-pressed juice supply chain through direct equipment partnerships and co-manufacturing arrangements.
High-Pressure Processing applies isostatic pressure between 400 and 600 MPa to packaged food products, inactivating vegetative pathogens and spoilage organisms without thermal degradation of vitamins or flavor compounds. The technology preserves food through non-thermal microbial reduction while maintaining fresh-like texture and nutrient profiles. Fruits and juices occupy mature volume positions where private-label penetration has compressed branded margins. Meat and fish applications represent the fastest-expanding product category as processors substitute HPP for traditional thermal pasteurization in ready-to-eat proteins. Preservation and microbial inactivation applications command the largest share of installed capacity, though texture enhancement for plant-based seafood analogs is emerging as a high-margin growth pocket.
The FDA's juice HACCP regulation and USDA-FSIS Listeria control guidelines shape HPP validation requirements for domestic market entry, while the EU's Novel Food Regulation and EFSA processing claims framework govern European commercialization pathways. Equipment manufacturers must navigate divergent pressure-validation protocols between FDA process filings and CE-marked machinery directives. Stakeholders should monitor how FDA guidance on HPP validation for extended shelf-life refrigerated foods evolves relative to competing clean-label preservation technologies.
Market Dynamics
Co-packing infrastructure concentration in California's Central Valley is redistributing margin capture from equipment manufacturers toward toll-processing networks that control regional capacity allocation.
Growth Catalysts
- USDA-FSIS Listeria Control Guidelines:Mandatory pathogen reduction protocols in ready-to-eat meats are accelerating HPP validation for deli and prepared protein categories.
- Plant-based seafood analogs:Texture enhancement applications for mycoprotein and algae-based formulations are opening high-margin processing contracts outside traditional preservation use cases.
- California Central Valley corridor:Dense cold-pressed juice co-packing clusters reduce per-unit processing costs through shared high-pressure line utilization.
Market Restraints
- Stainless steel and ultra-high-pressure vessel alloy inputs:Volatility in specialty metallurgy prices compresses equipment margin predictability for system fabricators.
- Avure Technologies' installed-base dominance:Concentrated aftermarket service contracts across North American juice processors create switching friction for competing equipment vendors.
- EU Novel Food Regulation pathway complexity:Divergent EFSA processing claims validation timelines delay European commercialization relative to FDA process filing routes.
Strategic Opportunities
- Extended shelf-life refrigerated foods:FDA guidance evolution on HPP validation for 45-90 day chilled distribution windows targets gaps left by competing clean-label preservation technologies.
- Meal kit direct partnerships:Subscription protein providers are bypassing traditional retail distribution through captive toll-processing agreements with regional HPP facilities.
- ISO 22000 and FSSC 22000 convergence:Unified food safety management certification is reducing dual-audit burdens for exporters serving multiple regulatory jurisdictions.
Industry Challenges
- High-pressure process engineering specialization:Scarce technician pools for 600 MPa system maintenance and pressure-validation protocol execution constrain facility expansion timelines.
- Legacy thermal pasteurization line retrofit integration:Cold-chain infrastructure reconfiguration creates capital allocation conflicts for mid-scale processors with depreciated steam tunnel assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Pressure Processing (HPP) Foods Market |
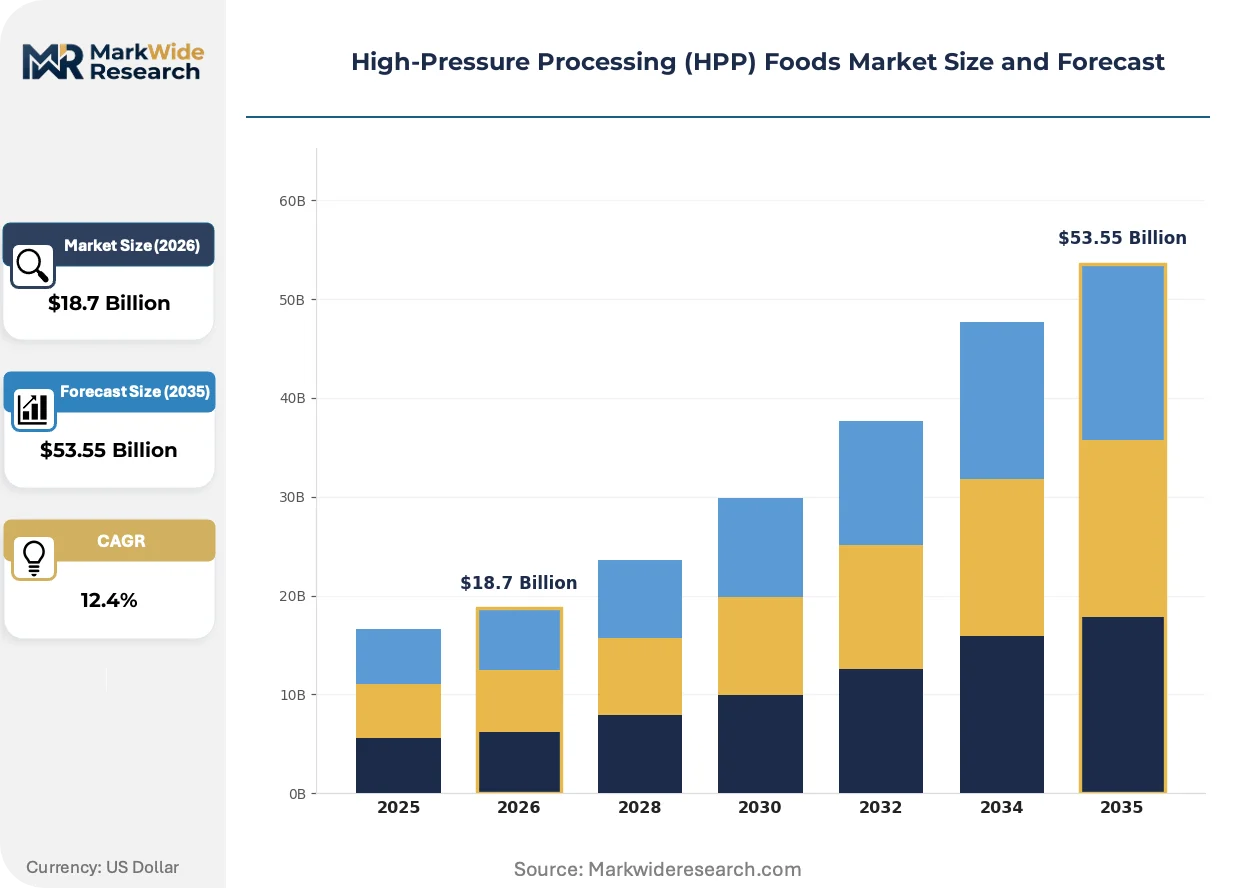
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $53.55 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Juices, Meat, Fish Application: Preservation, Microbial Inactivation, Texture Enhancement, Flavor Retention End User: Food Manufacturers, Restaurants, Retailers, Meal Prep Services Packaging Type: Flexible Packaging, Rigid Containers, Vacuum Packs, Tray Sealing |
| Companies Covered | Suja Life, Avure Technologies, Hormel Foods, Evolution Fresh, Clearwater Seafoods, Cargill, American Pasteurization Company, Universal Pasteurization Company, Hain Celestial Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Pressure Processing (HPP) Foods Market Emerging Trajectories
Equipment functionality is bifurcating between dedicated preservation systems and multi-purpose platforms that enable texture modification, with regulatory validation protocols struggling to keep pace with application expansion.
Ultra-high-pressure homogenization is hybridizing with traditional isostatic HPP in hybrid systems that simultaneously reduce particle size and inactivate pathogens. Plant-based dairy processors in the Northeast US are piloting these dual-function lines for oat and almond milk applications. The convergence is compressing capital requirements for entrants that would otherwise need separate emulsification and pasteurization equipment.
EFSA's updated processing claims framework is tightening evidentiary standards for non-thermal microbial reduction assertions in novel food categories. European juice and ready-to-eat salad processors face extended validation timelines as the agency demands challenge-study protocols beyond current FDA juice HACCP equivalency. German and Dutch co-packers are responding by front-loading clinical trial investments to secure first-mover positioning in refrigerated plant-based convenience foods.
Aftermarket service unbundling is fragmenting traditional equipment vendor revenue models. North American protein processors are negotiating à-la-carte maintenance contracts that separate pressure-vessel inspection, seal replacement, and control-system calibration into discrete purchasing events. California's cold-pressed juice networks exhibit the most advanced unbundling, with toll processors maintaining independent spare-part inventories to minimize OEM dependency.
High-Pressure Processing (HPP) Foods Market Segmentation
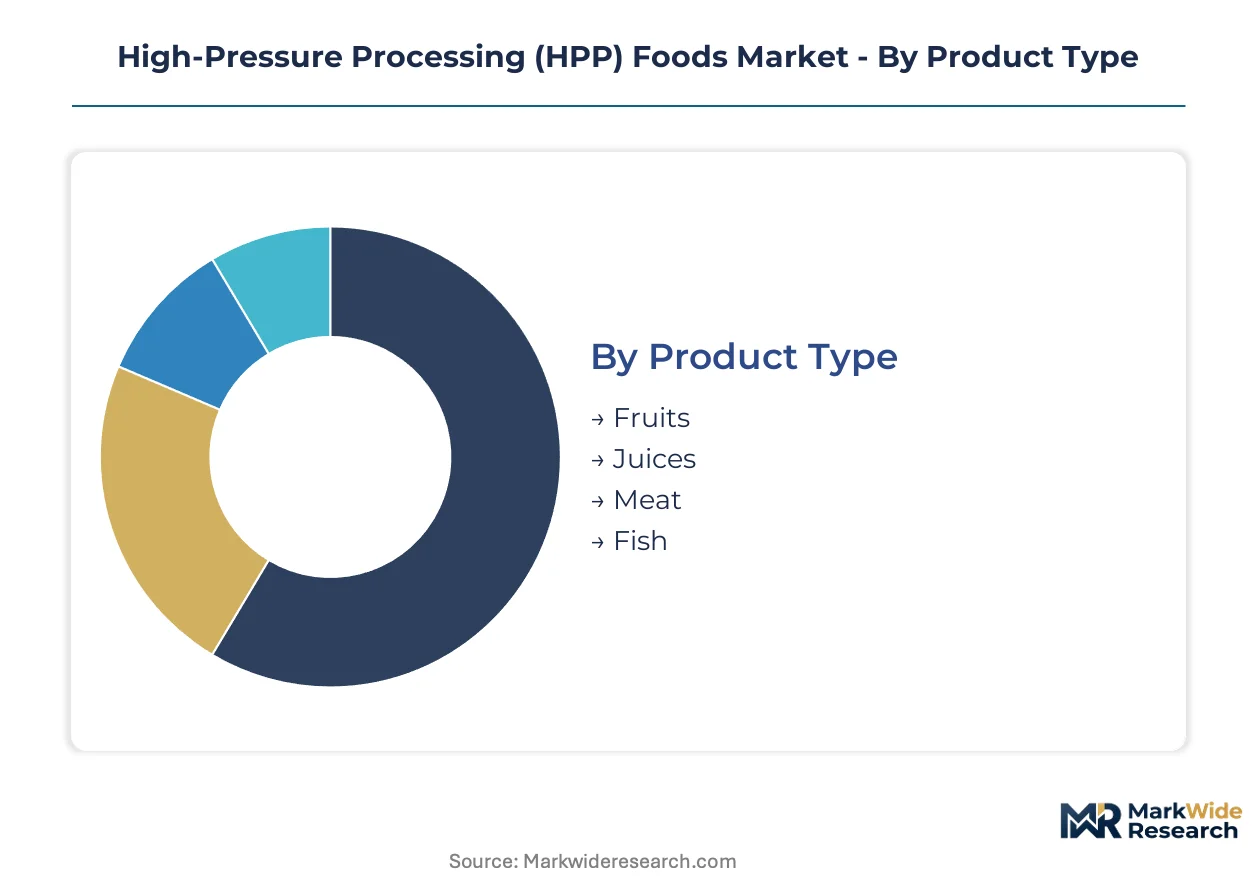
HPP technology serves divergent commercial cycles across food categories. Segmentation reveals where equipment utilization rates peak and where co-packing infrastructure concentrates margin capture.
Product Type:
Fruits and juices turn inventory fastest through California's cold-pressed co-packing networks, while meat and fish applications extend production cycles through USDA-FSIS validation protocols.
- Fruits:Mature category dominated by private-label compression in refrigerated produce sections. California Central Valley processors run near-continuous HPP lines for sliced and whole-fruit convenience packs.
- Juices:Cold-pressed formulations anchor the highest per-unit processing volumes. FDA juice HACCP compliance requirements have standardized validation protocols, reducing regulatory friction for new entrants in Florida and Texas markets.
- Meat:Ready-to-eat deli proteins and value-added cuts represent the steepest expansion trajectory. Hormel Foods and regional processors substitute HPP for thermal pasteurization to sustain clean-label positioning in premium retail channels.
- Fish:Smoked and marinated seafood applications concentrate in Pacific Northwest processing facilities. Extended shelf-life validation for refrigerated distribution remains the primary adoption constraint.
Juices anchor the volume base while meat gains share at the steepest rate.
Application:
Cost tier separation distinguishes commodity preservation from high-margin functional modifications that command premium toll-processing fees.
- Preservation:Dominates installed capacity utilization across North American facilities. Non-thermal shelf-life extension for refrigerated distribution commands standardized per-unit pricing in mature juice and fruit categories.
- Microbial Inactivation:Pathogen reduction protocols for Listeria and E. coli drive regulatory compliance investments. USDA-FSIS guidelines mandate validation for ready-to-eat meat processors.
- Texture Enhancement:Emerging high-margin application for plant-based seafood analogs. Mycoprotein and algae-based formulations in Northeast US pilot facilities utilize HPP for gelation and mouthfeel modification.
- Flavor Retention:Secondary benefit across all thermal-sensitive applications. Vitamin and volatile compound preservation supports premium positioning in cold-pressed juice and fresh-cut produce segments.
Preservation commands the deepest installed base while texture enhancement climbs the fastest as equipment vendors develop multi-purpose platform configurations.
End User:
Customer type determines contract structure, with captive in-house lines diverging from toll-processing arrangements on capital commitment and margin retention.
- Food Manufacturers:Largest equipment purchaser category. Hormel Foods and similar integrated processors deploy captive HPP lines to protect proprietary formulations and capture full margin on premium clean-label products.
- Restaurants:Limited direct adoption concentrated in high-volume prepared-food commissaries. Central kitchen operations for regional chains represent the primary addressable subset.
- Retailers:Private-label juice and prepared protein programs drive toll-processing contracts. Costco and similar operators source through California co-packing networks rather than direct equipment investment.
- Meal Prep Services:Subscription protein providers bypass traditional retail through direct partnerships with regional HPP facilities. Extended shelf-life validation supports 45-90 day chilled distribution windows.
Food manufacturers retain the deepest equipment ownership while meal prep services expand most quickly through outsourced processing agreements.
Packaging Type:
Supply concentration in flexible film extrusion shapes equipment compatibility requirements and limits format innovation for rigid container applications.
- Flexible Packaging:Dominates cold-pressed juice and sliced fruit applications. Stand-up pouches and film structures withstand isostatic pressure cycles while minimizing freight cube.
- Rigid Containers:Limited to high-value seafood and premium meat formats where structural integrity post-processing supports retail presentation. Higher per-unit packaging costs constrain adoption.
- Vacuum Packs:Standard for deli meat and fish portions. Modified atmosphere compatibility extends shelf-life gains from HPP microbial reduction.
- Tray Sealing:Emerging format for meal kit protein components. Lidding film specifications must balance pressure resistance with consumer peelability.
Flexible packaging holds the volume base while tray sealing gains share fastest as meal kit format requirements reshape packaging specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication clusters in Germany and the United States supply the majority of installed HPP capacity, while toll-processing networks in California and the Netherlands concentrate commercial utilization. Regulatory divergence between FDA juice HACCP pathways and EFSA processing claims frameworks shapes regional entry strategies.
United States
Ready-to-eat protein processors and cold-pressed juice co-packers drive equipment demand across California's Central Valley and the Pacific Northwest. FDA enforcement of updated juice HACCP regulations validates non-thermal pasteurization for extended shelf-life distribution. Fresno and Modesto host dense clusters of shared high-pressure lines serving private-label retailers and meal kit providers.
Germany
Precision engineering fabricators supply ultra-high-pressure vessel systems to European and export markets. EFSA's tightening evidentiary standards for non-thermal microbial reduction claims extend validation timelines for novel food categories. Bavaria's industrial machinery corridor anchors equipment manufacturing, with Stuttgart-area specialists developing multi-purpose platform configurations.
Netherlands
Plant-based seafood analog developers pilot texture enhancement applications for mycoprotein and algae-based formulations. REACH compliance and CE-marked machinery directives govern equipment import and commercial processing authorization. Wageningen-area food technology clusters integrate HPP validation with alternative protein R&D pipelines.
Canada
Pacific Northwest seafood processors adopt HPP for smoked and marinated fish shelf-life extension. Health Canada and PMRA coordinate food safety oversight with USDA-FSIS equivalency agreements for cross-border protein trade. British Columbia facilities concentrate on high-value refrigerated distribution to US West Coast markets.
Spain
Traditional cured meat producers evaluate HPP substitution for thermal pasteurization in premium export categories. Spanish Agency for Food Safety and Nutrition (AESAN) implements EU Novel Food Regulation pathways with EFSA-aligned processing claims requirements. Catalonia's food manufacturing belt experiments with clean-label preservation for Mediterranean diet-positioned products.
High-Pressure Processing (HPP) Foods Market Vendor Landscape
Integrated food manufacturers and specialized equipment fabricators split the market into captive processing and toll-service domains. Three archetypes dominate: engineering-heavy system vendors with installed-base service contracts, diversified protein processors deploying proprietary HPP lines, and regional co-packing networks controlling capacity allocation. Competitive moves center on aftermarket service unbundling and geographic expansion of toll-processing footprints.
Within the equipment tier, Avure Technologies anchors North American aftermarket service relationships across juice processing facilities. Suja Life and Hormel Foods exemplify divergent captive strategies—Suja Life through direct equipment partnerships and California co-manufacturing arrangements, Hormel Foods through in-house HPP lines protecting premium deli meat positioning. These three entities represent the spectrum from pure-play toll processor to vertically integrated food manufacturer.
| Leading Market Players |
|---|
| Suja Life |
| Avure Technologies |
| Hormel Foods |
| Evolution Fresh |
| Clearwater Seafoods |
| Cargill |
| American Pasteurization Company |
| Universal Pasteurization Company |
| Hain Celestial Group |
| Others |
Supply Flow & Price Mechanics
California's Central Valley freight corridor governs cold-chain logistics costs for HPP-processed goods, compressing per-unit economics as co-packing density rises while simultaneously enabling premium pricing tiers for processors with USDA-FSIS-validated lines.
Pricing Analysis
FDA juice HACCP dictates the pricing tier structure across HPP toll-processing networks. Three-tier pricing structure across premium, standard, and economy levels separates USDA-validated protein processors from commodity juice co-packers and unbranded private-label operators. Price differentiation hinges on certification grade and volume scale, with meal kit providers commanding preferential rates through captive offtake commitments. Pricing pressure stems from stainless steel alloy volatility squeezing equipment fabricator margins. Private-label retailers exhibit highest price sensitivity, while integrated food manufacturers like Hormel Foods demonstrate lowest sensitivity through captive line ownership.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates ultra-high-pressure vessel sourcing strategies. Equipment fabrication concentrates in Germany, the United States, and China, with specialty alloy inputs drawing from Swedish and Japanese metallurgy suppliers. Supply chain risk centers on single-source vulnerability for 600 MPa pressure vessel forgings. Distribution runs through regional co-packing hubs in California, the Netherlands, and Canada's Pacific Northwest, with cold-chain integrity requirements limiting direct-to-processor shipment models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HPP incumbents face substitution pressure from emerging clean-label preservation technologies including high-pressure thermal sterilization and advanced modified atmosphere packaging systems that threaten to erode non-thermal pasteurization's shelf-life advantages.
For Market Incumbents: Build installed-base service moats through unbundled aftermarket contracts that separate pressure-vessel inspection, seal replacement, and control-system calibration into discrete recurring revenue streams. Defend against emerging equipment vendors by locking California juice processors into multi-year maintenance agreements. Anchor capacity addition in the Central Valley corridor to capture meal kit provider offtake growth. Invest in ISO 22000 certification to reduce dual-audit burdens for export markets. For New Entrants and Emerging Players: Pursue texture enhancement applications for plant-based seafood analogs in Northeast US pilot facilities, where mycoprotein and algae-based formulations command premium toll-processing fees with limited incumbent competition. Target the meal prep services segment through direct partnerships with regional HPP facilities, bypassing traditional retail distribution. White-space exists in tray-sealing format development for protein components, where lidding film specifications remain underdeveloped. For Investors and Strategic Acquirers: Regional co-packing networks with captive Central Valley capacity represent the most defensible acquisition archetype, given their control over toll-processing allocation and established FDA validation protocols. Long-term viability hinges on HPP's sustained cost advantage over thermal pasteurization for clean-label positioning. Monitor FDA guidance evolution on extended shelf-life refrigerated foods as the inflection signal for 45-90 day chilled distribution window expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Aftermarket Service Unbundling | Avure Technologies captures recurring revenue through separated maintenance contracts across North American juice processors. |
| Multi-Purpose Platform Development | German fabricators in Stuttgart integrate texture modification with preservation functions for plant-based analog applications. |
| Co-Packing Network Expansion | California Central Valley density reduces per-unit processing costs through shared high-pressure line utilization. |
| Regulatory Certification Investment | ISO 22000 and FSSC 22000 convergence reduces dual-audit burdens for exporters serving FDA and EFSA jurisdictions. |
| Meal Kit Direct Partnership | Subscription protein providers bypass traditional retail through captive toll-processing agreements with regional HPP facilities. |
Methodological Framework
The analysis maps HPP equipment fabrication, toll-processing services, and end-use food manufacturing, each validated through equipment vendor executives, co-packing facility operators, and food manufacturer procurement leads. Primary interviews with aftermarket service heads and regulatory affairs specialists at USDA-FSIS-aligned processors combined with secondary validation from FDA juice HACCP filings, EFSA processing claims databases, and SEC 10-K equipment manufacturer disclosures. Bottom-up toll-processing volume estimates triangulated against top-down equipment installation data.
Assumptions held fixed include regulatory validation timelines for novel food categories and stainless steel alloy price volatility bands, while variables included meal kit provider adoption rates and plant-based seafood analog commercialization pace. Segmentation modeling spanned product type, application, end user, and packaging format dimensions across the projection horizon. CAGRs derived from equipment shipment data cross-referenced with co-packing utilization rates and protein processor substitution curves for thermal pasteurization displacement.
Sensitivities concentrate around FDA guidance evolution on extended shelf-life validation and EFSA processing claims framework tightening for non-thermal microbial reduction assertions. Forecasts reflect assumptions on regulatory pathway convergence and alloy input cost stabilization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Pizza Market
Processed Foods
China Freeze-Dried Food Market
Processed Foods
Processed Cashew Market
Processed Foods
United States Ice Cream Market
Processed Foods
Ready-To-Whip Toppings Market
Processed Foods
Europe Soup Market
Processed Foods
Fruit Processing Market
Processed Foods
Low Fat Vegetable Soups Market
Processed Foods
Coffee Creamer Market
Processed Foods
Asia-Pacific Soup Market
Processed Foods
South America Soup Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
Block Margarine Market
Processed Foods
Asia-Pacific Ice Cream Market
Processed Foods
Broth Market
Processed Foods
Low Fat Puddings Market