
 Global Pasta Market | 2026-2036
Global Pasta Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pasta Market Outlook
Chickpea flour is rebalancing cost structures across the premium pasta tier as protein-fortified alternatives command shelf-space premiums. Barilla Group leverages its vertically integrated durum wheat supply to sustain margin control across European retail channels. De Cecco anchors its position through bronze-die extrusion specialization, while Banza Inc. competes on legume-based formulations that occupy the allergen-free segment in North American grocery.
Pasta denotes an unleavened dough product manufactured from durum wheat semolina or alternative flours, extruded or laminated into defined shapes, then dried to moisture levels below 12.5 percent for shelf stability; its commercial purpose centers on providing a neutral, carbohydrate-dense substrate for prepared meals across retail and foodservice channels. Spaghetti maintains volume leadership in household purchases through familiar preparation protocols, while vacuum pack formats capture margin pools in premium retail by extending shelf life without preservatives. Restaurants and cafés represent the fastest-growing customer type as operators seek consistent cook times and portion control in high-throughput kitchens.
EU F-Gas Regulation constrains refrigeration-dependent drying technologies, pushing Italian and Spanish manufacturers toward ambient-air tunnel retrofits. FDA gluten-labeling standards and USDA organic certification shape product claims and market access for US-bound shipments. Stakeholders must monitor durum wheat price volatility against legume-flour substitution economics as climate patterns shift cultivation geography.
Market Dynamics
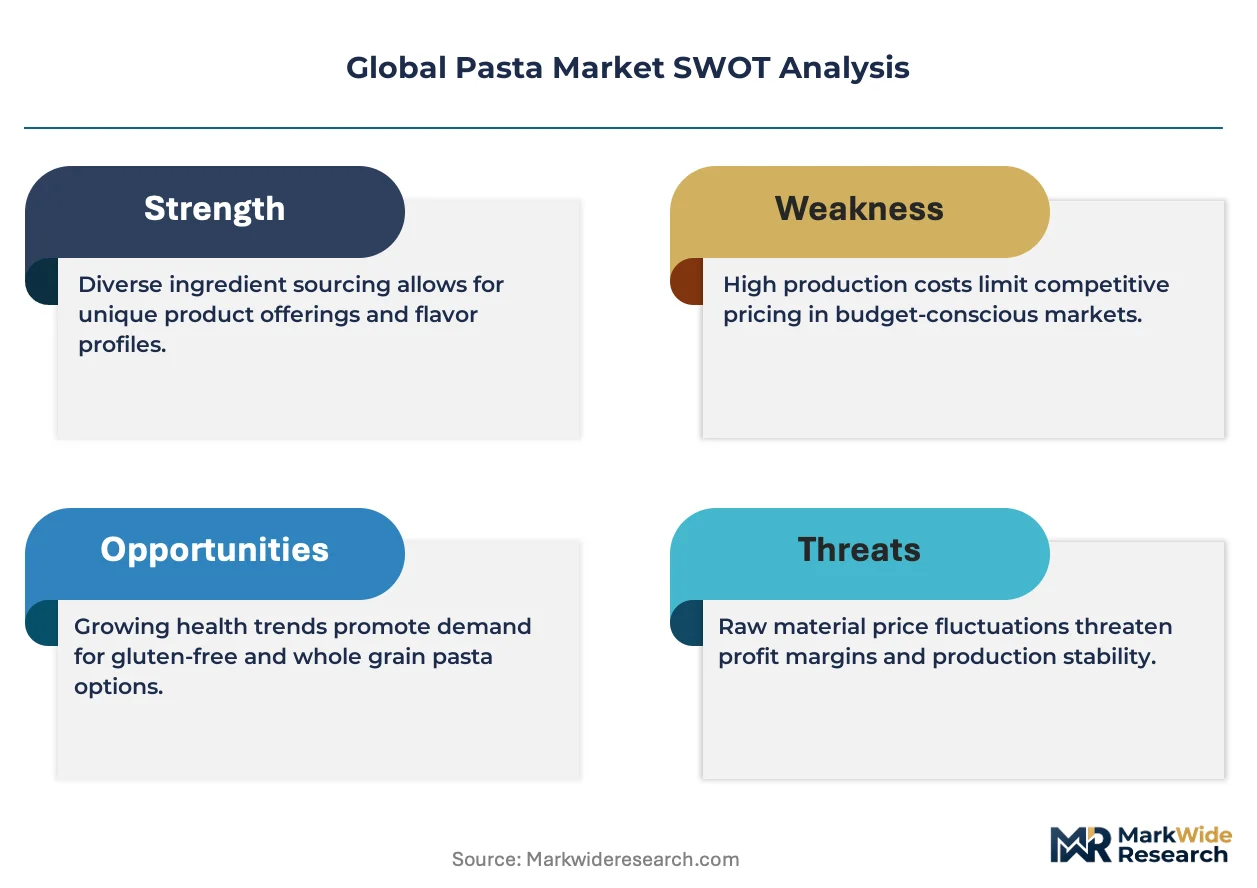
The legume-flour substitution wave is restructuring input sourcing economics across pasta manufacturing, compressing traditional durum wheat dependency while creating parallel supply chains for chickpea, lentil, and fava bean derivatives.
Growth Catalysts
- EU F-Gas Regulation:Equipment retrofit mandates in Italy and Spain are accelerating ambient-air tunnel adoption, reducing energy intensity in durum wheat drying operations and opening margin recovery pathways for mid-scale producers.
- Quick-service restaurant procurement:North American and European foodservice operators are standardizing legume-based pasta SKUs to capture allergen-sensitive traffic and simplify kitchen cross-utilization.
- Chickpea flour processing:Advances in dehulling and micronization are narrowing the cost gap with durum semolina, enabling protein-fortified formulations at mainstream price points.
Market Restraints
- Durum wheat price volatility:Canadian and Australian harvest variability is transmitting cost spikes directly to European millers, compressing margins on standard-grade pasta lines.
- Italian supply concentration:Over half of premium bronze-die capacity clusters in Puglia and Campania, creating geographic vulnerability to climate-driven water stress and labor disruption.
- Legume flour functional limits:Gluten-free alternatives exhibit texture degradation in extended hold applications, constraining penetration into institutional foodservice channels.
Strategic Opportunities
- India urban retail:Modern trade expansion in Mumbai, Delhi, and Bangalore is creating shelf-space for premium imported and domestic pasta brands previously confined to niche import channels.
- USDA organic certification:Certified organic durum wheat commands price premiums in US natural grocery, with supply scarcity creating first-mover advantages for backward-integrated growers.
- Vacuum pack technology:Modified-atmosphere packaging convergence with e-commerce fulfillment is enabling direct-to-consumer premium lines with extended shelf stability and reduced retail dependency.
Industry Challenges
- Bronze-die craftsmanship shortage:Italy's aging specialist workforce threatens artisanal production scaling, with apprenticeship pipelines failing to replace retiring die-makers in Foggia and Gragnano.
- Dual certification complexity:Simultaneous FDA gluten-labeling compliance and EU organic equivalence recognition is extending product launch timelines for cross-Atlantic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pasta Market |
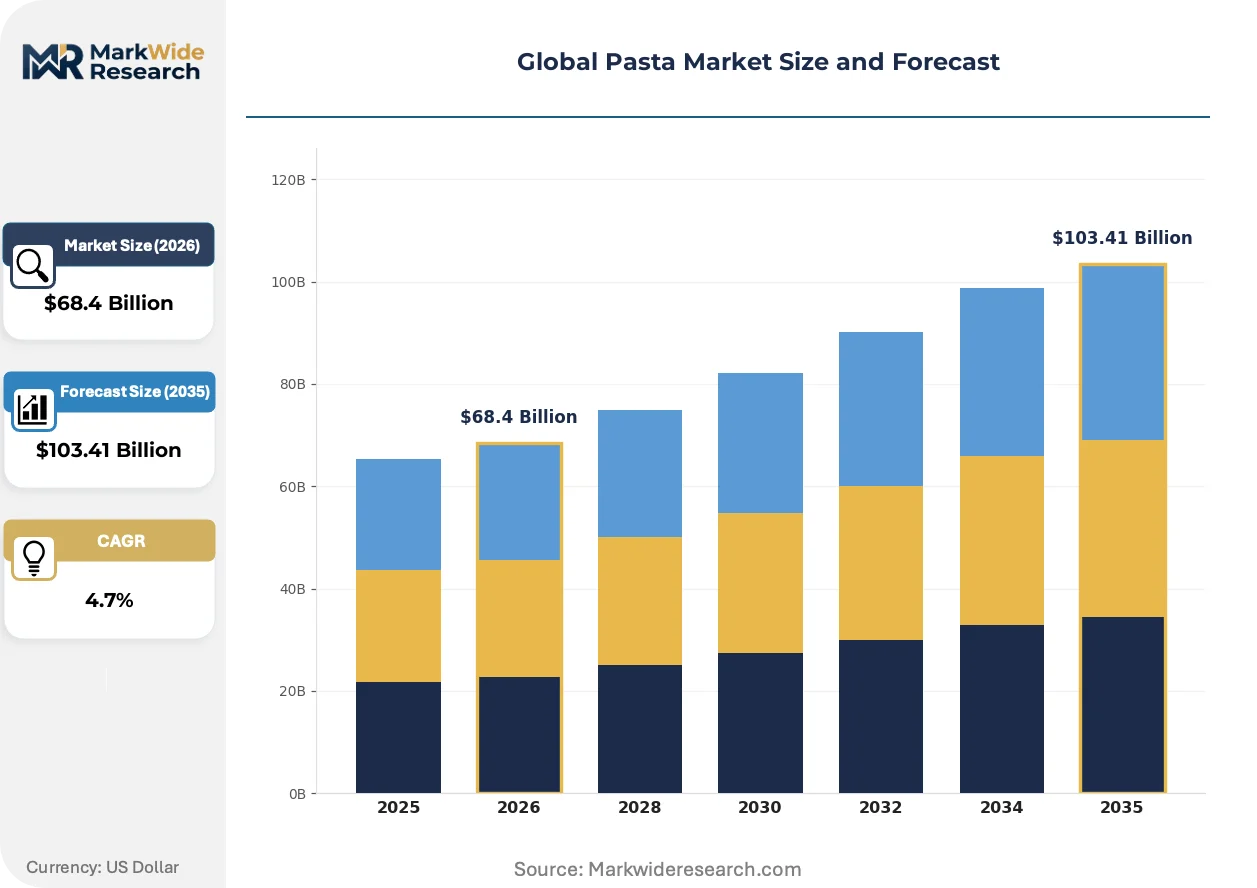
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spaghetti, Penne, Fusilli, Macaroni Customer Type: Households, Restaurants, Cafés, Catering Services Packaging Type: Box, Plastic Bag, Vacuum Pack, Bulk Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale |
| Companies Covered | Nestle, Kraft Heinz Company, Barilla Group, Pasta Zara, La Doria, Ebro Foods, Unilever Group, Banza Inc., De Cecco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pasta Market Strategic Shifts
Processing technology and regulatory compliance requirements are converging to reshape competitive advantage in pasta manufacturing, favoring capital-flexible producers capable of rapid input pivoting.
Extrusion monitoring systems using real-time moisture spectroscopy are decentralizing quality control from centralized lab testing to production-line decision nodes. Mid-scale Italian and Spanish manufacturers are adopting these sensors fastest, cutting batch rejection rates and enabling just-in-time formulation adjustments that compress working capital requirements.
REACH chemical safety pre-registration is forcing European pasta equipment suppliers to reformulate non-stick coatings and lubricants used in extrusion dies. Manufacturers sourcing from German and Italian machinery builders face compliance verification delays, with organic-certified producers most affected due to stricter substance prohibitions in their processing standards.
Foodservice procurement teams are consolidating supplier relationships around full-category pasta providers capable of delivering both traditional wheat and alternative-flour SKUs under single contract terms. This bundling behavior is displacing fragmented sourcing across multiple specialty vendors, with US and UK contract catering operators leading the consolidation pattern.
Global Pasta Market Segmentation
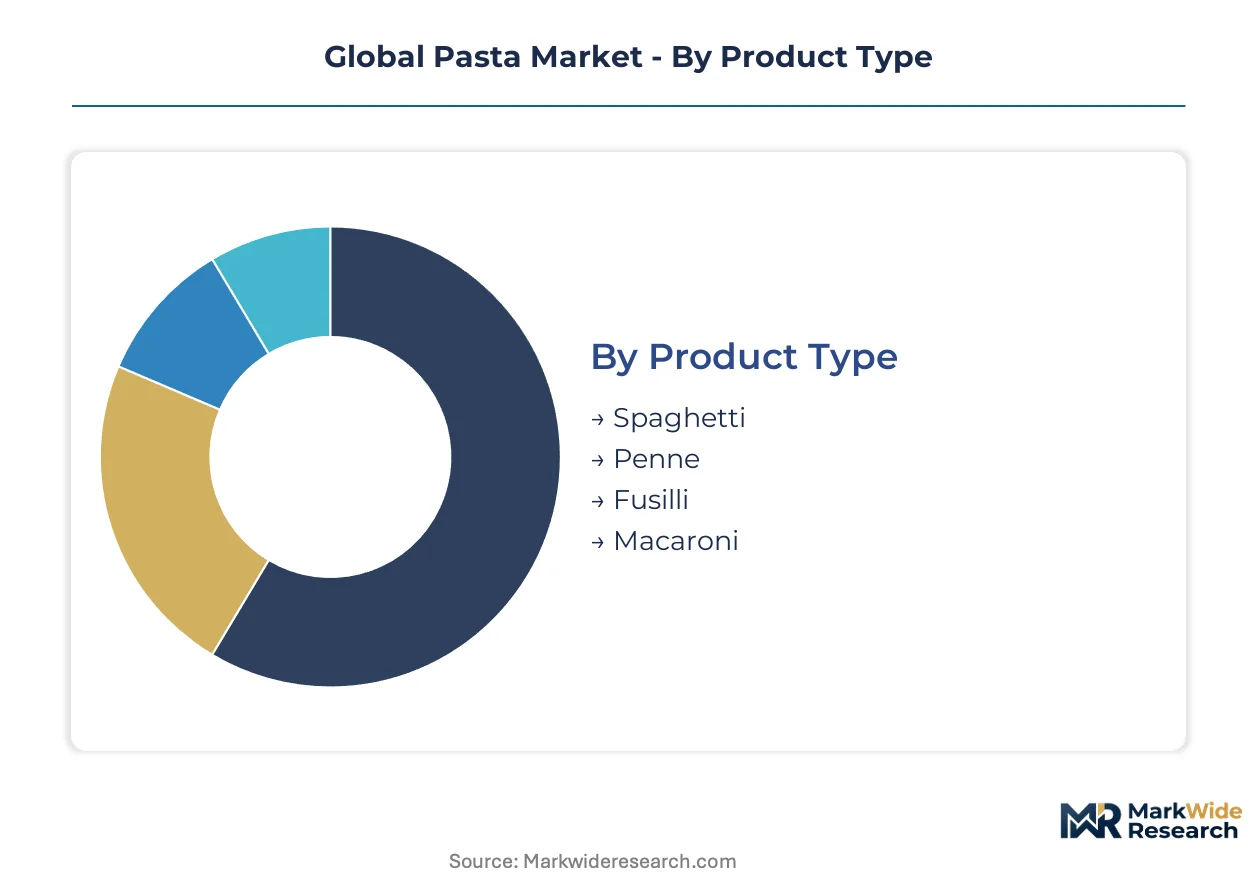
Pasta manufacturers configure production lines around shape-specific die requirements and moisture tolerance thresholds. Segmentation discipline separates commodity volume plays from premium margin capture across retail and foodservice channels.
Product Type:
Production gravity clusters around long-cut extrusion formats where die standardization permits scale economies.
- Spaghetti:Long-cut cylindrical strands extruded through circular dies with 1.5-2.2mm diameter specifications. Households in Italy and the United States absorb the majority of spaghetti volume, driven by familiar preparation protocols and sauce adhesion properties that simplify home cooking.
- Penne:Diagonally cut tubular shapes with ridged or smooth exterior surfaces requiring angled extrusion dies and precision cutting blades. Quick-service restaurants across North America are standardizing penne SKUs for pasta salad and baked applications where portion consistency matters.
- Fusilli:Corkscrew helical shapes produced through rotating die plates that impose spiral deformation on extruded dough. The geometry traps sauce effectively, supporting premium positioning in specialty retail.
- Macaroni:Curved tubular shapes historically dominant in North American casserole applications. Institutional foodservice channels in the United States maintain steady procurement of elbow macaroni for volume feeding operations.
Spaghetti absorbs the bulk of installed capacity; penne is expanding most quickly.
Customer Type:
Demand concentration shifts toward foodservice operators seeking cook-time consistency and cross-utilization flexibility.
- Households:Retail purchasers selecting shelf-stable formats for weekly meal planning. Italian households sustain the highest per-capita consumption rates globally, with pantry stocking patterns favoring 500g-1kg pack sizes.
- Restaurants:Full-service operators requiring al dente tolerance windows of 8-12 minutes for kitchen throughput optimization. Bronze-die extruded shapes command preference for sauce adherence in mid-tier Italian dining across Germany and France.
- Cafés:Limited-service outlets integrating pasta into grab-and-go lunch formats. Australian urban cafés are expanding cold pasta salad offerings, driving demand for short-cut shapes that hold texture under refrigeration.
- Catering Services:Contract feeding operators managing portion control at volume. UK school catering and corporate dining contracts specify 50-70g dry portions with extended hold tolerance requirements.
Households retain the largest volume share; restaurants are climbing the fastest.
Packaging Type:
Packaging selection directly determines shelf-life extension and retail channel access.
- Box:Paperboard cartons with window panels displaying product shape and color. Standard retail placement across European supermarkets depends on box formats that stack efficiently and communicate brand identity.
- Plastic Bag:Polypropylene or polyethylene film with resealable closures. Value-tier positioning in emerging markets relies on plastic bag economics that undercut rigid packaging costs.
- Vacuum Pack:Modified-atmosphere packaging removing oxygen to extend shelf life without preservatives. Premium retail channels in Japan and South Korea favor vacuum packs for imported Italian pasta where distribution cycles run longer.
- Bulk:Unpackaged or large-format sacks for foodservice and industrial processing. Restaurant chains in the United States procure 10-20lb bulk sacks for back-of-house efficiency.
Box formats dominate retail shelf space; vacuum pack is gaining share fastest.
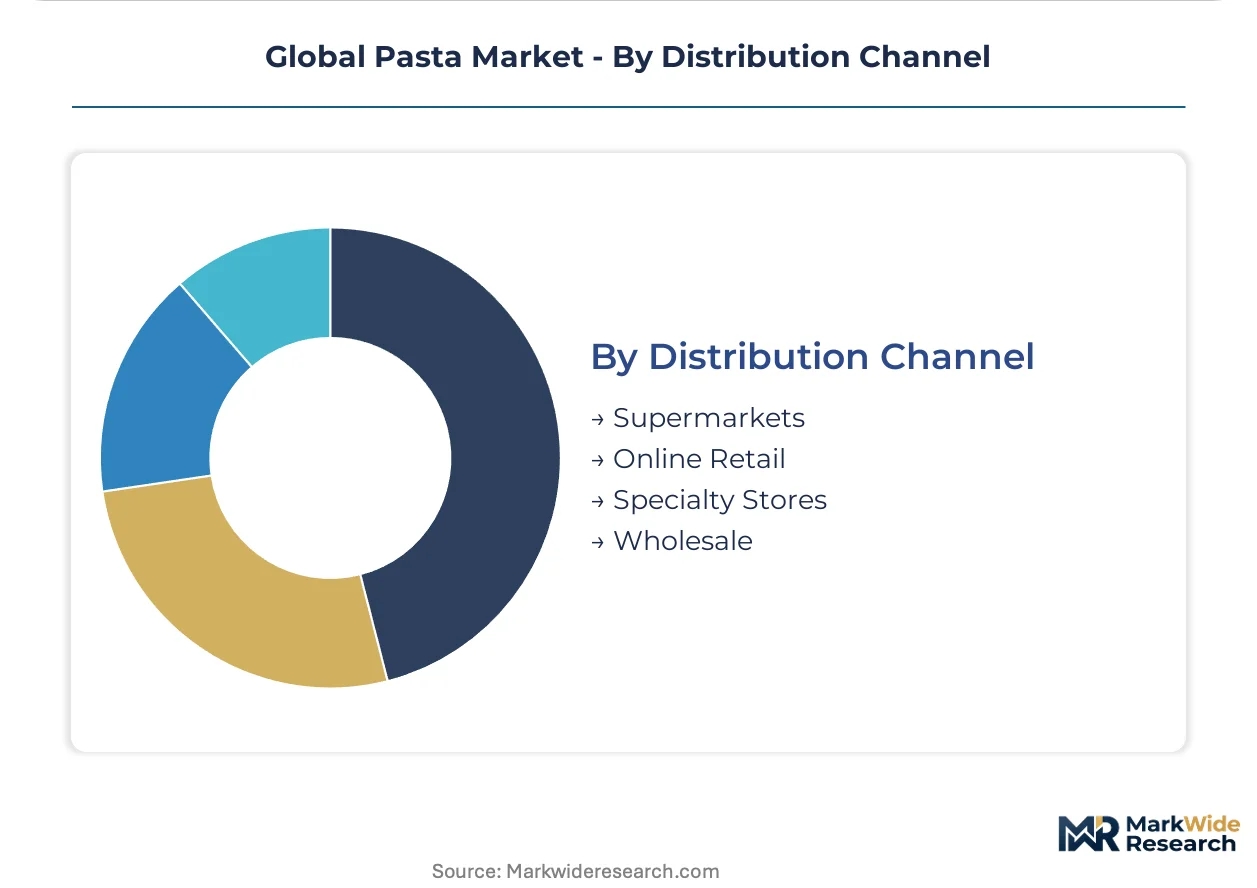
Distribution Channel:
Channel configuration shapes margin capture and brand control intensity.
- Supermarkets:Mass-market retail with category management and promotional slotting fees. Italian supermarket chains Conad and Coop control significant pasta volume through private-label and branded assortment.
- Online Retail:Direct-to-consumer and marketplace platforms with subscription mechanics. Amazon and specialized Italian food importers are expanding online pasta assortment in the United States and United Kingdom.
- Specialty Stores:Gourmet food retailers emphasizing provenance and artisanal credentials. Eataly and regional Italian delis in New York and London curate bronze-die and heritage grain selections.
- Wholesale:Foodservice distributors supplying restaurants and institutional kitchens. Sysco and US Foods in North America, plus Metro AG in Germany, consolidate pasta procurement for multi-unit operators.
Supermarkets command the largest throughput; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian households consume the highest per-capita pasta volumes globally, with demand concentration in Puglia and Campania driving bronze-die artisanal production clusters alongside industrial-scale facilities.
Italy
Domestic consumption absorbs the majority of durum wheat semolina output, with Gragnano and Foggia maintaining heritage bronze-die craftsmanship traditions. The EU F-Gas Regulation mandates ambient-air tunnel retrofits across Campania processing facilities, compressing margins for mid-scale producers. Puglia's water-stressed agricultural belt faces irrigation constraints that threaten durum wheat yield stability.
United States
Quick-service restaurant chains are standardizing legume-based pasta SKUs to capture allergen-sensitive consumer traffic and simplify kitchen cross-utilization. FDA gluten-labeling standards and USDA organic certification requirements shape product claims for retail-bound shipments. North Dakota and Montana durum wheat cultivation supplies domestic millers, though Canadian import dependency persists.
Germany
Retail channels through Conad and Coop equivalents sustain private-label and branded assortment competition, with discounters compressing price points on standard-grade lines. ECHA REACH compliance requirements affect non-stick coating formulations in extrusion equipment sourced from Italian machinery builders. Bavaria hosts processing facilities serving Central European distribution networks.
India
Modern trade expansion in Mumbai, Delhi, and Bangalore creates shelf-space for premium imported and domestic pasta brands previously confined to niche import channels. FSSAI labeling standards and import tariff structures shape market access for Italian exporters. Maharashtra and Gujarat host emerging domestic manufacturing capacity targeting urban retail penetration.
Japan
Vacuum pack formats dominate premium retail channels for imported Italian pasta, where extended distribution cycles favor modified-atmosphere packaging without preservatives. METI food safety standards and JIS packaging specifications govern import compliance. Tokyo and Osaka metropolitan areas concentrate foodservice demand for al dente-tolerant shapes in Italian dining concepts.
Global Pasta Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers balance traditional durum wheat lines against legume-based alternatives. The vendor base stratifies across vertically integrated agricultural holdings, specialized bronze-die artisans, and alternative-flour innovators. Three archetypes prevail: heritage Italian millers with captive wheat supply, North American allergen-free specialists, and diversified FMCG conglomerates leveraging distribution scale. M&A activity and capacity expansion in chickpea flour processing represent the dominant competitive vectors.
Among heritage Italian specialists, De Cecco and Pasta Zara exemplify bronze-die craftsmanship positioning, while Banza Inc. occupies the North American legume-based alternative tier. Barilla Group anchors the scale-driven integrated segment with backward control over durum wheat supply chains.
| Leading Market Players |
|---|
| Nestle |
| Kraft Heinz Company |
| Barilla Group |
| Pasta Zara |
| La Doria |
| Ebro Foods |
| Unilever Group |
| Banza Inc. |
| De Cecco |
| Others |
Value Chain & Pricing Dynamics
Durum wheat semolina costs cascade through three distinct pricing tiers, with Canadian and Australian harvest variability transmitting directly to European millers and compressing margins on standard-grade lines while bronze-die artisanal products in Puglia and Campania sustain premiums through scarcity positioning.
Pricing Analysis
Volume absorbs the bulk of pasta throughput at compressed margins, while vacuum pack and bronze-die formats capture premium pools through extended shelf stability and provenance signaling. Price differentiation rests on certification grade—USDA organic and EU organic equivalence recognition command retail premiums—and die type, with bronze-extruded shapes sustaining double-digit markups over Teflon-die equivalents. Cost compression in standard wheat lines is intensifying because legume-flour substitution economics are narrowing the protein-fortified price gap. Quick-service restaurant procurement teams exhibit highest price sensitivity due to contract catering volume commitments, while Japanese premium retail channels show lowest sensitivity for vacuum pack imports.
Supply Chain Analysis
EU F-Gas Regulation ambient-air tunnel mandates are reshaping Italian and Spanish equipment sourcing, pushing manufacturers toward domestic machinery builders in Bologna and Barcelona to satisfy local-content compliance timelines. Supply concentrates in Italy for bronze-die craftsmanship, Canada and Australia for durum wheat cultivation, and India for emerging chickpea flour processing scale. Raw material dependencies center on durum wheat semolina, legume flour derivatives, and modified-atmosphere packaging films. Single-source vulnerability clusters in Puglia's water-stressed agricultural belt, where irrigation constraints threaten yield stability. Distribution runs through Italian supermarket chains Conad and Coop, North American wholesale distributors Sysco and US Foods, and German retail networks Metro AG.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pasta market sits in a processing technology transition, with real-time moisture spectroscopy and ambient-air tunnel retrofits displacing legacy refrigeration-dependent drying systems across Italian and Spanish manufacturing clusters.
For Market Incumbents: Anchor bronze-die craftsmanship scarcity through apprenticeship pipeline investment in Foggia and Gragnano, countering the aging specialist workforce threat. Secure backward integration into durum wheat supply through long-term offtake agreements with Canadian and Australian growers, insulating margin compression from harvest volatility. Prioritize dual certification investment for simultaneous FDA gluten-labeling and EU organic equivalence to compress cross-Atlantic product launch timelines.
For New Entrants and Emerging Players: Capture shelf-space in Mumbai, Delhi, and Bangalore modern trade channels where FSSAI labeling compliance creates first-mover structural advantages over established Italian exporters. Target the North American allergen-free segment through legume-based formulation specialization, competing on kitchen cross-utilization simplicity for quick-service restaurant procurement teams. Deploy direct-to-consumer subscription mechanics via Amazon and specialized import platforms to bypass retail slotting fee barriers.
For Investors and Strategic Acquirers: Chickpea flour processing capacity expansion announcements are the leading indicator that protein-fortified substitution economics have reached mainstream viability, signaling acquisition timing for alternative-flour innovators. Frame long-term viability around the 5-10 year horizon through portfolio diversification capability—targets must demonstrate rapid input pivoting between durum wheat and legume derivatives. Monitor EU F-Gas Regulation compliance cost disclosures from mid-scale Campania producers as the inflection signal for distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Durum Wheat Supply | Captive semolina sourcing from Canadian prairie cultivation insulates Barilla Group from harvest volatility transmission. |
| Ambient-Air Tunnel Equipment Retrofit | Campania manufacturers adopting Bologna-built machinery satisfy EU F-Gas Regulation mandates while recovering energy cost margins. |
| Chickpea Flour Processing Scale-Up | Maharashtra and Gujarat milling capacity targets urban Indian retail penetration previously confined to niche import channels. |
| Vacuum Pack Technology Deployment | Modified-atmosphere packaging convergence with Amazon fulfillment enables De Cecco direct-to-consumer premium lines. |
| Bronze-Die Craftsmanship Apprenticeship Pipeline | Foggia and Gragnano workforce development counters aging specialist retirement threatening artisanal production scaling. |
Study Parameters
Independent corroboration across pasta manufacturing executives, quick-service restaurant procurement directors, Italian machinery builder technical leads, and retail category buyers underwrites the qualitative findings in this study. Primary fieldwork combined structured interviews with secondary validation through customs records, EU F-Gas Regulation compliance filings, and FSSAI import registration databases. Bottom-up triangulation across product type, customer channel, and packaging format segmentation converged with top-down macroeconomic anchoring.
Rate-of-change decomposition across the analysis window separated volume growth drivers from value capture mechanisms, with segmentation dimensions spanning product type, customer type, packaging format, and distribution channel. CAGRs were derived through iterative convergence of historical trajectory analysis and forward-looking regulatory impact assessment. Industry-specific forecast inputs incorporated durum wheat price volatility scenarios and legume-flour substitution elasticity parameters.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to climate-driven cultivation geography shifts and EU organic equivalence recognition timelines. Projections reflect assumptions around ambient-air tunnel adoption rates and FSSAI labeling standardization pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Processed Cashew Market
Processed Foods
Processed Mango Products Market
Processed Foods
Mashed Potatoes Market
Processed Foods
Porridge Market
Processed Foods
Coffee Creamer Market
Processed Foods
South America Soup Market
Processed Foods
Global Take Out Fried Chicken Market
Processed Foods
Processed Fruit Bases Market
Processed Foods
South America Processed Meat Market
Processed Foods
Ice Cream Parlor Market
Processed Foods
Tomato Puree Market
Processed Foods
Low Fat Pasta Market
Processed Foods
India Spray Dried Food Market
Processed Foods
Instant Curry Market
Processed Foods
Industrial Margarine Market
Processed Foods
Fermented Foods Market