
 Chilled Soup Market | 2026-2036
Chilled Soup Market Size, Share, and Industry Trends Forecast 2026-2036
Chilled Soup Market Analysis
EU Green Deal packaging mandates is recalibrating the cost-of-entry calculus for chilled soup producers entering European retail. Campbell Soup Company leverages its North American manufacturing scale to sustain refrigerated logistics advantages. Nestlé S.A. anchors its portfolio through R&D intensity in clean-label preservation technologies. Soupologie differentiates via plant-forward formulations that compete on ingredient transparency rather than price alone.
Chilled soup denotes ready-to-eat soup products maintained at refrigerated temperatures, typically processed through high-pressure processing or mild thermal treatment to preserve flavor compounds and extend shelf life without freezing. The primary commercial purpose centers on delivering convenience-oriented meal solutions that balance freshness claims with extended retail distribution windows. Vegetable and gazpacho varieties occupy margin-rich positions as Mediterranean flavor profiles gain traction in premium retail channels. Tetra Packs and pouches lead packaging growth by reducing cold-chain energy intensity relative to rigid containers, while supermarkets and online stores dominate distribution as home-delivery chilled logistics mature.
FDA oversight of refrigerated food safety standards and USDA organic certification requirements shape product development pathways and label claims in the United States. EFSA nutritional profiling rules and EU F-Gas Regulation cold-chain constraints influence formulation and refrigeration infrastructure decisions across European markets. Stakeholders must monitor evolving extended producer responsibility frameworks that will dictate packaging material transitions and reverse logistics obligations.
Market Dynamics
The EU Green Deal's extended producer responsibility mandates are forcing chilled soup manufacturers to abandon rigid plastic containers. Cold-chain energy costs and packaging material transitions now dominate capital allocation decisions across production networks.
Growth Catalysts
- High-pressure processing (HPP):This non-thermal preservation technology extends shelf life without flavor degradation. Retail buyers in Germany and France are prioritizing HPP-labeled products for premium positioning.
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon refrigerants is accelerating infrastructure upgrades. Cold-chain operators investing in natural refrigerant systems gain operational permits for expanded distribution.
- Plant-forward formulations:Consumer demand for ingredient transparency is pulling vegetable-based SKUs into mainstream supermarket placement. Clean-label positioning commands price premiums over conventional alternatives.
Market Restraints
- Input cost volatility:Natural gas and electricity price spikes in Germany and the Netherlands are compressing margins for refrigerated logistics operators. Energy hedging costs now factor into route viability calculations.
- Supply concentration risk:High-barrier flexible packaging films concentrate among three European converters. Qualifying alternative suppliers requires 18-month validation cycles for food-contact compliance.
- Technical limitation:Current aseptic filling lines cannot accommodate both rigid and flexible formats without retooling. Capital intensity limits mid-tier producers from format diversification.
Strategic Opportunities
- Poland and Czech Republic:Refrigerated ready-meal infrastructure remains underdeveloped relative to Western European penetration rates. Early entrants can secure shelf-space commitments before category saturation.
- Home-delivery subscription models:Direct-to-consumer chilled logistics are maturing in urban UK and French markets. Weekly soup box services bypass traditional retail slotting fees entirely.
- EU Green Deal packaging mandates:Mandatory recycled content thresholds create first-mover advantages for producers with validated circular supply chains. Reverse logistics partnerships with retailers lock in exclusive supply agreements.
Industry Challenges
- Food safety certification timelines:BRCGS and IFS accreditation processes stretch 12-16 months for new production facilities. Delayed certification blocks retailer onboarding and seasonal product launches.
- Refrigerated fleet reconfiguration:Transitioning from diesel to electric or hydrogen-powered cold-chain vehicles requires depot charging infrastructure. Route density mathematics must justify per-vehicle capital outlays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chilled Soup Market |
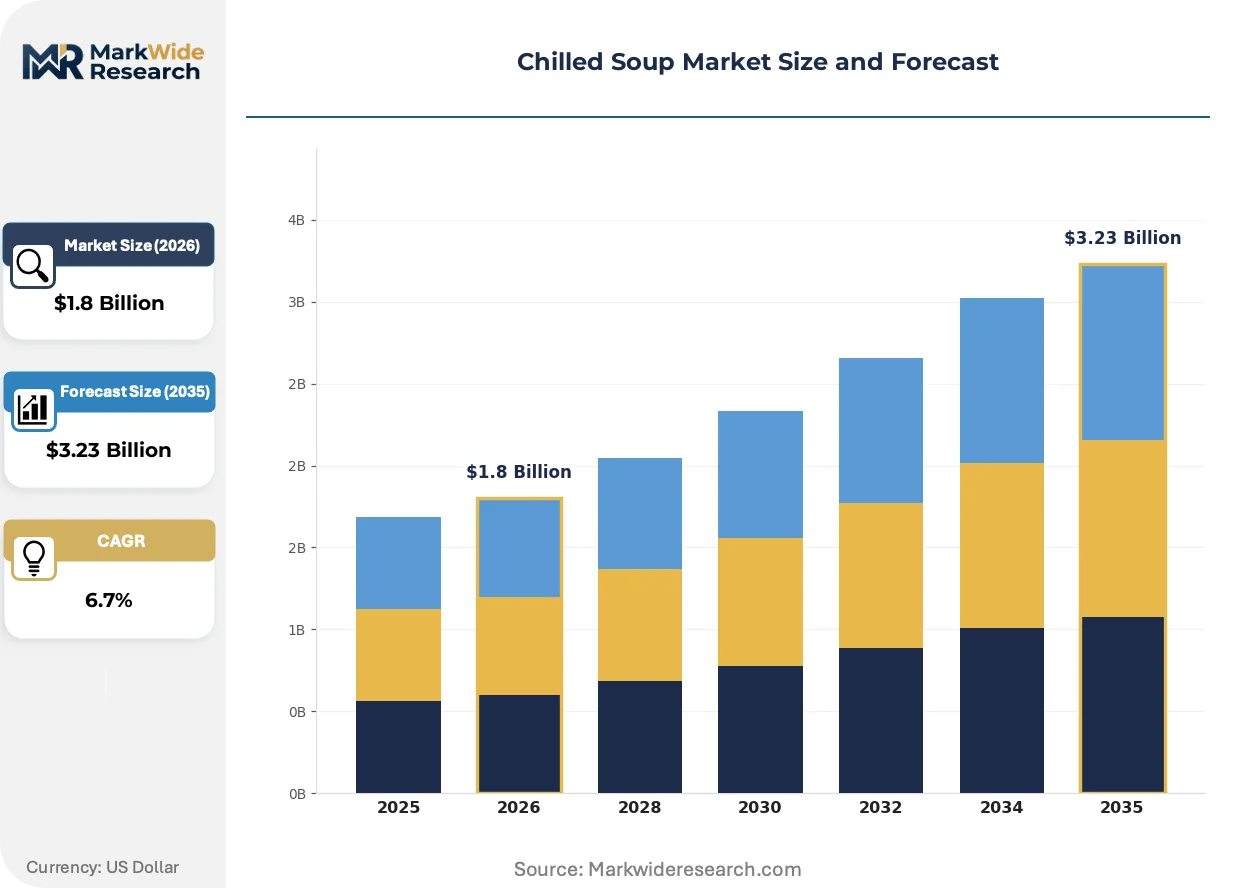
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable, Tomato, Chicken, Gazpacho Packaging Type: Bottles, Tetra Packs, Containers, Pouches End User: Retail Consumers, Restaurants, Cafes, Catering Services Distribution Channel: Supermarkets, Online Stores, Convenience Stores, Food Service |
| Companies Covered | PepsiCo, Inc., The Hain Daniels Group Ltd., Campbell Soup Company, Tio Gazpacho, Sonoma Brands, Woolworths Group Limited, Soupologie, The Billington, Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chilled Soup Market Emerging Trajectories
Clean-label preservation technologies and sustainable packaging formats are converging to redefine product differentiation. Manufacturers now compete on cold-chain carbon intensity as much as flavor profiles.
High-pressure processing equipment is converging with modified atmosphere packaging systems to eliminate thermal degradation entirely. Premium retailers in Germany and the Netherlands are adopting these combined lines for private-label chilled soup programs. The technology pairing compresses shelf-life variance and reduces spoilage returns.
EFSA nutritional profiling rules are tightening permissible health claims on chilled soup labels. Reformulation teams must document sodium and saturated fat thresholds before positioning products as balanced meal solutions. Mediterranean vegetable varieties face heightened scrutiny in French and Italian retail channels.
Subscription-based chilled meal delivery is displacing conventional supermarket purchasing among urban professionals aged 25-40. Weekly soup box services in London and Paris bundle variety packs with carbon-neutral shipping credentials. This channel shift concentrates demand planning around household-level consumption data rather than retail velocity metrics.
Chilled Soup Market Segmentation
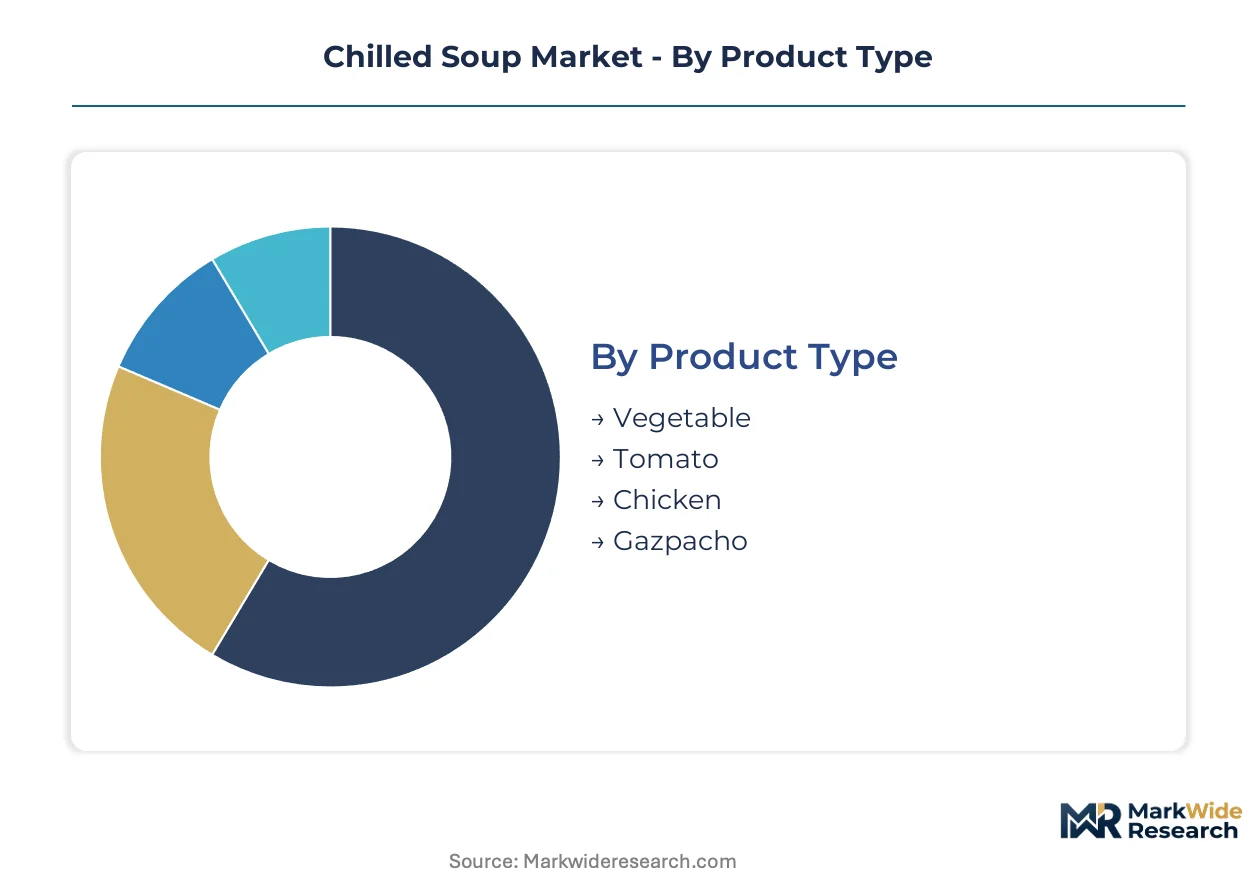
Chilled soup segmentation reveals how preservation technology and distribution infrastructure shape product positioning. Manufacturers align format decisions with cold-chain capabilities and retail channel requirements.
Product Type:
Vegetable and tomato formulations dominate standalone retail placement, while chicken and gazpacho variants embed into foodservice and premium channels respectively.
- Vegetable:Plant-forward formulations leveraging high-pressure processing to maintain cellular texture. German and French supermarket chains prioritize these SKUs for clean-label positioning in refrigerated ready-meal sections.
- Tomato:Acid-stable profiles suit extended shelf-life applications without flavor degradation. Demand concentrates in UK home-delivery subscription services where repeat purchase rates drive inventory planning.
- Chicken:Protein-enriched variants requiring stricter cold-chain compliance. EFSA nutritional profiling rules constrain sodium content claims in Mediterranean markets.
- Gazpacho:No-cook preparation aligns with summer seasonal demand peaks. Spanish retail infrastructure supports concentrated distribution during temperature-driven consumption windows.
Vegetable leads volumes today; gazpacho is gaining share fastest.
Packaging Type:
Format selection balances cold-chain energy intensity against shelf-space economics and EU Green Deal compliance timelines.
- Tetra Packs:Aseptic carton systems reduce refrigeration load versus rigid alternatives. French and Dutch retailers favor these for private-label programs targeting carbon footprint reduction.
- Pouches:Flexible high-barrier films enable portion-controlled formats with lower transport weight. Qualification cycles with European converters currently stretch 18 months for food-contact compliance.
- Bottles:PET and glass formats retain visibility advantages in conventional supermarket chilled cabinets. Germany's deposit-return systems create reverse logistics integration requirements.
- Containers:Rigid plastic tubs face mandatory recycled content thresholds under extended producer responsibility frameworks. Reformulation timelines compress margin recovery windows.
Tetra Packs anchor current production volumes; pouches are climbing the fastest.
End User:
Demand splits between at-home convenience seekers and away-from-home operators with differing freshness tolerance and portion requirements.
- Retail Consumers:Weekly purchasing patterns in urban UK and French markets favor variety packs. Subscription box services bypass traditional slotting fees through direct chilled logistics.
- Restaurants:Kitchen-ready formats reduce labor intensity for premium casual dining. HPP-labeled products command price premiums over thermally processed alternatives.
- Cafes:Grab-and-go placement requires single-serve portability with visible ingredient transparency. Clean-label positioning supports margin capture in high-rent locations.
- Catering Services:Bulk formats with extended holding stability suit event-based demand spikes. BRCGS certification requirements extend onboarding timelines for new suppliers.
Retail consumers dominate current demand; catering services show steepest expansion trajectory.
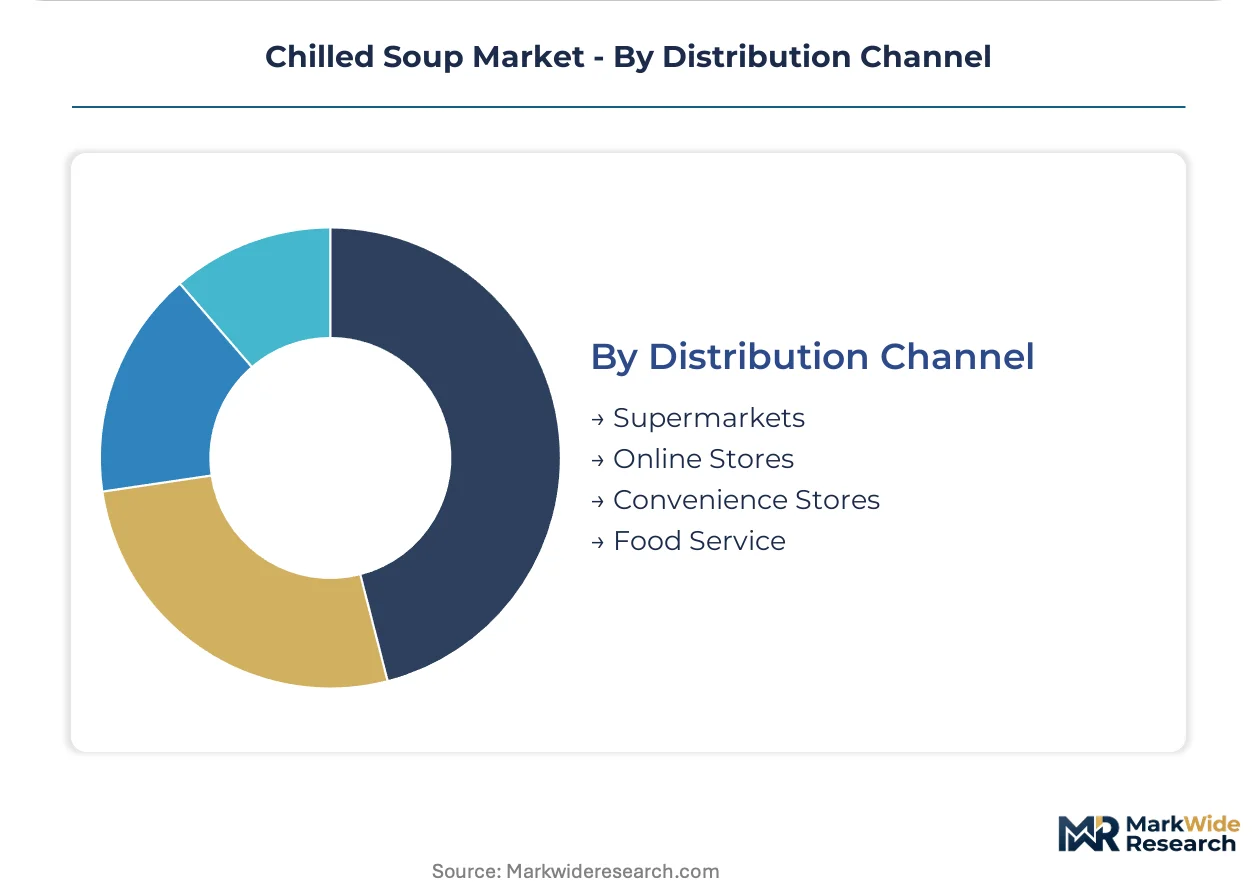
Distribution Channel:
Channel selection determines cold-chain investment intensity and margin structure through intermediary layers.
- Supermarkets:Refrigerated ready-meal infrastructure in Germany supports chilled soup penetration across discounter and premium chains. Slotting fees and promotional calendars compress net margins.
- Online Stores:Home-delivery logistics in London and Paris bundle carbon-neutral shipping credentials. Route density mathematics must justify electric vehicle fleet conversion costs.
- Convenience Stores:Limited chilled cabinet space favors high-velocity SKUs with proven sell-through. Urban location premiums restrict viable product range.
- Food Service:Direct distribution bypasses retail markups but requires specialized delivery scheduling. IFS accreditation blocks seasonal product launches for uncertified facilities.
Supermarkets lead volumes today; online stores are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologists and cold-chain logistics specialists cluster in Germany, France, and the United Kingdom, anchoring European chilled soup production expertise. Retail infrastructure density and refrigerated ready-meal penetration rates vary sharply across national markets. Regulatory frameworks in each jurisdiction reshape formulation and packaging compliance costs.
Germany
Discounter chains Aldi and Lidl drive private-label chilled soup volumes through refrigerated ready-meal sections. The EU F-Gas Regulation compels cold-chain operators to phase out hydrofluorocarbon refrigerants by 2030. Bavaria's food processing corridor hosts high-pressure processing equipment manufacturers supplying HPP lines to soup producers.
France
Urban professionals in Paris and Lyon subscribe to weekly soup box services with carbon-neutral delivery credentials. EFSA nutritional profiling rules restrict sodium content claims on vegetable-based formulations. The Île-de-France region concentrates contract manufacturers offering aseptic Tetra Pack filling for premium retailers.
United Kingdom
London's home-delivery logistics networks mature for direct-to-consumer chilled meal subscriptions. BRCGS food safety certification timelines stretch 12-16 months for new production facilities. The Midlands food manufacturing belt houses flexible packaging converters qualifying high-barrier films for pouch formats.
Spain
Summer temperature spikes concentrate gazpacho demand in Andalusia and Mediterranean coastal cities. Extended producer responsibility frameworks mandate recycled content thresholds for rigid containers. Barcelona's packaging innovation cluster develops fiber-based alternatives to plastic tubs.
Netherlands
Rotterdam's port infrastructure supports import-dependent ingredient supply chains for vegetable formulations. The EU Green Deal's packaging sustainability mandates accelerate transitions from rigid to flexible formats. Wageningen's food research campus pilots modified atmosphere packaging systems for extended shelf-life applications.
Chilled Soup Market Vendor Landscape
The competitive structure tilts toward multinational food conglomerates with refrigerated logistics scale advantages. Tiered specialization separates mass-market producers from plant-forward niche operators. Three archetypes dominate: diversified packaged food giants, chilled ready-meal specialists, and direct-to-consumer subscription brands. Capacity expansion in high-pressure processing equipment and strategic partnerships with sustainable packaging converters represent the dominant competitive moves reshaping positioning.
Within the diversified conglomerate tier, Nestlé S.A. and PepsiCo, Inc. occupy positions defined by North American and European manufacturing scale. Soupologie and Tio Gazpacho exemplify the plant-forward specialist archetype competing on ingredient transparency rather than price. Campbell Soup Company anchors the refrigerated logistics advantage segment through legacy cold-chain infrastructure. These named entities represent strategic positioning patterns rather than exhaustive market coverage.
| Leading Market Players |
|---|
| PepsiCo, Inc. |
| The Hain Daniels Group Ltd. |
| Campbell Soup Company |
| Tio Gazpacho |
| Sonoma Brands |
| Woolworths Group Limited |
| Soupologie |
| The Billington |
| Nestlé S.A. |
| Others |
Supply Flow & Price Mechanics
Food technologists specializing in high-pressure processing cluster in Bavaria's manufacturing corridor, where labor-cost differentials between German engineering talent and Eastern European production workers widen pricing-tier spreads across premium HPP-labeled and conventional thermally processed offerings.
Pricing Analysis
The bundled-versus-unbundled service split separates subscription box providers from conventional retail. Three-tier pricing structure across premium HPP-labeled, standard clean-label, and economy conventional tiers tracks certification grade and cold-chain carbon intensity. Pricing pressure stems from energy hedging costs in refrigerated logistics, compressing margins for mid-tier producers. Home-delivery subscribers show lowest price sensitivity; discounter shoppers in Germany exhibit highest.
Supply Chain Analysis
Dual-sourcing requirements from major retailers mandate multi-supplier qualification for high-barrier flexible films, forcing producers to validate alternative European converters. Raw material flows concentrate in Germany, the Netherlands, and France for HPP equipment and aseptic filling lines. Ingredient sourcing draws from Spain for tomatoes, Italy for Mediterranean vegetables, and Poland for emerging production capacity. Single-source vulnerability concentrates in three European film converters. Distribution runs through refrigerated ready-meal infrastructure at German supermarket chains and direct-to-consumer logistics in London and Paris.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chilled soup market reads as a late-cycle quality story justified by urban professional demand-shift toward carbon-neutral home-delivery subscriptions with ingredient transparency credentials.
For Market Incumbents: To counter plant-forward specialist encroachment in premium channels, Campbell Soup Company and Nestlé S.A. must deepen backward integration into HPP equipment manufacturing and secure exclusive reverse logistics partnerships with German discounters. Cold-chain carbon intensity certification becomes the priority defensive lever.
For New Entrants and Emerging Players: Subscription box operators represent the most accessible channel partner type for bypassing retail slotting fees. White-space targets include Poland and Czech Republic refrigerated ready-meal infrastructure and catering services bulk formats. A direct-to-consumer go-to-market angle with weekly variety packs captures urban professionals aged 25-40.
For Investors and Strategic Acquirers: Diversified packaged food conglomerates are the most active acquirer in this space, seeking HPP technology capabilities and sustainable packaging converter relationships. Long-term viability hinges on circular supply chain validation under extended producer responsibility frameworks. The signal to watch is EU Green Deal recycled content threshold acceleration forcing packaging material transitions.
| Strategic Initiative | Industry Significance |
|---|---|
| HPP Equipment Investment | High-pressure processing lines from Bavarian manufacturers enable premium shelf-life extension without thermal degradation. |
| Sustainable Packaging Transition | Tetra Pack and pouch format shifts reduce cold-chain energy intensity under EU Green Deal mandates. |
| Direct-to-Consumer Launch | Weekly soup box services in London and Paris bypass traditional supermarket slotting fees entirely. |
| Geographic Expansion | Poland and Czech Republic entry secures shelf-space before refrigerated ready-meal category saturation. |
| Reverse Logistics Partnership | Retailer-exclusive supply agreements lock in circular packaging material flows under extended producer responsibility. |
Methodological Framework
Multiple input streams — regulatory filing analysis, cold-chain operator interviews, and retail velocity data — were reconciled to construct market estimates. Primary discussions with chilled soup brand managers, supermarket category buyers, HPP equipment engineers, food safety certification auditors, and sustainable packaging converters informed demand-side and supply-side dynamics. Secondary validation drew from EFSA nutritional profiling guidance, EU F-Gas Regulation implementation timelines, customs records for high-barrier film imports, and refrigerated logistics operator disclosures. Bottom-up SKU-level volume builds were cross-checked against top-down category expenditure estimates.
Historical shipment patterns were cross-referenced against panel input from production facility operators to anchor growth trajectories across the projection horizon. Segmentation modeling captured preservation technology, packaging format, distribution channel, and end-user archetype dimensions. CAGRs were derived from trend extrapolation moderated by infrastructure penetration limits and regulatory compliance cost curves. Forecast inputs included HPP equipment installation rates, EU Green Deal packaging mandate phase-in schedules, and home-delivery logistics network maturation indicators.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU F-Gas Regulation enforcement pace and natural refrigerant system adoption costs. Deviation in extended producer responsibility timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
North America Dehydrated Food Market
Processed and Frozen Foods
North America Frozen Pizza Market
Processed and Frozen Foods
Europe Frozen Desserts Market
Processed and Frozen Foods
Refrigerated Liquid Eggs Market
Processed and Frozen Foods
Asia Pacific Frozen Desserts Market
Processed and Frozen Foods
Dehydrated Potato Products Market
Processed and Frozen Foods
Latin America Frozen Finger Chips Market
Processed and Frozen Foods
Frozen Yogurt Market
Processed and Frozen Foods
Turkey Cold Storage Market
Processed and Frozen Foods
Frozen Cheese Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
Cold Storage Market
Processed and Frozen Foods
Frozen Bread Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Dumplings Market