
 Egg White Cubes Market | 2026-2036
Egg White Cubes Market Size, Share, and Industry Trends Forecast 2026-2036
Egg White Cubes Market Foresight
Single-serve portioning is restructuring buyer choice across the egg white cubes category, as food service operators and fitness consumers trade bulk formats for freezer-ready units that reduce waste and prep time. SKM leverages its manufacturing scale to supply standardized cube geometries for industrial baking clients. Copain sustains brand recognition in European retail channels through specialized packaging for household end users. Michael Foods anchors North American food service distribution with frozen cube formats designed for high-volume restaurant kitchens.
Egg white cubes consist of pasteurized, separated albumen formed into frozen or dried geometric units, typically containing 3.5–4.0 grams of protein per 30-gram serving with moisture content below 5% in dried variants; the format exists to eliminate shelling labor and yolk separation steps in commercial and consumer food preparation. Frozen product types dominate current volume due to superior texture retention in baking and confectionery applications, though spray-dried variants are capturing margin pools in protein supplements where shelf stability commands premium positioning. Food processing applications lead absolute demand as manufacturers integrate pre-measured albumen units to standardize batch consistency, while online distribution channels are expanding fastest among households seeking direct-to-consumer protein solutions.
The FDA enforces egg safety rules under 21 CFR Part 118, requiring pasteurization and Salmonella prevention measures that elevate processing costs for frozen albumen formats. The USDA grades egg products for quality and inspects facilities under the Egg Products Inspection Act, shaping which suppliers qualify for institutional procurement contracts. The EU EFSA sets microbiological criteria for egg-derived ingredients under Regulation 2073/2005, influencing export eligibility for North American producers. Stakeholders must monitor evolving cold-chain traceability mandates and protein-labeling standards as regulators tighten oversight on functional food claims.
Market Dynamics
Pre-portioned frozen formats are restructuring procurement patterns across food service and fitness channels, compressing traditional bulk albumen purchasing into standardized unit economics that reward cold-chain specialists and penalize shell-egg handlers.
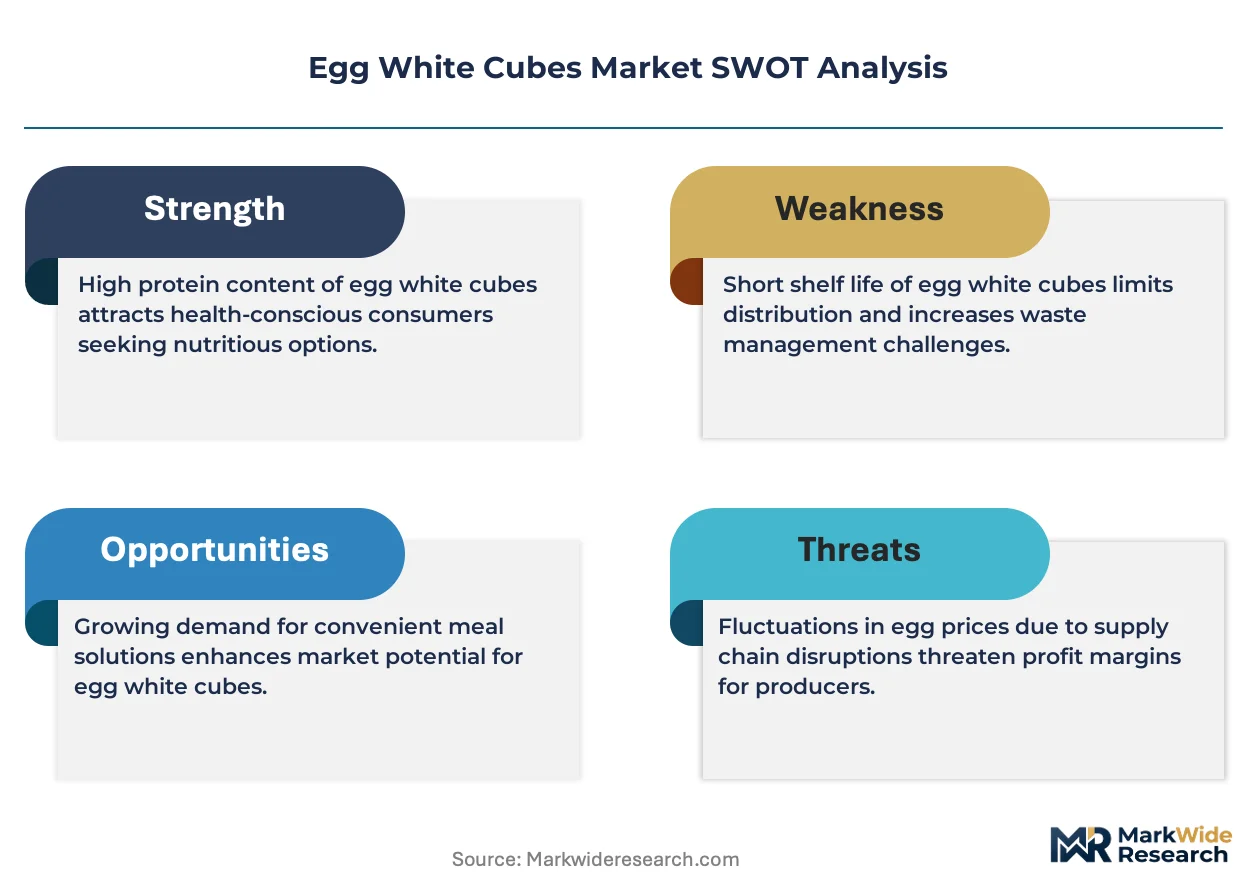
Growth Catalysts
- USDA Egg Products Inspection Act:Federal facility grading creates procurement gatekeeping that favors pasteurized cube suppliers over shell-egg handlers in institutional contracts.
- High-volume restaurant kitchens:Commercial operators trade labor-intensive separation for freezer-ready portions that reduce prep time and waste metrics.
- Spray-drying technology:Moisture reduction below 5% unlocks shelf-stable protein supplement applications previously inaccessible to frozen formats.
Market Restraints
- Feed cost volatility:Layer hen nutrition inputs fluctuate with grain commodity cycles, compressing processor margins without pricing power recovery.
- Cold-chain concentration:Frozen cube distribution depends on specialized logistics nodes concentrated in the United States, Germany, and Japan.
- 21 CFR Part 118 compliance:FDA Salmonella prevention mandates elevate pasteurization capital requirements, creating barrier-to-entry friction for regional processors.
Strategic Opportunities
- Direct-to-consumer channels:Online distribution bypasses traditional food service intermediaries, capturing household fitness segments with subscription models.
- EU Green Deal alignment:Carbon footprint labeling incentives favor concentrated protein formats over shell-egg transport emissions in European retail.
- Confectionery-bakery convergence:Standardized albumen geometries enable automated dosing integration with industrial mixing equipment.
Industry Challenges
- Batch certification timelines:USDA facility approval cycles delay new production capacity activation by 12-18 months.
- Legacy ERP integration:Frozen inventory tracking systems require cold-chain traceability module upgrades that strain mid-processor IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg White Cubes Market |
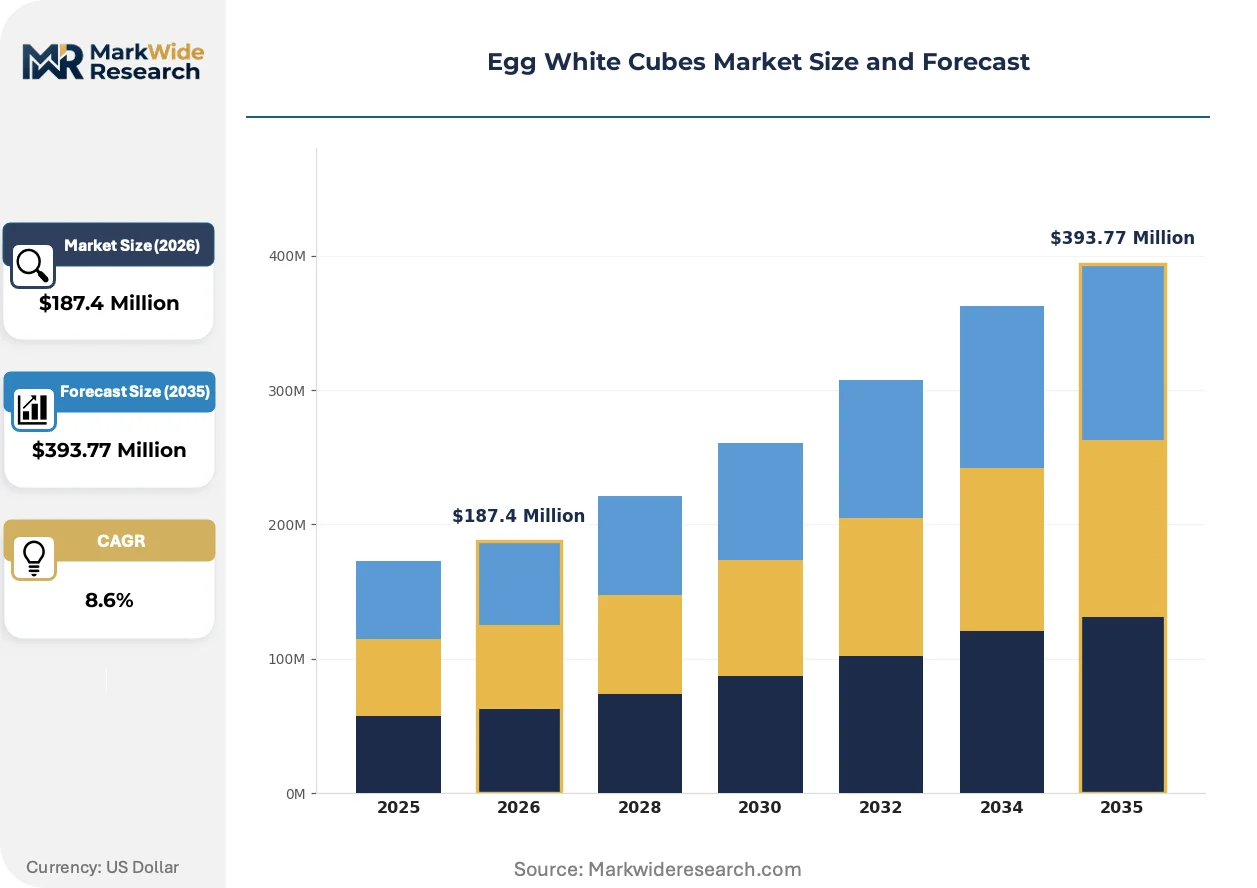
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen, Dried, Liquid, Spray-Dried Application: Baking, Food Processing, Protein Supplements, Confectionery Distribution Channel: Online, Retail, Food Service, Wholesale End User: Restaurants, Bakeries, Manufacturers, Households |
| Companies Covered | SKM, Copain, Munax, Ovo Fit Eiprodukte, NOW Foods, Eggology, Michael Foods, Crystal Farms, Tyson Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg White Cubes Market Shifts & Advancements
Automation in portioning and packaging is compressing unit economics while regulatory traceability mandates and channel fragmentation are forcing simultaneous investment in compliance infrastructure and direct fulfillment capabilities.
Precision-forming extrusion technology is modularizing cube geometry standardization across industrial baking lines. European confectionery manufacturers adopt these systems fastest, replacing manual albumen measurement with automated dosing that reduces batch variance. The technology is modularizing supplier relationships, as equipment compatibility requirements lock processors into specific cube dimension specifications.
EU Regulation 2073/2005 microbiological criteria are tightening export eligibility standards for North American albumen processors. EFSA enforcement actions against Salmonella-positive shipments have triggered enhanced cold-chain documentation requirements. Frozen cube exporters to Germany and France now face pre-shipment laboratory certification costs that spray-dried competitors avoid.
Subscription replenishment models are displacing traditional food service distribution for household fitness segments. Japanese consumers lead adoption of auto-ship frozen protein programs, bypassing retail intermediaries entirely. This channel compression concentrates fulfillment responsibility with cube processors, requiring last-mile cold-chain partnerships that bulk albumen suppliers never constructed.
Egg White Cubes Market Segmentation
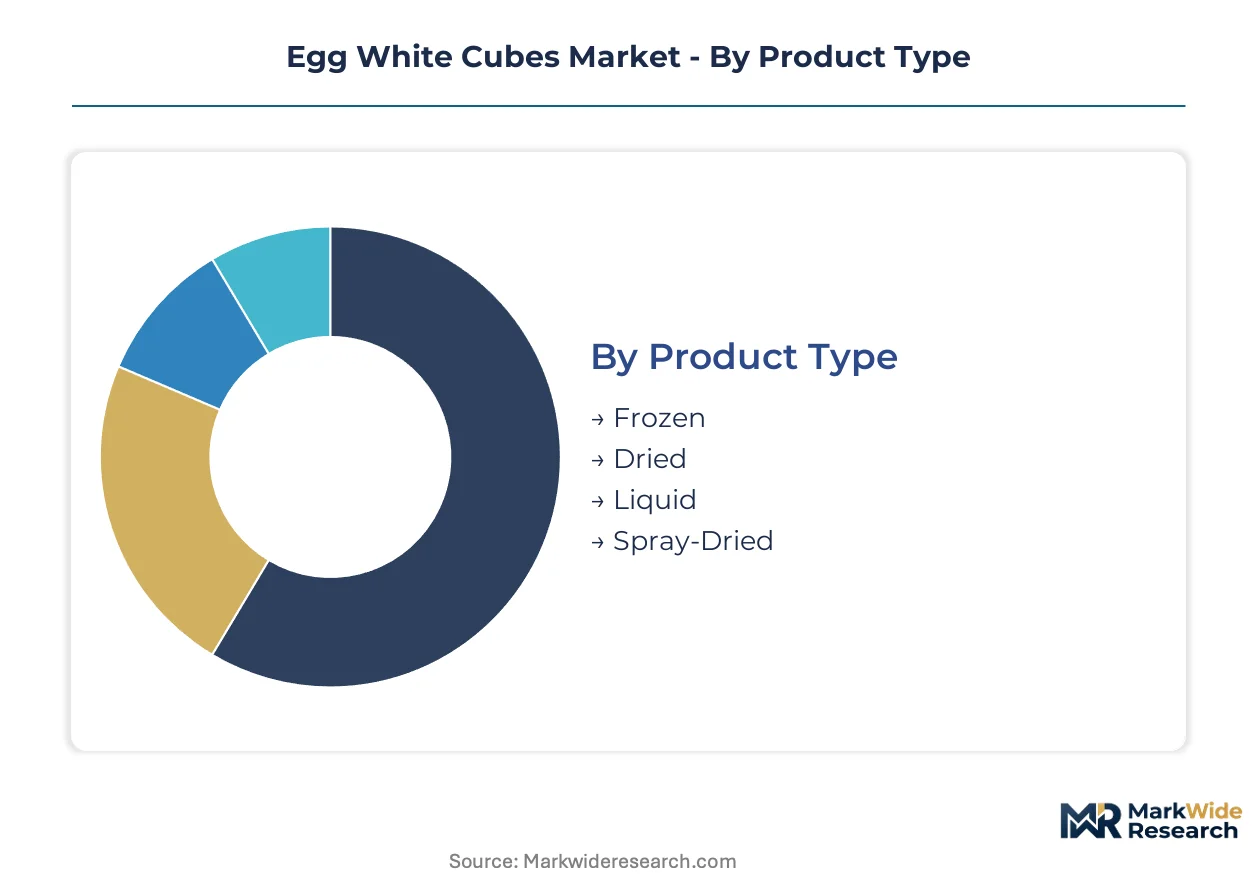
Egg white cubes fragment across four distinct category axes, each capturing different value chain positions from raw material form through final consumption context. Understanding these splits reveals where margin pools concentrate and which integration paths offer defensible positioning.
Product Type:
Frozen formats operate as standalone inputs requiring dedicated cold-chain infrastructure, while dried and spray-dried variants embed into broader ingredient systems with relaxed handling requirements.
- Frozen:Pasteurized albumen formed into geometric units with moisture content above 80%, delivering superior foam stability and texture retention in meringue and soufflé applications. Demand concentrates in United States food service channels where high-volume restaurant kitchens trade labor costs against cold-chain dependency.
- Spray-Dried:Atomized albumen particles with moisture below 5%, enabling ambient storage and extended shelf life that unlocks protein supplement and sports nutrition applications previously inaccessible to frozen competitors. Japanese direct-to-consumer channels favor this format for subscription replenishment models.
- Dried:Tray-dried or drum-dried albumen flakes with intermediate moisture profiles, serving industrial baking clients seeking cost-efficient bulk protein fortification without frozen logistics burdens.
- Liquid:Refrigerated pasteurized albumen in bulk containers, preferred by confectionery manufacturers with continuous production lines and captive cold storage capacity.
Frozen leads volumes today; spray-dried is gaining share fastest.
Application:
Cost tier separation distinguishes commodity-scale industrial uses from premium-positioned functional nutrition segments, with equipment compatibility and certification requirements driving divergent procurement patterns.
- Food Processing:Industrial manufacturers integrate pre-measured cube units to standardize batch consistency in mayonnaise, pasta, and prepared meal production. German processors lead adoption of automated dosing systems that lock suppliers into specific cube geometries.
- Protein Supplements:Fitness-oriented consumers and sports nutrition formulators demand spray-dried variants with labeled amino acid profiles and third-party purity certifications. United States direct-to-consumer brands capture premium positioning through subscription models.
- Baking:Artisan and industrial bakeries utilize frozen cubes for consistent foam structure in angel food cakes and macarons, with European confectionery houses specifying dimensional tolerances for automated line integration.
- Confectionery:Chocolate and candy manufacturers employ dried albumen as a binding and aerating agent, with French and Belgian producers driving specifications for low-odor, low-color variants.
Food processing leads volumes today; protein supplements is climbing the fastest.
Distribution Channel:
Customer type fragmentation separates institutional procurement through intermediaries from household acquisition via direct fulfillment, with margin capture and data ownership implications.
- Food Service:Broadline distributors and specialty protein suppliers deliver frozen cubes to restaurant chains and institutional cafeterias under long-term contracts with price-volume indexing. United States operators dominate this channel.
- Online:Brand-direct e-commerce and marketplace platforms enable subscription replenishment for fitness consumers, with Japanese and United States households showing highest auto-ship adoption rates.
- Retail:Supermarket freezer cases and specialty health food stores stock consumer-packaged formats, with German retail chains emphasizing carbon footprint labeling under EU Green Deal alignment.
- Wholesale:Cash-and-carry depots and food ingredient brokers serve small bakeries and independent restaurants with broken-case availability and flexible minimum order quantities.
Food service leads volumes today; online is expanding most quickly.
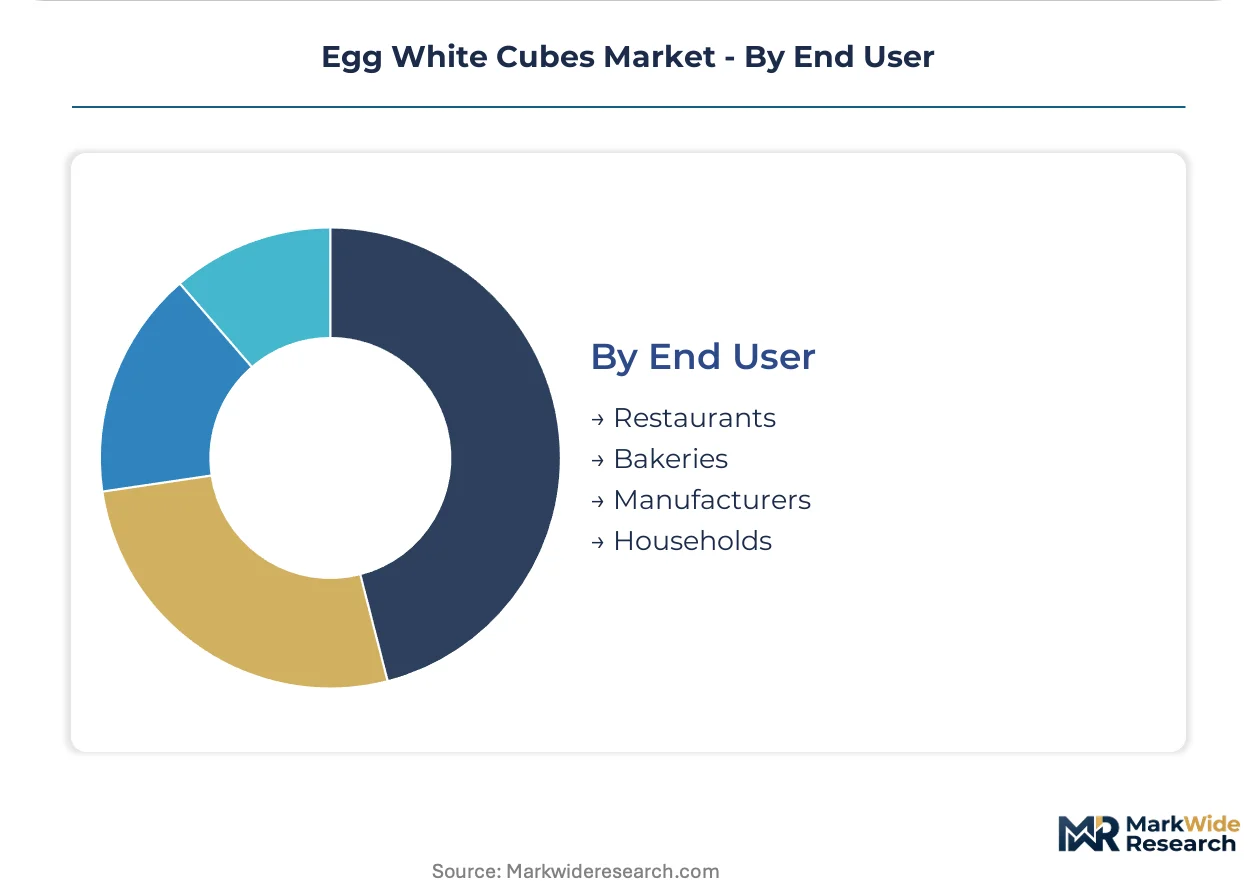
End User:
Supply concentration varies dramatically across user scale, from multinational manufacturers with captive procurement teams to fragmented household decision-makers.
- Manufacturers:Industrial food and supplement producers purchase bulk frozen or dried formats under technical specifications negotiated with quality assurance departments. United States and German manufacturers anchor demand.
- Restaurants:High-volume kitchen operators trade shell-egg handling labor against cold-chain storage investments, with quick-service chains standardizing on pre-portioned cubes for consistency metrics.
- Bakeries:Artisan and commercial bakeries select cube geometries compatible with existing mixing equipment, with French and Italian producers influencing European dimensional standards.
- Households:Fitness-oriented consumers and convenience-seeking home cooks purchase retail or online formats, with Japanese households showing highest per-capita frozen protein consumption.
Manufacturers lead volumes today; households is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egg white cube manufacturing originated in post-war United States food processing corridors, where pasteurization infrastructure developed to serve institutional baking and military procurement channels before expanding to commercial fitness applications.
United States
Fitness consumers and quick-service restaurant chains drive demand for pre-portioned frozen formats. The USDA Egg Products Inspection Act mandates facility grading that filters regional processors from national distribution contracts. Chicago and Minneapolis-St. Paul anchor frozen cube production capacity, serving broadline distributors supplying institutional cafeterias.
Germany
Industrial confectionery manufacturers specify automated dosing-compatible cube geometries for meringue production lines. EFSA microbiological criteria under Regulation 2073/2005 enforce pre-shipment laboratory certification for frozen imports. The Cologne-Düsseldorf corridor concentrates European albumen processing capacity, with Bavarian equipment manufacturers supplying precision-forming extrusion systems.
Japan
Household subscription models for spray-dried protein supplements displace traditional retail channels fastest globally. METI food labeling standards govern amino acid profile declarations on functional nutrition packaging. Tokyo and Osaka metropolitan areas host direct-to-consumer fulfillment centers with last-mile cold-chain partnerships.
France
Artisan bakeries and luxury confectionery houses demand low-odor, low-color dried albumen variants for premium macaron and chocolate applications. EU Green Deal carbon footprint labeling incentives favor concentrated protein formats over shell-egg transport emissions. The Lyon-Grenoble axis specializes in spray-drying technology for export-grade ingredient production.
United Kingdom
Health-focused retail chains stock consumer-packaged frozen cubes alongside carbon-labeled alternatives. FSA enforcement of Salmonella prevention protocols aligns with post-Brexit import documentation requirements. Greater London distribution hubs manage re-export flows to Irish and Nordic markets.
Egg White Cubes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across cold-chain certification tiers, with USDA-graded facilities commanding procurement gatekeeping power in institutional channels. The vendor base stratifies into three tiers: multinational food conglomerates with captive albumen processing, specialized egg product processors with regional cold-chain density, and direct-to-consumer brands leveraging subscription replenishment models. Scale-driven consolidation and regulatory compliance investments constitute the dominant competitive moves, as mid-cap processors face 12-18 month USDA facility approval cycles.
Among specialized egg product processors, SKM, Copain, and Michael Foods occupy distinct archetype positions. SKM represents manufacturing-scale suppliers delivering standardized cube geometries to industrial baking clients. Copain exemplifies European retail-channel specialists with household-focused packaging configurations. Michael Foods anchors North American food service distribution through frozen formats designed for high-volume kitchen operators. These three entities illustrate how geographic concentration, channel specialization, and format expertise segment competitive positioning without requiring identical capability portfolios.
| Leading Market Players |
|---|
| SKM |
| Copain |
| Munax |
| Ovo Fit Eiprodukte |
| NOW Foods |
| Eggology |
| Michael Foods |
| Crystal Farms |
| Tyson Foods |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up egg processing specialists anchor supply consolidation across the United States and Germany, translating cold-chain infrastructure scarcity into disciplined pricing power over food service distributors while compressing margins for ungraded regional handlers.
Pricing Analysis
Three-tier pricing structure across USDA-graded premium, standard commercial, and ungraded economy levels separates institutional procurement contracts from retail household formats. Price differentiation hinges on FDA 21 CFR Part 118 certification tier and volume-scale commitments, with quick-service restaurant chains capturing standard-tier discounts through multi-year offtake agreements. Pricing pressure stems from feed grain commodity volatility that processors cannot fully pass through to locked institutional buyers. Household fitness consumers show lowest price sensitivity, prioritizing amino acid profile transparency over per-gram cost.
Supply Chain Analysis
Layer hen nutrition inputs rest on United States corn and soybean meal markets, with secondary dependencies on German and Japanese cold-chain equipment manufacturers. Raw material sourcing draws from Midwest grain elevators, specialized vitamin premix suppliers, and automated cage-free housing systems. Single-source vulnerability concentrates in USDA-graded pasteurization equipment where two domestic suppliers dominate. Distribution runs through broadline food service intermediaries for frozen formats, while spray-dried variants bypass cold-chain nodes entirely via ambient parcel networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in spray-dried protein supplements where shelf-stable formats command premium positioning, enabled by moisture-reduction technology cost curves flattening production economics.
For Market Incumbents: Acquire precision-forming extrusion technology providers to lock industrial baking clients into proprietary cube geometries that raise switching costs. Secure backward integration into cage-free layer operations to buffer feed cost volatility and meet EU Green Deal sourcing requirements. Defend against direct-to-consumer subscription entrants by controlling last-mile cold-chain partnerships in Tokyo and Osaka metropolitan fulfillment zones. For New Entrants and Emerging Players: Spray-drying automation equipment offers a technology-first wedge into Japanese household subscription channels where incumbent frozen-cube processors lack ambient distribution infrastructure. Target underpenetrated artisan bakery segments in France and Italy with low-odor, low-color dried variants specified for macaron production. Pursue white-label manufacturing partnerships with United States fitness brands seeking amino acid-certified protein supplements without captive processing assets. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap European processors lacking USDA facility grading, creating acquisition targets for North American conglomerates seeking EU market access. Long-term viability favors operators with dual frozen-and-dried capability portfolios that span institutional food service and direct-to-consumer fitness channels. Watch EFSA enforcement actions against Salmonella-positive shipments as the signal indicating regulatory tightening that would accelerate consolidation toward graded facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Partnership | Last-mile frozen distribution in Japanese metropolitan areas captures household subscription growth. |
| Precision-Forming Extrusion Deployment | Automated dosing compatibility locks German confectionery manufacturers into supplier relationships. |
| Backward Integration into Layer Operations | Cage-free sourcing secures EU Green Deal eligibility and buffers feed commodity volatility. |
| Spray-Drying Capacity Expansion | Shelf-stable formats unlock protein supplement margins inaccessible to frozen competitors. |
| USDA Facility Grading Investment | Federal inspection qualification filters regional processors from national institutional contracts. |
Research Methodology
Coverage spans United States, Germany, Japan, France, and United Kingdom markets, with primary inputs from each region's egg processing executives, food service procurement directors, confectionery manufacturing engineers, and fitness brand supply chain managers. Secondary validation draws from USDA facility inspection records, FDA 21 CFR Part 118 compliance filings, EFSA microbiological criteria enforcement actions, EU Green Deal carbon labeling documentation, and METI food labeling standard submissions. Bottom-up volume modeling triangulates against top-down protein supplement and industrial ingredient consumption estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon, with segmentation dimensions spanning product type, application, distribution channel, and end user. CAGRs derive from fitted growth curves calibrated to historical frozen albumen trade flows and spray-dried protein supplement subscription adoption patterns. Industry-specific forecast inputs include layer hen flock size projections, grain commodity futures curves, and cold-chain logistics capacity expansion announcements.
The model holds under stable regulatory enforcement and grain input cost conditions; deviation in EFSA Salmonella testing stringency or Midwest drought frequency would shift volume and value trajectories. Forecasts reflect documented assumptions about pasteurization technology adoption rates and direct-to-consumer channel penetration ceilings. A small set of named triggers—USDA grading backlog duration, EU carbon border adjustment implementation, and Japanese subscription churn rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Ready to Cook Market
Processed Foods
Processed Eucheuma Seaweed Market
Processed Foods
Fermented Food and Drinks Market
Processed Foods
Artisanal Ice Cream Market
Processed Foods
Butter Crisco Market
Processed Foods
Potato Soup Market
Processed Foods
Imitation Whipped Cream Market
Processed Foods
Porridge Market
Processed Foods
Global Dried Processed Food Market
Processed Foods
Chocolate Filling Market
Processed Foods
Processed Potatoes Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
High-Pressure Processing (HPP) Foods Market
Processed Foods
Pizza Market
Processed Foods
Fat Free Soup Market
Processed Foods
Processed Peanut Market