
 Fresh Pasta Market | 2026-2036
Fresh Pasta Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Pasta Market Analysis
Artisanal extrusion technology is fragmenting traditional production methods across the fresh pasta supply chain. Barilla leverages automated sheeting lines to sustain volume leadership in European retail. Giovanni Rana anchors premium positioning through regional kitchen formats that emphasize recipe authenticity. De Cecco competes on semolina sourcing control, extending its durum supply network into Southern Italy.
Fresh pasta comprises uncooked dough sheets or shapes made from wheat flour and liquid eggs, typically containing minimum egg content of two hundred grams per kilogram of semolina under Italian trade standards, and requires refrigerated distribution to maintain shelf stability below four degrees Celsius. Filled pasta leads value contribution as ravioli and tortellini command price premiums in specialty stores and foodservice accounts. Noodles represent the fastest-expanding product type, driven by Asian fusion menus in restaurant channels across North America and Europe. Distribution through online retailers is accelerating as chilled last-mile logistics mature, though supermarkets still occupy the dominant share of household purchase occasions.
EU regulation 1169/2011 mandates detailed allergen and origin labeling for prepacked fresh pasta sold in member states, while FDA oversight in the United States enforces pasteurization standards for egg-based formulations distributed interstate. BIS certification requirements in India affect import access for European producers targeting emerging retail channels. Stakeholders must monitor evolving cold-chain regulations and labeling harmonization talks between major trading blocs to anticipate compliance costs and market entry timing.
Market Dynamics
Chilled last-mile logistics maturation is redistributing competitive advantage across the fresh pasta value chain, compressing traditional supermarket dominance while enabling direct-to-restaurant and subscription models that bypass conventional wholesale tiers.
Growth Catalysts
- EU Regulation 1169/2011:Mandatory allergen and origin labeling requirements push manufacturers toward cleaner formulations, creating premium positioning opportunities for producers with transparent supply chains.
- Asian fusion menu expansion:Restaurant channels across North America and Europe now incorporate fresh noodles into fusion dishes, pulling volume through foodservice distributors previously focused on dry pasta.
- Artisanal extrusion automation:Mid-scale producers deploy semi-automated bronze-die equipment to replicate hand-crafted texture at commercial scale, bridging the gap between industrial output and craft positioning.
Market Restraints
- Durum wheat price volatility:Semolina input costs fluctuate with North African and Canadian harvest cycles, squeezing margin structures for producers without long-term supply contracts.
- Cold-chain infrastructure concentration:Refrigerated distribution capacity clusters around major metropolitan logistics hubs, limiting rural and secondary city penetration.
- Refrigerated shelf-life limitation:Four-degree Celsius maximum storage temperature creates technical barriers to export expansion beyond adjacent markets.
Strategic Opportunities
- Direct-to-consumer subscription channels:Online retailers with mature chilled fulfillment networks capture recurring household purchase occasions outside supermarket dominance.
- Clean-label reformulation:Egg-free and alternative-protein dough innovations address allergen-sensitive segments while complying with FDA pasteurization standards for interstate distribution.
- Foodservice co-manufacturing partnerships:Restaurant chains seeking proprietary pasta specifications create white-label production demand for flexible manufacturing assets.
Industry Challenges
- Bronze-die craftsmanship scarcity:Skilled operators capable of maintaining traditional extrusion equipment for textured surface finish are retiring faster than training programs replace them.
- Multi-jurisdiction certification complexity:Producers targeting India must navigate BIS import certification alongside EU origin documentation, extending market entry timelines.
- Legacy ERP integration with traceability systems:Batch-level tracking requirements under EU 1169/2011 clash with decades-old production scheduling software in family-owned facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Pasta Market |
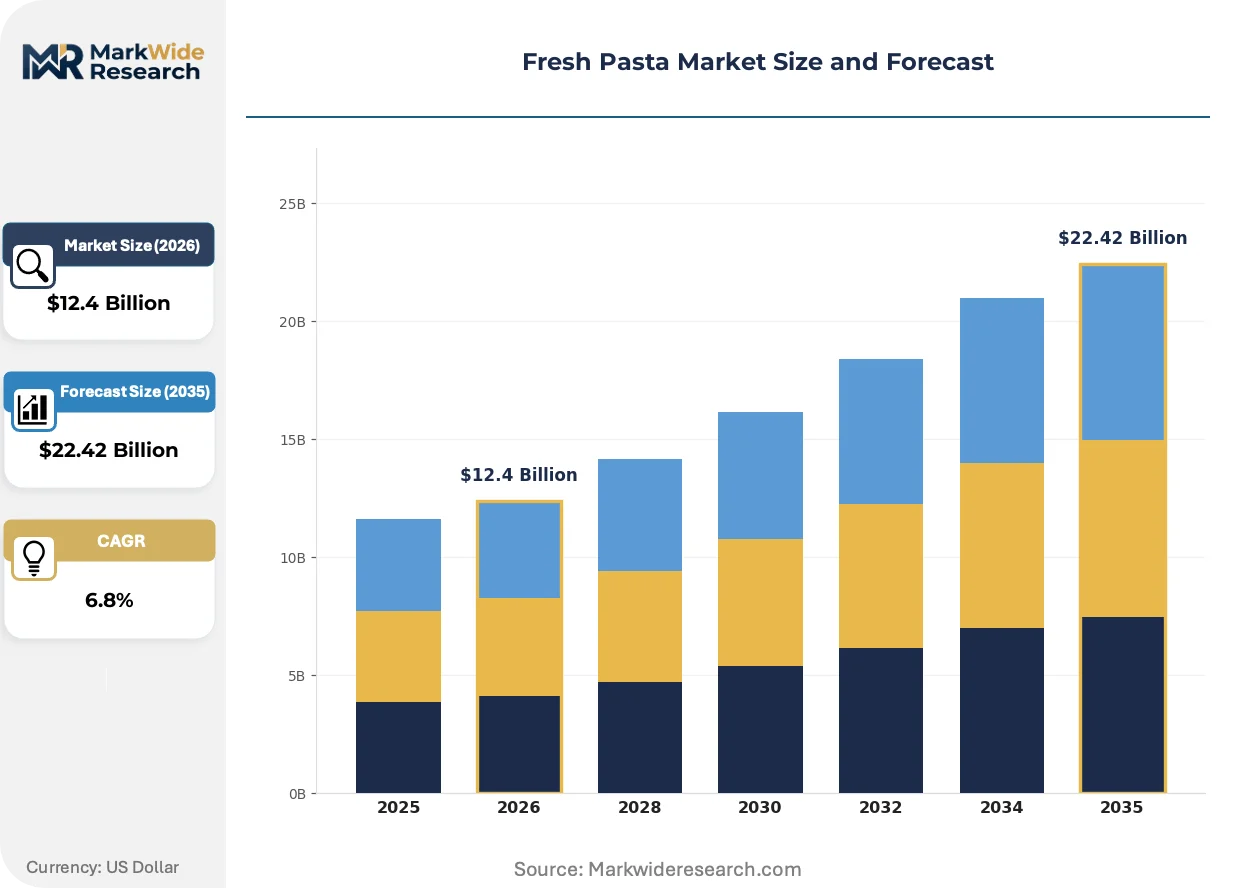
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filled Pasta, Noodles, Fettuccine, Linguine Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Foodservice End User: Households, Restaurants, Catering Services, Delis Packaging Type: Rigid Containers, Flexible Pouches, Vacuum Sealed, Others |
| Companies Covered | Rana, Buitoni, Barilla, Voltan SpA, Lilly's Fresh Pasta, Giovanni Rana, Pastificio Gaetarelli, Pastificio Di Martino, De Cecco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Pasta Market Emerging Trajectories
Automation, regulatory transparency mandates, and channel fragmentation are converging to reshape how fresh pasta reaches end consumers. These forces compress legacy cost structures while opening new competitive vectors.
High-pressure pasteurization (HPP) treatment of egg-based dough formulations extends refrigerated shelf stability without thermal degradation of texture. Premium retail brands and meal-kit assemblers adopt HPP lines to reduce spoilage rates in direct-to-consumer channels. This non-thermal processing technology is rendering obsolete the traditional trade-off between extended distribution reach and artisanal mouthfeel.
EU 1169/2011 enforcement continues tightening across member states, with national food safety authorities now conducting unannounced audits of semolina origin documentation. Manufacturers face reformulation costs or labeling redesign to maintain shelf placement in German and French retail. Filled pasta categories carrying complex ingredient lists bear disproportionate compliance burden, accelerating simplification of ravioli and tortellini recipes.
Restaurant procurement departments now source fresh pasta through specialized foodservice platforms that aggregate regional artisan producers. These digital intermediaries displace traditional broadline distributors for premium menu placements, capturing chef relationships through sample programs and customizable portion specifications. This channel shift concentrates most visibly in urban North American markets where independent restaurant density supports fragmented supplier aggregation.
Fresh Pasta Market Segmentation
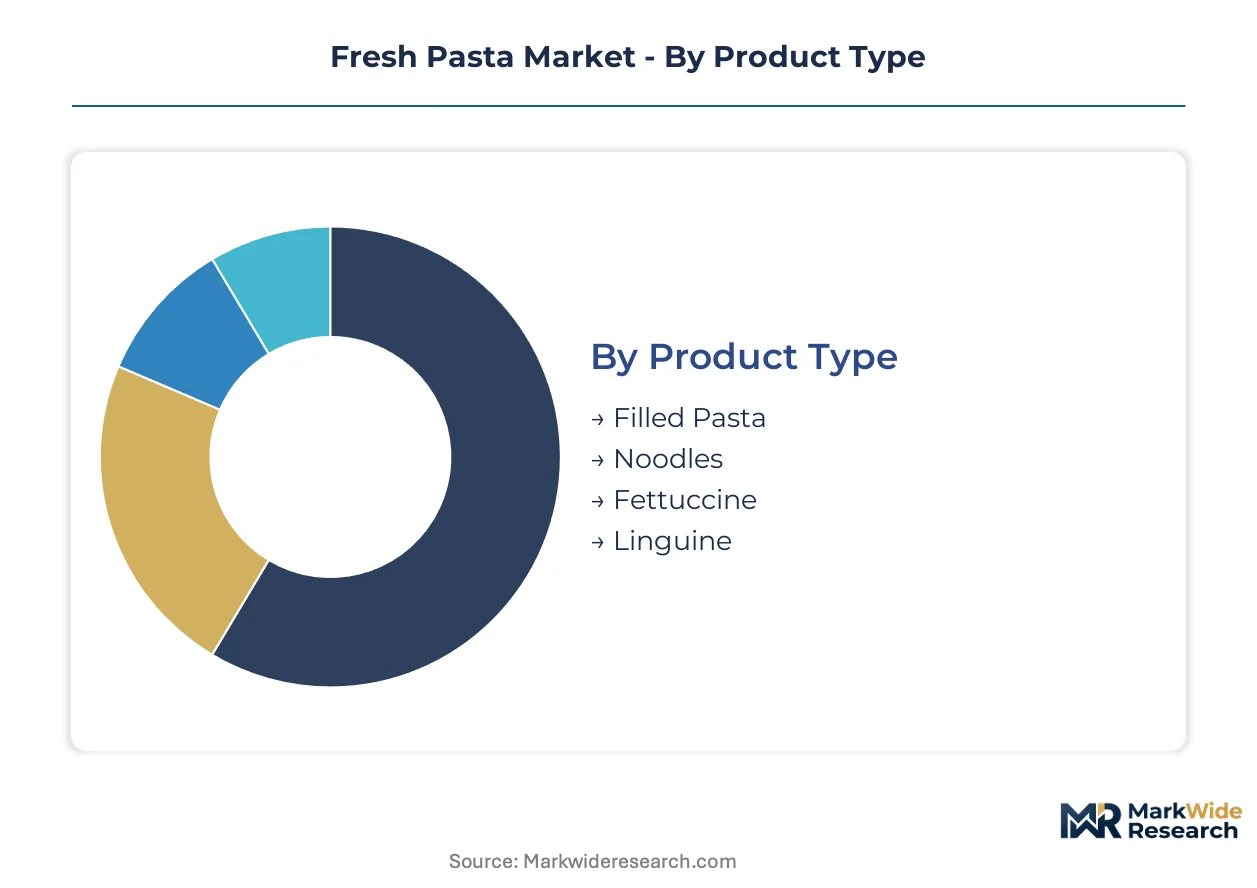
Fresh pasta segmentation reveals divergent velocity profiles across product formats and channel structures. Cycle time variation between refrigerated inventory turns and direct-to-restaurant fulfillment creates distinct margin architectures that reward specialized positioning over broad coverage.
Product Type:
Turnover velocity separates filled formats with complex assembly from simple-cut varieties with minimal processing steps.
- Filled Pasta:Ravioli and tortellini formulations carry egg-enriched dough wrapped around cheese, meat, or vegetable centers. German foodservice channels absorb disproportionate volume as institutional buyers specify filled formats for menu standardization.
- Noodles:Asian fusion applications in North American restaurants now specify fresh wheat noodles for ramen and stir-fry applications. This segment climbs the fastest as chef-driven demand bypasses traditional Italian-format preferences.
- Fettuccine:Broad ribbon cuts dominate retail refrigerated cases with straightforward bronze-die extrusion.
- Linguine:Narrow flat strands serve premium home-cooking occasions through specialty store placement.
Filled pasta anchors the volume base while noodles gain share at the steepest rate.
Distribution Channel:
Cost-to-serve economics stratify channels between mass retail scale and premium service intensity.
- Supermarkets:Chilled case placement requires slotting fees and promotional compliance that favor producers with national refrigerated distribution networks.
- Online Retailers:Direct-to-consumer subscription models with mature last-mile cold-chain infrastructure now capture recurring household purchases outside traditional retail dominance. This channel expands most quickly as meal-kit assemblers integrate fresh pasta into weekly delivery bundles.
- Specialty Stores:Italian delicatessens and gourmet grocers emphasize provenance labeling and short ingredient lists.
- Foodservice:Broadline and specialty distributors serve restaurant accounts with customized portion specifications and just-in-time replenishment.
Supermarkets retain the volume anchor position while online retailers accelerate fastest through subscription mechanics.
End User:
Application context determines formulation requirements from pasteurization levels to portion precision.
- Households:Retail-packaged formats with extended shelf-life claims through modified atmosphere packaging.
- Restaurants:Chef-specified textures and custom dimensions drive co-manufacturing relationships with flexible production assets. This segment shows the steepest trajectory as independent restaurant density in urban North America supports fragmented supplier aggregation.
- Catering Services:Bulk portion formats with holding stability for buffet and event service.
- Delis:Prepared-meal adjacencies requiring minimal final preparation by counter staff.
Households provide the stable demand foundation while restaurants pull volume growth through menu premiumization.
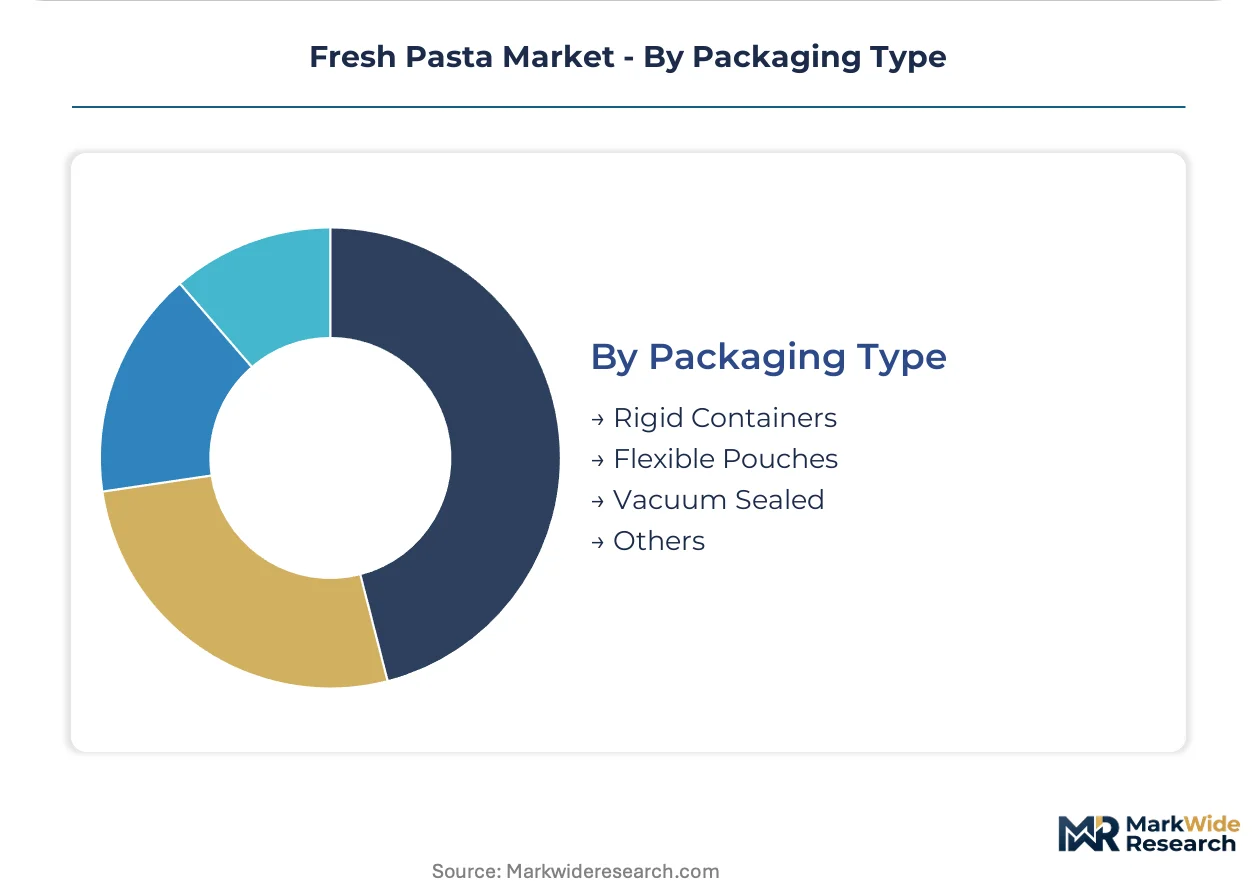
Packaging Type:
Material selection tracks shelf-life extension requirements against sustainability positioning pressures.
- Rigid Containers:Thermoformed trays with resealable lidding dominate filled pasta protection against compression damage.
- Flexible Pouches:Stand-up and flat pouch formats reduce freight cube and refrigeration load.
- Vacuum Sealed:Oxygen exclusion extends refrigerated stability for premium positioning and export tolerance.
- Others:Biodegradable films and paper-based alternatives emerging for sustainability-driven retail banners.
Rigid containers hold the volume base while vacuum sealed formats gain fastest through premium channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian fresh pasta exports flow primarily into German and French retail channels, while North American demand pulls specialty formats through foodservice distributors. Cold-chain infrastructure maturity determines export reach, with refrigerated logistics corridors extending from Emilia-Romagna into Central European markets and from domestic US production into Canadian urban centers.
Germany
Chilled pasta consumption in foodservice channels outpaces other European markets as institutional buyers standardize ravioli and tortellini specifications. EU regulation 1169/2011 enforcement through the Federal Office of Consumer Protection and Food Safety mandates granular allergen declarations, pushing importers toward simplified ingredient lists. The Rhine-Ruhr metropolitan cluster hosts centralized distribution hubs that consolidate Italian supply into broadline foodservice networks serving hospital and school catering accounts.
United States
Asian fusion menu expansion in independent restaurants drives fresh noodle demand through specialty distributors previously focused on dry pasta. FDA pasteurization standards for egg-based formulations create compliance barriers for European exporters, favoring domestic producers with integrated HPP processing. The New York metropolitan area anchors premium retail placement, while Los Angeles supports direct-to-restaurant channels for chef-specified custom dimensions.
France
Gourmet retail banners emphasize short ingredient lists and regional provenance labeling for fresh pasta placement in Parisian specialty stores. DGCCRF enforcement of EU 1169/2011 intensified unannounced audits of semolina origin documentation during 2024, accelerating reformulation costs for filled pasta categories. The Lyon gastronomic cluster concentrates artisan producer aggregation platforms that displace traditional broadline distributors for premium restaurant accounts.
Canada
Health Canada oversight aligns with FDA pasteurization benchmarks, enabling cross-border supply integration from US production facilities into Toronto and Vancouver retail. Provincial food safety authorities in Ontario and British Columbia maintain distinct cold-chain inspection protocols that extend market entry timelines for European exporters. The Greater Toronto Area hosts the dominant refrigerated distribution infrastructure for national supermarket chain replenishment.
Italy
Domestic production retains volume leadership through automated sheeting lines and bronze-die extrusion traditions concentrated in Emilia-Romagna and Lombardy. Updated EU 1169/2011 implementation through the Ministry of Health's National Food Safety Authority pushes producers toward cleaner declarations for prepacked formats. The Parma food valley cluster integrates semolina milling, egg processing, and chilled distribution within a 50-kilometer radius, compressing cost structures for export-competitive pricing.
Fresh Pasta Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Consolidation pressure concentrates among scale-driven manufacturers with national refrigerated distribution networks, while artisan specialists retain chef relationships through customizable production runs. Three archetypes dominate: vertically integrated mill-to-retail operators, flexible co-manufacturers serving white-label demand, and heritage-brand positioners emphasizing regional recipe authenticity. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing long-term durum supply contracts or aligning with meal-kit assemblers for recurring volume commitments.
Among Italian heritage-brand positioners, Giovanni Rana and De Cecco exemplify divergent strategic anchors. Rana occupies a position emphasizing regional kitchen formats and recipe authenticity for premium retail placement. De Cecco represents upstream control over semolina sourcing, extending durum supply networks into Southern Italian growing regions. Barilla anchors the scale-driven tier with automated sheeting infrastructure sustaining volume leadership across European retail channels. These three entities collectively illustrate the competitive spectrum from artisan craft positioning to industrial cost leadership.
| Leading Market Players |
|---|
| Rana |
| Buitoni |
| Barilla |
| Voltan SpA |
| Lilly's Fresh Pasta |
| Giovanni Rana |
| Pastificio Gaetarelli |
| Pastificio Di Martino |
| De Cecco |
| Others |
Supply Flow & Price Mechanics
The Rhine-Ruhr logistics corridor compresses freight costs for Italian exporters while amplifying price differentiation between mass-market supermarket tiers and premium direct-to-restaurant channels. Cold-chain infrastructure concentration in this cluster enables volume producers to defend margin structures through consolidated distribution, whereas secondary city penetration demands higher per-unit delivery premiums that strain economy-tier positioning.
Pricing Analysis
Traditional bronze-die extrusion commands sustained premiums against automated sheeting lines, while high-pressure pasteurization investments are reshaping price architecture through extended shelf-life claims. Three-tier pricing structure across premium, standard, and economy levels stratifies by semolina grade and provenance documentation, with EU 1169/2011 compliance costs accelerating price erosion in filled pasta categories carrying complex ingredient lists. Cost compression in economy retail tiers intensifies because of durum wheat price volatility, while foodservice buyers exhibit lowest price sensitivity due to menu premiumization pass-through mechanics.
Supply Chain Analysis
Flexible co-manufacturers in Emilia-Romagna, Lombardy, and Parma's food valley cluster hold dominant capacity for white-label production serving restaurant chains and meal-kit assemblers. Semolina milling draws from Southern Italian durum networks, egg processing rests on regional poultry supply integration, and chilled distribution feeds from metropolitan logistics hubs. Single-source vulnerability concentrates in bronze-die craftsmanship scarcity as skilled operators retire. Distribution runs through broadline foodservice networks, direct-to-consumer subscription platforms, and supermarket refrigerated cases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fresh pasta penetration in North American foodservice channels sits at early-cycle expansion, with Asian fusion menu adoption pulling volume through distributors previously anchored to dry pasta. Subscription mechanics and chef-specified customization are accelerating household and restaurant conversion simultaneously.
For Market Incumbents: Entrench supply security through long-term durum contracts in Southern Italian growing regions and backward integration into captive egg processing. Barilla-scale automated infrastructure faces substitution pressure from artisan-automation hybrids; defend through HPP line investments that extend shelf life without texture degradation. Channel control via meal-kit assembler partnerships secures recurring volume commitments against direct-to-restaurant platform disintermediation.
For New Entrants and Emerging Players: Secondary Canadian markets outside Toronto and Vancouver present underpenetration for European exporters with vacuum-sealed export formats. Target Ontario and British Columbia provincial regulatory pathways as the most penetrable entry corridor, leveraging Health Canada-FDA alignment on pasteurization benchmarks. Go-to-market angle: specialty foodservice platforms aggregating regional artisan producers for chef-specified custom dimensions.
For Investors and Strategic Acquirers: Heritage-brand positioners with regional recipe authenticity and existing bronze-die craftsmanship represent the priority acquisition archetype for portfolio premiumization. Long-term viability hinges on clean-label reformulation capabilities and direct-to-consumer chilled fulfillment infrastructure. Signal to monitor: BIS certification completion timelines for European producers targeting Indian retail expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| HPP Processing Line Deployment | Extends refrigerated shelf stability for direct-to-consumer channels without thermal texture degradation. |
| Backward Integration into Durum Supply | Captures semolina margin and insulates against North African harvest cycle volatility. |
| Meal-Kit Assembler Partnership | Secures recurring volume commitments through weekly delivery bundle integration. |
| Clean-Label Reformulation | Addresses EU 1169/2011 compliance costs while unlocking allergen-sensitive segment access. |
| Foodservice Platform Aggregation | Displaces traditional broadline distributors for premium chef relationship capture. |
Methodological Framework
Operator-level perspectives from pasta production managers, foodservice procurement directors, chilled logistics coordinators, and retail category buyers anchored the qualitative base. Primary interview insights combined with secondary validation from EU food safety authority enforcement records, FDA pasteurization guidance documents, customs trade data for semolina and fresh pasta flows, and refrigerated distribution infrastructure databases. Bottom-up volume modeling across product formats and channels triangulated against top-down market sizing from trade association publications and production facility capacity disclosures.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning product type, distribution channel, end-user application, and regional cold-chain maturity. CAGRs derived from fitted growth curves adjusted for regulatory implementation timelines and infrastructure buildout patterns. Industry-specific forecast inputs incorporated chef menu adoption surveys for Asian fusion applications and subscription service churn metrics for direct-to-consumer channels.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by automated sheeting specialists or rapid BIS certification completion by European exporters would shift outcomes. Quarterly review of durum wheat futures pricing, chilled last-mile logistics startup formation rates, and foodservice platform transaction volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
South America Processed Meat Market
Processed Foods
Processed Eucheuma Seaweed Market
Processed Foods
Imitation Whipped Cream Market
Processed Foods
Europe Processed Egg Market
Processed Foods
Apple Butter Market
Processed Foods
Middle East and Africa Processed Meat Market
Processed Foods
Low Moisture Food Market
Processed Foods
Spreadable Fats Market
Processed Foods
Porridge Market
Processed Foods
Low Fat Pasta Market
Processed Foods
Global Dried Processed Food Market
Processed Foods
North America Ice Cream Market
Processed Foods
Europe Egg Powder Market
Processed Foods
Africa Soup Market
Processed Foods
Chocolate Filling Market
Processed Foods
Processed Potatoes Market