
 Africa Soup Market | 2026-2036
Africa Soup Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Soup Market Outlook
Asset-light distributor financing is fragmenting competitive access across African soup markets. Unilever PLC leverages its pan-African logistics network to sustain shelf presence in fragmented retail. Nestle SA anchors instant soup segments through manufacturing scale in Côte d'Ivoire and Kenya. Imana Foods competes on localized flavor profiles that dominate South African and neighboring markets.
Africa soup comprises water-based liquid or semi-liquid food preparations, typically thermally processed at 85–121°C for commercial sterility, containing vegetables, proteins, or grains as primary solids, packaged in cans, pouches, or cups for ambient or chilled distribution. The category serves household meal replacement, food service portion control, and institutional feeding programs. Instant soup leads volume due to low unit price and minimal preparation requirements, while organic soup captures emerging margin pools among health-conscious urban consumers. Dehydrated soup sustains rural penetration where cold-chain gaps persist, and ready-to-eat formats gain traction in quick-service restaurant supply.
National food safety regulators in Nigeria, Kenya, and South Africa enforce progressively stricter labeling, additive, and shelf-life standards that favor formal manufacturers over informal producers. CODEX Alimentarius guidelines and national bureau of standards frameworks shape import compliance for multinational suppliers. Stakeholders must monitor evolving local content requirements and certification costs that determine market access trajectories across the continent's diverse regulatory landscapes.
Market Dynamics
Retail cold-chain infrastructure expansion across Lagos, Nairobi, and Accra is compressing shelf-life requirements and forcing formal manufacturers to displace informal vendors through FSSAI-equivalent compliance investments.
Growth Catalysts
- Urban working-class demand:Dual-income households in West and East African cities seek protein-enriched meal replacements that reduce cooking time.
- Standards harmonization:CODEX Alimentarius-aligned national food safety regimes in Nigeria, Kenya, and South Africa tighten labeling mandates that favor packaged over unpackaged soup.
- Dehydrated formats:Cold-chain gaps in rural Africa sustain penetration of ambient-stable soup powders requiring only boiling water.
Market Restraints
- Import input volatility:Wheat and dairy powder costs fluctuate with currency depreciation in Nigeria and Kenya, compressing margin structures for soup manufacturers.
- Informal vendor density:Unregulated street vendors in Lagos and Accra undercut formal pricing by 40-60 percent through unlabeled bulk sales.
- Refrigeration infrastructure gaps:Ready-to-eat chilled soup formats face distribution radius constraints outside South Africa's urban corridors.
Strategic Opportunities
- Ethiopia and Tanzania penetration:These East African markets show underdeveloped formal retail soup presence relative to Kenya's maturing channels.
- Quick-service restaurant supply:Portion-controlled soup cups are displacing in-house preparation for African fast-casual chains.
- Organic certification tailwinds:South Africa's Department of Agriculture, Land Reform and Rural Development incentivizes organic production through export market access programs.
Industry Challenges
- Food technologist scarcity:Formulation expertise for thermal processing at 85–121°C commercial sterility thresholds concentrates in South Africa and Kenya.
- Label compliance timelines:Nigeria's National Agency for Food and Drug Administration and Control extends approval cycles for imported soup additives.
- Legacy distributor fragmentation:Asset-light financing models fragment route-to-market control, complicating inventory visibility for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Soup Market |
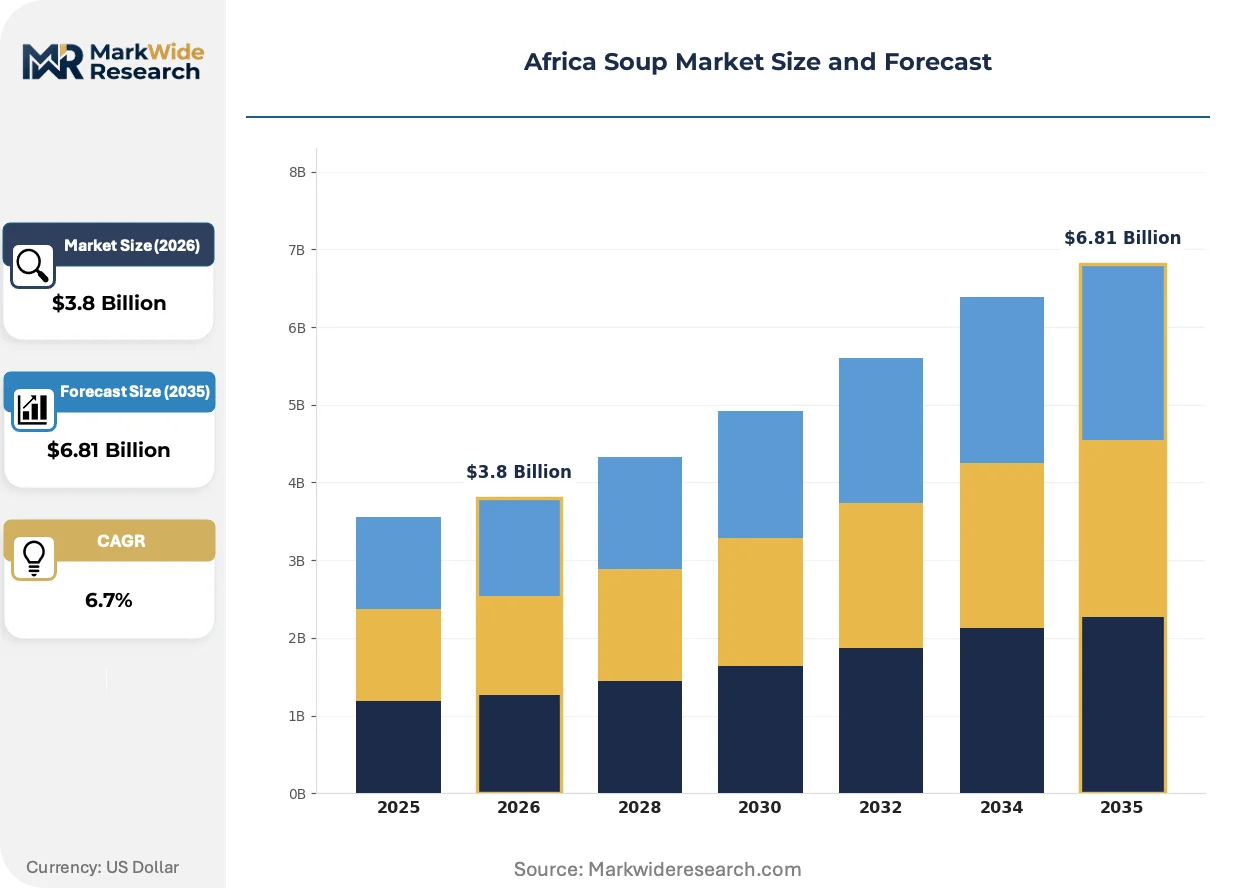
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Soup, Ready-to-Eat Soup, Dehydrated Soup, Organic Soup Ingredient Type: Vegetable Base, Meat Base, Fish Base, Grain Base End User: Households, Restaurants, Food Service, Meal Kit Providers Flavor Profile: Spicy, Savory, Mild, Traditional |
| Companies Covered | The Kraft Heinz Company, General Mills Inc, Unilever PLC, Baxter's Food Group, Mars Incorporated, Nestle SA, Conagra Brands Inc, Imana Foods, The Campbell Soup Company, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Soup Market Strategic Shifts
Thermal processing advances and regulatory alignment are compressing production economics while urban consumption patterns pivot toward convenience formats that minimize preparation steps.
Retort pouch technology is hybridizing with traditional canning methods to reduce packaging weight and energy inputs during sterilization. Mid-tier manufacturers in Kenya and Côte d'Ivoire are adopting hybrid lines that switch between pouch and can formats based on export destination requirements. This flexibility is compressing capital intensity barriers for regional players seeking South African retail listings.
South Africa's Department of Health is enforcing stricter additive disclosure rules that mirror EFSA precautionary principles on sodium and preservative thresholds. Manufacturers must reformulate legacy recipes or face delisting from Shoprite and Pick n Pay shelves. The instant soup segment bears the highest compliance burden due to concentrated flavoring systems.
Urban consumers in Lagos and Nairobi are consolidating weekly grocery trips into monthly stock-up visits at formal supermarkets. This pattern shift elevates multi-serve soup formats over single-serve cups. Quick-service restaurants in Accra are responding by unbundling soup from combo meals, enabling à la carte procurement that mirrors household bulk-buying behavior.
Africa Soup Market Segmentation
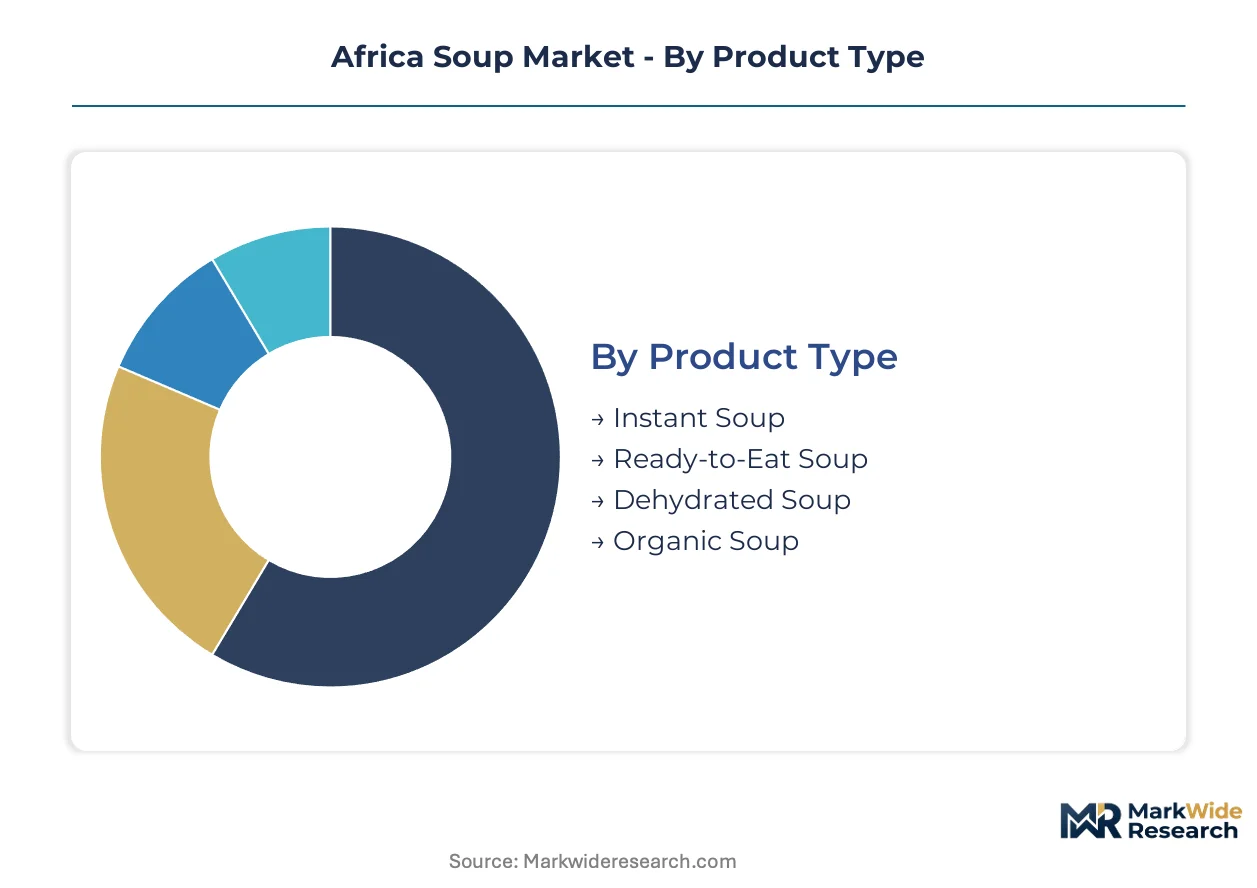
African soup manufacturers configure production lines around format stability and preparation speed. Cycle times vary dramatically: instant formats turn inventory weekly while organic SKUs sit for months awaiting certification clearance.
Product Type:
Inventory velocity separates formats that ship daily from those that warehouse for extended certification cycles.
- Instant Soup:Spray-dried or freeze-dried concentrates reconstitute with boiling water in under three minutes. Lagos and Nairobi working-class households purchase these in bulk during monthly supermarket stock-ups, compressing replenishment cycles to days rather than weeks.
- Ready-to-Eat Soup:Thermally processed at 85–121°C for commercial sterility and packaged in retort pouches or cans. South African quick-service restaurants source portion-controlled cups for combo meal unbundling, though cold-chain gaps outside urban corridors constrain distribution radius.
- Dehydrated Soup:Ambient-stable powders sustain rural penetration where refrigeration infrastructure remains sparse.
- Organic Soup:Certified ingredient sourcing and extended shelf-life testing elongate production-to-shelf timelines significantly.
Instant Soup dominates installed base. Ready-to-Eat Soup is where expansion concentrates.
Ingredient Type:
Raw material sourcing costs stratify segments between locally available inputs and import-dependent proteins.
- Vegetable Base:Tomato, onion, and indigenous greens formulations leverage Nigeria and Kenya's agricultural output. Urban households seeking meat-free protein alternatives are elevating this segment's share in Accra and Nairobi formal retail.
- Meat Base:Beef and chicken extracts require cold-chain integrity from abattoir to processing plant. Currency depreciation in Nigeria and Kenya compresses margin structures for manufacturers reliant on imported dairy and wheat adjuncts.
- Fish Base:Coastal West African supply chains anchor smoked and dried fish soup traditions.
- Grain Base:Millet, sorghum, and maize thickeners align with Sahelian dietary patterns.
Vegetable Base commands volume leadership. Meat Base carries the steepest expansion trajectory among protein-enriched formats.
End User:
Procurement patterns diverge between fragmented household purchasing and consolidated institutional contracts.
- Households:Dual-income urban families in Lagos, Nairobi, and Accra drive demand for convenient meal replacements that reduce evening cooking time. Monthly stock-up visits to formal supermarkets favor multi-serve formats over single-serve cups.
- Restaurants:Quick-service chains in Accra are unbundling soup from combo meals, enabling à la carte procurement that mirrors household bulk-buying behavior while displacing in-house preparation.
- Food Service:Institutional feeding programs require portion-controlled packaging and extended shelf stability.
- Meal Kit Providers:Emerging subscription services in South African metros integrate soup bases into weekly recipe boxes.
Households anchor revenue concentration. Restaurants are gaining share fastest as formal dining chains expand across West African cities.
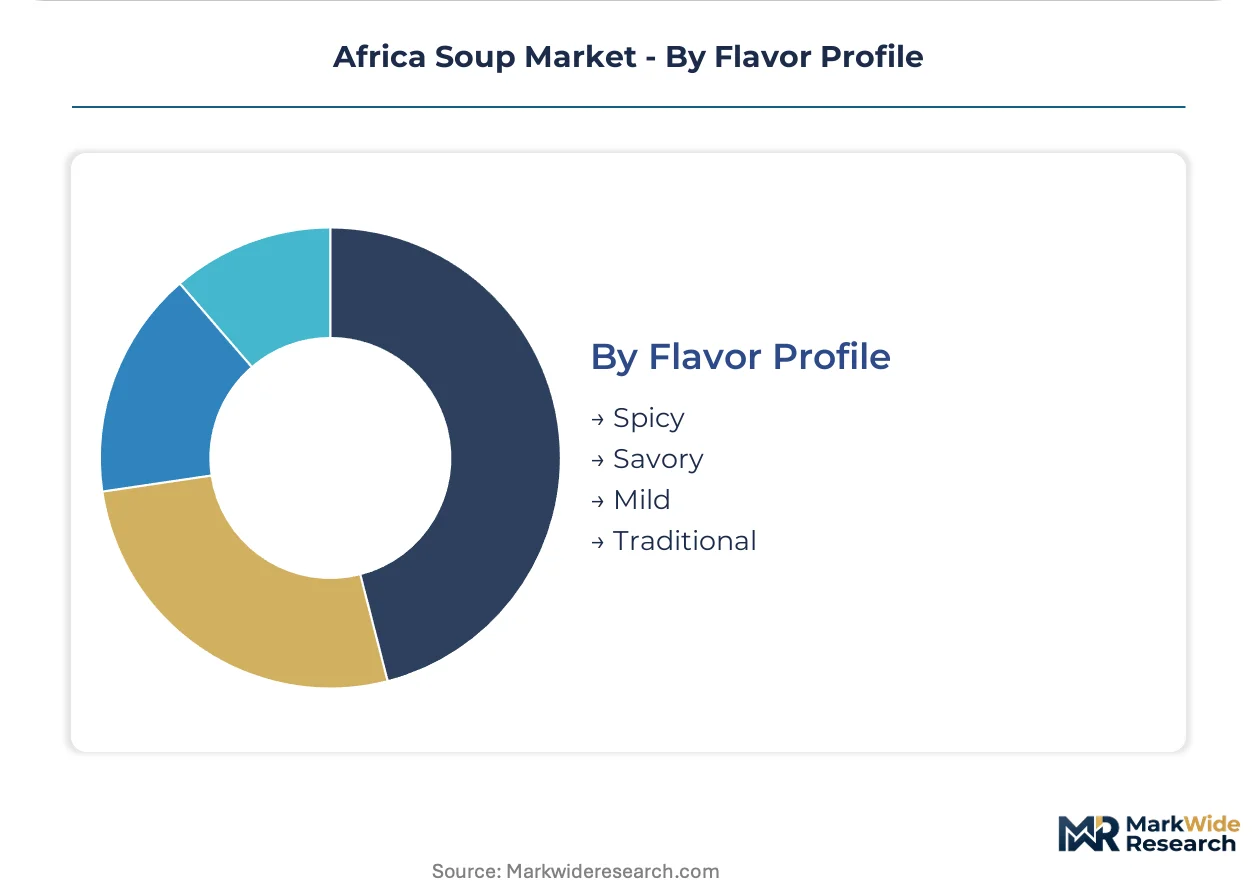
Flavor Profile:
Localization requirements create formulation complexity that favors regional specialists over standardized multinational recipes.
- Spicy:Chili, ginger, and pepper formulations dominate West African markets where heat tolerance runs high. Imana Foods and comparable regional players compete through localized profiles that multinational brands struggle to replicate.
- Savory:Umami-rich stocks using fermented locust beans or dried fish align with traditional preparation methods. South African retail shelves carry the broadest savory range due to mature formal distribution infrastructure.
- Mild:Reduced sodium and gentle seasoning target health-conscious segments and pediatric consumption.
- Traditional:Indigenous recipes using specific herb and spice combinations vary by ethnic group and geography.
Spicy profiles command West African shelf space. Savory formats are climbing the fastest as urban consumers seek depth without extreme heat.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for wheat and dairy powders shapes competitive positioning across African soup markets, while formal retail expansion in coastal cities accelerates local manufacturing investment. Export-oriented producers in South Africa and Kenya supply neighboring markets with retort-processed formats. Cold-chain gaps in interior regions sustain dehydrated powder penetration where ambient stability dominates procurement decisions.
Nigeria
Lagos working-class households drive demand for protein-enriched instant soups that reduce evening cooking time. The National Agency for Food and Drug Administration and Control enforces progressively stricter additive disclosure and shelf-life labeling mandates. Manufacturing clusters in Lagos State and Ogun State attract Unilever and Nestle production facilities serving West African distribution networks.
South Africa
Quick-service restaurant chains in Johannesburg and Cape Town displace in-house soup preparation with portion-controlled ready-to-eat procurement. The Department of Agriculture, Land Reform and Rural Development incentivizes organic certification through export market access programs. Industrial processing corridors in Gauteng and Western Cape concentrate thermal sterilization expertise and food technologist talent pools.
Kenya
Nairobi dual-income families favor multi-serve formats during monthly supermarket stock-up visits. Kenya Bureau of Standards aligns domestic labeling requirements with CODEX Alimentarius guidelines for import compliance. Manufacturing zones in Nairobi and Mombasa anchor Nestle regional production serving East African retail expansion into Tanzania and Ethiopia.
Ghana
Accra urban consumers consolidate grocery trips into formal supermarket visits that elevate packaged soup over informal vendor alternatives. Food and Drugs Authority enforcement tightens standards on unlabeled bulk sales that previously undercut formal pricing. Tema industrial enclave hosts emerging domestic processors competing with Nigerian imports for shelf space.
Ethiopia
Addis Ababa's emerging middle class generates nascent demand for convenient meal replacement formats as formal retail infrastructure develops. Ethiopian Food and Drug Authority builds regulatory capacity for packaged food standards harmonization with regional benchmarks. Industrial parks around Addis Ababa attract foreign investment targeting underpenetrated East African markets beyond Kenya's maturing channels.
Africa Soup Market Competitive Environment
On the supply side, the industry is consolidating around multinational manufacturing scale and regional flavor localization specialists. Tiered competitive dynamics separate pan-African logistics networks from country-specific formulation expertise. Three archetypes dominate: multinational FMCG conglomerates with integrated distribution, regional specialists leveraging indigenous taste profiles, and emerging domestic processors capturing formal retail slots. Capacity expansion and portfolio diversification represent the dominant competitive moves as players position for standards harmonization.
Within the multinational tier, Unilever PLC and Nestle SA exemplify scale-driven manufacturing anchoring. Unilever leverages pan-African logistics infrastructure to sustain shelf presence across fragmented retail environments. Nestle occupies a position exemplifying regional production concentration in Côte d'Ivoire and Kenya. Among localization specialists, Imana Foods represents the archetype of flavor-profile differentiation that dominates South African and neighboring markets through indigenous recipe adaptation.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| General Mills Inc |
| Unilever PLC |
| Baxter's Food Group |
| Mars Incorporated |
| Nestle SA |
| Conagra Brands Inc |
| Imana Foods |
| The Campbell Soup Company |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in South African thermal processing facilities is compressing lead times for retort sterilization services and elevating pricing power among Gauteng-based contract manufacturers serving Nigerian and Kenyan brand owners.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the Africa soup market. Price differentiation hinges on CODEX Alimentarius certification tier and volume scale commitments from quick-service restaurant chains. Cost compression in economy-tier instant soup is intensifying because currency depreciation in Nigeria and Kenya inflates imported wheat and dairy powder costs. Street vendor alternatives in Lagos and Accra maintain the highest price sensitivity, while South African supermarket chains exhibit lowest sensitivity due to organic certification premiums.
Supply Chain Analysis
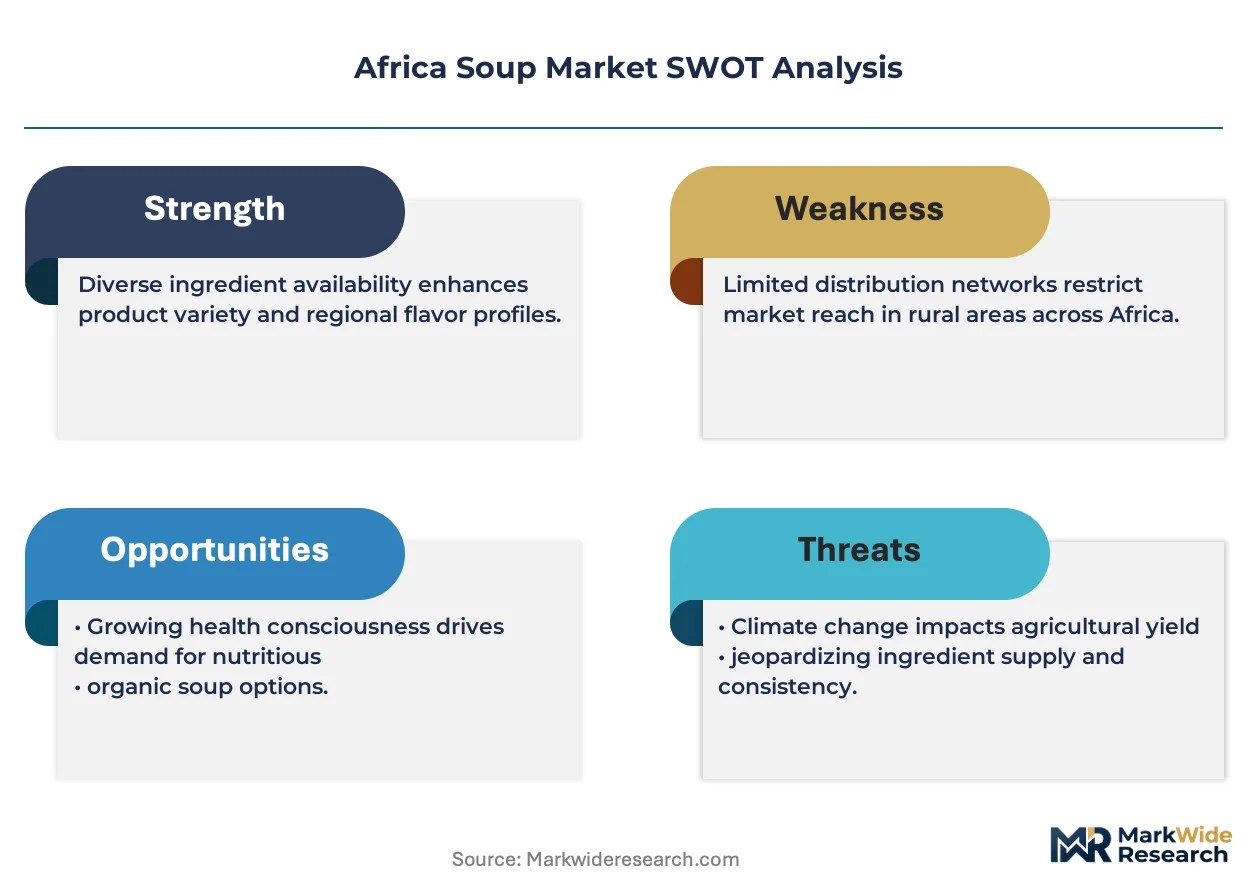
Upstream feedstock flows from South Africa, Kenya, and Côte d'Ivoire concentrate thermal processing capacity and flavor formulation expertise. Wheat powder, dairy proteins, and indigenous spice blends constitute critical input dependencies for protein-enriched formats. Single-source vulnerability runs through Nigerian manufacturing clusters dependent on Lagos Port cold-chain infrastructure. Distribution runs through asset-light distributor networks that fragment inventory visibility across West and East African retail corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa soup market is exiting a cyclical trough as urban working-class demand in Lagos, Nairobi, and Accra accelerates formal retail penetration and displaces informal vendor volume.
For Market Incumbents: Insulate margin structures by securing backward integration into indigenous spice supply chains and expanding thermal processing capacity in Kenya's industrial zones. Threat from unregulated street vendors undercutting formal pricing by 40-60 percent demands CODEX-aligned certification investment as a defensive moat. For New Entrants and Emerging Players: Build out Ethiopia and Tanzania penetration before Kenyan channels mature, targeting dehydrated soup formats that bypass cold-chain gaps. Quick-service restaurant supply contracts in Accra offer the most penetrable entry vector through à la carte procurement relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional flavor localization specialists with entrenched South African retail shelf presence. Long-term viability over a 5-10 year window favors acquisition targets with organic certification pipelines and export market access programs. Monitor NAFDAC and Kenya Bureau of Standards approval cycle extensions as early signals of regulatory barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Retort Pouch Manufacturing Scale-Up | Hybrid pouch-can lines in Kenya and Côte d'Ivoire compress capital intensity for South African retail listings. |
| Backward Integration into Indigenous Spices | Captive supply of fermented locust beans and dried fish extracts shields margin from import volatility. |
| CODEX Certification Investment | NAFDAC-aligned labeling compliance displaces informal vendors from Lagos supermarket shelves. |
| Quick-Service Restaurant Supply Partnership | Portion-controlled cup formats for Accra chains displace in-house soup preparation. |
| Organic Certification Pipeline | South Africa's Department of Agriculture export incentives unlock premium pricing in health-conscious urban segments. |
Study Parameters
Initial hypotheses were tested against primary input from brand managers at multinational FMCG conglomerates, category buyers at Shoprite and Pick n Pay, channel sales heads across Lagos distributor networks, and supply planners at Kenyan manufacturing zones, then refined against secondary validation from customs and trade data, Kenya Bureau of Standards filings, Nielsen retail audit data, and SEC 10-K disclosures from listed parent companies, with bottom-up and top-down triangulation across volume and value estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product format stability, ingredient base sourcing, end-user procurement pattern, and flavor profile localization. CAGRs were derived from rolling average growth trajectory analysis incorporating urban household income elasticity, cold-chain infrastructure rollout pace, and regulatory compliance cost escalation as industry-specific forecast inputs.
Practitioners should monitor NAFDAC additive approval extensions, Kenya Bureau of Standards labeling mandate revisions, and currency depreciation spikes in Nigeria and Kenya for early signals of forecast deviation. Cross-checking against WHO CODEX Alimentarius guideline updates and regional customs import volume data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Egg Powder Market
Processed Foods
Yogurt Dip Market
Processed Foods
US Tomato Paste Market
Processed Foods
Spray Cheese Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
South America Processed Meat Market
Processed Foods
North America Soup Market
Processed Foods
Noodles Market
Processed Foods
Casual Marinated Products Market
Processed Foods
Europe Processed Egg Market
Processed Foods
Processed Vegetable Market
Processed Foods
Global Potato Flake Market
Processed Foods
Fermented Foods Market
Processed Foods
Pea Processed Ingredients Market
Processed Foods
Low Fat Soups Market
Processed Foods
Sugar-Free Ice Cream Market