
 India Ready to Mix Food Market | 2026-2036
India Ready to Mix Food Market Size, Share, and Industry Trends Forecast 2026-2036
India Ready to Mix Food Market Foresight
Aftermarket recipe customization and regional flavor adaptation is tilting margin pools away from standardized national SKUs toward localized portfolio variants. MTR Foods leverages its Karnataka manufacturing base to sustain dominance in South Indian breakfast mixes. Haldiram's anchors North Indian snack and meal kit demand through controlled distribution networks. ITC Ltd. competes across multiple price tiers with extensive cold chain and modern retail partnerships.
India ready to mix food comprises dehydrated or partially pre-processed ingredient blends requiring only water, milk, or minimal fresh additions for preparation, typically employing spray-drying, freeze-drying, or blending of spice matrices with flours or grains to achieve shelf stability between six and eighteen months. The category serves time-constrained consumers seeking authentic regional cuisine without traditional preparation labor. Curry mix and dosa mix segments occupy the deepest household penetration, while soup mix trails in per-capita consumption but expands fastest among urban millennials. Pouch packaging leads volume due to cost efficiency, though jar formats command premium placement in supermarkets.
FSSAI labeling and fortification standards shape permissible additive profiles and nutritional claims across all retail channels. BIS packaging material specifications and state-level plastic waste management rules influence format selection and sustainability investments. Companies must monitor evolving e-commerce food safety notifications from regulators and anticipate stricter sodium and preservative thresholds in forthcoming amendments.
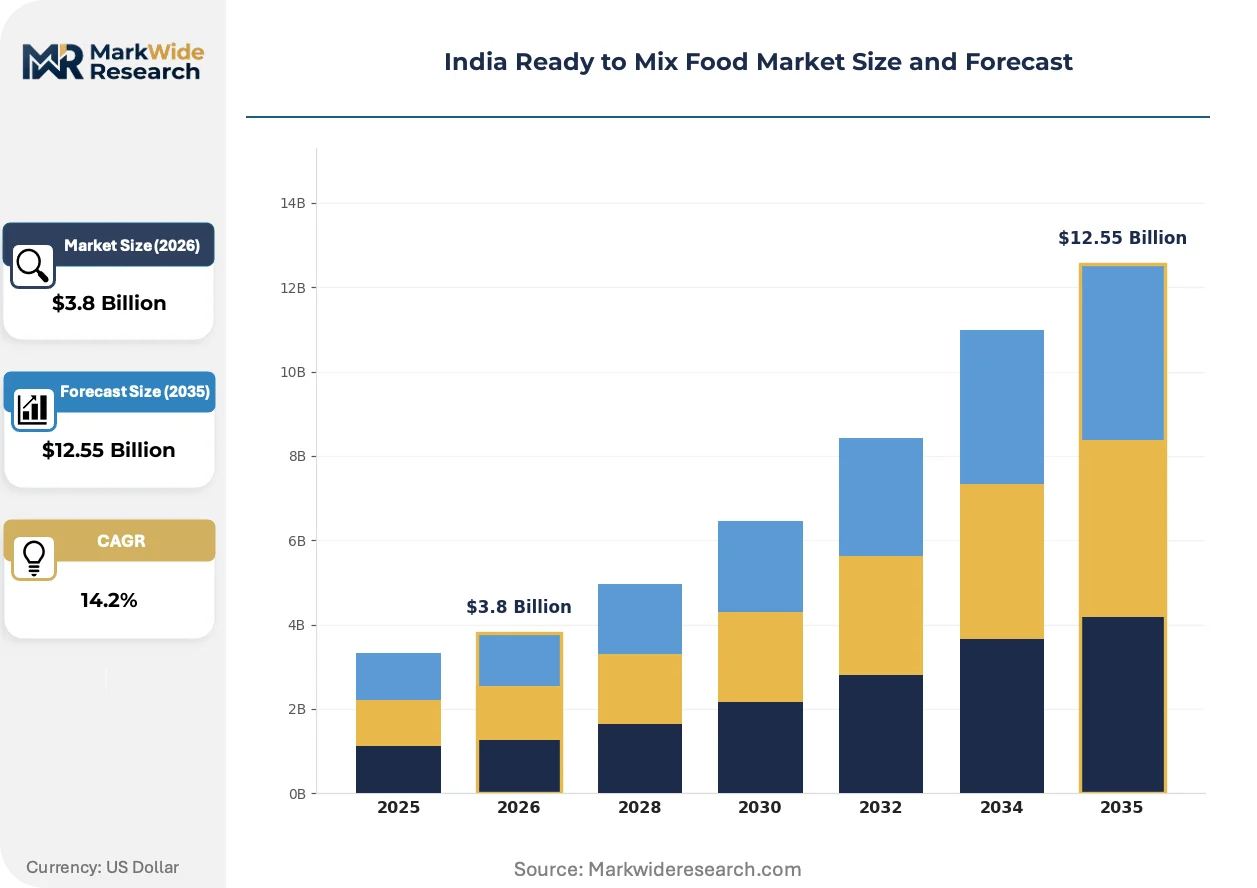
Market Dynamics
FSSAI fortification mandates and BIS packaging specifications are compressing formulation flexibility while accelerating clean-label R&D cycles across Maharashtra and Karnataka manufacturing clusters.
Growth Catalysts
- Dual-income urbanization:Nuclear households in Bengaluru and Mumbai prioritize time-saving meal solutions, expanding dosa and curry mix penetration beyond traditional breakfast occasions.
- FSSAI micronutrient mandates:Mandatory iron and vitamin fortification in wheat-based mixes creates differentiation opportunities for compliant manufacturers serving anganwadi and mid-day meal programs.
- Spray-drying technology maturation:Domestic equipment suppliers in Pune and Hyderabad reduce capital barriers for regional processors entering the dehydrated spice blend segment.
Market Restraints
- Input cost volatility:Turmeric and red chili prices fluctuate with monsoon patterns in Andhra Pradesh and Telangana, squeezing margin stability for masala mix producers.
- Cold chain dependency:Freeze-dried vegetable inclusions require uninterrupted refrigeration from Tamil Nadu processing hubs to northern distribution points, limiting rural reach.
- Preservative threshold compression:Draft FSSAI amendments proposing sodium reduction targets threaten shelf-life extensions currently achieved through potassium sorbate formulations.
Strategic Opportunities
- North-eastern underpenetration:Assam and Manipur present white-space demand for fermented rice batter mixes adapted to local sticky rice varieties and bamboo shoot flavor profiles.
- E-commerce direct fulfillment:Quick-commerce platforms in Gurugram and Noida enable same-day delivery of refrigerated dosa batter, bypassing traditional kirana shelf constraints.
- PLI scheme alignment:Food processing infrastructure incentives under the Production Linked Incentive scheme support automated blending and packaging line upgrades for export-ready units.
Industry Challenges
- Formulation talent scarcity:Food technologists with dual expertise in traditional spice chemistry and modern dehydration protocols command premium compensation in Hyderabad and Mumbai.
- Legacy equipment integration:Semi-automated blending lines in family-owned units resist seamless retrofit with FSSAI-mandated metal detection and batch traceability systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Ready to Mix Food Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulav Mix, Curry Mix, Soup Mix, Dosa Mix End User: Households, Restaurants, Catering Services, Food Trucks Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale Packaging Type: Bottles, Pouches, Jars, Sachets |
| Companies Covered | Haldiram’s, Priya Foods, MTR Foods, Maiyas Beverages and Foods Pvt. Ltd., Bambino Agro Industries Ltd., Gits Food Products Pvt. Ltd., Kohinoor Foods Ltd., Ushodaya Enterprises Pvt. Ltd., ITC Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Ready to Mix Food Market Shifts & Advancements
Clean-label dehydration technologies and regional flavor micro-segmentation are fragmenting the standardized national SKU model that dominated the previous decade.
Freeze-drying equipment with modified atmosphere packaging is rendering obsolete conventional hot-air dehydration for premium vegetable inclusions. South Indian breakfast mix manufacturers in Bengaluru and Chennai adopt these systems to preserve color intensity in drumstick and curry leaf powders. The technology is rendering obsolete six-month shelf-life limitations, enabling eighteen-month stability claims that command modern retail placement.
FSSAI's proposed front-of-pack labeling regulations will mandate nutritional disclosure thresholds for sodium, sugar, and saturated fat content across all retail channels. Reformulation costs will concentrate among mid-tier processors lacking in-house analytical laboratories. Clean-label masala mixes with natural preservative systems face accelerated approval timelines compared to synthetic additive alternatives.
Quick-commerce platforms are compressing traditional distributor networks for perishable batter and fermented mix categories. Urban millennials in Pune and Hyderabad now source idli-dosa batter through thirty-minute delivery apps rather than weekly kirana purchases. This channel rotation forces manufacturers to reconfigure production scheduling toward small-batch, high-frequency fulfillment patterns.
India Ready to Mix Food Market Segmentation
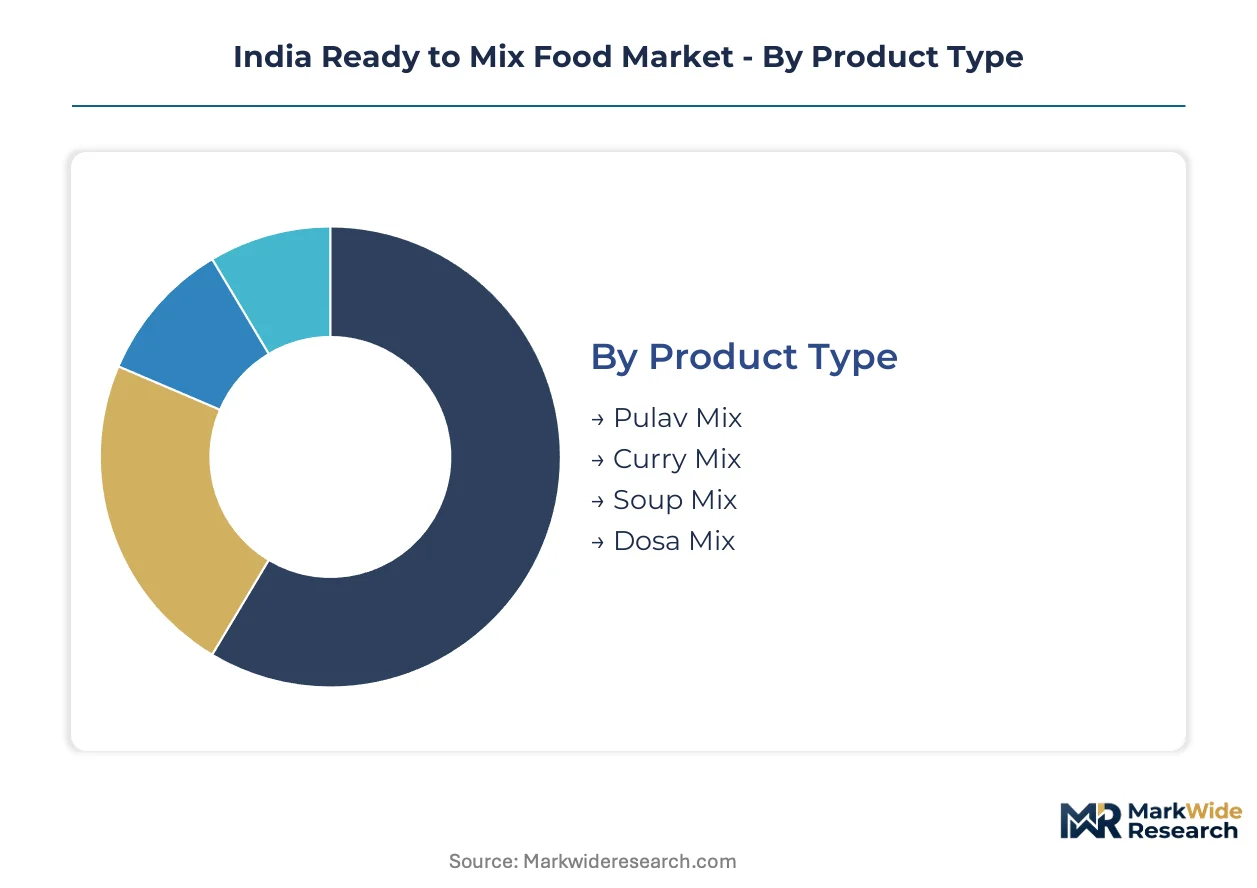
Segmentation in India's ready to mix food market reveals distinct margin profiles and service intensity requirements across product categories. Each dimension exposes divergent growth trajectories and regulatory exposure zones that shape portfolio allocation decisions.
Product Type:
After-sales service intensity varies sharply across product types, with fermented batter mixes requiring cold chain support and dehydrated spice blends demanding minimal post-purchase intervention.
- Curry Mix:Dehydrated spice and vegetable matrices blended with roasted gram flour or coconut powder for instant gravy preparation. Maharashtra and Karnataka households drive volume through daily dinner applications, though FSSAI fortification mandates are compressing formulation flexibility for wheat-thickened variants.
- Dosa Mix:Fermented rice and urad dal flours requiring water addition and brief resting for traditional breakfast preparation. Bengaluru and Chennai urban millennials source through quick-commerce platforms, bypassing kirana shelf constraints entirely.
- Pulav Mix:Whole spice and dehydrated vegetable blends targeting single-pot rice preparations.
- Soup Mix:Freeze-dried vegetable and broth powder combinations with shorter purchase cycles among metro office workers.
Curry Mix holds the largest share; momentum sits with Dosa Mix.
End User:
Cost tier stratification separates premium ingredient sourcing for foodservice from economy formulations targeting household price sensitivity.
- Households:Individual and nuclear family units purchasing through modern retail and e-commerce channels for convenience-driven meal solutions.
- Restaurants:Commercial kitchens in Mumbai and Hyderabad leveraging standardized mixes for consistency across outlet networks.
- Catering Services:Bulk procurement units serving weddings and institutional events in Gujarat and Rajasthan with large-format packaging requirements.
- Food Trucks:Mobile vendors in Gurugram and Noida prioritizing shelf-stable inventory with minimal refrigeration dependency.
Households dominate volume; Catering Services are expanding most quickly through event-sector recovery.
Distribution Channel:
Volume concentration tilts toward traditional trade, though margin accretion concentrates in emerging channels with direct manufacturer relationships.
- Supermarkets:Organized retail chains in Pune and Bengaluru commanding premium placement fees for jar formats and clean-label variants.
- Online Retail:Platform-agnostic e-commerce and quick-commerce aggregators enabling same-day delivery of perishable batter categories.
- Convenience Stores:Urban kirana networks with limited SKU depth but high purchase frequency for impulse curry mix acquisitions.
- Wholesale:Bulk distribution corridors connecting Tamil Nadu manufacturing clusters to northern tier-two city distributors.
Supermarkets anchor value capture; Online Retail shows steepest expansion trajectory.
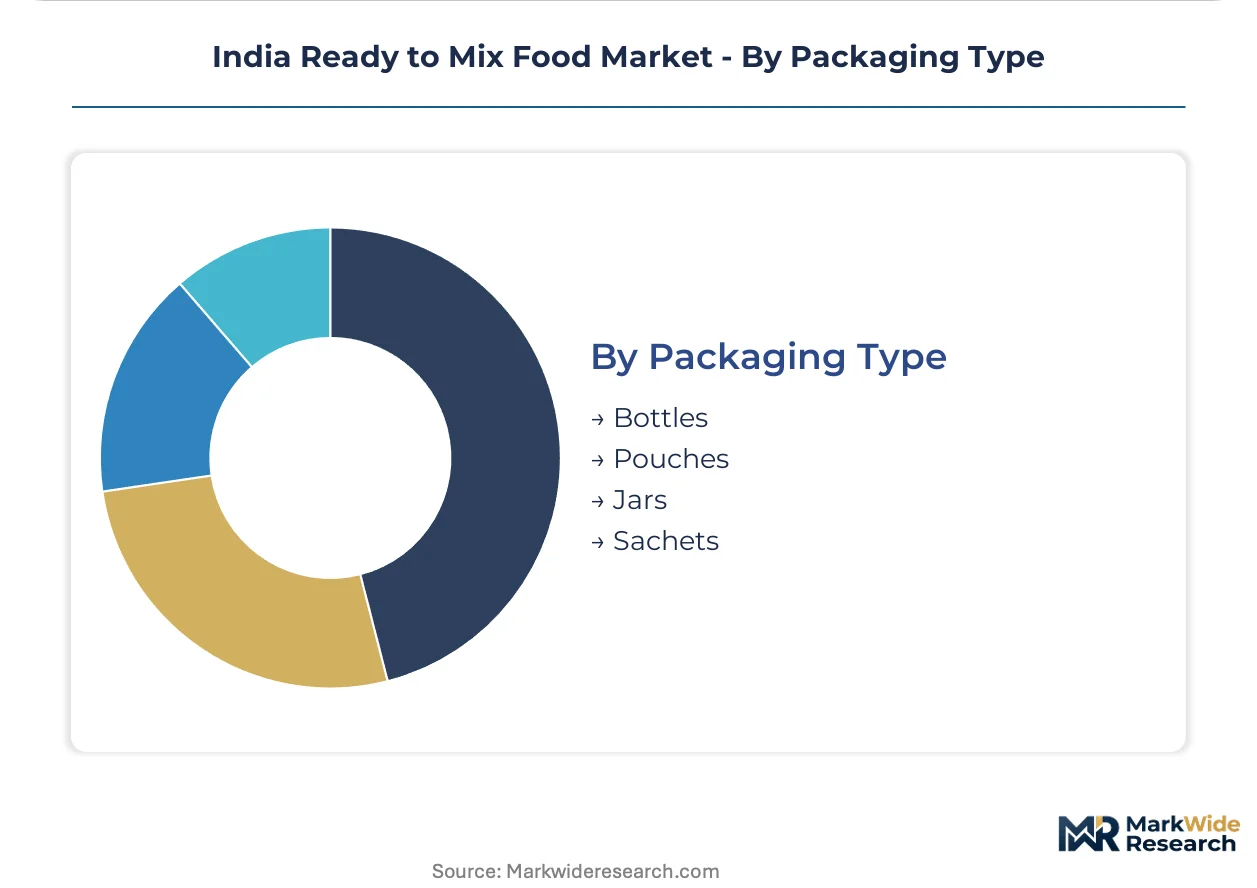
Packaging Type:
Supply concentration in flexible packaging manufacturing around Ahmedabad and Vadodara shapes format availability and cost structures.
- Pouches:Multi-layer polymer laminates with six-to-twelve month barrier protection for mass-market curry and pulav mixes.
- Jars:Glass or PET rigid containers commanding premium shelf positioning in modern retail with resealability for intermittent use patterns.
- Sachets:Single-serve foil laminates targeting trial purchases and travel consumption occasions.
- Bottles:Rigid PET or HDPE formats for liquid batter and fermented mix categories requiring gas barrier properties.
Pouches lead volume throughput; Jars concentrate margin contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Indian states. Urban Maharashtra and Karnataka households absorb premium pricing for clean-label variants. Rural Uttar Pradesh and Bihar markets remain acutely sensitive to per-gram cost metrics.
Maharashtra
Mumbai and Pune dual-income households drive dosa mix and curry mix volume through quick-commerce channels. FSSAI fortification mandates for wheat-based products reshape formulation standards for processors serving mid-day meal programs. Nashik and Aurangabad manufacturing clusters expand spray-drying capacity for dehydrated spice blends targeting western India distribution.
Karnataka
Bengaluru urban millennials source fermented batter mixes through thirty-minute delivery apps rather than traditional retail. BIS packaging specifications for flexible laminates influence pouch format selection among Bangalore-based processors. Mysuru and Tumakuru industrial corridors anchor South Indian breakfast mix production with automated blending lines.
Tamil Nadu
Chennai foodservice operators leverage standardized mixes for consistency across outlet networks. State-level plastic waste management rules accelerate sustainable packaging investments among Coimbatore processors. Madurai and Salem manufacturing hubs specialize in freeze-dried vegetable inclusions for premium curry mix variants.
Gujarat
Ahmedabad and Vadodara flexible packaging manufacturers supply multi-layer polymer laminates to national ready-to-mix brands. PLI scheme incentives for food processing infrastructure support automated packaging line upgrades in Surat processing units. Rajkot distribution corridors connect manufacturing clusters to northern tier-two city markets.
Telangana
Hyderabad food technologists with dual expertise in spice chemistry and dehydration protocols command premium compensation. FSSAI labeling standards for nutritional disclosure reshape product development cycles among Secunderabad-based formulators. Warangal and Karimnagar procurement zones face turmeric and red chili price volatility from monsoon pattern shifts.
India Ready to Mix Food Market Competitive Landscape
Capability concentration sits with regional specialists possessing traditional recipe expertise; scale advantage sits with diversified conglomerates with cold chain and modern retail partnerships. The market structures around three tiers: heritage brands with decades of consumer trust, diversified food conglomerates with multi-category portfolios, and emerging regional processors with localized flavor adaptation. M&A activity concentrates on acquiring regional distribution networks. Portfolio diversification targets adjacent meal solution categories.
Within the heritage specialist tier, MTR Foods and Haldiram's occupy positions defined by geographic origin and category focus. MTR Foods exemplifies South Indian breakfast mix concentration through its Karnataka manufacturing base. Haldiram's anchors North Indian snack and meal kit demand through controlled distribution networks. ITC Ltd. sits within the diversified conglomerate archetype, competing across multiple price tiers with extensive retail partnerships.
| Leading Market Players |
|---|
| Haldiram's |
| Priya Foods |
| MTR Foods |
| Maiyas Beverages and Foods Pvt. Ltd. |
| Bambino Agro Industries Ltd. |
| Gits Food Products Pvt. Ltd. |
| Kohinoor Foods Ltd. |
| Ushodaya Enterprises Pvt. Ltd. |
| ITC Ltd. |
| Others |
Supply & Pricing Matrix
Nashik and Aurangabad manufacturing clusters anchor spray-drying capacity for dehydrated spice blends, concentrating upstream supply power among processors serving western India distribution corridors. This geographic concentration enables volume-based pricing leverage for turmeric and chili-based masala mixes while compressing margin flexibility for smaller regional formulators lacking captive drying infrastructure.
Pricing Analysis
After-sales recipe customization and regional flavor adaptation drives lifetime value beyond initial pouch purchases. Three-tier pricing structure across premium, standard, and economy levels separates clean-label jar formats with natural preservative systems from mass-market sachets with synthetic additives. Price differentiation hinges on fortification compliance costs and cold chain service bundling for fermented batter categories. Pricing pressure stems from FSSAI's proposed sodium reduction mandates threatening shelf-life extensions currently achieved through potassium sorbate formulations. Rural Uttar Pradesh and Bihar households exhibit acute per-gram cost sensitivity, while Mumbai and Bengaluru dual-income units absorb premium positioning for clean-label variants.
Supply Chain Analysis
BIS packaging specifications for flexible laminates function as de facto export-control barriers limiting unqualified processor participation. Raw material sourcing concentrates in Andhra Pradesh and Telangana for turmeric and red chili, with secondary dependence on Tamil Nadu for freeze-dried vegetable inclusions. Supply chain risk centers on monsoon-driven commodity price volatility squeezing margin stability for masala mix producers. Distribution runs through wholesale corridors connecting Tamil Nadu manufacturing hubs to northern tier-two city distributors, with quick-commerce platforms emerging as parallel direct-to-urban channels bypassing traditional kirana networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India ready to mix food market rewards processors possessing rare hybrid expertise in traditional spice chemistry and modern dehydration protocols, creating acute talent scarcity that constrains formulation capacity expansion.
For Market Incumbents: Pre-empt margin erosion from clean-label reformulation mandates by securing in-house analytical laboratories ahead of FSSAI's front-of-pack labeling rollout. Acquire regional distribution networks in Assam and Manipur to lock out emerging competitors targeting north-eastern white-space demand for fermented rice batter mixes adapted to local sticky rice varieties. For New Entrants and Emerging Players: Build out quick-commerce direct fulfillment capabilities in Gurugram and Noida, where same-day delivery of refrigerated dosa batter bypasses traditional kirana shelf constraints entirely. Target catering services recovery in Gujarat and Rajasthan with large-format packaging for wedding and institutional event procurement. Anchor initial positioning through PLI scheme-aligned automated blending line investments qualifying for food processing infrastructure incentives. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regional specialists with decades of consumer trust in traditional recipe expertise command scarcity premiums amid M&A activity concentrating on distribution network acquisition. Target family-owned processors in Karnataka and Maharashtra with semi-automated legacy equipment requiring FSSAI-mandated metal detection and batch traceability retrofits. Monitor draft FSSAI sodium and preservative threshold amendments as inflection signals for reformulation cost concentration among mid-tier players lacking captive R&D infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | Accelerates FSSAI compliance timelines for natural preservative systems versus synthetic additive alternatives. |
| Quick-Commerce Channel Integration | Enables thirty-minute delivery fulfillment for perishable batter categories in Pune and Hyderabad. |
| Regional Flavor Micro-Segmentation | Captures margin pools shifting from standardized national SKUs toward localized portfolio variants. |
| PLI Scheme Infrastructure Upgrade | Supports automated blending and packaging line modernization for export-ready manufacturing units. |
| North-Eastern Distribution Acquisition | Secures white-space positioning in Assam and Manipur for bamboo shoot-adapted fermented rice mixes. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FSSAI fortification notifications, BIS packaging specifications, and state-level plastic waste management rules. Interviews with food technologists, modern retail category buyers, quick-commerce operations heads, and cold chain logistics providers informed demand-side validation. Secondary sources include customs records for dehydrated spice blend trade flows, PLI scheme disbursement disclosures, and anganwadi procurement databases. Bottom-up volume estimates triangulated against top-down market sizing across product type, end user, and distribution channel dimensions.
Forecast inputs span dual-income household formation rates, spray-drying equipment capacity additions in Pune and Hyderabad, and evolving e-commerce food safety notifications. Segmentation modeling covers curry mix, dosa mix, pulav mix, and soup mix categories crossed with household, restaurant, catering, and food truck end users. CAGRs derive from regression analysis of historical consumption patterns adjusted for regulatory inflection points. Industry-specific inputs include FSSAI amendment timelines and quick-commerce penetration velocity in Bengaluru and Mumbai.
Practitioners should monitor monsoon pattern shifts in Andhra Pradesh and Telangana, draft FSSAI sodium threshold revisions, and quick-commerce platform consolidation for early signals requiring forecast reassessment. Cross-checking against Nielsen retail audit data for modern trade channel velocity is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Africa Soup Market
Processed Foods
Block Margarine Market
Processed Foods
Industrial Margarine Market
Processed Foods
Tomato Puree Market
Processed Foods
Global Pasta Market
Processed Foods
Processed Egg Market
Processed Foods
Fruit Processing Market
Processed Foods
Fermented Foods Market
Processed Foods
Egg Powder Market
Processed Foods
North America Soup Market
Processed Foods
Middle East and Africa Processed Meat Market
Processed Foods
Asia-Pacific Ice Cream Market
Processed Foods
Low Fat Vegetable Soups Market
Processed Foods
Low Fat Soups Market
Processed Foods
Butter Crisco Market
Processed Foods
Global Dried Processed Food Market