
 Chocolate Filling Market | 2026-2036
Chocolate Filling Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Filling Market Analysis
Confectionery formulation expertise is rotating toward cocoa sustainability and clean-label chemistry as brands reformulate legacy recipes. Barry Callebaut anchors its position through certified cocoa sourcing programs that extend across West African cooperatives. Cargill Inc. competes with vertically integrated bean-to-filling supply chains that dominate North American industrial bakery accounts. Nestle S.A. differentiates through precision-tempering technologies that sustain texture stability in high-temperature processing environments.
Chocolate filling denotes a fat-based confectionery matrix with cocoa solids content typically ranging from twenty to seventy percent, engineered for flow control, snap, and mouthfeel in finished goods. Manufacturers deploy conching and tempering sequences to achieve specified particle size distributions and polymorphic crystal structures that prevent fat bloom during shelf life. Milk chocolate formulations occupy the largest volume share across candy bar applications where cost-positioning and familiar flavor profiles drive procurement decisions. Vegan chocolate segments attract accelerated investment as European bakers navigate EFSA allergen labeling protocols and plant-based ingredient sourcing requirements. Powder forms retain dominance in industrial scale operations where dry blending with sugar and dairy fractions enables process efficiency.
FDA food additive regulations and USDA organic certification standards govern ingredient declarations and processing claims in the United States, while EFSA and EU Green Deal sustainability frameworks reshape cocoa traceability obligations across European supply chains. Compliance costs escalate as dual carbon goals from China's MEE and REACH chemical restrictions from ECHA impose parallel testing and documentation burdens on multinational suppliers. Stakeholders must monitor how divergent national labeling regimes reshape formulation flexibility and determine where regional production assets warrant consolidation versus duplication.
Market Dynamics
Clean-label chemistry mandates and cocoa sustainability traceability requirements are forcing wholesale reformulation of legacy chocolate filling recipes across industrial bakery and confectionery supply chains.
Growth Catalysts
- EFSA Allergen Labeling Protocols:European bakers accelerate plant-based chocolate filling procurement to preempt mandatory allergen disclosure expansions, creating demand for vegan formulations with equivalent mouthfeel profiles.
- Automated Tempering Systems:Confectionery manufacturers in Germany's industrial baking corridor deploy precision-temperature control technologies that sustain polymorphic crystal stability through high-throughput processing environments.
- West African Cooperative Sourcing:Certified cocoa programs anchor supply security for manufacturers seeking deforestation-free documentation under EU Green Deal sustainability frameworks.
Market Restraints
- Cocoa Butter Price Volatility:Weather-induced supply disruptions in Côte d'Ivoire and Ghana compress margins for fat-based filling producers locked into annual procurement contracts.
- Dual Compliance Burdens:REACH chemical restrictions from ECHA and China's MEE dual carbon goals impose parallel testing documentation requirements that duplicate certification costs for multinational suppliers.
- Shelf-Stability Limitations:Clean-label emulsifier exclusions reduce fat bloom resistance in high-temperature distribution corridors, constraining geographic reach for premium artisanal formulations.
Strategic Opportunities
- India Industrial Bakery Expansion:FSSAI food safety modernization and PLI scheme incentives for food processing equipment create entry pathways for automated filling system suppliers.
- Precision Fermentation Convergence:Cell-cultured cocoa butter alternatives combined with enzymatic lipid modification enable vegan chocolate fillings with authentic snap and melting profiles.
- Direct-to-Manufacturer Digital Platforms:B2B ingredient marketplaces bypass traditional distributor markups for mid-sized European artisanal bakeries seeking specialty filling formulations.
Industry Challenges
- Confectionery Chemist Talent Scarcity:Formulation expertise in polymorphic crystal engineering and clean-label emulsifier substitution commands premium compensation that mid-tier producers struggle to match.
- Legacy Equipment Retrofit Complexity:Existing tempering and conching infrastructure requires capital-intensive modification to handle lower-melting-point plant-based fat matrices without throughput degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Filling Market |
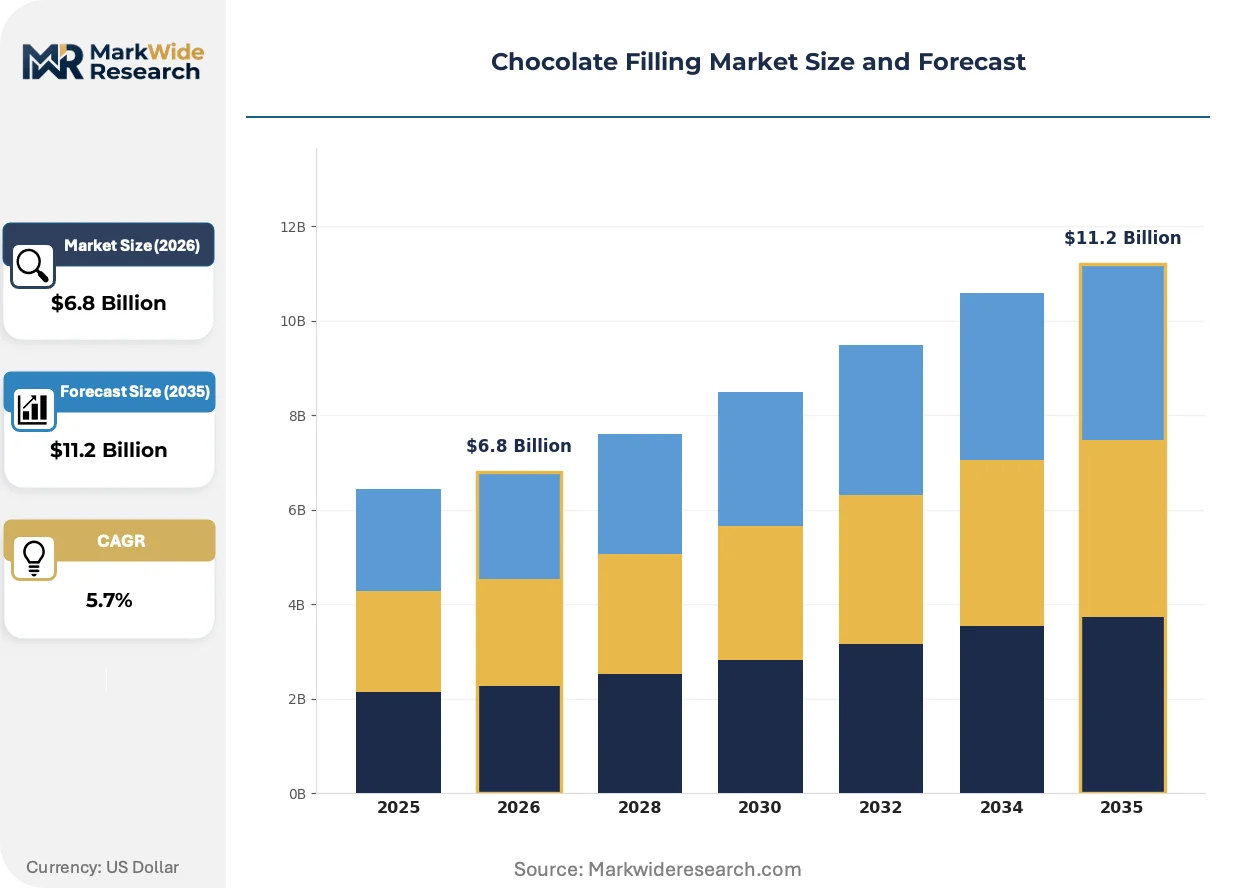
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Vegan Chocolate Form: Liquid, Cream, Solid, Powder Application: Candy Bars, Pastries, Ice Cream, Spreads End User: Bakers, Confectioners, Food Manufacturers, Retailers |
| Companies Covered | Mondelez International, The Hershey Company, Barry Callebaut, Cargill Inc., Lindt & Sprüngli, Nestle S.A., Ferrero Group, Blommer Chocolate Company, Mars Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Filling Market Emerging Trajectories
Formulation science is pivoting toward bioengineered lipid systems and precision-temperature processing that reconcile sensory performance with escalating sustainability documentation requirements.
Enzymatic interesterification of shea and palm fractions is supplanting traditional hydrogenation for plastic fat generation in chocolate filling matrices. Industrial bakeries in France and Belgium adopt these enzymatic routes at accelerating pace to eliminate trans-fat declarations. The technology is compressing the performance gap between conventional and clean-label fat systems, enabling premium positioning without sensory compromise.
EU F-Gas Regulation phase-down schedules are compelling refrigeration-dependent filling manufacturers to retrofit tempering lines with low-global-warming-potential cooling systems. Industrial consequence includes capital redeployment toward closed-loop temperature control infrastructure. German confectionery clusters lead compliance adoption, with equipment suppliers reporting order backlogs for CO2-based secondary cooling circuits.
Specification-driven procurement now dominates European artisanal bakery chains, where buyers mandate batch-level cocoa traceability documentation and carbon intensity scores alongside traditional quality metrics. This displaces relationship-based supplier selection with audited certification requirements. The shift is most visible in Switzerland and the Netherlands, where retail private-label programs enforce farm-to-filling blockchain verification for premium chocolate product lines.
Chocolate Filling Market Segmentation
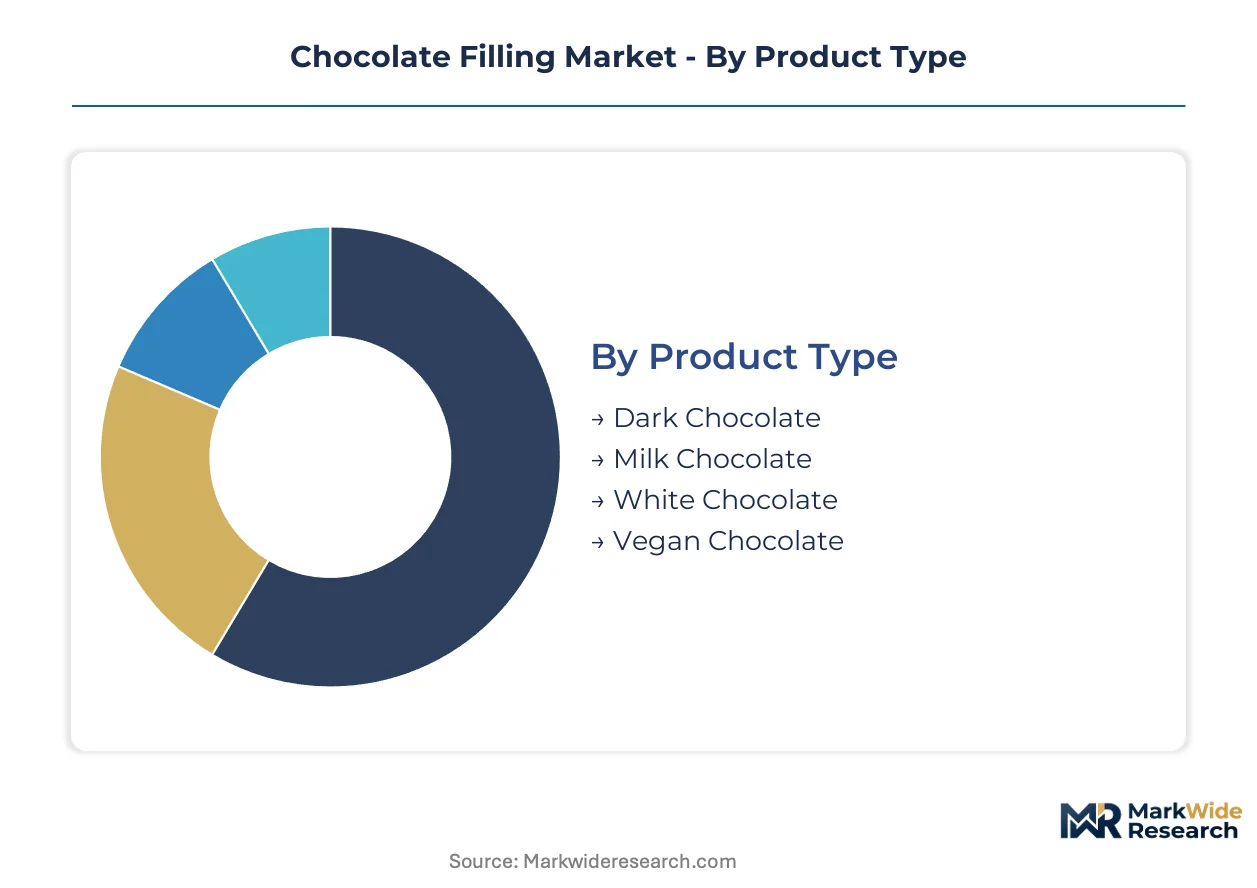
Chocolate filling procurement patterns diverge sharply across formulation chemistry and physical state, with clean-label mandates and processing automation reshaping which segments capture investment. Understanding these fault lines reveals where substitution threats and margin compression concentrate.
Product Type:
Plant-based alternatives and sustainability certification programs are displacing conventional cocoa-fat matrices fastest in segments where allergen labeling and carbon traceability carry premium weight.
- Dark Chocolate:High cocoa solids content (fifty to seventy percent) delivers intense flavor profiles and superior snap characteristics for premium candy bar applications. German industrial bakeries and Swiss artisanal chains prioritize certified-sourced dark chocolate fillings to satisfy EU Green Deal deforestation documentation requirements.
- Milk Chocolate:Dairy-fat emulsions with twenty to forty percent cocoa solids dominate volume procurement across North American and European confectionery accounts where cost positioning and familiar mouthfeel drive repeat purchase. EFSA allergen protocols are accelerating reformulation toward lactose-free alternatives in French and Belgian manufacturing clusters.
- White Chocolate:Cocoa butter base without cocoa solids serves niche pastry decoration and ice cream variegate applications.
- Vegan Chocolate:Plant-fat matrices using shea, coconut, or enzymatically interesterified oils are gaining formulation share in Netherlands and UK bakery chains navigating clean-label chemistry mandates.
Milk chocolate retains volume leadership; vegan chocolate holds the steepest expansion curve.
Form:
Processing throughput requirements and temperature stability needs determine which physical states command premium pricing versus commodity positioning.
- Liquid:Pumpable cocoa-fat suspensions at controlled viscosity enable continuous deposition onto enrobing lines and automated candy bar production. German confectionery manufacturers in the industrial baking corridor specify liquid fillings for high-speed tempering systems that sustain polymorphic crystal stability.
- Powder:Spray-dried or agglomerated cocoa matrices blend with sugar and dairy fractions in dry mixing operations, delivering logistics efficiency and extended ambient shelf life. Industrial scale bakeries across India's FSSAI-regulated processing sector favor powder forms for equipment compatibility with legacy infrastructure.
- Cream:Intermediate moisture fat-water emulsions suit pastry injection and spreadable applications.
- Solid:Tempered blocks and chips require controlled-temperature distribution but offer formulation flexibility for small-batch artisanal producers.
Powder form retains volume leadership; liquid form holds the steepest expansion curve.
Application:
End-use thermal stress and shelf-life duration dictate fat bloom resistance specifications and emulsifier selection across application categories.
- Candy Bars:Enrobed and molded chocolate products require precise tempering sequences to prevent fat bloom during multi-month distribution cycles. Automated filling lines in Germany and Switzerland concentrate procurement of high-stability formulations.
- Pastries:Croissant, Danish, and puff pastry applications demand fillings that maintain viscosity through lamination and baking thermal profiles without oiling out.
- Ice Cream:Low-temperature snap and controlled melting characteristics define specification requirements for variegate and inclusion applications.
- Spreads:Jar-stable emulsions with extended ambient shelf life compete with nut-based alternatives in European retail channels.
Candy bars retain volume leadership; spreads hold the steepest expansion curve.
End User:
Scale economies and technical capability gaps fragment procurement behavior across customer types, with automation readiness determining supplier selection criteria.
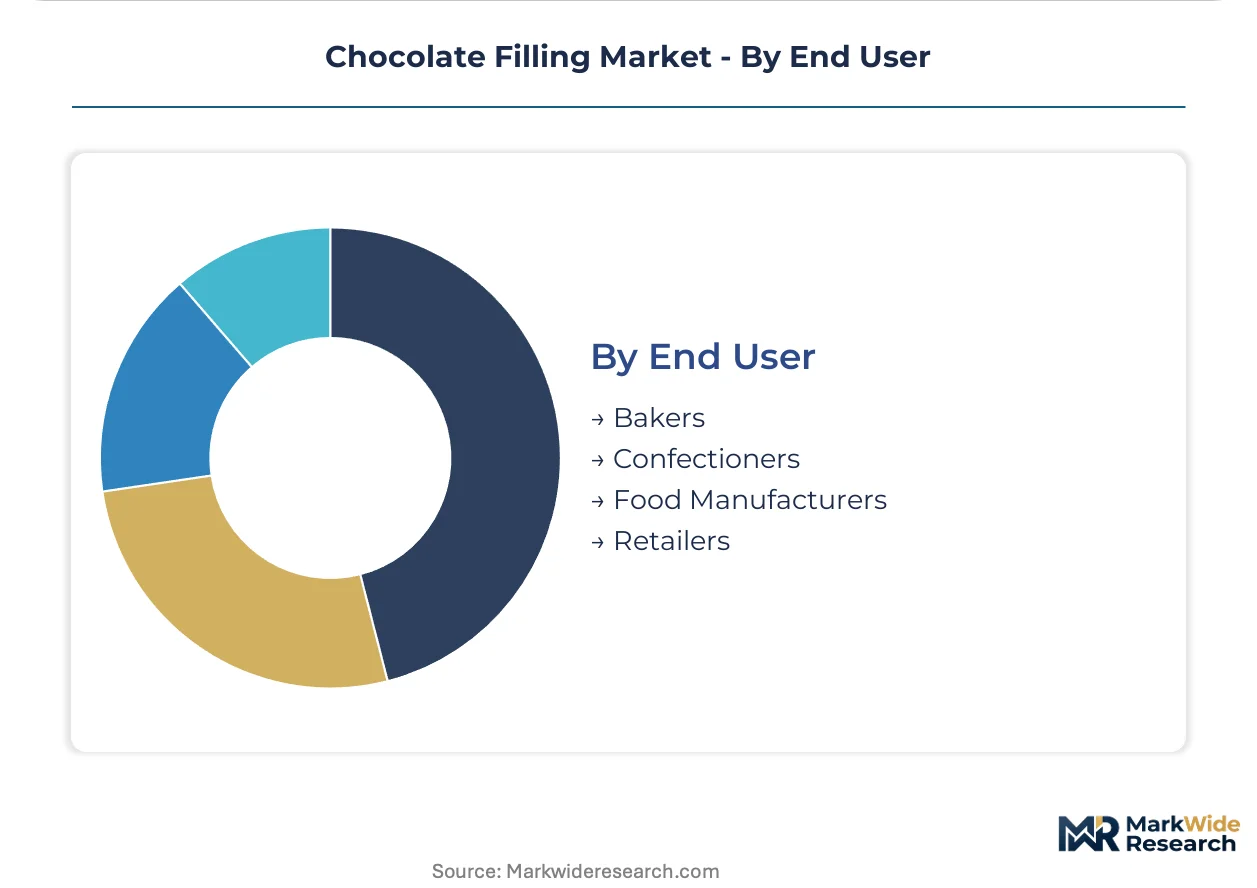
- Food Manufacturers:Large-scale confectionery and bakery operations with integrated tempering and enrobing infrastructure specify bulk liquid and powder deliveries with batch-level traceability documentation. These accounts drive certified cocoa program adoption and blockchain verification requirements.
- Bakers:Artisanal and industrial bakery chains balance formulation flexibility with equipment compatibility, increasingly demanding clean-label emulsifier alternatives.
- Confectioners:Specialty candy producers prioritize sensory performance and customization over scale economies.
- Retailers:Private-label program managers enforce sustainability scoring and carbon intensity metrics alongside traditional quality specifications.
Food manufacturers retain volume leadership; bakers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA clean-label mandates and EU Green Deal traceability requirements anchor European demand concentration, while automated filling adoption accelerates across German industrial bakery corridors and certified cocoa programs expand through West African cooperatives.
Germany
Automated tempering systems and precision-temperature control technologies dominate procurement in the industrial baking corridor between Cologne and Hamburg. The EU F-Gas Regulation drives retrofit investment in CO2-based secondary cooling circuits across confectionery clusters. Bavarian equipment manufacturers report order backlogs for closed-loop temperature control infrastructure serving high-throughput filling operations.
United States
FDA food additive regulations and USDA organic certification standards govern formulation declarations for industrial bakery accounts. North American procurement concentrates on milk chocolate fillings where cost positioning and familiar mouthfeel drive repeat purchase decisions. Midwestern confectionery manufacturers deploy bulk liquid delivery systems with batch-level traceability documentation.
Switzerland
Retail private-label programs enforce farm-to-filling blockchain verification for premium chocolate product lines. Swissmedic-aligned quality protocols and EFSA allergen labeling expansions accelerate plant-based formulation investment. Zurich and Basel artisanal bakery chains mandate carbon intensity scores alongside traditional quality metrics in specification-driven procurement.
India
FSSAI food safety modernization and PLI scheme incentives for food processing equipment create entry pathways for automated filling system suppliers. Powder form formulations dominate industrial scale operations where dry blending compatibility with legacy infrastructure reduces capital requirements. Maharashtra and Gujarat bakery clusters favor spray-dried cocoa matrices for logistics efficiency and extended ambient shelf life.
Netherlands
Plant-based chocolate filling procurement accelerates as Dutch bakery chains navigate EFSA allergen disclosure expansions and clean-label chemistry mandates. Rotterdam distribution hubs concentrate certified cocoa program adoption for deforestation-free documentation under EU Green Deal frameworks. Precision fermentation convergence attracts investment for cell-cultured cocoa butter alternatives with authentic snap profiles.
Chocolate Filling Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in chocolate filling supply. Tier-one participants control captive cocoa sourcing and tempering technology portfolios, while mid-scale operators compete on formulation flexibility for artisanal accounts. The competitive landscape separates into three archetypes: integrated bean-to-filling suppliers, precision-tempering technology licensors, and regional formulation specialists. Dominant competitive moves include certified cocoa program expansion and automated tempering system deployment.
Among integrated supply chain operators, Barry Callebaut and Cargill Inc. exemplify the bean-to-filling archetype through West African cooperative sourcing programs. Nestle S.A. occupies a position within precision-temperature processing technology, sustaining polymorphic crystal stability in high-throughput environments. These three companies anchor the competitive structure, representing distinct vectors of capability concentration.
| Leading Market Players |
|---|
| Mondelez International |
| The Hershey Company |
| Barry Callebaut |
| Cargill Inc. |
| Lindt & Sprüngli |
| Nestle S.A. |
| Ferrero Group |
| Blommer Chocolate Company |
| Mars Incorporated |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German confectionery clusters shapes both supply concentration and price floors for cocoa-fat matrices. Automated tempering infrastructure in the Cologne-Hamburg corridor anchors premium pricing tiers while smaller artisanal producers absorb margin compression from legacy equipment retrofit costs.
Pricing Analysis
Geographic price spreads between West African cooperative-sourced and conventional commodity cocoa butter run through certified-sustainability premiums. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-verified organic fillings from mass-market milk chocolate formulations. Pricing pressure stems from cocoa butter price volatility in Côte d'Ivoire and Ghana compressing margins for contract-locked producers. Industrial bakery accounts in North America exhibit highest price sensitivity; Swiss private-label programs demonstrate lowest sensitivity due to carbon-intensity scoring mandates.
Supply Chain Analysis
Inventory lead times for cocoa butter alternatives have extended as enzymatic interesterification capacity constraints strain shea and palm fraction availability. Supply concentrates in Côte d'Ivoire, Ghana, and Indonesia for bean sourcing; Germany, Switzerland, and Belgium for finished filling production. Raw material dependencies center on cocoa beans, dairy fractions, and plant-based lipid systems. Single-source vulnerability in West African cooperative networks threatens deforestation-free documentation compliance. Distribution runs through Rotterdam and Hamburg hub-and-spoke networks serving European artisanal bakery chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise in polymorphic crystal engineering and clean-label emulsifier substitution has become the constraining asset, with mid-tier producers struggling to match premium compensation for scarce confectionery chemists.
For Market Incumbents: Compound defensive positioning through certified cocoa program expansion across West African cooperatives and precision-tempering technology deployment in high-throughput German facilities. Backward integration into shea fraction processing mitigates enzymatic lipid supply constraints. Channel control through direct-to-manufacturer digital platforms secures mid-sized European artisanal bakery accounts against emerging B2B marketplace competitors. For New Entrants and Emerging Players: EU organic certification fast-tracks unlock premium positioning in Netherlands and UK bakery chains navigating EFSA allergen disclosure expansions. White-space concentration in India's FSSAI-regulated industrial bakery sector offers penetrable entry through powder-form compatibility with legacy equipment. Precision fermentation partnerships for cell-cultured cocoa butter alternatives provide differentiated go-to-market positioning against incumbent fat-matrix suppliers. For Investors and Strategic Acquirers: Regional formulation specialists with established clean-label emulsion capabilities represent the most compelling acquisition archetype for portfolio consolidation. Long-term viability hinges on enzymatic processing technology ownership and automated tempering system integration. Monitor precision fermentation scale-up announcements as inflection indicators for plant-based fat system cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Cocoa Program Expansion | West African cooperative sourcing secures deforestation-free documentation under EU Green Deal frameworks. |
| Automated Tempering System Deployment | CO2-based secondary cooling circuits in German clusters comply with EU F-Gas Regulation phase-down schedules. |
| Precision Fermentation Partnership | Cell-cultured cocoa butter alternatives enable authentic snap profiles in vegan chocolate formulations. |
| Direct-to-Manufacturer Digital Platform | B2B ingredient marketplaces bypass distributor markups for mid-sized European artisanal bakeries. |
| Enzymatic Interesterification Scale-Up | Shea and palm fraction processing eliminates trans-fat declarations for French and Belgian industrial bakeries. |
Methodological Framework
Initial hypotheses were tested against primary input from confectionery formulation chemists, industrial bakery procurement directors, cocoa cooperative managers, and equipment manufacturing engineers and refined through secondary validation. Trade data from customs authorities, EFSA regulatory filings, EU Green Deal sustainability documentation, and SEC disclosures from publicly traded ingredient suppliers anchored quantitative baselines. Bottom-up volume estimates from tempering system installations and top-down value projections from cocoa butter futures pricing were triangulated to constrain forecast variance.
Variance decomposition across product type, form, application, and end-user segments structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate blending weighted by base-period revenue contribution. Cocoa sustainability certification penetration rates and automated filling system adoption curves served as industry-specific forecast inputs throughout the modeling period.
Decision-makers should treat outputs as directional under assumptions of sustained EU regulatory enforcement and stable West African cooperative network integrity; material deviation in cocoa butter price volatility or F-Gas Regulation compliance timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Ready to Cook Market
Processed Foods
Low Calorie Rice Pudding Market
Processed Foods
Processed Peanut Market
Processed Foods
Global Take Out Fried Chicken Market
Processed Foods
Fermented Foods Market
Processed Foods
Egg Powder Market
Processed Foods
United States Egg Powder Market
Processed Foods
Soup Market
Processed Foods
United States Food Spread Market
Processed Foods
Imitation Whipped Cream Market
Processed Foods
Ready to Serve Prefabricated Dishes Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
Fat Free Soup Market
Processed Foods
India Ready to Mix Food Market
Processed Foods
Processed Beef Market
Processed Foods
Butter Crisco Market