
 Fat Free Soup Market | 2026-2036
Fat Free Soup Market Size, Share, and Industry Trends Forecast 2026-2036
Fat Free Soup Market Analytics
The gap between premium organic fat-free soups and commodity private-label offerings is broadening as ingredient transparency becomes a decisive purchase factor. The Campbell Soup Company leverages its centralized R&D network to sustain formulation leadership across North American retail channels. Nestlé S.A. anchors European positioning through controlled supply chains for vegetable-based broth stocks. Unilever PLC competes on brand recognition in emerging Asian markets where Western dietary patterns gain traction.
Fat-free soup denotes prepared liquid food products containing less than 0.5 grams of fat per standardized serving, achieved through skimming processes, lean protein selection, and emulsifier-free stabilization. Manufacturers deploy retort thermal processing to extend shelf stability without lipid-based carriers. Broth-based formulations command the largest volume share due to inherent low-fat composition and minimal reformulation requirements. Pouch packaging exhibits the fastest growth trajectory as flexible materials reduce shipping weights and enable microwave-ready convenience for meal delivery services. Creamy segments rely on modified starch and protein-stabilized emulsions to replicate mouthfeel without dairy fat, creating concentrated margin pools for hydrocolloid suppliers.
The FDA governs fat-content labeling thresholds in the United States, while the EU Nutrition and Health Claims Regulation enforces substantiation requirements for reduced-fat positioning across member states. Both frameworks elevate compliance costs for new entrants but simultaneously validate premium pricing for certified formulations. Stakeholders must monitor evolving front-of-pack labeling mandates and alternative protein integration pathways as sodium reduction targets intensify technical complexity.
Market Dynamics
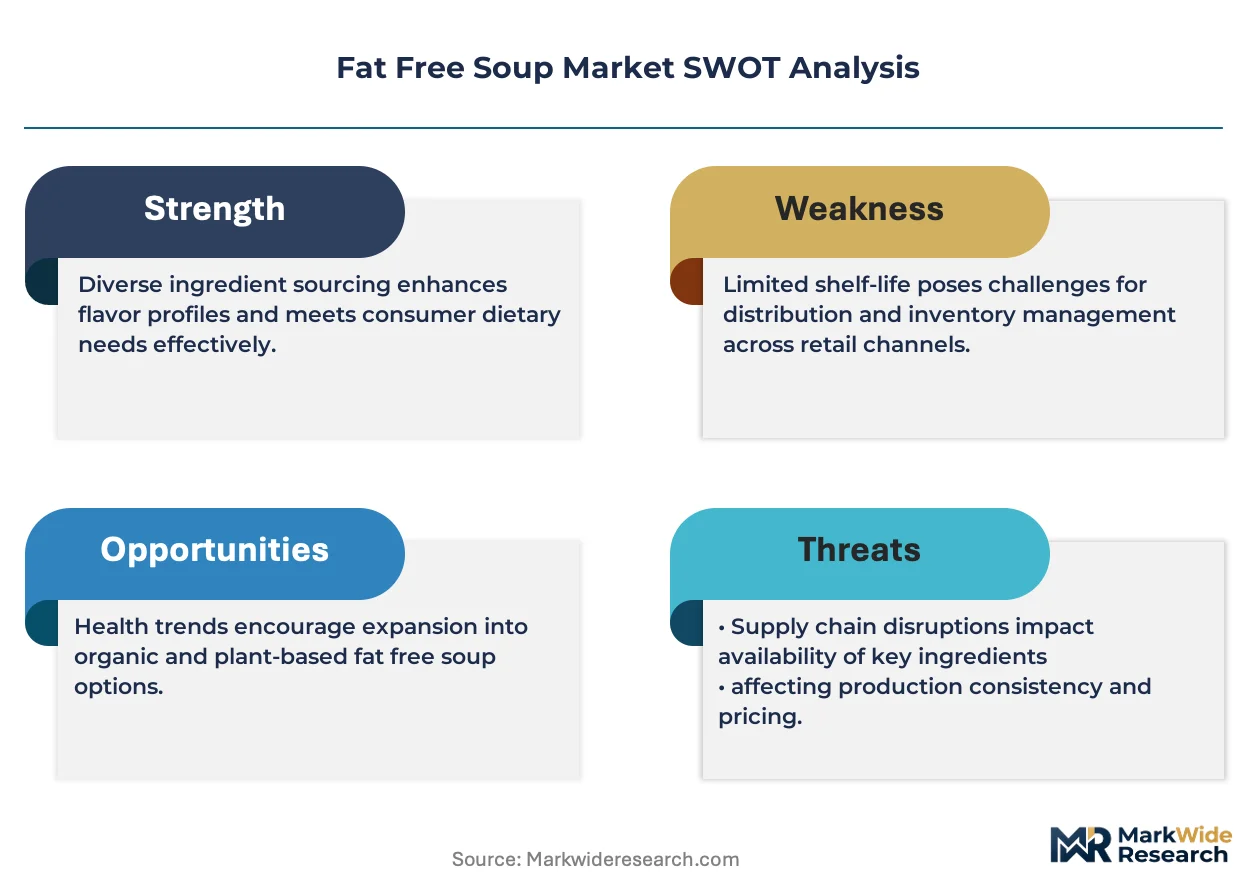
Sodium reduction mandates under the EU Nutrition and Health Claims Regulation are forcing reformulation investments across broth-based portfolios, compressing margins for manufacturers lacking centralized R&D infrastructure while validating premium positioning for compliant brands.
Growth Catalysts
- Meal delivery channel expansion:Urban logistics networks in the United States prioritize low-calorie menu additions, creating dedicated procurement slots for retort-pouch formats.
- REACH-compliant emulsifier alternatives:European hydrocolloid suppliers develop protein-stabilized systems that replicate dairy mouthfeel without lipid carriers.
- Front-of-pack labeling mandates:Germany's tightened sodium disclosure rules under EU framework drive household switching toward transparently labeled broth stocks.
Market Restraints
- Modified starch input volatility:Creamy segment manufacturers face margin pressure from fluctuating tapioca and potato derivative costs.
- Thermal processing equipment concentration:Retort system suppliers cluster in Italy and Germany, creating bottleneck risk for capacity expansion.
- Clean-label substitution threat:Refrigerated fresh soup formats with minimal processing claims capture health-conscious buyers seeking shorter ingredient lists.
Strategic Opportunities
- India urban penetration:Metro household disposable income growth creates first-mover advantage for shelf-stable broth positioning in modern trade formats.
- Microwave-ready pouch innovation:Flexible packaging with venting technology opens direct-to-consumer subscription channels bypassing traditional retail slotting.
- FSSAI clean-label harmonization:India's forthcoming front-of-pack nutrient disclosure standards will validate reformulation investments ahead of enforcement.
Industry Challenges
- Sensory scientist scarcity:Formulation teams struggle to recruit specialists in protein-stabilized emulsion design for fat-mimetic applications.
- Dual certification timelines:Simultaneous FDA and EFSA substantiation processes for reduced-fat claims extend product launch windows by 14-18 months.
- Legacy ERP integration:Batch-level traceability systems for ingredient transparency require costly middleware deployment with existing manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fat Free Soup Market |
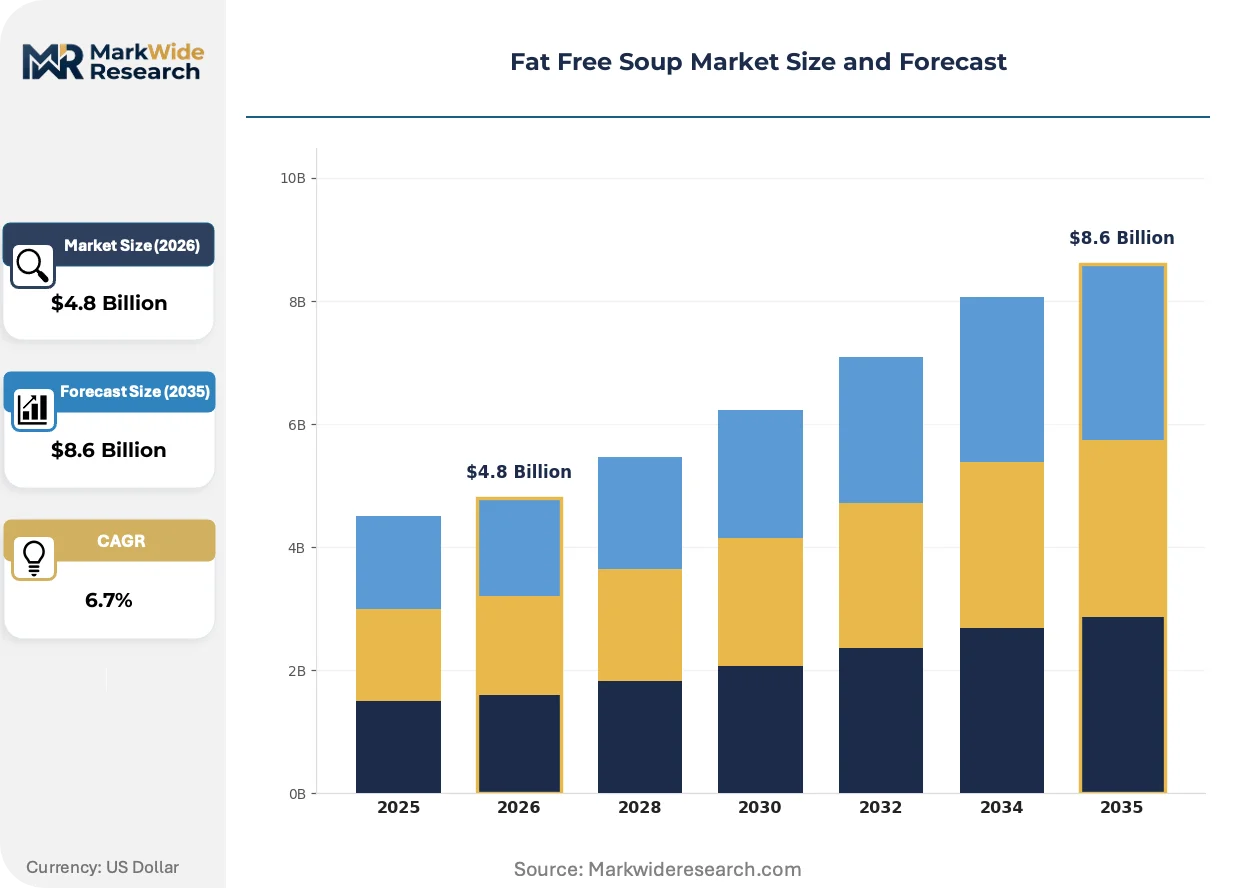
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creamy, Broth-Based, Chunky, Pureed Packaging Type: Carton, Can, Bag, Pouch Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops End User: Households, Restaurants, Cafes, Meal Delivery Services |
| Companies Covered | The Campbell Soup Company, Nestlé S.A., Unilever PLC, The Kraft Heinz Company, General Mills Inc., Conagra Brands Inc., Baxters Food Group Limited, Hindustan Unilever Limited, Associated British Foods plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fat Free Soup Market Evolving Landscape
Active packaging technologies and regulatory disclosure mandates are restructuring competitive advantage around supply chain visibility rather than formulation secrecy alone.
High-pressure processing is converging with aseptic pouch filling to extend shelf stability without retort thermal degradation of vegetable broth volatiles. Premium organic brands in California and New York metro corridors pilot these hybrid lines to capture clean-label buyers. The technology is converging with microwave-ready convenience formats, compressing the traditional trade-off between shelf stability and sensory freshness.
EU Green Deal Farm-to-Fork targets are tightening sodium reduction timelines for processed foods, with EFSA reviewing substantiation protocols for reduced-fat health claims. Manufacturers must reformulate ahead of 2025-2026 enforcement windows or forfeit premium positioning. Broth-based portfolios face the steepest compliance burden given their reliance on sodium for microbial stability and flavor impact.
Direct-to-pantry subscription models are displacing conventional retail slotting for household pantry staples, with meal-kit aggregators curating rotating soup selections. This channel shift concentrates buyer power with platform algorithms rather than brand equity. Germany and United Kingdom urban households show highest adoption velocity, driven by convenience-seeking dual-income demographics.
Fat Free Soup Market Segmentation
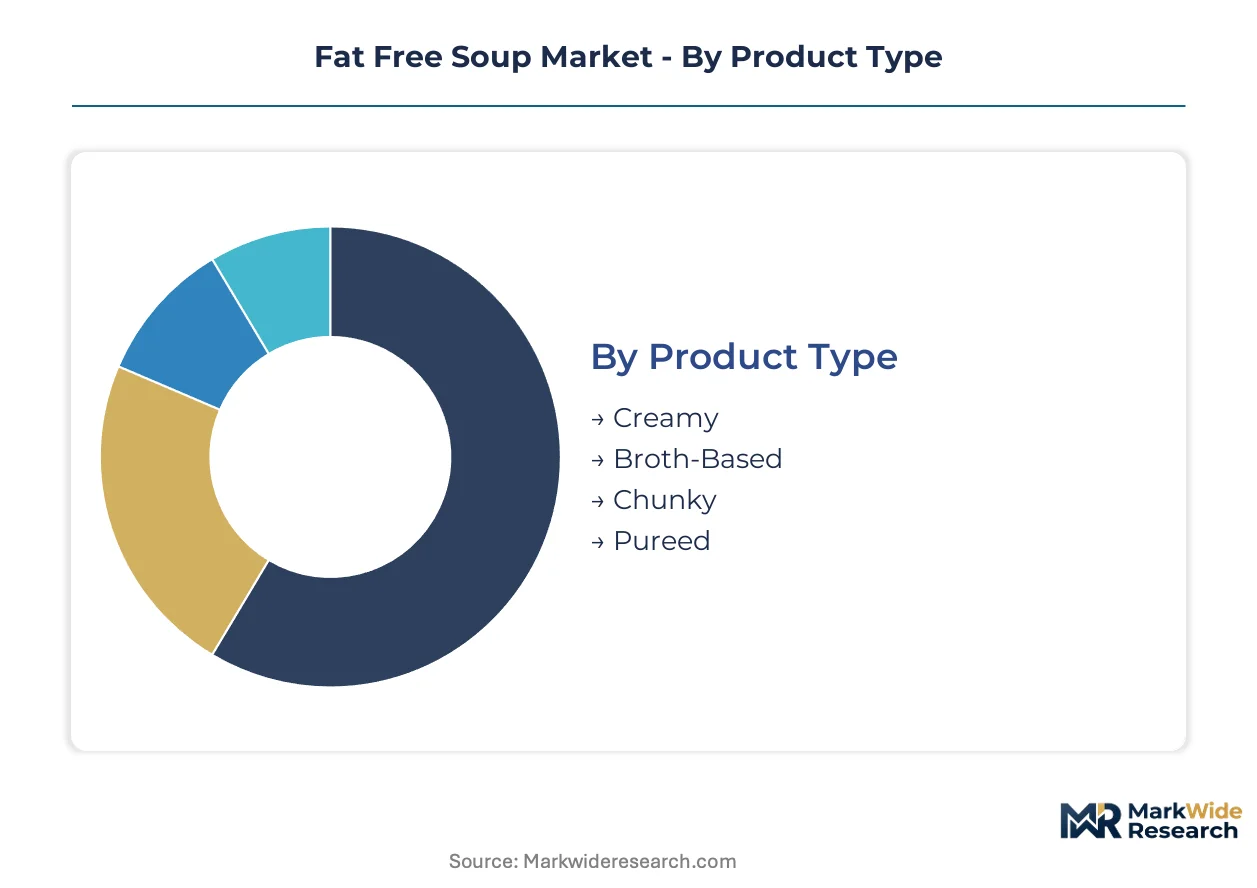
Fat-free soup manufacturers calibrate production lines across four distinct category axes. Product formulation determines thermal processing requirements, while packaging selection governs distribution economics and channel access.
Product Type:
Customization intensity spans from standardized broth stocks requiring minimal reformulation to engineered creamy systems demanding protein-stabilized emulsion design.
- Broth-Based:Clear liquid formulations achieve sub-0.5g fat thresholds through skimming and lean protein selection without emulsifier intervention. German households under tightened EU sodium-labeling rules are expanding purchases of transparently labeled formats. Demand concentrates in North American urban centers where meal delivery services prioritize low-calorie menu additions.
- Creamy:Modified starch and hydrocolloid-stabilized systems replicate dairy mouthfeel without lipid carriers, creating concentrated margin pools for specialty ingredient suppliers. European manufacturers face margin pressure from fluctuating tapioca and potato derivative input costs.
- Chunky:Vegetable and protein particulates suspended in reduced-fat bases require careful viscosity management to prevent phase separation during retort processing.
- Pureed:Uniform texture achieved through high-shear homogenization appeals to clinical nutrition and pediatric segments with specific swallowing requirements.
Most installed capacity flows through Broth-Based. Expansion is steepest in Creamy.
Packaging Type:
Material selection tracks the convenience-premium trade-off, with flexible formats gaining share in direct-to-consumer channels while rigid containers dominate traditional retail.
- Pouch:Flexible materials reduce shipping weights and enable microwave-ready convenience with venting technology for meal delivery services. Direct-to-pantry subscription models in Germany and United Kingdom urban households show highest adoption velocity.
- Carton:Aseptic brick formats suit broth-based portfolios with extended ambient shelf stability requirements in European retail.
- Can:Metal containers retain dominance in North American mass retail for heritage brand recognition and crush resistance.
- Bag:Bulk foodservice formats serve restaurant and cafe procurement with reduced unit economics for high-volume operators.
Can formats retain the largest installed base. Pouch configurations are climbing the fastest.
Distribution Channel:
Channel selection determines margin capture, with traditional retail ceding share to platform-curated subscription models that concentrate buyer power with algorithmic recommendation engines.
- Supermarkets:Slotting fees and promotional calendars govern brand visibility for shelf-stable broth stocks in conventional retail.
- Online Retail:Direct-to-consumer channels bypass traditional slotting constraints, enabling rotating soup selections curated by meal-kit aggregators.
- Convenience Stores:Grab-and-go positioning for single-serve microwave-ready formats targets urban commuter demand.
- Specialty Shops:Premium organic positioning with ingredient transparency claims captures health-conscious buyers seeking shorter ingredient lists.
Supermarkets process the highest volume throughput. Online Retail is gaining share fastest.
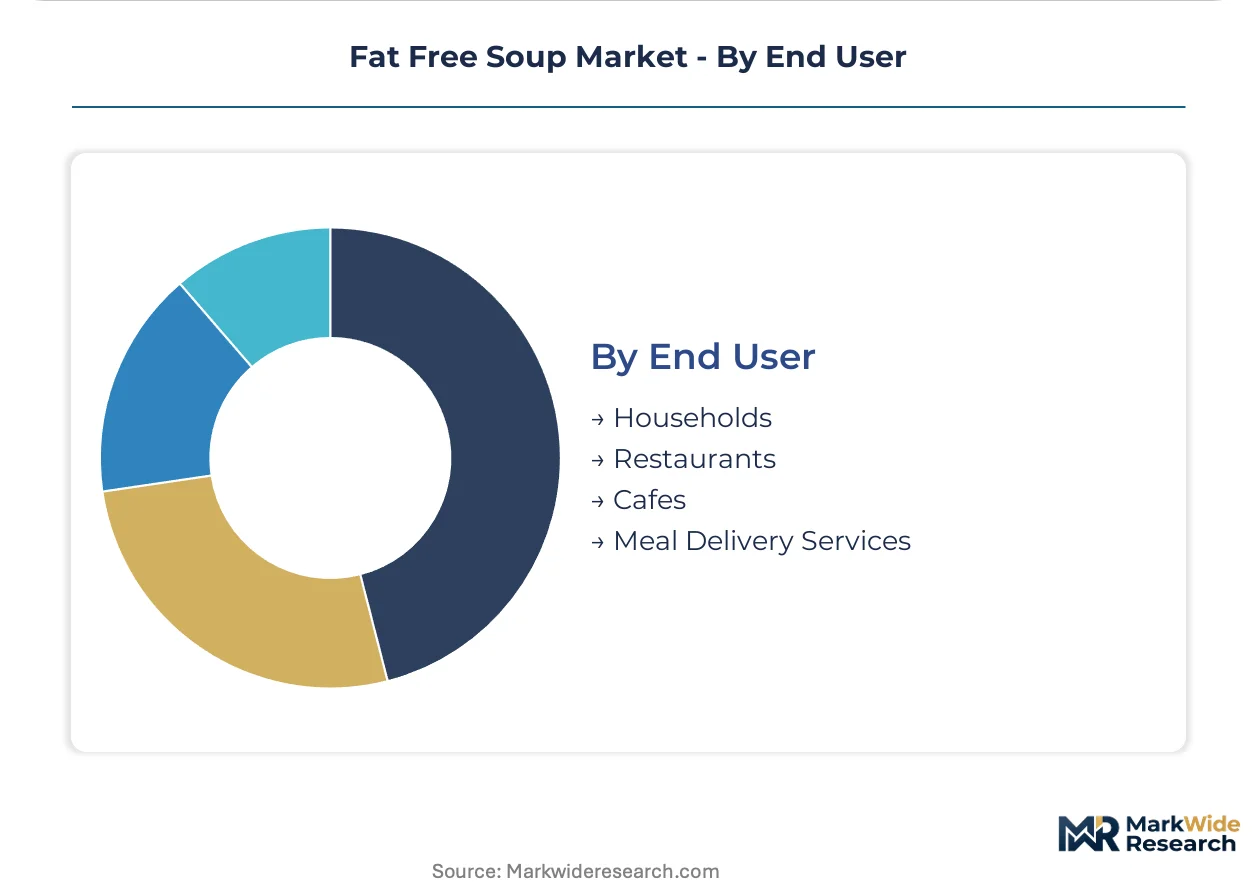
End User:
Customer segmentation reflects divergent procurement logic between household pantry stocking and foodservice operational requirements.
- Households:Health-conscious dual-income demographics in Germany and United States metro corridors drive demand for transparently labeled, sodium-reduced formats.
- Meal Delivery Services:Platform algorithms curate rotating soup selections, displacing conventional brand equity with data-driven procurement.
- Restaurants:Foodservice operators prioritize consistent portion control and labor minimization through ready-to-heat formats.
- Cafes:Limited-service operators seek compact storage footprints and extended holding stability for grab-and-go soup offerings.
Households represent the largest addressable base. Meal Delivery Services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized sensory scientists and protein-stabilized emulsion designers cluster in Germany, the United States, and India, anchoring formulation capabilities for fat-mimetic applications across three continents.
United States
Meal delivery platforms in New York and Los Angeles metro corridors drive procurement of retort-pouch formats for low-calorie menu additions. FDA fat-content labeling thresholds govern sub-0.5g per serving claims, elevating compliance costs for new entrants. Chicago and Austin host concentrated R&D operations where centralized formulation networks sustain North American retail channel leadership.
Germany
Health-conscious households in Berlin and Munich expand transparently labeled broth stock purchases under tightened EU sodium disclosure rules. The EU Nutrition and Health Claims Regulation enforces substantiation requirements for reduced-fat positioning, compressing margins for manufacturers lacking centralized infrastructure. Baden-Württemberg clusters retort system suppliers, creating equipment bottleneck risk for regional capacity expansion.
India
Metro household disposable income growth in Mumbai and Delhi-NCR creates first-mover advantage for shelf-stable broth positioning in modern trade formats. FSSAI clean-label harmonization through forthcoming front-of-pack nutrient disclosure standards validates reformulation investments ahead of enforcement. Bangalore and Hyderabad concentrate meal-kit aggregator operations curating rotating soup selections for dual-income demographics.
United Kingdom
Urban households in London and Manchester show highest adoption velocity for direct-to-pantry subscription models displacing conventional retail slotting. REACH-compliant emulsifier alternatives from European hydrocolloid suppliers enable protein-stabilized systems replicating dairy mouthfeel. The Midlands region hosts flexible packaging innovators developing venting technology for microwave-ready convenience formats.
Japan
Clinical nutrition and pediatric segments in Tokyo and Osaka metro areas sustain demand for pureed formats with specific swallowing requirements. METI standards influence aseptic processing equipment specifications for high-pressure processing convergence with pouch filling. Nagoya anchors thermal processing machinery clusters supporting hybrid line pilot programs for clean-label premium positioning.
Fat Free Soup Market Competitive Landscape
Capital-heavy producers with captive retort thermal processing infrastructure compete with asset-light brand designers outsourcing manufacturing to third-party copackers. The vendor base concentrates around three tiers: multinational conglomerates with centralized R&D networks, regional specialists controlling vegetable-based supply chains, and private-label copackers serving retail channel consolidation. Strategic archetypes include formulation leaders leveraging sensory science capabilities, supply chain controllers integrating hydrocolloid procurement, and platform-dependent brands riding meal-kit aggregator algorithms. Dominant competitive moves encompass M&A for hydrocolloid supplier integration and geographic licensing partnerships for microwave-ready pouch technology access.
Within the multinational conglomerate tier, The Campbell Soup Company and Nestlé S.A. exemplify divergent regional anchoring strategies, with the former representing North American retail channel concentration and the latter occupying European supply chain control positions. Unilever PLC sits within the emerging market expansion archetype, leveraging brand recognition infrastructure in Asian markets where Western dietary patterns gain traction. Among these three, formulation leadership separates asset-heavy R&D investors from brand-reliant market entrants.
| Leading Market Players |
|---|
| The Campbell Soup Company |
| Nestlé S.A. |
| Unilever PLC |
| The Kraft Heinz Company |
| General Mills Inc. |
| Conagra Brands Inc. |
| Baxters Food Group Limited |
| Hindustan Unilever Limited |
| Associated British Foods plc |
| Others |
Value Network & Pricing Analysis
Captive retort thermal processing infrastructure anchors both supply security and pricing power for fat-free soup manufacturers, with asset-heavy producers commanding premium positioning while third-party copackers compete on volume flexibility. This integration choice separates formulation leaders who control batch-level traceability from brand designers vulnerable to input cost pass-through.
Pricing Analysis
The bundled service split separates premium organic positioning with ingredient transparency certification from commodity private-label offerings competing on unit economics. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and sodium-reduction compliance under EU and FDA frameworks. Cost compression in creamy segments intensifies because modified starch input volatility from tapioca and potato derivatives squeezes margin pools. Private-label buyers at mass retail show highest price sensitivity, while meal delivery platforms prioritize consistent quality over per-unit cost.
Supply Chain Analysis
Certification gating under REACH, FDA fat-content thresholds, and FSSAI clean-label harmonization restricts supplier pools to qualified hydrocolloid and retort equipment providers. Raw material sourcing concentrates in Germany for thermal processing machinery, India for vegetable-based broth inputs, and Italy for aseptic filling systems. Protein-stabilized emulsion design, modified starch derivatives, and flexible pouch materials constitute critical input dependencies. Single-source vulnerability clusters around retort system suppliers in Baden-Württemberg. Distribution runs through supermarket slotting agreements, meal-kit aggregator platforms, and direct-to-pantry subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU sodium reduction timelines compress margins faster than FDA enforcement windows, rewarding early reformulation investments in European supply chains.
For Market Incumbents: Cement formulation leadership through captive R&D networks in Chicago and Austin while consolidating hydrocolloid supplier relationships to lock in protein-stabilized emulsion capacity. Threat from refrigerated fresh soup formats with minimal processing claims demands accelerated high-pressure processing pilot deployment. Vertical integration into pouch venting technology secures direct-to-consumer channel access. For New Entrants and Emerging Players: FSSAI clean-label harmonization in India opens a window for shelf-stable broth positioning ahead of enforcement, targeting metro household disposable income growth in Mumbai and Delhi-NCR. White-space exists in microwave-ready pouch innovation for meal-kit aggregator curation. Go-to-market leverage rests on bypassing traditional retail slotting through platform algorithmic procurement. For Investors and Strategic Acquirers: Roll-up economics work for regional specialists controlling vegetable-based supply chains because fragmented copacker bases lack batch-level traceability infrastructure. Long-term viability centers on five-to-ten-year consolidation of formulation capabilities and certification assets. Watch FSSAI enforcement timing as inflection indicator for Indian market premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrocolloid Supply | Captures margin pools from modified starch and protein-stabilized emulsion inputs for creamy segment production. |
| High-Pressure Processing Pilot Deployment | Extends shelf stability without retort thermal degradation, validating clean-label claims for California and New York metro buyers. |
| Microwave-Ready Pouch Venting Technology | Enables direct-to-pantry subscription channels bypassing supermarket slotting fees in Germany and United Kingdom urban corridors. |
| Dual Certification Investment (FDA/EFSA) | Compresses product launch windows for reduced-fat claims while validating premium pricing across North American and European retail. |
| Meal-Kit Aggregator Platform Partnership | Concentrates buyer power with algorithmic curation, displacing conventional brand equity in rotating soup selections. |
Research Methodology
Multiple input streams — formulation scientist interviews, procurement manager surveys, and regulatory filing analysis — were reconciled against secondary validation. Primary discussions with R&D directors at soup manufacturers, hydrocolloid supplier technical leads, meal-kit aggregator category managers, and retort equipment specialists informed demand-side and supply-side dynamics. Secondary sources included FDA GRAS notifications, EFSA health claim substantiation records, FSSAI draft labeling standards, and trade customs data for modified starch and flexible packaging materials. Bottom-up volume modeling and top-down value reconciliation triangulated market sizing.
Historical shipment data cross-referenced against panel input from category buyers and platform procurement officers anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product formulation type, packaging material technology, distribution channel structure, and end-user procurement logic. CAGRs were derived from slope analysis of annualized growth patterns adjusted for regulatory enforcement phase-ins. Industry-specific inputs incorporated EU Green Deal Farm-to-Fork sodium reduction timelines and meal delivery channel expansion rates in United States metro corridors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated clean-label substitution or retort equipment supply bottlenecks. Deviation in FSSAI enforcement timing or REACH emulsifier restriction scope would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Tomato Puree Market
Processed Foods
Fruit Processing Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
Ready-To-Whip Toppings Market
Processed Foods
Low Fat Soups Market
Processed Foods
Apple Butter Market
Processed Foods
Broth Market
Processed Foods
Dairy Desserts Market
Processed Foods
Processed Mango Products Market
Processed Foods
Processed Peanut Market
Processed Foods
India Ready to Mix Food Market
Processed Foods
Low-Fat Desserts to Buy Market
Processed Foods
Fermented Food and Drinks Market
Processed Foods
Africa Soup Market
Processed Foods
Asia-Pacific Ice Cream Market
Processed Foods
Global Take Out Fried Chicken Market