
 US Processed Pumpkin Market | 2026-2036
US Processed Pumpkin Market Size, Share, and Industry Trends Forecast 2026-2036
US Processed Pumpkin Market Intelligence
A transition from single-grower agreements to multi-source agricultural contracts is realigning procurement strategies for major food manufacturers in the US. Libby's sustains its market position through large-scale, proprietary canning operations, primarily centered in Illinois. In contrast, Seneca Foods leverages its broad portfolio of canned vegetables to optimize seasonal production capacity and manage agricultural risk. Del Monte Foods competes by emphasizing its extensive brand recognition across national supermarket and online retail channels.
Processed pumpkin refers to pumpkin flesh that has been cooked and mechanically prepared for commercial use as a food ingredient, available as puree, canned solid-pack, or frozen blocks. Key product specifications include controlled Brix levels for sweetness and consistent viscosity, which are critical for industrial baking and sauce production. While canned pumpkin remains the dominant and most mature product type, demand for organic puree is expanding rapidly within the baby food application. Baked goods represent the largest end-use category by volume, driven by strong seasonal consumption patterns.
The US Food and Drug Administration (FDA) governs product safety and labeling, including standards of identity that define what can be marketed as "pumpkin." Concurrently, USDA regulations for organic certification impose strict guidelines on cultivation and processing methods, creating a distinct premium market segment. Navigating these dual regulatory frameworks for both conventional and organic supply chains is a key operational consideration for all processors.
Market Dynamics
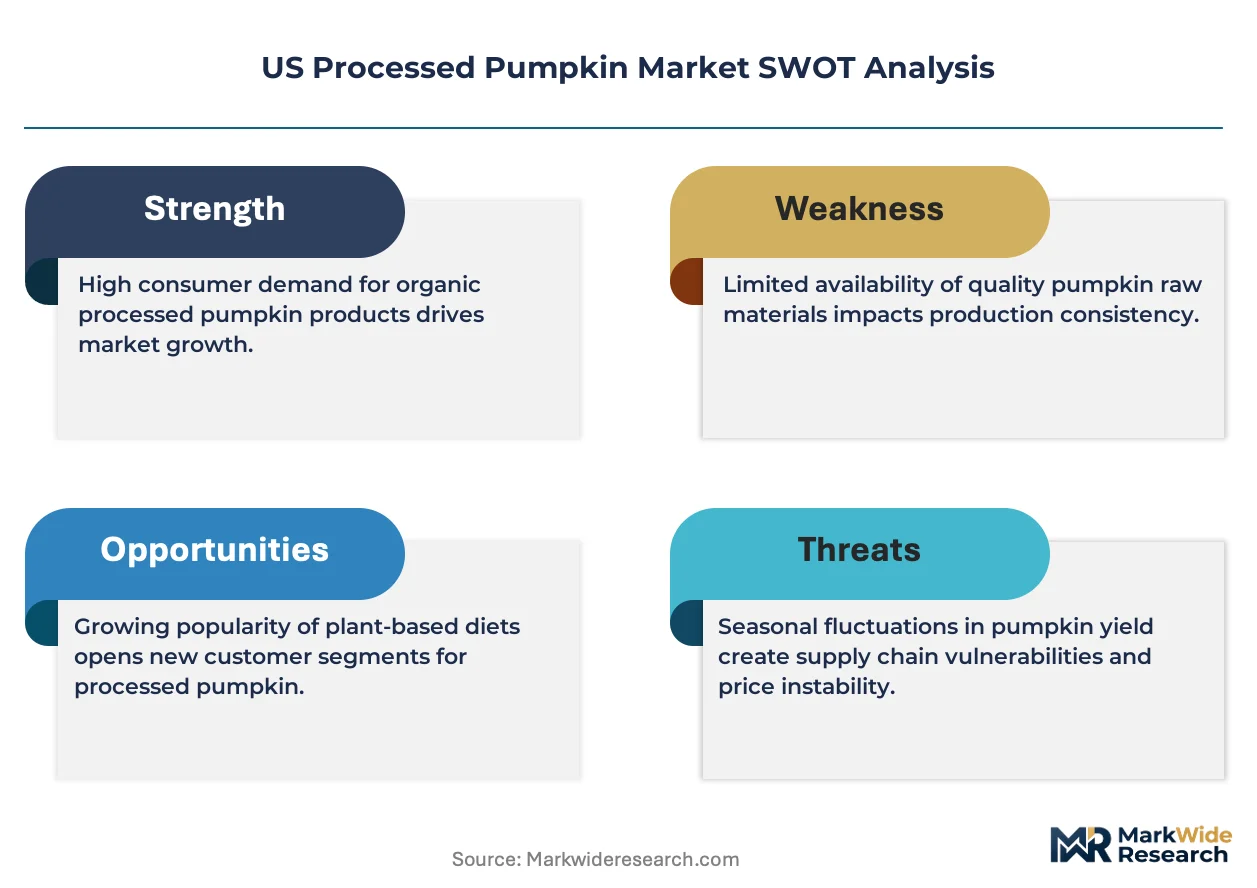
The fundamental market dynamic is the growing bifurcation of supply chains. Processors must simultaneously manage high-volume, conventional canning operations for mature end-uses and a separate, high-cost certified organic stream to meet clean-label demand in premium segments like baby food.
Growth Catalysts
- Clean-Label Ingredient Demand:The baby food sector's preference for simple, recognizable ingredients is expanding the market for organic pumpkin puree, which serves as a base for numerous formulations.
- USDA Organic Certification:Federal standards for organic products enable a distinct premium market segment, allowing processors to capture higher margins from consumers willing to pay for certified goods.
- Midwest Processing Infrastructure:The concentration of cultivation and processing facilities in states like Illinois creates economies of scale and logistical efficiencies, supporting cost-effective production for the national market.
Market Restraints
- Agricultural Volatility:The market is vulnerable to weather-related disruptions in key pumpkin-growing regions, which can cause significant fluctuations in raw material availability and price.
- Crop-Specific Diseases:Fungal blights and viruses specific to cucurbit crops pose a constant threat to yields, requiring significant investment in crop management and risk mitigation from growers.
- Substitution from Other Purees:In applications like soups, sauces, and baked goods, processed pumpkin faces direct competition from lower-cost or more readily available vegetable purees, such as butternut squash or sweet potato.
Strategic Opportunities
- Pet Food Formulation:The inclusion of pumpkin as a functional, fiber-rich ingredient in premium and veterinary pet food formulas represents a significant volume opportunity outside of human food applications.
- Functional Food Powders:Developing dehydrated pumpkin powders and flours for the nutritional supplement and health food industries opens new channels beyond traditional canned and frozen formats.
- Foodservice Expansion:Targeting national restaurant chains and institutional foodservice providers with value-added pumpkin-based sauces, fillings, and soup bases can drive year-round demand.
Industry Challenges
- Dual Regulatory Compliance:Processors face the operational complexity and cost of maintaining separate protocols to satisfy both FDA food safety regulations for conventional products and stringent USDA rules for organic lines.
- Seasonal Labor Management:Securing and managing a large, temporary workforce for the short, intensive harvest and processing season is a persistent logistical and human resources challenge, particularly in rural areas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Processed Pumpkin Market |
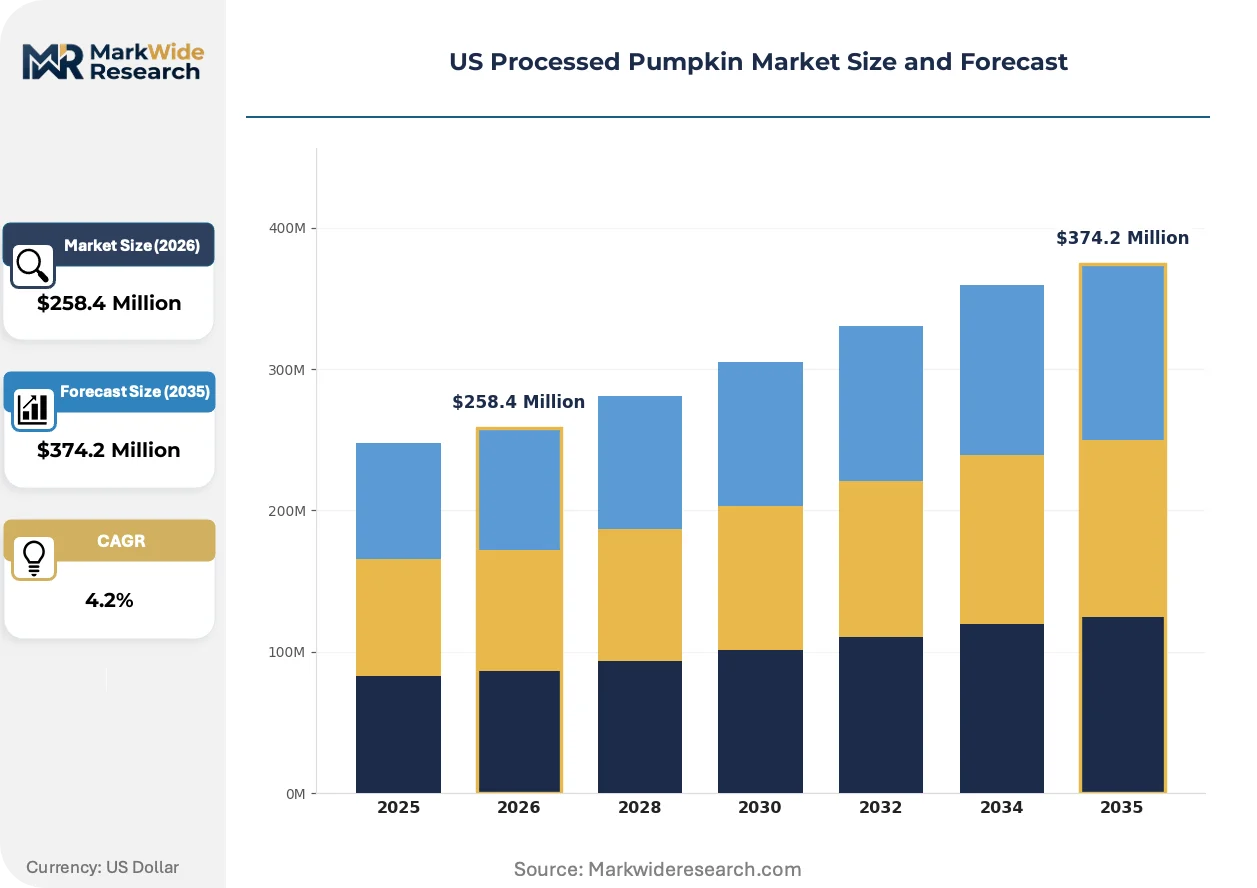
| Market Size in 2026 | $258.4 Million |
| Market Size in 2035 | $374.2 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Pumpkin, Frozen Pumpkin, Dehydrated Pumpkin, Puree Application: Baked Goods, Soups, Sauces, Baby Food Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Farmers' Markets End User: Food Manufacturers, Restaurants, Home Cooks, Catering Services |
| Companies Covered | Kraft Heinz, Woodland Gourmet, Libby's, Alsum Farms and Produce, Döhler, Del Monte Foods, Pinnacle Foods, Pumpkin Patch Fundraisers, Seneca Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Processed Pumpkin Market Strategic Shifts & Innovations
Product development is reshaping the market, shifting processed pumpkin from a seasonal commodity to a versatile, year-round functional ingredient. This evolution is driven by processing technology advancements and a deeper focus on specific nutritional and textural attributes for industrial buyers.
Aseptic packaging technology provides a sterile, shelf-stable alternative to traditional canning. Food manufacturers, particularly in the organic baby food segment, are adopting this format for its superior preservation of flavor, color, and nutrients. Aseptic processing is overtaking conventional canning for premium product lines where quality attributes justify a higher price point.
The FDA's Food Safety Modernization Act (FSMA) mandates comprehensive, prevention-based controls across the food supply chain. This regulation requires processors to implement and document detailed food safety plans, including hazard analysis and risk-based preventive controls. The bakery and prepared foods segments are most affected, responding by upgrading processing equipment and investing in enhanced traceability systems.
Contracting models are evolving from single-season agreements to multi-year partnerships between processors and agricultural cooperatives. This change helps insulate large-scale food manufacturers from annual price volatility and secures supply of specific pumpkin varieties with desired Brix or viscosity levels. This shift in procurement patterns is most pronounced in the Midwest, where major processors seek to stabilize their primary input costs.
US Processed Pumpkin Market Segmentation
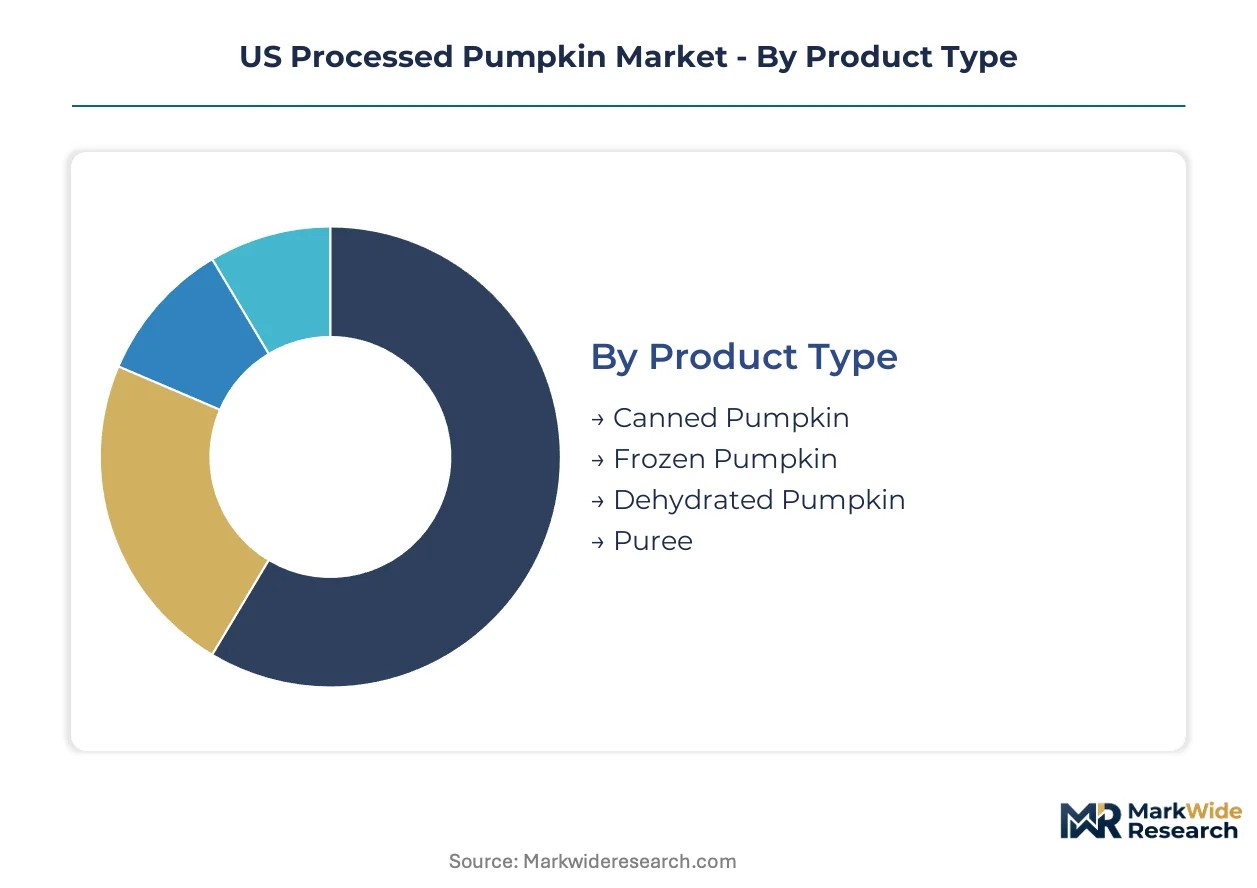
Understanding the varied segments within the US processed pumpkin market reveals distinct consumer needs and industrial applications. This segmentation highlights how product forms, end-uses, distribution methods, and customer types influence procurement strategies and product development across the industry.
Product Type:
Buyers in this category differentiate based on processing method and intended use, influencing shelf stability and specific functional attributes.
- Canned Pumpkin:This traditional format includes solid-pack or puree, cooked and sealed in metal containers for extended shelf life. Demand remains high in seasonal baking applications, particularly in the Midwest, due to its convenience and established consumer familiarity.
- Puree:Finely processed pumpkin flesh, often with controlled Brix levels and viscosity, available in various formats including aseptic pouches. Demand is concentrating in the baby food sector for its clean-label appeal and consistent texture.
- Frozen Pumpkin:Pumpkin prepared and rapidly frozen to preserve freshness and nutritional value. This format is favored by commercial kitchens seeking bulk convenience.
- Dehydrated Pumpkin:Pumpkin processed into flakes or powder, offering lightweight, long-shelf-life options for ingredient manufacturers and nutritional supplements.
Canned Pumpkin leads volumes today; Puree is gaining share fastest.
Application:
Application dictates the required consistency and nutritional profile of processed pumpkin.
- Baked Goods:Utilizes processed pumpkin primarily as a moistening agent and flavor enhancer in pies, breads, and muffins. This application represents the largest end-use category by volume, driven by strong seasonal consumption patterns.
- Baby Food:Requires organic, clean-label pumpkin puree with strict quality control and nutrient retention. This segment is expanding rapidly, leveraging pumpkin's nutritional benefits for infant formulations.
- Soups:Processed pumpkin contributes body, flavor, and color to various soup formulations, from creamy purees to hearty stews.
- Sauces:Pumpkin adds a unique sweetness and thickness to savory sauces, particularly in seasonal and specialty food products.
Demand in Baked Goods shows consistent growth, while Baby Food offers high-margin opportunities.
Distribution Channel:
The reach and consumer convenience of a distribution channel significantly influence product availability and market penetration.
- Supermarkets:Serve as the primary retail channel for conventional canned pumpkin and other processed pumpkin products, offering broad accessibility to a mass consumer base. These large chains facilitate high-volume sales through established supply chains.
- Online Retail:Provides a growing platform for niche and organic processed pumpkin products, enabling direct-to-consumer sales and reaching a wider geographic audience. E-commerce platforms support specialized brands and bulk purchases.
- Specialty Stores:Focus on premium, organic, or gourmet processed pumpkin offerings, catering to consumers seeking unique or high-quality ingredients.
- Farmers' Markets:Offer limited, often seasonal, direct sales of fresh or minimally processed pumpkin products, connecting local growers with consumers.
Mass market availability through Supermarkets underpins volume, while Online Retail captures evolving consumer preferences.
End User:
End-user requirements determine the scale of packaging, product specifications, and consistency of supply for processed pumpkin.
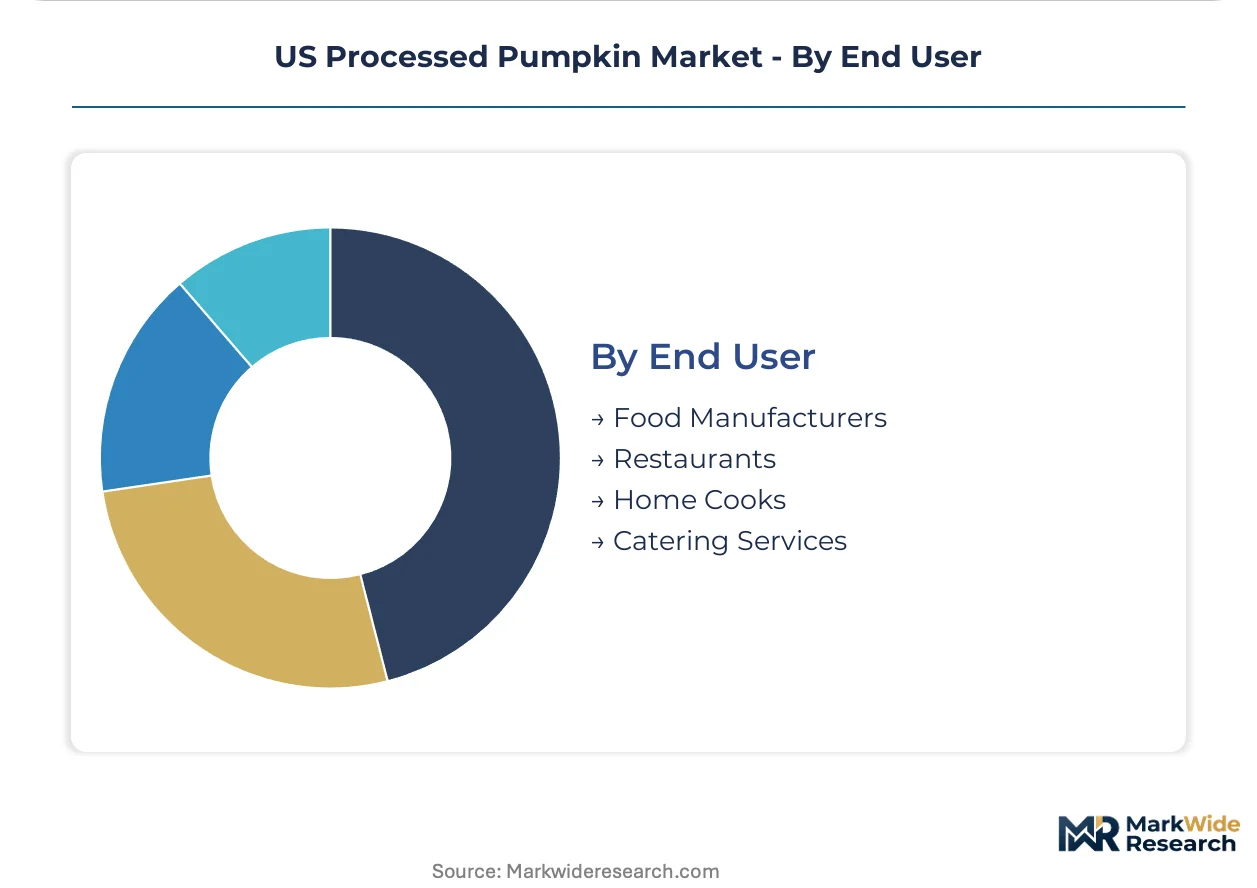
- Food Manufacturers:Represent the largest end-user segment, utilizing processed pumpkin as a key ingredient in numerous products like baby food, baked goods, and prepared meals. These buyers prioritize consistent quality, bulk packaging, and reliable supply contracts.
- Restaurants:Incorporate processed pumpkin into seasonal menus, specialty dishes, and dessert offerings, demanding consistent quality and convenient formats for kitchen efficiency. Foodservice providers value ease of preparation and stable pricing.
- Home Cooks:Primarily purchase canned pumpkin through retail channels for traditional baking and home meal preparation, driven by seasonal demand.
- Catering Services:Use processed pumpkin in large-scale meal production for events and institutions, requiring bulk quantities and consistent product specifications.
Industrial scale demand from Food Manufacturers drives the market, with Restaurants offering growth in value-added applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Midwest's concentration of pumpkin cultivation and processing infrastructure underpins national supply for the US processed pumpkin market. This region provides significant logistical advantages and economies of scale for large-volume production. Demand patterns vary across US sub-regions, reflecting diverse end-use applications and consumer preferences.
Illinois
Large-scale processing operations, particularly for conventional canned pumpkin, drive significant demand in Illinois. The USDA organic certification standards influence product development for premium offerings within the state. Major processors like Libby's maintain extensive canning operations in Illinois, anchoring the national supply chain.
California
Demand for organic pumpkin puree, especially from the baby food sector, is prominent in California. FDA food safety regulations, including FSMA, mandate stringent controls for processors operating within the state. Food manufacturing hubs across California require specialized, clean-label ingredients for various formulations.
Midwest
The broader Midwest region, encompassing states beyond Illinois, exhibits strong demand from baked goods and seasonal consumption patterns. USDA regulations for organic certification impact procurement strategies for agricultural cooperatives across the region. Numerous agricultural cooperatives and processing facilities in the Midwest stabilize primary input costs for food manufacturers.
Northeast
The Northeast region, including states like New York and Pennsylvania, shows growing demand from foodservice expansion and urban consumer markets. State-level food safety and labeling standards complement federal FDA rules for processed food products. Major food manufacturing centers and distribution networks in the Northeast facilitate year-round demand for value-added pumpkin applications.
US Processed Pumpkin Market Key Industry Players
Global majors compete with regional champions across scale of operations and product diversification in the US processed pumpkin market. The conventional segment exhibits consolidation among large-scale processors, while the organic and niche segments show more fragmentation. Large-scale processors, specialized organic producers, and brand-focused marketers represent key strategic archetypes. Multi-year agricultural contracts and optimizing seasonal production capacity are dominant competitive moves.
At the scale-driven end, Libby's sustains its market position through large-scale, proprietary canning operations. Seneca Foods leverages its broad portfolio of canned vegetables to optimize seasonal production capacity and manage agricultural risk. Del Monte Foods competes by emphasizing its extensive brand recognition across national supermarket and online retail channels, securing shelf space for its processed pumpkin offerings.
| Leading Market Players |
|---|
| Kraft Heinz |
| Woodland Gourmet |
| Libby's |
| Alsum Farms and Produce |
| Döhler |
| Del Monte Foods |
| Pinnacle Foods |
| Pumpkin Patch Fundraisers |
| Seneca Foods |
| Others |
Cost & Logistics Intelligence
Seasonal labor availability in key Midwest processing regions creates wage differentials that influence pricing tiers for processed pumpkin products. These labor costs directly impact the profitability of high-volume conventional canning operations versus specialized organic puree production.
Pricing Analysis
Input-cost pass-through from raw pumpkin cultivation significantly shapes pricing for processed pumpkin. The dominant pricing structure combines long-term contract-based offtake agreements for industrial buyers with commodity spot pricing for surplus or less differentiated products. Price differentiation drivers include USDA organic certification status and consistent Brix levels for industrial applications. Pricing pressure stems from agricultural volatility, which can restrict raw material availability. Baby food manufacturers exhibit low price sensitivity for certified organic puree, while home cooks purchasing canned pumpkin remain highly price sensitive.
Supply Chain Analysis
Securing seasonal workforce availability in Midwest manufacturing geographies, particularly Illinois, is a persistent challenge for processors. Geographic supply concentration for raw pumpkin centers primarily on Illinois and other Midwest states. This market depends on specific pumpkin varieties and reliable packaging materials like steel cans and aseptic pouches. A key structural risk is agricultural volatility, including weather disruptions and crop-specific diseases. Downstream distribution runs predominantly through mass-market supermarkets for conventional products and online retail for niche organic offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a margin-expansion story, driven by the premiumization opportunities within the clean-label and functional food segments.
For Market Incumbents: Hedge against agricultural volatility through multi-year contracts with agricultural cooperatives. Consolidate processing capacity in the Midwest to optimize economies of scale and counter rising operational costs. Substitution from other purees poses a threat, necessitating continuous product innovation. Investment in advanced aseptic processing lines represents a key lever for premium product development.
For New Entrants and Emerging Players: Online retail platforms offer direct access to health-conscious consumers seeking specialized ingredients. Target white-space opportunities in pet food formulations and functional food powders. The specialty store segment for organic, ready-to-use pumpkin products is most penetrable. A go-to-market angle emphasizing transparent sourcing and unique nutritional profiles can differentiate offerings.
For Investors and Strategic Acquirers: Large food manufacturers are the most active acquirers in this space, seeking to expand their clean-label portfolios. The market exhibits long-term viability, underpinned by sustained consumer demand for nutritious, plant-based ingredients. Niche organic puree producers or aseptic packaging specialists represent attractive acquisition targets. Consumer preference shifts towards plant-based diets serve as a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Agricultural Contracts | Stabilizes raw material supply and mitigates price volatility for major processors in the US. |
| Investment in Aseptic Processing | Enables premium product lines for baby food and enhances shelf stability without preservatives. |
| Organic Certification Expansion | Captures higher margins from clean-label demand in rapidly growing premium market segments. |
| Functional Food Powder Development | Diversifies product offerings beyond traditional formats and targets the nutritional supplement industry. |
| Foodservice Channel Penetration | Drives year-round demand for value-added pumpkin ingredients in national restaurant chains. |
Research Approach
Multiple input streams — primary interviews, secondary market data, and proprietary databases — were reconciled to construct a comprehensive market view. This study engaged with food manufacturers' procurement managers, baby food R&D specialists, agricultural cooperative leaders, and retail category buyers. Secondary validation drew from USDA agricultural statistics, FDA regulatory guidelines, company annual reports, and trade association publications. Bottom-up and top-down triangulation ensured data accuracy and consistency.
Data-stream reconciliation informed the analytical framework used to project market trends across the analysis window. The model integrated segmentation dimensions including product type, application, distribution channel, end-user, and regional demand. Compound annual growth rates were derived from historical data analysis and projected market drivers. Key industry-specific forecast inputs included pumpkin crop yields and organic ingredient pricing trends.
The model assumes a particular technology adoption path; alternative pathways for aseptic packaging technology would alter the outlook. Forecasts reflect assumptions regarding agricultural stability and sustained consumer preference for clean-label products. Agricultural volatility and changes in consumer dietary preferences represent specific risk factors. Practitioners should monitor new USDA organic standards and major crop disease outbreaks for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Europe Soup Market
Processed Foods
Asia-Pacific Soup Market
Processed Foods
Spray Cheese Market
Processed Foods
Low Fat Chicken Soup Market
Processed Foods
Tomato Paste Market
Processed Foods
United States Food Spread Market
Processed Foods
Processed Potatoes Market
Processed Foods
Fresh Pasta Market
Processed Foods
Pea Processed Ingredients Market
Processed Foods
Block Margarine Market
Processed Foods
Processed Vegetable Market
Processed Foods
Potato Soup Market
Processed Foods
China Freeze-Dried Food Market
Processed Foods
Global Dried Processed Food Market
Processed Foods
Global Potato Flake Market
Processed Foods
Low-Calorie Margarine Market