
 Global Malted Milk Market | 2026-2036
Global Malted Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Global Malted Milk Market Foresight
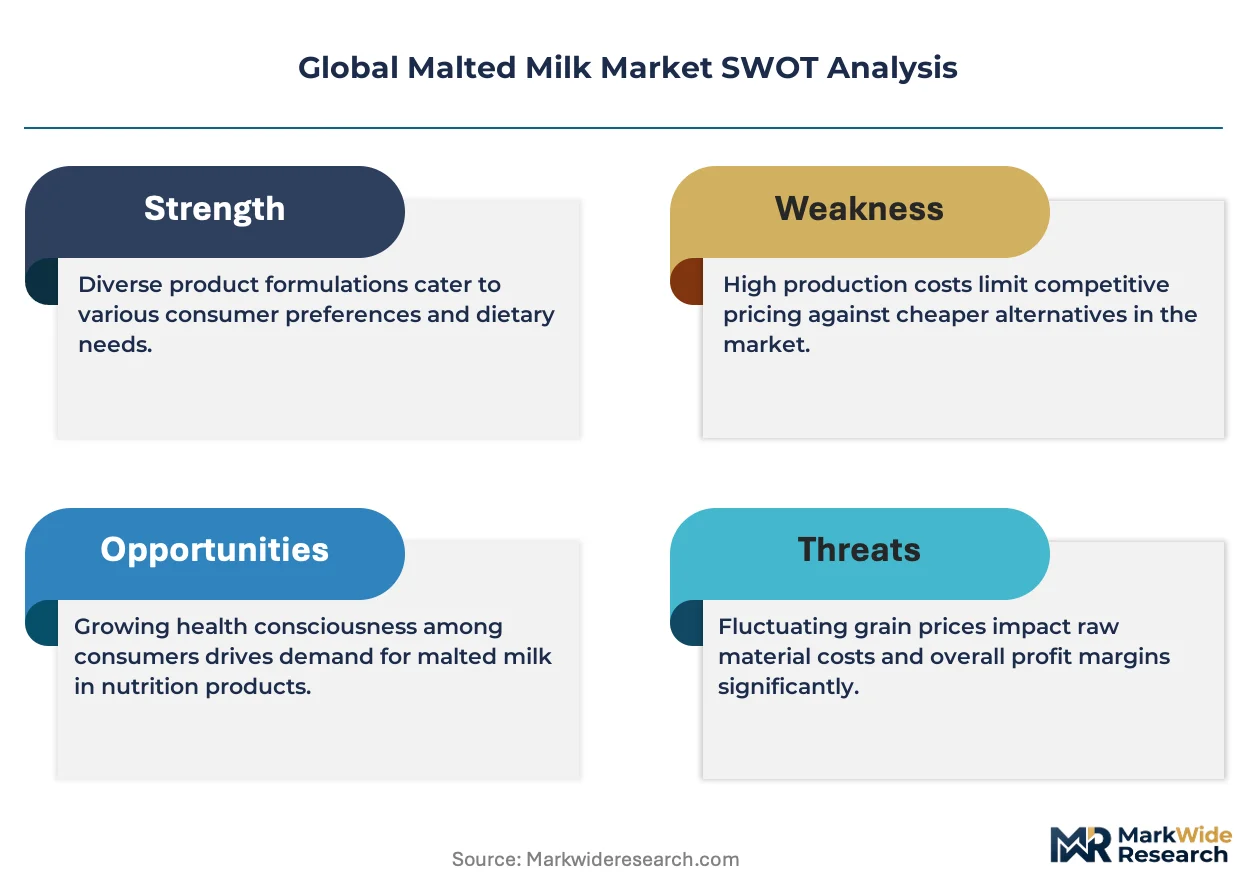
Retail consumers is collapsing toward nutraceutical manufacturers as the dominant buyer archetype for bulk malted milk powder. Nestlé S.A. leverages its backward integration into malt extract production to secure ingredient supply across infant nutrition lines. Associated British Foods Plc anchors its position through specialized malted milk bar formulations targeting sports recovery segments. Briess Malt & Ingredients dominates craft malt supply for premium beverage enhancer applications in North American microbreweries.
Malted milk comprises malted barley or wheat extract combined with milk solids and typically contains 7-8% maltose by weight, produced through controlled germination, kilning, and spray-drying processes. The ingredient functions primarily as a flavor carrier, nutritive additive, and natural sweetener across food and beverage manufacturing. Powdered malted milk sustains the largest volume share due to its extended shelf stability and flexibility across bakery and confectionery formulations, while malted milk drinks represent the fastest-growing product type as ready-to-drink formats gain traction in convenience channels. Instant malted milk occupies the premium tier where solubility performance and clean-label positioning command margin premiums over standard powder grades.
The FDA governs malted milk labeling and fortification claims under its food additive regulations, while EFSA evaluates novel malt extract health claims within the EU nutrition and health claims framework. India's FSSAI mandates specific protein and micronutrient thresholds for products marketed as malted milk foods, directly shaping formulation requirements for exporters. China's SAMR enforces GB standards for dairy-blended powders that affect cross-border malted milk ingredient trade. Stakeholders must monitor evolving front-of-pack labeling mandates across these jurisdictions to anticipate reformulation costs and market access barriers.
Market Dynamics
Sports nutrition manufacturers are consolidating procurement of bulk malted milk powder for protein fortification, compressing traditional retail distribution channels and forcing ingredient suppliers to reconfigure volume contracts toward B2B nutraceutical specifications.
Growth Catalysts
- Protein fortification mandates:India's FSSAI tightening of nutritional labeling requirements for fortified foods is accelerating compliance-driven demand for standardized malted milk ingredients among exporters targeting Indian infant formula processors.
- Dedicated production infrastructure:Brazilian dairy processors building captive malted milk production lines for domestic infant formula supply are expanding regional manufacturing capacity and reducing import dependency.
- Spray-drying process advances:Controlled germination and kilning technologies are improving maltose retention rates, enabling cleaner-label positioning in premium instant malted milk segments.
Market Restraints
- Barley input cost volatility:Malted barley prices fluctuate with agricultural commodity cycles, compressing margins for malt extract producers unable to pass through raw material swings.
- Supply concentration in malted barley:Germination and kilning capacity clusters in traditional malting regions, creating geographic vulnerability for powder manufacturers dependent on distant extract supply.
- Regulatory friction from dual carbon goals:China's MEE enforcement of emissions standards on kilning operations is raising compliance costs for malt extract imports under SAMR's GB standards for dairy-blended powders.
Strategic Opportunities
- Underpenetrated craft beverage channel:North American microbreweries represent expanding demand for premium malt ingredients in beverage enhancer applications beyond traditional food uses.
- Clean-label instant formats:Solubility performance improvements in spray-dried powders command margin premiums in convenience channels where ready-to-drink formats gain traction.
- EU nutrition and health claims framework:EFSA evaluation pathways for novel malt extract health claims create first-mover advantage for substantiated functional positioning in European sports nutrition.
Industry Challenges
- Reformulation talent scarcity:Protein fortification expertise combining dairy science with malt biochemistry remains concentrated among legacy infant nutrition formulators, constraining new market entrants.
- Multi-jurisdiction certification timelines:Simultaneous FDA food additive compliance, FSSAI micronutrient threshold verification, and SAMR GB standard alignment extend product launch cycles.
- Legacy spray-drying asset retrofit costs:Existing powder plants require capital-intensive upgrades to achieve instant-grade solubility specifications demanded by premium channel buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Malted Milk Market |
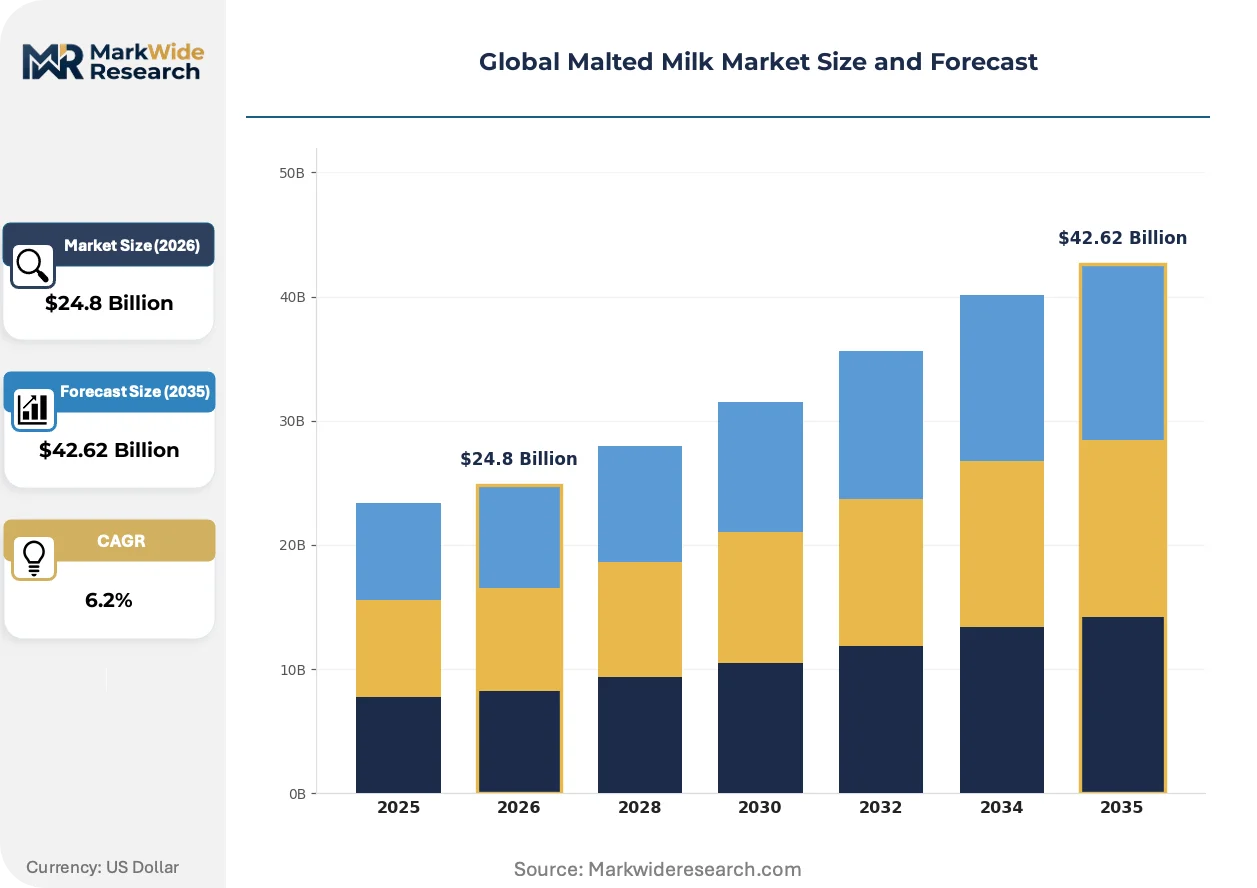
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $42.62 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Malted Milk, Instant Malted Milk, Malted Milk Bars, Malted Milk Drinks Application: Infant Nutrition, Sports Nutrition, Bakery Products, Confectionery Ingredients, Beverage Enhancers Packaging Type: Plastic Jar, Tetra Pak, Glass Bottle, Pouch, Canister End User: Retail Consumers, Food Service Providers, Nutraceutical Manufacturers, Sports Facilities |
| Companies Covered | Nestlé S.A., Unilever Plc, Associated British Foods Plc, GlaxoSmithKline Plc, Mondelēz International, Briess Malt & Ingredients, Muntons plc, Imperial Malts Ltd., Amul, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Malted Milk Market Shifts & Advancements
Clean-label positioning and solubility performance are bifurcating product tiers across the malted milk value chain, with spray-drying technology advances enabling new format differentiation while regulatory substantiation requirements reshape competitive access.
Spray-drying process control systems incorporating real-time moisture monitoring and precision kilning temperature management are improving maltose retention and powder flow characteristics. Nutraceutical manufacturers targeting protein fortification applications are adopting these systems at accelerated pace to meet FSSAI and FDA dual compliance. The technology is bifurcating the market between premium instant grades commanding formulation partnerships and commodity powders relegated to bulk ingredient trading.
REACH registration requirements for novel malt extract derivatives are tightening substance characterization obligations for European market access. Industrial consequence includes extended toxicological study timelines and documentation costs for health claim substantiation under EFSA's nutrition and health claims framework. Sports nutrition segments targeting EU distribution are responding by consolidating supplier relationships with established extract producers possessing existing dossier portfolios.
Buyer concentration among sports nutrition contract manufacturers is displacing traditional foodservice distribution for bulk malted milk powder. Volume contracting directly with germination and kilning operations is replacing multi-tier ingredient trading in North American and European procurement patterns. This behavioral shift is most visible in procurement departments of integrated nutraceutical companies backward integrating into captive malt extract supply arrangements.
Global Malted Milk Market Segmentation
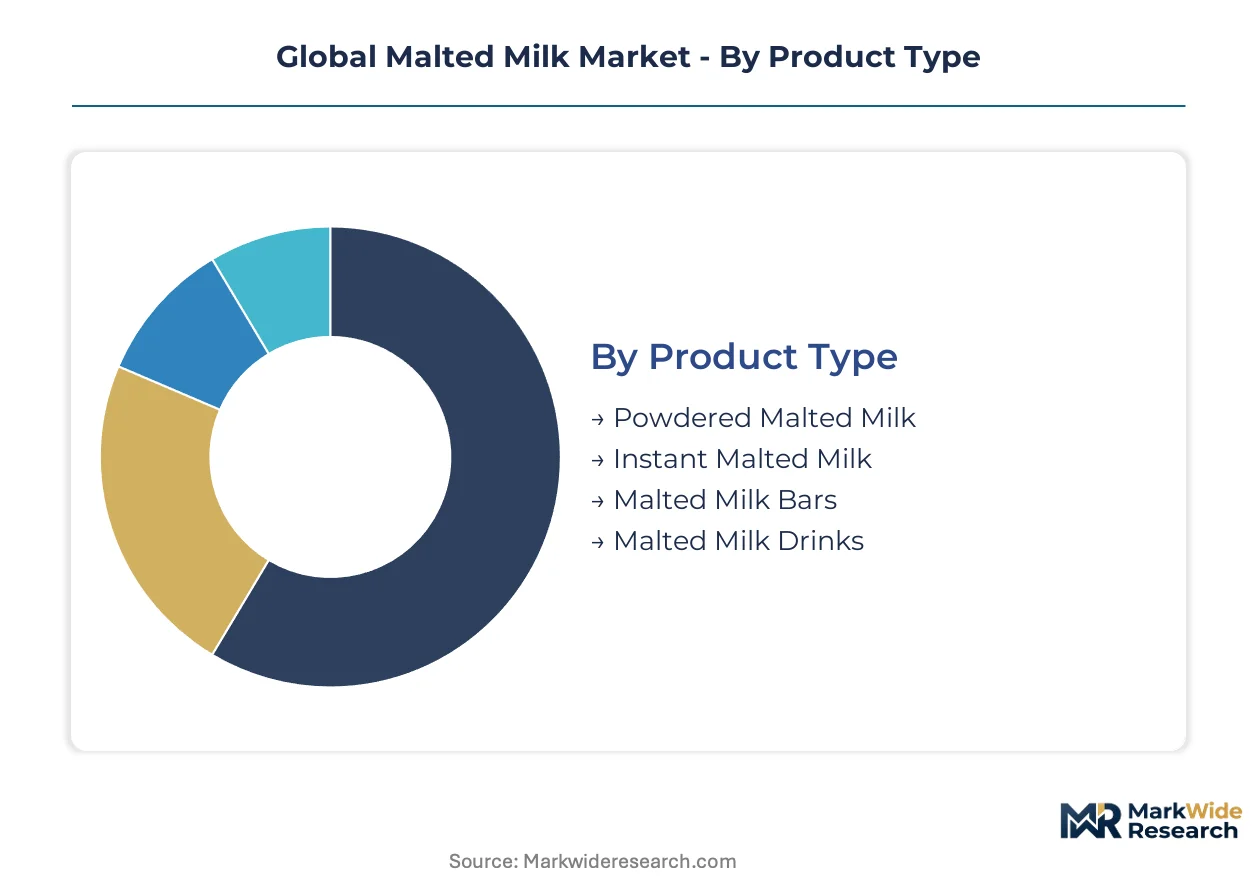
Channel configuration across the malted milk value chain determines which product formats, packaging specifications, and buyer archetypes command procurement priority. Spray-dried powders flow predominantly through B2B nutraceutical channels, while ready-to-drink formats concentrate in retail convenience networks.
Product Type:
Channel-mix dynamics favor powder formats in bulk ingredient procurement, while beverage-ready formats capture shelf-space premiums in direct-to-consumer retail.
- Powdered Malted Milk:Spray-dried maltose-retentive powders with 7-8% maltose by weight serve as the foundational input for bakery, confectionery, and infant formula manufacturing. Demand concentrates among Brazilian dairy processors building captive production lines for domestic infant formula supply, driven by FSSAI compliance requirements for protein-fortified exports to India.
- Instant Malted Milk:Solubility-optimized powders command formulation partnerships through precision kilning temperature management and real-time moisture monitoring. North American microbreweries and premium beverage channels are adopting these grades fastest, where clean-label positioning justifies margin premiums over standard powder grades.
- Malted Milk Bars:Compressed malt extract formulations target sports recovery segments through specialized bar formats. Associated British Foods anchors positioning here.
- Malted Milk Drinks:Ready-to-drink liquid formats gain traction in convenience channels where portability drives purchase decisions. Tetra Pak and glass bottle packaging dominate this flow.
By volume, Powdered Malted Milk leads. By growth pace, Malted Milk Drinks is expanding most quickly.
Application:
Margin tiers separate commodity ingredient supply from substantiated health claim positioning, with regulatory verification costs acting as the sorting mechanism.
- Infant Nutrition:Protein-fortified formulations meeting FSSAI micronutrient thresholds and FDA food additive regulations require dual-compliance documentation. Indian infant formula processors are consolidating supplier relationships with established extract producers possessing existing dossier portfolios.
- Sports Nutrition:EFSA health claim substantiation pathways create first-mover advantage for functional positioning in European markets. Protein fortification expertise combining dairy science with malt biochemistry remains concentrated among legacy formulators.
- Bakery Products:Flavor carrier and natural sweetener functions in bread and pastry applications. Extended shelf stability requirements favor powdered formats.
- Confectionery Ingredients:Maltose sweetness and browning characteristics in chocolate and candy manufacturing. Briess Malt dominates craft supply for premium applications.
- Beverage Enhancers:Malt extract additions to coffee, shakes, and craft beverages. North American microbreweries represent expanding demand beyond traditional food uses.
Sports Nutrition generates the steepest margin expansion. Infant Nutrition maintains the largest absolute volume flow.
Packaging Type:
Supply concentration in germination and kilning regions shapes packaging selection for export versus domestic distribution.
- Plastic Jar:Retail pantry staples for household reconstitution. Moisture barrier properties suit humid climates.
- Tetra Pak:Aseptic liquid malted milk drinks for ambient distribution. Shelf stability enables emerging market penetration.
- Glass Bottle:Premium positioning in convenience channels where perceptual quality drives purchase. Heaviest logistics cost structure.
- Pouch:Single-serve and travel formats for sports facilities and on-premise consumption. Lowest material cost per unit.
- Canister:Bulk powder containment for food service and nutraceutical manufacturing. Nestlé leverages backward integration into captive canister filling.
Plastic Jar holds the highest shipment volume. Pouch formats are climbing the fastest in procurement tenders.
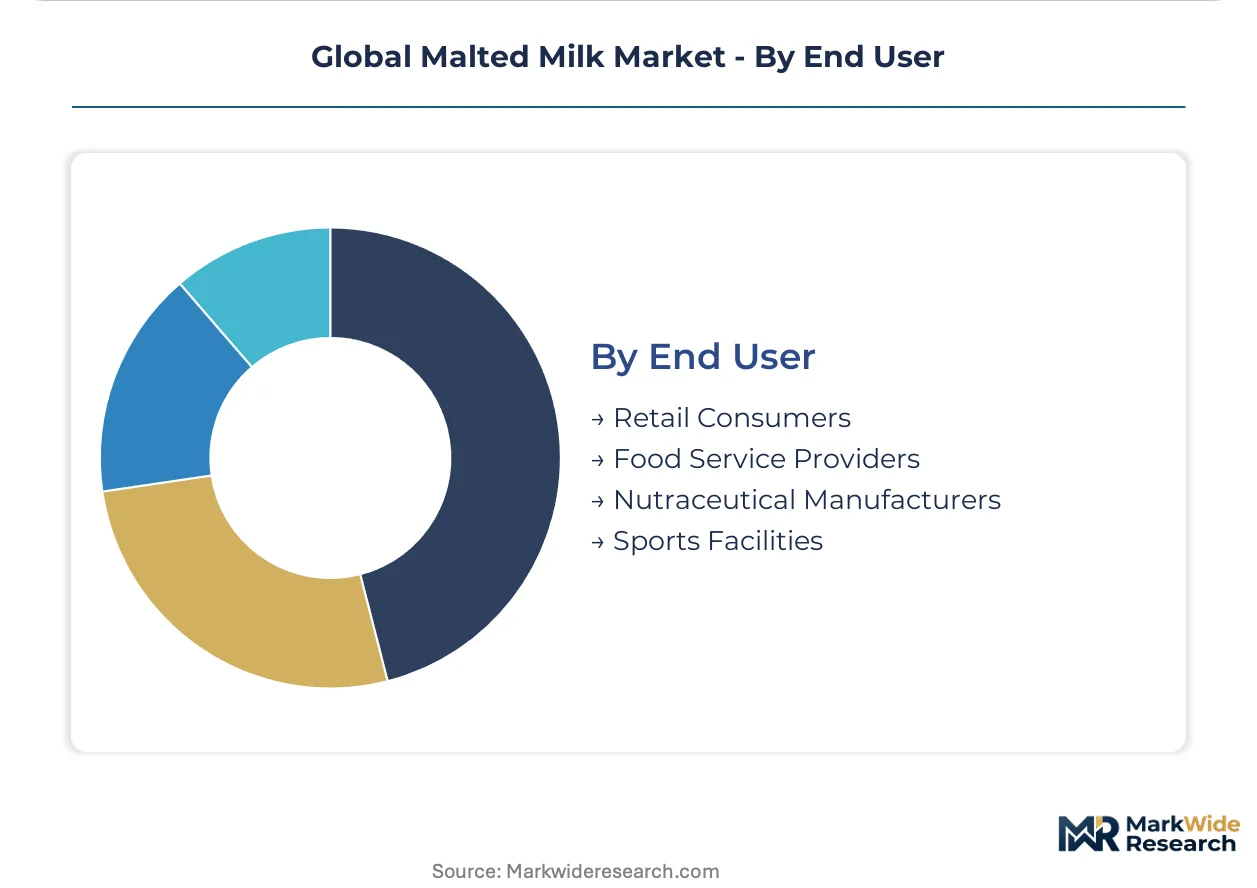
End User:
Buyer concentration is displacing traditional distribution tiers, with direct contracting to germination and kilning operations replacing multi-tier ingredient trading.
- Retail Consumers:Supermarket and e-commerce channels for household consumption. Collapsing share as B2B volumes expand.
- Food Service Providers:Cafeteria, restaurant, and hospitality malted milk beverage service. Standard powder grades dominate.
- Nutraceutical Manufacturers:Protein fortification contract manufacturers consolidating procurement of bulk malted milk powder. Fastest-expanding buyer archetype.
- Sports Facilities:On-premise ready-to-drink dispensing and recovery product retail. Pouch and Tetra Pak formats preferred.
Nutraceutical Manufacturers lead by procurement volume growth. Retail Consumers retain the widest geographic footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian malted milk exports flow predominantly toward Indian infant formula processors, creating a dedicated trade corridor shaped by FSSAI protein fortification mandates and backward integration strategies among South American dairy conglomerates.
United States
North American microbreweries and sports nutrition contract manufacturers drive malt extract procurement for beverage enhancer and protein fortification applications. The FDA governs malted milk labeling under food additive regulations, creating compliance documentation requirements for cross-border ingredient trade. Milwaukee and Denver brewing clusters anchor premium malt ingredient demand beyond traditional food manufacturing.
Germany
Specialized malting equipment and germination technology suppliers concentrate in Bavaria and North Rhine-Westphalia, serving European extract producers. ECHA REACH registration requirements for novel malt derivatives tighten substance characterization obligations for health claim substantiation. Hamburg and Munich house formulation partnerships between legacy maltsters and sports nutrition brands seeking EFSA-compliant functional positioning.
India
Domestic infant formula processors consolidate supplier relationships with established extract producers possessing FSSAI-compliant dossier portfolios for protein-fortified malted milk foods. The FSSAI mandates specific protein and micronutrient thresholds that directly shape import specifications for Brazilian and European suppliers. Gujarat and Maharashtra dairy corridors are building dedicated procurement channels for standardized malted milk ingredients.
China
SAMR enforcement of GB standards for dairy-blended powders affects cross-border malted milk ingredient trade, particularly from Australian and New Zealand extract suppliers. The MEE's emissions standards on kilning operations raise compliance costs for malt extract imports under dual carbon policy implementation. Yangtze River Delta beverage manufacturers are reformulating around domestic malt supply to reduce import dependency.
Brazil
Local dairy processors build captive malted milk production lines for domestic infant formula supply, reducing historical import reliance on Argentine and European extract sources. ANVISA alignment with CODEX standards facilitates regional export positioning toward Mercosur markets. São Paulo and Minas Gerais production clusters are expanding spray-drying capacity for FSSAI-compliant export grades targeting Indian buyers.
Global Malted Milk Market Competitive Landscape
Listed leaders compete with private specialists across backward integration depth and regulatory dossier depth, producing a tiered structure where scale-driven multinationals anchor volume contracts while regional maltsters capture premium craft segments. Three archetypes dominate: diversified food conglomerates with captive extract supply, specialized malt and ingredients producers with germination-to-powder integration, and dairy cooperatives with localized formulation capabilities. Capacity expansion in spray-drying assets and strategic partnerships for multi-jurisdiction certification represent the dominant competitive moves.
Within the diversified conglomerate tier, Nestlé S.A. and Unilever Plc exemplify scale-driven players leveraging global procurement networks, while Associated British Foods Plc occupies a specialized position in malted milk bar formulations. Among ingredients specialists, Briess Malt & Ingredients and Muntons plc represent germination-to-powder integrated producers with established regulatory dossier portfolios for EFSA and FDA compliance pathways.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Unilever Plc |
| Associated British Foods Plc |
| GlaxoSmithKline Plc |
| Mondelēz International |
| Briess Malt & Ingredients |
| Muntons plc |
| Imperial Malts Ltd. |
| Amul |
| Others |
Supply & Pricing Matrix
India's FSSAI protein fortification mandates gate both supplier qualification and price tiering simultaneously, as exporters must absorb dual-compliance documentation costs to access Indian infant formula processors while clean-label instant grades command formulation premiums over commodity powders.
Pricing Analysis
Standard spray-dried powders, instant solubility-optimized grades, and next-generation precision-kilned extracts occupy distinct price bands. Three-tier pricing structure across premium, standard, and economy levels separates FSSAI-compliant export grades from domestic commodity supply and craft microbrewery specialty malts. Cost compression in standard powder tiers is intensifying because Brazilian captive production lines are displacing Argentine import volumes. Nutraceutical manufacturers show least price sensitivity due to backward integration imperatives, while foodservice providers remain most elastic.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes and container availability constraints on Brazil-India routes are elevating landed costs for malt extract shipments. Germination and kilning capacity clusters in Germany, the United Kingdom, and Brazil feed spray-drying operations across three continents. Malted barley, milk solids, and specialized malting equipment constitute the core input stack. Single-source vulnerability concentrates in Bavarian equipment suppliers. Distribution runs through direct B2B nutraceutical contracting rather than multi-tier ingredient trading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer fragmentation across sports nutrition contract manufacturers, craft beverage channels, and infant formula processors creates multiple specialization niches for targeted positioning.
For Market Incumbents: Compound regulatory dossier depth through EFSA health claim substantiation investments and FSSAI certification expansion. Nestlé's backward integration into malt extract production demonstrates how captive supply buffers barley input cost volatility. Capacity addition in São Paulo spray-drying clusters defends Brazilian export positioning against rising Chinese domestic malt supply. For New Entrants and Emerging Players: Differentiate on clean-label instant solubility performance for North American microbrewery beverage enhancer applications. The underpenetrated craft channel offers lowest certification barriers compared to infant nutrition's dual-compliance requirements. Direct formulation partnerships with sports recovery brands bypass established distribution tiers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed malt ingredients specialists possessing established EFSA and FDA dossier portfolios but limited geographic footprint expansion. The five-to-ten year viability window favors producers with germination-to-powder integration and multi-jurisdiction certification capabilities. Watch for FSSAI threshold tightening as inflection signal for consolidation urgency among fragmented Indian import suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Malt Extract | Nestlé's captive supply secures infant nutrition lines against barley price volatility. |
| Spray-Drying Capacity Expansion | Brazilian processors target FSSAI-compliant export grades for Indian infant formula demand. |
| EFSA Health Claim Substantiation | First-mover functional positioning captures European sports nutrition margin premiums. |
| Clean-Label Instant Format Development | Solubility-optimized powders command partnerships in premium convenience channels. |
| Multi-Jurisdiction Certification Investment | Dual FDA-FSSAI compliance documentation accelerates product launch cycles for exporters. |
Research Methodology
The analysis maps malted milk powder grades, instant solubility tiers, and beverage-ready formats, each validated through procurement directors at nutraceutical contract manufacturers, formulation scientists at infant nutrition processors, and malting operations managers. Primary interviews with sports nutrition brand managers, craft brewery purchasing leads, and regulatory affairs specialists at extract producers combined with secondary validation against FSSAI fortification guidelines, FDA food additive regulations, and EFSA health claim databases. Bottom-up volume modeling and top-down value triangulation anchored forecast outputs.
Consistency checks against external benchmarks validated projection outputs across the analysis window. Segmentation dimensions modeled include product type, application category, packaging format, and end-user archetype, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derived from trend extrapolation of procurement volume shifts and capacity expansion announcements, incorporating barley commodity cycle patterns and spray-drying technology adoption curves as industry-specific inputs.
Material uncertainties — regulatory threshold revisions, kilning emissions enforcement intensification, and germination capacity relocation — sit outside the modeled envelope. Forecasts reflect documented assumptions about compliance timeline stability and trade lane cost structures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Europe Processed Egg Market
Processed Foods
Butter Crisco Market
Processed Foods
Broth Market
Processed Foods
Global Pasta Market
Processed Foods
Global Potato Flake Market
Processed Foods
Ready to Serve Prefabricated Dishes Market
Processed Foods
Fat Free Food Market
Processed Foods
Low Fat Pasta Market
Processed Foods
Processed Mango Products Market
Processed Foods
Mashed Potatoes Market
Processed Foods
Egg Powder Market
Processed Foods
United States Egg Powder Market
Processed Foods
Chocolate Filling Market
Processed Foods
Imitation Whipped Cream Market
Processed Foods
Accompanying Marinated Product Market
Processed Foods
Europe Soup Market