
 India Spray Dried Food Market | 2026-2036
India Spray Dried Food Market Size, Share, and Industry Trends Forecast 2026-2036
India Spray Dried Food Market Foresight
The instant beverage sector is rebalancing toward spray dried coffee and milk powders as food manufacturers reformulate for longer shelf stability and cleaner labels. Nestlé sustains technology leadership in soluble coffee extraction and spray drying systems across South Indian processing corridors. GCMMF (Amul) anchors national milk powder supply through its Gujarat-based dairy cooperative network. Tata Consumer Products competes in premium instant beverage blends with integrated sourcing from Assam and Nilgiri estates.
Spray dried food refers to thermally processed powders produced by atomizing liquid feedstock into a heated air stream, typically operating at inlet temperatures between 150°C and 250°C to preserve flavor volatiles and achieve moisture content below 5%. The resulting powders serve as shelf-stable ingredients for reconstitution in commercial food production and retail consumer preparation. Milk powder occupies the dominant value share among product types, reflecting India's position as the world's largest milk producer and the structural dependence of confectionery and infant nutrition on domestically processed dairy solids. Coffee powder represents the fastest-growing product category, driven by café chain expansion and single-serve format proliferation in urban markets. Among applications, beverages command the largest volume throughput, while sauces generate higher per-kilogram margins due to customized tomato and spice powder formulations for quick-service restaurant supply chains.
FSSAI mandates on additive limits and labeling transparency directly shape product development cycles for spray dried ingredient suppliers seeking national distribution clearance. BIS certification requirements for milk powder density and solubility indices create compliance thresholds that filter smaller unorganized processors from institutional procurement channels. The PLI scheme for food processing infrastructure subsidizes capital expenditure on automated spray drying towers, accelerating capacity modernization in Madhya Pradesh and Karnataka. Stakeholders must monitor evolving FSSAI fortification rules and state-level dairy cooperative consolidation patterns to align capacity investments with downstream demand trajectories.
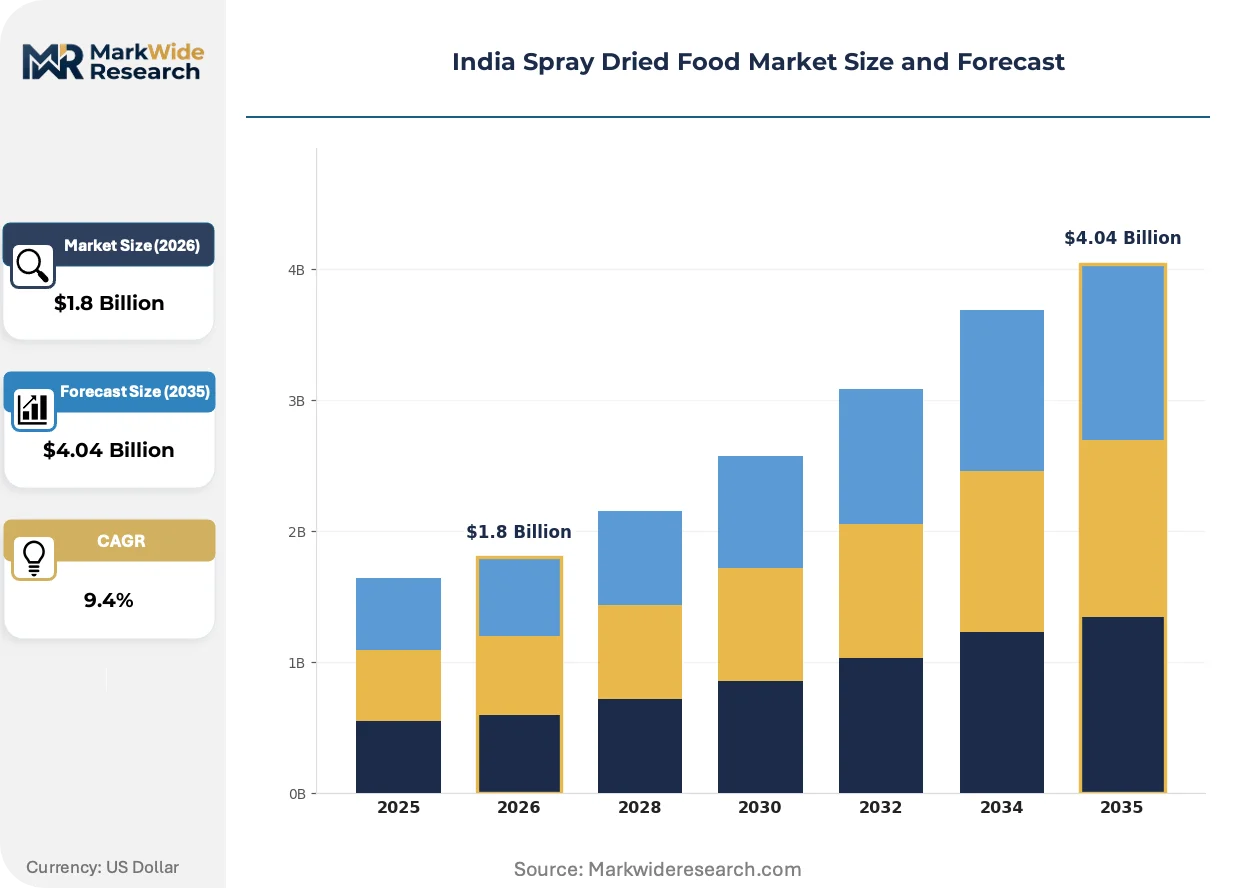
Market Dynamics
FSSAI fortification mandates and BIS density specifications are compressing supplier margins while filtering unorganized processors from institutional channels. Maharashtra and Gujarat dairy cooperatives now dominate procurement flows for spray dried milk powders.
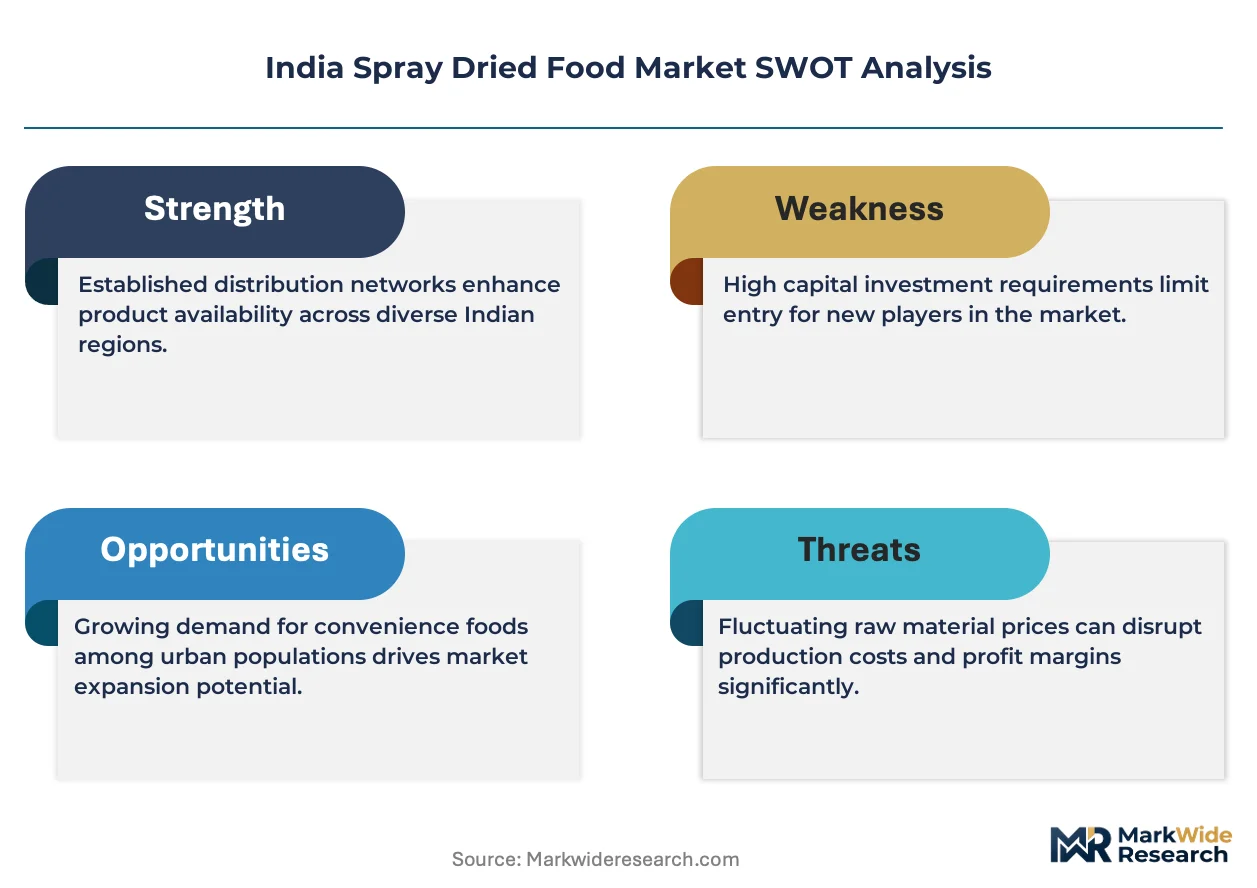
Growth Catalysts
- PLI scheme subsidies:The food processing infrastructure incentive accelerates automated spray drying tower installations in Madhya Pradesh and Karnataka, reducing capital recovery periods for mid-scale processors.
- Café chain proliferation:Single-serve format demand in urban markets pulls procurement volumes for spray dried coffee powder through quick-service restaurant supply chains.
- FSSAI fortification rules:Mandatory micronutrient addition to milk powders creates specification tiers that premium processors exploit for institutional contract capture.
Market Restraints
- Natural gas price volatility:Thermal energy inputs for inlet air heating constitute 35-40% of operating costs, exposing margins to fuel market swings.
- Gujarat-Maharashtra supply concentration:Over 60% of installed spray drying capacity sits within 300 kilometers of Anand and Pune, creating regional disruption risk.
- Freeze-drying substitution:Premium nutraceutical and probiotic applications increasingly specify lyophilization for volatile retention, capping spray drying's addressable premium segment.
Strategic Opportunities
- Northeast dairy catchment:Assam and West Bengal milk surplus remains underprocessed for powder conversion, offering first-mover capacity positioning.
- Customized sauce powder formulations:Quick-service restaurant chains seek proprietary tomato and spice blends with specific reconstitution profiles.
- Direct-to-manufacturer platforms:B2B ingredient marketplaces bypass traditional distributor markups for mid-sized confectionery and bakery buyers.
Industry Challenges
- Process automation talent scarcity:PLC programming and spray nozzle calibration expertise concentrates in Gujarat dairy clusters, constraining expansion timelines elsewhere.
- BIS certification timelines:Solubility index and bulk density testing queues at accredited laboratories extend product launch cycles by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Spray Dried Food Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk Powder, Egg Powder, Coffee Powder, Tomato Powder Application: Bakery, Beverages, Confectionery, Sauces Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Food Service End User: Households, Food Manufacturers, Restaurants, Catering Services |
| Companies Covered | Vinayak Ingredients, Drytech Processes, Nestlé, Tata Consumer Products, Mevive International, GCMMF (Amul), Aarkay Food Products Ltd, Hatsun Agro Product Ltd, Givaudan SA (Naturex), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Spray Dried Food Market Shifts & Advancements
Atomization control systems and closed-loop thermal management are reshaping powder quality consistency. Regulatory fortification mandates and direct procurement platforms are simultaneously compressing legacy supply structures.
Low-temperature spray drying is expanding into heat-sensitive ingredient categories previously reserved for freeze-drying. Probiotic and enzyme powder manufacturers in Karnataka pilot inlet air temperatures below 120°C to preserve cell viability. This thermal envelope compression is expanding into nutraceutical contract manufacturing, enabling domestic suppliers to bid for pharmaceutical adjuvant contracts previously sourced from European lyophilization specialists.
FSSAI's 2023 micronutrient premix mandate for standardized milk powders has triggered reformulation cycles across cooperative and private dairy processors. The regulation requires iron, folic acid, and vitamin A integration at spray drying stage, not post-blending. Large-format processors in Gujarat have absorbed premix infrastructure costs fastest, while smaller Maharashtra units face equipment retrofit delays that freeze their institutional eligibility.
Urban café chains now specify direct supplier relationships with spray dried coffee processors, displacing traditional spice trade intermediaries. Third-wave coffee roasters in Bengaluru and Mumbai contract directly with Chikmagalur and Coorg estate processors for single-origin soluble extracts. This channel disintermediation concentrates volume with processors holding integrated extraction-to-powder capabilities, marginalizing traders lacking drying asset control.
India Spray Dried Food Market Segmentation
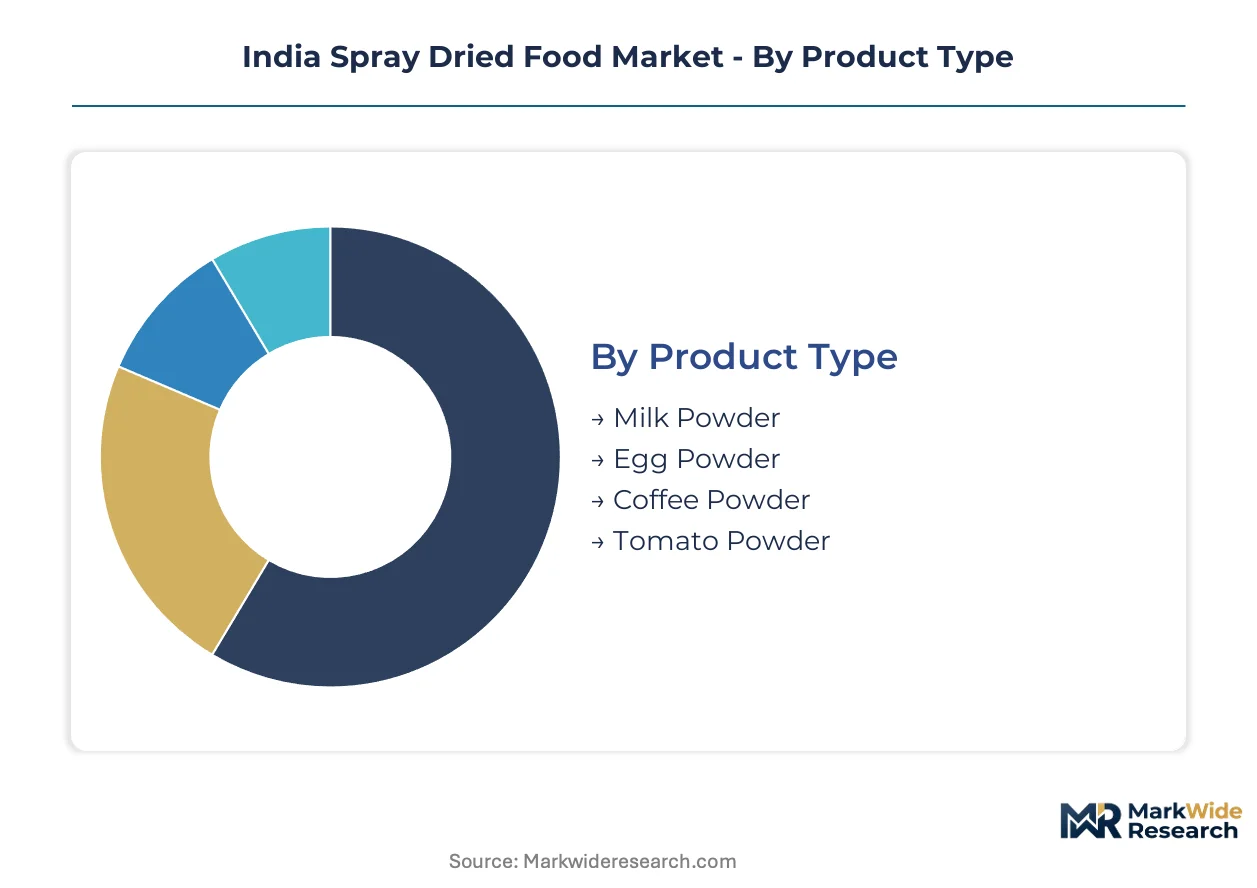
Spray dried food procurement patterns diverge sharply between commodity bulk buyers and specialty ingredient seekers. Understanding these segment boundaries clarifies where technology investments concentrate versus where price competition dominates.
Product Type:
Standalone powder formats command direct retail premiums, while embedded ingredient powders sell through B2B contracts with tighter specification windows.
- Milk Powder:Standardized dairy solids with fat content ranging from full-cream to skim variants, processed through multi-stage evaporation before atomization. Gujarat and Maharashtra dairy cooperatives supply institutional confectionery and infant nutrition manufacturers under FSSAI fortification mandates. BIS density and solubility specifications filter smaller processors from national distribution channels.
- Coffee Powder:Soluble extracts from Robusta-Arabica blends, spray dried at controlled inlet temperatures to preserve volatile aromatic compounds. Bengaluru and Mumbai café chains now contract directly with Chikmagalur estate processors, displacing traditional spice trade intermediaries for single-origin soluble formats.
- Egg Powder:Dehydrated whole egg and yolk fractions used in bakery premixes and pasta manufacturing.
- Tomato Powder:Concentrated solids for sauce reconstitution in quick-service restaurant supply chains.
Milk powder leads volumes today; coffee powder is gaining share fastest.
Application:
Volume throughput concentrates in high-frequency consumption categories, while margin extraction favors customized industrial formulations.
- Beverages:Instant coffee and milk-based drink mixes requiring rapid reconstitution without sedimentation. Urban single-serve format proliferation pulls procurement through quick-service restaurant supply chains and vending machine networks.
- Sauces:Customized tomato and spice powder blends with specific viscosity profiles upon rehydration. Quick-service restaurant chains specify proprietary formulations that generate higher per-kilogram margins than commodity powders.
- Bakery:Egg and milk powders for premix stability and extended shelf life in packaged goods.
- Confectionery:Dairy solids for chocolate and candy manufacturing.
Beverages dominate absolute throughput; sauces deliver the steepest margin expansion.
Distribution Channel:
Channel selection tracks buyer scale and specification complexity, with large manufacturers bypassing traditional intermediaries.
- Food Service:Direct bulk procurement by restaurant chains and institutional caterers with technical specification teams. This channel captures the largest B2B volumes for standardized milk and coffee powders.
- Supermarkets:Packaged retail formats for household reconstitution, competing on brand recognition and fortification labeling.
- Online Retail:Specialty and organic spray dried products reaching urban consumers.
- Convenience Stores:Single-serve sachets for immediate consumption.
Food service channels move the most tonnage; online retail is climbing the fastest.
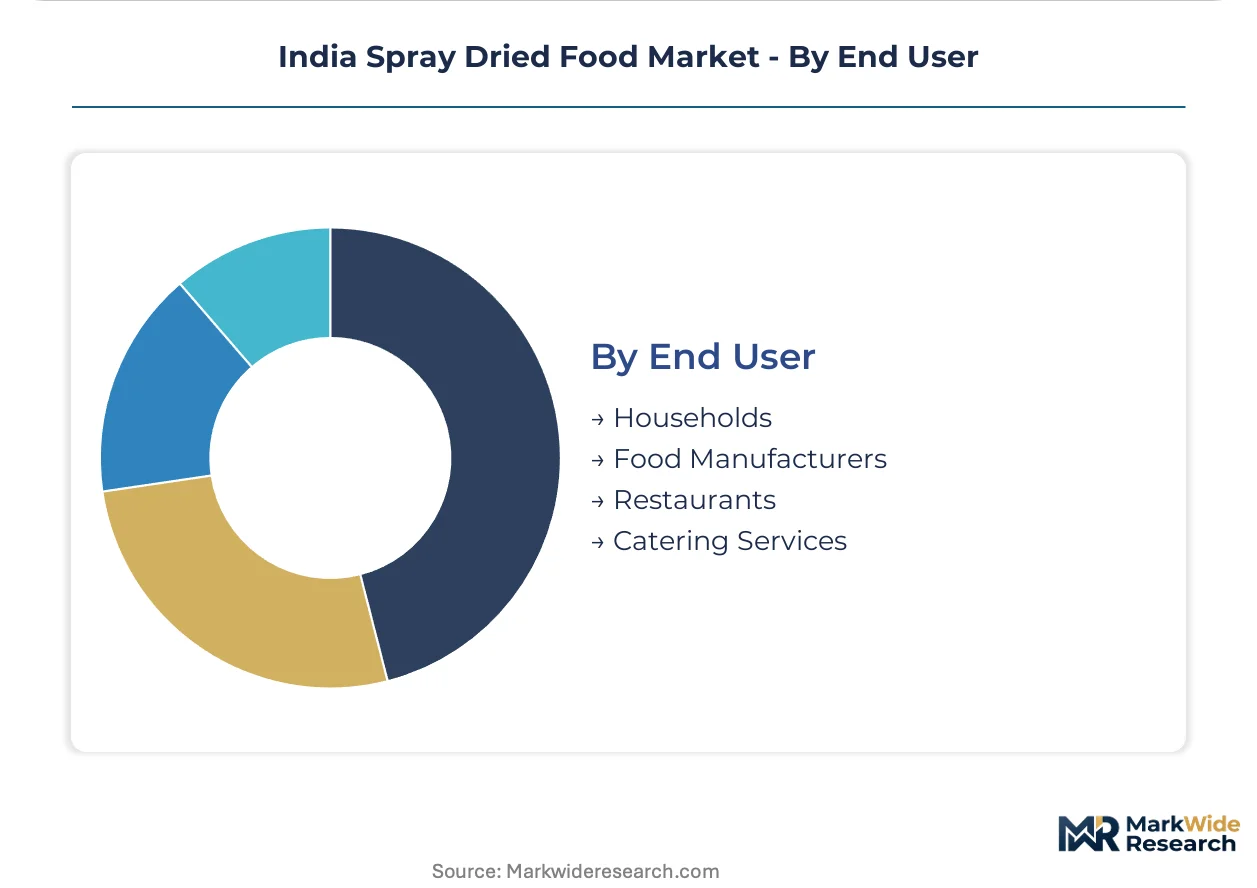
End User:
User sophistication determines whether procurement prioritizes commodity pricing or technical specification compliance.
- Food Manufacturers:Industrial buyers with in-house quality labs validating solubility indices and microbial loads. These buyers drive specification tightening under FSSAI and BIS mandates.
- Restaurants:Mid-scale operators seeking consistent reconstitution performance without capital investment in blending equipment.
- Households:Retail consumers purchasing packaged formats for convenience.
- Catering Services:Volume buyers for event and institutional feeding.
Food manufacturers anchor procurement volumes today; restaurant direct-sourcing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting spray dried food production toward states with lower compliance friction and subsidized infrastructure. Gujarat and Maharashtra maintain capacity dominance, while Karnataka and Madhya Pradesh attract new investment through PLI scheme incentives.
Maharashtra
Pune-based dairy cooperatives and instant beverage manufacturers drive procurement volumes for spray dried milk and coffee powders. FSSAI fortification mandates require micronutrient premix integration at the drying stage, filtering smaller processors from institutional channels. The Pune-Ahmednagar corridor hosts concentrated spray drying tower installations serving quick-service restaurant supply chains.
Gujarat
Anand-centered dairy networks anchor national milk powder supply under GCMMF cooperative structures. BIS density and solubility specifications create compliance thresholds that organized processors exploit for contract capture. The Anand-Vadodara belt concentrates multi-stage evaporation and atomization capacity for confectionery and infant nutrition ingredient supply.
Karnataka
Bengaluru café chains and third-wave coffee roasters pull single-origin soluble extract demand through direct estate contracts. PLI scheme subsidies accelerate automated spray drying tower installations, reducing capital recovery periods for mid-scale processors. The Chikmagalur-Coorg highlands supply arabica-robusta blends for premium instant beverage formulation.
Madhya Pradesh
Underprocessed milk surplus in the Indore-Ujjain catchment offers first-mover positioning for powder conversion capacity. Central government food processing infrastructure incentives subsidize thermal energy system upgrades for inlet air heating optimization. The Malwa plateau is attracting dairy cooperative expansion from Gujarat-based parent federations seeking geographic diversification.
West Bengal
Hooghly basin milk production exceeds local processing capacity, creating arbitrage opportunities for spray dried ingredient supply to eastern markets. State dairy development schemes support cooperative consolidation to meet FSSAI quality mandates for national distribution eligibility. The Kolkata metropolitan area generates concentrated food service demand for customized sauce and spice powder formulations.
India Spray Dried Food Market Competitive Landscape
Capacity expansion dominates the current landscape as PLI scheme beneficiaries scale automated tower installations. The market exhibits tiered consolidation: organized dairy cooperatives and multinational extractors control institutional channels, while regional specialists serve customized quick-service restaurant formulations. Two strategic archetypes prevail—vertically integrated estate-to-powder processors and technology-licensed toll manufacturers. Competitive intensity concentrates on BIS certification speed and direct procurement platform integration.
Among multinational food extractors, Nestlé and Givaudan SA (Naturex) occupy positions emphasizing soluble coffee and natural ingredient preservation technology respectively. Tata Consumer Products represents the integrated beverage blend archetype with upstream estate control. Domestic dairy cooperatives exemplify scale-driven supply security, with GCMMF (Amul) anchoring national milk powder throughput through Gujarat-based processing networks. Regional specialists including Vinayak Ingredients and Mevive International sit within the customized formulation tier, serving proprietary sauce and spice powder specifications for restaurant chains.
| Leading Market Players |
|---|
| Vinayak Ingredients |
| Drytech Processes |
| Nestlé |
| Tata Consumer Products |
| Mevive International |
| GCMMF (Amul) |
| Aarkay Food Products Ltd |
| Hatsun Agro Product Ltd |
| Givaudan SA (Naturex) |
| Others |
Supply & Pricing Matrix
Food service procurement teams at quick-service restaurant chains command pricing leverage through direct bulk contracting, compressing distributor margins while rewarding processors holding integrated extraction-to-powder capabilities with premium tier access.
Pricing Analysis
Distributor markups of 12-18 percent on commodity milk powders are collapsing as institutional buyers shift to direct manufacturer relationships. Three-tier pricing structure across premium fortified, standard BIS-certified, and economy unorganized tiers separates processors by FSSAI compliance depth. Pricing pressure stems from natural gas cost volatility feeding thermal energy inputs. Quick-service restaurant chains exhibit highest price sensitivity due to standardized menu costing, while infant nutrition manufacturers absorb premiums for certified supply security.
Supply Chain Analysis
Direct-to-manufacturer channels handle hyperscale dairy cooperative procurement, bypassing traditional trader networks. Raw material sourcing draws from Gujarat and Maharashtra milk surplus belts, with Chikmagalur estate coffee supplying soluble extract feedstock. Natural gas price volatility constitutes the dominant supply chain risk for thermal energy-dependent atomization. Distribution runs through cooperative federations for institutional volumes and B2B ingredient platforms for mid-scale bakery and confectionery buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in spray dried food processing rests on thermal energy cost optimization and premium-tier fortification compliance separating organized from unorganized supply.
For Market Incumbents: Hedge against freeze-drying substitution in nutraceutical applications by piloting low-temperature spray drying below 120°C for probiotic retention. Absorb premix infrastructure costs ahead of FSSAI fortification mandate expansion to freeze smaller competitors from institutional eligibility. Anchor capacity in Madhya Pradesh through PLI scheme subsidies to diversify beyond Gujarat-Maharashtra concentration risk. For New Entrants and Emerging Players: Launch via direct-to-manufacturer B2B platforms targeting mid-scale confectionery buyers underserved by cooperative federations. Exploit underprocessed milk surplus in Assam and West Bengal for first-mover powder conversion positioning. Capture quick-service restaurant sauce formulation contracts through proprietary viscosity-profile customization. For Investors and Strategic Acquirers: Dairy cooperatives seeking geographic diversification are the most active acquirer in this space, consolidating regional processors to secure national distribution eligibility. Target mid-scale processors holding BIS certification but lacking capital for automated tower upgrades. Monitor PLI scheme disbursement velocity as inflection indicator for capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Spray Drying Tower Installation | PLI scheme subsidies compress capital recovery periods for Madhya Pradesh and Karnataka processors. |
| Direct Estate Contracting | Bengaluru café chains displace spice trade intermediaries for Chikmagalur single-origin soluble extracts. |
| Micronutrient Premix Integration | FSSAI fortification mandates require iron and folic acid addition at drying stage, not post-blending. |
| Low-Temperature Thermal Envelope Expansion | Karnataka probiotic manufacturers pilot sub-120°C inlet air to bid for pharmaceutical adjuvant contracts. |
| B2B Ingredient Platform Integration | Mid-scale bakery and confectionery buyers bypass distributor markups through direct procurement channels. |
Research Methodology
Bottom-up beverage and sauce application modeling reconciled against top-down dairy cooperative capacity tracking forms the analytical core of this study. Primary interviews with spray drying plant managers, FSSAI regulatory affairs leads, quick-service restaurant procurement directors, and cooperative federation supply planners combined with secondary validation from BIS certification databases, FSSAI fortification notifications, PLI scheme disbursement records, and customs trade data on milk powder flows.
Historical trendline analysis of installed spray drying capacity and procurement volume trajectories informed the projection framework. Segmentation dimensions span product type, application category, distribution channel, and end-user sophistication tier across the modeling period. CAGRs derive from regression analysis of capacity utilization rates and downstream demand elasticity, with natural gas price scenarios and FSSAI regulatory phase-in schedules as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged BIS certification queue delays or abrupt FSSAI additive specification revisions. Projections reflect assumptions on cooperative consolidation velocity and PLI scheme geographic disbursement patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
North America Soup Market
Processed Foods
Fat Free Soup Market
Processed Foods
Margarine Market
Processed Foods
Tomato Puree Market
Processed Foods
Europe Processed Egg Market
Processed Foods
Fermented Food and Drinks Market
Processed Foods
Block Margarine Market
Processed Foods
Middle East and Africa Processed Meat Market
Processed Foods
Imitation Whipped Cream Market
Processed Foods
Fermented Foods Market
Processed Foods
Processed Potatoes Market
Processed Foods
US Tomato Paste Market
Processed Foods
Fast-Food Reusable Market
Processed Foods
Global Potato Flake Market
Processed Foods
Fruit Processing Market
Processed Foods
Yogurt Dip Market