
 United States Processed Meat Market | 2026-2036
United States Processed Meat Market Size, Share, and Industry Trends Forecast 2026-2036
United States Processed Meat Market Analytics
Subscription-based cold-chain monitoring and maintenance contracts is consolidating recurring revenue around shelf-life guarantees rather than one-time product sales. Tyson Foods leverages its vertically integrated feed-to-retail network to sustain margin control across volatile input cycles. JBS USA anchors large-scale beef and pork processing capacity in the High Plains and Midwest. Hormel Foods differentiates through branded deli and bacon portfolios that command premium placement in retail.
Processed meat encompasses muscle tissue subjected to curing, smoking, fermentation, thermal processing, or mechanical restructuring to extend shelf stability, enhance flavor, and ensure pathogen elimination, with sodium content, water activity, and nitrite levels serving as critical safety and quality parameters. Deli meats and bacon occupy the largest volume positions, while fresh sausage captures faster growth as consumers shift toward perceived less-processed formats. Vacuum packaging dominates institutional and club channels, though retail packs and chubs expand in grocery and convenience store segments where portion flexibility drives purchase frequency.
USDA-FSIS inspection protocols and HACCP mandates govern slaughter and further-processing facilities, while FDA oversees ingredient additives and nutrition labeling under FSMA authorities. OSHA workplace safety standards and EPA effluent limitations shape capital allocation toward automation and wastewater treatment. State-level California Proposition 65 warnings and Massachusetts animal confinement regulations create compliance patchwork that processors must navigate. Stakeholders should monitor how cell-cultured protein labeling rulemakings and sodium reduction guidance reshape product formulation priorities and competitive positioning.
Market Dynamics
USDA-FSIS labeling mandates are compressing formulation timelines while cold-chain subscription models shift processor revenue from unit sales to shelf-life guarantees.
Growth Catalysts
- Proposition 65 compliance infrastructure:California's warning-label requirements have spawned specialized formulation services that processors now bundle nationwide as premium advisory offerings.
- Feedlot-to-retail traceability:RFID-enabled lot tracking from High Plains cattle operations through further-processing facilities satisfies institutional buyer audit demands.
- High Plains processing concentration:Clustered slaughter capacity within 200 miles of major feedlots minimizes live-haul stress and dark-cutting losses.
Market Restraints
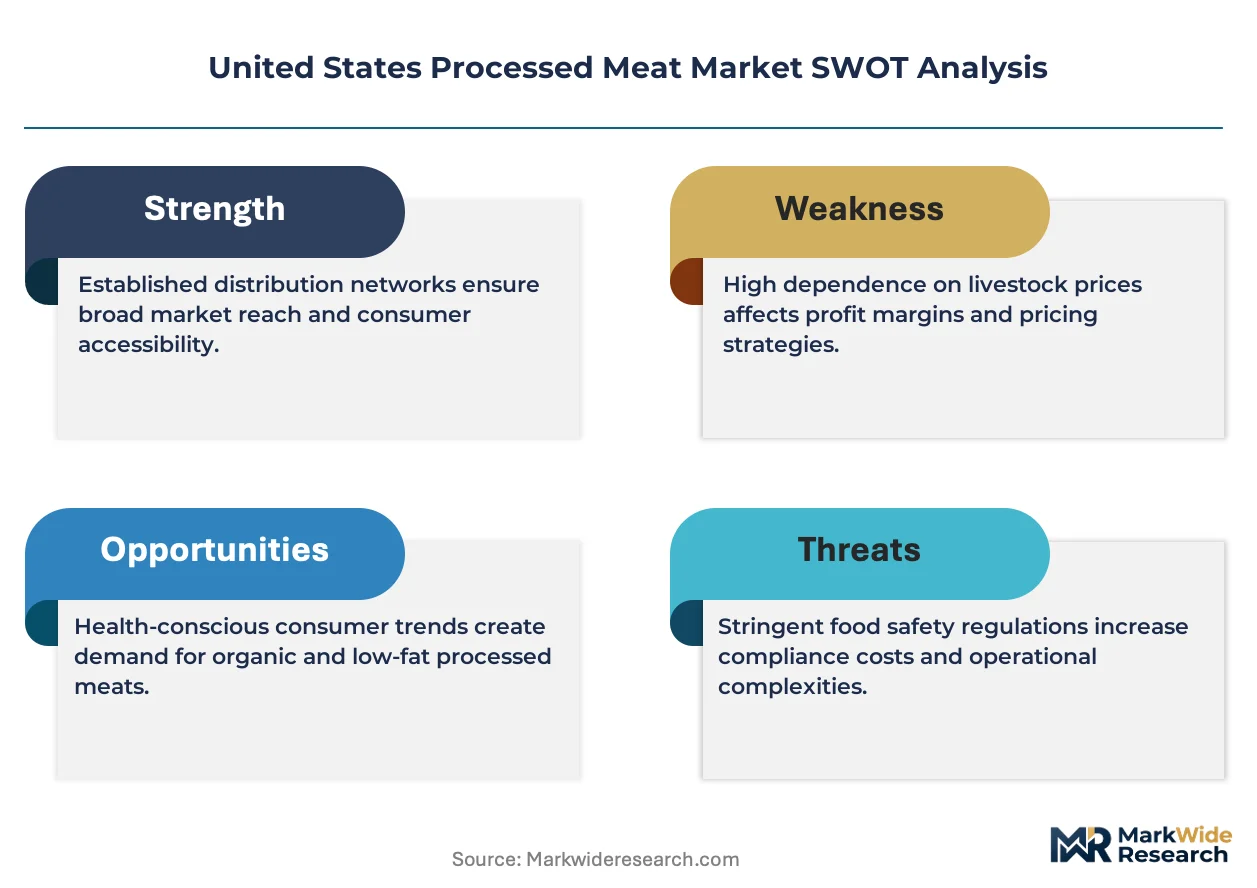
- Corn and soybean meal volatility:Feed input costs swing with ethanol policy and export demand, compressing packer margins during protein oversupply cycles.
- Mid-Atlantic processing desert:Limited slaughter capacity between Pennsylvania and North Carolina forces Northeast retailers to absorb elevated freight costs from Midwest plants.
- Sodium reduction technical ceiling:Below 400mg per serving, water activity management fails without costly alternative humectant systems.
Strategic Opportunities
- Massachusetts confinement-rule arbitrage:Early compliance with Question 3 housing standards opens premium retail placement before federal preemption debates resolve.
- Direct-to-foodservice portion-cutting:Cryovac subprimal-to-steak programs bypass distributor cutting floors, capturing value previously lost to middle-margin operators.
- Cell-cultured hybrid formulations:Blended products combining conventional and cultivated protein sidestep current labeling rulemaking uncertainty while building consumer familiarity.
Industry Challenges
- HAACP plan revision cadence:USDA-FSIS requires complete hazard analysis updates for every formulation change, consuming technical staff capacity.
- Automation integration with legacy rail systems:New robotic carcass-splitting equipment interfaces poorly with 1990s-era chain configurations, demanding full line rebuilds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Processed Meat Market |
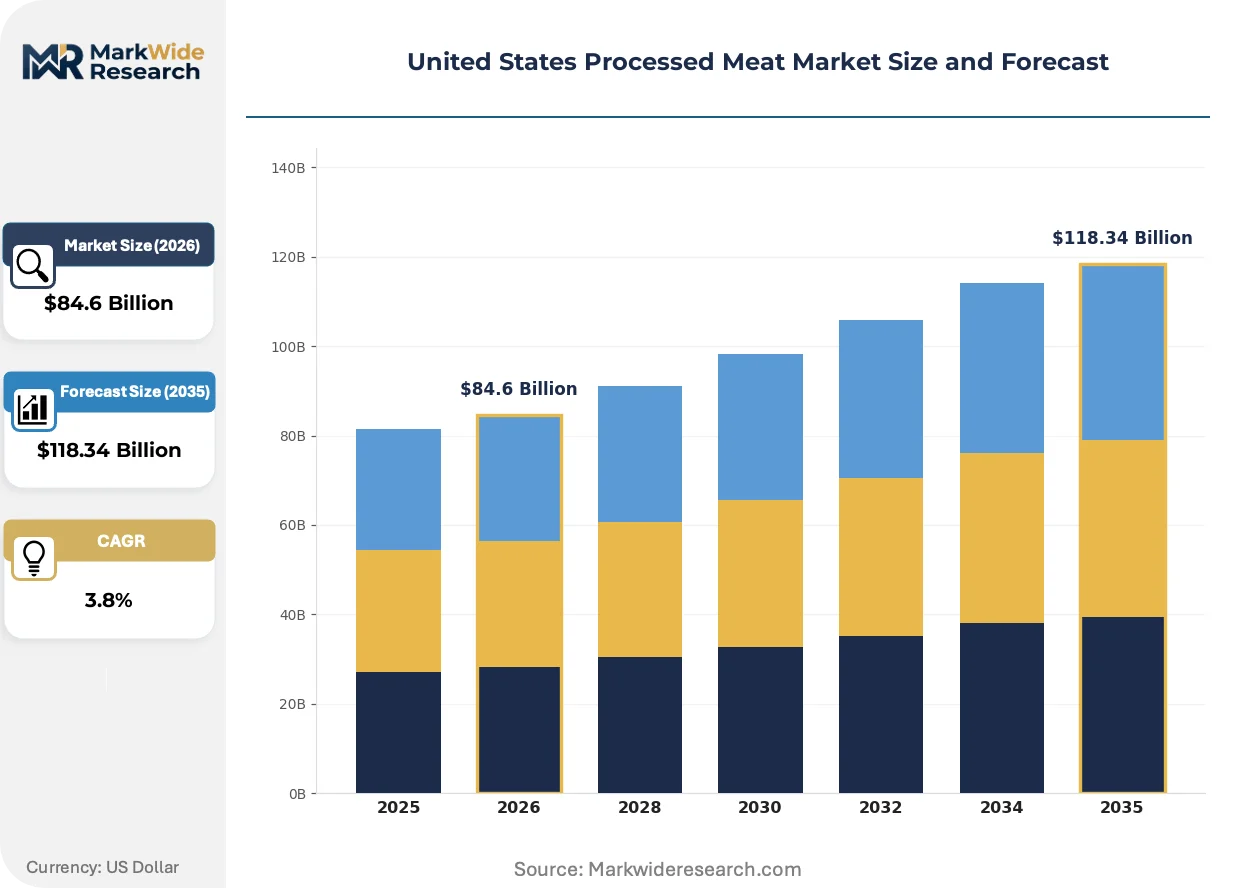
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $118.34 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Sausage, Deli Meats, Hot Dogs, Bacon Distribution Channel: Supermarkets, Grocery Stores, Online Retail, Convenience Stores End User: Households, Foodservice, Retailers, Institutions Packaging Type: Vacuum Packs, Canned, Chubs, Retail Packs |
| Companies Covered | Cargill, JBS USA, Tyson Foods, Sysco Corporation, Smithfield Foods, Hormel Foods, The Kraft Heinz Company, Pilgrim's Pride, Conagra Brands, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Processed Meat Market Evolving Landscape
Electrification of thermal processing and regulatory pressure on sodium content are forcing simultaneous capital redeployment toward precision cooking and reformulation R&D.
Radio-frequency pasteurization is electrifying post-pack lethality treatment for ready-to-eat deli logs. Major club-store suppliers are retrofitting spiral ovens with RF finishing units to eliminate Listeria risk without surface overcooking. This technology is compressing hold-time requirements from hours to minutes, enabling same-day pack-and-ship cycles previously impossible under thermal-only regimes.
FDA sodium-reduction guidance issued under FSMA voluntary targets is forcing reformulation across bacon and cured ham categories. Manufacturers are deploying potassium chloride blends and yeast extracts to maintain flavor intensity while stepping down sodium levels. Deli case operators in California and New York metro corridors are responding fastest, anticipating eventual mandatory thresholds.
Foodservice procurement teams are consolidating protein spend through managed-service contracts that bundle specification development, inventory financing, and waste-reduction guarantees. Distributor sales representatives are ceding menu-engineering authority to processor-employed culinary technologists who embed directly with chain restaurant headquarters. This shift is most visible in the Southwest, where Texas-based steakhouse and fast-casual chains have eliminated independent meat buyers in favor of processor-direct category management.
United States Processed Meat Market Segmentation
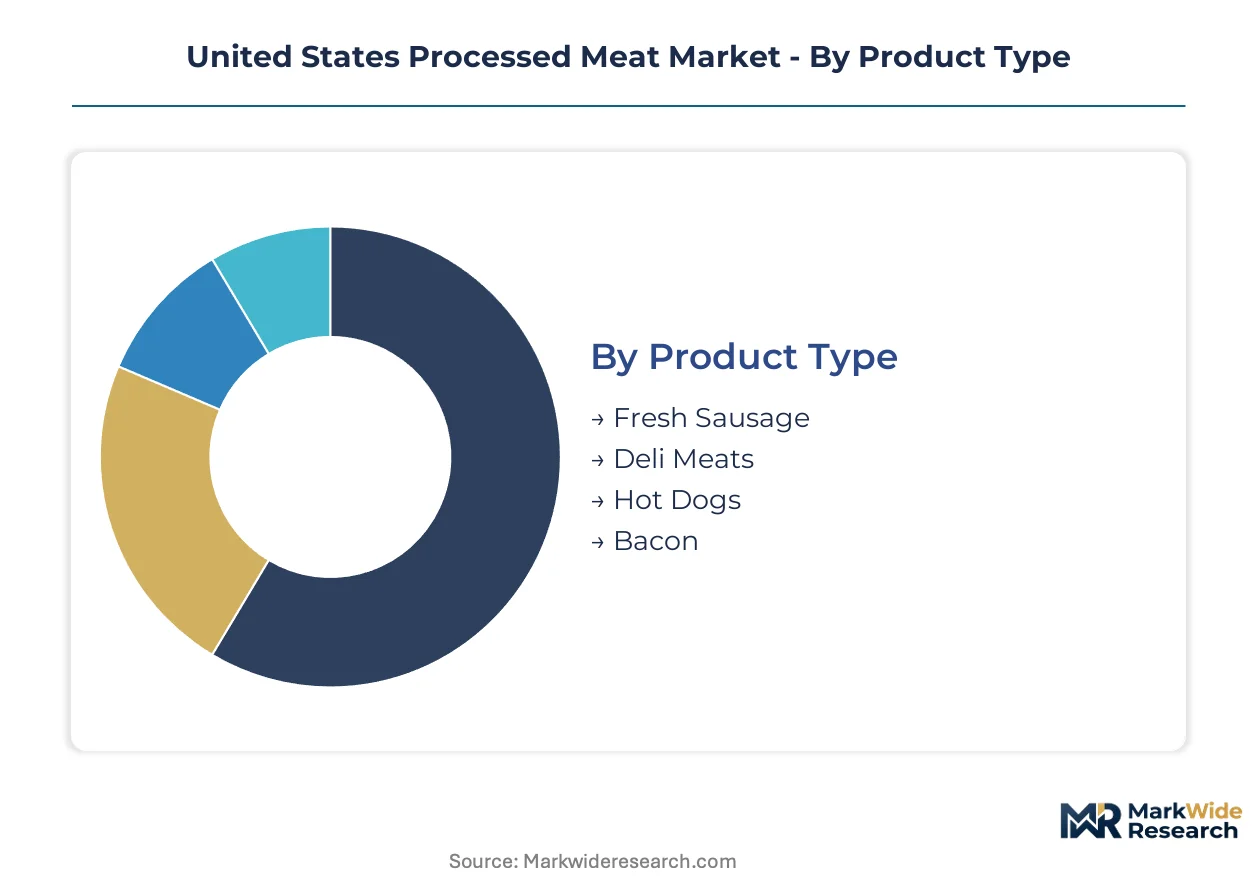
Processed meat segmentation reveals how capital allocation, regulatory exposure, and channel economics fragment the competitive landscape. Distinct segments demand specialized processing equipment, cold-chain infrastructure, and formulation expertise that few operators can span simultaneously.
Product Type:
Capital intensity peaks with thermal processing lines and fermentation cellars, while grinding and stuffing equipment serves multiple formats.
- Fresh Sausage:Coarsely ground muscle trim blended with fat, seasonings, and minimal preservatives, stuffed into natural or collagen casings. Demand clusters in Texas and the broader Southwest, where regional spice profiles and direct-to-foodservice programs bypass traditional retail distribution.
- Deli Meats:Whole-muscle or restructured products subjected to brine injection, tumbling, and thermal processing for uniform sliceability. Institutional buyers in the Northeast absorb volume despite freight premiums from Midwest plants, driven by sandwich program standardization requirements.
- Hot Dogs:Emulsified meat batters cooked in cellulose or natural casings, requiring high-speed linkers and smokehouses.
- Bacon:Pork bellies cured, smoked, and sliced with specialized belly presses and high-capacity slicers.
Deli meats absorb the bulk of installed capacity; fresh sausage is expanding most quickly.
Distribution Channel:
Channel selection determines pack size, shelf-life requirements, and promotional spend allocation.
- Supermarkets:Full-service meat departments with service counters and pre-packaged sections demanding case-ready programs and just-in-time replenishment systems.
- Grocery Stores:Smaller-format operators with limited refrigerated space favoring vacuum-packed subprimals and value-priced chubs.
- Online Retail:Direct-to-consumer shipments requiring insulated packaging and expedited delivery guarantees, concentrated in dense metro corridors.
- Convenience Stores:Grab-and-go formats driving single-serve and microwaveable portion development for travel plaza and urban locations.
Supermarkets anchor volume throughput; online retail is gaining share fastest.
End User:
User type dictates specification stringency, contract structure, and technical service intensity.
- Households:Retail purchasers prioritizing portion flexibility, label transparency, and price-point accessibility across weekly shopping trips.
- Foodservice:Chain restaurants and independent operators requiring consistent cook yields, labor-saving formats, and supply assurance through managed-service contracts.
- Retailers:Private-label programs demanding co-manufacturing partnerships with dedicated line time and exclusive formulation access.
- Institutions:Schools, hospitals, and correctional facilities with mandatory nutritional compliance and lowest-acceptable-bid procurement protocols.
Foodservice commands the highest technical service investment; retailers are consolidating sourcing fastest.
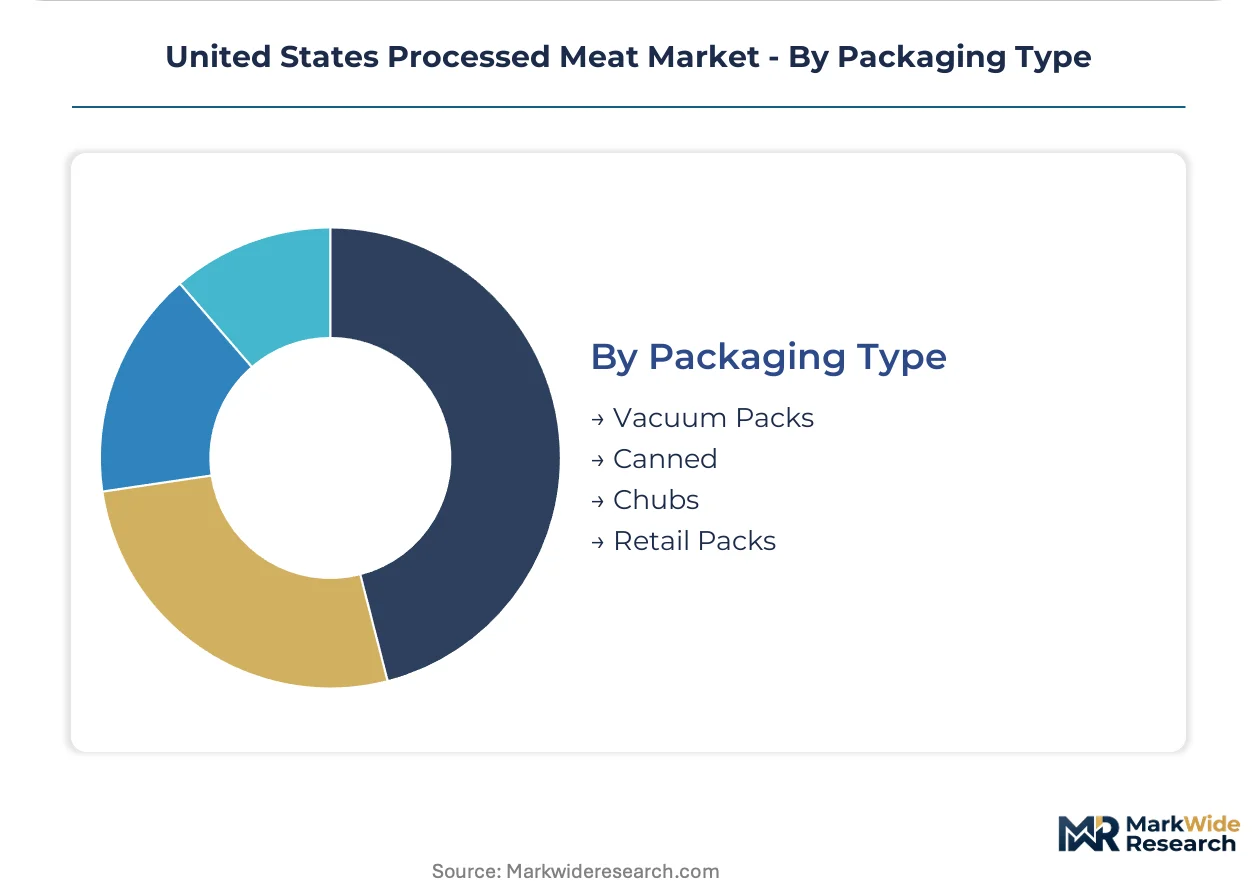
Packaging Type:
Packaging technology governs shelf stability, distribution radius, and retail presentation options.
- Vacuum Packs:Barrier films with oxygen scavengers enabling extended refrigerated shelf life for club-store and institutional volumes.
- Canned:Retort processing for ambient distribution, concentrated in military and emergency stockpile applications.
- Chubs:Flexible casings for bulk ground and emulsified products, favored by value-oriented retail and foodservice prep kitchens.
- Retail Packs:Modified-atmosphere trays with absorbent pads and clear lidding for case-ready meat department display.
Vacuum packs dominate institutional throughput; retail packs are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Amarillo anchors the nation's densest concentration of fed-cattle supply and slaughter capacity, with five major packers operating within a 100-mile radius of the Texas Panhandle feedlot corridor.
Texas and the Southwest
Feedlot capacity exceeds 7 million head across the High Plains, drawing corn-byproduct flows from ethanol plants in the Texas Panhandle and eastern New Mexico. USDA-FSIS inspection stations at Cactus and Plainview process record volumes. Amarillo and Lubbock host specialized further-processing facilities that supply regional tortilla and taco chains with portion-controlled protein.
Midwest Corn Belt
Iowa and Nebraska hog finishing operations supply raw material to large-scale pork cutting plants. EPA effluent regulations under Clean Water Act permits constrain expansion along the Missouri River watershed. Sioux Falls and Sioux City maintain integrated pork complexes that convert live animals to boxed primals within single-shift cycles.
Southeast Atlantic
Poultry-dominant protein demand in Georgia and the Carolinas forces beef and pork processors to ship from Midwest plants, inflating landed costs for institutional buyers. OSHA workplace safety enforcement intensified following 2021 amputation incidents at Carolina cutting facilities. Charlotte distribution hubs consolidate mixed-protein loads for hospital and school contract feeding.
California and the Pacific Coast
Proposition 65 warning-label mandates have triggered specialized formulation services that processors now market nationwide. California Department of Public Health inspection backlogs delay new product approvals. Central Valley cities including Fresno and Modesto host mid-scale further-processors serving Latino retail formats with chorizo and longaniza specialties.
Northeast Corridor
Mid-Atlantic slaughter capacity scarcity forces Boston and New York metro retailers to absorb freight premiums from Midwest plants. Massachusetts Question 3 animal confinement rules create compliance arbitrage opportunities for early adopters. Philadelphia and Baltimore cold-storage terminals function as break-bulk points for imported cured hams and domestic deli meat redistribution.
United States Processed Meat Market Competitive Landscape
Capital-heavy packers compete with asset-light branded marketers for margin capture across the value chain. The market structure concentrates upstream slaughter and disassembly capacity among four integrated operators while downstream formulation and brand management fragments across specialized players. Strategic archetypes divide between feedlot-anchored packers, brand-centric marketers, and distributor-integrated protein suppliers. Competitive moves center on backward integration into genetics and feed supply, plus forward integration into prepared foods and foodservice category management.
Within the integrated packer tier, Tyson Foods and JBS USA occupy positions defined by captive cattle supply and multi-species processing breadth. Hormel Foods exemplifies the brand-marketer archetype through premium deli and bacon portfolios that command retail placement premiums. These three operators anchor distinct competitive vectors: scale-driven commodity supply, vertically coordinated margin control, and differentiated consumer branding.
| Leading Market Players |
|---|
| Cargill |
| JBS USA |
| Tyson Foods |
| Sysco Corporation |
| Smithfield Foods |
| Hormel Foods |
| The Kraft Heinz Company |
| Pilgrim's Pride |
| Conagra Brands |
| Others |
Value Network & Pricing Analysis
Radio-frequency pasteurization retrofitting is compressing thermal-processing capital cycles while concentrating margin capture among packers with installed RF finishing capacity. This electrification shift simultaneously raises per-unit processing costs and rewards geographic clustering near High Plains feedlot corridors.
Pricing Analysis
Yield-guarantee contracts now anchor protein pricing, with foodservice operators paying premiums for verified cook-loss performance rather than raw weight. Three-tier pricing structure across premium branded, private-label standard, and commodity economy levels reflects brand equity and traceability certification. Pricing pressure stems from corn and soybean meal input volatility compressing packer spreads during oversupply periods. Institutional buyers in the Northeast exhibit highest price sensitivity due to freight premiums from Midwest plants, while Texas-based fast-casual chains absorb moderate premiums for direct-procurement convenience.
Supply Chain Analysis
Single-source vulnerability sits with High Plains cattle supply concentration; five major packers operate within 100 miles of the Amarillo feedlot corridor. Livestock flows draw from Texas, Nebraska, and Kansas feedlots, while processing equipment and cold-chain packaging feed from Ohio, Illinois, and Pennsylvania manufacturing bases. Tariff exposure on imported casing materials and sodium-reduction additives threatens formulation flexibility. Distribution runs through regional cold-storage terminals in Dallas, Chicago, and Philadelphia that break bulk for retail and foodservice redeployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification of thermal processing is displacing legacy smokehouse infrastructure, creating asymmetric reward for early capital deployers and stranded-asset risk for laggards.
For Market Incumbents: Acquire RF pasteurization equipment fleets and trained technical cadres before supplier backlogs extend. Secure captive feedlot supply through forward-contracting or equity stakes in High Plains cattle operations to defend against input cost spikes. USDA-FSIS HACCP revision cadence consumes technical staff capacity, making automated compliance documentation systems a critical defensive lever. For New Entrants and Emerging Players: Enter via Massachusetts Question 3 compliance-ready premium pork programs, exploiting early-adopter retail placement before federal preemption debates resolve. Target Mid-Atlantic institutional buyers desperate for regional slaughter capacity, bypassing freight-inflated Midwest supply. Deploy cryovac subprimal-to-steak direct-to-foodservice programs that capture value lost to distributor cutting floors. For Investors and Strategic Acquirers: Exit pathways concentrate in processor-direct category management contracts with Southwest steakhouse and fast-casual chains eliminating independent meat buyers. Long-term viability favors operators with integrated feed-to-retail traceability systems and cold-chain subscription revenue models. Watch cell-cultured protein labeling rulemakings as inflection signal; regulatory clarity will determine whether hybrid formulation strategies capture transitional value or become stranded investments.| Strategic Initiative | Industry Significance |
|---|---|
| RF Pasteurization Retrofit | Electrified post-pack lethality treatment eliminates Listeria risk while enabling same-day pack-and-ship cycles for club-store suppliers. |
| Feedlot-to-Retail Traceability Investment | RFID-enabled lot tracking from High Plains operations satisfies institutional buyer audit demands and commands placement premiums. |
| Sodium Reduction R&D Partnership | Potassium chloride and yeast extract formulation collaborations with California advisory services anticipate mandatory threshold adoption. |
| Direct-to-Foodservice Portion Cutting | Cryovac subprimal programs bypass distributor margins and capture value previously lost to middle-operator cutting floors. |
| Massachusetts Question 3 Compliance Buildout | Early housing-standard adherence opens premium retail placement before federal preemption debates resolve competitive positioning. |
Research Methodology
USDA-FSIS inspection records, EPA Clean Water Act permit filings, and SEC 10-K protein-segment disclosures formed the secondary backbone. Primary interviews with feedlot operations managers, USDA inspection station supervisors, foodservice procurement directors, and cold-chain logistics coordinators validated demand and supply assumptions. Bottom-up plant capacity utilization data and top-down retail scanner trends were triangulated against trade flow records.
Bottom-up modeling anchored volume projections on individual packer throughput capacities and feedlot placement rates, while top-down demand validation drew from foodservice protein spend consolidation patterns. Segmentation dimensions included product type, distribution channel, end-user specification intensity, and packaging technology tier. CAGRs were derived from trend extrapolation moderated by regulatory intervention probability and input cost cycle positioning. Forecast inputs incorporated ethanol policy sensitivity and export demand elasticity for feed grains.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt sodium-reduction mandate timing or cell-cultured protein labeling preemption. Projections reflect documented assumptions about feedlot capacity expansion, cold-chain infrastructure investment, and FSIS inspection resource allocation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Potato Soup Market
Processed Foods
North America Soup Market
Processed Foods
High-Pressure Processing (HPP) Foods Market
Processed Foods
Europe Processed Egg Market
Processed Foods
Mashed Potatoes Market
Processed Foods
India Spray Dried Food Market
Processed Foods
Low Fat Vegetable Soups Market
Processed Foods
Middle East and Africa Processed Meat Market
Processed Foods
Global Potato Flake Market
Processed Foods
Broth Market
Processed Foods
Processed Superfruits Market
Processed Foods
Low Moisture Food Market
Processed Foods
Processed Eucheuma Seaweed Market
Processed Foods
Low-Calorie Margarine Market
Processed Foods
Instant Cooking Food Market
Processed Foods
Fermented Foods Market