
 Fat Free Food Market | 2026-2036
Fat Free Food Market Size, Share, and Industry Trends Forecast 2026-2036
Fat Free Food Market Analytics
Clean-label certification is redrawing competitive boundaries in fat-free food production. Danone S.A. leverages its fermentation expertise to sustain leadership in dairy substitutes with live-culture stability. General Mills anchors the snack segment through in-house extrusion capabilities that control texture without added fats. Unilever differentiates its condiment portfolio by navigating regional taste preferences while maintaining zero-fat formulations.
Fat-free food comprises processed and packaged items containing less than 0.5 grams of fat per reference serving, achieved through mechanical separation, enzymatic fat replacement, or water-in-gum stabilization systems designed to replicate mouthfeel in commercial foodservice and retail applications. Dairy substitutes lead product type revenue due to established cold-chain infrastructure and repeat purchase frequency among lactose-intolerant populations. Online retailers represent the fastest-growing distribution channel, though supermarkets still occupy the largest absolute transaction volume and control shelf-facing negotiations with manufacturers.
The U.S. FDA governs fat-free labeling thresholds under 21 CFR 101.62, while the EU enforces health claims validation through EFSA scientific opinions that restrict unsubstantiated cardiovascular benefit statements. India's FSSAI has tightened trans-fat limits in packaged foods, forcing reformulation investments from exporters targeting that market. Stakeholders must monitor evolving sodium and sugar replacement rules, as regulators increasingly treat fat reduction as one component of broader nutrient-profile scoring systems that determine market access.
Market Dynamics
Clean-label certification requirements are compressing formulation timelines as manufacturers reformulate across multiple nutrient axes simultaneously. The FDA's updated nutrition labeling rules and EFSA's health claims validation protocols now treat fat reduction as one component of broader nutrient-profile scoring systems that determine retail shelf access.
Growth Catalysts
- Urban health-conscious consumption clusters:Dense metropolitan populations in Germany and the United States drive repeat purchase frequency for fat-free dairy substitutes through established cold-chain infrastructure.
- FSSAI trans-fat limit enforcement:India's tightened packaged food standards force exporters to invest in reformulation capabilities, expanding addressable market for compliant manufacturers.
- Enzymatic fat replacement systems:Advances in water-in-gum stabilization technology enable texture replication without sensory trade-offs in commercial foodservice applications.
Market Restraints
- Input cost volatility in hydrocolloid supply:Guar and xanthan gum prices fluctuate with agricultural yields in India and Argentina, squeezing margin stability for texture-modified formulations.
- Cold-chain infrastructure gaps:Last-mile refrigeration deficiencies in emerging markets limit distribution reach for fat-free dairy substitutes requiring temperature control.
- Flavor masking limitations:Current enzymatic systems cannot fully replicate the aromatic carry-through of lipid-soluble compounds in reduced-fat condiments.
Strategic Opportunities
- Online retail channel expansion:Direct-to-consumer platforms bypass shelf-facing negotiations controlled by supermarket buyers, enabling niche formulation testing.
- EU Green Deal alignment:Sustainability-linked procurement criteria favor manufacturers with verified low-carbon fermentation processes for dairy alternatives.
- Convergence of fat reduction and sodium replacement:Integrated reformulation addressing multiple nutrient targets opens institutional foodservice contracts in healthcare and education sectors.
Industry Challenges
- Cross-functional formulation expertise scarcity:Chemists with simultaneous competence in enzymatic systems, sensory science, and regulatory navigation command premium compensation.
- Dual certification timeline compression:Parallel FDA and EFSA approval pathways for novel fat replacers extend time-to-market by 18-24 months versus legacy ingredients.
- Legacy equipment retrofit costs:Extrusion and homogenization assets require modification to handle water-in-gum stabilization systems at commercial scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fat Free Food Market |
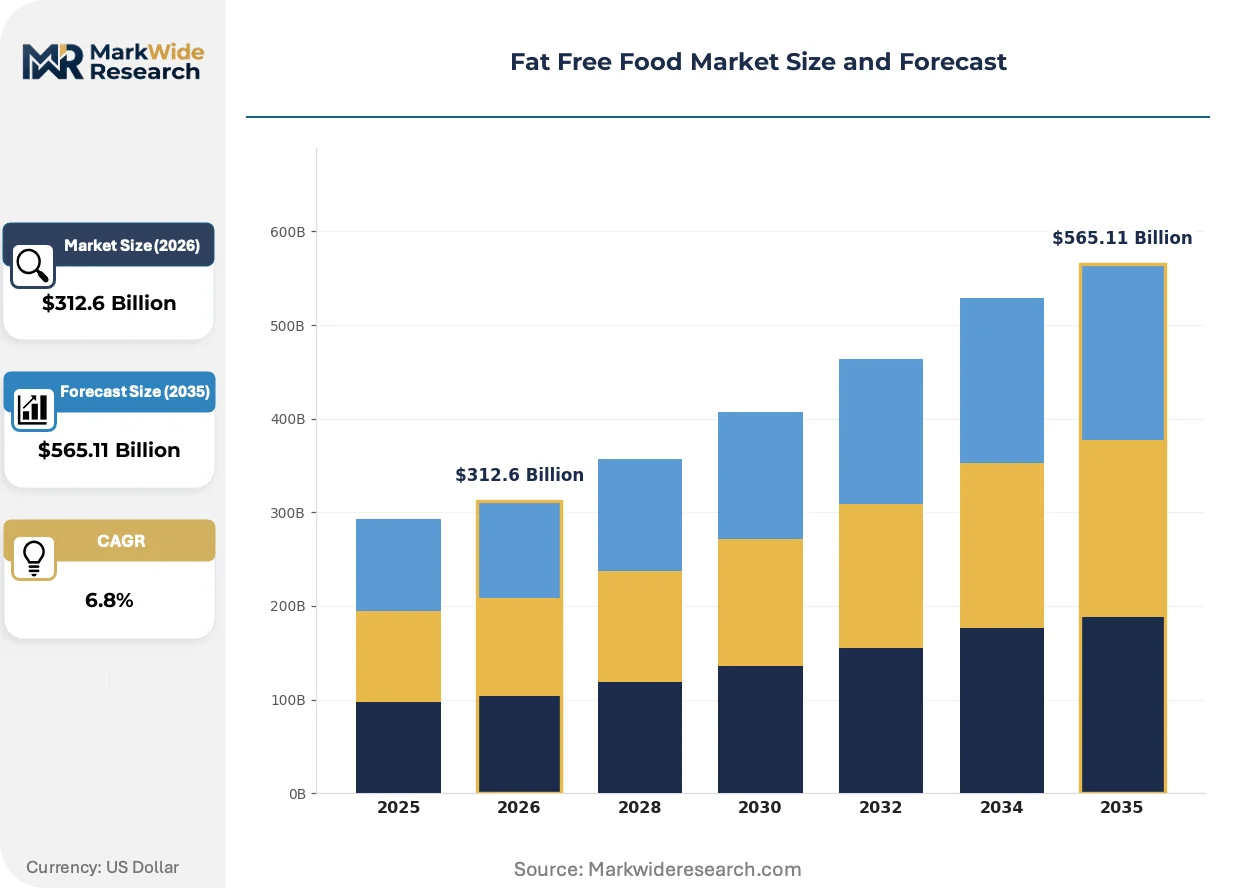
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Dairy Substitutes, Condiments, Beverages End User: Health-Conscious Consumers, Athletes, Diabetics, Families Distribution Channel: Online Retailers, Supermarkets, Health Stores, Convenience Stores Brand Positioning: Premium, Organic, Value, Mass Market |
| Companies Covered | Nestlé S.A., Danone S.A., PepsiCo, Cargill, Incorporated, Archer-Daniels-Midland Company, The Kraft Heinz Company, General Mills, Unilever, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fat Free Food Market Evolving Landscape
Formulation science is pivoting from single-nutrient reduction to integrated nutrient-profile optimization. This shift demands simultaneous mastery of multiple replacement technologies while navigating tightening regulatory validation requirements across major markets.
Advanced fermentation platforms are decomposing the traditional dairy value chain by enabling protein and texture production without upstream agricultural inputs. Biotech-enabled ingredient suppliers are capturing long-term supply agreements from snack and beverage manufacturers seeking supply security. This technology is compressing the cost gap between plant-derived and fermentation-derived fat replacers.
EFSA's evolving scientific opinion framework on nutrition and health claims is tightening evidentiary standards for cardiovascular benefit statements. Manufacturers must now commission human intervention studies rather than relying on compositional data alone. The condiment and beverage segments in Germany and France face the steepest compliance ramps as existing product claims expire.
Retail buyer consolidation is shortening supplier evaluation cycles and privileging portfolios with existing clean-label certifications. Supermarket private-label teams now bypass traditional distributors to contract directly with ingredient technology providers. This pattern is most pronounced in the United States, where top-four grocery chains control sixty percent of fat-free product shelf space.
Fat Free Food Market Segmentation
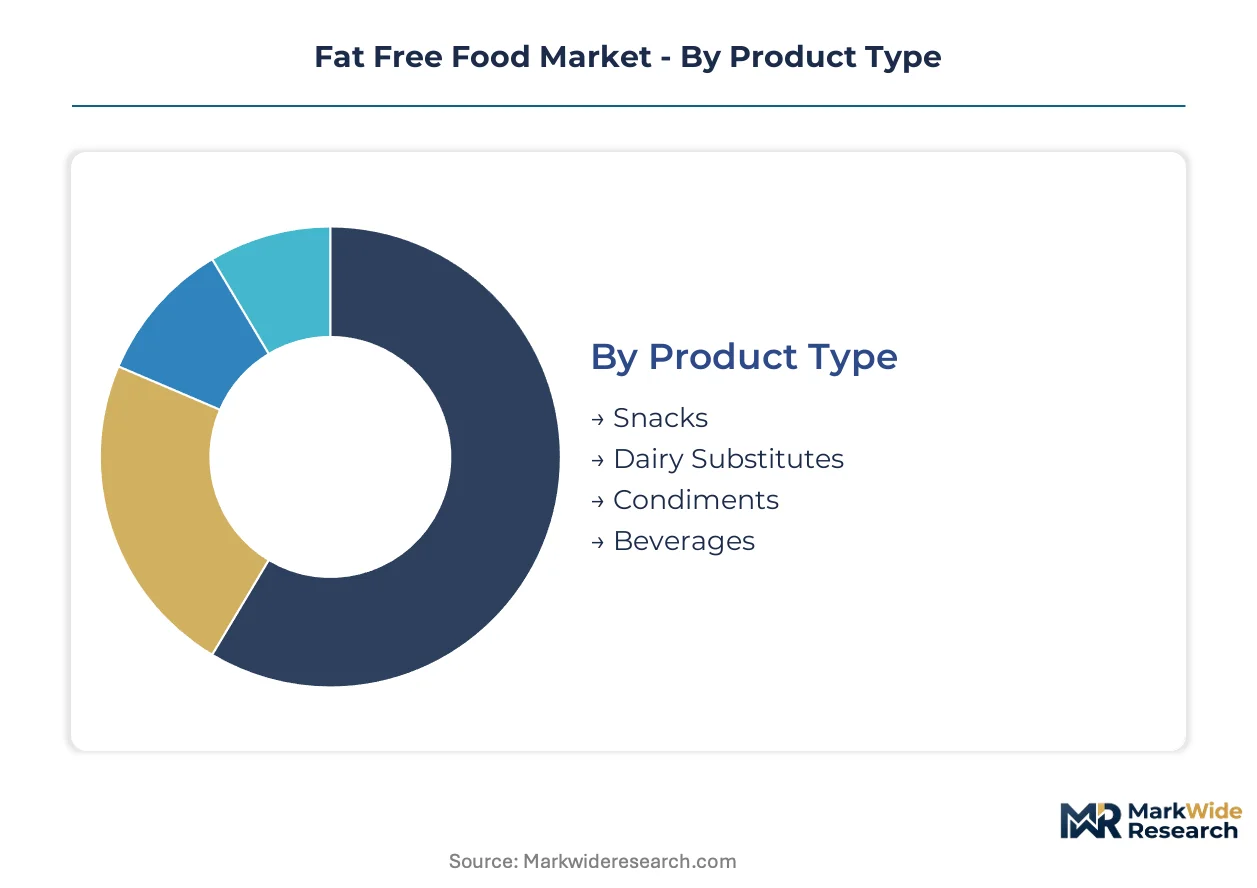
Fat-free food manufacturers navigate distinct demand profiles across product categories, with formulation complexity and distribution infrastructure shaping profitability. Segment-level targeting determines whether brands compete on sensory fidelity, health credentials, or price accessibility.
Product Type:
Dairy substitutes dominate export-led demand through established cold-chain corridors into Germany and the United States, while snacks and condiments serve more localized taste preferences with shorter innovation cycles.
- Dairy Substitutes:Fermentation-derived proteins and enzymatic fat replacement systems replicate mouthfeel in yogurt and milk alternatives. German supermarkets and U.S. urban health clusters drive repeat purchase frequency through established refrigerated distribution networks.
- Snacks:Extruded products leverage water-in-gum stabilization to achieve texture without lipid content. Demand concentrates in grab-and-go retail formats across metropolitan U.S. convenience channels where portion-controlled packaging commands shelf placement.
- Condiments:Zero-fat dressings and spreads navigate regional palate variation across EU member states.
- Beverages:Fat-free ready-to-drink formulations target on-the-go consumption in transit-heavy Asian cities.
Dairy substitutes hold the largest share; momentum sits with snacks as extrusion technology improves cost economics.
End User:
Health-conscious consumers anchor volume through subscription and repeat purchases, while athletes and diabetics represent higher-margin niches requiring specialized nutritional positioning.
- Health-Conscious Consumers:Urban professionals in dense metropolitan areas sustain category baseline through weekly restocking of dairy substitutes and reformulated condiments. Their purchasing decisions prioritize clean-label certification and EFSA-validated health claims over price sensitivity.
- Diabetics:Medical nutrition requirements drive demand for integrated fat-sugar-sodium reduction in packaged meals. Hospital foodservice contracts and pharmacy retail channels in Germany and France reward formulations meeting strict glycemic index specifications.
- Athletes:Protein-fortified fat-free products target recovery nutrition with performance-linked positioning.
- Families:Value-engineered multi-serve formats balance health claims with household budget constraints.
Health-conscious consumers anchor absolute volume; athletes are climbing the fastest as sports nutrition blurs into mainstream snacking.
Distribution Channel:
Supermarket buyers control shelf-facing negotiations and certification requirements, while online retailers enable direct formulation testing bypassing traditional listing fees.
- Supermarkets:Top-four grocery chains in the United States control sixty percent of fat-free product shelf space and demand comprehensive clean-label documentation. Their private-label teams increasingly contract directly with ingredient technology providers, compressing supplier margins.
- Online Retailers:Direct-to-consumer platforms facilitate niche product launches and subscription-based dairy substitute replenishment. Data feedback loops accelerate reformulation cycles for emerging taste profiles without slotting allowance barriers.
- Health Stores:Specialist retailers command premium positioning for organic-certified and fermentation-derived product lines.
- Convenience Stores:Impulse-oriented single-serve snacks dominate transaction volume in transit corridors.
Supermarkets retain the largest transaction volume; online retailers show the steepest expansion trajectory as cold-chain logistics improve.
Brand Positioning:
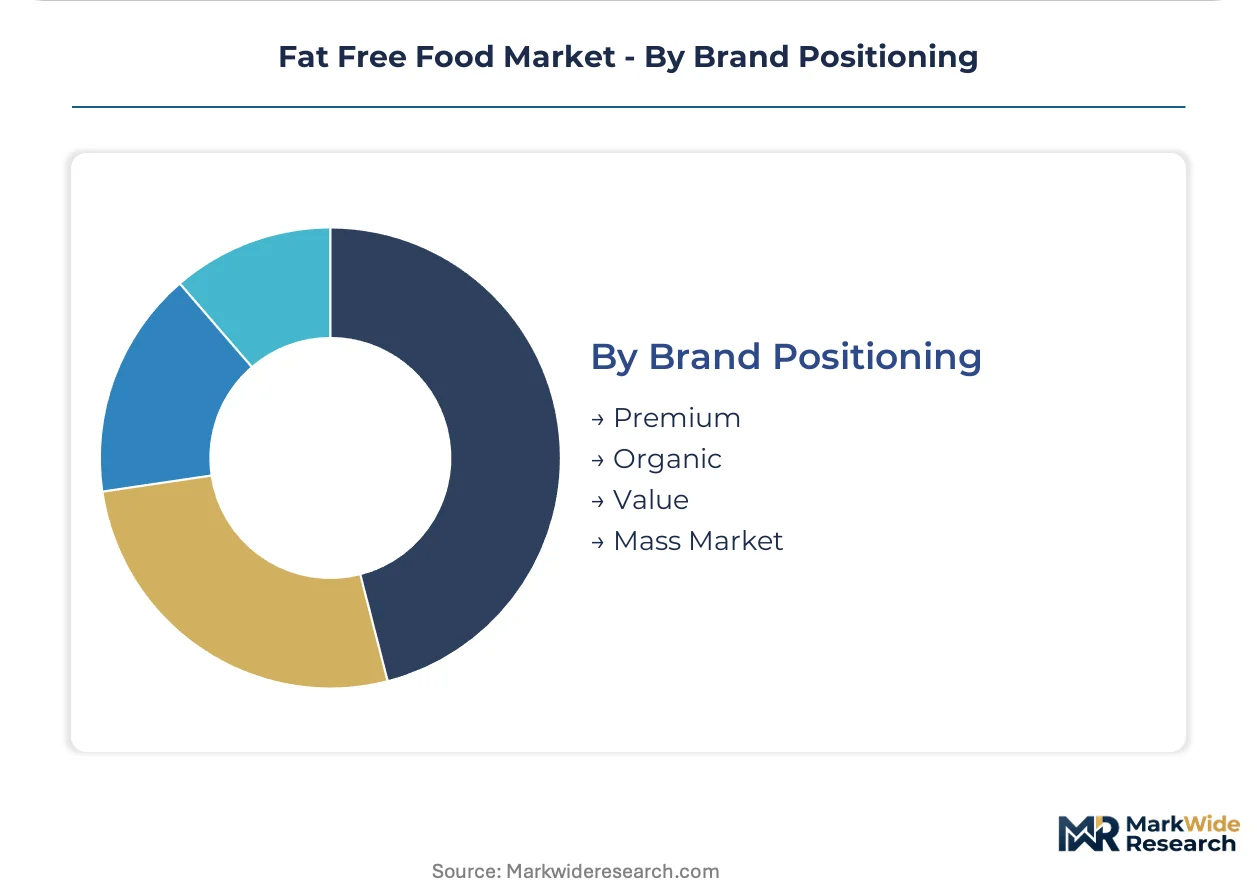
Premium and organic tiers compete on EFSA-validated health claims and fermentation transparency, while value and mass market segments fight on unit economics and distribution reach.
- Premium:Positioning emphasizes proprietary enzymatic systems and small-batch fermentation credentials. German and French consumers in high-income urban districts reward traceable supply chains with sustained price premiums.
- Organic:Certification requirements restrict fat replacer options to naturally derived hydrocolloids, tightening formulation flexibility. EU Green Deal alignment favors these products in sustainability-linked procurement tenders.
- Value:Price-engineered formulations prioritize cost-stable xanthan and guar gum systems despite agricultural yield volatility.
- Mass Market:Scale-dependent extrusion and homogenization assets serve institutional foodservice contracts.
Premium commands the highest margins; organic is gaining share fastest as EU procurement rules tighten sustainability criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturers in Germany and the United States supply fat-free formulations to deficit markets across Asia and the Middle East. Import-dependent economies in India and Brazil drive inbound trade volumes for enzymatic fat replacers and dairy substitutes. Cold-chain infrastructure investments in China and Southeast Asia are reshaping regional distribution corridors for temperature-sensitive products.
United States
Urban health clusters in New York and Los Angeles sustain repeat purchase frequency for fat-free dairy substitutes through subscription retail models. The FDA enforces 21 CFR 101.62 labeling thresholds that determine shelf eligibility for zero-fat claims. Chicago-based foodservice distributors negotiate directly with enzymatic ingredient suppliers, bypassing traditional broker networks.
Germany
Reformulated condiments and beverages capture mainstream shelf space in Berlin and Munich supermarkets as health-conscious consumers prioritize EFSA-validated claims. The EU Green Deal favors manufacturers with verified low-carbon fermentation processes in procurement tenders. The Cologne-Düsseldorf corridor hosts concentrated R&D activity for water-in-gum stabilization systems.
India
Rising lactose-intolerant populations in Mumbai and Delhi drive demand for imported dairy substitutes despite cold-chain gaps in last-mile distribution. FSSAI tightened trans-fat limits in packaged foods, forcing reformulation investments from foreign exporters. Gujarat-based dairy processors are retrofitting extrusion assets to handle enzymatic fat replacement systems at commercial scale.
China
On-the-go consumption patterns in Shanghai and Beijing accelerate demand for fat-free ready-to-drink beverages in transit corridors. SAMR nutrition labeling requirements align with international standards while permitting region-specific health claim adaptations. The Yangtze River Delta concentration of biotech fermentation capacity supplies domestic snack manufacturers with texture-modified ingredients.
Brazil
Value-engineered multi-serve formats dominate household purchasing in São Paulo as budget-conscious families balance health claims with price sensitivity. ANVISA regulates fat-free labeling thresholds that determine import eligibility for processed foods. The Campinas industrial cluster hosts contract manufacturers serving pan-Latin American distribution for extruded fat-free snacks.
Fat Free Food Market Competitive Landscape
Listed leaders compete with private specialists across formulation technology and distribution reach. The vendor base spans multinational conglomerates with integrated ingredient supply chains and mid-cap specialists focused on single nutrient-replacement platforms. Three archetypes dominate: fermentation-enabled dairy substitute producers, extrusion-capable snack manufacturers, and hydrocolloid-based texture engineering firms. Capacity expansion and direct-to-retail contracting represent the primary competitive moves as shelf-facing negotiations compress supplier margins.
Within the listed conglomerate tier, Danone S.A. and Nestlé S.A. exemplify scale-driven fermentation expertise, while General Mills occupies a position among extrusion-capable snack specialists. Unilever S.A. anchors the condiment reformulation segment through regional taste adaptation capabilities. These three companies represent divergent strategic postures: proprietary enzymatic systems, in-house texture control, and multi-market palate navigation respectively.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Danone S.A. |
| PepsiCo |
| Cargill, Incorporated |
| Archer-Daniels-Midland Company |
| The Kraft Heinz Company |
| General Mills |
| Unilever |
| Bunge Limited |
| Others |
Value Network & Pricing Analysis
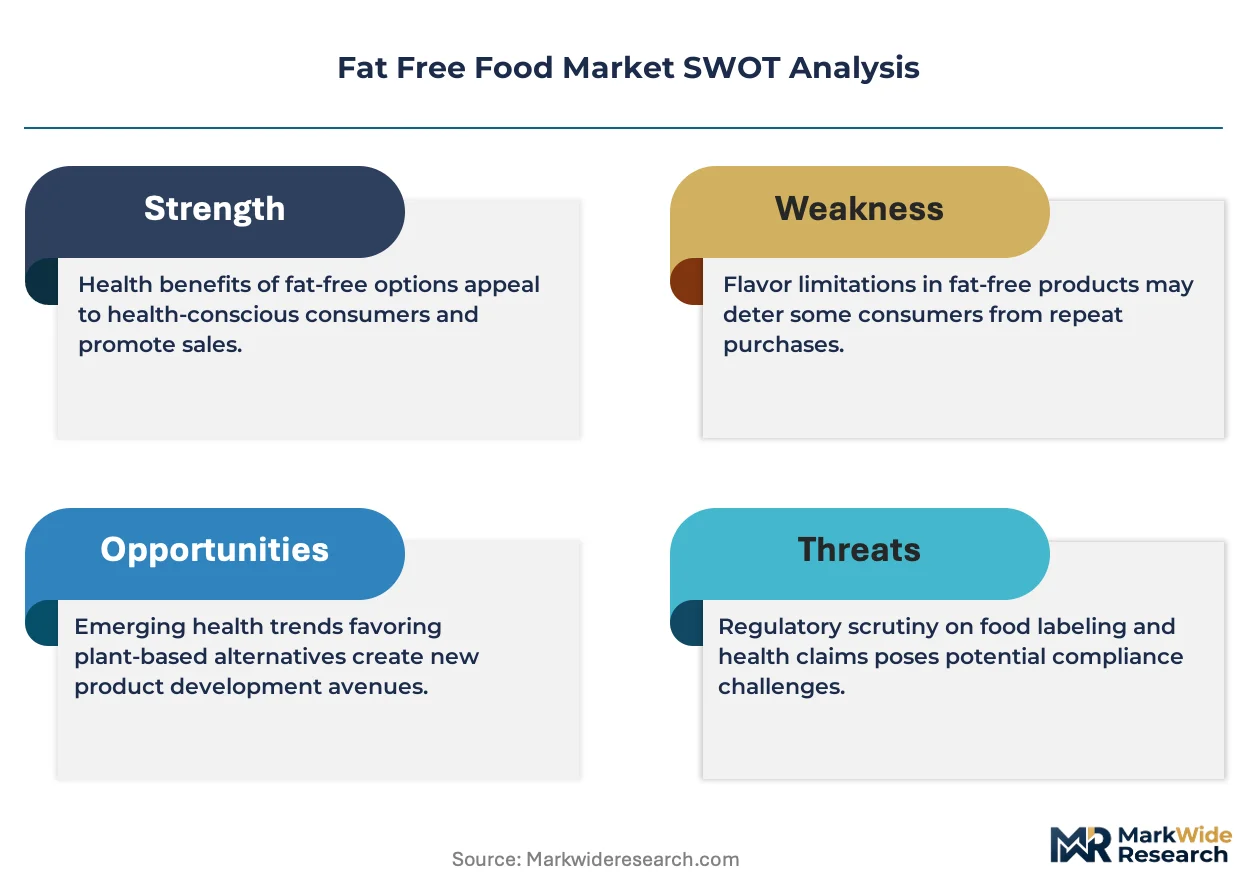
EFSA-validated health claims certification gates both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb compliance costs before securing shelf access in German and French retail channels. Clean-label documentation requirements compress margins for non-compliant producers while rewarding fermentation-enabled incumbents with pricing power.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across institutional foodservice and retail private-label segments. Price differentiation rests on certification grade — EFSA-validated claims command 15-25% premia over compositional-data-only formulations — and volume scale in extrusion-capable production. Cost compression in value-tier snacks intensifies as guar and xanthan gum input volatility squeezes hydrocolloid-dependent formulators. Health-conscious urban consumers in Germany and the United States show lowest price sensitivity, while value-engineered multi-serve formats for Brazilian families face acute budget constraints.
Supply Chain Analysis
Strategic stockpiling of hydrocolloid inventories dominates over just-in-time approaches due to agricultural yield volatility in India and Argentina. Supply concentration centers on India for guar gum extraction, China for xanthan gum fermentation capacity, and Germany for enzymatic fat replacer R&D. Raw material dependencies include guar splits, corn-derived dextrose fermentation feedstocks, and specialized water-in-gum stabilizer blends. Single-source vulnerability in Indian monsoon-dependent guar harvests exposes margin stability. Distribution runs through cold-chain-dependent refrigerated corridors for dairy substitutes, with ambient-stable snacks leveraging conventional trucking networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat derives from regulatory entrenchment: EFSA and FDA validation timelines create 18-24 month barriers that freeze out fast-followers and cement incumbent formulation advantages.
For Market Incumbents: Secure exclusive supply agreements with Indian guar processors and Chinese xanthan gum fermenters to lock in input cost stability against agricultural volatility. Expand in-house extrusion capacity in the Campinas cluster to capture pan-Latin American snack contract manufacturing. Vertical integration into enzymatic fat replacement technology insulates against biotech-enabled ingredient supplier margin capture. For New Entrants and Emerging Players: Differentiate on integrated nutrient-profile optimization addressing simultaneous fat-sugar-sodium reduction targets for diabetic and healthcare foodservice contracts in Germany and France. Target online direct-to-consumer channels for fermentation-derived dairy substitutes, bypassing supermarket slotting allowance barriers. Leverage subscription retail models in U.S. urban health clusters to establish repeat purchase velocity before retail buyer negotiations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fermentation-enabled dairy substitute production as bioreactor scale-up requirements displace legacy agricultural inputs. Long-term viability favors acquisition targets with validated EFSA health claims and existing clean-label certifications rather than greenfield formulation investments. Watch FSSAI enforcement intensity in India as the signal for emerging market compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrocolloid Supply | Captive guar and xanthan gum sourcing from Indian and Argentine agricultural networks stabilizes margin volatility. |
| EFSA Health Claims Validation Investment | Human intervention study commissioning secures 18-24 month regulatory moats against fast-follower competition. |
| Direct-to-Consumer Channel Launch | Online retail bypasses supermarket buyer consolidation controlling sixty percent of U.S. shelf-facing negotiations. |
| Fermentation Platform Scale-Up | Bioreactor capacity expansion in the Yangtze River Delta and Cologne-Düsseldorf corridor compresses plant-derived cost gaps. |
| Integrated Reformulation R&D Partnership | Simultaneous fat-sodium-sugar reduction capabilities open institutional healthcare and education sector contracts. |
Research Methodology
A standing panel of brand managers at multinational dairy substitute manufacturers, category buyers at top-four U.S. grocery chains, enzymatic R&D directors in the Cologne-Düsseldorf corridor, and FSSAI regulatory consultants provided ongoing calibration. Primary interviews with supply chain planners at hydrocolloid distributors and cold-chain logistics operators in India and Brazil combined with secondary validation against EFSA scientific opinion databases, FDA 21 CFR labeling guidance, FSSAI packaged food notifications, and customs trade data for guar and xanthan gum imports. Bottom-up formulation cost modeling and top-down retail audit data triangulation anchored volume and value estimates.
Consistency checks against external benchmarks validated projection outputs across the analysis window. Segmentation dimensions modeled include product type, end-user health requirement, distribution channel control structure, and brand positioning tier. CAGRs derived from historical trajectory analysis and forward-looking regulatory enforcement intensity assumptions. Industry-specific forecast inputs incorporated enzymatic fat replacement technology adoption curves and cold-chain infrastructure investment pipelines in China and Southeast Asia.
Material uncertainties — FSSAI trans-fat limit enforcement escalation, EFSA health claims opinion reversals, Indian monsoon yield volatility — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory timeline stability and input cost mean-reversion. Revision becomes warranted when EFSA evidentiary standards for cardiovascular benefit claims cross thresholds requiring clinical endpoint studies rather than compositional data.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
South America Soup Market
Processed Foods
Mashed Potatoes Market
Processed Foods
Low Fat Chicken Soup Market
Processed Foods
Low Fat Pasta Market
Processed Foods
Global Potato Flake Market
Processed Foods
Europe Egg Powder Market
Processed Foods
Processed Beef Market
Processed Foods
Noodles Market
Processed Foods
Processed Vegetable Market
Processed Foods
Egg White Cubes Market
Processed Foods
Global Malted Milk Market
Processed Foods
High-Pressure Processing (HPP) Foods Market
Processed Foods
India Ready to Mix Food Market
Processed Foods
Processed Egg Market
Processed Foods
Instant Curry Market
Processed Foods
Global Dried Processed Food Market