
 Instant Soup Market | 2026-2036
Instant Soup Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Soup Market Outlook
Asian noodle and broth producers is restructuring manufacturing footprints to offset wheat and palm oil volatility. Nissin Foods Holdings leverages vertical integration across flavor labs and packaging lines in Japan and Southeast Asia. Campbell Soup Co. anchors North American shelf-stable distribution through direct-store-delivery networks. Unilever PLC competes on brand equity in emerging markets with localized taste profiles.
Instant soup comprises dehydrated or pre-cooked broth bases, reconstituted with hot water in under three minutes, typically containing sodium levels between 1,500 and 2,000 mg per serving. The category serves industrial foodservice operators and retail consumers seeking meal solutions with sub-five-minute preparation cycles. Cup soup formats lead volume in convenience channels across East Asia, while powdered soup dominates household pantry replenishment in North America and Europe. Ready-to-eat tetra pack variants capture margin pools in premium urban retail, where packaging innovation commands price premiums over bag formats.
The FDA enforces Nutrition Facts Label sodium disclosure rules that push manufacturers toward reduced-sodium recipes or front-of-pack warning systems. EFSA evaluates health claims scrutiny across the EU, while Japan's Consumer Affairs Agency mandates allergen labeling precision for processed soup bases. Stakeholders must monitor reformulation cost pass-through dynamics and regional labeling divergence as portfolio complexity rises.
Market Dynamics
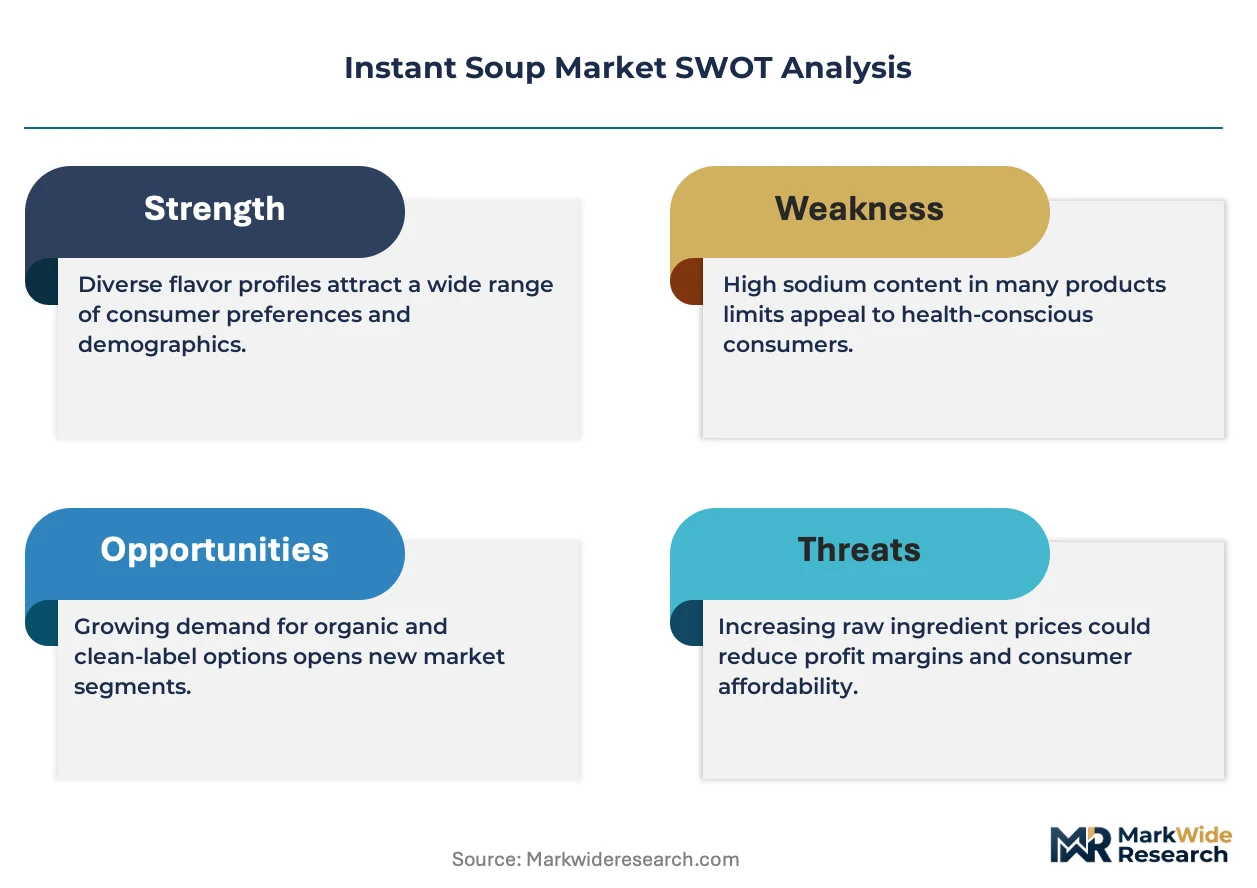
Sodium disclosure mandates from the FDA and EFSA are forcing simultaneous recipe reformulation and front-of-pack labeling investments across instant soup portfolios, compressing margin structures while elevating compliance costs.
Growth Catalysts
- Urban time compression:Households in Tokyo, Seoul, and Mumbai now allocate under 25 minutes to meal preparation, channeling demand toward sub-three-minute reconstitution formats.
- EFSA health claims pathway:The EU regulator's clarified substantiation criteria enable reduced-sodium positioning with validated cardiovascular benefit language.
- Cup format infrastructure:Convenience store density in Japan and South Korea creates captive distribution for single-serve heat-stable packaging.
Market Restraints
- Wheat and palm oil volatility:Asian noodle producers face margin erosion from commodity price swings that resist full pass-through in price-sensitive retail channels.
- Sodium reduction technical ceiling:Potassium chloride and yeast extract replacements hit flavor authenticity limits at sub-1,200 mg sodium levels, constraining clean-label reformulation.
- Single-use plastic scrutiny:Japan's Consumer Affairs Agency and EU Single-Use Plastics Directive threaten cup format viability without fiber-based lining breakthroughs.
Strategic Opportunities
- India tier-two urbanization:Cities including Pune, Ahmedabad, and Kochi show underpenetrated modern trade presence for premium tetra-pack broth variants.
- Clean-label umami technologies:Fermented rice koji and shiitake-derived glutamates converge to replace synthetic flavor enhancers in premium positioning.
- Direct-to-pantry subscription:Quarterly replenishment models bypass traditional grocery slotting fees while capturing household pantry share.
Industry Challenges
- Flavor chemist scarcity:The specialized expertise required for sodium-reduced taste modulation commands premium compensation in Japan and South Korea.
- Dual certification timelines:Simultaneous FDA Nutrition Facts Label updates and EFSA health claims substantiation stretch regulatory affairs capacity.
- Legacy equipment retrofitting:Aseptic filling lines designed for high-sodium matrices require revalidation for reformulated low-sodium recipes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Soup Market |
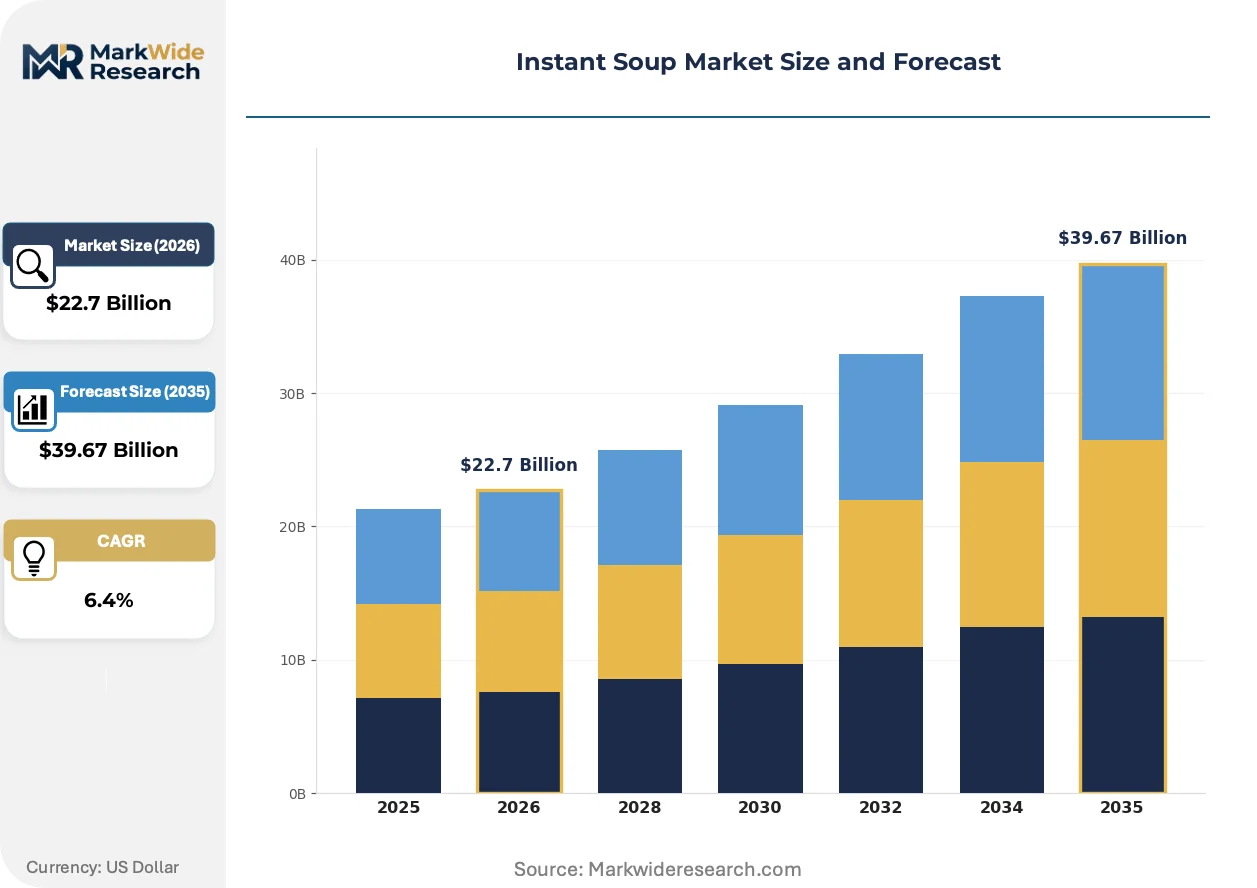
| Market Size in 2026 | $22.7 Billion |
| Market Size in 2035 | $39.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Soup, Cup Soup, Ready-to-Eat Soup, Dehydrated Soup Flavor Profile: Chicken, Tomato, Vegetable, Seafood End User: Households, Restaurants, Cafeterias, Convenience Stores Packaging Type: Bags, Cups, Tetra Packs, Jars |
| Companies Covered | Nissin Foods Holdings Co. Ltd., Baxters Food Group Ltd., The Kraft Heinz Co., Unilever PLC, General Mills Inc., Nestle SA, Conagra Brands Inc., House Foods Group Inc., Campbell Soup Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Soup Market Strategic Shifts
Reformulation science and packaging substrate innovation are converging to redefine competitive advantage, with regulatory pressure acting as the forcing function rather than consumer pull alone.
Freeze-dried vegetable and protein inclusions are absorbing moisture control complexity previously managed through synthetic humectants. Premium cup soup lines in Japan now embed separately compartmented freeze-dried toppings that rehydrate with texture integrity. This technology is absorbing the premiumization burden that sodium reduction otherwise undermines.
REACH chemical registration requirements in the EU are tightening scrutiny on flavor additive safety dossiers. Manufacturers must now submit extended toxicity data for pyrazine and furan compounds common in roasted broth notes. Powdered soup exporters to Germany and France face reformulation deadlines or supply exclusion.
Urban households in Asia-Pacific are consolidating weekly pantry replenishment into fewer, larger digital grocery orders. Instant soup multipacks and subscription bundles displace single-unit impulse purchases at physical convenience stores. This pattern concentrates most visibly in Shanghai and Singapore, where delivery app penetration exceeds 70 percent among working-age consumers.
Instant Soup Market Segmentation
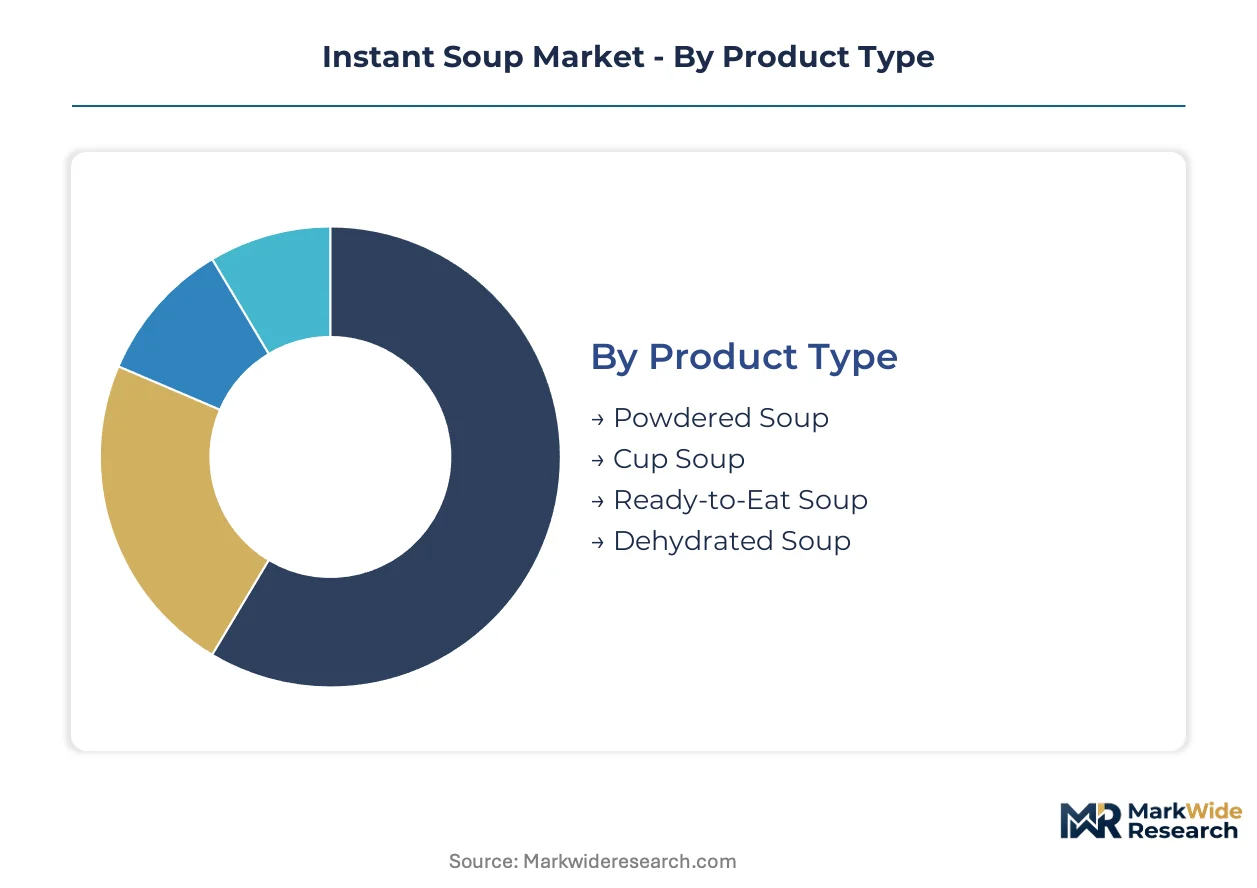
Instant soup manufacturers configure production assets around format-specific filling technologies and shelf-stability requirements. Segmentation reveals where capital deployment concentrates and which vectors drive portfolio complexity.
Product Type:
Capital intensity varies sharply across formats, with aseptic filling lines and retort equipment demanding the heaviest upfront investment.
- Cup Soup:Heat-stable single-serve containers require specialized forming and sealing equipment with validated microbiological barriers. Demand clusters in Japanese and South Korean convenience channels where 24-hour retail density supports premium placement. EFSA packaging migration limits are forcing liner material transitions that elevate per-unit capital costs.
- Ready-to-Eat Soup:Tetra Pak and retort pouch formats demand sterile filling infrastructure with hydrogen peroxide or steam-based decontamination systems. Urban Indian households in Mumbai and Delhi are shifting toward these variants as modern trade penetration deepens. FSSAI thermal process validation requirements extend commissioning timelines for new lines.
- Powdered Soup:Blending and sachet-forming equipment carries lower capital thresholds, with multi-lane vertical form-fill-seal machines serving high-volume output. Bag-in-box formats dominate North American pantry replenishment cycles.
- Dehydrated Soup:Freeze-drying or air-drying towers require substantial energy inputs and climate-controlled storage infrastructure. Noodle-inclusive variants absorb moisture management complexity through modified atmosphere packaging.
Cup Soup absorbs the bulk of installed capacity; Ready-to-Eat Soup is expanding most quickly.
Flavor Profile:
Formulation R&D intensity and raw material sourcing complexity differentiate segments by margin structure rather than capital deployment.
- Chicken:Broth base standardization across poultry sourcing geographies demands consistent umami extraction protocols. Households in the United States and Germany treat this as the default pantry staple, with sodium reduction mandates driving yeast extract and potassium chloride substitution research.
- Seafood:Dried shrimp, bonito flake, and kelp-derived stocks require allergen segregation infrastructure and precise iodine content management. Japanese and South Korean consumers absorb premium pricing for Hokkaido kelp and Katsuobushi authenticity markers.
- Tomato:Acidic pH profiles enable natural preservation but constrain protein inclusion stability. Mediterranean and Latin American markets concentrate demand for this profile.
- Vegetable:Seasonal raw material variability necessitates flexible procurement contracts across multiple growing regions. Clean-label positioning favors this segment in German and French retail.
Chicken commands the largest production volume allocation; Seafood carries the steepest premium pricing trajectory.
End User:
Customer-type segmentation determines order cycle predictability and specification stringency rather than equipment specialization.
- Households:Multipack configurations and subscription replenishment models are displacing single-unit impulse purchases in Shanghai and Singapore digital grocery channels. Sodium disclosure readability drives front-of-pack design investments.
- Restaurants:Foodservice operators specify bulk dehydrated bases with consistent reconstitution ratios for kitchen labor efficiency. HACCP documentation requirements exceed retail standards.
- Convenience Stores:Single-serve cup formats with attached spoons dominate Japanese 7-Eleven and Lawson shelf sets. SKU proliferation pressures inventory turns.
- Cafeterias:Institutional buyers negotiate annual contracts with volume-tier pricing and nutritional compliance certification. USDA school meal guidelines constrain sodium thresholds in the United States.
Households generate the steadiest demand baseline; Convenience Stores are gaining share fastest through 24-hour retail expansion.
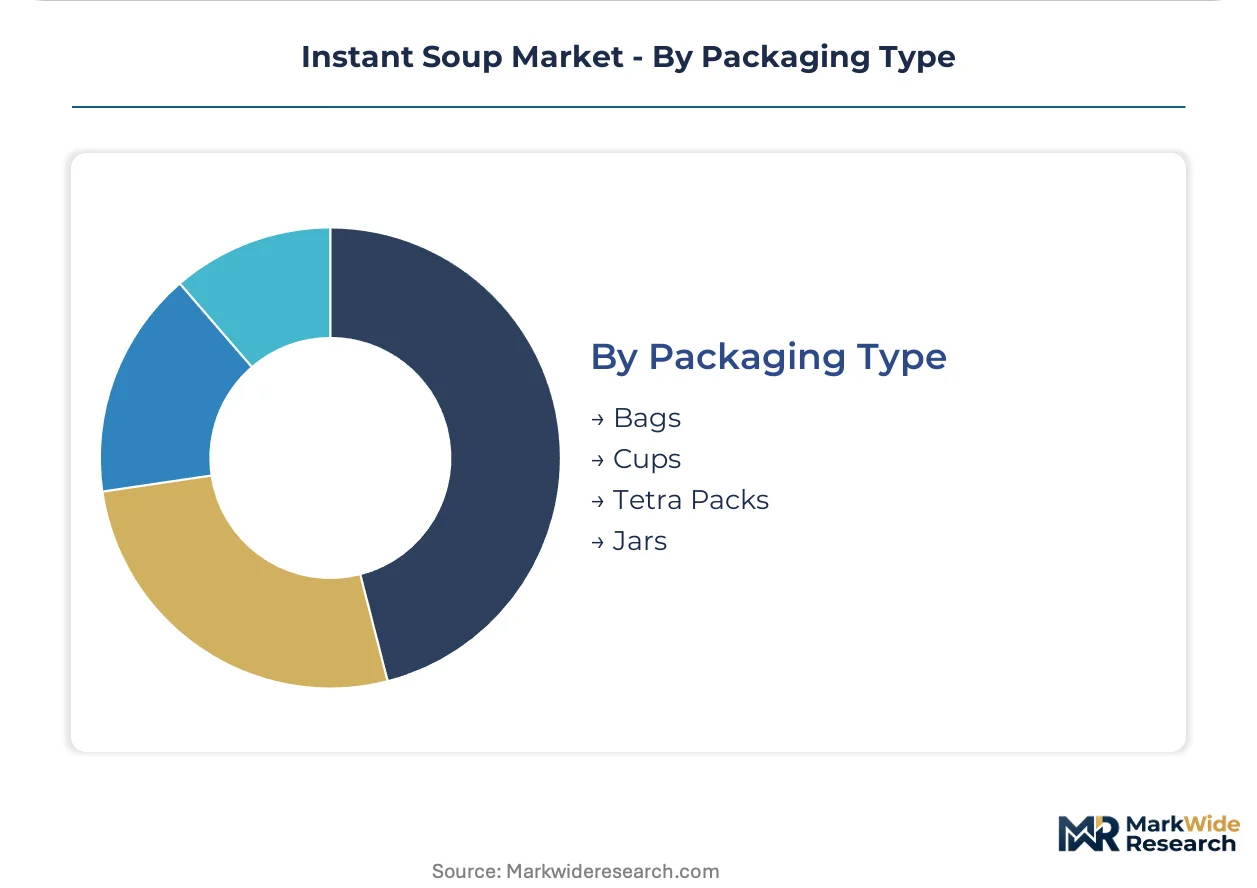
Packaging Type:
Material science investments and regulatory compliance burdens segment this category by sustainability transition exposure.
- Cups:Polypropylene and paperboard laminates face EU Single-Use Plastics Directive and Japan Consumer Affairs Agency fiber-content mandates. Separately compartmented topping chambers add assembly complexity.
- Tetra Packs:Aseptic carton technology with aluminum barrier layers commands premium positioning in Indian and Brazilian urban retail. Recycling infrastructure gaps constrain circularity claims.
- Bags:Multi-layer flexible films with oxygen scavengers dominate powdered soup shelf stability. Vertical form-fill-seal throughput rates exceed rigid container lines.
- Jars:Glass packaging supports premium positioning in German organic retail but elevates freight costs and breakage risk. Retort processing compatibility limits recipe flexibility.
Cups retain the dominant installed base; Tetra Packs are climbing the fastest on sustainability positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wheat cultivation zones in the North American Great Plains and palm oil processing clusters across Southeast Asia anchor raw material sourcing for instant soup manufacturing networks.
United States
Households in Chicago and Dallas drive powdered soup pantry replenishment through warehouse club channels. The FDA enforces updated Nutrition Facts Label sodium disclosure timelines that compress reformulation windows. Campbell Soup Co. maintains direct-store-delivery infrastructure across the Midwest and Southeast retail corridors.
Japan
Tokyo and Osaka convenience store density sustains 24-hour cup soup consumption patterns. METI oversees packaging material standards that accelerate fiber-based liner transitions. Nissin Foods Holdings operates captive flavor laboratories and forming equipment clusters in Kanto and Kansai manufacturing belts.
India
Mumbai and Delhi urban households shift toward tetra-pack ready-to-eat variants as modern trade penetration deepens. FSSAI thermal process validation requirements extend commissioning timelines for new aseptic filling lines. Pune and Ahmedabad tier-two cities show underpenetrated premium broth positioning.
Germany
Clean-label positioning drives vegetable-profile demand in Berlin and Munich organic retail channels. EFSA health claims substantiation criteria enable reduced-sodium cardiovascular benefit language. REACH chemical registration tightens scrutiny on pyrazine and furan flavor additive safety dossiers.
South Korea
Seoul's time-compressed professional class sustains premium cup soup placement in CU and GS25 convenience networks. MFDS allergen labeling precision mandates affect processed soup base import documentation. Busan-Ulsan manufacturing corridors concentrate heat-stable packaging production equipment.
Instant Soup Market Competitive Environment
Global majors compete with regional champions across sodium-reduction technology and convenience channel placement. The vendor base stratifies between diversified packaged food conglomerates with cross-category R&D budgets and specialized Asian broth producers with captive umami extraction capabilities. Three archetypes dominate: vertically integrated flavor technology owners, shelf-stable distribution specialists with direct-store-delivery networks, and clean-label positioning innovators. Capacity expansion in aseptic filling infrastructure and strategic partnerships for fiber-based packaging substrates represent the dominant competitive moves.
Among Japanese and American packaged food conglomerates, Nissin Foods Holdings Co. Ltd., Campbell Soup Co., and Unilever PLC occupy positions across the technology-differentiated and distribution-anchored tiers. Nissin exemplifies the vertically integrated archetype through captive supply of flavor extraction and forming equipment. Campbell represents the shelf-stable distribution specialist model with established replenishment infrastructure. Unilever sits within the brand-equity tier competing on localized taste profile adaptation.
| Leading Market Players |
|---|
| Nissin Foods Holdings Co. Ltd. |
| Baxters Food Group Ltd. |
| The Kraft Heinz Co. |
| Unilever PLC |
| General Mills Inc. |
| Nestle SA |
| Conagra Brands Inc. |
| House Foods Group Inc. |
| Campbell Soup Co. |
| Others |
Value Chain & Pricing Dynamics
Wheat futures volatility in the North American Great Plains and palm oil price swings across Malaysian and Indonesian processing clusters transmit directly through instant soup manufacturing cost structures, stratifying finished goods into premium-mid-economy pricing tiers that reflect input sourcing geography and reformulation complexity.
Pricing Analysis
Service bundling separates contract foodservice supply—with technical support for reconstitution ratios and HACCP documentation—from unbundled retail shelf pricing where slotting fees and trade promotion absorb margin. Three-tier pricing structure across premium, standard, and economy levels tracks sodium reduction investment depth, with clean-label umami technologies commanding 15-25 point spreads over commodity yeast extract formulations. Cost compression in economy-tier powdered sachets is intensifying because private-label competition resists full commodity pass-through. Household pantry replenishment buyers in North America show highest price elasticity, while Japanese convenience channel operators absorb premium cup placement costs for 24-hour access.
Supply Chain Analysis
Direct-store-delivery networks anchored by Campbell Soup Co. handle hyperscale retail replenishment across Midwest and Southeast US corridors, while Nissin Foods Holdings operates captive distribution through Kanto and Kansai manufacturing belts feeding Japanese convenience density. Wheat sourcing concentrates in the United States, Canada, and Australia; palm oil draws from Malaysia, Indonesia, and Thailand; flavor extraction infrastructure clusters in Japan and South Korea. Single-source vulnerability in Hokkaido kelp and Katsuobushi supply creates concentration risk for seafood-profile premium positioning. Distribution runs through modern trade expansion in Indian tier-two cities and digital grocery consolidation in Shanghai and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Instant soup manufacturing functions as a cost-of-compliance market where FDA sodium disclosure mandates and EFSA health claims substantiation create regulatory moats that favor incumbents with dedicated regulatory affairs capacity and reformulation R&D budgets.
For Market Incumbents: Deploy captive flavor laboratory infrastructure to accelerate clean-label umami substitution timelines ahead of yeast extract supply constraints. Sodium reduction technical ceilings threaten flavor authenticity at sub-1,200 mg thresholds; backward integration into fermented rice koji and shiitake-derived glutamate sourcing defends premium positioning against commodity input volatility. Fiber-based packaging liner transitions required by Japan's Consumer Affairs Agency and EU Single-Use Plastics Directive demand equipment revalidation investment that smaller competitors cannot absorb. For New Entrants and Emerging Players: Launch via direct-to-pantry subscription models bypassing traditional grocery slotting fee structures in underpenetrated Indian tier-two cities including Pune, Ahmedabad, and Kochi. Tetra-pack ready-to-eat broth variants show whitespace opportunity where modern trade penetration deepens ahead of cup format infrastructure density. Clean-label positioning with fermented ingredient transparency captures German and French organic retail price premiums absent from commodity powdered soup competition. For Investors and Strategic Acquirers: MFDS allergen labeling precision mandate enforcement in South Korea is the leading indicator that regulatory complexity is accelerating across Asia-Pacific, favoring acquisition targets with established multi-jurisdictional compliance infrastructure. Vertically integrated mid-cap specialists with captive umami extraction and forming equipment clusters offer defensive positioning through input cost control and format flexibility. Watch for fiber-based packaging substrate partnership announcements as signal of capital deployment into sustainability-mandated equipment transitions.| Strategic Initiative | Industry Significance |
|---|---|
| Sodium Reduction R&D Investment | Yeast extract and potassium chloride substitution research defends market access under FDA disclosure rules. |
| Fiber-Based Packaging Transition | EU Single-Use Plastics Directive compliance requires liner material revalidation for cup format viability. |
| Direct-to-Consumer Subscription Launch | Quarterly replenishment models bypass grocery slotting fees while capturing Shanghai and Singapore pantry share. |
| Tier-Two Urban Distribution Expansion | Pune and Ahmedabad modern trade penetration offers premium tetra-pack positioning ahead of convenience infrastructure. |
| Clean-Label Umami Technology Partnership | Fermented rice koji and shiitake-derived glutamate sourcing enables synthetic flavor enhancer replacement. |
Study Parameters
Independent corroboration across regulatory filing analysis, trade flow databases, and channel inventory audits underwrites the qualitative findings in this study. Primary interviews with instant soup brand managers, category buyers at modern trade retailers, flavor technology R&D directors, and foodservice procurement officers combined with secondary validation from FDA guidance documents, EFSA health claims registers, FSSAI thermal process standards, and Nielsen retail audit data. Bottom-up volume modeling across cup, tetra-pack, powdered, and dehydrated formats triangulates against top-down value estimates from customs records and SEC 10-K segment disclosures.
Rate-of-change decomposition across the projection horizon isolates format shift velocity, sodium reformulation adoption curves, and packaging substrate transition timelines. Segmentation dimensions modeled include product type, flavor profile, end-user channel, and packaging material class, with geographic regulatory cluster effects layered across country-level forecasts. CAGRs derive from historical volume trajectories adjusted for urban time-compression demand elasticity and modern trade penetration rates in emerging consumption clusters.
The model assumes a particular technology adoption path; alternative pathways for freeze-dried topping compartmentalization and aseptic filling line revalidation would alter the outlook if fiber-based barrier commercialization delays or clean-label umami extraction cost curves flatten. Forecasts reflect base-case assumptions about regulatory enforcement timelines and commodity input price normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Impulse Ice-Cream Market
Packaged Foods
Instant Cereals Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Jams and Spreads Market
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
Injectable Cocoa Fillings Market
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
North America Packaged Salad Market
Packaged Foods
Instant Rice Market
Packaged Foods
Tortilla Market
Packaged Foods
Condensed Canned Soups Market
Packaged Foods
Asia-Pacific Ready Meals Market
Packaged Foods
Dried Soup Market
Packaged Foods
Dehydrated and Dried Beans Market
Packaged Foods
North America Chewing Gum Market
Packaged Foods
Global Dessert Mixes Market