
 Asia-Pacific Food Spread Market | 2026-2036
Asia-Pacific Food Spread Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Food Spread Market Outlook
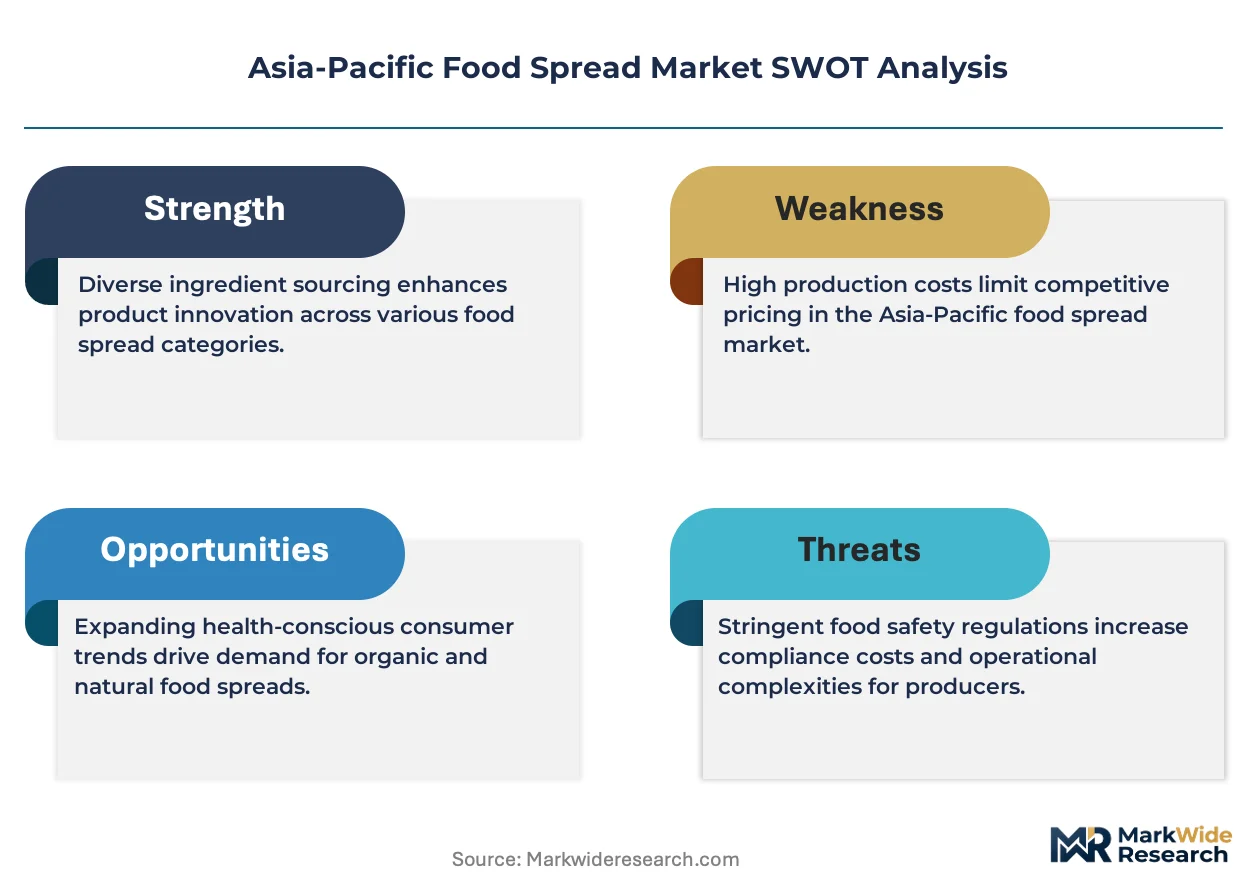
FSSAI nutritional labeling and fortification compliance is reorganizing competitive access across the Asia-Pacific food spread landscape. Nestlé S.A. leverages its dairy supply chain depth to sustain cost-advantaged positioning in butter and margarine segments across Southeast Asia. Ferrero Group anchors its premium nut butter portfolio through specialized hazelnut sourcing relationships that competitors struggle to replicate.
Food spreads encompass emulsified, pasteurized, or preserved lipid-based formulations designed for direct consumption or recipe integration, typically containing 60-80% fat content with stabilizers ensuring shelf stability between 6-24 months under ambient or refrigerated conditions. Fruit spreads lead volume contribution due to lower price points and established jam consumption traditions in Australia and Japan, while nut butters capture accelerating growth from protein-positioned snacking trends in India and China. Breakfast applications concentrate the largest margin pool as manufacturers command premium positioning for fortified and functional spread variants targeting morning consumption rituals.
India's FSSAI fortification standards, Australia's FSANZ labeling requirements, and Japan's JAS organic certification collectively elevate formulation costs while filtering out sub-scale regional blenders lacking analytical capabilities. China's SAMR food safety audits further tighten import clearance protocols for foreign spread manufacturers seeking mainland market access. Stakeholders must monitor evolving front-of-pack labeling mandates across ASEAN member states as these regulations will determine which product portfolios remain commercially viable without reformulation investment.
Market Dynamics
FSSAI fortification mandates are compressing formulation flexibility while simultaneously opening premium positioning for compliant manufacturers across India and influencing neighboring regulatory frameworks.
Growth Catalysts
- Protein-Enriched Breakfast Positioning:Urban Indian households are adopting nut butters and fortified dairy spreads as core morning protein sources, displacing traditional ghee consumption in tier-1 and tier-2 cities.
- FSSAI Micronutrient Standards:India's mandatory fortification requirements for packaged spreads are creating competitive moats for manufacturers with in-house analytical laboratories and supply chain traceability systems.
- Cold Chain Infrastructure:Refrigerated logistics networks across Southeast Asia are extending shelf-stable spread distribution into previously unserved rural and semi-urban catchments.
Market Restraints
- Palm Oil Price Volatility:Margarine and compound spread formulations remain exposed to Malaysian and Indonesian palm oil futures fluctuations, compressing margin predictability for cost-positioned brands.
- Hazelnut Supply Concentration:Premium chocolate-hazelnut spreads depend on Turkish and Italian hazelnut harvests, creating geographic concentration risk that limits formulation diversification.
- Import Clearance Friction:China's SAMR food safety audit protocols impose extended clearance timelines on foreign spread manufacturers, constraining market access velocity for non-domestic players.
Strategic Opportunities
- Vietnam and Philippines Penetration:Organized retail expansion in Vietnamese and Filipino urban centers offers first-mover positioning for fortified spreads targeting emerging middle-class breakfast routines.
- E-Commerce Direct-to-Consumer Channels:Platform-native spread brands are bypassing traditional FMCG distribution layers through Tmall, Lazada, and Shopee flagship stores with subscription-based replenishment models.
- PLI Scheme Alignment:India's Production Linked Incentive schemes for food processing infrastructure reward domestic manufacturing scale, favoring localized production investments over import-dependent models.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Emulsion stability expertise for ambient-temperature lipid systems remains concentrated among senior food technologists, constraining R&D team scaling for mid-tier manufacturers.
- Multi-Jurisdiction Labeling Complexity:Simultaneous compliance with FSSAI front-of-pack requirements, FSANZ nutritional panels, and JAS organic certification demands dedicated regulatory affairs capacity that smaller blenders lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Food Spread Market |
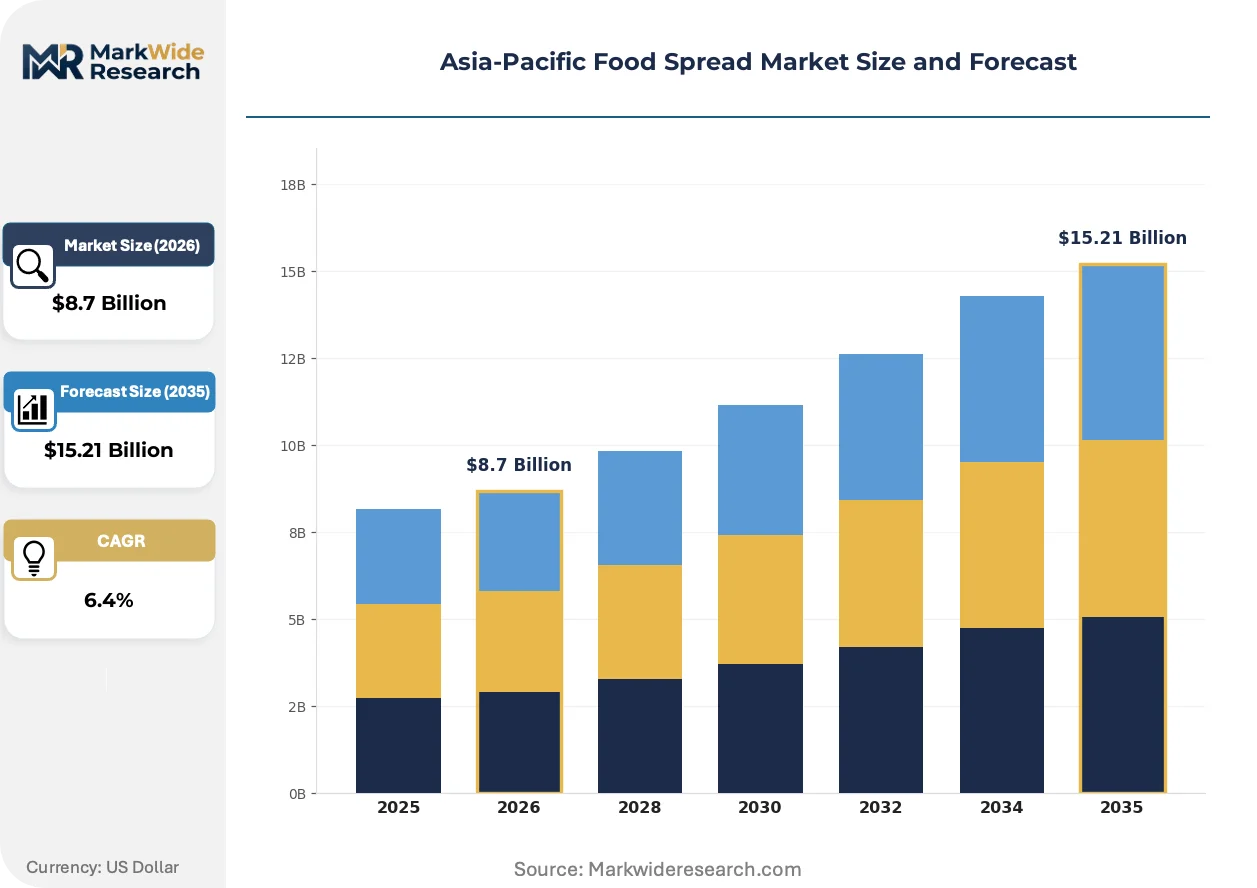
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter, Margarine, Nut Butters, Fruit Spreads Application: Breakfast, Snacks, Baking, Sauces Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores Customer Type: Households, HoReCa, Food Manufacturers, Schools |
| Companies Covered | Cremica Agro Foods Limited, Ferrero Group, Unilever PLC, The Hershey Company, The J.M. Smucker Company, Nestlé S.A., Mondelez International, Kraft Heinz Company, Conagra Brands, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Food Spread Market Strategic Shifts
Clean-label emulsification systems and precision fermentation-derived ingredients are restructuring competitive differentiation across the Asia-Pacific spread landscape, with regulatory compliance and protein positioning as parallel innovation axes.
High-pressure processing is supplanting traditional thermal pasteurization in premium fruit spread manufacturing. Australian and Japanese organic brands are adopting HPP systems to preserve volatile aromatic compounds without synthetic preservatives. This technology is compressing the shelf-life gap between conventional and clean-label products while enabling ambient distribution for previously refrigerated-only positioning.
FSANZ front-of-pack health star rating recalibrations are forcing reformulation investments across Australian spread portfolios. Manufacturers are reducing added sugars and sodium to maintain competitive star ratings on retail shelves. The breakfast spread segment is responding fastest, with major retailers delisting sub-three-star products from core planogram positions.
Convenience-driven single-serve sachet formats are disrupting bulk jar purchasing in Indian and Chinese urban markets. Foodservice channels and airline catering programs are adopting portion-controlled nut butter and fruit spread sachets, replacing traditional institutional tubs. This format rotation is most visible in Shanghai, Mumbai, and Bangalore, where on-the-go consumption occasions dominate morning routines.
Asia-Pacific Food Spread Market Segmentation
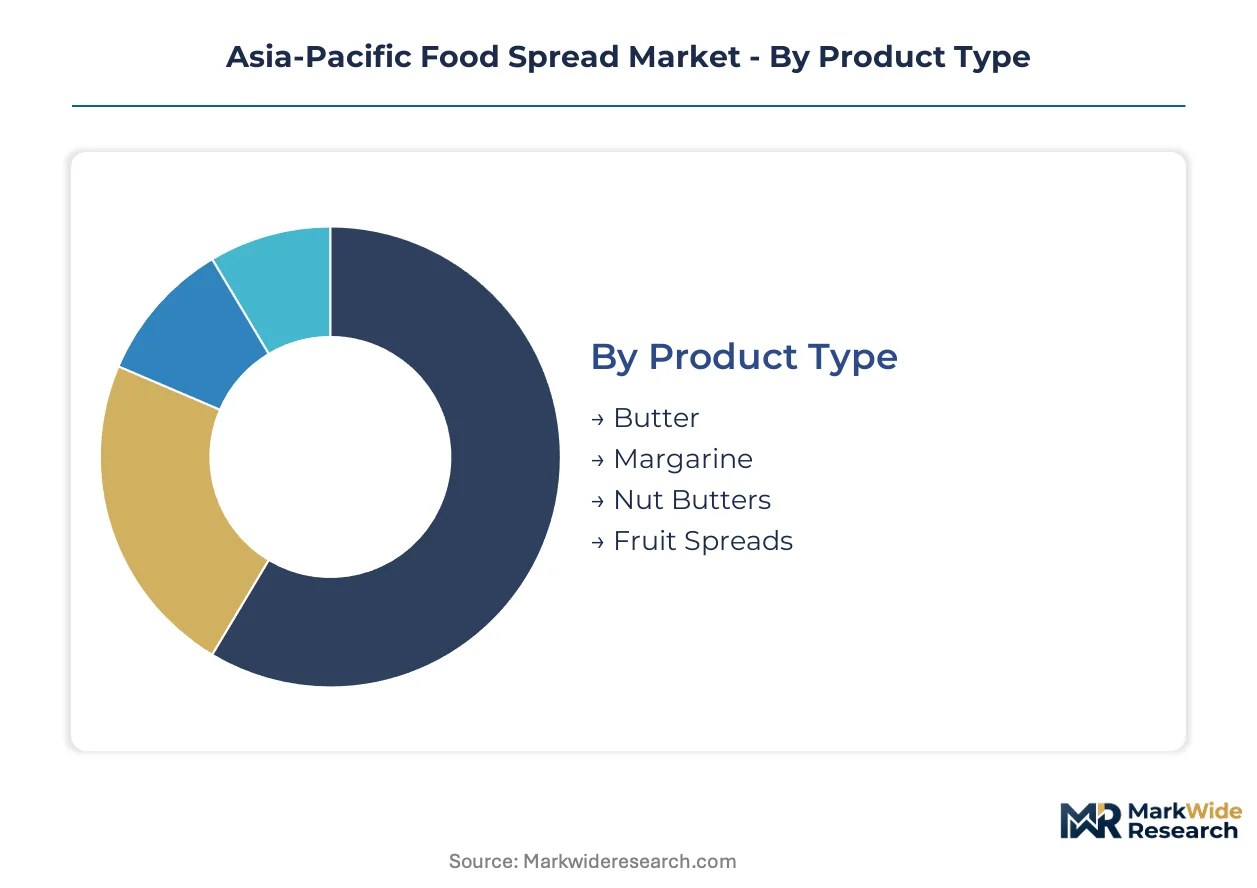
Segmentation in the Asia-Pacific food spread market reveals how margin pools concentrate around breakfast rituals and protein-positioned snacking. Manufacturers optimize formulation investments by tracking which product-application combinations command premium shelf positioning versus commodity substitution risk.
Product Type:
Margin concentration skews heavily toward nut butters and premium dairy derivatives, while fruit spreads compete on volume throughput at thinner unit economics.
- Butter:Traditional churned dairy fat formulations with 80-82% milk fat content serve baking and direct consumption across Australian and Japanese households. Indian FSSAI fortification mandates are forcing reformulation investments among domestic creamery processors targeting organized retail expansion in Mumbai and Delhi.
- Nut Butters:Ground legume and tree nut pastes—peanut, almond, cashew—deliver 20-25% protein positioning for urban Indian and Chinese breakfast routines. Demand clusters in Bangalore and Shanghai where fitness-positioned consumption displaces traditional ghee.
- Margarine:Emulsified vegetable oil spreads with added vitamins compete on cost in Southeast Asian food manufacturing channels. Palm oil price volatility compresses margin predictability for Malaysian and Indonesian blenders supplying HoReCa bulk contracts.
- Fruit Spreads:Preserved fruit preparations with 35-65% soluble solids dominate Australian and Japanese retail jam traditions. High-pressure processing adoption among organic brands is narrowing the shelf-life gap with conventional thermally processed alternatives.
Fruit spreads hold installed capacity across established Australian manufacturing bases. Nut butters are rotating up the share rankings as protein enrichment drives premiumization in Indian and Chinese urban markets.
Application:
Breakfast occasions generate the steepest margin premiums, while baking applications concentrate volume throughput at negotiated contract pricing.
- Breakfast:Direct table spreads consumed with bread, roti, or congee anchor manufacturer profitability through fortified and functional variant pricing. FSSAI micronutrient standards create compliance moats that filter out sub-scale regional competitors in Indian organized retail.
- Snacks:Protein-positioned nut butter consumption between meals drives fastest expansion in Chinese and Indian metropolitan areas. Single-serve sachet formats are disrupting bulk jar purchasing in Shanghai, Mumbai, and Bangalore convenience channels.
- Baking:Industrial and artisanal bakery procurement of bulk margarine and compound spreads operates on cost-plus contracts with limited brand differentiation. Southeast Asian food manufacturers source through established Malaysian and Indonesian supply relationships.
- Sauces:Spread-derived cooking bases and finishing glazes serve restaurant and institutional kitchen applications across Vietnam and Philippines urban centers. Local flavor adaptations—chili-infused, tamarind-forward—determine competitive access in these emerging markets.
Breakfast commands premium positioning. Snacks are climbing the fastest as on-the-go consumption patterns reshape portion format requirements.
Distribution Channel:
Cold chain reach determines which product formats penetrate beyond tier-1 urban cores, with digital channels bypassing traditional FMCG distribution layers.
- Supermarkets:Organized retail chains in India, Australia, and Japan enforce front-of-pack labeling compliance that filters non-compliant spread portfolios. Planogram positioning for fortified variants commands slotting fee premiums in tier-1 city locations.
- Online Retail:Tmall, Lazada, and Shopee flagship stores enable platform-native brands to deploy subscription-based replenishment models. Direct-to-consumer logistics bypass traditional distributor margins while capturing consumption data for flavor innovation.
- Convenience Stores:Urban grab-and-go channels in Tokyo, Seoul, and Singapore concentrate single-serve and travel-format spread sales. Refrigerated shelf space constraints limit ambient-stable product lines in these high-rent locations.
- Specialty Stores:Organic and gourmet retail in Australian and Japanese metropolitan areas curate clean-label and JAS-certified spread assortments. High-pressure processed fruit spreads and small-batch nut butters command price multiples over mass-market alternatives.
Supermarkets hold installed capacity across established retail infrastructure. Online retail is gaining share fastest as platform economics reshape customer acquisition economics.
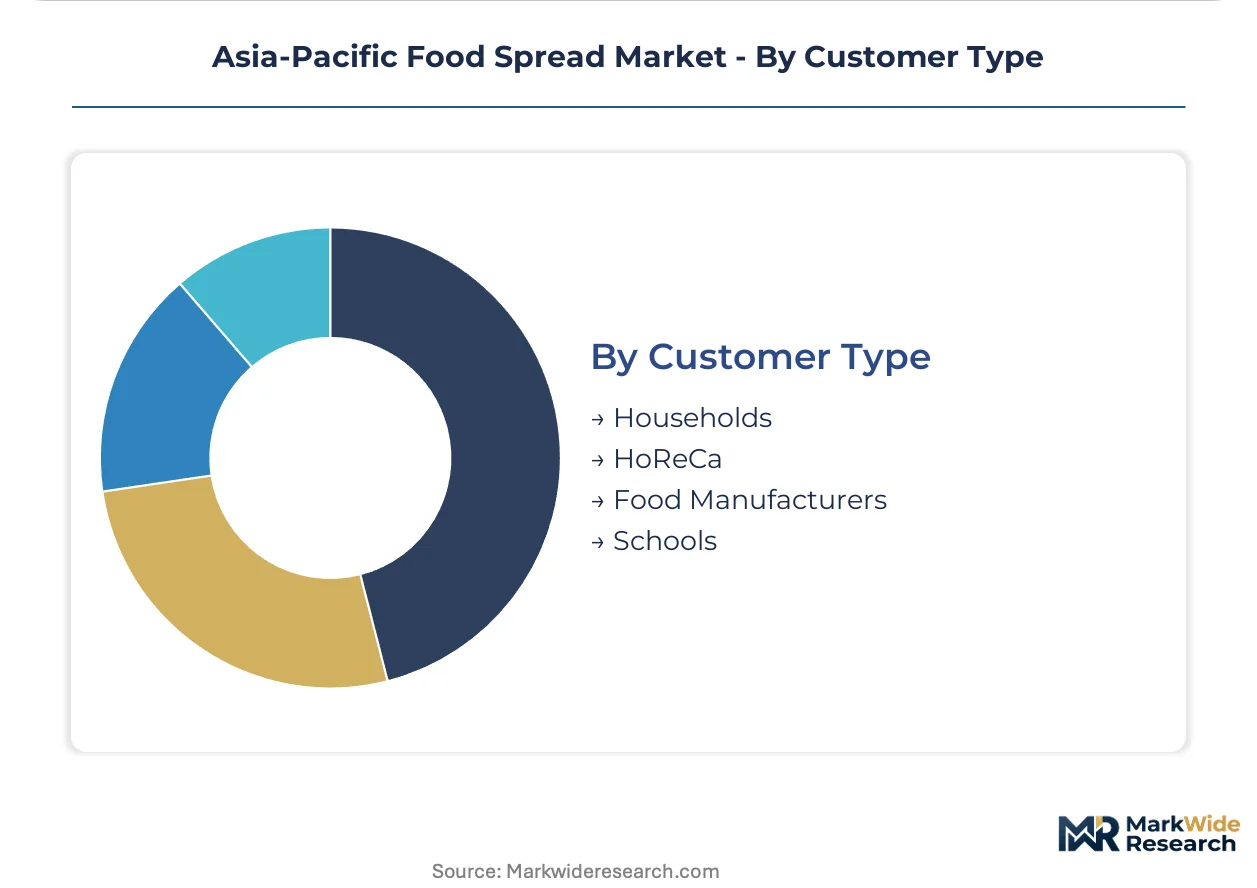
Customer Type:
Procurement sophistication varies sharply across customer types, with institutional buyers demanding supply chain traceability that household consumers rarely verify.
- Households:Individual and family purchasers drive flavor innovation through scan data feedback loops in Indian and Australian retail systems. Fortification awareness campaigns by FSSAI and FSANZ are elevating label literacy among urban middle-class segments.
- HoReCa:Hotel, restaurant, and catering procurement operates on specification-driven tenders with mandatory allergen documentation and batch traceability. Bulk margarine and portion-controlled sachet formats compete on delivered cost and packaging convenience.
- Food Manufacturers:Industrial bakery and confectionery processors source compound spreads and specialized fat systems through long-term supply agreements. Emulsion stability specifications and melting point profiles determine technical qualification.
- Schools:Institutional feeding programs in India and Southeast Asia represent emerging volume channels with mandatory fortification compliance. FSSAI-aligned suppliers capture preferred vendor status in government tender processes.
Households hold installed capacity across consumer marketing infrastructure. HoReCa is rotating up the share rankings as foodservice recovery and institutional format innovation expand addressable volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for food processing infrastructure is redirecting manufacturing investment toward domestic production bases. FSSAI fortification mandates are compressing formulation flexibility while creating compliance moats for scaled operators. Cold chain expansion across Southeast Asia is extending distribution reach into previously unserved catchments.
India
Urban households in Bangalore and Mumbai are displacing traditional ghee consumption with protein-enriched nut butters and fortified dairy spreads. FSSAI micronutrient standards for packaged spreads mandate in-house analytical capabilities that filter sub-scale regional blenders from organized retail. Maharashtra and Karnataka host the fastest-expanding manufacturing clusters, where domestic creamery processors are retrofitting facilities to meet fortification compliance.
China
Shanghai and Beijing metropolitan consumers are driving single-serve sachet adoption for on-the-go breakfast routines. SAMR food safety audit protocols impose extended clearance timelines on foreign spread manufacturers, constraining import velocity. The Yangtze River Delta concentration of food processing infrastructure supports platform-native brands deploying Tmall flagship stores with subscription replenishment models.
Australia
FSANZ front-of-pack health star rating recalibrations are forcing sugar and sodium reduction investments across spread portfolios. Major retailers are delisting sub-three-star products from core planogram positions. Victoria and New South Wales manufacturing bases are adopting high-pressure processing systems to preserve aromatic compounds in clean-label fruit spreads without synthetic preservatives.
Japan
JAS organic certification requirements are elevating formulation costs for premium positioning in Tokyo and Osaka metropolitan markets. Established jam consumption traditions sustain volume throughput for fruit spreads at thinner unit economics. The Kanto region concentration of specialty retail curates small-batch nut butter assortments commanding price multiples over mass-market alternatives.
Vietnam
Organized retail expansion in Ho Chi Minh City and Hanoi is creating first-mover positioning for fortified spreads targeting emerging middle-class breakfast routines. Local flavor adaptations—chili-infused and tamarind-forward variants—determine competitive access in foodservice channels. Central government infrastructure investment is extending refrigerated logistics networks into semi-urban catchments previously limited to ambient-stable products.
Asia-Pacific Food Spread Market Competitive Environment
Listed leaders compete with private specialists across fortified formulation capabilities and cold chain distribution reach. The market structure tilts toward consolidated multinational presence in premium nut butter and chocolate-hazelnut segments, with fragmented domestic creamery processors competing on cost in butter and margarine. Three archetypes dominate: dairy supply chain integrators, premium nut sourcing specialists, and platform-native direct-to-consumer brands. Competitive moves concentrate on M&A for regional manufacturing assets and strategic partnerships for e-commerce channel access.
Within the multinational tier, Nestlé S.A. and Ferrero Group occupy positions anchored by supply chain depth and specialized sourcing relationships respectively. Unilever PLC and The Hershey Company exemplify scale-driven portfolio diversification across multiple spread categories. Kraft Heinz Company and Mondelez International sit within the packaged foods conglomerate archetype, leveraging existing retail relationships for shelf positioning. Cremica Agro Foods Limited represents the domestic specialist model competing on localized flavor adaptation and regulatory compliance proximity.
| Leading Market Players |
|---|
| Cremica Agro Foods Limited |
| Ferrero Group |
| Unilever PLC |
| The Hershey Company |
| The J.M. Smucker Company |
| Nestlé S.A. |
| Mondelez International |
| Kraft Heinz Company |
| Conagra Brands |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Malaysian palm oil refiners and Southeast Asian margarine blenders lock in feedstock access while capping margin volatility for eighteen-to-twenty-four month windows. These contracts tether pricing visibility to plantation harvest cycles and FSSAI fortification cost pass-through clauses.
Pricing Analysis
Certification level creates the primary spread between JAS organic-certified Japanese fruit spreads and conventional thermally processed alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects fortification compliance costs, cold chain delivery premiums, and brand heritage positioning. Cost compression in economy-tier margarine is intensifying because Indonesian palm oil futures volatility feeds directly into compound spread formulations. HoReCa procurement teams exhibit highest price sensitivity, while Australian specialty retail consumers absorb premiums for clean-label HPP-processed variants.
Supply Chain Analysis
Port congestion along the Shanghai-Ningbo corridor and container availability constraints on the China-Australia trade lane are extending lead times for imported nut butter ingredients. Manufacturing gravity centers on India, Malaysia, and Turkey, with hazelnut paste production anchored in Turkish processing clusters and palm oil refining concentrated in Malaysian port zones. Formulation chemistry talent scarcity in emulsion stability represents a single-source vulnerability for mid-tier manufacturers lacking senior food technologist retention. Distribution runs through organized retail chains in tier-1 Indian cities, platform-native DTC channels, and foodservice institutional tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
In-house analytical laboratory capabilities and FSSAI compliance proximity are becoming scarce assets that filter competitive access, with mid-tier blenders struggling to recruit emulsion chemistry specialists for ambient lipid system development.
For Market Incumbents: Fortify supply chain control through backward integration into hazelnut sourcing relationships or captive dairy processing infrastructure in Maharashtra and Karnataka. Nestlé and Ferrero demonstrate how specialized ingredient access creates formulation moats that emerging competitors cannot replicate. Prioritize certification maintenance across FSSAI, FSANZ, and JAS standards to defend shelf positioning against private label encroachment. For New Entrants and Emerging Players: Anchor in Vietnamese and Filipino organized retail expansion corridors where fortification-compliant portfolios face limited domestic competition. Single-serve sachet formats for nut butters represent the most penetrable white space, displacing bulk jar purchasing in Ho Chi Minh City and Manila convenience channels. Deploy Tmall or Lazada flagship stores with subscription replenishment to bypass traditional FMCG distributor margins. For Investors and Strategic Acquirers: Capital is best deployed toward domestic Indian creamery processors with retrofitting capabilities for FSSAI fortification compliance and existing relationships with organized retail chains. Long-term viability over the next decade hinges on regulatory proximity and cold chain distribution reach rather than brand equity alone. Monitor PLI scheme allocation announcements as the critical signal for which manufacturing clusters will capture government-backed scale incentives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hazelnut Sourcing | Turkish and Italian orchard relationships secure premium chocolate-hazelnut spread formulation access against supply concentration risk. |
| FSSAI Compliance Laboratory Investment | In-house micronutrient testing capabilities filter sub-scale competitors from Indian organized retail distribution. |
| Direct-to-Consumer Platform Launch | Tmall and Lazada flagship stores with subscription models bypass traditional distributor margins while capturing consumption data. |
| High-Pressure Processing System Adoption | HPP technology preserves aromatic compounds in Australian clean-label fruit spreads without synthetic preservatives. |
| Single-Serve Sachet Format Expansion | Portion-controlled packaging addresses on-the-go breakfast routines in Shanghai, Mumbai, and Bangalore convenience channels. |
Study Parameters
Desk research of FSSAI regulatory filings, FSANZ front-of-pack labeling guidelines, and ASEAN trade flow databases preceded structured interviews with food technologists, organized retail category buyers, cold chain logistics operators, and HoReCa procurement managers. Primary fieldwork across Mumbai, Shanghai, and Melbourne manufacturing clusters was cross-validated against secondary sources including customs records, Nielsen retail audit data, and SAMR import clearance statistics. Bottom-up capacity assessments and top-down consumption estimates were triangulated to constrain variance.
Variance decomposition across product type, application occasion, distribution channel, and customer procurement sophistication shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and price evolution assumptions, with particular weighting assigned to protein-enriched breakfast adoption curves and fortification compliance cost pass-through elasticity. Palm oil futures volatility and refrigerated logistics network expansion served as key forecast sensitivity inputs.
Material uncertainties — regulatory recalibration across ASEAN member states, hazelnut harvest yield fluctuations, and cold chain infrastructure buildout delays — sit outside the modeled envelope. Forecasts reflect assumptions about FSSAI enforcement consistency and PLI scheme disbursement velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
North America Ice Cream Market
Processed Foods
Soup & Broth Market
Processed Foods
Middle East and Africa Processed Meat Market
Processed Foods
Apple Butter Market
Processed Foods
China Freeze-Dried Food Market
Processed Foods
Processed Meat Market
Processed Foods
Fresh Pasta Market
Processed Foods
Broth Market
Processed Foods
Egg Powder Market
Processed Foods
Fast-Food Reusable Market
Processed Foods
Asia-Pacific Ice Cream Market
Processed Foods
Pizza Market
Processed Foods
Coffee Creamer Market
Processed Foods
United States Egg Powder Market
Processed Foods
Block Margarine Market
Processed Foods
Ready to Serve Prefabricated Dishes Market