
 Europe Processed Egg Market | 2026-2036
Europe Processed Egg Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Processed Egg Market Analysis
Automation in shell egg breaking and pasteurization is fragmenting the traditional processor landscape across Europe. Interovo Egg Group B.V. leverages its Dutch processing network to supply liquid egg volumes to industrial bakeries throughout the Benelux region. Sanovo Technology Group anchors equipment and processing know-how that smaller operators depend on to meet EU hygiene standards. Eurovo sustains a southern European presence with specialized dried egg and egg white powder production for confectionery and sauce applications.
Processed egg products encompass liquid, dried, frozen, and powdered forms derived from shell eggs through mechanical breaking, thermal treatment, and dehydration to extend shelf stability and ensure pathogen control. Pasteurization at precise temperature-time profiles eliminates Salmonella while preserving functional proteins critical for foaming, emulsification, and gelation in industrial food manufacturing. Liquid egg dominates volume flows into bakery and ready-to-eat meal channels where operational efficiency favors pumpable, pre-portioned inputs over shell egg handling. Dried egg and egg white powder capture margin pools in confectionery and high-protein applications where transport economics and extended ambient storage justify premium conversion costs.
EFSA sets microbiological criteria and residue limits that determine which processing outputs gain formulation approval across EU member states, while REACH governs sanitizing chemicals used in plant sanitation protocols. The EU Green Deal and F-Gas Regulation push processors toward lower-carbon refrigeration and energy recovery systems that alter capital allocation for facility upgrades. Stakeholders must monitor how ECHA reviews of processing aids and the EU AI Act's implications for automated grading and inspection systems reshape compliance burdens and equipment procurement timelines.
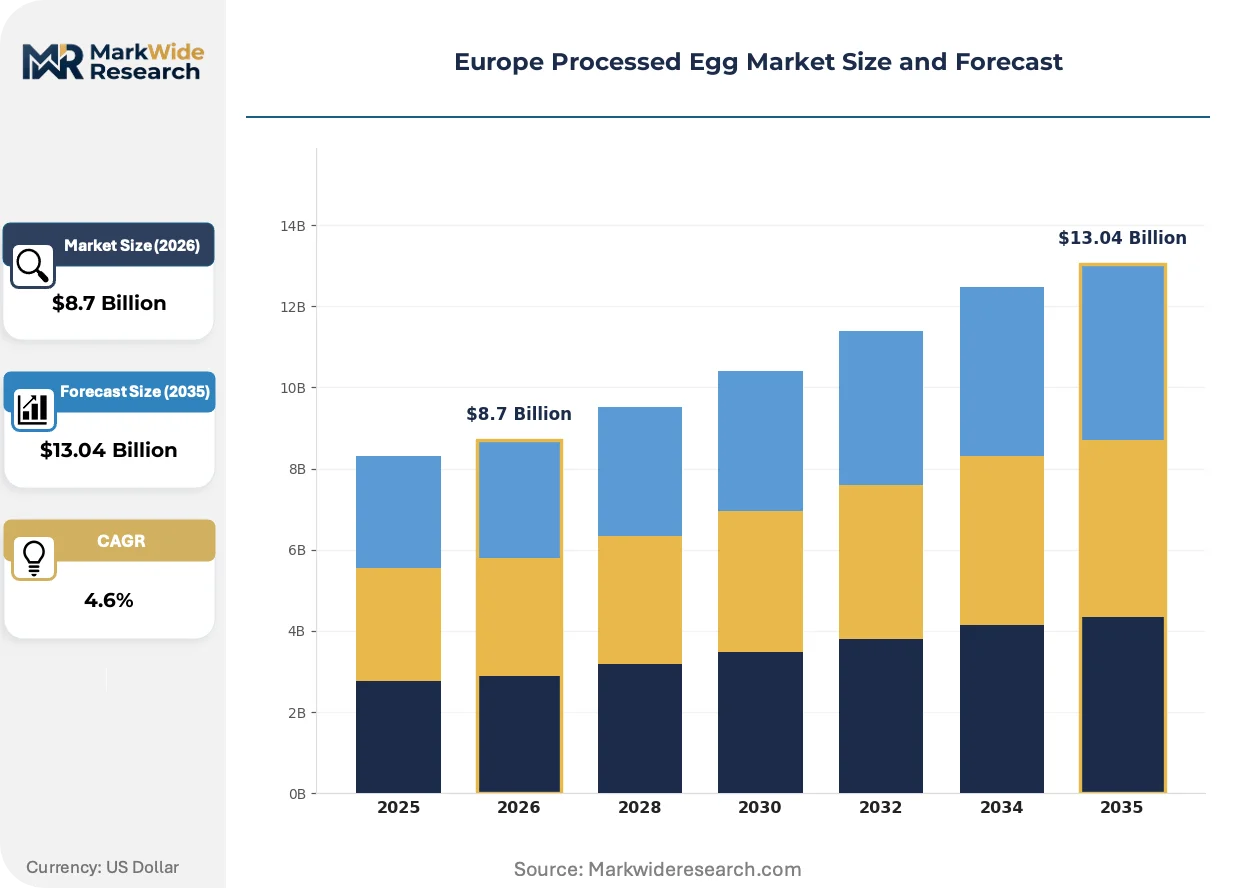
Market Dynamics
EFSA cage-free mandates and the EU Green Deal are forcing capital redeployment across European egg processors, as automated breaking and pasteurization lines replace manual handling to meet hygiene and welfare standards simultaneously.
Growth Catalysts
- Clean-label bakery demand:Industrial bakeries in Germany and France are scaling liquid egg purchases to eliminate artificial stabilizers from dough and batter formulations.
- EU Green Deal energy recovery:Capital subsidies for lower-carbon refrigeration systems are accelerating facility upgrades in the Netherlands and Poland.
- REACH sanitizing compliance:Chemical residue limits are pushing processors toward closed-loop pasteurization systems that reduce water and sanitizer consumption.
Market Restraints
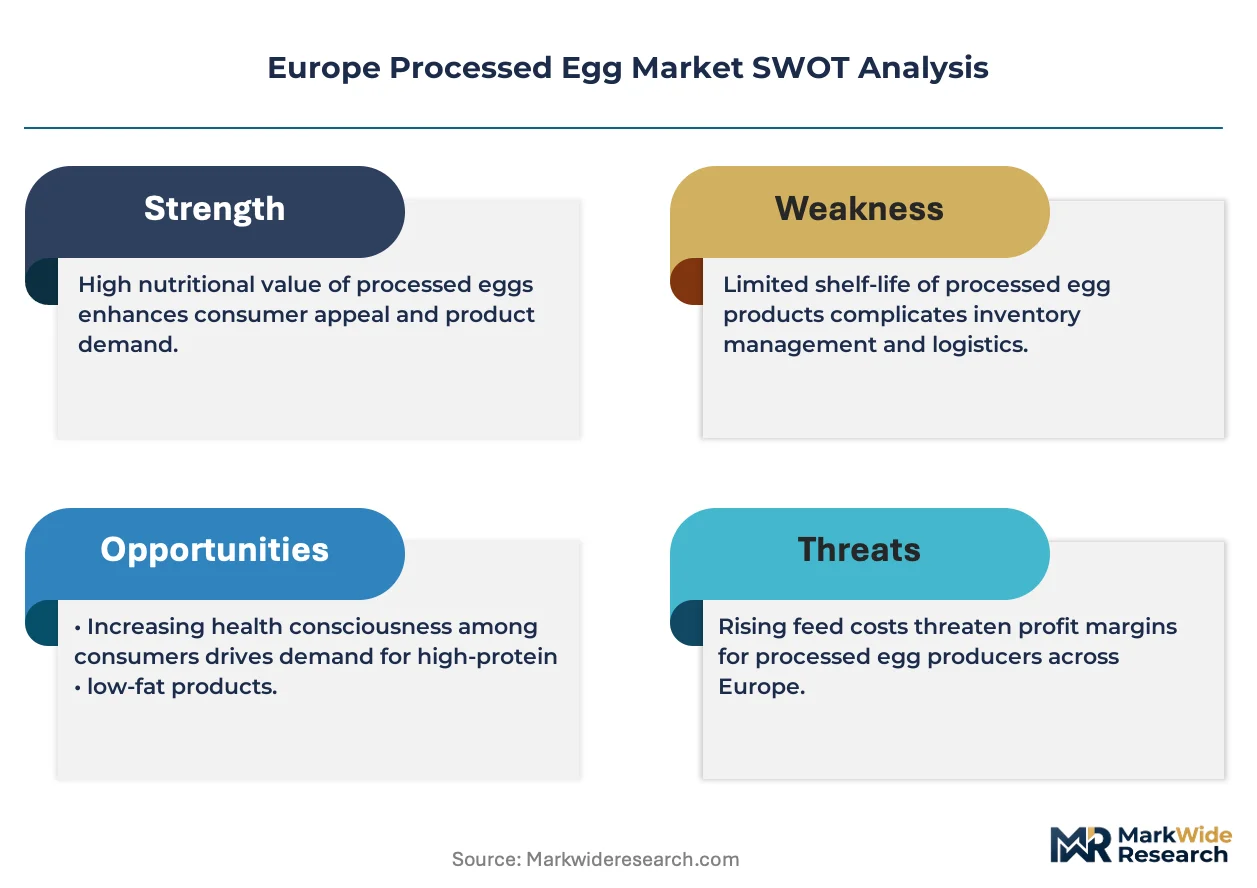
- Feed cost volatility:Soybean and corn price swings in Ukraine and Argentina transmit directly to shell egg input costs, compressing processor margins.
- Dutch processing concentration:Overreliance on Rotterdam-Antwerp corridor facilities creates single-point vulnerability for Benelux liquid egg supply.
- Functional protein degradation:Thermal pasteurization above 60°C damages ovalbumin foaming properties, limiting applications in high-volume meringue production.
Strategic Opportunities
- Polish capacity expansion:Lower labor and energy costs relative to Western Europe attract greenfield pasteurization investments serving Central European bakery chains.
- Egg white powder in sports nutrition:Ambient-stable protein concentrates are penetrating ready-to-mix shake formulations as whey prices fluctuate.
- EU AI Act inspection systems:Automated optical grading for shell defects and blood spots qualifies for regulatory fast-track approval, reducing manual labor dependence.
Industry Challenges
- Salmonella validation timelines:EFSA requires 90-day continuous monitoring for new pasteurization line approvals, delaying commercial startup.
- Retrofitting legacy breaking equipment:Pre-2015 mechanical systems lack data interfaces for EU AI Act-compliant traceability, forcing expensive control system replacements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Processed Egg Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Egg, Dried Egg, Frozen Egg, Egg White Powder Application: Baking, Sauces, Ready-to-Eat Meals, Confectionery End User: Food Service, Retail, Industrial, Bakery Manufacturers Packaging Type: Cartons, Bags, Tubs, Bulk Containers |
| Companies Covered | Interovo Egg Group B.V., Derovo Group, Sanovo Technology Group, Avril Group, Pulviver, Eurovo, IGRECA, EPS S.P.A., Rembrandt Enterprises, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Processed Egg Market Emerging Trajectories
Automation, regulatory tightening, and protein diversification are converging to reshape how European processors convert shell eggs into industrial food ingredients.
High-speed centrifugal separation technology is rendering obsolete traditional static filtration methods for yolk-white splitting. Industrial bakeries in France and Germany are adopting these systems at accelerating pace to achieve consistent emulsification indices. Manual intervention in breaking halls is rendering obsolete as labor costs and EFSA hygiene audits intensify simultaneously.
REACH reviews of quaternary ammonium sanitizers are restricting chemical options for plant hygiene protocols. Processors are responding by installing steam-in-place sterilization circuits that reduce chemical dependency. The F-Gas Regulation phase-down of hydrofluorocarbon refrigerants is most acutely affecting Dutch and Danish facilities with legacy cold storage infrastructure.
Ready-to-eat meal manufacturers are consolidating supplier lists to processors with dual organic and conventional certifications. Long-term volume contracts with fixed quarterly price adjustments are replacing spot market purchases for liquid egg. This consolidation pattern is most visible in the United Kingdom, where retail private-label ready meals specify single-source pasteurized egg inputs.
Europe Processed Egg Market Segmentation
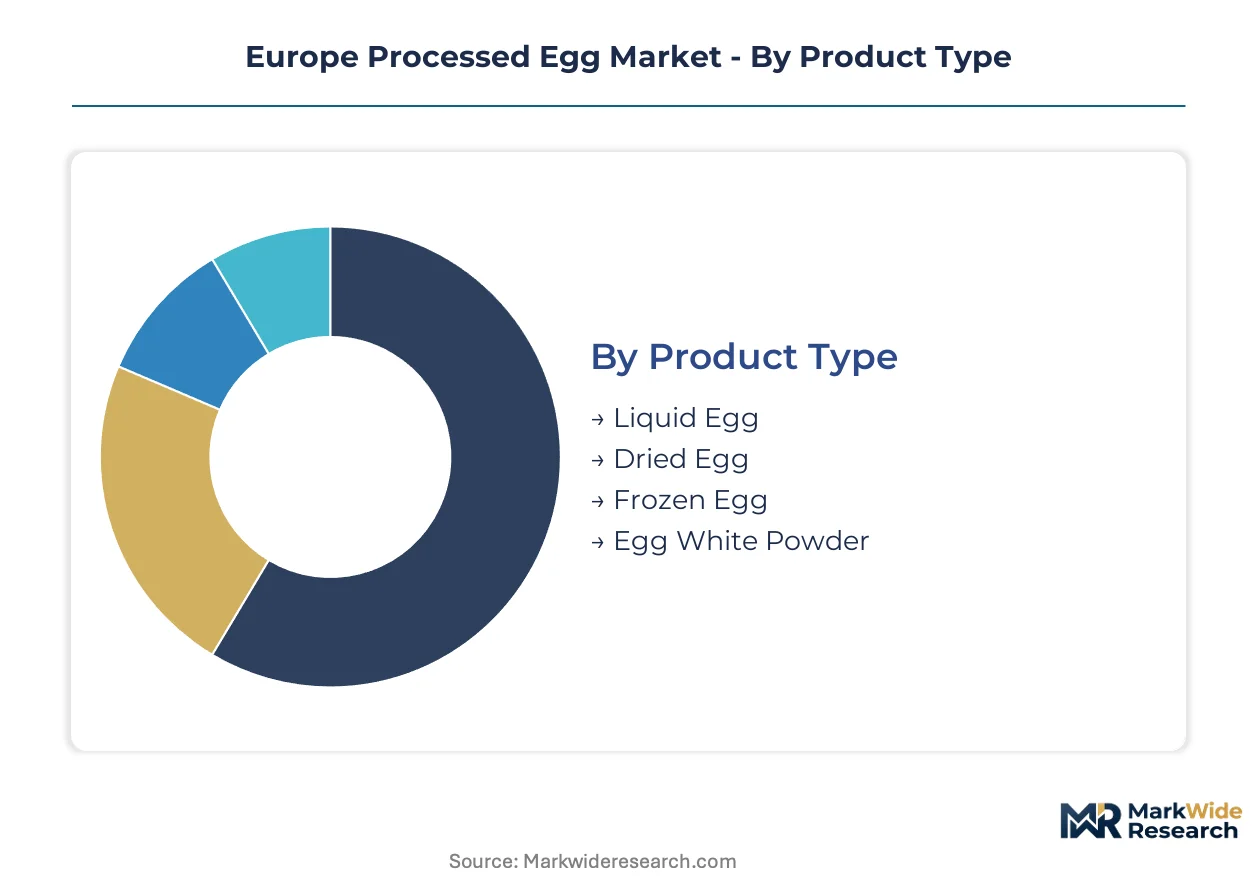
Processed egg markets fragment along functional performance lines. Industrial buyers select formats based on thermal stability, pumpability, and protein integrity requirements specific to their manufacturing processes.
Product Type:
Liquid egg spans high-volume industrial dosing through premium refrigerated distribution, while dried formats command premium positioning in ambient supply chains.
- Liquid Egg:Pumpable whole egg, yolk, or white suspensions pasteurized at precise temperature-time profiles to eliminate Salmonella while preserving foaming and emulsification properties. German and French bakery manufacturers favor liquid formats for automated dough and batter lines where shell egg handling creates throughput bottlenecks. REACH water discharge limits are pushing Dutch processors toward closed-loop pasteurization systems that reduce effluent volumes.
- Dried Egg:Spray-dried or pan-dried whole egg and yolk powders with moisture content below 5% for ambient storage stability. Central European confectionery producers in Poland and the Czech Republic source dried egg for long-haul distribution to secondary processing facilities where refrigeration infrastructure is limited. Transport economics favor dried formats for shipments exceeding 500 kilometers from breaking plants.
- Frozen Egg:Blast-frozen liquid egg at minus 18 degrees Celsius for extended shelf stability without dehydration-induced protein denaturation. Food service distributors in the United Kingdom and Ireland maintain frozen inventories for catering contracts with variable demand patterns.
- Egg White Powder:Isolated ovalbumin concentrates with gelation and whipping functionality preserved through controlled thermal processing. Sports nutrition formulators in the Netherlands and Germany are incorporating egg white powder into ready-to-mix protein shakes as whey price volatility redirects sourcing strategies.
Established volume favors liquid egg; emerging adoption favors egg white powder.
Application:
Functional protein requirements vary sharply across end-use categories, with thermal tolerance and emulsification indices determining format selection.
- Baking:Liquid whole egg and yolk provide structure, moisture retention, and Maillard browning in industrial bread, pastry, and cake production. French and German industrial bakeries specify liquid egg with defined solids content for automated depositor compatibility.
- Sauces:Pasteurized liquid yolk delivers emulsification stability in mayonnaise and hollandaise manufacturing where fat-liquid binding is critical. Dutch sauce processors source yolk with specified lecithin content for consistent viscosity control.
- Ready-to-Eat Meals:Pre-cooked scrambled egg and omelet components require pasteurized liquid egg with minimal syneresis during microwave reheating. United Kingdom retail private-label manufacturers consolidate supplier lists to single-source pasteurized inputs meeting EFSA Listeria criteria.
- Confectionery:Dried egg white and albumen powders supply whipping agents for meringue, nougat, and marshmallow applications where foam stability determines product texture. Italian and Spanish confectioners specify spray-dried albumen with defined whipping volume indices.
Baking commands the largest volume share; ready-to-eat meals are climbing the fastest as chilled prepared food penetration deepens.
End User:
Procurement scale and specification stringency separate industrial buyers from food service and retail channels.
- Food Service:Restaurants, hotels, and institutional caterers purchasing liquid egg in bag-in-box or portion-controlled formats for kitchen efficiency. EFSA hygiene audits drive consolidation toward processors with HACCP certification and batch traceability systems.
- Retail:Supermarket chains and specialty grocers stocking branded liquid egg, egg white cartons, and frozen breakfast items for consumer households. German and Austrian retailers are expanding private-label liquid egg ranges in refrigerated dairy adjacent sets.
- Industrial:Large-scale food manufacturers integrating liquid or dried egg into formulated products such as pasta, noodles, and processed meats. Polish pasta producers are scaling liquid egg purchases for premium fresh pasta lines targeting export markets.
- Bakery Manufacturers:Dedicated industrial bakeries with automated production lines specifying liquid egg with defined viscosity and solids parameters for depositor and mixer compatibility. Benelux bakery chains source through Rotterdam-Antwerp corridor processors for just-in-time delivery schedules.
Industrial buyers dominate tonnage flows; bakery manufacturers are gaining share fastest as automated production expands.
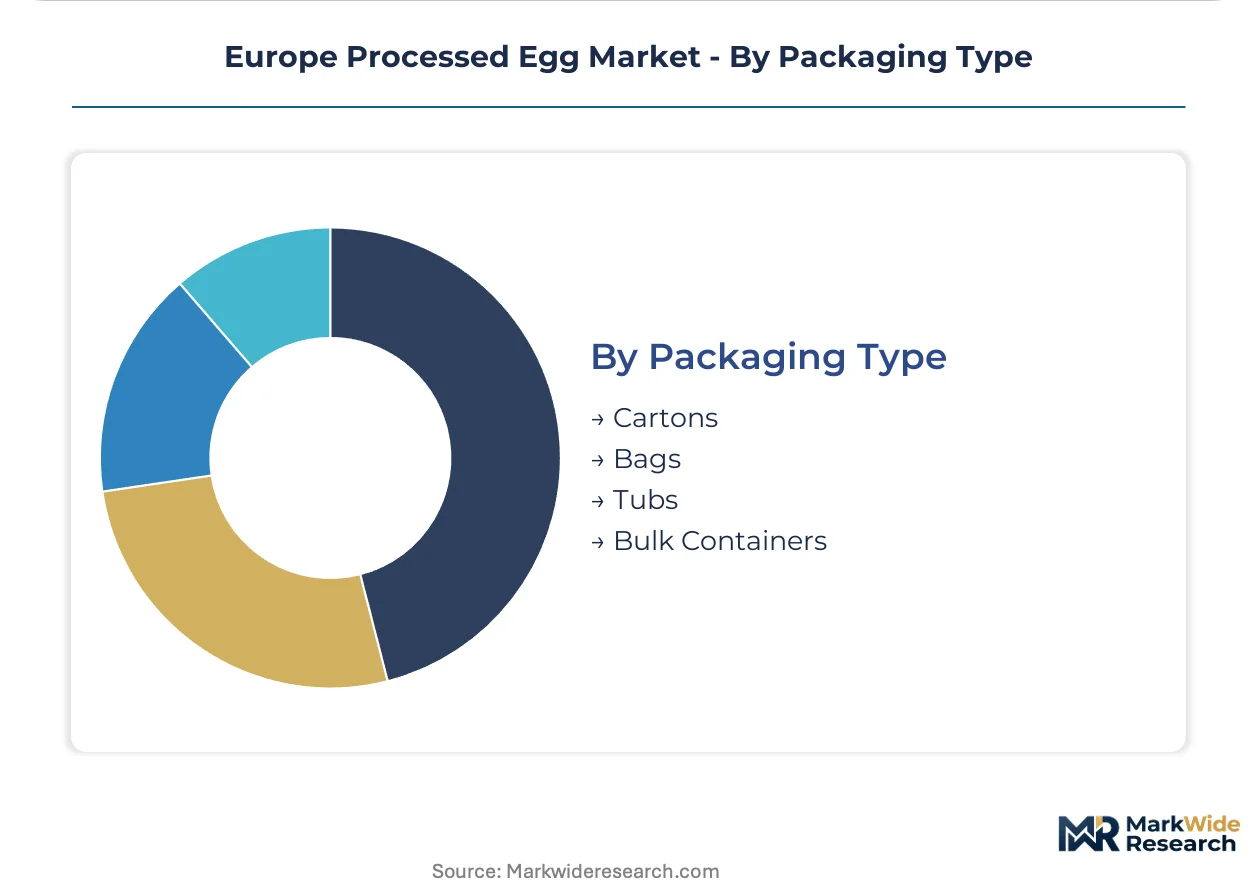
Packaging Type:
Packaging selection balances shelf stability, handling efficiency, and regulatory compliance across distribution distances.
- Cartons:Refrigerated liquid egg in gable-top or rectangular cartons for retail and small-scale food service distribution. French retailers favor cartons with tamper-evident closures and EFSA-compliant labeling for consumer transparency.
- Bags:Flexible pillow or stand-up pouches for liquid and frozen egg in food service and industrial bulk applications. Dutch processors are transitioning to recyclable mono-material bags to meet EU Green Deal packaging targets.
- Tubs:Rigid plastic containers for liquid egg white, scrambled egg mixes, and frozen egg products in retail and catering channels. United Kingdom food service distributors specify tamper-evident tubs with integrated pour spouts for kitchen efficiency.
- Bulk Containers:Intermediate bulk containers and tanker deliveries for industrial users with dedicated receiving infrastructure and high-throughput processing lines. German industrial bakeries with automated receiving systems source liquid egg in 1000-liter totes for direct pump transfer to holding tanks.
Bulk containers anchor industrial procurement; bags are expanding most quickly as sustainability mandates reshape packaging specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands exports liquid egg volumes through the Rotterdam-Antwerp corridor to German and French industrial bakeries. Poland ships dried egg powders to Central European confectionery markets. France supplies pasteurized yolk to Benelux sauce manufacturers.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia scale liquid egg purchases for automated dough lines. EFSA cage-free mandates force processors to retrofit breaking equipment for welfare compliance. The Frankfurt-Rhine-Main cluster hosts specialized pasteurization facilities serving premium bakery chains.
France
Confectionery producers in Île-de-France demand dried egg white with defined whipping indices for meringue applications. The EU Green Deal subsidizes energy recovery systems in breaking plants. The Brittany agricultural belt supplies shell eggs to Normandy processing facilities converting volume to liquid and dried formats.
Netherlands
Rotterdam-Antwerp corridor processors concentrate liquid egg supply for Benelux bakery chains with just-in-time delivery requirements. REACH water discharge limits push facilities toward closed-loop pasteurization. Gelderland and North Brabant host automated breaking halls with optical grading systems.
Poland
Central European bakery chains source Polish liquid egg for cost-advantaged production versus Western European supply. Lower labor and energy costs attract greenfield pasteurization investments. The Greater Poland and Lower Silesia regions consolidate shell-to-liquid processing capacity for export markets.
United Kingdom
Retail private-label ready-meal manufacturers consolidate supplier lists to single-source pasteurized egg inputs. EFSA Listeria criteria drive HACCP certification requirements across receiving facilities. The Midlands food manufacturing belt demands pre-cooked scrambled egg components with minimal syneresis.
Europe Processed Egg Market Vendor Landscape
On the supply side, the industry is consolidating around automated processing specialists with integrated breaking and pasteurization capabilities. Mid-scale operators face margin compression from feed cost volatility and regulatory compliance burdens. Three archetypes dominate: Dutch-Belgian corridor processors with liquid egg volume leadership, Italian-Spanish dried egg specialists, and equipment-technology hybrid providers. Competitive moves center on backward integration into shell egg supply and geographic expansion into Polish and Czech markets.
Among Dutch-based processors, Interovo Egg Group B.V. and Sanovo Technology Group exemplify the integrated model combining volume production with equipment know-how. Eurovo represents the southern European dried egg specialization serving confectionery applications. These three anchors sit within distinct competitive vectors: liquid supply chain control, technology licensing leverage, and ambient-stable product differentiation.
| Leading Market Players |
|---|
| Interovo Egg Group B.V. |
| Derovo Group |
| Sanovo Technology Group |
| Avril Group |
| Pulviver |
| Eurovo |
| IGRECA |
| EPS S.P.A. |
| Rembrandt Enterprises |
| Others |
Supply Flow & Price Mechanics
Feed cost volatility originating in Ukrainian and Argentine grain markets determines both pricing tier spreads and supply chain shape across European processed egg markets. Soybean and corn price swings transmit directly to shell egg input costs, compressing processor margins and forcing tiered pricing structures that separate organic-certified premium supply from conventional volume grades.
Pricing Analysis
Automation-generation pricing gaps separate high-speed centrifugal breaking systems from legacy mechanical equipment. Three-tier pricing structure across premium, standard, and economy levels stratifies by EFSA cage-free certification status and organic feed verification. Pricing pressure stems from feed cost volatility compressing margins at the conventional tier. Industrial bakery manufacturers in Germany and France demonstrate lowest price sensitivity due to formulation lock-in requirements, while Central European food service distributors show highest elasticity.
Supply Chain Analysis
Extended payment terms from Dutch-Belgian corridor processors anchor supplier-financing relationships with Benelux bakery chains. Supply concentrates in the Netherlands, Poland, and France for shell-to-liquid processing capacity. Raw material dependencies center on Ukrainian and Argentine feed grains, Dutch breeding stock, and specialized sanitizing chemicals governed by REACH. Single-source vulnerability runs through Rotterdam-Antwerp corridor facilities for liquid egg distribution. Distribution runs through refrigerated tanker networks for industrial bulk, with bag-in-box and cartons serving food service and retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe processed egg market sits in a feed cost-driven cyclical recovery, with soybean and corn price normalization enabling margin restoration for automated processors.
For Market Incumbents: Insulate margin structures by deepening backward integration into shell egg supply in Poland and the Czech Republic. EFSA cage-free mandate compliance deadlines threaten stranded assets for processors with pre-2015 breaking equipment. Prioritize closed-loop pasteurization system upgrades to capture EU Green Deal energy recovery subsidies and reduce REACH water discharge exposure. For New Entrants and Emerging Players: Polish liquid egg processing capacity expansion offers the most penetrable white-space target, with lower labor and energy costs relative to Western European supply. Central European bakery chains sourcing for export markets present undercontracted demand. Sports nutrition egg white powder applications in the Netherlands and Germany provide a second entry vector. Pursue toll-processing arrangements with existing shell egg suppliers to minimize capital intensity. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors equipment-technology hybrid providers with integrated breaking and pasteurization capabilities. Long-term viability hinges on automation scale and regulatory compliance infrastructure over a five-to-ten year horizon. Target acquisition archetypes include mid-scale Polish processors with greenfield pasteurization assets and dual organic-conventional certification capabilities. Monitor EFSA AI Act implementation timelines for automated inspection systems as an inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Shell Egg Supply | Captures margin pool from feed cost volatility and secures EFSA cage-free compliant volume. |
| Closed-Loop Pasteurization System Deployment | Reduces REACH water discharge exposure and qualifies for EU Green Deal capital subsidies. |
| Egg White Powder Capacity Expansion | Addresses sports nutrition demand in the Netherlands and Germany as whey prices fluctuate. |
| Automated Optical Grading Implementation | Accelerates EU AI Act compliance and reduces manual labor dependence in breaking halls. |
| Polish Greenfield Processing Investment | Exploits labor and energy cost advantages to serve Central European bakery export markets. |
Methodological Framework
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this study. Plant managers at Dutch and Polish breaking facilities, procurement leads at German industrial bakeries, distribution channel partners in the Benelux corridor, and EFSA regulatory affairs specialists contributed operational perspectives. Secondary sources include EFSA guidance documents, REACH chemical registration databases, EU Green Deal implementation reports, and customs trade data for shell egg and processed egg product flows. Bottom-up volume modeling triangulates against top-down market sizing from processor capacity disclosures.
Calibration against historical volume trajectories and documented capacity expansion timelines validates the projection framework. Segmentation dimensions span product type, application, end user, packaging format, and regional production hub. CAGRs derive from slope analysis across the modeling period, with cross-checks against feed cost elasticity and automation adoption curves. Industry-specific inputs include EFSA cage-free mandate compliance schedules and EU AI Act implementation timelines for automated inspection systems.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Polish greenfield entrants or accelerated EFSA regulatory tightening would shift outcomes. Macroeconomic feed grain price spikes, REACH chemical restriction revisions, or technological breakthroughs in alternative protein emulsification would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Broth Market
Processed Foods
Instant Curry Market
Processed Foods
Fruit Processing Market
Processed Foods
Fermented Food and Drinks Market
Processed Foods
Ready to Serve Prefabricated Dishes Market
Processed Foods
Margarine Market
Processed Foods
Middle East and Africa Processed Meat Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
United States Food Spread Market
Processed Foods
Global Dried Processed Food Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
Porridge Market
Processed Foods
North America Ice Cream Market
Processed Foods
India Spray Dried Food Market
Processed Foods
Fermented Foods Market
Processed Foods
United States Processed Meat Market