
 Europe Oilfield Chemicals Market | 2026-2036
Europe Oilfield Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Oilfield Chemicals Market Foresight
Exploration companies are collapsing their historical reliance on generic service provider bundles and instead building direct chemical specification capabilities. BASF SE leverages its Ludwigshafen integrated production complex to supply corrosion inhibitors with tight batch consistency for North Sea operators. Nouryon anchors its position through seawater-compatible biocide chemistry tailored to Norwegian offshore platforms. Schlumberger Limited competes by embedding chemical packages within integrated drilling contracts, reducing procurement friction for capital-constrained exploration firms.
Europe oilfield chemicals comprise formulated specialty additives—typically comprising surfactant blends, nitrogen-based corrosion inhibitors, or quaternary ammonium biocides—designed to manage fluid behavior, prevent equipment degradation, and maintain flow assurance in hydrocarbon extraction operations. These formulations function at dosage rates measured in parts per million to modify interfacial tension, inhibit electrochemical reactions, or control microbial proliferation across drilling, production, and completion phases. Corrosion inhibitors and demulsifiers together command the dominant share of product-type revenue, reflecting the region's aging offshore infrastructure and high water-cut mature fields. Drilling and production applications absorb the majority of volume, though completion chemical demand is expanding fastest as operators re-fracture tight gas reservoirs in the Netherlands and Poland.
REACH registration requirements enforced by ECHA mandate full toxicological dossiers for chemical substances imported or manufactured above one tonne annually, directly shaping formulation choices and supplier qualification timelines across the continent. The EU Green Deal and F-Gas Regulation progressively restrict fluorinated surfactant chemistries, forcing reformulation investments that favor suppliers with dedicated European R&D infrastructure. Stakeholders must monitor regulatory divergence between EU member states and the UK post-REACH regime, as divergent substance approval timelines could fragment supply chain compliance costs and alter competitive positioning for cross-border chemical distributors.
Market Dynamics
The EU Green Deal and REACH registration timelines are compressing formulation cycles across European oilfield chemical suppliers, forcing accelerated R&D investment in biodegradable alternatives while tightening supplier qualification windows for North Sea operators.
Growth Catalysts
- REACH compliance mandates:ECHA registration requirements above one tonne annually drive demand for pre-registered chemical portfolios, advantaging suppliers with established toxicological dossiers.
- Brownfield redevelopment:Norwegian offshore platforms require specialized corrosion inhibitor packages as mature fields exhibit accelerating water-cut ratios and electrochemical degradation.
- Biodegradable demulsifier chemistry:Surfactant formulations derived from renewable feedstocks gain traction as operators preempt F-Gas Regulation restrictions on fluorinated compounds.
Market Restraints
- Ethylene oxide supply volatility:Key surfactant precursor prices fluctuate with European petrochemical cracker operating rates, compressing formulation margins.
- Supplier concentration in Germany:Integrated production complexes along the Rhine corridor control critical corrosion inhibitor intermediate supply, creating geographic vulnerability.
- Technical substitution limits:Seawater-compatible biocide alternatives to glutaraldehyde demonstrate reduced efficacy against sulfate-reducing bacteria in high-pressure reservoirs.
Strategic Opportunities
- Polish tight gas re-fracturing:Completion chemical demand expands as operators stimulate unconventional reservoirs with high-performance friction reducer packages.
- UK post-REACH divergence:Divergent substance approval timelines between HSE and ECHA create arbitrage potential for cross-border chemical distributors with dual registration capabilities.
- Digital chemical monitoring:IoT-enabled dosage optimization systems converge with predictive maintenance platforms, enabling performance-based supply contracts.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in surfactant-biocide synergy and reservoir-specific compatibility testing remains concentrated among retiring technical specialists.
- REACH dossier compilation timelines:Extended toxicological study requirements delay new product commercialization, compressing effective patent windows.
- Legacy platform integration:Automated chemical injection systems face retrofit complexity with decades-old North Sea infrastructure lacking digital instrumentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Oilfield Chemicals Market |
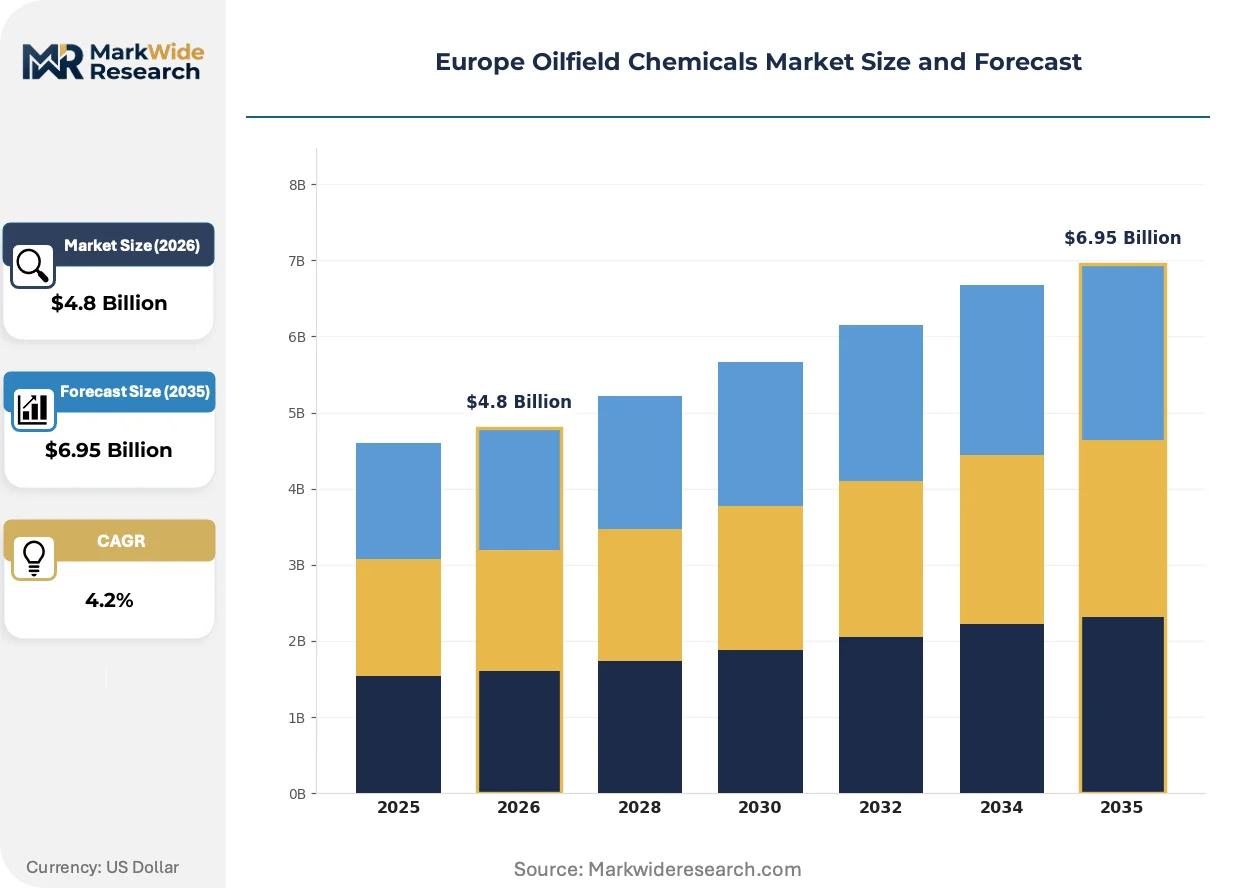
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrosion Inhibitors, Demulsifiers, Surfactants, Biocides Application: Drilling, Production, Completion, Workover End User: Exploration Companies, Service Providers, Oil Producers, Refineries Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | BASF SE, Solvay, Clariant AG, Schlumberger Limited, Halliburton Company, Baker Hughes Company, AkzoNobel N.V., Nouryon, Evonik Industries AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Oilfield Chemicals Market Shifts & Advancements
Formulation science is pivoting toward bio-based molecular architectures as regulatory chemistry restrictions harden, while procurement architectures fragment traditional service bundling. Three developments command attention.
Polymeric scale inhibitor chemistry is fragmenting conventional phosphonate dominance in high-temperature reservoir applications. Operators in the Norwegian North Sea adopt maleic acid copolymer alternatives at accelerating rates, drawn by thermal stability above 150°C and reduced environmental persistence. This molecular shift is fragmenting incumbent supplier relationships as specialty polymer houses capture specification authority from integrated oilfield service firms.
F-Gas Regulation phase-down schedules are eliminating per- and polyfluoroalkyl surfactants from demulsifier formulations by 2030. European chemical manufacturers reformulate with bio-based alkyl polyglucosides and modified fatty acid esters, accepting performance trade-offs in heavy crude separation. Norwegian offshore platforms face the steepest adaptation curve due to waxy crude characteristics and stringent discharge permits.
Direct chemical specification by exploration companies is displacing bundled service procurement. Capital-constrained operators in the UK North Sea unbundle chemical selection from drilling contracts, building in-house technical teams to negotiate directly with BASF, Nouryon, and specialty distributors. This behavioral shift concentrates most visibly among mid-cap independents seeking 15-20% cost reduction on chemical spend.
Europe Oilfield Chemicals Market Segmentation
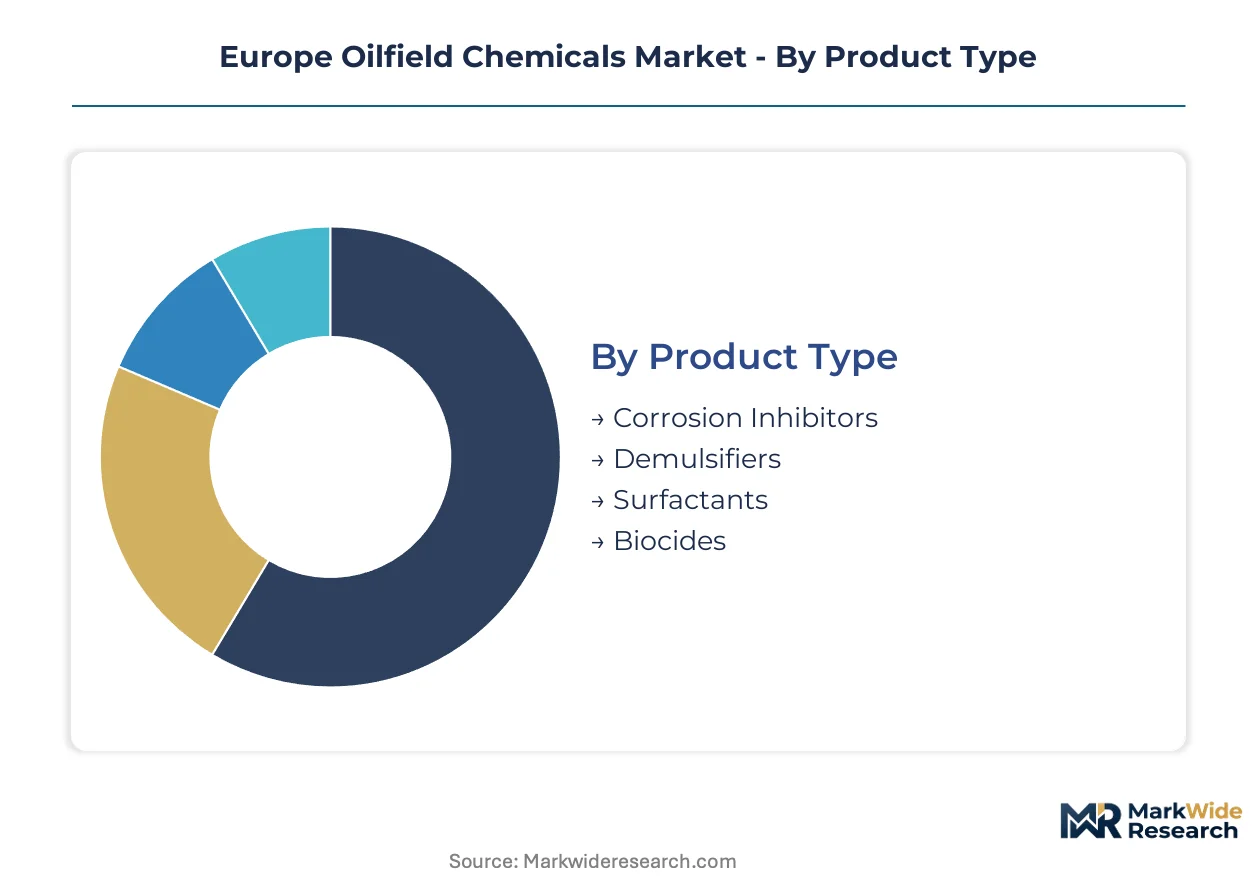
Europe Oilfield Chemicals Market segmentation reveals how REACH dossier requirements and F-Gas Regulation timelines reshape procurement patterns across distinct chemical categories. Product specifications diverge sharply between offshore platforms requiring seawater-compatible biocides and onshore tight gas operations demanding high-temperature scale inhibitors.
Product Type:
ECHA registration thresholds above one tonne annually fragment competitive positioning between pre-registered legacy portfolios and novel biodegradable formulations seeking market entry.
- Corrosion Inhibitors:Nitrogen-based formulations dominate mature North Sea applications where water-cut ratios accelerate electrochemical degradation. Norwegian offshore platforms drive specialized demand for film-forming amine chemistry compatible with high-pressure CO2 environments.
- Demulsifiers:Surfactant blends derived from renewable alkyl polyglucosides gain specification authority as operators preempt F-Gas Regulation phase-down of fluorinated compounds. Waxy crude characteristics in Norwegian fields impose performance trade-offs requiring tailored fatty acid ester architectures.
- Surfactants:Ethylene oxide-derived precursors face margin pressure from European cracker operating rate volatility.
- Biocides:Glutaraldehyde alternatives struggle against sulfate-reducing bacteria in high-pressure reservoirs, constraining substitution timelines.
Corrosion inhibitors handle the majority of throughput; demulsifiers are gaining share fastest as regulatory chemistry restrictions harden.
Application:
Cost tier differentiation separates capital-intensive offshore brownfield redevelopment from price-sensitive onshore tight gas stimulation campaigns.
- Drilling:Formulated fluid systems integrate lubricants, shale inhibitors, and weighting agents at dosage rates measured in parts per million. North Sea operators prioritize synthetic-based mud chemistry for high-pressure high-temperature wells.
- Production:Flow assurance chemicals dominate mature field economics where scale, corrosion, and wax deposition threaten output. Norwegian platforms absorb the highest per-barrel chemical intensity in the region.
- Completion:Friction reducers and breakers expand most quickly as Polish and Dutch operators re-fracture unconventional reservoirs.
- Workover:Remedial treatments concentrate in UK North Sea assets requiring wellbore intervention to restore declining production rates.
Production applications command the largest volume position; completion chemicals climb the fastest as tight gas development accelerates.
End User:
Procurement architecture fragmentation distinguishes integrated majors with direct specification capabilities from service-dependent independents.
- Exploration Companies:Mid-cap UK and Norwegian independents unbundle chemical selection from drilling contracts, building in-house technical teams to negotiate directly with specialty suppliers and capture 15-20% cost reductions.
- Service Providers:Integrated oilfield service firms embed chemical packages within bundled drilling and completion contracts, reducing procurement friction for capital-constrained operators.
- Oil Producers:National oil companies and majors leverage volume scale to enforce performance-based supply contracts with IoT-enabled dosage optimization.
- Refineries:Downstream chemical demand concentrates in corrosion protection for crude unit overhead systems and desalter operations.
Exploration companies drive the fastest procurement transformation; oil producers maintain the largest absolute chemical throughput.
Distribution Channel:
Supply concentration along the Rhine corridor shapes geographic vulnerability in channel selection for time-critical offshore logistics.
- Direct Sales:BASF SE and Nouryon leverage integrated production complexes to supply corrosion inhibitors with tight batch consistency for North Sea operators requiring just-in-time offshore delivery.
- Distributors:Specialty chemical distributors capture specification authority for mid-tier independents lacking technical procurement infrastructure, particularly in UK post-REACH divergence arbitrage.
- Online Sales:Digital platforms penetrate standard commodity biocides and scale inhibitors for onshore Polish tight gas operators with predictable demand profiles.
- Retail:Limited to consumable additives and small-volume remedial treatments for marginal well operators.
Direct sales channels manage the highest-value formulations; distributors show the steepest expansion trajectory as procurement unbundling proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp petrochemical corridor anchors European oilfield chemical distribution, with pipeline networks feeding North Sea offshore logistics hubs and Rhine barge terminals supplying onshore stimulation campaigns.
Norway
Statoil-operated Johan Sverdrup and legacy Ekofisk platforms drive specialized corrosion inhibitor demand as water-cut ratios exceed sixty percent in mature reservoirs. Petroleum Safety Authority Norway enforces stringent chemical discharge permits under the Pollution Control Act, accelerating biodegradable demulsifier qualification timelines. Bergen and Stavanger host technical service clusters where operators co-develop seawater-compatible biocide formulations with specialty chemical suppliers.
United Kingdom
Decades-old Brent and Forties infrastructure requires escalating workover chemical intensity to combat scale deposition and pipeline corrosion. The Health and Safety Executive operates a parallel post-REACH substance approval regime, creating regulatory arbitrage complexity for cross-border distributors. Aberdeen maintains Europe's densest concentration of oilfield chemical technical specialists, though expertise scarcity intensifies as veteran formulation chemists retire.
Germany
Ludwigshafen's integrated chemical complexes supply nitrogen-based corrosion inhibitor intermediates with batch consistency critical for North Sea operator specifications. ECHA headquarters in Helsinki shapes continental registration timelines, while German environmental regulators enforce stricter local discharge standards than EU minimums. The Rhine corridor concentration creates geographic supply vulnerability for time-critical offshore deliveries.
Netherlands
Groningen tight gas field depletion and subsequent seismic-induced production caps redirect chemical demand toward smaller onshore remediation projects. Port of Rotterdam storage terminals handle bulk surfactant precursor imports from Middle Eastern and Asian sources. Amsterdam-based distributors capture specification authority for mid-tier independents lacking direct supplier relationships.
Poland
Unconventional tight gas reservoirs in the Lublin and Podlasie basins expand completion chemical consumption for re-fracturing campaigns targeting Carboniferous sandstone formations. Polish environmental inspectors apply EU groundwater protection directives with particular rigor near agricultural zones, constraining biocide selection for onshore operations. Wrocław and Kraków emerging as logistics consolidation points for eastern European chemical distribution.
Europe Oilfield Chemicals Market Competitive Landscape
Concentration sits with integrated petrochemical conglomerates controlling corrosion inhibitor intermediate supply. Three archetypes define competitive positioning: Rhine-based integrated producers with captive raw material access; offshore-specialized service companies embedding chemicals within bundled contracts; and nimble distributors exploiting regulatory arbitrage between EU and UK approval regimes. Capacity rationalization and direct procurement bypass represent the dominant competitive vectors as exploration companies unbundle chemical selection from drilling packages.
Among integrated chemical producers, BASF SE anchors the archetype with Ludwigshafen manufacturing scale, while Nouryon occupies a parallel position in seawater-compatible specialty formulations. Schlumberger Limited exemplifies the service-embedded model, competing through procurement friction reduction rather than standalone chemical specification. These three entities represent distinct strategic postures without implying specific market share or operational claims.
| Leading Market Players |
|---|
| BASF SE |
| Solvay |
| Clariant AG |
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| AkzoNobel N.V. |
| Nouryon |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
REACH dossier requirements enforced by ECHA gate both supplier qualification timelines and price differentiation tiers simultaneously, compressing margins for non-registered portfolios while rewarding pre-registered legacy formulations with specification premiums. Buyers face bifurcated sourcing economics between compliant premium tiers and stranded non-compliant inventory.
Pricing Analysis
Volume-discount tiering separates integrated majors negotiating long-term offtake agreements from spot-market independents purchasing standard biocide formulations. Price differentiation rests on REACH registration status and batch consistency certification for North Sea offshore delivery. Pricing pressure intensifies in surfactant-derived categories as ethylene oxide feedstock volatility feeds through formulation costs. Mid-cap exploration companies exhibit highest price sensitivity, while Norwegian national operators absorb premiums for seawater-compatible specialty chemistry.
Supply Chain Analysis
Germany and the Netherlands anchor corrosion inhibitor intermediate production through Ludwigshafen integrated complexes and Rotterdam-Antwerp petrochemical corridors. Raw material dependencies center on ethylene oxide derivatives, nitrogen-based amine precursors, and renewable alkyl polyglucoside feedstocks. Single-source vulnerability concentrates in Rhine corridor production hubs exposed to barge logistics disruptions. Distribution runs through direct sales channels for high-value offshore formulations and specialty distributors for mid-tier onshore procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
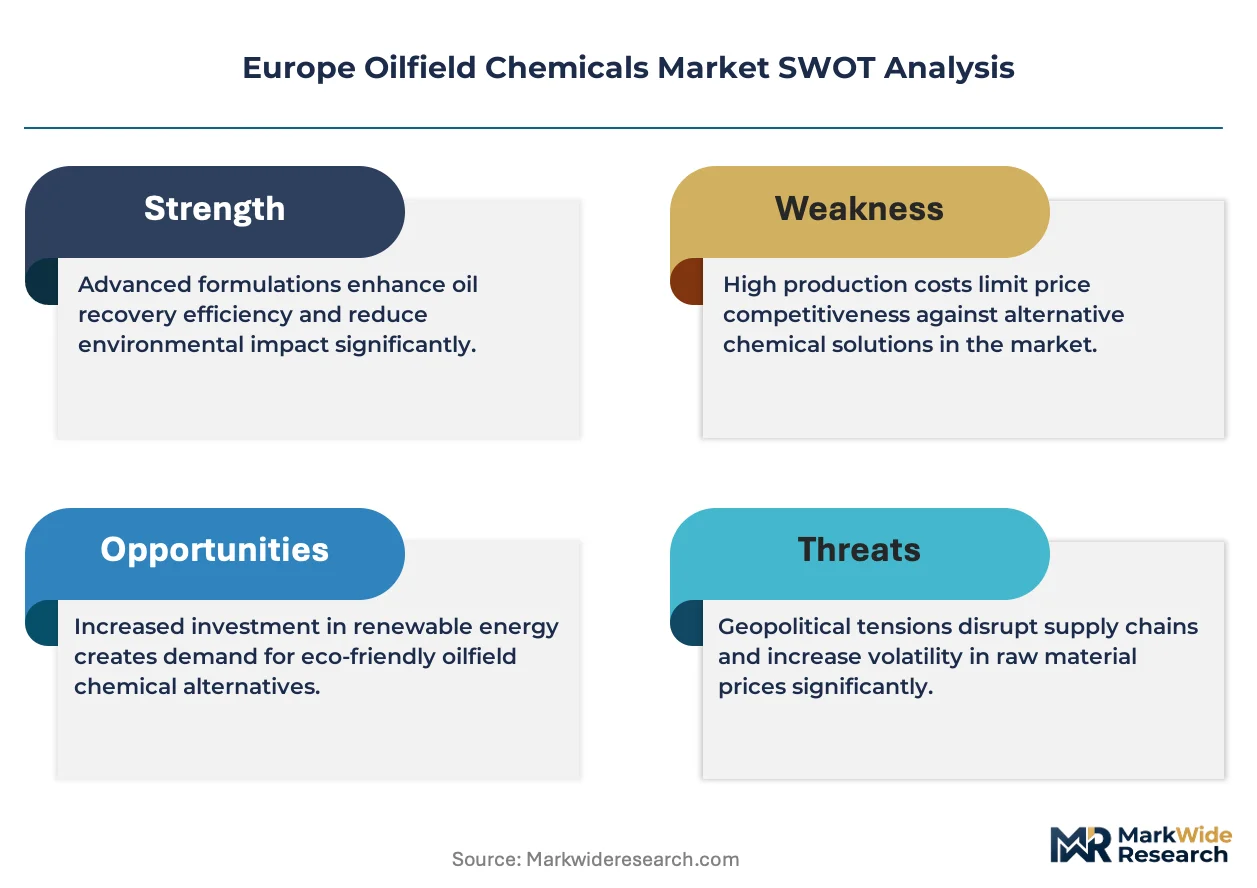
This market sits in early-cycle expansion as brownfield redevelopment accelerates chemical intensity per barrel across mature North Sea reservoirs. Biodegradable formulation mandates under F-Gas Regulation timelines create sustained specification upgrade demand.
For Market Incumbents: Secure backward integration into ethylene oxide derivative supply to defend margin position against feedstock volatility. Anchor certification investment in ECHA REACH dossier extensions for novel biodegradable demulsifier architectures before competitor qualification windows open. For New Entrants and Emerging Players: Direct chemical specification services for UK mid-cap independents unbundling from bundled drilling contracts offer immediate white-space penetration. Target Polish tight gas completion chemical demand with friction reducer formulations optimized for Carboniferous sandstone re-fracturing campaigns. For Investors and Strategic Acquirers: F-Gas Regulation phase-down schedules reshape the acquisition landscape toward biodegradable formulation specialists with active ECHA registration pipelines. Long-term viability favors targets with dual EU-UK post-REACH registration capabilities. Monitor ECHA substance approval velocity as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide Derivatives | Captive supply of surfactant precursors insulates BASF and Nouryon from Rhine corridor cracker volatility. |
| ECHA REACH Dossier Extension Investment | Pre-registered toxicological portfolios accelerate biodegradable demulsifier commercialization timelines for Norwegian operators. |
| Dual EU-UK Registration Capability Buildout | Cross-border distributors capture arbitrage value as HSE and ECHA approval timelines diverge post-Brexit. |
| Seawater-Compatible Biocide Formulation Partnership | Collaboration with Bergen technical service clusters addresses Petroleum Safety Authority discharge permit requirements. |
| Digital Chemical Monitoring Platform Deployment | IoT-enabled dosage optimization enables performance-based supply contracts with Statoil-operated platforms. |
Research Methodology
A spread of perspectives from plant managers at integrated chemical complexes, procurement leads at North Sea exploration companies, distribution channel partners, and technical R&D directors converged on the working assumptions. Primary interview insights combined with secondary validation from ECHA registration databases, Cefic industry reports, customs trade data, and SEC filings. Bottom-up volume modeling triangulated against top-down market sizing across corrosion inhibitor, demulsifier, and biocide product categories.
Segmentation dimensions modeled include product type tier, application phase, end-user procurement architecture, and distribution channel structure across the analysis window. CAGRs derived from trend extrapolation of brownfield redevelopment activity, regulatory chemistry substitution timelines, and tight gas stimulation campaign intensity. Forecast inputs incorporated water-cut ratio trajectories in mature Norwegian fields and F-Gas Regulation phase-down compliance deadlines.
Forecasts assume regulatory continuity in REACH and F-Gas Regulation enforcement; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Vacuum Gas Oil Market
Oil & Gas
United States Oil and Gas Market
Oil & Gas
Enclosed Flares Market
Oil & Gas
North America Artificial Lift Systems Market
Oil & Gas
Italy Oil and Gas Upstream Market
Oil & Gas
Asia-Pacific Small-Scale LNG Market
Oil & Gas
Iron Ore Mining Market
Oil & Gas
North America Oil and Gas Storage Tank Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
Global Oil and Chemical Spill Kits Market
Oil & Gas
Coiled Tubing Services Market
Oil & Gas
Angola Oil and Gas Upstream Market
Oil & Gas
Europe Intelligent Pigging Market
Oil & Gas
LNG Loading Skid Market
Oil & Gas
United States Oil and Gas Midstream Market
Oil & Gas
Oman Oil and Gas Upstream Market