
 North America Seismic Services Market | 2026-2036
North America Seismic Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Seismic Services Market Analytics
Market Dynamics
Upstream capital allocation is shifting toward offshore and unconventional reservoirs, reshaping procurement patterns across the seismic value chain. Schlumberger Ltd leverages its integrated geophysical platform to anchor deepwater survey contracts in the Gulf of Mexico. Halliburton Company competes through specialized hydraulic fracture monitoring services tied to Permian Basin operators. CGG SA differentiates via high-performance computing assets that compress seismic processing timelines for exploration teams.
Technology and Segment Structure
North America seismic services encompass the design, acquisition, processing, and interpretation of subsurface acoustic data using controlled-source energy and dense sensor arrays, typically resolving geological structures from surface to depths exceeding ten kilometers for hydrocarbon prospecting and geohazard assessment. 3D seismic technologies dominate contract value due to their established role in pre-drilling risk reduction across the Gulf of Mexico shelf and deepwater provinces. Data processing software represents the fastest-expanding margin pool as cloud-native architectures displace on-premise compute clusters. Geophones retain volume leadership in land programs, though vibrational sensor adoption accelerates in urban and environmentally restricted zones where reduced source intensity matters.
Regulatory Environment and Outlook
The US Bureau of Ocean Energy Management governs offshore permitting timelines, while EPA methane regulations and the SEC climate disclosure rules shape operator investment in reservoir monitoring infrastructure. Canada's Energy Regulator and Alberta Energy Regulator impose distinct seismicity thresholds for oil sands and tight oil development, fragmenting compliance requirements across the continental market. Stakeholders must weigh the divergence between US and Canadian regulatory timelines when positioning multi-jurisdictional service portfolios.
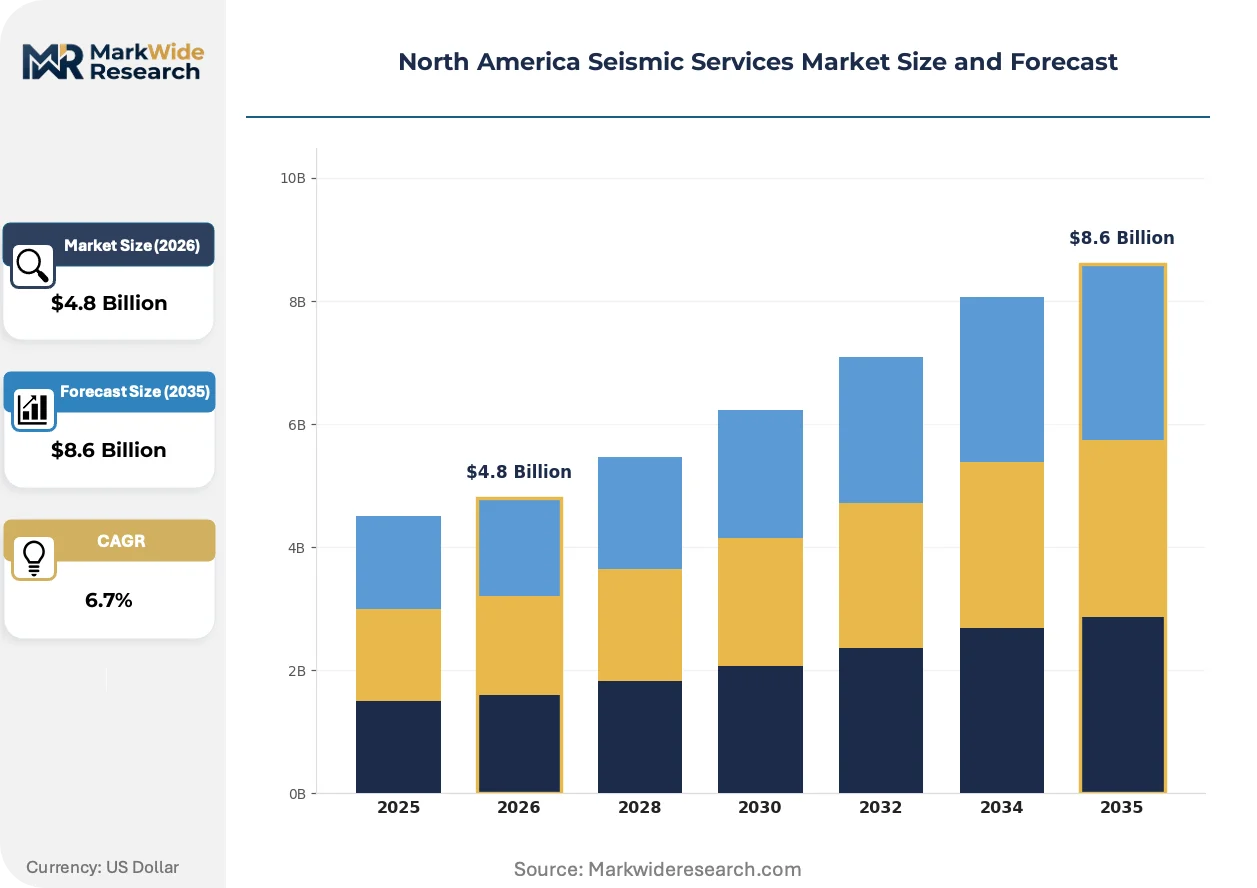
Market Dynamics
Upstream capital allocation is pivoting toward continuous reservoir surveillance as EPA methane regulations and SEC climate disclosure rules force operators to document subsurface fluid movements with greater precision. This regulatory compression is restructuring procurement priorities across the seismic value chain.
Growth Catalysts
- EPA Methane Rules:Continuous monitoring mandates are expanding contract scope for 4D time-lapse surveys in mature basins. Operators now require denser sensor arrays to detect fugitive emissions.
- Unconventional Development:Permian Basin operators are commissioning microseismic monitoring for every hydraulic fracture stage. Real-time fracture geometry data reduces completion inefficiencies.
- Cloud-Native Processing:Exploration teams are migrating seismic interpretation workflows to distributed compute architectures. Processing turnaround times compress from weeks to days.
Market Restraints
- Specialized Vessel Scarcity:Deepwater seismic acquisition depends on a concentrated fleet of ocean-bottom node deployment vessels. Newbuild delivery timelines extend beyond thirty-six months.
- Sensor Input Costs:MEMS accelerometer supply chains face allocation pressure from automotive and consumer electronics demand. Land array costs fluctuate with semiconductor foundry capacity.
- Permitting Friction:BOEM environmental review timelines for Gulf of Mexico surveys now average eighteen months. Regulatory uncertainty delays survey scheduling.
Strategic Opportunities
- Carbon Capture Site Characterization:Saline aquifer and depleted reservoir screening for sequestration projects requires high-resolution velocity modeling. This application segment is underpenetrated relative to hydrocarbon exploration.
- Alberta Oil Sands Monitoring:Steam-assisted gravity drainage operations need continuous caprock integrity surveillance. Thermal-induced microseismicity monitoring represents a service expansion vector.
- AI-Assisted Interpretation:Machine learning algorithms trained on legacy seismic libraries are converging with cloud compute to automate fault detection. This technology pairing reduces interpreter hours per square kilometer.
Industry Challenges
- Geophysicist Talent Pipeline:University geophysics enrollment has declined for eight consecutive years. Experienced velocity modelers and quantitative interpreters command premium compensation.
- Legacy Data Integration:Decades of proprietary seismic formats obstruct AI training dataset assembly. Data standardization across operator archives remains incomplete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Seismic Services Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Seismic Data Acquisition, Interpretation Services, Consulting, Monitoring Services End User: Oil & Gas, Mining, Construction, Environmental Technology: Vibrational Sensors, Geophones, 3D Seismic Technologies, Data Processing Software Application: Reservoir Characterization, Earthquake Studies, Civil Engineering, Hydrocarbon Exploration |
| Companies Covered | Schlumberger Ltd, Halliburton Company, CGG SA, Fugro NV, ION Geophysical Corporation, Baker Hughes, TGS, SAExploration Holdings Inc, Shearwater GeoServices Holding AS, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Seismic Services Market Evolving Landscape
Distributed acoustic sensing is rewiring how subsurface data is acquired and monetized. Fiber-optic cables are replacing discrete sensor arrays across multiple application verticals.
Interferometric synthetic aperture radar is absorbing capital allocation from traditional 4D marine surveys for surface deformation monitoring. CO2 storage operators in Texas and Alberta are deploying InSAR to track caprock uplift at a fraction of ocean-bottom node costs. The technology is absorbing market share from marine contractors in shallow-water carbon storage site screening.
EPA's Subpart W methane reporting requirements are mandating quarterly facility-level emissions verification. Permian Basin operators must now correlate surface methane detections with subsurface reservoir models. This regulation is forcing seismic contractors to integrate atmospheric monitoring data with traditional acoustic interpretation workflows.
Exploration procurement is consolidating under integrated service contracts that bundle acquisition, processing, and interpretation. Gulf of Mexico operators are abandoning discrete bid packages for single-vendor accountability. This bundling trend is most visible in deepwater pre-salt screening campaigns where timeline risk transfer outweighs cost optimization.
North America Seismic Services Market Segmentation
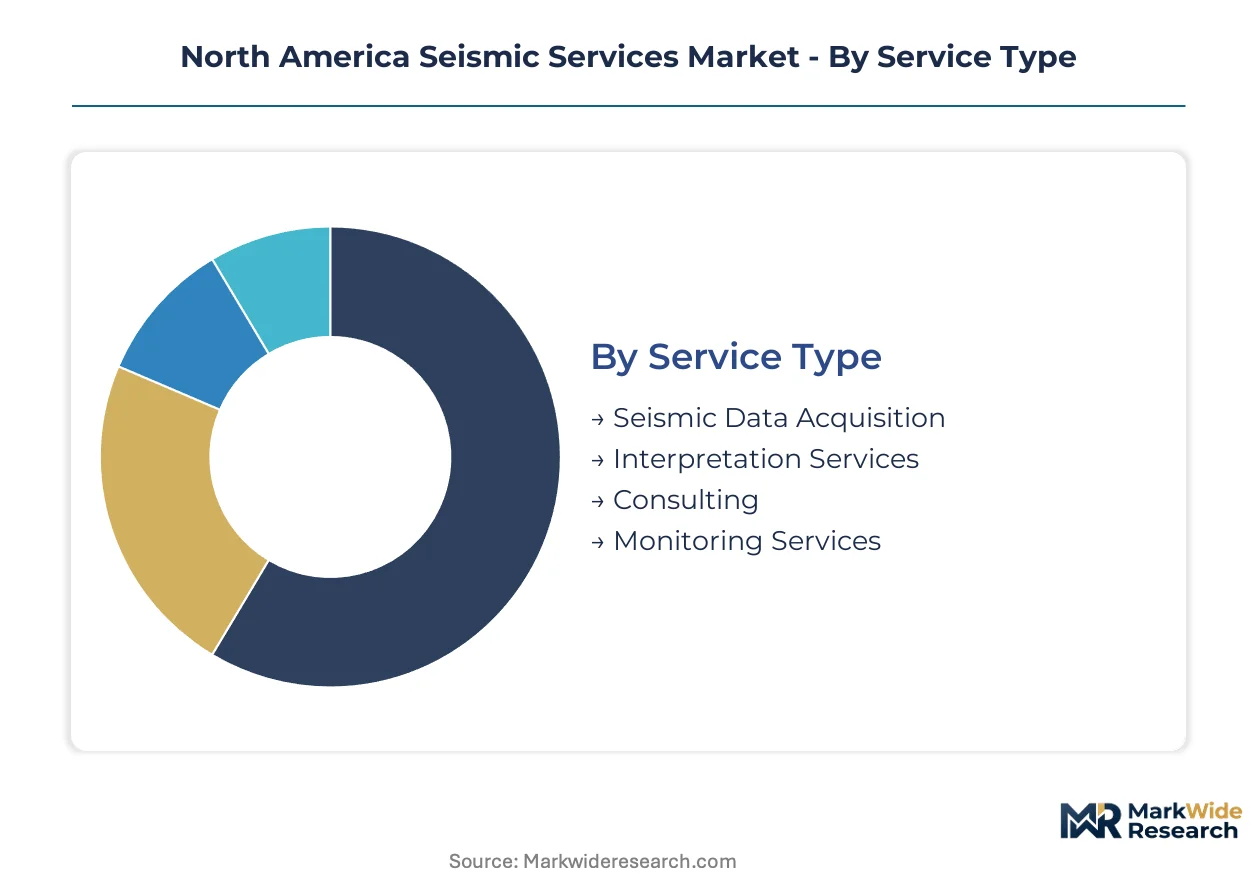
Seismic service procurement patterns diverge sharply between exploration-driven contracts and regulatory-mandated monitoring. Understanding segment boundaries reveals where technology premiums command pricing power versus where commoditization pressures margins.
Service Type:
Volume concentrates in field execution while premium margins pool in specialized interpretation and continuous monitoring.
- Seismic Data Acquisition:Field crews deploy controlled-source energy and dense sensor arrays to capture subsurface acoustic reflections. Gulf of Mexico deepwater campaigns and Permian Basin land programs drive contract concentration, though vessel scarcity and permitting delays constrain scheduling flexibility.
- Interpretation Services:Geophysicists transform raw seismic volumes into drillable prospects through velocity modeling and structural analysis. Cloud-native compute architectures are compressing project timelines, tightening the talent market for quantitative interpreters who command premium compensation.
- Consulting:Advisory engagements span survey design optimization and regulatory compliance strategy. Operators in Alberta and Texas retain consultants to navigate divergent seismicity thresholds.
- Monitoring Services:Continuous reservoir surveillance detects fluid movements and caprock integrity changes. EPA methane rules and SEC climate disclosure requirements are expanding contract scope for time-lapse monitoring in mature basins.
Today's leader: Seismic Data Acquisition. Tomorrow's challenger: Monitoring Services.
End User:
Application maturity varies dramatically across extractive industries versus emerging environmental compliance verticals.
- Oil & Gas:Hydrocarbon operators represent the established revenue base, with procurement spanning pre-drilling exploration through enhanced recovery. Unconventional development in Texas and the Permian Basin is embedding microseismic monitoring into every fracture stage.
- Mining:Hardrock and aggregate operations employ seismic methods for ore body delineation and blast optimization. Canadian mining jurisdictions are adopting seismic hazard assessment protocols for tailings dam stability.
- Construction:Urban development projects utilize shallow seismic surveys for geotechnical risk characterization. Vibrational sensor adoption accelerates in environmentally restricted zones where reduced source intensity matters.
- Environmental:Carbon capture site characterization and groundwater monitoring represent underpenetrated expansion vectors. Saline aquifer screening for sequestration projects requires high-resolution velocity modeling that traditional hydrocarbon workflows adapt readily.
Oil & Gas anchors current procurement volumes; Environmental applications are climbing the fastest as climate infrastructure spending accelerates.
Technology:
Hardware margins face semiconductor supply pressure while software and processing services capture expanding value pools.
- 3D Seismic Technologies:Multi-azimuth and wide-azimuth acquisition geometries dominate pre-drilling risk reduction across the Gulf of Mexico shelf and deepwater provinces. These established methods command premium pricing in complex subsalt imaging campaigns.
- Data Processing Software:Cloud-native architectures displace on-premise compute clusters, compressing turnaround from weeks to days. Machine learning algorithms trained on legacy seismic libraries are automating fault detection and reducing interpreter hours per square kilometer.
- Geophones:Electromechanical velocity sensors retain volume leadership in land seismic programs. MEMS accelerometer supply chains face allocation pressure from automotive and consumer electronics demand, creating input cost volatility.
- Vibrational Sensors:Solid-state MEMS devices enable denser array deployment with lower environmental footprint. Adoption accelerates in urban and restricted-access zones where reduced source intensity enables permit approval.
Geophones dominate unit volumes; Data Processing Software is gaining share fastest as exploration teams migrate workflows to distributed architectures.
Application:
Commercial maturity stratifies between hydrocarbon prospecting and emerging climate infrastructure monitoring.
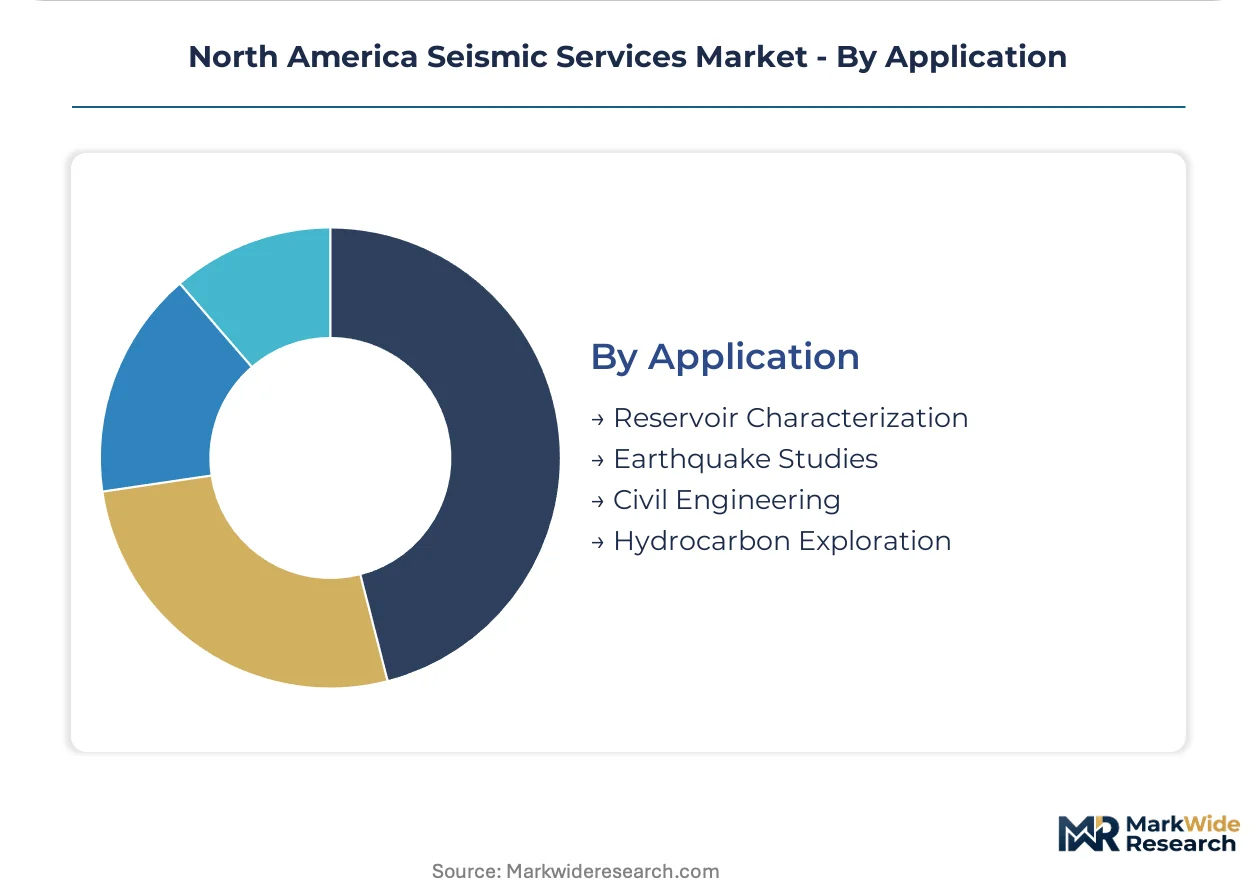
- Hydrocarbon Exploration:Traditional seismic prospecting for oil and gas reserves remains the revenue foundation. Operators in the US Gulf Coast and Permian Basin commission surveys across shelf, deepwater, and unconventional plays.
- Reservoir Characterization:Time-lapse seismic monitoring tracks fluid displacement during enhanced recovery operations. 4D surveys are expanding in mature basins as operators optimize production from existing assets.
- Civil Engineering:Transportation and infrastructure projects employ shallow seismic methods for tunnel route selection and foundation design. Urban tunneling in Texas and California cities drives demand for low-impact vibrational surveys.
- Earthquake Studies:Academic and government research programs deploy seismic networks for tectonic hazard assessment. The US Geological Survey and Canadian counterparts maintain permanent array infrastructure with periodic expansion contracts.
Hydrocarbon Exploration holds established position; Reservoir Characterization shows steepest expansion trajectory as continuous monitoring mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where operators commission seismic surveys, with compliance cost differentials between US and Canadian jurisdictions redirecting capital toward states with streamlined permitting frameworks.
United States
Deepwater exploration in the Gulf of Mexico and Permian Basin unconventional development drive contract concentration. The EPA's methane emissions rules and SEC climate disclosure requirements are expanding demand for continuous reservoir monitoring. Houston anchors the service provider ecosystem, with specialist firms clustering around the Energy Corridor to support offshore and onshore campaigns simultaneously.
Canada
Alberta's oil sands operations and British Columbia's tight gas plays sustain land seismic demand despite regulatory complexity. The Alberta Energy Regulator imposes distinct seismicity thresholds for steam-assisted gravity drainage projects that exceed US requirements. Calgary hosts the headquarters of several acquisition specialists serving both domestic operators and cross-border US clients.
Mexico
Offshore licensing rounds in the Gulf of Mexico are attracting international operators seeking access to underexplored deepwater blocks. The National Hydrocarbons Commission governs survey permitting timelines that remain longer than US equivalents but shorter than Brazilian counterparts. Ciudad del Carmen on the Campeche coast serves as the logistical hub for marine seismic campaigns targeting Mexican territorial waters.
North America Seismic Services Market Competitive Landscape
Integrated service bundling dominates the current landscape as Gulf of Mexico operators abandon discrete bid packages for single-vendor accountability. The vendor base stratifies across three tiers: integrated energy technology conglomerates with full-stack geophysical platforms, specialized marine and land acquisition contractors with concentrated vessel or crew assets, and boutique processing shops leveraging cloud-native architectures. Portfolio diversification and strategic partnerships represent the primary competitive vectors, with firms racing to add carbon capture site characterization capabilities before climate infrastructure spending peaks.
Within the integrated conglomerate tier, Schlumberger Ltd and Halliburton Company exemplify full-service positioning across acquisition, processing, and interpretation workflows. CGG SA occupies a specialized position anchored on high-performance computing assets and marine seismic expertise. These three firms collectively represent the competitive standard against which mid-tier specialists and emerging cloud-native processors benchmark their service offerings.
| Leading Market Players |
|---|
| Schlumberger Ltd |
| Halliburton Company |
| CGG SA |
| Fugro NV |
| ION Geophysical Corporation |
| Baker Hughes |
| TGS |
| SAExploration Holdings Inc |
| Shearwater GeoServices Holding AS |
| Others |
Value Network & Pricing Analysis
Quantitative interpreter concentration in Houston's Energy Corridor widens pricing-tier spreads as talent scarcity at the premium tier forces operators toward standardized processing packages or economy-grade acquisition crews with compressed margins.
Pricing Analysis
Project-based contract structures dominate seismic procurement, with three-tier pricing separating integrated full-stack vendors from specialized acquisition contractors and boutique processing shops. Price differentiation hinges on certification tier for EPA methane compliance and after-sales monitoring bundling. Cost compression in economy-tier land programs is intensifying because MEMS accelerometer allocation pressure from automotive demand inflates sensor array costs. Permian Basin independents exhibit highest price sensitivity; deepwater Gulf of Mexico operators prioritize timeline certainty over rate negotiation.
Supply Chain Analysis
Direct-to-operator channels handle hyperscale exploration demand while specialized marine contractors feed integrated vendors through subcontracting arrangements. Geographic supply concentration centers on the United States for deepwater vessel operations, Norway for ocean-bottom node manufacturing, and Taiwan for MEMS foundry capacity. Raw material dependencies include fiber-optic cable for distributed acoustic sensing, high-performance computing clusters for cloud-native processing, and specialized marine fuel for acquisition fleets. Single-source vulnerability in ocean-bottom node deployment vessels creates scheduling chokepoints. Distribution runs through Houston-based procurement offices for Gulf of Mexico campaigns and Calgary hubs for Canadian oil sands operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Alberta's stricter seismicity thresholds for steam-assisted gravity drainage push capital toward Texas permitting frameworks with streamlined EPA compliance pathways.
For Market Incumbents: Acquire high-performance computing assets to anchor cloud-native processing differentiation against software-native entrants. Secure captive supply of MEMS accelerometers through backward integration into semiconductor sourcing partnerships. Defensive positioning requires locking Permian Basin operators into multi-year monitoring contracts before carbon capture site characterization fragments procurement. For New Entrants and Emerging Players: Cloud-native processing platforms offer the lowest barrier to entry for specialized interpretation services targeting mid-tier independents. Carbon capture site characterization in Texas saline aquifers represents the most penetrable white-space segment. Lead with AI-assisted fault detection workflows that compress project timelines for exploration teams lacking in-house geophysicist capacity. For Investors and Strategic Acquirers: Integrated energy technology conglomerates are the most active acquirer in this space, consolidating specialized marine contractors to secure vessel access. Long-term viability hinges on exposure to continuous monitoring mandates rather than cyclical exploration spending. Monitor EPA enforcement patterns for Subpart W methane reporting as the inflection signal for monitoring service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Site Characterization Capability | Positions vendors for saline aquifer screening contracts under EPA Class VI permitting. |
| Cloud-Native Processing Platform Migration | Compresses turnaround timelines from weeks to days for Permian Basin operators. |
| Ocean-Bottom Node Vessel Access Agreement | Secures scheduling priority for Gulf of Mexico deepwater campaigns amid fleet scarcity. |
| AI-Assisted Interpretation Algorithm Development | Reduces geophysicist hours per square kilometer through automated fault detection. |
| Integrated Service Contract Bundling | Transfers timeline risk from operators to single-vendor accountability in pre-salt screening. |
Research Methodology
Direct dialogue with seismic acquisition crew managers, geophysicist team leads at processing shops, procurement officers at Permian Basin operators, and BOEM permitting specialists grounded the qualitative framework. Secondary validation drew from EPA regulatory filings, BOEM lease sale records, SEC 10-K disclosures from listed service providers, and customs data for seismic equipment imports. Bottom-up crew-day rates and top-down operator capex allocations were triangulated to calibrate market sizing.
Bottom-up modeling of contract values across acquisition, processing, and interpretation service types was cross-referenced against top-down operator seismic budget disclosures. Segmentation dimensions included service type, technology tier, application maturity, and regional regulatory cluster. CAGRs were derived from trend extrapolation of crew utilization rates and processing software license growth. Forecast inputs incorporated vessel delivery timelines and EPA enforcement trajectory assumptions.
The model assumes a particular technology adoption path; alternative pathways for distributed acoustic sensing displacement of discrete arrays would alter the outlook. Forecasts reflect assumptions regarding permitting timeline normalization and methane regulation enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle-East Enhanced Oil Recovery Market
Oil & Gas
Oil and Gas Fittings Market
Oil & Gas
Thermal Spray Coating for Oil and Gas Market
Oil & Gas
Asia-Pacific Well Intervention Market
Oil & Gas
Logging While Drilling (LWD) Market
Oil & Gas
Gulf of Mexico Oil and Gas Upstream Market
Oil & Gas
Digital Oil Field Technology Market
Oil & Gas
Ecuador Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Engineering Services Market
Oil & Gas
Injection Well Market
Oil & Gas
Slickline Services Market
Oil & Gas
Australia Oil and Gas Upstream Market
Oil & Gas
CO2 EOR Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Asia-Pacific Oilfield Chemicals Market
Oil & Gas
Latin America Coiled Tubing Market