
 United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market | 2026-2036
United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market Size, Share, and Industry Trends Forecast 2026-2036
United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market Insights
A shift from single-source maintenance contracts toward multi-vendor service frameworks is restructuring procurement across the United States pipeline MRO sector. Kinder Morgan sustains one of the largest captive maintenance workforces in North America, covering interstate natural gas systems from the Rocky Mountains to the Southeast. Michels Corporation specializes in emergency response and integrity digs, leveraging its union-trained labor pool to compete for time-critical repair contracts. Energy Transfer controls extensive crude and NGL networks across Texas, positioning its in-house MRO units as benchmarks for vertical scope.
United States oil and gas pipeline maintenance, repair, and overhaul encompasses the technical preservation of steel and composite conduit systems operating at pressures from 200 to 1,440 psig, employing weld repair, composite sleeve reinforcement, and cathodic protection to ensure hydrocarbon containment across transmission and distribution networks. Smart pigging technology leads the technology segment as operators deploy magnetic flux leakage and ultrasonic inline inspection tools to detect metal loss and cracking before seam failures occur. Emergency repairs capture expanding margin pools as PHMSA incident response timelines compress and operators face escalating liability exposure from ruptures on high-consequence areas.
PHMSA integrity management rules, EPA spill prevention requirements, and OSHA pipeline construction standards collectively shape MRO demand by mandating documented inspection frequencies, qualified repair procedures, and worker certification benchmarks. The EPA's Clean Water Act spill response protocols and state-level Texas Railroad Commission rules further tighten compliance windows for coastal and riparian crossings. Stakeholders must monitor how proposed PHMSA gas gathering line expansions and methane emission detection mandates redirect service provider capabilities toward smaller-diameter, higher-frequency inspection cycles.
Market Dynamics
PHMSA's 2023 gas gathering line expansion rule is forcing midstream operators to extend integrity management protocols to previously unregulated 8-inch and smaller pipelines across the Permian Basin and Appalachian shale plays.
Growth Catalysts
- PHMSA Integrity Management Mandates:Federal rules now require inline inspection of gas transmission lines in high-consequence areas every seven years, creating recurring demand for smart pigging services and follow-up dig programs.
- Permian Basin Infrastructure Density:Over 16,000 miles of gathering lines in West Texas require simultaneous corrosion monitoring and compression station maintenance as production volumes strain legacy steel networks.
- Ultrasonic Inline Inspection Tools:Crack-detection capabilities now resolve anomalies below two millimeters, allowing operators to schedule repairs before seam failures trigger emergency shutdowns.
Market Restraints
- Specialized Welder Shortages:API 1104-certified pipeline welders command premium rates exceeding $85 per hour in the Gulf Coast, constraining contractor capacity during integrity dig seasons.
- Steel Tariff Volatility:Section 232 duties on imported line pipe increase material costs for sleeve reinforcement and replacement spool fabrication.
- Epoxy Coating Supply Concentration:Three domestic manufacturers control 80% of fusion-bonded epoxy supply for external corrosion protection, creating price inflexibility during demand surges.
Strategic Opportunities
- Hydrogen Pipeline Repurposing:Texas and Louisiana operators are assessing existing natural gas infrastructure for hydrogen blending compatibility, requiring new embrittlement testing protocols and gasket material upgrades.
- Drone-Based Leak Detection:Optical gas imaging mounted on unmanned aerial systems is converging with methane monitoring mandates to create subscription-based inspection services for mid-size gathering operators.
- Carbon Capture Transport Networks:EPA 45Q tax credits are incentivizing CO2 pipeline construction across the Midwest and Gulf Coast, requiring corrosion-resistant metallurgy and dense-phase compression maintenance capabilities.
Industry Challenges
- Inline Inspection Data Integration:Operators struggle to normalize magnetic flux leakage signals across multiple vendor platforms, delaying corrosion growth rate calculations and repair prioritization.
- Louisiana Coastal Access Constraints:Marshland pipeline corridors require specialized amphibious equipment for integrity digs, limiting contractor pools during hurricane season shutdown windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market |
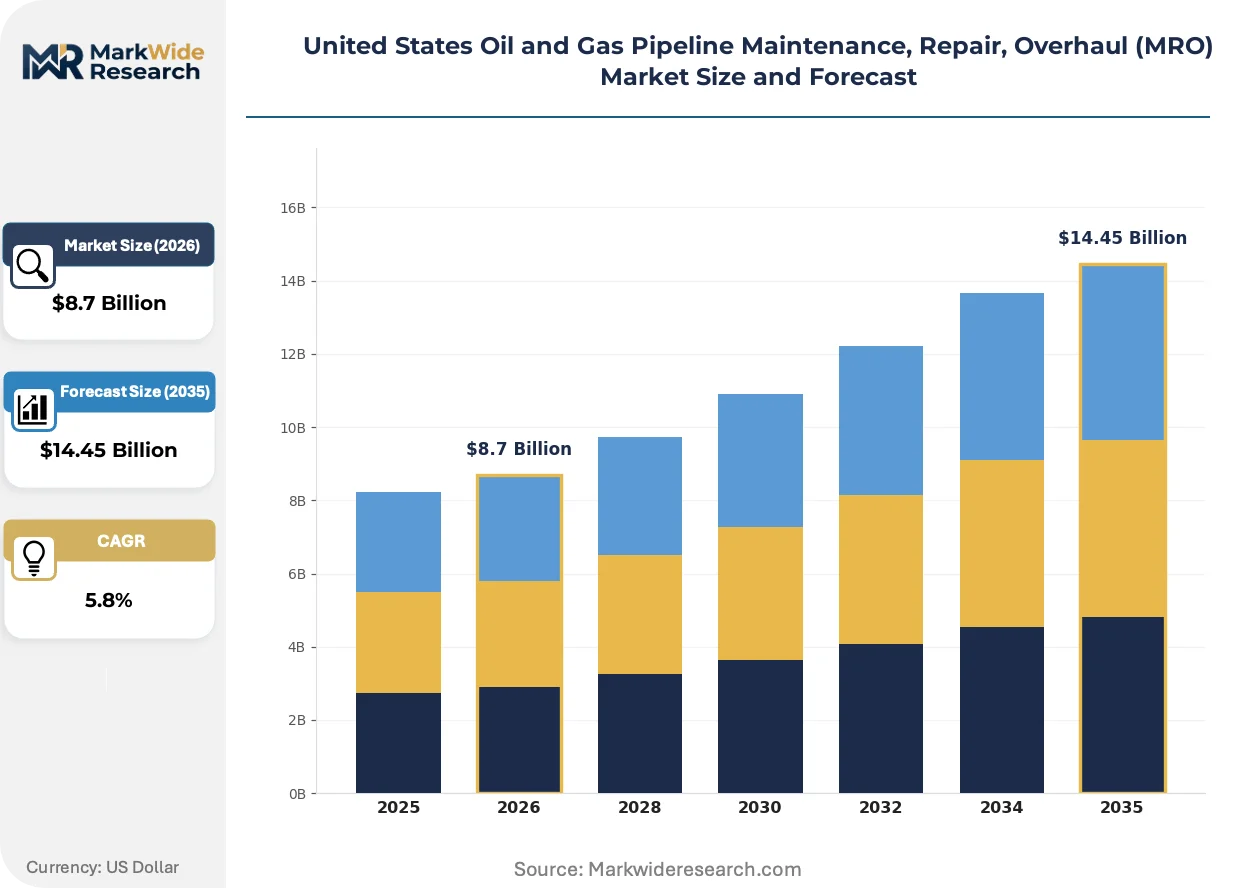
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Routine Maintenance, Emergency Repairs, Inspections, Corrosion Management Technology: Smart Pigging, Hydraulic Monitoring, Leak Detection Systems, Automated Valves End User: Midstream Companies, Utility Providers, Oil Producers, Contract Service Providers Installation: Above Ground, Below Ground, Offshore, Onshore |
| Companies Covered | Mastec, Kiewit Corporation, Kinder Morgan, Energy Transfer, Pembina Pipeline, TC Energy Corporation, Michels Corporation, Enbridge, TechnipFMC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market Trends and Innovations
Digital twin deployment is compressing inspection-to-repair cycles as operators simulate pipeline stress states before excavating. Automation of anomaly assessment is reducing engineering judgment bottlenecks.
Robotic ultrasonic testing crawlers are converging with permanent sensor networks to enable continuous wall-thickness monitoring without production interruptions. Offshore platform operators in the Gulf of Mexico are deploying these systems on riser strings and subsea flowlines. The technology is converging with predictive maintenance platforms to shift repair scheduling from calendar-based to condition-based intervals.
EPA methane emission detection mandates under the Inflation Reduction Act now require quarterly surveys of compressor stations and storage facilities using optical gas imaging or equivalent methods. Midstream companies are retraining maintenance crews or outsourcing to certified leak detection contractors. The rule most affects Texas and New Mexico operators with extensive gathering system footprints, who are consolidating vendor relationships to ensure audit-ready documentation.
Multi-year service agreements are displacing transactional repair contracts as operators seek capped-cost predictability for integrity management programs. Large midstream companies now bundle smart pigging, engineering assessment, and excavation services under single-source frameworks. This pattern concentrates procurement leverage in the hands of integrated providers while marginalizing specialty contractors lacking full-scope capabilities.
United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market Segmentation
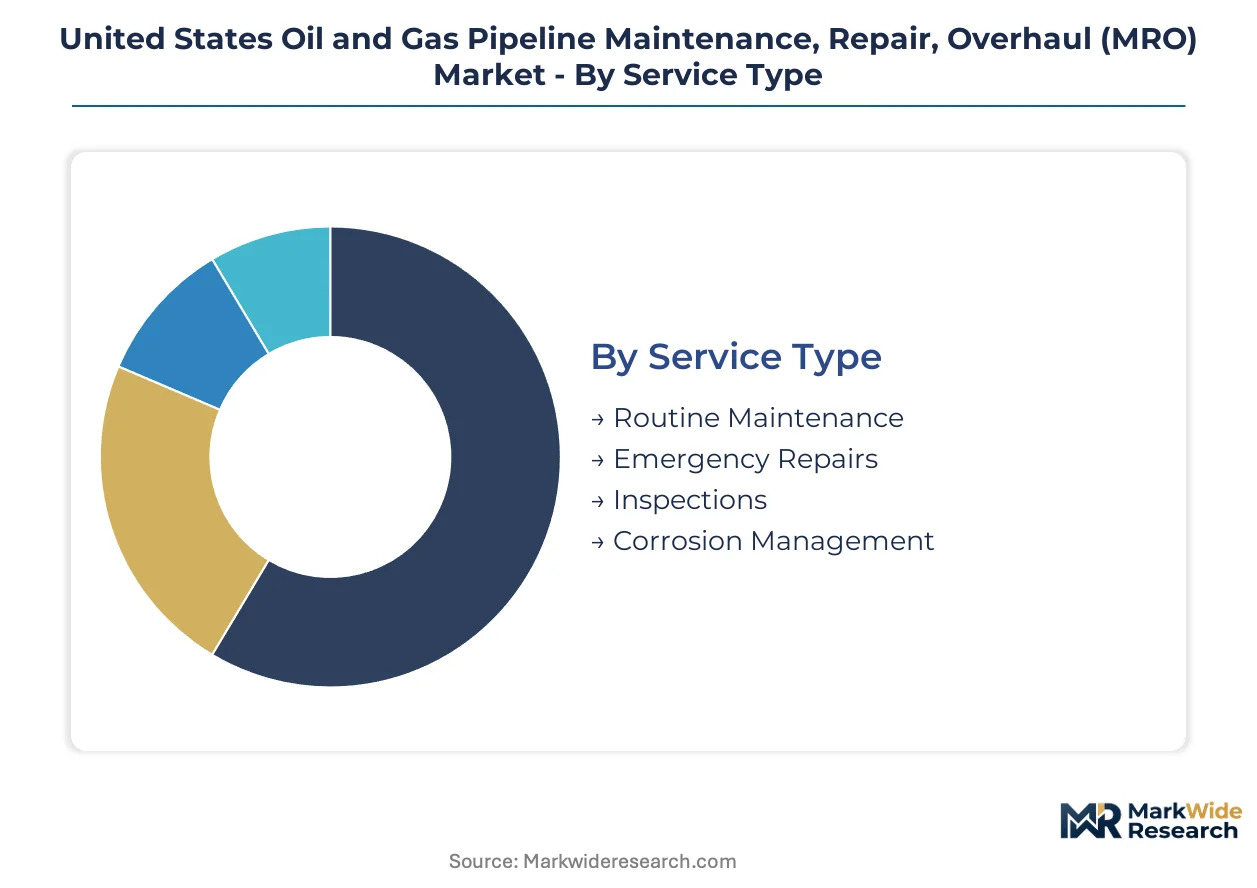
Pipeline MRO procurement patterns diverge sharply by operational urgency and regulatory exposure. Midstream operators structure vendor relationships around predictable inspection cycles, while emergency response capabilities command premium positioning in high-consequence corridors.
Service Type:
Cost tier separates planned expenditure from catastrophic liability exposure.
- Routine Maintenance:Scheduled compressor station servicing, valve exercising, and cathodic protection system calibration dominate procurement volumes across interstate transmission networks. Texas and Louisiana operators bundle these services under multi-year framework agreements to cap integrity management costs.
- Emergency Repairs:Rupture response and integrity dig execution require API 1104-certified welding crews mobilized within hours. Gulf Coast contractors leverage union labor pools to capture time-critical contracts where PHMSA incident timelines compress liability windows.
- Inspections:Inline tool runs and direct assessment programs verify pipeline fitness per federal mandates.
- Corrosion Management:Coating rehabilitation and cathodic protection retrofitting extend asset life in coastal environments.
Routine Maintenance leads volumes today; Emergency Repairs is gaining share fastest.
Technology:
Application context determines technology selection between predictive and reactive deployment models.
- Smart Pigging:Magnetic flux leakage and ultrasonic inline inspection tools detect metal loss and cracking anomalies before seam failures trigger shutdowns. Permian Basin operators deploy these systems quarterly on gathering lines now subject to expanded PHMSA jurisdiction.
- Leak Detection Systems:Computational pipeline monitoring and fiber-optic sensing arrays satisfy EPA methane detection mandates under Inflation Reduction Act protocols. Appalachian shale operators consolidate vendor relationships to ensure audit-ready documentation for quarterly compressor station surveys.
- Hydraulic Monitoring:Pressure transient analysis identifies blockages and leaks in liquid pipelines.
- Automated Valves:Remote-actuated isolation systems reduce spill volumes during rupture events.
Smart Pigging leads volumes today; Leak Detection Systems is expanding most quickly.
End User:
Customer type dictates procurement scale and in-house capability depth.
- Midstream Companies:Kinder Morgan and Energy Transfer maintain captive maintenance workforces covering interstate systems, yet outsource specialized inspection and emergency response to certified contractors. Vertical scope concentration allows these operators to benchmark MRO unit costs against third-party providers.
- Oil Producers:Permian Basin E&P companies face expanded integrity management obligations on previously unregulated gathering lines. Smaller operators lack scale for in-house pigging programs, creating subscription demand for outsourced inspection services.
- Utility Providers:Local distribution companies manage low-pressure urban networks with distinct safety protocols.
- Contract Service Providers:Independent specialists capture overflow demand during integrity dig seasons.
Midstream Companies lead volumes today; Oil Producers is climbing the fastest.
Installation:
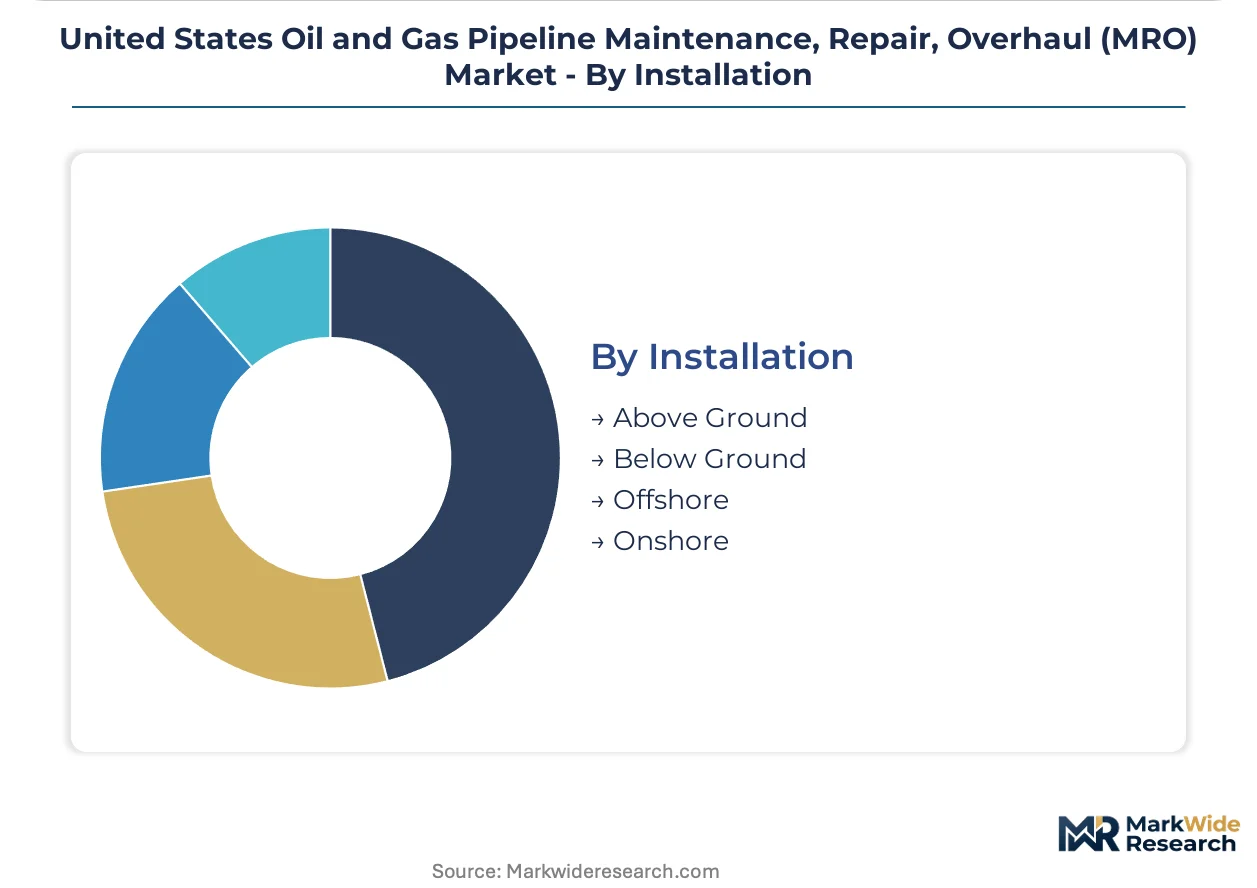
Geography and access constraints fragment contractor capabilities and equipment requirements.
- Below Ground:Buried transmission corridors across the Midwest and Southwest require excavation for integrity digs and sleeve reinforcement. Michels Corporation and similar contractors deploy directional drilling and hydrovac equipment to minimize surface disruption during repair windows.
- Offshore:Gulf of Mexico platform networks and subsea flowlines demand robotic ultrasonic crawlers and diving support vessels. Louisiana coastal access constraints limit contractor pools during hurricane season shutdowns.
- Above Ground:Elevated river crossings and compressor station piping simplify inspection access.
- Onshore:Shale gathering systems concentrate in West Texas and North Dakota production fields.
Below Ground leads volumes today; Offshore is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin anchors national pipeline MRO demand, with over 16,000 miles of gathering infrastructure requiring simultaneous corrosion management and smart pigging deployment.
Texas
Gulf Coast petrochemical corridors and West Texas shale networks drive concentrated maintenance expenditure. PHMSA expanded integrity management rules to 8-inch gathering lines, compelling Permian operators to schedule quarterly inline inspections. Houston anchors contractor headquarters for emergency response and integrity dig services.
Louisiana
Offshore platform networks and coastal marshland pipelines require specialized amphibious equipment for subsea flowline maintenance. State environmental regulations under the Coastal Use Permit program tighten repair windows for riparian crossings. Lake Charles and Port Fourchon concentrate diving support vessels and robotic crawler deployment capabilities.
Oklahoma
Midcontinent storage hub infrastructure and interstate compression stations sustain routine maintenance volumes. Oklahoma Corporation Commission pipeline safety directives mandate documented cathodic protection calibration cycles. Cushing storage terminals require continuous valve exercising and pressure boundary inspections.
North Dakota
Bakken shale gathering systems face seasonal integrity challenges from freeze-thaw cycling and high-paraffin crude characteristics. North Dakota Industrial Commission spill response protocols compress emergency repair mobilization timelines. Williston Basin operators outsource smart pigging programs to third-party vendors lacking captive inspection assets.
Pennsylvania
Appalachian Marcellus-Utica gathering lines fall under expanded PHMSA jurisdiction, triggering new inline inspection obligations on previously unregulated networks. Pennsylvania Department of Environmental Protection methane monitoring rules align with federal IRA quarterly survey mandates. Pittsburgh-area contractors capture overflow demand from mid-size operators without vertical maintenance capabilities.
United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue drone-based leak detection and hydrogen compatibility testing as differentiation vectors. The market structures around three archetypes: integrated midstream operators with captive workforces, specialized emergency response contractors, and technology-focused inspection vendors. Consolidation pressure intensifies as multi-year framework agreements displace transactional repair contracts. Dominant competitive moves include backward integration into inspection tool manufacturing and geographic clustering around Permian and Gulf Coast demand nodes.
Among integrated midstream operators, Kinder Morgan and Energy Transfer anchor the captive maintenance model, each sustaining in-house workforces covering interstate transmission corridors while benchmarking unit costs against third-party providers. Michels Corporation exemplifies the emergency response specialist archetype, leveraging union-trained labor pools to capture time-critical integrity dig contracts where PHMSA incident timelines compress liability exposure.
| Leading Market Players |
|---|
| Mastec |
| Kiewit Corporation |
| Kinder Morgan |
| Energy Transfer |
| Pembina Pipeline |
| TC Energy Corporation |
| Michels Corporation |
| Enbridge |
| TechnipFMC |
| Others |
Pricing and Supply Chain Analysis
API 1104-certified welder rates exceeding $85 per hour on the Gulf Coast cascade through emergency repair quotes, compressing margins for contractors while pushing midstream operators toward multi-year framework agreements that cap integrity management costs. Steel tariffs on imported line pipe and epoxy coating supply concentration among three domestic manufacturers further amplify input cost volatility across sleeve reinforcement and cathodic protection programs.
Pricing Analysis
Input-cost pass-through dominates as Section 232 steel duties and specialized labor premiums flow directly into project-based repair quotes. Pricing stratifies across emergency response, scheduled integrity digs, and routine maintenance tiers, with API certification grade and union labor scale as primary differentiation drivers. Pricing pressure stems from welder shortages constraining contractor capacity during peak dig seasons. Small Permian Basin E&P operators exhibit highest price sensitivity, lacking scale for captive maintenance workforces, while integrated midstream companies leverage vertical scope to benchmark third-party rates.
Supply Chain Analysis
Specialized inspection tool manufacturing rests on German and Japanese producers of magnetic flux leakage and ultrasonic sensor arrays, while fusion-bonded epoxy coating feedstock draws from domestic petrochemical complexes in Texas and Louisiana. Raw material dependencies include high-grade steel plate, rare-earth magnetic components, and corrosion-resistant alloy spools. Single-source vulnerability concentrates in smart pigging electronics and diving support vessel availability for Gulf of Mexico operations. Distribution runs through Houston-based contractor hubs serving Permian and Gulf Coast demand nodes, with regional equipment staging yards compressing mobilization timelines for emergency response contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
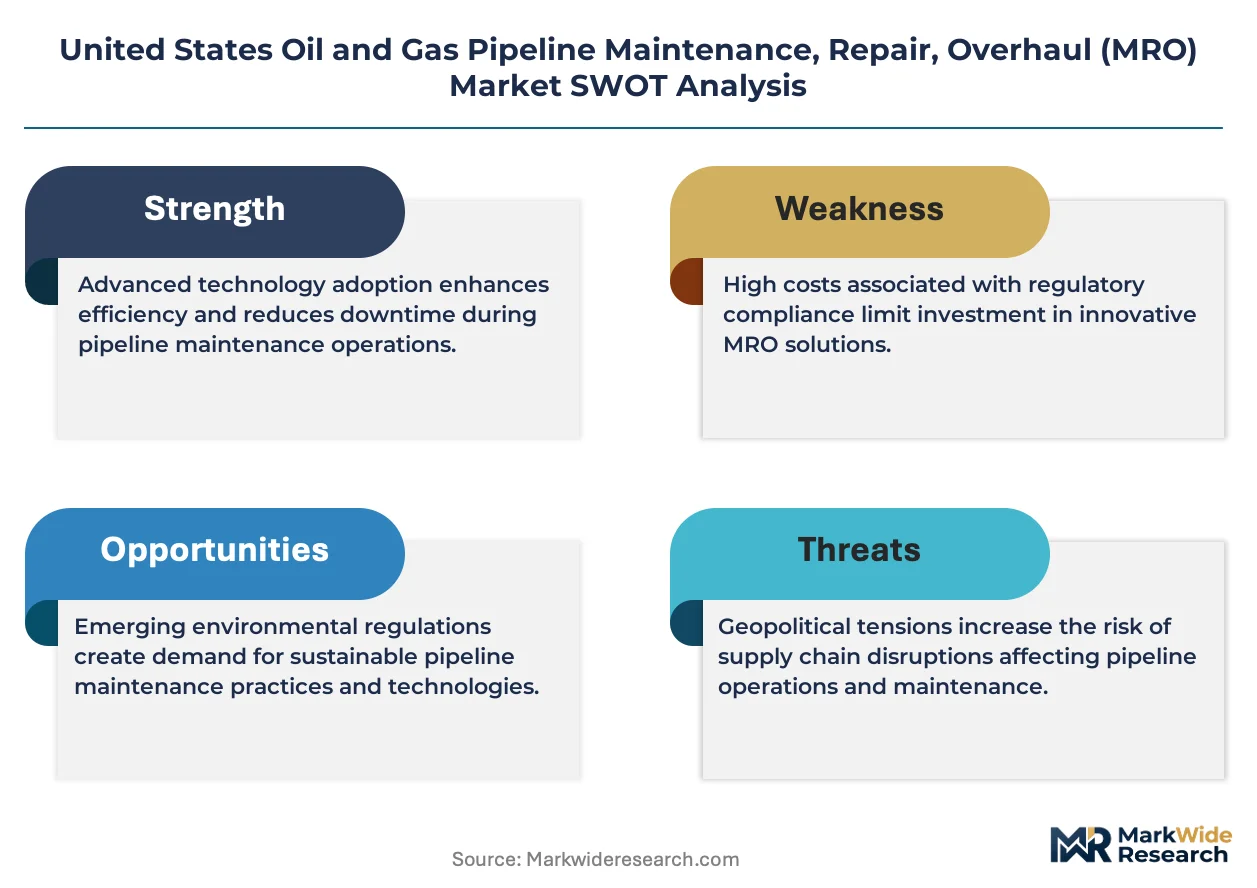
The United States pipeline MRO market functions as a geographic-arbitrage play where Louisiana coastal access constraints and Permian Basin labor scarcity create 20-30% cost differentials between onshore and offshore repair mobilizations. Regulatory divergence between PHMSA federal mandates and Texas Railroad Commission state rules fragments compliance cost structures across state lines.
For Market Incumbents: Cement multi-year framework agreements with midstream operators before drone-based leak detection vendors achieve scale, locking in smart pigging and integrity dig volumes. Backward integration into inspection tool manufacturing reduces dependency on German and Japanese sensor suppliers. Prioritize amphibious equipment fleets for Louisiana marshland corridors where hurricane season shutdowns limit contractor pools and sustain premium pricing power. For New Entrants and Emerging Players: Regional pigging contractors in North Dakota and Pennsylvania represent the most penetrable channel partner type, serving Bakken and Marcellus operators lacking captive inspection assets. Target subscription-based methane monitoring services for mid-size gathering operators facing EPA quarterly survey mandates under Inflation Reduction Act protocols. Pursue certified leak detection contractor status to capture outsourcing demand from E&P companies retraining maintenance crews. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-year framework agreements displace transactional repair contracts, concentrating procurement leverage in integrated providers. Long-term viability favors specialists with full-scope capabilities spanning smart pigging, engineering assessment, and excavation services. Watch PHMSA gas gathering line enforcement patterns as the inflection indicator for inspection frequency acceleration and vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Inspection Tool Manufacturing | Reduces dependency on German and Japanese sensor suppliers while capturing margin from magnetic flux leakage and ultrasonic inline inspection systems. |
| Multi-Year Framework Agreement Expansion | Locks in recurring smart pigging and integrity dig volumes with Kinder Morgan and Energy Transfer while capping cost predictability for operators. |
| Drone-Based Leak Detection Service Launch | Captures EPA methane monitoring mandate compliance demand from mid-size Permian and Appalachian gathering operators lacking in-house optical gas imaging capabilities. |
| Amphibious Equipment Fleet Buildout | Secures premium positioning in Louisiana coastal corridors where marshland access constraints limit contractor pools during hurricane season repair windows. |
| Hydrogen Compatibility Testing Certification | Positions for Texas and Louisiana natural gas infrastructure repurposing assessments as operators evaluate hydrogen blending and embrittlement protocols. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pipeline integrity managers, PHMSA compliance officers, union welding contractors, and midstream procurement directors with secondary validation through PHMSA incident databases, EPA spill prevention filings, and FERC interstate pipeline safety reports. Bottom-up project pipeline tracking and top-down market sizing triangulated volume estimates across service type, technology, and end-user segments.
Segment-weighting approaches modeled routine maintenance, emergency repair, inspection, and corrosion management service types alongside smart pigging, leak detection, and monitoring technology tiers. End-user segmentation captured midstream operators, oil producers, utility providers, and contract service providers with installation context distinguishing below-ground, offshore, above-ground, and onshore environments. CAGRs derived from historical expenditure patterns, regulatory mandate timelines, and infrastructure age profiles across the Permian Basin, Gulf Coast, and Appalachian shale corridors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PHMSA enforcement intensity, welder labor pool expansion, and steel tariff policy shifts. Forecasts reflect documented assumptions regarding integrity management rule expansion and smart pigging technology adoption curves. A small set of triggers—including proposed methane emission detection mandate revisions and hydrogen pipeline repurposing regulatory clarity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Natural Gas Market
Oil & Gas
US Sand Control Systems Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Canada LNG Market
Oil & Gas
United States Artificial Lift Systems Market
Oil & Gas
India Natural Gas Market
Oil & Gas
Global Oil and Chemical Spill Kits Market
Oil & Gas
Integrated Gas System Market
Oil & Gas
Dry Natural Gas Market
Oil & Gas
Turkmenistan Oil and Gas Market
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
Coiled Tubing Services Market
Oil & Gas
Venezuela Oil and Gas Market
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
Microbial Enhanced Oil Recovery Market